
 User Feedback Software Market | 2026-2036
User Feedback Software Market Size, Share, and Industry Trends Forecast 2026-2036
User Feedback Software Market Insights
Platform licensing revenue from standalone survey tools is narrowing as vendors bundle analytics and automation into unified suites. Qualtrics leverages its integration capabilities to anchor enterprise accounts with workflow connectivity across CRM ecosystems. Zendesk competes by embedding feedback loops directly into customer service pipelines, reducing friction between support and product teams. Hotjar specializes in behavioral analytics, occupying the mid-market segment with visual session replay tools that differentiate on implementation speed.
User feedback software encompasses digital platforms that collect, aggregate, and analyze customer sentiment through structured surveys, unstructured text processing, and behavioral telemetry, typically operating via web-based interfaces with API connectivity to enterprise systems. These platforms employ natural language processing engines and statistical clustering algorithms to transform raw input into actionable product intelligence for commercial decision-making. Cloud-based deployment leads the market as organizations prioritize elastic scaling and reduced infrastructure overhead, while data analytics features represent the fastest-expanding capability area as buyers demand predictive sentiment scoring. The B2B customer type commands premium pricing due to complex procurement workflows and multi-stakeholder approval chains, whereas small business end users gravitate toward SaaS tiers with pre-built templates and self-service onboarding.
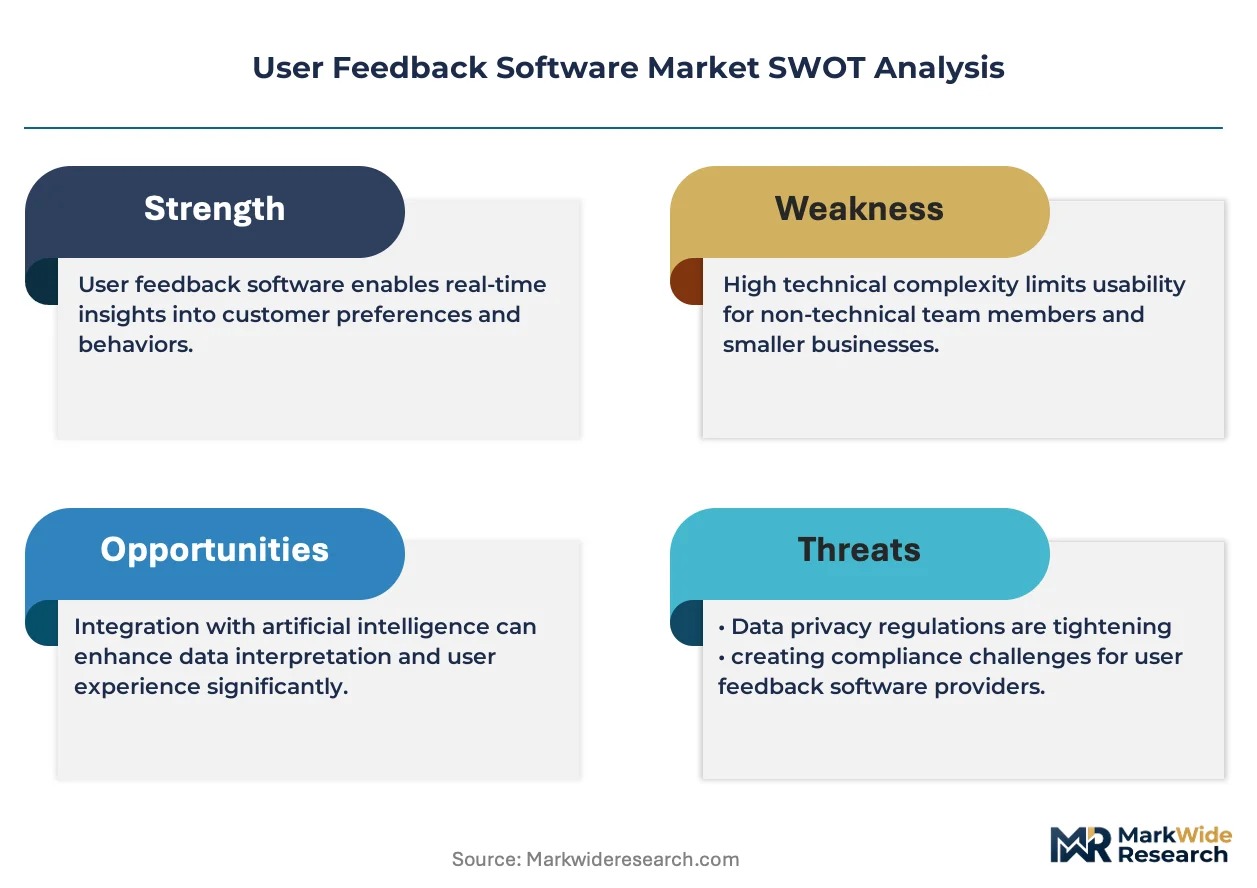
The EU AI Act and GDPR impose algorithmic transparency and consent-management requirements on automated feedback processing, compelling vendors to deploy explainable classification models and granular data-retention controls. In the United States, HIPAA and SOX frameworks restrict how healthcare and financial services firms handle recorded customer interactions, creating compliance moats for vendors with certified audit trails and encryption standards. Stakeholders must monitor regulatory divergence between privacy regimes to determine whether modular architecture or region-specific instances better serve expansion strategies.
Market Dynamics
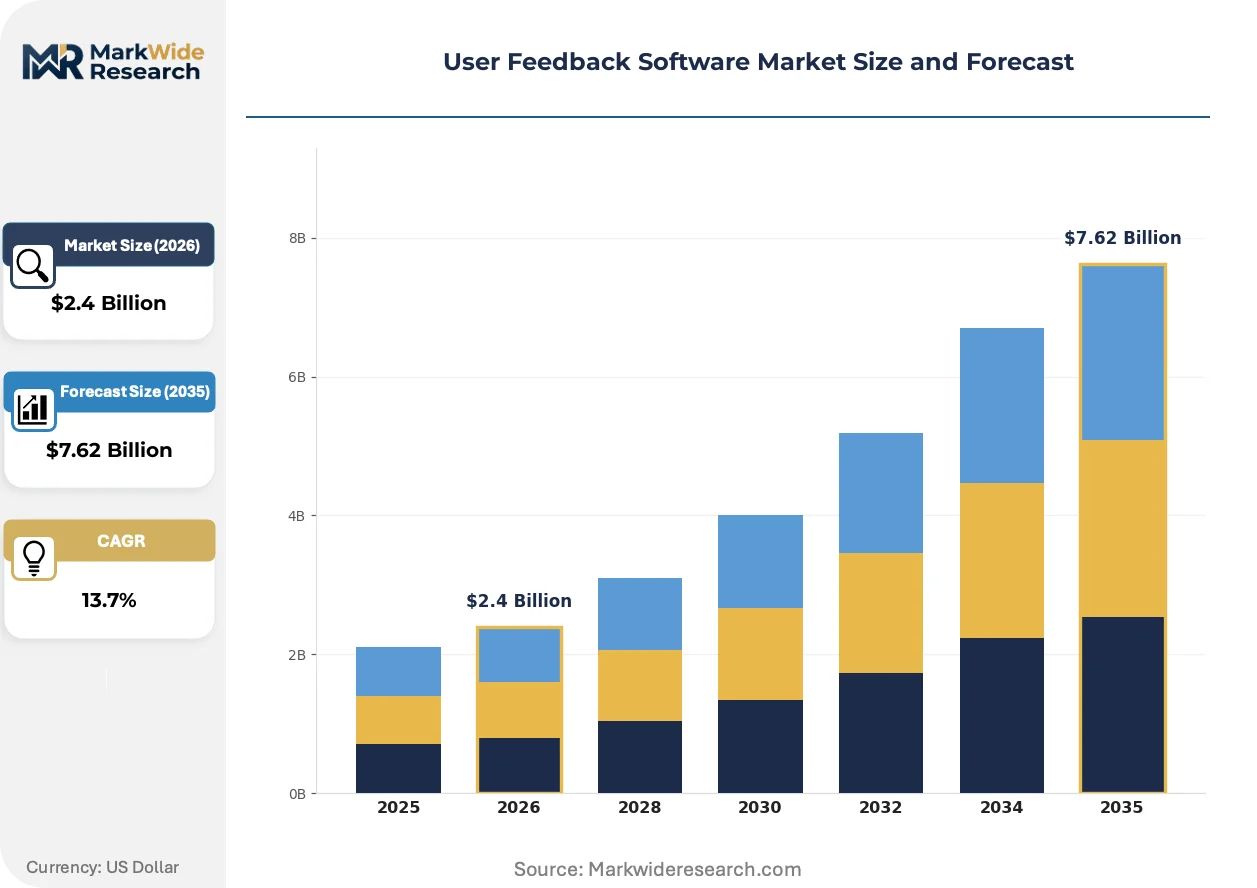
Enterprise procurement of user feedback software is pivoting from standalone survey licensing toward unified platforms embedding predictive analytics, driven by buyer demands for workflow integration with existing CRM investments and pressure from GDPR and EU AI Act compliance costs.
Growth Catalysts
- Real-time sentiment analysis:SaaS providers deploy natural language processing engines to transform unstructured customer text into actionable product intelligence, compressing decision cycles for product teams.
- GDPR Article 22 mandates:Automated decision-making transparency requirements in Europe push vendors to develop explainable classification models, creating competitive differentiation for compliant architectures.
- Healthcare vertical concentration:United States hospitals and insurers seek HIPAA-aligned voice-of-customer platforms to capture patient experience data within encrypted audit trails.
Market Restraints
- Cloud infrastructure concentration:AWS, Microsoft Azure, and Google Cloud dominate hosting for feedback platforms, creating single-point-of-failure risk and limited vendor negotiation leverage.
- EU AI Act compliance timeline:Algorithmic risk classification and conformity assessment procedures impose 12-18 month certification delays for high-risk sentiment analysis deployments.
- Privacy-preserving computation costs:Federated learning and differential privacy implementations require 40-60% additional compute overhead compared to centralized data processing.
Strategic Opportunities
- Mid-market behavioral analytics:Visual session replay and heatmap tools remain underpenetrated among sub-500 employee software companies in Germany and France.
- API-first distribution:Embedded feedback widgets sold through developer marketplaces and low-code platforms reach product teams outside traditional enterprise procurement channels.
- CSRD reporting convergence:European sustainability disclosure requirements create demand for stakeholder sentiment tracking as auditable ESG input, opening new budget lines.
Industry Challenges
- Data engineering talent scarcity:Pipeline construction for real-time feedback ingestion competes with broader AI/ML hiring demand, inflating compensation for specialists.
- Legacy CRM integration complexity:Custom API development for on-premise SAP and Oracle systems consumes 30-40% of implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | User Feedback Software Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Enterprises, Small Businesses, Freelancers, Agencies Feature: Survey Tools, Data Analytics, Integration Capabilities, Automation Customer Type: B2B, B2C, Non-Profit, Educational Institutions |
| Companies Covered | HubSpot, Zendesk, Qualtrics, SurveyMonkey, Bazaarvoice, Trustpilot, Yotpo, Hotjar, Intercom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
User Feedback Software Market Trends and Innovations
Feedback platform architecture is converging toward composable microservices, enabling buyers to license specific capabilities rather than monolithic suites. This shift is compressing vendor R&D cycles and forcing specialization bets.
Large language model fine-tuning for domain-specific sentiment classification is collapsing the performance gap between generic NLP APIs and custom-built engines. Healthcare and financial services buyers in the United States now adopt pre-trained models with HIPAA-compliant hosting, eliminating prior requirements for proprietary data science teams. The technology is collapsing barriers to predictive scoring for mid-market buyers previously priced out of advanced analytics tiers.
The EU AI Act risk-based classification system mandates human oversight for high-risk automated feedback processing affecting credit or employment decisions. Vendors serving European financial institutions must deploy explainability interfaces documenting model logic and confidence intervals. German and French banking regulators are scrutinizing sentiment-derived product recommendations for discriminatory pattern risks.
Subscription bundling now dominates enterprise procurement, with buyers demanding feedback analytics as a standard module within broader customer success platforms rather than separate line items. Value-based pricing tied to measurable retention improvements displaces per-seat licensing in healthcare and B2B software verticals. This shift is most visible in United States enterprise renewals, where procurement teams consolidate vendor relationships.
User Feedback Software Market Segmentation
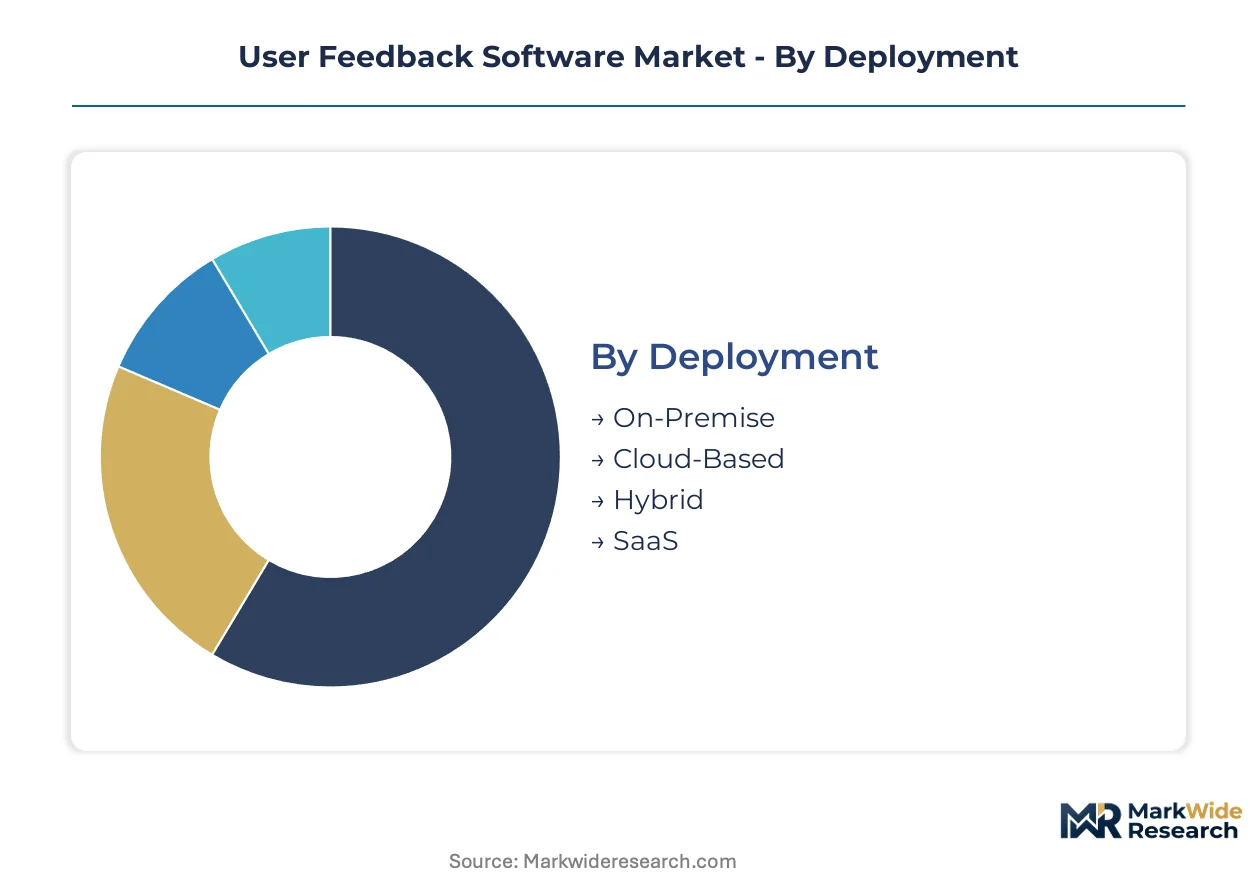
Segmentation in user feedback software reveals distinct procurement rhythms and capability requirements across buyer profiles. Deployment mode determines infrastructure overhead and compliance posture. End-user scale shapes pricing architecture and support intensity.
Deployment:
Cloud-based deployments compress implementation cycles to days, while on-premise installations extend to quarters due to security certification requirements.
- On-Premise:Deployed within client-controlled data centers with dedicated hardware stacks. Financial services firms in the United States mandate this model for SOX-compliant audit trails and encryption key custody.
- Cloud-Based:Hosted on elastic infrastructure with API-native architecture. Healthcare providers across Germany and France adopt this for rapid scaling of patient experience programs under GDPR Article 32 safeguards.
- Hybrid:Sensitive feedback data remains on-premise while analytics processing shifts to cloud nodes. Manufacturing conglomerates with legacy ERP investments favor this split architecture.
- SaaS:Fully managed multi-tenant platforms with zero infrastructure burden. Freelancers and boutique agencies in the United States gravitate toward tiered subscription models with template libraries.
Cloud-based deployments dominate installed base. SaaS represents the fastest expansion trajectory as procurement teams consolidate vendor relationships.
End User:
Enterprise accounts command annual contract values an order of magnitude above freelancer segments, though sales cycles stretch across fiscal quarters.
- Enterprises:Multi-divisional rollouts with custom integration requirements and dedicated customer success managers. United States B2B software vendors anchor here for retention analytics tied to net revenue retention metrics.
- Small Businesses:Self-service onboarding with pre-built survey templates and dashboard presets. German mid-market manufacturers adopt behavioral analytics suites for conversion optimization without dedicated data teams.
- Freelancers:Individual practitioners purchasing monthly subscriptions for client project work. French marketing consultants drive demand for lightweight feedback widgets embeddable in portfolio sites.
- Agencies:Multi-client management portals with white-labeling and consolidated billing. Creative agencies across the United States leverage these for brand tracking studies across consumer portfolios.
Enterprises anchor revenue concentration. Small businesses are where vendor acquisition investments concentrate most heavily.
Feature:
Feature bundling determines competitive positioning, with integrated suites displacing standalone point solutions across procurement evaluations.
- Survey Tools:Structured questionnaire builders with branching logic and multilingual distribution. Healthcare systems in the United States deploy these for HCAHPS-compliant patient satisfaction measurement.
- Data Analytics:Predictive sentiment scoring and statistical clustering engines. Financial services firms across France and Germany require explainable model outputs under EU AI Act risk classification rules.
- Integration Capabilities:Native connectors to CRM, helpdesk, and product management platforms. Enterprise SaaS vendors prioritize Salesforce and HubSpot interoperability in procurement scoring.
- Automation:Triggered feedback collection and closed-loop alerting workflows. Subscription software companies automate NPS pulse surveys tied to usage milestone events.
Survey tools dominate legacy installed base. Data analytics capabilities are climbing the fastest as buyers demand predictive intelligence.
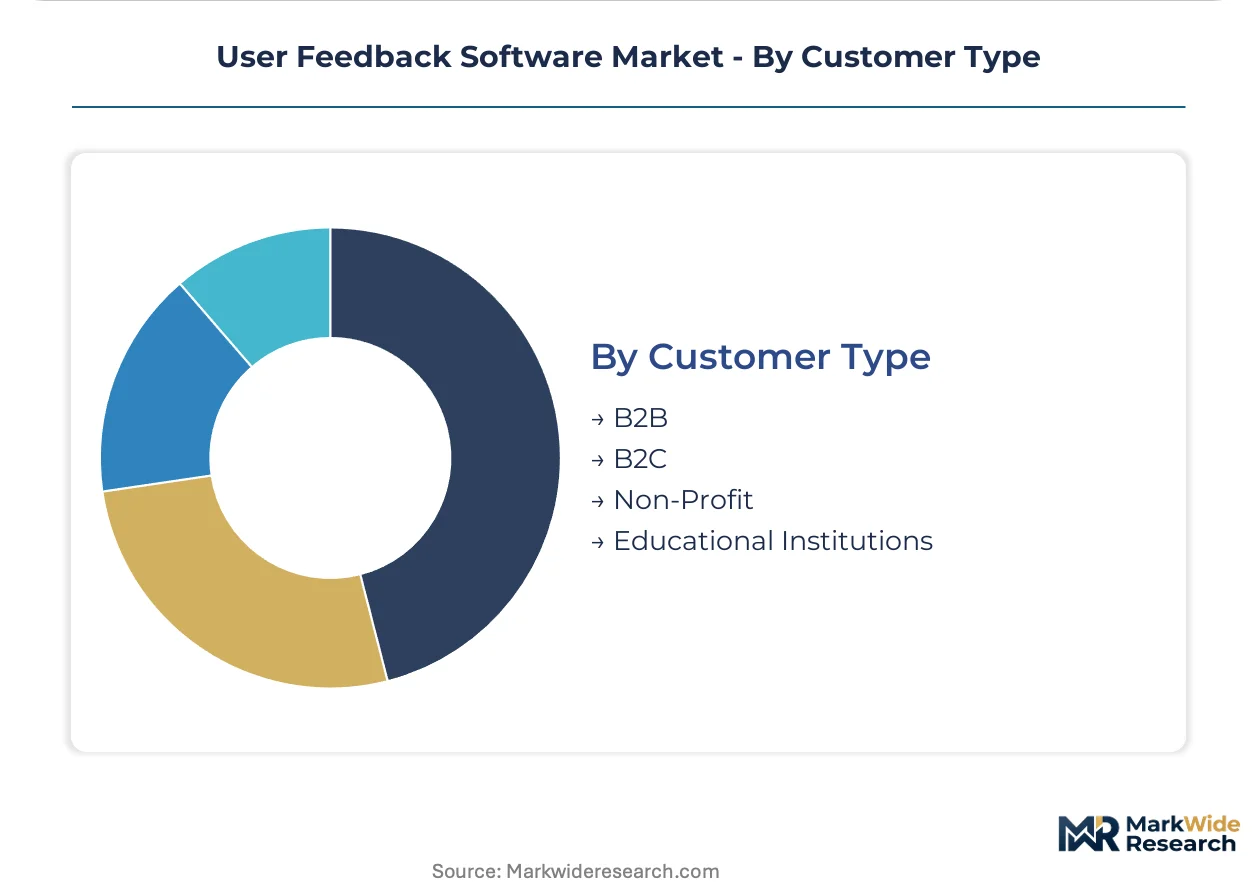
Customer Type:
B2B procurement involves complex stakeholder alignment, while B2C deployments prioritize response volume and demographic segmentation.
- B2B:Account-level feedback tied to renewal risk scoring and expansion opportunity identification. United States enterprise software vendors anchor pricing to measurable retention improvements.
- B2C:High-volume transactional feedback with demographic slicing and brand tracking. Retail chains across Germany deploy post-purchase surveys for Net Promoter Score benchmarking.
- Non-Profit:Donor sentiment tracking and volunteer experience measurement with discounted pricing tiers. Foundations in France utilize these for stakeholder reporting under CSRD-aligned disclosure frameworks.
- Educational Institutions:Course evaluation systems and alumni engagement platforms with semester-aligned deployment cycles. Universities in the United States integrate these with learning management systems.
B2B commands premium pricing tiers. B2C is where volume scaling and automation investments concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development for feedback analytics concentrates in the United States, with secondary engineering hubs emerging across Western Europe and India. Cloud infrastructure spending patterns reveal enterprise procurement gravitating toward jurisdictions with established data protection frameworks.
United States
Healthcare systems and financial services firms drive demand for HIPAA and SOX-compliant sentiment platforms. The SEC scrutinizes algorithmic transparency in customer-facing recommendation engines. Boston and San Francisco anchor development clusters where vendors refine NLP models for regulated industries.
Germany
Automotive manufacturers and industrial conglomerates adopt behavioral analytics for supplier quality feedback loops. The KBA coordinates with BSI on cybersecurity certification for connected vehicle data collection. Munich and Stuttgart host implementation teams serving Mittelstand exporters.
United Kingdom
B2B SaaS vendors prioritize real-time integration with Salesforce and HubSpot ecosystems. The Information Commissioner's Office enforces GDPR-derived accountability measures for automated profiling. London's fintech corridor generates concentrated demand for voice-of-customer platforms tied to retention metrics.
France
Luxury brands and retail chains deploy post-transaction sentiment tracking for Net Promoter Score benchmarking. The CNIL mandates explicit consent flows for cookie-based behavioral analytics. Paris agencies specialize in white-labeled feedback portals for multi-brand portfolios.
India
IT services exporters and domestic SaaS startups consume API-first feedback widgets for product iteration cycles. The Ministry of Electronics and Information Technology promotes data localization through draft Digital Personal Data Protection rules. Bangalore and Hyderabad engineering centers develop cost-optimized sentiment classification for mid-market buyers.
User Feedback Software Market Competitive Landscape
Enterprise suite providers and specialized behavioral analytics vendors split the market into distinct competitive spheres. Consolidation pressure favors vendors with native CRM connectivity and certified compliance postures. Two archetypes dominate: workflow-integrated platforms anchoring multi-year enterprise contracts, and implementation-light tools capturing mid-market share through self-service onboarding. M&A activity concentrates on acquiring NLP engineering talent and regional compliance expertise.
Within the enterprise suite tier, Qualtrics and Zendesk exemplify divergent integration strategies—one anchoring through analytics depth, the other through service pipeline embedding. Hotjar occupies a position among mid-market behavioral specialists, differentiating on visual session replay capabilities that compress time-to-insight for product teams without dedicated data science resources.
| Leading Market Players |
|---|
| HubSpot |
| Zendesk |
| Qualtrics |
| SurveyMonkey |
| Bazaarvoice |
| Trustpilot |
| Yotpo |
| Hotjar |
| Intercom |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure concentration across AWS, Microsoft Azure, and Google Cloud creates single-source dependency that compresses mid-market SaaS pricing spreads while forcing enterprise buyers toward premium tiers with redundant hosting architectures. This chokepoint simultaneously widens the gap between self-service subscription tiers and compliance-heavy enterprise contracts.
Pricing Analysis
EU AI Act risk classification dictates the pricing tier structure across European deployments, separating high-risk sentiment analysis modules requiring conformity assessment from standard feedback collection tools. HIPAA and SOX certification tiers in the United States command 40-60% premiums over baseline SaaS rates due to encrypted audit trail requirements. Cost compression in mid-market behavioral analytics is intensifying because LLM fine-tuning collapses the performance gap between generic and custom NLP engines. Freelancers and boutique agencies exhibit the highest price sensitivity, gravitating toward monthly subscriptions with template libraries, while healthcare systems show the lowest sensitivity given budget allocation to patient experience mandates.
Supply Chain Analysis
Upstream compute and storage feedstocks draw from United States hyperscaler regions, Irish data center clusters, and Singapore cloud nodes serving Asia-Pacific latency requirements. NVIDIA GPU allocations for model training, specialized encryption hardware for HIPAA workloads, and API gateway infrastructure constitute critical input dependencies. Single-source vulnerability concentrates in foundation model providers supplying sentiment classification capabilities. Distribution runs through direct enterprise sales teams for complex procurement workflows, with developer marketplaces and low-code platforms capturing product team segments outside traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
User feedback software functions as a service-attach opportunity where predictive analytics and compliance modules expand recurring revenue faster than core survey licensing, with value-based pricing tied to retention metrics displacing per-seat models.
For Market Incumbents: Insulate enterprise accounts by embedding feedback loops deeper into CRM and helpdesk workflows, reducing churn risk from standalone survey tool displacement. Acquire regional compliance expertise in Germany and France to defend against EU AI Act certification delays. Prioritize API-native architecture investments that anchor multi-year contracts through integration switching costs. For New Entrants and Emerging Players: Mid-market software companies in Germany and France with sub-500 employees represent the most penetrable entry point, as behavioral analytics suites remain underpenetrated among manufacturers lacking dedicated data teams. Developer marketplaces and low-code platform distribution channels bypass entrenched procurement gatekeepers. Target API-first feedback widgets embeddable in product workflows rather than competing head-to-head with unified suites. For Investors and Strategic Acquirers: EU AI Act enforcement timelines reshape the acquisition landscape, favoring targets with pre-certified explainable classification models and granular consent-management infrastructure. Long-term viability centers on vendors bridging predictive sentiment scoring with workflow automation rather than point solutions. Monitor German and French banking regulatory scrutiny of sentiment-derived recommendations as an inflection signal for compliance-moat valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Salesforce and HubSpot connectors anchor enterprise renewals through workflow switching costs. |
| Acquisition of Specialist Firm | NLP engineering talent scarcity in Bangalore and Hyderabad drives consolidation for model development capabilities. |
| Geographic Expansion | Munich and Stuttgart implementation teams capture Mittelstand exporters with supplier quality feedback loops. |
| Strategic Partnership | Healthcare system partnerships in Boston and San Francisco refine HIPAA-compliant hosting for regulated verticals. |
| Product Launch | Explainable classification interfaces address EU AI Act mandates for German and French financial institutions. |
Research Methodology
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and integration specialists anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie usage data, and EU regulatory filings. Bottom-up deployment modeling across cloud, on-premise, hybrid, and SaaS configurations triangulated against top-down vertical spending estimates.
Scenario-bracketing around regulatory compliance timelines and LLM adoption curves structured the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment mode, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from elasticity-adjusted pricing trajectories and seat-count expansion assumptions, with specific inputs from healthcare patient experience budget allocations and B2B software net revenue retention benchmarks.
Practitioners should monitor EU AI Act enforcement variance across German and French banking regulators, HIPAA audit frequency shifts, and hyperscaler GPU allocation constraints for early signals of forecast revision. Cross-checking against Gartner and IDC enterprise software spending benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Time Series Analysis Software Market
Software & Services
School Timetable Software Market
Software & Services
Sales Platforms Software Market
Software & Services
Federal Government Software Market
Software & Services
Global AB Testing Software Market
Software & Services
Smartphone Applications Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Courier Software Market
Software & Services
Construction Jobsite Management Software Market
Software & Services
North America Digital Marketing Software Market
Software & Services
Saas-Based Expense Management Market
Software & Services
Global Software Resellers Market
Software & Services
Adaptive Learning Software Market
Software & Services
Global Sweepstakes Software Market
Software & Services
Global Recruiting Software Market