
 Self-Storage Software Market | 2026-2036
Self-Storage Software Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Storage Software Market Outlook
Facility management revenue is fragmenting across standalone point solutions and unified platform ecosystems. Yardi Systems Inc. dominates property technology infrastructure with deep vertical functionality spanning multiple real estate categories. Storable Group Inc. specializes in self-storage-native workflows that anchor tenant lifecycle management from lead generation to move-out. SiteLink Web Edition competes through established channel partnerships with hardware vendors and payment processors.
Self-storage software encompasses integrated digital systems that automate unit inventory, billing, access control, and customer relationship workflows through cloud-native architectures with API interconnectivity. These platforms serve commercial facility operators seeking to replace spreadsheet-dependent processes with real-time visibility into occupancy, pricing, and maintenance scheduling. Cloud-based deployment leads structural expansion as operators prioritize remote accessibility and reduced IT overhead over on-premise server maintenance. Management software occupies the deepest margin pool by embedding payment processing and insurance cross-sell functionality directly into core workflows. Security software represents the fastest-growing segment as biometric access and video analytics displace traditional keypad entry systems.
The Federal Trade Commission scrutinizes automated pricing algorithms for potential collusion, while state-level data breach notification laws compel vendors to hardened cybersecurity architectures. PCI DSS compliance shapes payment module design, and the California Consumer Privacy Act imposes tenant data handling constraints that propagate across vendor product roadmaps. Stakeholders must monitor how evolving state privacy legislation fragments compliance requirements and whether platform consolidation absorbs specialized security vendors before regulatory thresholds tighten.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for facility operators while embedding payment processing and insurance cross-sell functionality directly into tenant lifecycle workflows. This structural shift rewards vendors with API-first platforms over legacy on-premise systems.
Growth Catalysts
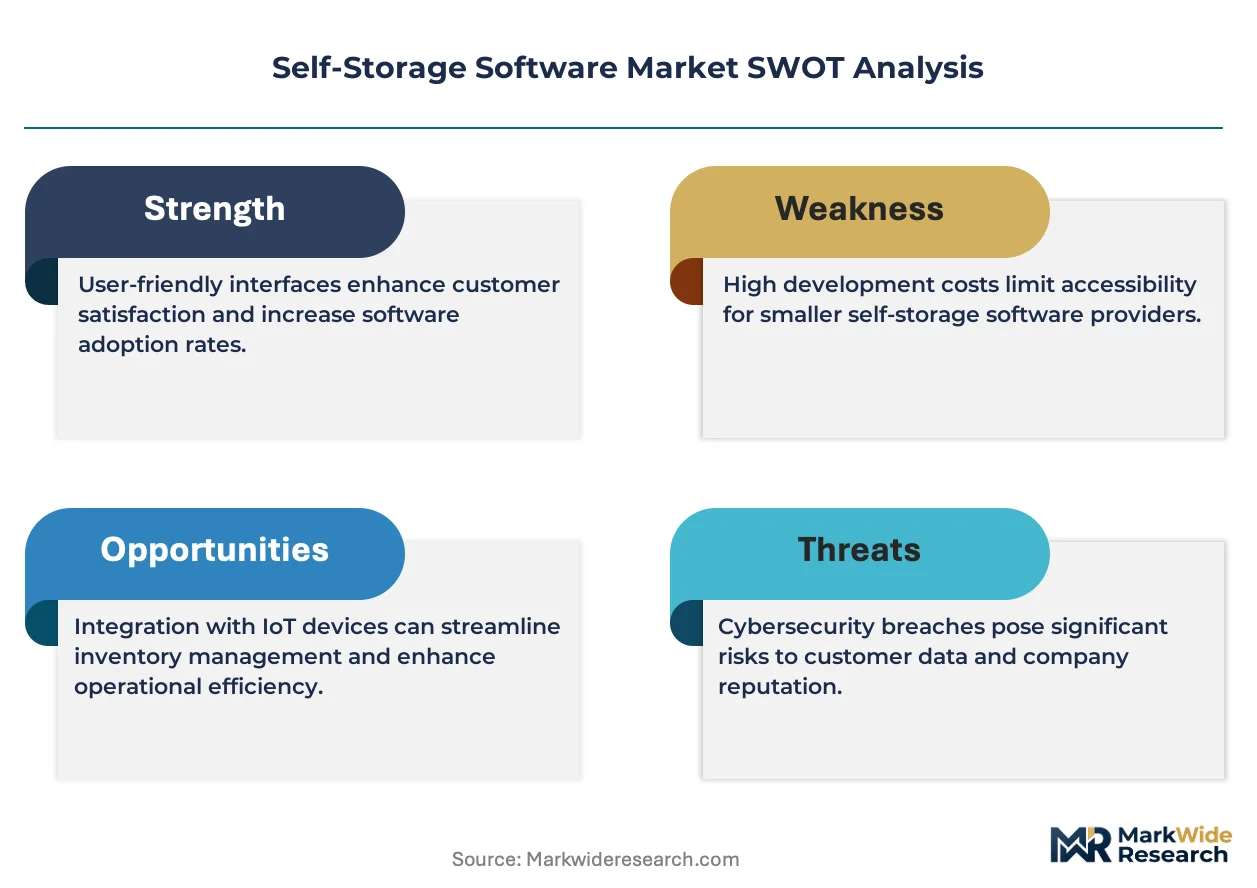
- EU AI Act compliance mandates:Automated pricing and access control systems face new algorithmic transparency requirements across European facilities. Vendors with built-in audit trails capture upgrade budgets.
- Biometric authentication adoption:Fingerprint and facial recognition systems are replacing keypad entry at high-security urban facilities. Hardware-software bundles accelerate platform stickiness.
- United States operator fragmentation:The dispersed ownership structure among independent facility owners creates substantial addressable volume for integrated software suites replacing spreadsheets.
Market Restraints
- PCI DSS compliance costs:Payment module certification requires ongoing security audits and infrastructure hardening that elevates vendor operating expenses.
- Cyber insurance premium volatility:Ransomware exposure against tenant databases drives unpredictable cost absorption for mid-sized platform providers.
- Legacy system integration friction:Proprietary access control hardware from established manufacturers resists API connectivity with newer cloud platforms.
Strategic Opportunities
- India facility digitization:Urban self-storage penetration remains minimal against rising apartment density in Mumbai and Bangalore. Early entrants shape category standards.
- Climate-controlled unit expansion:Wine storage and document preservation applications require specialized environmental monitoring modules absent from generic property management software.
- API marketplace development:Third-party developers build tenant-facing applications atop open platform architectures, extending ecosystem value without vendor R&D burden.
Industry Challenges
- Data engineering talent scarcity:Real-time pricing algorithm development requires specialized machine learning expertise rarely found in traditional property technology teams.
- State privacy law fragmentation:California Consumer Privacy Act, Virginia Consumer Data Protection Act, and Colorado Privacy Act impose conflicting tenant data handling requirements.
- Hardware-software certification alignment:Biometric access devices must synchronize firmware updates with platform security patches across distributed facility networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Storage Software Market |
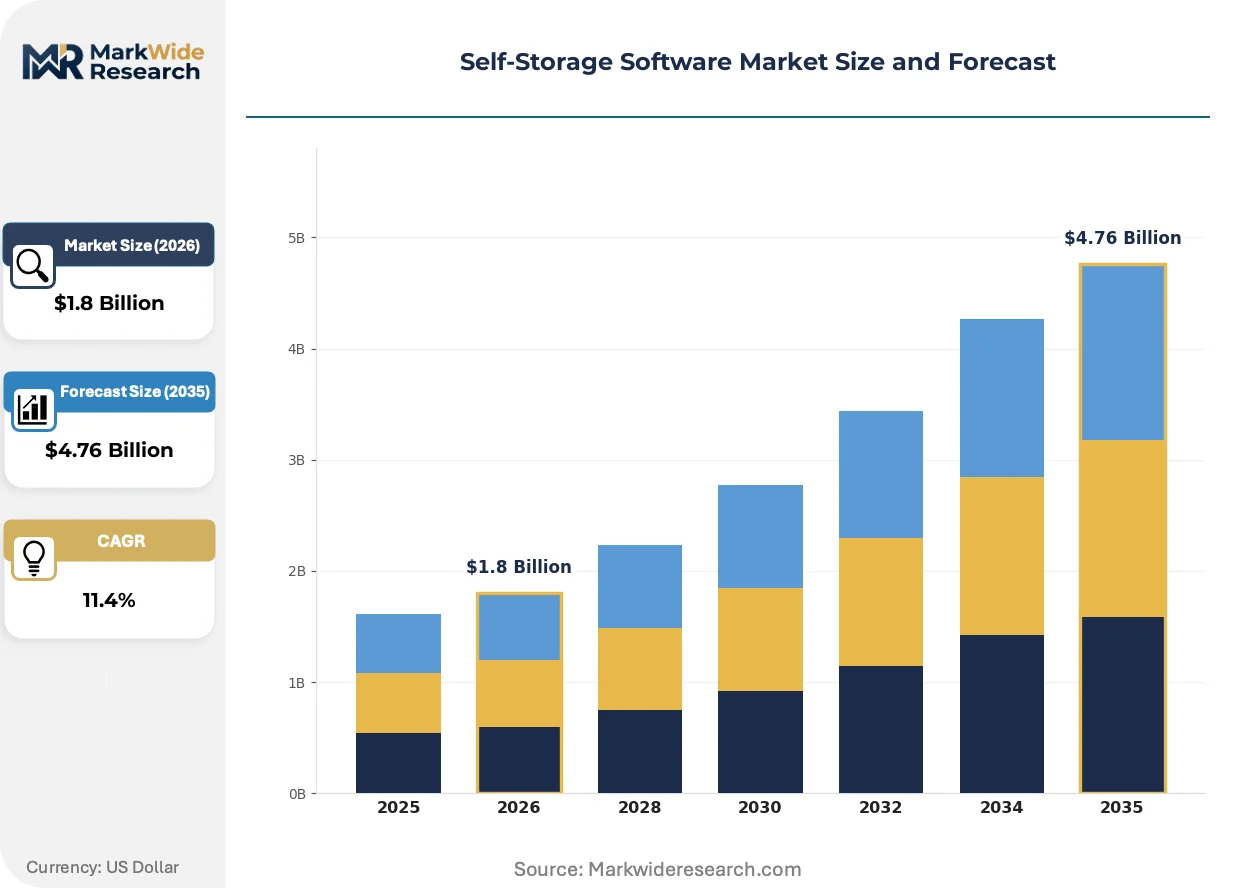
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Management Software, Accounting Software, CRM Software, Security Software Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Applications End User: Individual Customers, Small Businesses, Enterprises, Facility Owners Service Type: Subscription, License, Maintenance, Consulting |
| Companies Covered | Storable Group Inc., Yardi Systems Inc., Corrigo Incorporated, U-Haul International Inc., DOMICO Software Inc., SiteLink Web Edition, storEDGE, QuikStor Security & Software, 6Storage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Storage Software Market Strategic Shifts
Automated decision systems are penetrating facility operations from dynamic pricing to predictive maintenance scheduling. This wave of intelligence is restructuring competitive advantage around data velocity rather than feature breadth.
Mobile-first tenant portals are digitizing the entire rental journey from unit selection to contract execution. Small and mid-sized operators in Texas and Florida are adopting these platforms fastest to compete against REIT-branded facilities. Real-time availability visualization and digital lease signing are compressing the traditional 48-hour reservation-to-move-in cycle into sub-hour transactions.
The Federal Trade Commission's algorithmic pricing scrutiny is forcing vendors to document competitive intelligence sourcing and automated rate-setting logic. Facility management platforms must now maintain audit trails demonstrating independent pricing decisions rather than coordinated market behavior. United States operators face the steepest compliance burden as state attorneys general replicate federal enforcement priorities.
Tenant acquisition patterns are fragmenting across digital channels with paid search and marketplace listings displacing drive-by visibility as primary lead sources. Operators in dense urban submarkets now attribute over half of new rentals to online discovery rather than physical signage. This channel rotation demands integrated CRM workflows that attribute revenue to specific campaign spend and automate follow-up sequences.
Self-Storage Software Market Segmentation
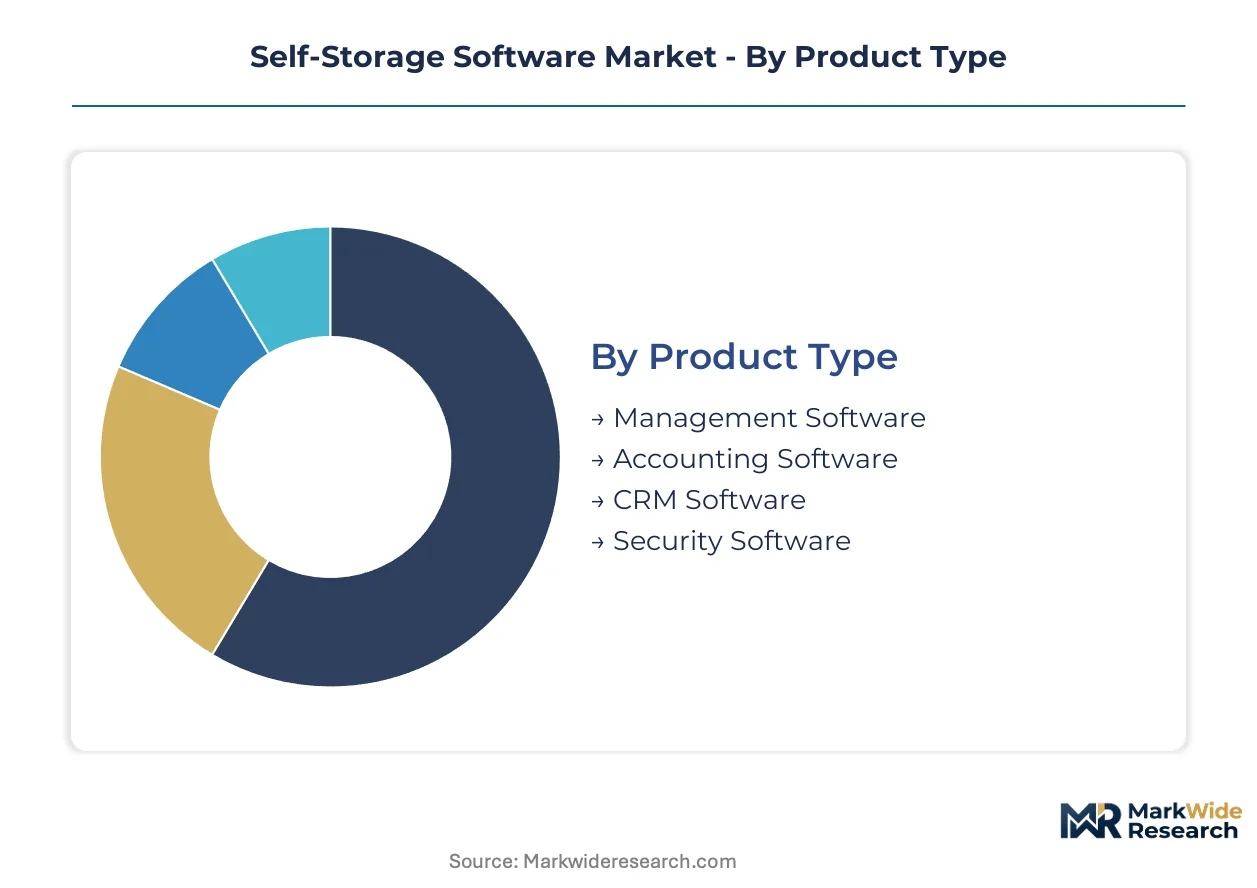
Segmentation reveals how self-storage software vendors capture value across divergent operational maturity levels. Facility owners prioritize deployment flexibility and service intensity based on portfolio scale and technical sophistication.
Product Type:
After-sales service intensity varies sharply across product categories, with security and management platforms demanding continuous firmware synchronization and tenant support.
- Management Software:Core platforms orchestrate unit inventory, billing cycles, and access control through unified dashboards. Demand concentrates among multi-facility operators in Texas and Florida seeking to consolidate fragmented operational visibility. These systems embed payment processing and insurance cross-sell modules that deepen vendor recurring revenue.
- Security Software:Biometric authentication and video analytics modules replace legacy keypad entry at urban high-density facilities. Operators in Chicago and Los Angeles are adopting fingerprint and facial recognition systems fastest, driven by tenant liability concerns and insurance premium reductions.
- Accounting Software:Specialized modules handle property tax calculations, depreciation schedules, and REIT-compliant financial reporting.
- CRM Software:Lead scoring and automated nurture sequences attribute revenue to specific digital acquisition channels.
By volume, Management Software leads. By growth pace, Security Software is ahead.
Deployment:
Cost tier separation drives deployment choice, with cloud-native architectures commanding premium pricing against legacy on-premise installations.
- Cloud-Based:Remote accessibility and automatic updates eliminate server maintenance burdens for independent operators. Small and mid-sized facility owners across Arizona and Nevada prioritize these platforms to compete against REIT-branded competitors without dedicated IT staff.
- On-Premise:Legacy installations persist at security-conscious enterprises requiring air-gapped tenant databases. Defense contractors and government-leased facilities in Virginia and Maryland mandate local data sovereignty for compliance with federal contracting requirements.
- Hybrid:Split architectures keep sensitive access logs on-premise while pushing billing data to cloud endpoints.
- Mobile Applications:Tenant-facing iOS and Android portals enable sub-hour reservation-to-move-in cycles.
Cloud-Based deployments dominate new installations. Mobile Applications show the steepest expansion trajectory among emerging categories.
End User:
Application complexity scales with user sophistication, from individual renters seeking unit visibility to enterprise portfolios requiring predictive analytics.
- Facility Owners:Independent operators with 1-10 properties represent the deepest addressable volume for integrated software suites. These stakeholders across Ohio and Georgia replace spreadsheet-dependent processes with real-time occupancy and pricing visibility.
- Enterprises:REITs and institutional investors demand API interconnectivity with existing property technology stacks. Publicly traded storage operators in New York and California require SOC 2 Type II certification and automated compliance reporting for shareholder disclosure.
- Small Businesses:Contractors and retailers use self-storage for inventory overflow and seasonal equipment staging.
- Individual Customers:Residential renters access platforms primarily through mobile portals for payment and gate entry.
Facility Owners generate the highest transaction volume. Enterprises command the largest annual contract values.
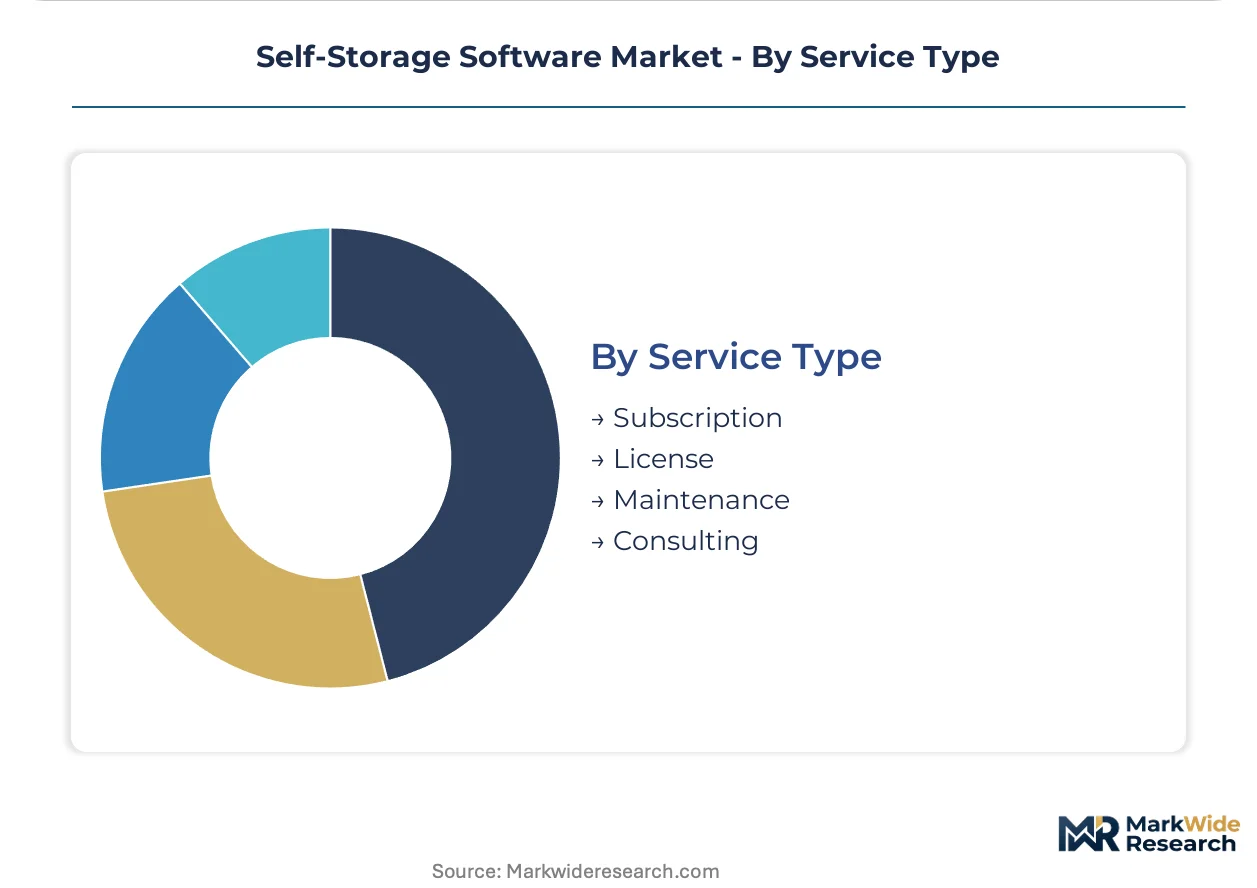
Service Type:
Customer type determines commercial structure, with subscription models anchoring long-term relationships against perpetual license alternatives.
- Subscription:Monthly recurring revenue models align vendor incentives with continuous platform improvement. Tiered pricing separates premium analytics and white-label tenant portals from basic inventory management tiers.
- Maintenance:Critical for security software requiring firmware patch coordination across distributed biometric devices. Vendors absorb cyber insurance volatility while guaranteeing uptime SLAs.
- License:Perpetual purchases persist at conservative family-owned facilities with decade-long technology refresh cycles.
- Consulting:Implementation and data migration services accelerate time-to-value for spreadsheet-to-platform transitions.
Subscription revenue exceeds license bookings. Maintenance contracts are expanding most quickly as biometric hardware penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity as facility owners prioritize platform functionality over licensing costs, while operators in emerging markets exhibit acute sensitivity to subscription tiers and implementation fees.
United States
Independent facility owners across Texas and Florida drive cloud platform adoption to compete against REIT-branded competitors. The Federal Trade Commission scrutinizes automated pricing algorithms for potential collusion, compelling vendors to maintain detailed audit trails. Dallas-Fort Worth and Miami metropolitan clusters show the fastest deployment of integrated management suites replacing spreadsheet-dependent operations.
Germany
Urban facilities in Berlin and Munich accelerate biometric access control upgrades to meet tenant liability standards. The EU AI Act imposes algorithmic transparency requirements on automated pricing and access systems. Bavaria-based operators lead adoption of environmental monitoring modules for climate-controlled wine and document storage applications.
United Kingdom
London operators face compressed margins from high real estate costs, intensifying demand for revenue optimization software. GDPR compliance requirements reshape vendor data processing architectures and tenant consent workflows. The Greater London Authority's planning restrictions on new facility construction drive existing operators toward occupancy-maximizing platforms.
India
Rising apartment density in Mumbai and Bangalore creates latent demand for digitized self-storage operations. The country's national data protection framework compels vendors to localize tenant databases and audit access logs. Early software entrants in Maharashtra and Karnataka are establishing category standards before market saturation.
Australia
Sydney and Melbourne facility owners adopt mobile-first tenant portals to capture digitally native residential renters. The Australian Privacy Principles impose constraints on cross-border data transfers that influence vendor hosting decisions. New South Wales operators lead penetration of API-marketplace architectures enabling third-party application development.
Self-Storage Software Market Competitive Environment
Vertical specialists and horizontal platform providers split the market along workflow depth versus integration breadth. The vendor base concentrates around three strategic archetypes: self-storage-native specialists, multi-vertical property technology platforms, and hardware-software bundle providers. Dominant competitive moves include API-first architecture development and biometric hardware certification partnerships.
Within the self-storage-native tier, Storable Group Inc. and SiteLink Web Edition exemplify workflow specialization from lead generation through move-out. Yardi Systems Inc. occupies a position spanning multiple real estate verticals with deep infrastructure functionality. These three anchors demonstrate how competitive positioning crystallizes around either domain-specific feature depth or cross-category platform leverage.
| Leading Market Players |
|---|
| Storable Group Inc. |
| Yardi Systems Inc. |
| Corrigo Incorporated |
| U-Haul International Inc. |
| DOMICO Software Inc. |
| SiteLink Web Edition |
| storEDGE |
| QuikStor Security & Software |
| 6Storage |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure concentration among hyperscalers in the United States anchors margin pools in payment processing modules and biometric hardware certification tiers. Facility operators absorb subscription premiums for embedded financial services that legacy on-premise deployments cannot replicate.
Pricing Analysis
Maintenance and firmware synchronization contracts drive lifetime value beyond initial SaaS subscriptions. Three-tier pricing structure across enterprise, professional, and basic levels separates API access depth from tenant portal customization. Pricing pressure stems from mid-sized vendors absorbing cyber insurance volatility to compete against REIT-preferred platforms. Independent operators in Texas and Florida exhibit lowest price elasticity, while emerging market buyers in India demand freemium entry tiers.
Supply Chain Analysis
Tariff exposure between the United States and China dominates hardware-software bundle economics for biometric access devices. Firmware development concentrates in the United States, Taiwan, and Israel, while cloud hosting infrastructure draws from domestic data sovereignty requirements. Single-source vulnerability persists in specialized machine learning talent for real-time pricing algorithms. Distribution runs through direct vendor sales teams serving multi-facility operators and value-added resellers targeting independent owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency mandates constitute a regulatory inflection that rewards vendors with pre-built audit infrastructure, compressing upgrade cycles for laggard platforms.
For Market Incumbents: Entrench platform stickiness through biometric hardware certification partnerships that synchronize firmware lifecycles with core software updates. Acquire specialized environmental monitoring vendors before climate-controlled unit expansion commoditizes their functionality. Vertical integration into payment processing deepens recurring revenue against fintech disintermediation threats. For New Entrants and Emerging Players: Maharashtra and Karnataka's minimal self-storage software penetration offers first-mover positioning before category standards crystallize. Target wine storage and document preservation operators with specialized environmental monitoring modules absent from generic property management suites. Pursue API-first architectures that attract third-party developers to build tenant-facing applications atop open platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed self-storage-native specialists seeking exit liquidity against horizontal property technology platform competition. Five-to-ten-year viability hinges on cloud migration completion rates among independent operators. Monitor FTC algorithmic pricing enforcement intensity as signal for compliance infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Hardware Certification Partnership | SiteLink Web Edition's channel alliances demonstrate how firmware synchronization locks in multi-year maintenance contracts. |
| API Marketplace Development | Open platform architectures attract third-party developers to extend ecosystem value without vendor R&D burden. |
| Environmental Monitoring Module Launch | Climate-controlled wine and document storage applications require specialized sensors absent from generic property software. |
| Payment Processing Integration | Embedded financial services deepen recurring revenue and reduce fintech disintermediation risk for platform vendors. |
| Geographic Expansion to India | Mumbai and Bangalore's rising apartment density creates latent demand for digitized facility operations before market saturation. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured interviews with facility owners, platform product managers, biometric hardware engineers, and payment processing integration specialists. Secondary validation drew from SEC filings of REIT-operators, PCI DSS certification databases, EU AI Act implementation guidance, and hyperscaler cloud infrastructure disclosure reports. Bottom-up facility adoption modeling and top-down market sizing triangulated volume estimates.
Calibration against historical cloud migration patterns and biometric hardware deployment timelines anchored projections across the analysis window. Segmentation dimensions modeled include deployment architecture, facility portfolio scale, integration complexity tier, and regional regulatory cluster. CAGRs were derived from slope analysis of adoption curves adjusted for compliance-driven upgrade acceleration. Forecast inputs incorporated FTC enforcement priority shifts and EU algorithmic transparency implementation pacing.
Practitioners should monitor state privacy law fragmentation and cyber insurance premium volatility for early signals of vendor margin compression. Forecasts reflect assumptions about cloud infrastructure cost trajectories and biometric hardware certification alignment feasibility. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Application Performance Management (APM) Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Federal Government Software Market
Software & Services
Appointment Scheduling Software Market
Software & Services
Category Management Software Market
Software & Services
3D Printing Medical Device Software Market
Software & Services
Global Process Mining Software Market
Software & Services
Global Cloud Testing Market
Software & Services
Event Management Software Market
Software & Services
Software Repository Market
Software & Services
Global Inspection Management Software Market
Software & Services
Global Testing Software Market
Software & Services
Global Managed Application Services Market
Software & Services
Human Capital Management (HCM) Saas Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Weather Forecast Software Market