
 Cushion Case Liner Market | 2026-2036
Cushion Case Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Cushion Case Liner Market Analytics
Aftermarket service revenue for cushion case liner refurbishment and replacement programs is fragmenting across institutional channels. Sealed Air Corporation leverages its protective packaging expertise to extend into specialty bedding logistics, while Pregis Corporation sustains a focused position in foam-based cushioning solutions for commercial end users. Sonoco Products Company anchors its competitiveness through integrated fiber-based manufacturing capabilities that serve hospitality procurement networks.
A cushion case liner constitutes a protective or decorative textile layer inserted between a cushion core and its outer case, typically manufactured from woven or non-woven substrates including polyester, cotton, foam, or nylon with specified denier weights and breathability coefficients. Foam material types command the dominant margin pool in commercial and hospitality segments where pressure-distribution performance determines procurement decisions, while polyester variants lead household volumes due to wash-cycle durability and cost efficiency. The custom size category represents the fastest-growing configuration as boutique hotel chains and healthcare facilities specify non-standard dimensions for specialized bedding systems.
ISO textile standards, the U.S. Consumer Product Safety Commission flammability protocols, and OEKO-TEX certification requirements shape material selection, testing expenditures, and market access conditions for cushion case liner suppliers operating across North America and Europe. REACH chemical restrictions in the European Union further constrain foam additive formulations and dye chemistry choices for exporters serving continental hospitality buyers. Stakeholders must monitor evolving state-level mattress and bedding component regulations in California and New York, where chemical disclosure mandates are tightening ahead of broader federal harmonization efforts.
Market Dynamics
Post-pandemic hospitality procurement teams are compressing linen refresh cycles while simultaneously tightening performance specifications for pressure-relief and flame-retardant properties, creating simultaneous volume expansion and margin pressure across supplier tiers.
Growth Catalysts
- REACH chemical compliance:European Union restrictions on foam additives are accelerating certified supplier consolidation, pushing hospitality buyers toward pre-qualified OEKO-TEX certified manufacturers.
- Healthcare pressure-distribution standards:Acute care facilities are mandating enhanced foam density specifications for patient bedding systems, expanding commercial-grade liner deployment.
- Germany's hospitality cluster:Premium hotel renovation activity in Berlin and Munich is concentrating demand for custom-dimension flame-retardant case liners.
Market Restraints
- Polyurethane feedstock volatility:Foam liner manufacturers face margin compression from petrochemical input cost swings without pass-through pricing power in contracted hospitality supply agreements.
- China-based textile substrate concentration:Woven polyester liner supply chains exhibit geographic concentration risk that procurement teams are struggling to diversify within cost constraints.
- California TB 117-2013 flammability testing:State-level chemical disclosure mandates create compliance friction for foam additive formulations that differ from federal standards.
Strategic Opportunities
- India hospitality infrastructure expansion:International hotel chains entering secondary Indian cities lack established local liner suppliers, creating first-mover positioning for certified exporters.
- RFID-enabled linen tracking convergence:Integration of textile RFID tags with case liner manufacturing is enabling outcome-based rental models for institutional buyers.
- EU Green Deal circular textile targets:Mandated recycled content thresholds for commercial textiles by 2030 favor suppliers with closed-loop fiber recovery capabilities.
Industry Challenges
- OEKO-TEX Standard 100 certification timelines:Extended laboratory testing queues for new foam formulations delay product launches and contract eligibility.
- Legacy ERP integration with traceability systems:Fiber-based manufacturers face capex burdens connecting shop-floor quality data to buyer-mandated supply chain transparency platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cushion Case Liner Market |
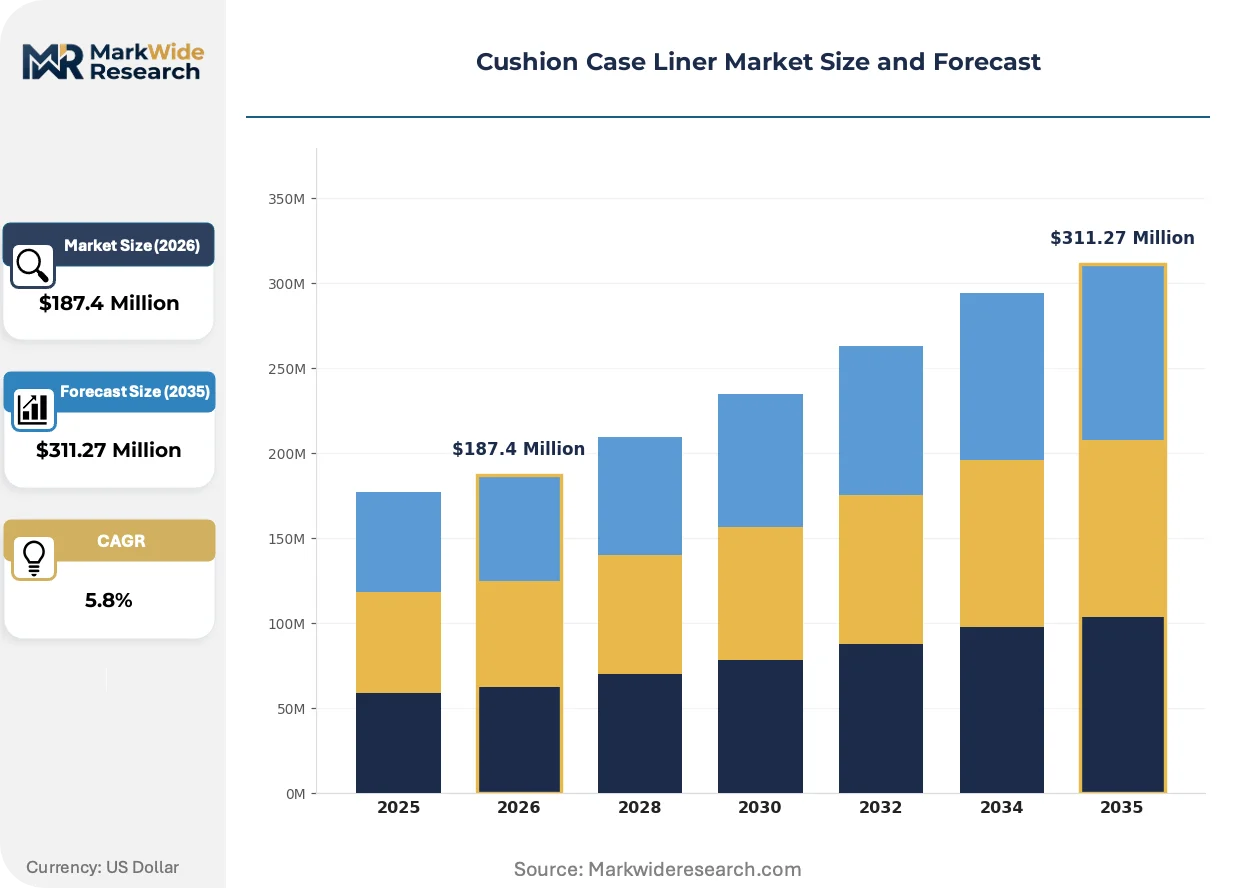
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyester, Cotton, Foam, Nylon Design Style: Traditional, Modern, Minimalist, Bohemian Size: Standard, King, Queen, Custom End User: Household, Hospitality, Retail, Commercial |
| Companies Covered | Sealed Air Corporation, Pregis Corporation, Sonoco Products Company, Smurfit Kappa Group, Mondi Group, International Paper Company, DS Smith Plc, WestRock Company, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cushion Case Liner Market Evolving Landscape
Digital design workflows and regulatory chemistry constraints are simultaneously compressing product development cycles and expanding certification requirements across the value chain.
Digital pattern-matching software is virtualizing the custom sizing process for boutique hospitality chains. Procurement teams in Germany and Japan are adopting cloud-based measurement platforms that transmit non-standard dimensions directly to manufacturing equipment. This compression of specification-to-production workflows is virtualizing traditional sampling and approval stages that previously extended lead times.
REACH Annex XVII restrictions on flame retardant formulations are forcing foam additive substitutions across European hospitality supply chains. Manufacturers serving German and French hotel groups are reformulating polyurethane chemistry to maintain certified performance without restricted halogenated compounds. The regulatory pressure is concentrating supplier relationships toward compounders with in-house toxicology testing capabilities.
Hospital procurement departments are unbundling liner replacement from full bedding system contracts. Acute care facilities in the United States and Japan are establishing direct supplier relationships for refresh cycles that were previously managed through mattress OEMs. This channel disintermediation is most visible in tertiary care networks where capital equipment and consumable budgets operate under separate governance structures.
Cushion Case Liner Market Segmentation
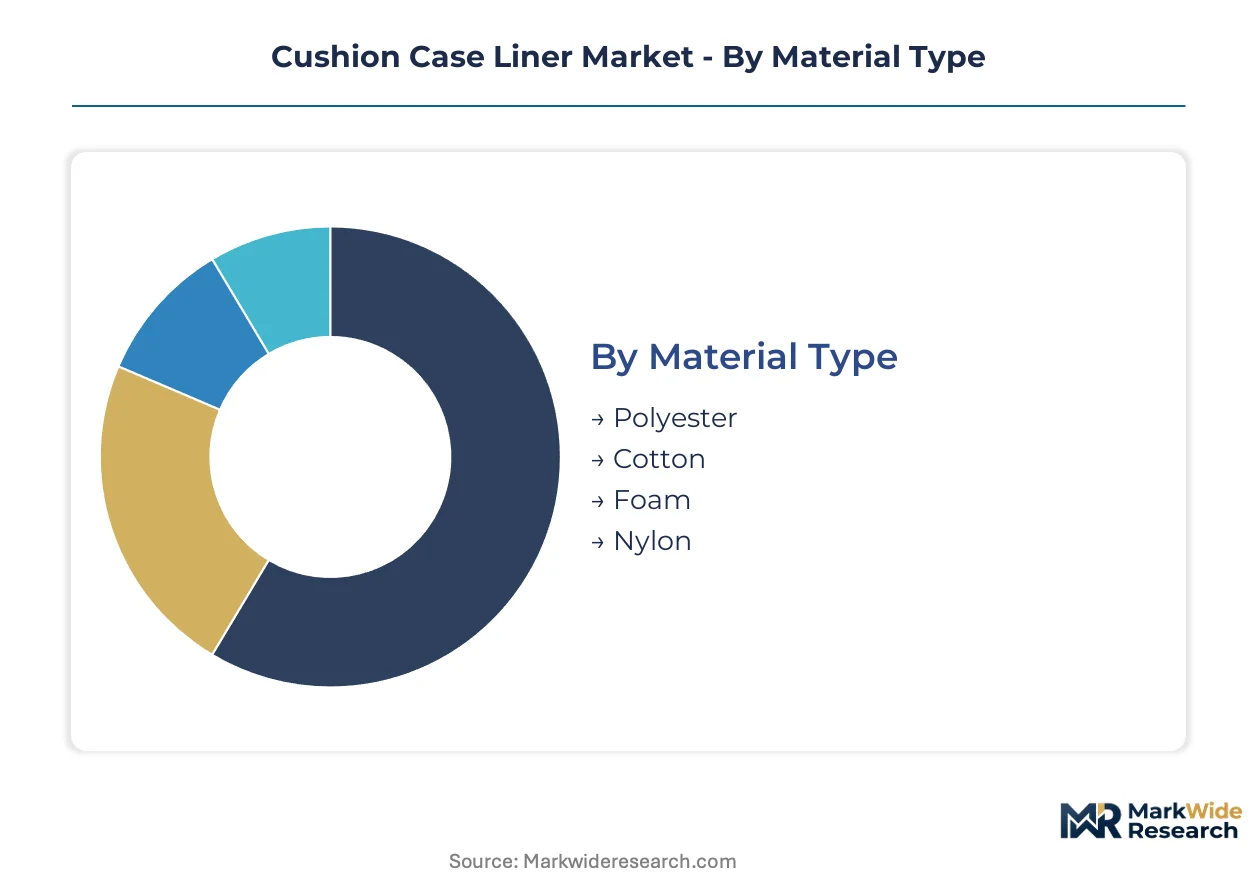
Procurement teams in hospitality and healthcare channels navigate distinct performance specifications across material grades and dimensional configurations. Segmentation discipline separates volume-driven household demand from margin-intensive commercial contracts where flame-retardant certification and pressure-distribution standards dominate supplier selection.
Material Type:
Polyurethane chemistry variations and woven substrate specifications create tiered performance profiles across institutional procurement channels.
- Foam:High-density polyurethane formulations deliver calibrated pressure-distribution performance for acute care bedding systems. German hospital networks and Japanese hospitality chains specify certified foam densities that exceed residential durability benchmarks by substantial margins.
- Polyester:Synthetic woven substrates engineered for commercial wash-cycle endurance anchor household volume procurement. United States mass-market retailers source polyester variants from concentrated textile manufacturing clusters in Asia-Pacific supply corridors.
- Cotton:Natural fiber construction appeals to sustainability-positioned hospitality brands seeking OEKO-TEX Standard 100 differentiation.
- Nylon:Abrasion-resistant synthetic blends serve high-traffic commercial seating applications with extended replacement intervals.
The dominant share belongs to Foam, while Polyester is closing the gap fastest through expanded hospitality refresh programs.
Design Style:
Aesthetic differentiation tracks renovation cycles across boutique hotel segments and residential replacement demand.
- Modern:Clean-line geometric patterns align with contemporary hospitality interiors in Berlin and Tokyo design-forward properties. Procurement teams specify machine-washable substrates that maintain dimensional stability across institutional laundering protocols.
- Traditional:Ornate woven textures and classical patterning concentrate in heritage hospitality properties and residential segments seeking timeless aesthetic positioning.
- Minimalist:Reduced visual complexity and neutral palettes serve Scandinavian-influenced commercial interiors and healthcare environments prioritizing clinical cleanliness perception.
- Bohemian:Artisanal-inspired textures and eclectic patterning target lifestyle hospitality brands and residential segments emphasizing handcrafted positioning.
Modern styling commands premium positioning in contract hospitality, while Minimalist designs are expanding most quickly through healthcare facility standardization.
Size:
Dimensional standardization confronts bespoke specification requirements across specialized bedding systems.
- Custom:Non-standard dimensions specified by boutique hotel chains and acute care facilities require direct-to-equipment digital measurement workflows. German and Japanese procurement teams transmit specifications through cloud-based platforms that bypass traditional sampling stages.
- Standard:Conventional sizing serves mass-market retail and budget hospitality segments with inventory efficiency priorities.
- King:Oversized configurations align with premium residential and upscale hospitality positioning in North American markets.
- Queen:Mid-scale dimensional specification balances space efficiency with comfort perception across commercial lodging tiers.
Standard sizing retains volume leadership, though Custom configurations are gaining share fastest through healthcare unbundling of liner procurement from mattress OEM contracts.
End User:
Channel governance structures determine specification authority and replacement cycle frequency.
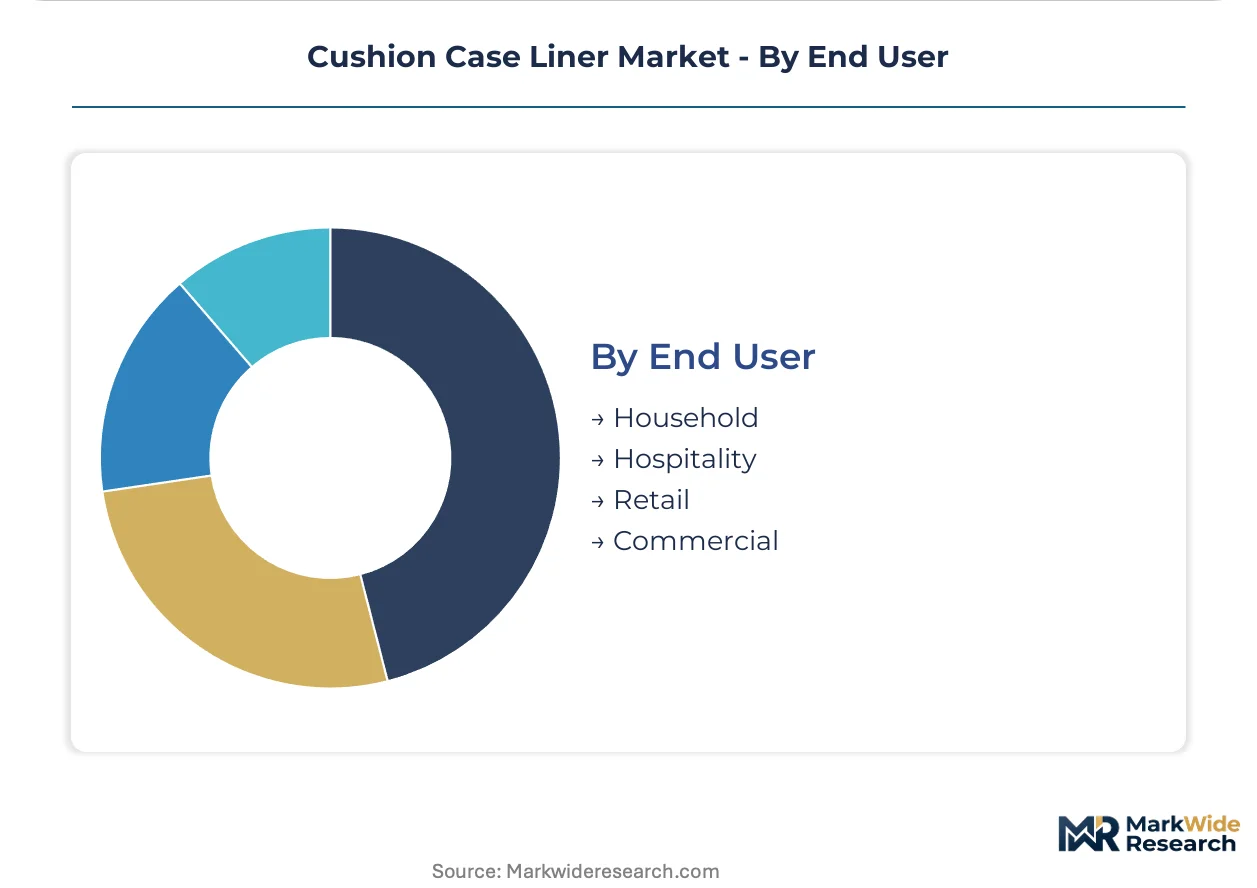
- Hospitality:Post-pandemic occupancy normalization in Germany, the United States, and Japan compresses linen refresh cycles while tightening flame-retardant and pressure-relief specifications. Procurement teams consolidate supplier relationships toward OEKO-TEX certified manufacturers with REACH-compliant foam chemistry.
- Household:Cost-efficient polyester variants dominate residential replacement demand through mass-market retail distribution.
- Commercial:Office and institutional seating applications specify abrasion-resistant substrates with extended durability warranties.
- Retail:Branded liner programs serve aftermarket replacement and accessory positioning through specialty bedding channels.
Hospitality channels concentrate margin pool capture, while Commercial segments are expanding most quickly through facility management outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies: German hospital procurement teams absorb premium pricing for certified flame-retardant foam liners, while United States mass-market retailers drive polyester volumes through cost-optimized sourcing from Asia-Pacific supply corridors.
United States
Post-pandemic hospitality occupancy normalization compresses linen refresh cycles across premium hotel chains. The U.S. Consumer Product Safety Commission flammability protocols and California TB 117-2013 chemical disclosure mandates shape foam additive formulations. New York City and Los Angeles concentrate procurement authority for institutional bedding contracts.
Germany
REACH Annex XVII restrictions on halogenated flame retardants accelerate certified supplier consolidation toward OEKO-TEX Standard 100 manufacturers. Berlin and Munich renovation activity concentrates demand for custom-dimension case liners with certified pressure-distribution performance. German hospital networks specify foam densities exceeding residential benchmarks.
Japan
Acute care facilities mandate enhanced foam density specifications for patient bedding systems under METI-influenced healthcare procurement standards. Tokyo and Osaka hospitality chains drive premium-grade liner demand with certified flame-retardant properties. Japanese tertiary care networks unbundle liner procurement from mattress OEM contracts.
India
International hotel chains entering secondary cities lack established local liner suppliers, creating positioning opportunities for certified exporters. BIS textile standards and state-level hospitality infrastructure investments shape procurement specifications. Mumbai and Bangalore concentrate demand for commercial-grade bedding components.
United Kingdom
Heritage hospitality properties in London and Edinburgh sustain demand for traditional woven textures with institutional wash-cycle durability. UKCA marking requirements and EU Green Deal circular textile targets influence supplier selection. London procurement teams specify OEKO-TEX certified materials for boutique hotel renovation programs.
Cushion Case Liner Market Competitive Landscape
Protective packaging specialists and fiber-based manufacturers split the market across divergent capability requirements. The vendor base concentrates around three strategic archetypes: foam chemistry compounders with in-house toxicology testing, integrated fiber converters serving hospitality networks, and protective packaging multinationals leveraging logistics expertise. Competitive moves center on REACH-compliant formulation partnerships and RFID-enabled traceability system integration.
Within the protective packaging tier, Sealed Air Corporation exemplifies logistics-to-bedding extension strategies, while Pregis Corporation occupies a position focused on foam-based cushioning solutions. Among integrated fiber specialists, Sonoco Products Company anchors competitiveness through manufacturing capabilities aligned with hospitality procurement requirements. These three entities represent distinct archetype positions without implying specific market share or strategic action claims.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis Corporation |
| Sonoco Products Company |
| Smurfit Kappa Group |
| Mondi Group |
| International Paper Company |
| DS Smith Plc |
| WestRock Company |
| Huhtamaki Oyj |
| Others |
Value Network & Pricing Analysis
Polyurethane feedstock volatility stemming from petrochemical input cost swings determines both margin compression in contracted hospitality supply agreements and the geographic distribution of foam liner manufacturing capacity. This raw material uncertainty widens pricing spreads between certified OEKO-TEX manufacturers and uncertified competitors while accelerating procurement consolidation toward pre-qualified supplier networks.
Pricing Analysis
Aftermarket refurbishment and replacement service revenue drives lifetime value capture across institutional channels. Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX certified flame-retardant foam liners from REACH-compliant uncertified variants and basic polyester household grades. Cost compression in standard-tier hospitality contracts is intensifying because of locked-in annual pricing clauses that prevent petrochemical pass-through. Budget hospitality segments exhibit highest price sensitivity, while German hospital procurement teams absorb premium positioning for certified pressure-distribution performance.
Supply Chain Analysis
Tariff exposure between China and the United States dominates sourcing decisions for woven polyester substrate procurement. Manufacturing concentrates in China, Vietnam, and Bangladesh for textile substrates, while foam compounding clusters in Germany, Japan, and the United States serve premium hospitality and healthcare specifications. Raw material flows draw from TDI/MDI petrochemical feedstocks, cotton fiber bourses, and synthetic polymer resin markets. Single-source vulnerability in China-based textile substrate concentration drives procurement diversification efforts toward Vietnam and India. Distribution runs through hospitality procurement networks, healthcare GPO contracts, and mass-market retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cushion case liner market operates as a defensive-moat story anchored in regulatory entrenchment. REACH and OEKO-TEX certification requirements create substantial switching costs for hospitality buyers while consolidating supplier relationships toward compounders with in-house toxicology testing capabilities.
For Market Incumbents: Entrench market position through backward integration into polyurethane foam compounding and captive supply of certified flame-retardant additive formulations. Expand OEKO-TEX Standard 100 certification coverage across product lines to defend against emerging specialty bedding logistics entrants. Prioritize ERP integration with RFID-enabled traceability platforms to capture outcome-based rental model opportunities from institutional buyers. For New Entrants and Emerging Players: Build out white-space positioning in India's secondary city hospitality infrastructure where international hotel chains lack established local liner suppliers. Target acute care facility unbundling trends in Japanese and United States tertiary care networks as the most penetrable procurement channel. Pursue cloud-based digital measurement platform partnerships as the primary go-to-market angle for custom-dimension specification workflows. For Investors and Strategic Acquirers: EU Green Deal circular textile targets reshape the acquisition landscape toward suppliers with closed-loop fiber recovery capabilities and recycled content threshold compliance infrastructure. Five-to-ten year viability favors integrated fiber converters over pure-play foam compounders given chemistry regulatory trajectory. Target acquisition archetype: mid-cap OEKO-TEX certified manufacturers with established hospitality procurement network relationships. Signal to monitor: California TB 117-2013 chemical disclosure mandate expansion to additional states as inflection indicator for compliance capability premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Partnership | Secures market access for German and French hospitality procurement teams under Annex XVII restrictions. |
| RFID-Enabled Traceability Integration | Enables outcome-based rental models for institutional buyers requiring linen lifecycle tracking. |
| India Market Entry | Captures first-mover positioning in secondary cities where international hotel chains expand infrastructure. |
| Closed-Loop Fiber Recovery Investment | Aligns supplier capabilities with EU Green Deal mandated recycled content thresholds for commercial textiles. |
| Cloud-Based Custom Sizing Platform | Virtualizes specification-to-production workflows for boutique hotel chains and healthcare facilities. |
Research Methodology
Desk research of customs trade databases, hospitality procurement contract filings, and textile chemical regulatory repositories preceded structured interviews with hospitality procurement directors, foam compounding technical leads, healthcare GPO contract managers, and OEKO-TEX certification laboratory directors. Primary fieldwork combined with secondary validation through SEC filings of protective packaging multinationals, REACH Annex XVII amendment tracking, and hospital bedding system tender databases. Bottom-up volume modeling across material type and end-user segments triangulated against top-down macroeconomic indicators for commercial textile demand.
Assumptions held fixed include REACH regulatory enforcement intensity, petrochemical feedstock price band ranges, and hospitality occupancy normalization trajectories across the analysis window. Segmentation dimensions modeled encompass material chemistry grade, flame-retardant certification tier, dimensional configuration standardization, and channel governance structure. CAGRs derived from logistic adoption curves for RFID-enabled linen tracking and replacement cycle compression rates in post-pandemic hospitality. Industry-specific inputs incorporated foam density specification trends in acute care facilities and boutique hotel renovation pipeline data from Berlin, Munich, and Tokyo.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by China-based textile substrate manufacturers or accelerated chemical disclosure mandate harmonization beyond California and New York would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Corrugated Wraps Market
Packaging Materials
PCR Packaging Market
Packaging Materials
Kraft Packaging Market
Packaging Materials
Carded Packaging Market
Packaging Materials
Cavitated Films Market
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Face Stock Films Market
Packaging Materials
Punnet Packaging Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Packaging Suction Cups Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Cold Chain Packaging Materials Market
Packaging Materials
Polystyrene Packaging Market
Packaging Materials
Packaging Lacquering Market
Packaging Materials
Cutting Tool Packaging Market