
 Tube Packaging Market | 2026-2036
Tube Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Tube Packaging Market Intelligence
Pharmaceutical buyers are redrawing procurement priorities toward barrier-enhanced and child-resistant tube formats. Albéa Group leverages European manufacturing scale to dominate high-barrier laminated tubes for prescription topicals. Essel Propack Ltd. anchors Asian supply networks with specialized oral-care and pharma tube capacity. Hoffmann Neopac AG differentiates through precision metal tube engineering for sensitive formulations.
Tube packaging denotes cylindrical primary containers—extruded, drawn, or rolled from plastics, aluminum, or multi-layer laminates—typically ranging from 10 ml to 300 ml capacity, sealed at one end and fitted with a dispensing closure at the other, designed to protect semi-solid and viscous products from contamination, oxidation, and moisture ingress across shelf-life periods. Laminated tubes lead value contribution due to superior oxygen and light barrier properties that command premium positioning in pharmaceutical and cosmeceutical segments. Plastic tubes represent the broadest volume base, sustained by cost efficiency and design flexibility in mass personal care applications. Aluminum tubes retain specialized demand for reactive pharmaceutical creams requiring absolute inertness and collapsibility.
FDA enforces stringent extractables and leachables testing for pharmaceutical tube materials, while EMA's Medical Device Regulation extends conformity requirements to drug-device combination tubes such as metered-dose applicators. REACH chemical restrictions and EU Green Deal circularity targets are forcing material transitions toward mono-material recyclable structures and bio-based barrier layers. Stakeholders must monitor evolving Extended Producer Responsibility frameworks and recyclability certification schemes that will determine market access eligibility across European and North American supply chains.
Market Dynamics
Pharmaceutical stability mandates are compressing material qualification timelines while forcing capital redeployment toward barrier-certified tube formats. FDA extractables-leachables testing protocols now govern supplier selection decisions across North American contract manufacturing.
Growth Catalysts
- EMA Medical Device Regulation:Metered-dose tube applicators for topical drug-device combinations now require conformity assessment, expanding specialized tube demand across German and Swiss pharmaceutical corridors.
- India's PLI scheme for packaging:Capital subsidies for domestic manufacturing capacity are attracting laminated tube investments to serve oral-care and personal care export demand.
- Mono-material recyclable structures:Brand sustainability commitments are pulling demand toward polyethylene-only barrier tubes that maintain oxygen protection without aluminum foil layers.
Market Restraints
- Aluminum price volatility:Reactive pharmaceutical cream formulations require absolute inertness, but London Metal Exchange aluminum pricing swings compress margin predictability for metal tube converters.
- German supplier concentration:High-barrier laminate film production clusters around three specialized extrusion facilities, creating single-source vulnerability for pharmaceutical tube manufacturers.
- REACH chemical restrictions:ECHA substance-of-very-high-concern listings are forcing reformulation of conventional adhesive layers, extending material qualification cycles.
Strategic Opportunities
- Brazil's ANVISA traceability mandates:Serialized tube coding requirements for pharmaceutical exports create demand for integrated printing and authentication capabilities.
- Bio-based barrier layers:Cellulose-derived oxygen barriers are converging with conventional extrusion equipment, enabling renewable-content claims without capital-intensive line replacement.
- Direct-to-clinic distribution:Hospital and specialty pharmacy procurement consolidation is opening channel space for unit-dose tube formats bypassing traditional wholesale.
Industry Challenges
- Extractables-leachables analytical capacity:FDA pharmaceutical tube material testing requires specialized chromatography expertise that resides in limited third-party laboratories, extending qualification timelines.
- Legacy line integration:Converting existing tube-sealing equipment for mono-material polyethylene structures demands mechanical retrofits that interrupt production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tube Packaging Market |
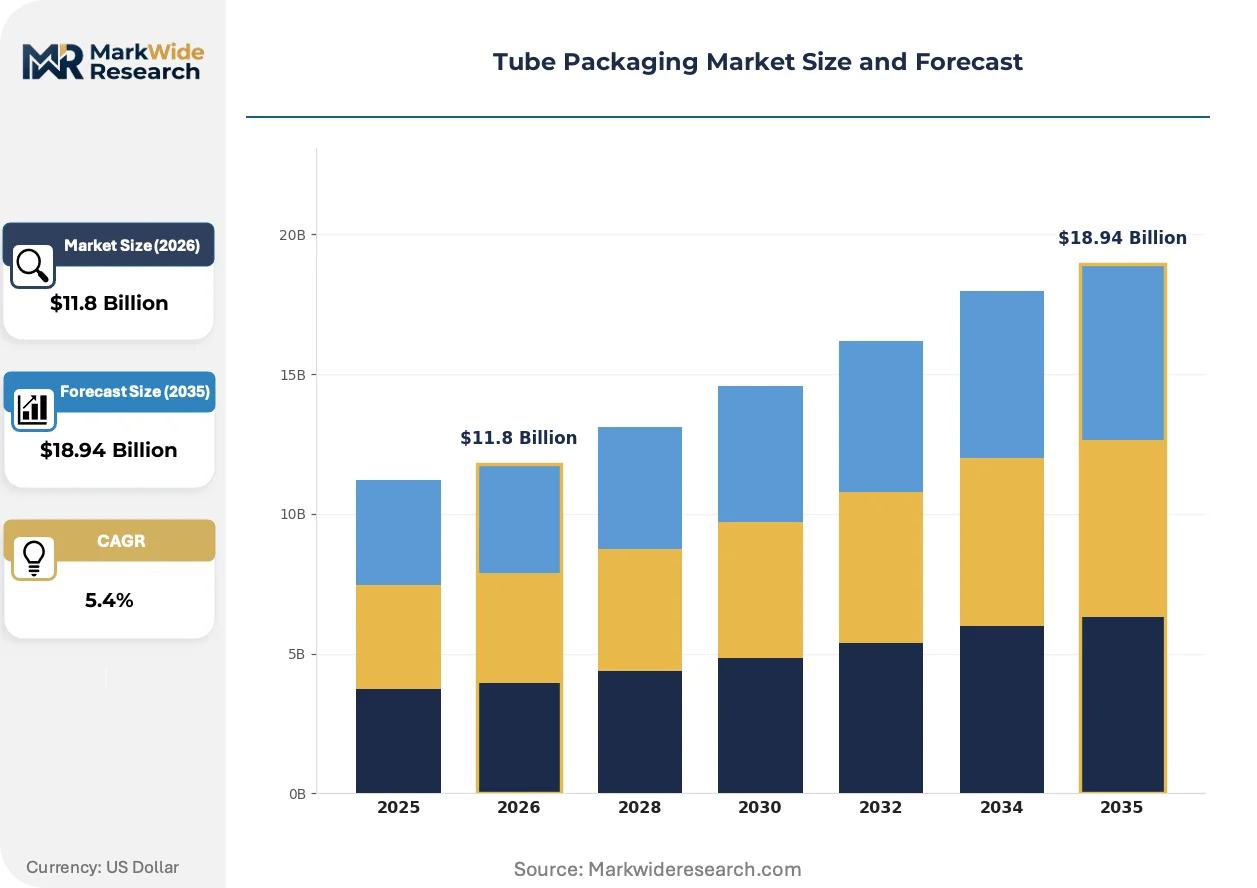
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Tubes, Aluminum Tubes, Laminated Tubes, Paper Tubes End User: Cosmetics, Pharmaceuticals, Food & Beverage, Personal Care Size: Small, Medium, Large, Extra Large Closure Type: Screw Cap, Flip Top, Nozzle, Easy Open |
| Companies Covered | Albéa Group, Amcor plc, Essel Propack Ltd., ALLTUB, Hoffmann Neopac AG, Berry Global Inc., Huhtamaki Oyj, Sonoco Products Company, ALPLA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tube Packaging Market Strategic Shifts & Innovations
Material science advances are collapsing the performance gap between sustainable and conventional barrier structures. Regulatory chemical restrictions are accelerating substitution timelines faster than equipment depreciation cycles.
Ethylene vinyl alcohol copolymer barrier layers are displacing aluminum foil in mid-performance pharmaceutical tubes. Oral-care brands in Germany and Switzerland are qualifying these structures for oxygen-sensitive formulations. The shift is compressing aluminum tube demand in non-reactive applications while expanding EVOH extrusion capacity.
EU Green Deal circularity targets are mandating recyclability certification for primary packaging placed on European markets. Tube converters must demonstrate mono-material compatibility or face Extended Producer Responsibility fee penalties. Pharmaceutical and cosmeceutical segments are responding with polyethylene-only laminate specifications that trade some barrier performance for recycling stream acceptance.
Hospital procurement consolidation is compressing supplier rosters and demanding integrated tube-plus-applicator formats. Specialty pharmaceutical buyers are shifting from component sourcing to finished drug-device combination procurement. This pattern concentrates most visibly in German and Swiss hospital networks where pharmacy centralization has advanced furthest.
Tube Packaging Market Segmentation
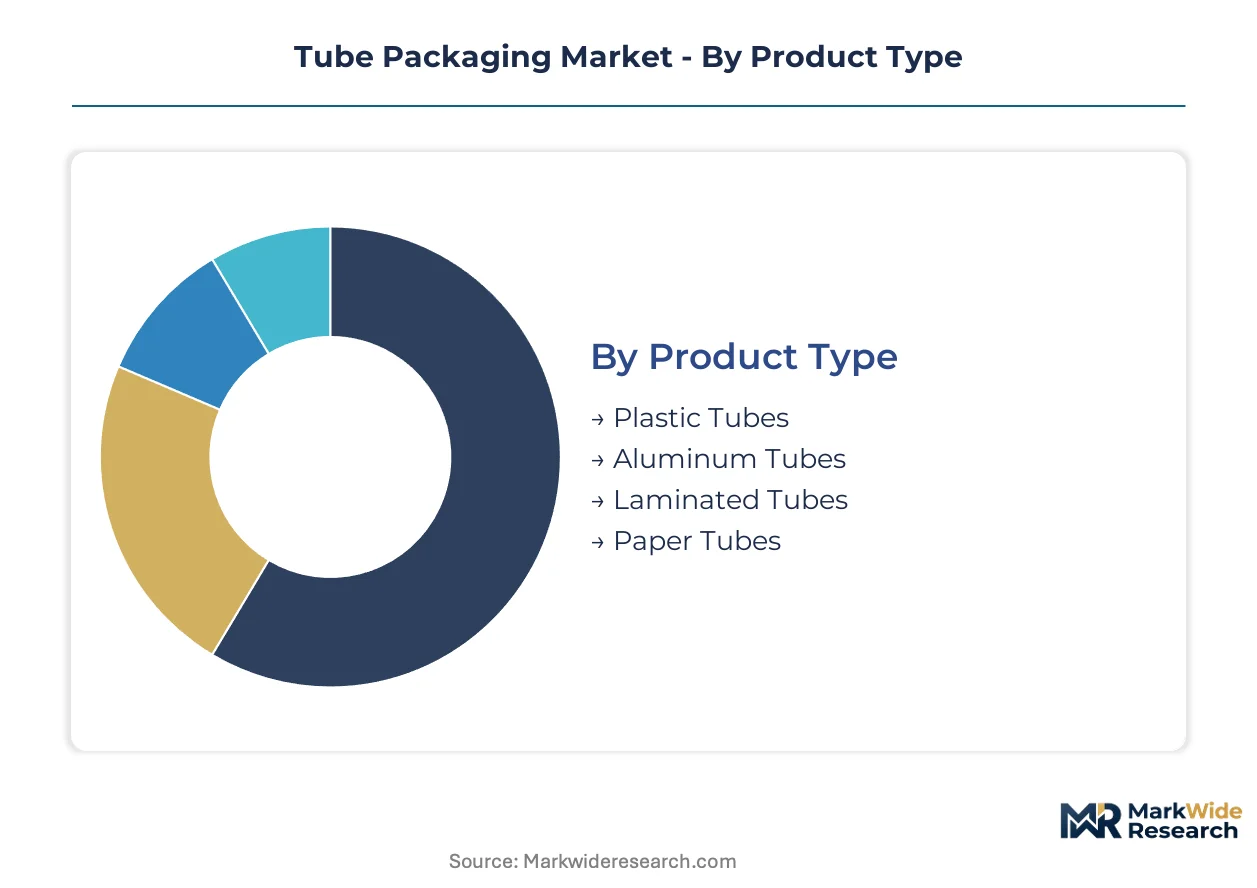
Tube packaging segmentation reveals divergent supply chain architectures. Pharmaceutical and personal care buyers impose distinct barrier specifications that reshape converter capacity allocation across material categories.
Product Type:
Domestic production concentrates on plastic and aluminum formats serving regional personal care brands. Export-oriented capacity clusters around laminated tubes for pharmaceutical multinationals requiring FDA and EMA qualification.
- Laminated Tubes:Multi-layer structures combine polyethylene, aluminum foil, and adhesive barriers to achieve oxygen transmission rates below 0.1 cc/m²/day. German pharmaceutical corridors and Swiss contract manufacturers specify these formats for prescription topicals requiring extended stability. EMA Medical Device Regulation conformity assessments now govern metered-dose applicator sourcing.
- Plastic Tubes:Mono-material polyethylene structures dominate mass personal care applications with cost positions 40% below laminated alternatives. India's oral-care manufacturing belt and Southeast Asian cosmetic converters drive volume procurement of these formats. Brand sustainability mandates are accelerating transitions toward recyclable-only specifications.
- Aluminum Tubes:Drawn metal cylinders provide absolute inertness for reactive pharmaceutical creams. London Metal Exchange price volatility constrains margin predictability for European and North American converters.
- Paper Tubes:Kraft-based cylindrical containers serve dry cosmetic powders and solid formulations. Limited moisture resistance restricts adoption to shelf-stable applications.
Laminated tubes command the established base. The steepest expansion runs through plastic tubes as mono-material recyclability gains procurement priority.
End User:
Cost tier separation distinguishes premium pharmaceutical specifications from mass-market personal care procurement. Barrier certification requirements widen the pricing spread between segments.
- Pharmaceuticals:FDA extractables-leachables testing and EMA stability mandates govern primary packaging selection. Unit-dose dispensing formats for topical drug-device combinations require specialized tube-plus-applicator integration. German hospital network consolidation is compressing supplier rosters toward qualified converters.
- Personal Care:Oral-care and skincare brands in India and Southeast Asia specify high-volume plastic tube procurement with design flexibility for shelf differentiation. PLI scheme subsidies are attracting laminated tube investments to serve export demand.
- Cosmetics:Premium positioning emphasizes tactile and visual differentiation through specialized coatings and metallization. European luxury brands prioritize aesthetic customization over barrier performance.
- Food & Beverage:Condiment and puree applications require food-contact compliance without pharmaceutical-grade documentation. Limited segment penetration relative to rigid alternatives.
Pharmaceuticals anchor the premium tier. Personal care delivers volume scale fastest.
Size:
Application requirements dictate dimensional spread from travel formats to institutional dispensing. Pharmaceutical unit-dose trends favor smaller capacities while food service drives large-format adoption.
- Small:10-30 ml capacities serve ophthalmic ointments and sample cosmetics. Precision dosing requirements dominate pharmaceutical specification.
- Medium:50-100 ml range captures standard toothpaste and skincare cream formats. Highest production volume across converter portfolios.
- Large:150-200 ml structures serve family-size personal care and professional salon applications. Emerging demand from direct-to-clinic distribution channels.
- Extra Large:250-300 ml capacities address institutional food service and industrial adhesive dispensing. Limited pharmaceutical applicability.
Medium sizes command production throughput. Small formats gain share through unit-dose pharmaceutical expansion.
Closure Type:
Customer type separation distinguishes child-resistant pharmaceutical mandates from convenience-driven personal care preferences. Regulatory requirements increasingly govern closure specification.
- Screw Cap:Threaded closures provide resealability for multi-use pharmaceutical and cosmetic applications. German and Swiss buyers specify torque consistency for automated filling lines.
- Flip Top:Hinged lids enable single-hand dispensing for oral-care and on-the-go cosmetics. India's manufacturing belt standardizes this format for export markets.
- Nozzle:Precision orifices control viscous pharmaceutical cream deposition. Metered-dose applicators for drug-device combinations require calibrated flow engineering.
- Easy Open:Reduced-force access aids elderly and disabled users. Accessibility regulations in European markets are expanding specification requirements.
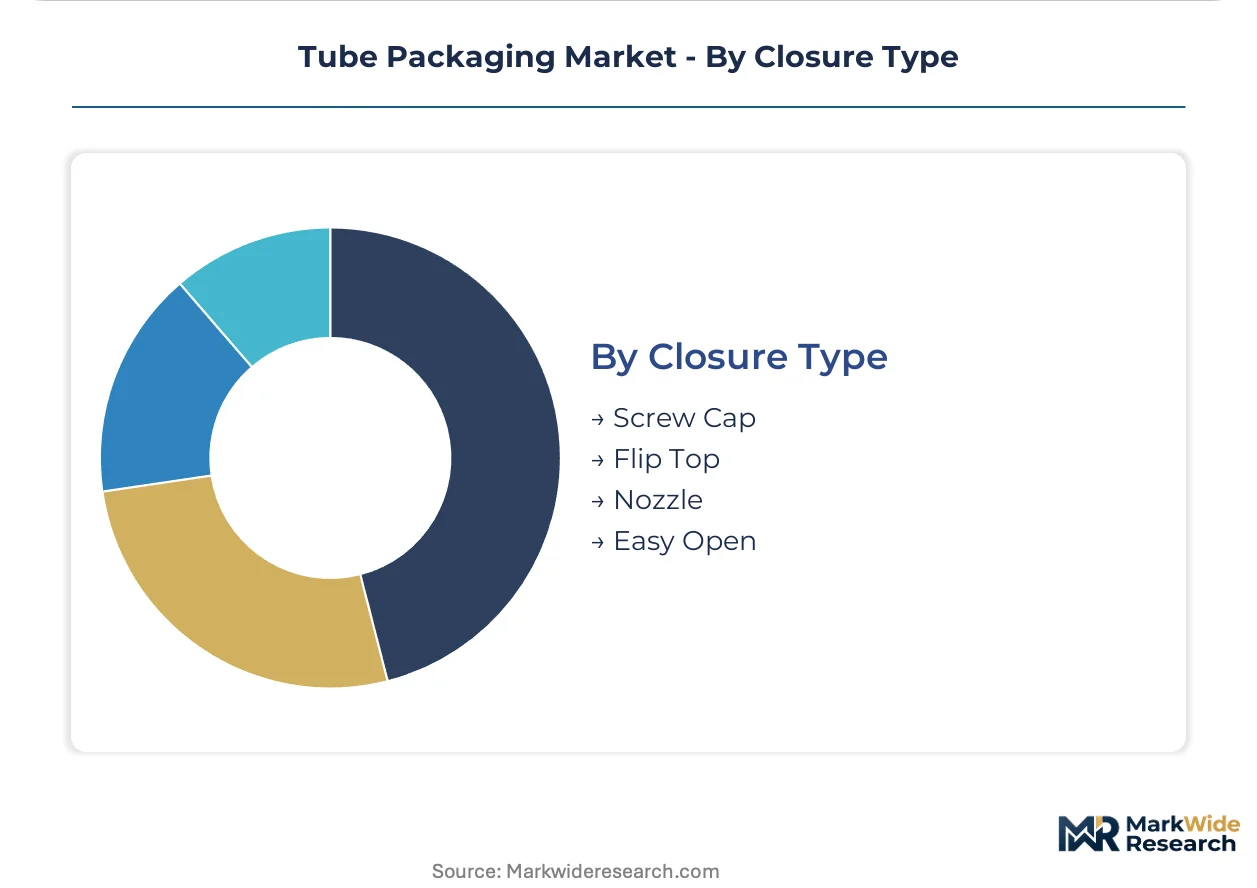
Screw caps retain the installed base. Flip top configurations expand fastest through oral-care volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports laminated tube capacity to European pharmaceutical buyers while Germany ships high-barrier formats to Swiss contract manufacturers. Trade corridors concentrate converter investments around FDA and EMA qualification hubs.
United States
FDA extractables-leachables testing mandates are compressing supplier qualification timelines for topical drug-device combinations. The IRA domestic manufacturing incentives are pulling laminated tube investments toward Puerto Rico and New Jersey pharmaceutical corridors. New Jersey hosts concentrated contract manufacturing demand for unit-dose dispensing formats.
Germany
EMA Medical Device Regulation conformity assessments are expanding specialized tube-plus-applicator procurement from Swiss hospital networks. REACH chemical restrictions are forcing adhesive layer reformulations that extend material qualification cycles. The Baden-Württemberg pharmaceutical corridor anchors high-barrier laminate production for prescription topicals.
India
PLI scheme capital subsidies are attracting laminated tube capacity to serve oral-care export demand from Gujarat and Maharashtra. CDSCO stability documentation requirements are tightening for pharmaceutical tube exports to regulated markets. The Mumbai-Pune manufacturing belt concentrates personal care tube production for Southeast Asian buyers.
Switzerland
Swissmedic drug-device combination oversight is driving precision tube-applicator integration for metered-dose topical delivery. Hospital pharmacy centralization is compressing supplier rosters toward qualified converters with EMA certification. Basel-Zurich corridor demand concentrates on barrier-certified formats for sensitive formulations.
Brazil
ANVISA serialized coding mandates for pharmaceutical exports are creating demand for integrated tube printing and authentication capabilities. Import substitution policies are pulling laminated tube investments toward São Paulo state for regional personal care supply. The São Paulo manufacturing belt is expanding capacity for Latin American oral-care brand supply.
Tube Packaging Market Key Industry Players
Listed leaders compete with private specialists across barrier certification and geographic coverage dimensions. The vendor base organizes around three strategic archetypes: European high-barrier specialists, Asian volume-scale converters, and diversified packaging conglomerates with cross-material portfolios. Competitive moves concentrate on EMA qualification capacity expansion and backward integration into laminate film extrusion.
Among European specialists, Hoffmann Neopac AG and Albéa Group occupy positions anchored by pharmaceutical-grade barrier engineering and EMA-certified production networks. Essel Propack Ltd. exemplifies the Asian volume-scale archetype with concentrated capacity serving oral-care export demand. Amcor plc represents the diversified conglomerate model with cross-regional laminate and plastic tube portfolios spanning multiple end-use qualifications.
| Leading Market Players |
|---|
| Albéa Group |
| Amcor plc |
| Essel Propack Ltd. |
| ALLTUB |
| Hoffmann Neopac AG |
| Berry Global Inc. |
| Huhtamaki Oyj |
| Sonoco Products Company |
| ALPLA |
| Others |
Cost & Logistics Intelligence
Converter scale economies in high-barrier laminate extrusion determine supply concentration and price floors across pharmaceutical tube procurement. German and Swiss buyers face elevated entry thresholds as multi-layer film qualification cycles absorb capital that smaller competitors cannot deploy.
Pricing Analysis
Three-generation pricing stratification separates aluminum foil-based barriers from EVOH copolymer alternatives and emerging bio-based structures. Pharmaceutical buyers pay premium differentials for FDA extractables-leachables certification tiers, while personal care procurement gravitates toward standard-grade mono-material polyethylene. Cost compression in mid-tier laminated formats is intensifying because EVOH extrusion capacity expansion outpaces specialized converter growth. Oral-care brands in India exhibit highest price sensitivity; German hospital networks show least elasticity due to regulatory compliance mandates.
Supply Chain Analysis
German high-barrier film extrusion facilities create single-source chokepoints for pharmaceutical tube manufacturers serving EMA-regulated markets. Raw material flows draw from Saudi polyethylene resin, Chinese aluminum foil rolling capacity, and Japanese EVOH polymer production. Commodity price volatility in London Metal Exchange aluminum contracts generates margin unpredictability for metal tube converters. Distribution runs through qualified converter networks with direct pharmaceutical filling-line integration rather than distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tube packaging fragmentation creates entry niches as EMA Medical Device Regulation splits demand between drug-device combination specialists and commodity personal care suppliers.
For Market Incumbents: Consolidate backward integration into captive laminate film extrusion to defend against emerging Asian competitors with PLI-subsidized capacity. Albéa Group's European manufacturing scale and Hoffmann Neopac's precision metal engineering demonstrate defensible positioning through certification depth and equipment specialization.
For New Entrants and Emerging Players: Anchor in Brazil's ANVISA traceability mandate implementation as serialized coding requirements outstrip incumbent printing capacity. Direct-to-clinic distribution channels for unit-dose pharmaceutical formats offer white-space penetration with lower regulatory qualification barriers than wholesale supply.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among EMA-certified tube-plus-applicator specialists with hospital network contracts. Long-term viability favors converters with demonstrated FDA and EMA dual qualification. Watch bio-based barrier layer technical validation as inflection signal for sustainable packaging premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laminate Film Extrusion | German pharmaceutical corridor demand concentrates around converters with captive high-barrier supply. |
| EMA Medical Device Regulation Certification | Swiss hospital network consolidation favors qualified tube-applicator integration specialists. |
| Mono-Material Recyclable Structure Development | EU Green Deal circularity targets mandate polyethylene-only formats for market access. |
| ANVISA Traceability Capability Investment | Brazilian pharmaceutical export requirements create integrated printing and authentication demand. |
| Bio-Based Barrier Layer Qualification | Cellulose-derived oxygen barriers enable renewable-content claims without capital-intensive line replacement. |
Research Approach
Cross-validation between converter production data and pharmaceutical buyer procurement records anchors the qualitative findings in this study. Primary interviews with tube manufacturing executives, regulatory affairs specialists at FDA and EMA, hospital pharmacy procurement managers, and personal care brand supply chain directors combined with secondary sources including FDA 510(k) filings, EMA conformity assessment databases, CDSCO export documentation, and trade customs data. Bottom-up capacity modeling and top-down demand estimation provided triangulation across the analysis window.
Sensitivity analysis around aluminum price volatility and EVOH polymer supply assumptions shaped the forecast framework. Segmentation dimensions modeled include material technology generation, barrier performance tier, end-use regulatory intensity, and regional qualification cluster. CAGRs derived from installed capacity utilization trajectories and buyer procurement cycle analysis. Pharmaceutical stability mandate timelines and sustainability certification adoption curves served as industry-specific demand drivers.
Underlying assumptions cover EMA regulatory implementation pace and REACH chemical restriction enforcement, with deviation risk concentrated in aluminum commodity price swings and bio-based barrier technical validation timelines. Practitioners should keep alternative scenarios live as EU Extended Producer Responsibility fee structures and Indian PLI scheme disbursement schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Global Liquid Packaging Market
Packaging Materials
US Packaging Market
Packaging Materials
Single Dose Detergent Packaging Market
Packaging Materials
Twist Tie Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Window Packaging Market
Packaging Materials
North America Single-Use Packaging Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Child Resistant Zipper Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Gift Wrapping Product Market