
 Squeeze Tube Market | 2026-2036
Squeeze Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Squeeze Tube Market Analytics
Buyer concentration in the squeeze tube market is shifting as mid-sized cosmetics brands fragment demand while pharmaceutical contract manufacturers consolidate procurement volumes. Berry Global Inc. leverages its North American manufacturing footprint to serve high-volume personal care accounts. Huhtamaki OYJ anchors European laminate tube supply through specialized barrier technology. Amcor Limited competes on multi-material platform breadth across pharmaceutical and food-grade specifications.
A squeeze tube is a cylindrical collapsible container, typically manufactured from polyethylene, aluminum, or multi-layer laminates with wall thicknesses of 0.30–0.50 mm, designed for controlled dispensing of viscous or semi-liquid products. The laminated segment leads value contribution due to superior oxygen and moisture barrier properties demanded by pharmaceutical ointments and retinol skincare formulations. Plastic tubes dominate unit volume in mass-market cosmetics and household applications where cost efficiency outweighs barrier performance requirements. Flip-top closures are gaining preference in travel-size and on-the-go formats across the 30ml and 50ml size categories.
FDA regulations govern pharmaceutical tube labeling and child-resistant closure standards in the United States, while REACH and EU Packaging and Packaging Waste Directive shape material composition and recyclability mandates across Europe. China's SAMR enforces GB standards for food-contact plastics that constrain import eligibility for non-compliant suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based material certification schemes to secure long-term formulation and sourcing flexibility.
Market Dynamics
Cosmetics brands are fragmenting demand across mid-sized portfolios while pharmaceutical contract manufacturers consolidate procurement, creating bifurcated sourcing dynamics that reshape supplier relationships and capacity allocation priorities.
Growth Catalysts
- Barrier laminate technology:Multi-layer structures with ethylene vinyl alcohol cores meet oxygen transmission requirements for retinol and pharmaceutical ointments, expanding addressable premium applications.
- Germany's Rhine-Ruhr cluster:Concentrated converting capacity and polymer compounding expertise reduce lead times for European cosmetics brands launching skincare lines.
- REACH chemical safety mandates:Compliance requirements for tube laminates are accelerating material substitution toward certified recyclable substrates, opening specification windows for qualified suppliers.
Market Restraints
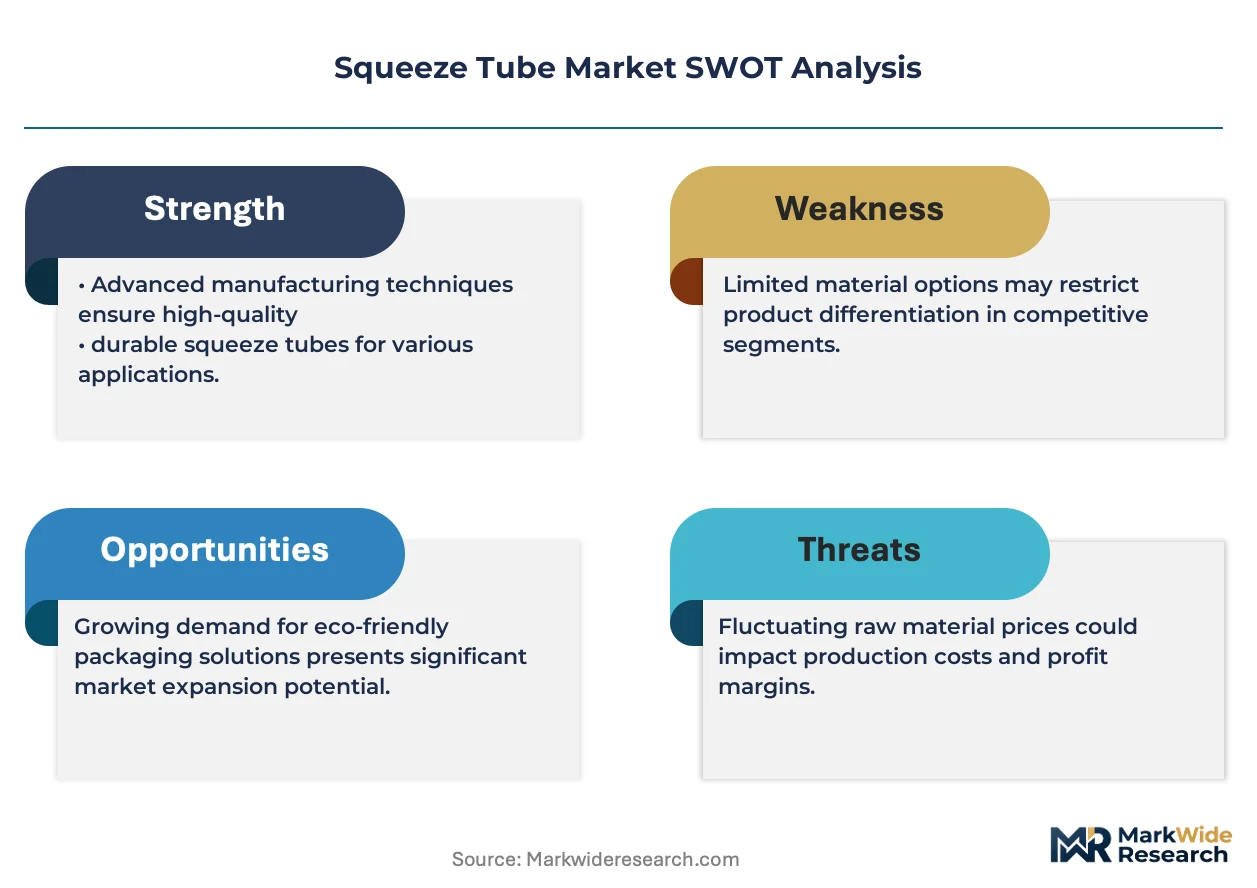
- Aluminum price volatility:Input cost swings for metal barrier layers compress margins on aluminum-plastic laminate tubes, forcing inventory risk onto converters.
- European converter concentration:Barrier tube supply clusters in Germany and Italy create geographic vulnerability to energy cost shocks and logistics disruptions.
- Recyclability certification delays:Extended producer responsibility frameworks lack harmonized testing protocols, slowing material qualification cycles by 12-18 months.
Strategic Opportunities
- India personal care expansion:Domestic cosmetics brands are localizing packaging sourcing to meet BIS standards and reduce import duty exposure.
- Monomaterial polyethylene platforms:Full-PE tube structures with compatible closures align with EU Packaging and Packaging Waste Directive recyclability targets.
- Direct-to-consumer sampling formats:Single-use 5ml and 10ml tubes bypass traditional retail distribution for subscription skincare services.
Industry Challenges
- Barrier polymer formulation expertise:Shortage of chemists skilled in coextrusion die design and adhesive lamination limits converter expansion.
- Legacy printing system integration:Digital sleeve decoration adoption requires retrofitting gravure lines, straining capex budgets at mid-tier facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Squeeze Tube Market |
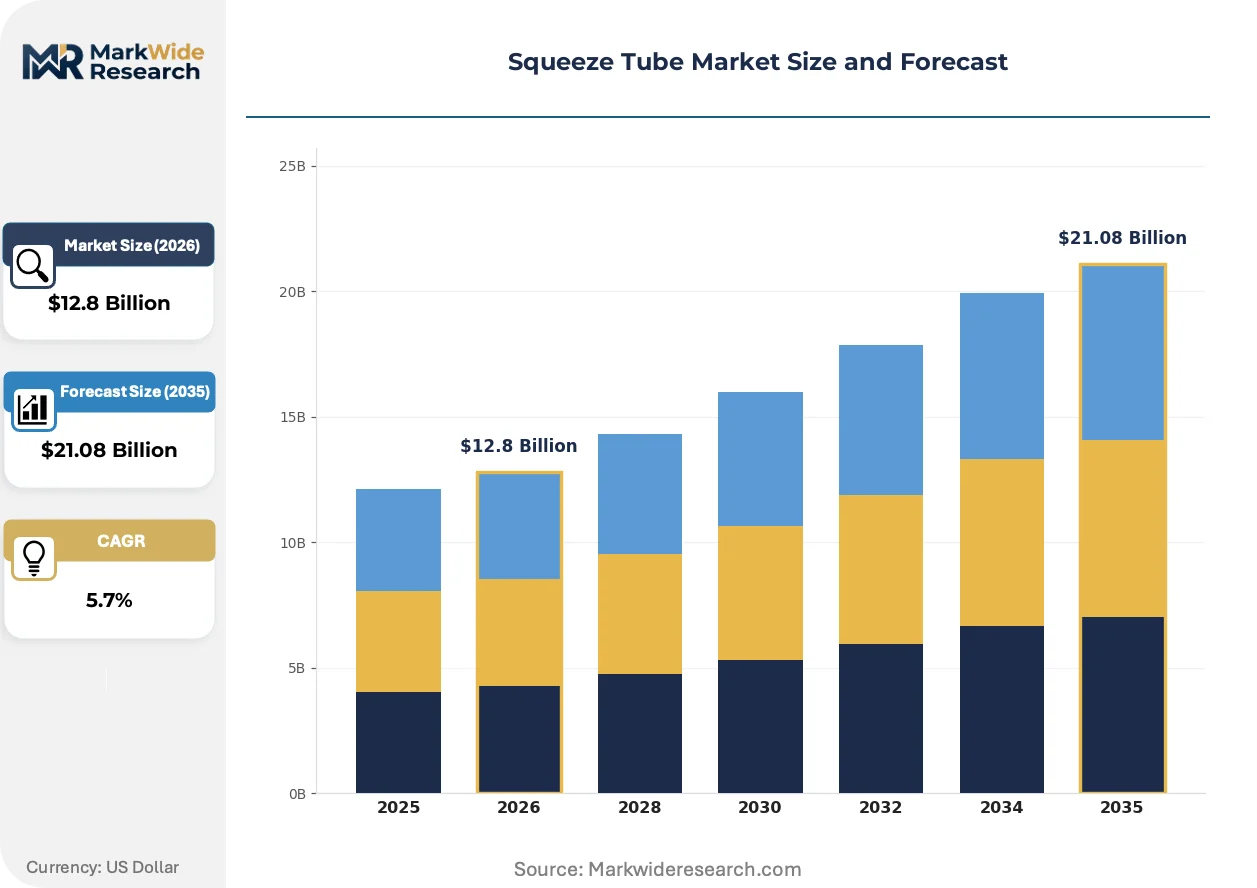
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Aluminum, Laminated, Glass Application: Cosmetics, Pharmaceuticals, Food Packaging, Household Products Closure Type: Screw Cap, Flip Top, Spout, Nozzle Size: 30ml, 50ml, 100ml, 200ml |
| Companies Covered | Berry Global Inc., Huhtamaki OYJ, Amcor Limited, Montebello Packaging Inc., Sonoco Products Company, Essel Propack Limited, Hoffmann Neopac AG, Intrapac International Corporation, Albea S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Squeeze Tube Market Evolving Landscape
Material science advances and regulatory pressure on recyclability are converging to transform tube construction methods, closure systems, and supply chain verification protocols across personal care and pharmaceutical applications.
Monomaterial polyethylene tubes with integrated flip-top closures are modularizing production workflows. European cosmetics brands are adopting these structures for mass-market skincare lines to simplify post-consumer sorting. This standardization is compressing SKU complexity and enabling regional converters to compete on scale rather than proprietary barrier formulations.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer barrier coatings from laminate tubes. Converters are qualifying silicone oxide and aluminum oxide vapor-deposited alternatives for oxygen-sensitive pharmaceutical ointments. German and French packaging clusters are investing in vacuum deposition capacity to maintain compliance without sacrificing shelf-life performance.
Beauty brands are unbundling decoration from tube manufacturing, sourcing plain extruded tubes for in-house digital printing. This disintermediation of pre-printed sleeve supply is compressing minimum order quantities and enabling micro-batch launches for influencer-driven skincare lines. The shift is most visible in California and South Korea, where direct-to-consumer brands prioritize packaging agility over unit cost optimization.
Squeeze Tube Market Segmentation
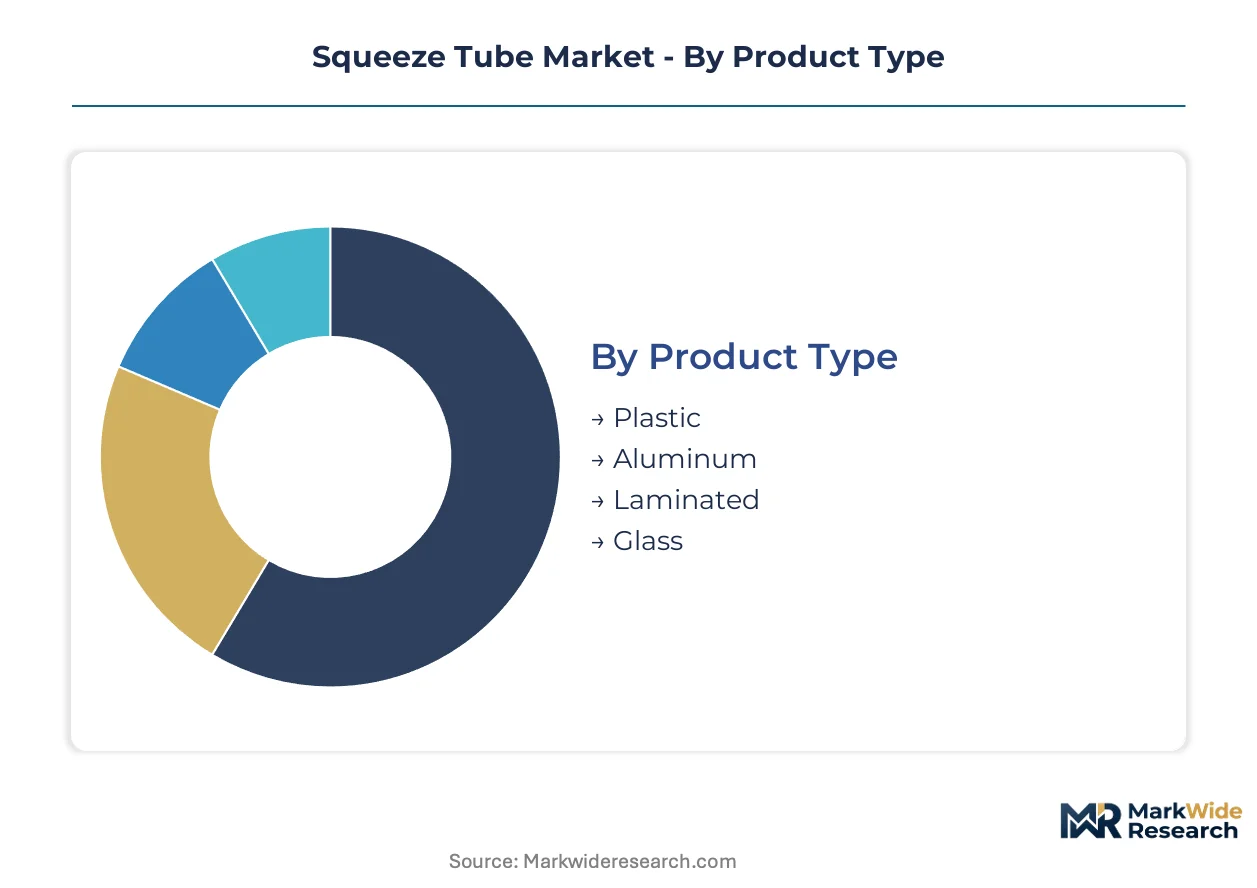
Tube construction methods and closure systems create distinct performance tiers that reshape procurement priorities across personal care and pharmaceutical supply chains. Material selection directly governs barrier properties, recyclability compliance, and decoration compatibility for brand owners.
Product Type:
Upgrade cycles from aluminum to laminate structures, and now toward monomaterial polyethylene, are redefining converter investment priorities and customer switching costs.
- Plastic:Polyethylene extrusions with 0.30–0.50 mm wall thickness serve mass-market cosmetics and household applications where unit cost dominates specification. Demand clusters in high-volume personal care accounts across North America and Asia-Pacific.
- Laminated:Multi-layer structures with ethylene vinyl alcohol cores deliver oxygen transmission rates below 0.1 cc/m²/day for retinol skincare and pharmaceutical ointments. REACH chemical safety mandates are accelerating material substitution toward certified recyclable substrates.
- Aluminum:Collapsible metal tubes retain niche demand for pigment-heavy artist materials and certain pharmaceutical creams requiring absolute light blockage.
- Glass:Premium skincare sampling formats utilize borosilicate constructions for perceived luxury positioning despite fragility constraints.
Volume placements concentrate in Plastic; the faster expansion belongs to Laminated.
Application:
Cost tier stratification separates premium pharmaceutical barrier requirements from mass-market cosmetics where decoration agility outweighs material performance.
- Cosmetics:Skincare brands fragment demand across mid-sized portfolios, sourcing 30ml and 50ml formats for travel retail and direct-to-consumer subscription services. Flip-top closures are gaining preference in on-the-go segments.
- Pharmaceuticals:Ointment and cream formulations demand oxygen and moisture barriers exceeding cosmetic specifications. FDA labeling and child-resistant closure standards govern US market entry.
- Food Packaging:Condiment and sauce applications utilize high-barrier laminates with flavor scalping resistance.
- Household Products:Adhesives, sealants, and cleaning pastes prioritize puncture resistance and chemical compatibility over aesthetic decoration.
Procurement volumes cluster in Pharmaceuticals; Cosmetics exhibits the steepest expansion trajectory.
Closure Type:
Customer type preferences diverge between pharmaceutical contract manufacturers standardizing on child-resistant formats and beauty brands chasing unboxing experience differentiation.
- Flip Top:Integrated hinge mechanisms enable single-hand dispensing for travel-size cosmetics and on-the-go formats. Monomaterial polyethylene platforms now integrate compatible flip-top structures for simplified recycling streams.
- Screw Cap:Threaded closures retain dominance in pharmaceutical applications requiring tamper-evident seals and precise torque specifications.
- Spout:Controlled-flow geometries serve viscous food products and industrial sealants requiring directional application.
- Nozzle:Precision-tip extrusion supports hair colorants, adhesives, and medical-grade topical applications.
Volume concentrates in Screw Cap; Flip Top is climbing the fastest.
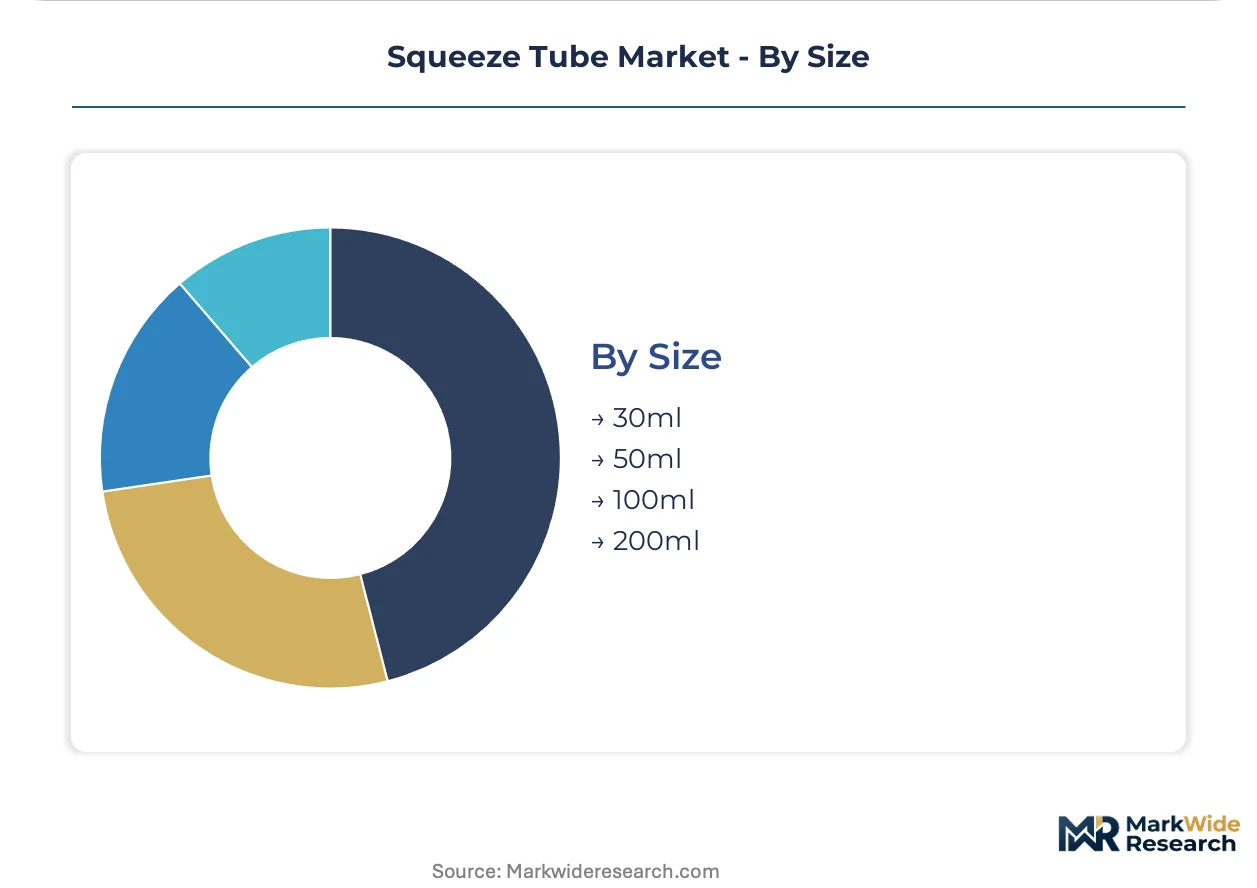
Size:
Geography-driven format preferences separate European pharmacy standard sizes from North American retail and Asian travel retail configurations.
- 30ml:Airline-compliant travel formats and premium skincare sampling sizes. Direct-to-consumer brands in California and South Korea prioritize this format for influencer-driven micro-batch launches.
- 50ml:Extended-stay travel and mid-tier cosmetic lines balance portability with per-unit economics.
- 100ml:Standard retail skincare and pharmaceutical maintenance prescriptions dominate European pharmacy shelves.
- 200ml:Family-size household products and professional salon formats maximize per-unit value.
Volume placements concentrate in 100ml; 30ml formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetics procurement concentrates in Germany's Rhine-Ruhr corridor, while pharmaceutical contract manufacturers cluster procurement volumes across the United States and Switzerland. China's SAMR enforcement of GB standards for food-contact plastics is constraining import eligibility for non-compliant tube suppliers.
Germany
Barrier laminate demand from retinol skincare brands and pharmaceutical ointment manufacturers drives converter capacity investments. REACH chemical safety mandates on tube laminates are accelerating material substitution toward certified recyclable substrates. The Rhine-Ruhr packaging cluster concentrates polymer compounding expertise and converting capacity, reducing lead times for European cosmetics launches.
United States
FDA labeling requirements and child-resistant closure standards govern pharmaceutical tube specifications for domestic ointment manufacturers. EPA oversight of chemical safety in packaging materials intersects with state-level extended producer responsibility frameworks emerging in California and New York. Berry Global Inc. leverages its North American manufacturing footprint to serve high-volume personal care accounts concentrated in the Midwest and Southeast.
China
SAMR enforcement of GB standards for food-contact plastics constrains import eligibility for non-compliant squeeze tube suppliers serving condiment and sauce applications. Domestic cosmetics brands are localizing packaging sourcing to reduce import duty exposure and meet local certification requirements. Yangtze River Delta converters are expanding monomaterial polyethylene capacity to align with recyclability targets in export markets.
Switzerland
Swissmedic pharmaceutical packaging standards demand oxygen transmission rates below 0.1 cc/m²/day for topical ointment tubes, exceeding cosmetic barrier requirements. Precision manufacturing clusters around Basel and Zurich serve contract manufacturers supplying European pharmacy chains. Hoffmann Neopac AG anchors specialized aluminum and laminate tube supply for premium pharmaceutical applications.
India
BIS standards compliance is becoming mandatory for domestic cosmetics brands localizing packaging sourcing to avoid import duty exposure. Personal care market expansion in Maharashtra and Gujarat is driving demand for 30ml and 50ml travel formats. Essel Propack Limited maintains converting presence to serve regional skincare and oral care accounts.
Squeeze Tube Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue monomaterial recyclability certifications and digital printing agility. The market structures around three tiers: multinational converters with multi-material platforms, regional specialists in barrier laminate technology, and mid-tier facilities competing on decoration flexibility. Strategic archetypes include scale-driven volume suppliers, barrier technology specialists, and agile micro-batch decorators. Capacity expansion and portfolio diversification toward pharmaceutical-grade specifications dominate competitive moves.
Among North American-based fabricators, Berry Global Inc. and Sonoco Products Company exemplify scale-driven volume supply archetypes. Huhtamaki OYJ represents the barrier technology specialist position anchored in European laminate expertise. These three occupy positions reflecting distinct geographic and capability concentrations rather than overlapping competitive terrain.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Huhtamaki OYJ |
| Amcor Limited |
| Montebello Packaging Inc. |
| Sonoco Products Company |
| Essel Propack Limited |
| Hoffmann Neopac AG |
| Intrapac International Corporation |
| Albea S.A. |
| Others |
Value Network & Pricing Analysis
Barrier-performance divergence between laminate and monomaterial polyethylene tubes manifests in both procurement premiums and supply chain footprint choices. REACH-compliant EVOH-core laminates command specification premiums from pharmaceutical ointment manufacturers, while full-PE structures sacrifice barrier ratings for recyclability certification and regional sourcing flexibility.
Pricing Analysis
Volume-mass-market polyethylene tubes trade on thin converter margins, while barrier laminate specifications retain pricing power through EVOH core scarcity and pharmaceutical-grade certification requirements. Price differentiation hinges on oxygen transmission certification tiers and closure system compatibility with EU sorting infrastructure. Pricing pressure stems from aluminum price volatility forcing inventory risk onto European converters. Mass-market cosmetics brands exhibit highest price sensitivity; pharmaceutical contract manufacturers prioritize barrier performance over unit cost.
Supply Chain Analysis
Post-consumer tube collection and mechanical recycling flows remain underdeveloped, constraining closed-loop feedstock availability for monomaterial polyethylene converters. Raw material supply concentrates in Germany, Italy, and China, with polymer compounding expertise clustering in the Rhine-Ruhr corridor. EVOH barrier resins and aluminum coil stock constitute critical input dependencies. Single-source vulnerability to energy cost shocks in European converting hubs threatens margin stability. Distribution runs through regional packaging distributors serving cosmetics brands and direct procurement relationships with pharmaceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The squeeze tube market sits in a material-transition phase as monomaterial polyethylene platforms displace legacy laminate structures for recyclability compliance. This substitution wave rewards converters with certified circular supply chains and punishes those anchored in multi-layer barrier expertise without adaptation pathways.
For Market Incumbents: Anchor barrier technology leadership in pharmaceutical-grade specifications where EVOH-core laminates retain irreplaceable oxygen transmission performance. Invest in vacuum deposition capacity for aluminum oxide barrier coatings as fluoropolymer alternatives face REACH elimination. Consolidate position in Swissmedic-certified supply relationships before monomaterial platforms penetrate ointment applications. For New Entrants and Emerging Players: Digital printing agility serves as the primary wedge for micro-batch cosmetics contracts, bypassing gravure minimum order quantity constraints that burden legacy converters. Target direct-to-consumer skincare brands in California and South Korea with 5ml and 10ml sampling formats. Pursue BIS certification for Indian domestic cosmetics localization to capture import substitution demand. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational packaging platforms seeking European barrier expertise or recyclability certification assets. Five-to-ten-year viability favors converters with monomaterial platform patents and established pharmaceutical-grade audit trails. Monitor REACH per- and polyfluoroalkyl substance restriction implementation timelines as inflection indicators for barrier technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Monomaterial Platform Certification | Full-PE tube structures with compatible closures align with EU Packaging and Packaging Waste Directive recyclability mandates. |
| Vacuum Deposition Capacity Investment | Silicon oxide and aluminum oxide vapor deposition replaces fluoropolymer coatings under REACH chemical safety restrictions. |
| Digital Printing System Integration | In-house sleeve decoration capability reduces minimum order quantities for influencer-driven skincare micro-batch launches. |
| Pharmaceutical-Grade Barrier Qualification | Oxygen transmission rates below 0.1 cc/m²/day secure Swissmedic and FDA ointment tube specifications. |
| Regional Converting Footprint Expansion | India and Yangtze River Delta capacity addresses BIS compliance and GB standards for localized sourcing requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with tube converting plant managers, cosmetics brand packaging directors, pharmaceutical contract manufacturing procurement leads, and polymer compounding technical directors supplemented secondary validation. FDA 510(k) submissions, ECHA REACH registration databases, and EU Packaging and Packaging Waste Directive implementation reports provided regulatory trajectory inputs. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Segmentation granularity modeled tube construction method, closure system, application sector, and geographic regulatory cluster across the projection horizon. Product type splits between plastic, laminated, aluminum, and glass constructions captured material substitution dynamics. Application segmentation separated cosmetics, pharmaceutical, food packaging, and household product specifications with distinct barrier and decoration requirements. CAGRs derived from annual growth rate reconciliation across segment-level demand drivers and capacity expansion announcements. Aluminum price volatility indices and EVOH resin supply constraints informed cost-side forecast inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory acceleration of extended producer responsibility frameworks and breakthrough bio-based barrier material commercialization. Forecasts reflect assumptions regarding REACH implementation timelines and pharmaceutical certification stability. Practitioners should monitor fluoropolymer restriction enforcement schedules and monomaterial polyethylene post-consumer recycling rate achievements for early signals of material transition velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Packaging Materials Market
Packaging Materials
New Packages and Materials for Power Devices Market
Packaging Materials
Global Liquid Packaging Market
Packaging Materials
Wooden and Plywood Packaging Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Polystyrene Packaging Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
Asia - Pacific Disposable Tableware Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
Chemical Packaging Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Stick Packaging Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Water Soluble Pods Packaging Market
Packaging Materials
Middle East and Africa Single-Use Packaging Market
Packaging Materials
Single-Use Packaging Market