
 LAMEA Rapeseed Oil Market | 2026-2036
LAMEA Rapeseed Oil Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Rapeseed Oil Market Analytics
High-oleic and low-erucic acid specification tiers is bifurcating the LAMEA rapeseed oil landscape into premium nutrition streams and industrial feedstock channels. Cargill Incorporated leverages its integrated crushing and refining footprint across Argentina and Brazil to secure origination advantages. Louis Dreyfus Company anchors South American export flows through port terminal investments and farmer financing programs. Bunge Limited competes on oilseed processing scale, with multiple facilities converting rapeseed into food-grade and technical oils.
Rapeseed oil, extracted from Brassica napus seeds, contains approximately 10% saturated fat, 60% monounsaturated fat, and 30% polyunsaturated fat with a smoke point of 230°C in refined form; processors deploy pre-press solvent extraction or cold-pressing to yield oils for food frying, biodiesel transesterification, and cosmetic emollient applications. The refined oil segment dominates volume as food manufacturers and biofuel producers prioritize oxidative stability and neutral flavor profiles. Cold-pressed oil commands premium positioning within cosmetics and specialty food channels where minimal processing retains tocopherols and phytosterols. Bulk container packaging leads industrial procurement, while bottle and tetra pack formats serve retail and foodservice segments with shorter replenishment cycles.
Brazil's ANVISA and Argentina's national food safety authority enforce maximum erucic acid thresholds and labeling standards that determine which rapeseed oil grades access food versus technical markets. The EU Green Deal and REACH compliance requirements shape LAMEA export viability, as European buyers demand certified sustainable sourcing with traceable greenhouse gas intensity data. Stakeholders must monitor regulatory divergence between Mercosur technical standards and Middle Eastern import specifications to avoid market access friction.
Market Dynamics
EU Green Deal carbon intensity thresholds are forcing LAMEA rapeseed oil exporters to reconfigure crushing and refining operations, splitting the market between compliant premium grades and constrained technical feedstock channels.
Growth Catalysts
- Biodiesel blending mandates:Argentina's biofuel law and Brazil's RenovaBio program mandate rising renewable diesel incorporation, pulling rapeseed oil into fuel transesterification at the expense of palm and soybean alternatives.
- High-oleic trait adoption:Seed breeders and crushing operators across the Southern Cone are converting acreage to high-oleic varieties that deliver superior frying stability and extended shelf life for food manufacturers.
- Middle East import liberalization:Saudi Arabia and the UAE have relaxed vegetable oil import licensing, opening Gulf foodservice and retail channels previously dominated by palm oil suppliers.
Market Restraints
- Input cost volatility:Natural gas and hexane solvent prices govern extraction economics, with Argentine processors exposed to pipeline supply disruptions from Bolivia.
- Supply concentration risk:Over 70% of LAMEA crushing capacity sits in Argentina's Rosario corridor, creating origination bottlenecks during port congestion or labor disputes.
- Regulatory friction:Divergent erucic acid thresholds between ANVISA in Brazil and Mercosur technical standards block seamless cross-border product flows.
Strategic Opportunities
- Underpenetrated geography:Colombia and Chile maintain minimal rapeseed crushing infrastructure, presenting first-mover advantages for integrated processors establishing import-dependent refining.
- Regulatory tailwind:EU deforestation-free supply chain regulations create premium pricing windows for LAMEA exporters with certified sustainable sourcing and traceable farm-level data.
- Cosmetic emollient channels:Cold-pressed, minimally processed grades are capturing positioning in Middle Eastern personal care formulations where tocopherol retention commands formulation premiums.
Industry Challenges
- Certification timeline compression:ISCC and RSB sustainability audits require 12-18 month implementation cycles, delaying EU market access for new entrant crushers.
- Legacy equipment retrofitting:Solvent extraction plants built for soybean processing lack the temperature control precision needed for high-oleic rapeseed without capital-intensive line modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Rapeseed Oil Market |
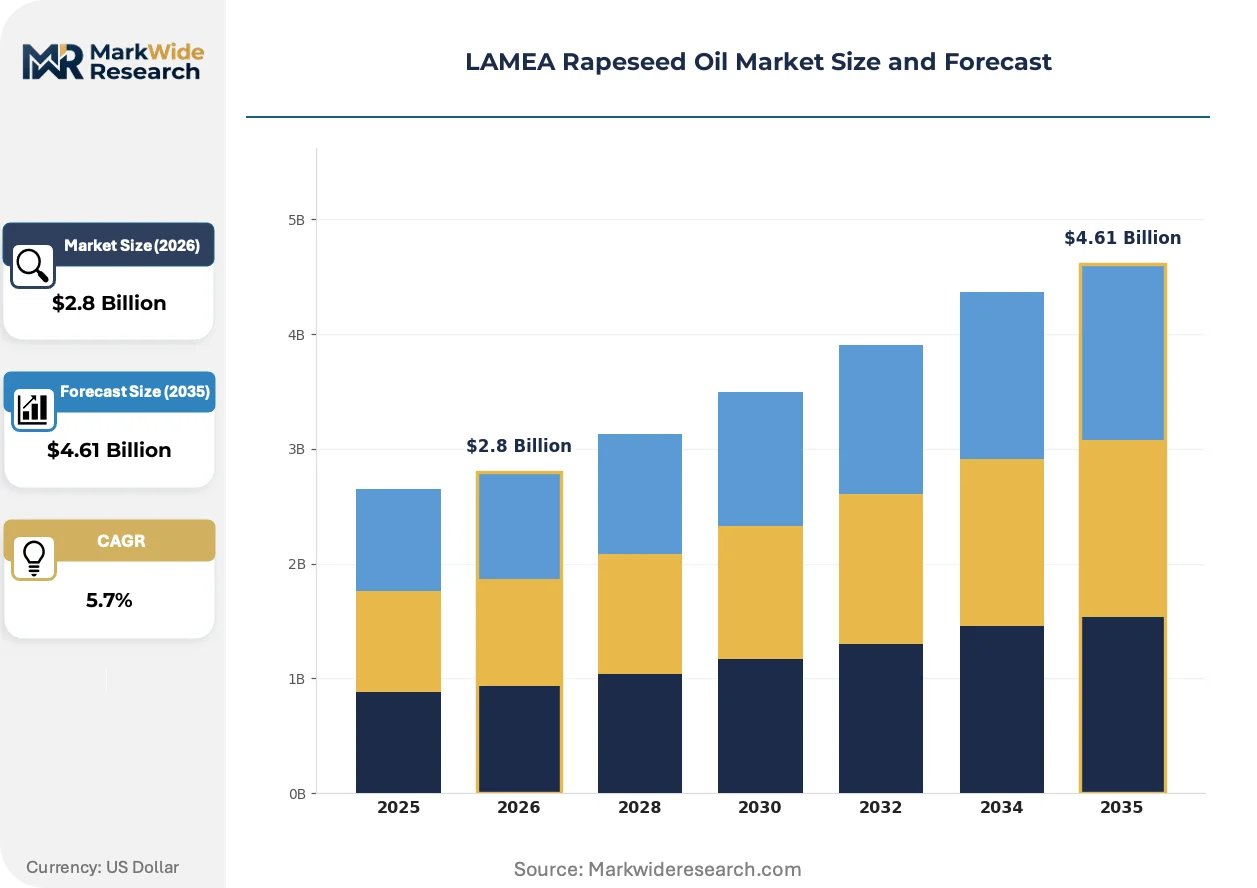
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Crude Oil, Cold-Pressed Oil, Organic Oil End User: Food Industry, Biofuel Producers, Cosmetics, Animal Feed Packaging Type: Bottles, Drums, Bulk Containers, Tetra Packs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Cargill Incorporated, The Archer Daniels Midland Company, RISOIL S.A., Ola Oils, Mackintosh of Glendaveny, Louis Dreyfus Company, Bunge Limited, Conagra Brands Inc., Glencore Grain Investment LLC, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Rapeseed Oil Market Evolving Landscape
Processing technology and regulatory compliance requirements are fragmenting the LAMEA rapeseed oil landscape into parallel supply chains optimized for distinct end-use specifications and carbon accounting standards.
High-oleic and low-erucic acid specification tiers is bifurcating the LAMEA rapeseed oil landscape into premium nutrition streams and industrial feedstock channels. Food manufacturers in Brazil and Argentina are accelerating procurement of high-oleic grades for extended frying cycles in quick-service restaurant operations. This technological split is compressing margins for commodity-standard crushers while rewarding integrated operators with seed breeding and refining capabilities.
EU Green Deal spillover effects are reshaping export compliance architecture for LAMEA rapeseed oil suppliers. European buyers now require certified greenhouse gas intensity data and deforestation-free sourcing documentation as contractual preconditions. Argentine and Brazilian exporters with ISCC-EU certification are capturing preferential offtake agreements, while uncertified volumes face exclusion or steep price discounts.
Foodservice procurement patterns are rotating toward consolidated supplier relationships with integrated traceability. Large Brazilian restaurant chains and Middle Eastern hospitality groups are reducing vendor counts and demanding batch-level origin documentation. This concentration is most visible in São Paulo and Dubai, where procurement directors prioritize single-source accountability over spot-market price optimization.
LAMEA Rapeseed Oil Market Segmentation
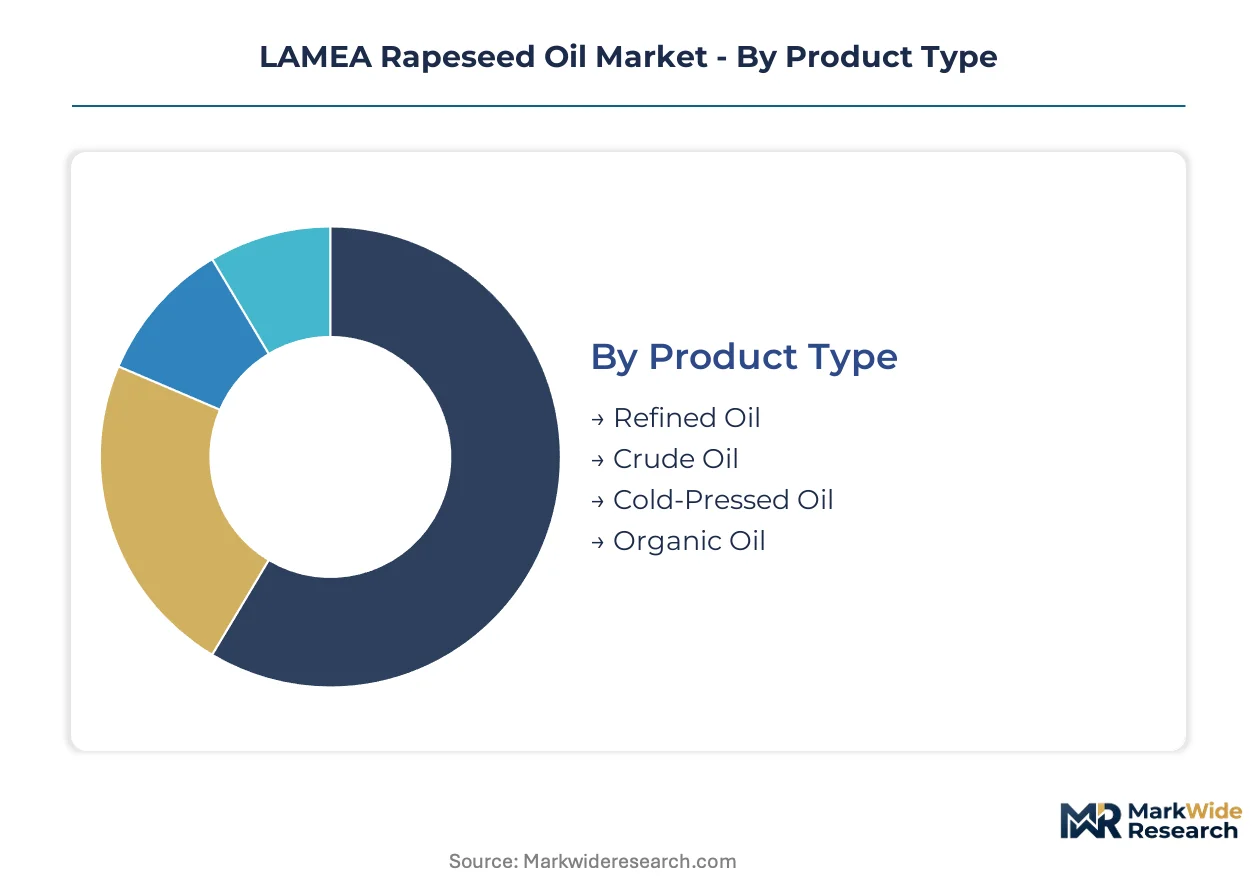
Specification tiers and end-use certification requirements fragment the LAMEA rapeseed oil landscape into parallel supply chains with divergent margin profiles. Processors must configure crushing and refining assets for either premium food-grade channels or technical feedstock markets.
Product Type:
Margin pools concentrate in cold-pressed and organic grades where tocopherol retention commands formulation premiums, while refined oil volumes anchor cash flow stability.
- Refined Oil:Neutral flavor profiles and 230°C smoke points suit extended frying cycles in Brazilian quick-service restaurant operations. ANVISA and Mercosur erucic acid thresholds determine which batches access food versus technical markets.
- Cold-Pressed Oil:Minimal thermal processing preserves phytosterols and tocopherols for cosmetic emollient applications in Middle Eastern personal care formulations. Saudi and UAE import liberalization is accelerating Gulf procurement of unrefined grades.
- Crude Oil:Intermediate product for downstream refining or biodiesel transesterification, priced on fatty acid composition and moisture content.
- Organic Oil:Certified cultivation and processing commands shelf-space premiums in Brazilian retail and export channels bound for EU deforestation-free supply chains.
Refined oil holds installed capacity. Cold-pressed oil is rotating up the share rankings.
End User:
Application-driven specification requirements split procurement patterns between food safety regulators and fuel blend mandate compliance.
- Food Industry:Bakery and frying applications in Brazil and Argentina specify high-oleic grades for oxidative stability. Rosario corridor crushers configure seed intake for monounsaturated fat concentration targets.
- Biofuel Producers:Argentina's biofuel law and Brazil's RenovaBio program mandate rising renewable diesel incorporation. Transesterification economics favor rapeseed over palm and soybean alternatives when carbon intensity data satisfies EU Green Deal thresholds.
- Cosmetics:Cold-pressed grades with retained tocopherols penetrate Middle Eastern personal care formulations.
- Animal Feed:Rapeseed meal byproduct from crushing operations supplies protein content for livestock nutrition in Southern Cone operations.
Food industry offtake dominates volume. Biofuel producers are climbing the fastest.
Packaging Type:
Procurement scale and replenishment frequency determine format selection across industrial, foodservice, and retail channels.
- Bulk Containers:Industrial procurement from Argentine crushers serving biodiesel and food manufacturing operations with continuous production schedules.
- Bottles:Retail shelf presence in Brazilian supermarkets and Middle Eastern hypermarkets with branding and labeling compliance requirements.
- Drums:Foodservice and mid-scale manufacturing with intermediate volume requirements and handling constraints.
- Tetra Packs:Extended shelf-life positioning for export markets and premium retail segments requiring light and oxygen barrier properties.
Bulk containers anchor industrial procurement. Tetra packs are gaining share fastest.
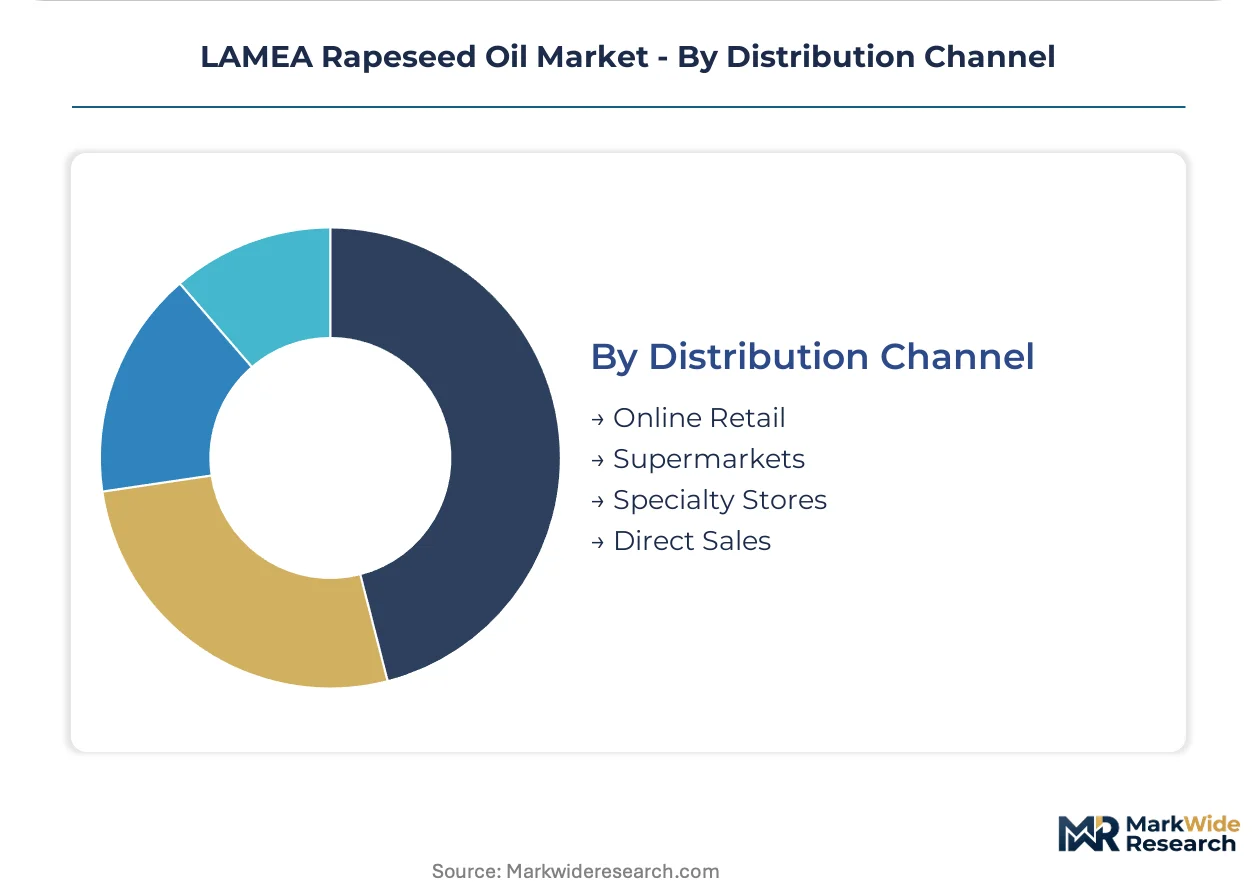
Distribution Channel:
Customer concentration and traceability requirements reshape route-to-market economics across integrated and fragmented buyer segments.
- Direct Sales:Large Brazilian restaurant chains and Middle Eastern hospitality groups consolidate procurement with single-source accountability demands. Batch-level origin documentation replaces spot-market price optimization.
- Supermarkets:Brazilian retail consolidation drives shelf-space negotiations for refined and organic grades with ANVISA labeling compliance.
- Online Retail:Premium cold-pressed and organic oils reach specialty food consumers in São Paulo and Dubai with subscription replenishment models.
- Specialty Stores:Cosmetic-grade cold-pressed oils access formulation chemists and personal care manufacturers in Middle Eastern free trade zones.
Direct sales holds volume concentration. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crushing infrastructure across the LAMEA region clusters heavily in Argentina's Rosario corridor, where over 70 percent of installed capacity processes rapeseed into food-grade and technical oils. This geographic concentration creates origination bottlenecks during port congestion periods, while simultaneously anchoring export flows to Middle Eastern and European destinations.
Brazil
ANVISA enforces maximum erucic acid thresholds that determine which rapeseed oil grades access food versus technical markets. The São Paulo metropolitan area hosts procurement directors from large restaurant chains demanding batch-level origin documentation and single-source accountability. RenovaBio program mandates continue pulling rapeseed oil into renewable diesel transesterification.
Argentina
The national food safety authority regulates labeling standards and fatty acid composition for domestic and export-bound production. Rosario corridor crushers configure seed intake specifically for high-oleic monounsaturated fat concentration targets demanded by Brazilian quick-service restaurant operations. Pipeline supply disruptions from Bolivia expose processors to natural gas and hexane solvent price volatility.
Saudi Arabia
The Saudi Food and Drug Authority has relaxed vegetable oil import licensing, opening Gulf foodservice channels previously dominated by palm oil suppliers. Riyadh-based hospitality groups are consolidating procurement relationships and demanding integrated traceability from crushing origin through final delivery. Cold-pressed cosmetic-grade oils penetrate personal care formulations with tocopherol retention premiums.
United Arab Emirates
MOHAP import specifications govern food safety compliance for rapeseed oil entering Dubai and Abu Dhabi markets. Dubai-based procurement directors for hospitality groups prioritize single-source accountability over spot-market price optimization. Free trade zones host formulation chemists sourcing cold-pressed grades for Middle Eastern personal care manufacturers.
Colombia
The country maintains minimal rapeseed crushing infrastructure, presenting first-mover positioning for integrated processors establishing import-dependent refining operations. Bogotá and Medellín food manufacturers currently source from Argentine exporters, creating vulnerability to Rosario corridor bottlenecks. National regulators are harmonizing technical standards with Mercosur frameworks to facilitate future cross-border flows.
LAMEA Rapeseed Oil Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the LAMEA rapeseed oil landscape. Integrated agribusiness conglomerates with seed breeding and refining capabilities capture premium positioning in high-oleic and certified-sustainable channels, while commodity-focused crushers compete on throughput scale and port access. The market structure splits between multinational trading houses with terminal investments and regional specialists with farmer financing relationships. Dominant competitive moves include ISCC-EU certification acquisition for EU market access and crushing asset retrofitting for high-oleic temperature control precision.
Within the integrated trading house tier, Cargill Incorporated and Louis Dreyfus Company represent archetypes with origination advantages through South American crushing and refining footprints. Bunge Limited exemplifies scale-driven processing positioning with multiple facilities converting rapeseed into differentiated oil grades. Among these, Cargill's Argentine and Brazilian infrastructure anchors food-grade supply chains, while Louis Dreyfus leverages port terminal investments to secure export flow control.
| Leading Market Players |
|---|
| Cargill Incorporated |
| The Archer Daniels Midland Company |
| RISOIL S.A. |
| Ola Oils |
| Mackintosh of Glendaveny |
| Louis Dreyfus Company |
| Bunge Limited |
| Conagra Brands Inc. |
| Glencore Grain Investment LLC |
| Others |
Value Network & Pricing Analysis
ISCC-EU certification gates both supply qualification and price differentiation simultaneously, separating Argentine and Brazilian crushers into premium export tiers versus discounted domestic channels. EU Green Deal carbon intensity thresholds force processors to absorb audit costs that stratify final pricing across compliant and non-compliant batches.
Pricing Analysis
EU Green Deal carbon intensity thresholds dictate the pricing tier structure across LAMEA rapeseed oil exports. Three-tier pricing structure across premium, standard, and economy levels separates ISCC-EU certified high-oleic grades from conventional food-grade and technical feedstock volumes. Price differentiation hinges on certification level and fatty acid composition, with Middle Eastern hospitality groups showing lowest sensitivity due to single-source accountability demands. Cost compression in commodity-standard crushing is intensifying because Rosario corridor bottlenecks concentrate origination leverage.
Supply Chain Analysis
Strategic stockpile preferences dominate Argentine crusher procurement, with Rosario corridor operators maintaining seed inventory buffers against Bolivian natural gas disruption. Supply concentrates in Argentina, Brazil, and Paraguay as crushing origination points. Hexane solvent and natural gas feed extraction economics that hinge on pipeline reliability from Bolivia. Single-source vulnerability runs through the Rosario corridor where labor disputes or port congestion trigger origination bottlenecks. Distribution runs through integrated trading houses with terminal investments rather than fragmented broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Palm oil substitution pressure from Southeast Asian suppliers threatens LAMEA rapeseed oil positioning in Middle Eastern foodservice channels, forcing incumbents to defend through certification differentiation and origination control.
For Market Incumbents: Consolidate crushing capacity around Rosario corridor assets to tighten origination control against Argentine pipeline disruption risks. Deepen backward integration into high-oleic seed breeding programs to capture premium frying stability specifications demanded by Brazilian quick-service restaurant chains. Prioritize ISCC-EU certification renewal cycles to maintain EU market access against emerging competitor audits. For New Entrants and Emerging Players: ISCC-EU certification fast-track offers entry acceleration into premium export channels previously blocked to uncertified volumes. Colombia and Chile present white-space crushing infrastructure opportunities where import-dependent refining bypasses Rosario bottleneck exposure. Target Middle Eastern cosmetic emollient channels with cold-pressed grade positioning and tocopherol retention marketing. For Investors and Strategic Acquirers: EU deforestation-free supply chain regulations reshape the acquisition landscape toward certified-sustainable asset premiums. Long-term viability centers on integrated operators with seed breeding and refining capabilities rather than commodity throughput players. Monitor ISCC-EU certification penetration rates across Argentine crusher portfolios as inflection indicator for export pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ISCC-EU Certification Acquisition | Unlocks EU Green Deal compliant export channels with preferential offtake terms from European buyers. |
| High-Oleic Crushing Retrofit | Enables temperature-controlled processing for premium frying stability specifications in Brazilian foodservice. |
| Backward Integration into Seed Breeding | Captures margin pools from trait development through origination control over monounsaturated fat concentration. |
| Rosario Corridor Capacity Expansion | Consolidates origination leverage against supply concentration risk from Bolivian natural gas pipeline exposure. |
| Middle East Distribution Partnership | Secures Gulf foodservice access through Dubai and Riyadh hospitality procurement consolidation trends. |
Research Methodology
Desk research of customs trade databases, EU regulatory filings, and crushing capacity registries preceded structured interviews with Argentine plant managers, Brazilian procurement directors at quick-service restaurant chains, Middle Eastern hospitality group sourcing leads, and seed breeding program directors. Primary fieldwork with Rosario corridor operators and ANVISA compliance officers combined with secondary validation against ANVISA labeling standards and Mercosur technical regulations. Bottom-up volume triangulation from crushing facility throughput data reconciled with top-down trade flow analysis.
Variance decomposition across specification tiers, end-use certification requirements, and geographic export corridors shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end user industry, packaging format, and distribution channel complexity. CAGRs derived from facility expansion pipelines and biofuel mandate trajectories incorporated RenovaBio program compliance curves and Argentina biofuel law implementation pacing.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and stable Bolivian pipeline supply; material deviation in either assumption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
India Agriculture Market
Agriculture and Agri Products
Animal Derivatives Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
Coir Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Elaeis Guineensis (Palm) Fruit Extract Market
Agriculture and Agri Products
Oman Agriculture Market
Agriculture and Agri Products
North America Shiitake Mushroom Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
Feed Protein Market