
 Oman Agriculture Market | 2026-2036
Oman Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Agriculture Market Insights
The Oman agriculture sector is restructuring around a widening gap between premium greenhouse produce and open-field commodity crops. Gulf Mushroom Products Company SAOG leverages controlled-environment expertise to dominate specialty mushroom supply for hospitality and retail channels. Oman Agriculture Development Company anchors large-scale date palm and fodder operations across interior governorates. Dhofar Cattle Feed Co SAOG sustains integrated feed milling that ties coastal grain imports to livestock finishing programs in the south.
Oman agriculture encompasses crop cultivation, livestock husbandry, horticulture under protected structures, and marine aquaculture, operating across arid-zone conditions where water efficiency parameters dictate system selection and salinity tolerance thresholds define viable species for coastal farms. Its primary commercial purpose centers on reducing food import dependency while generating exportable surpluses of dates, fish, and specialty vegetables for Gulf neighbors. Crops and horticulture segments lead current output value, with horticulture commanding margin premiums through greenhouse cherry tomatoes, capsicum, and leafy greens sold to supermarket chains. Aquaculture represents the fastest-growing structural category, driven by industrial shrimp farm licenses and seabream cage operations in Al Wusta and Dhofar waters.
The Ministry of Agriculture and Fisheries sets planting calendars and irrigation quotas that directly determine which commodities farmers can scale, while the Public Authority for Water and Wastewater Services enforces groundwater extraction limits that push adoption of drip and hydroponic systems. Municipalities in Muscat and Al Batinah apply food safety inspection regimes modeled on GCC standardization protocols for fresh produce entering retail channels. Stakeholders must monitor whether desalination cost trajectories and renewable-powered pumping investments can sustain the irrigation expansion implied by protected-area targets without eroding farm-level returns.
Market Dynamics
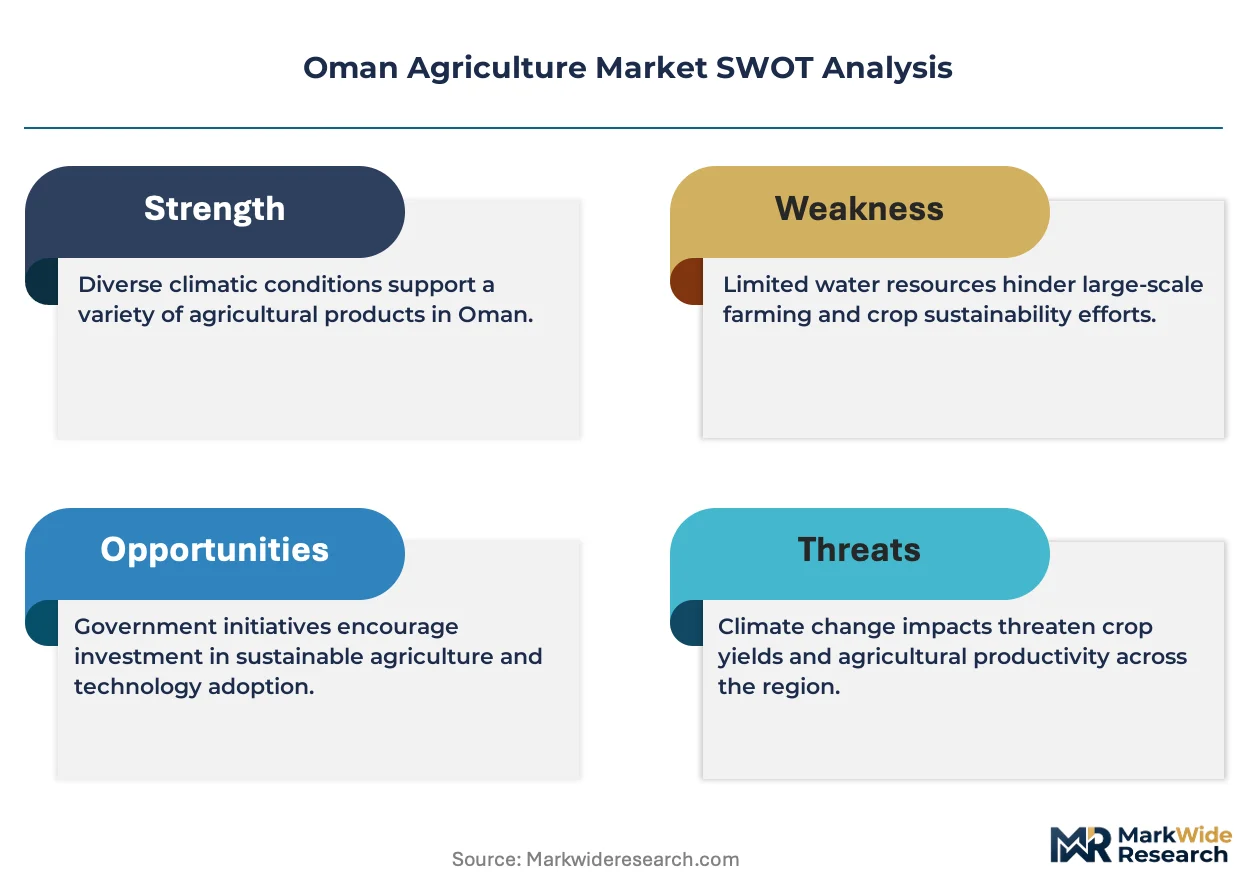
Subsidy programs from the Ministry of Agriculture and Fisheries are redirecting capital toward controlled-environment farming, creating a structural divergence between capital-intensive greenhouse operations and rain-fed open-field cultivation across Oman's interior governorates.
Growth Catalysts
- Greenhouse Subsidy Framework:Ministry of Agriculture and Fisheries reimbursement programs for protected-structure construction are accelerating farmer migration from open-field to hydroponic and drip-irrigated systems in Al Batinah South Governorate.
- Food Processing Procurement:Domestic hotel chains and supermarket retailers are expanding contracted purchase agreements with Omani vegetable growers, replacing previous reliance on UAE re-exports.
- Coastal Aquaculture Licensing:Industrial shrimp farm permits issued by the Ministry of Agriculture and Fisheries in Al Wusta and Dhofar waters are attracting foreign technical partnerships for intensive marine production.
Market Restraints
- Groundwater Extraction Quotas:Public Authority for Water and Wastewater Services pumping limits constrain expansion of fodder crops and date palm irrigation in interior governorates where fossil aquifers dominate.
- Desalination Cost Structure:Energy-intensive reverse osmosis for coastal greenhouse irrigation compresses margins when diesel or grid electricity prices fluctuate, particularly affecting smallholder operations in Muscat periphery.
- Import Dependency for Feed Grains:Dhofar Cattle Feed Co and livestock finishers remain tethered to volatile international sorghum and barley markets, with limited domestic grain production to buffer price spikes.
Strategic Opportunities
- Dhofar Monsoon Agriculture:Salalah's seasonal rainfall patterns support off-cycle vegetable production for Gulf markets during summer months when northern hemisphere supply contracts.
- Renewable-Powered Pumping:Solar photovoltaic integration with groundwater extraction systems offers path to defray irrigation energy costs under Ministry of Energy and Minerals rural electrification programs.
- Specialty Mushroom Cultivation:Controlled-environment expertise developed for hospitality supply can extend to pharmaceutical-grade fungal biomass for nutraceutical export markets.
Industry Challenges
- Hydroponic System Integration:Transitioning from soil-based cultivation to nutrient film technique requires technical training pipelines that Oman's agricultural extension services have not yet scaled.
- Food Safety Certification Timelines:Municipal inspection regimes in Muscat and Al Batinah modeled on GCC standardization protocols create compliance bottlenecks for smallholders seeking supermarket supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Agriculture Market |
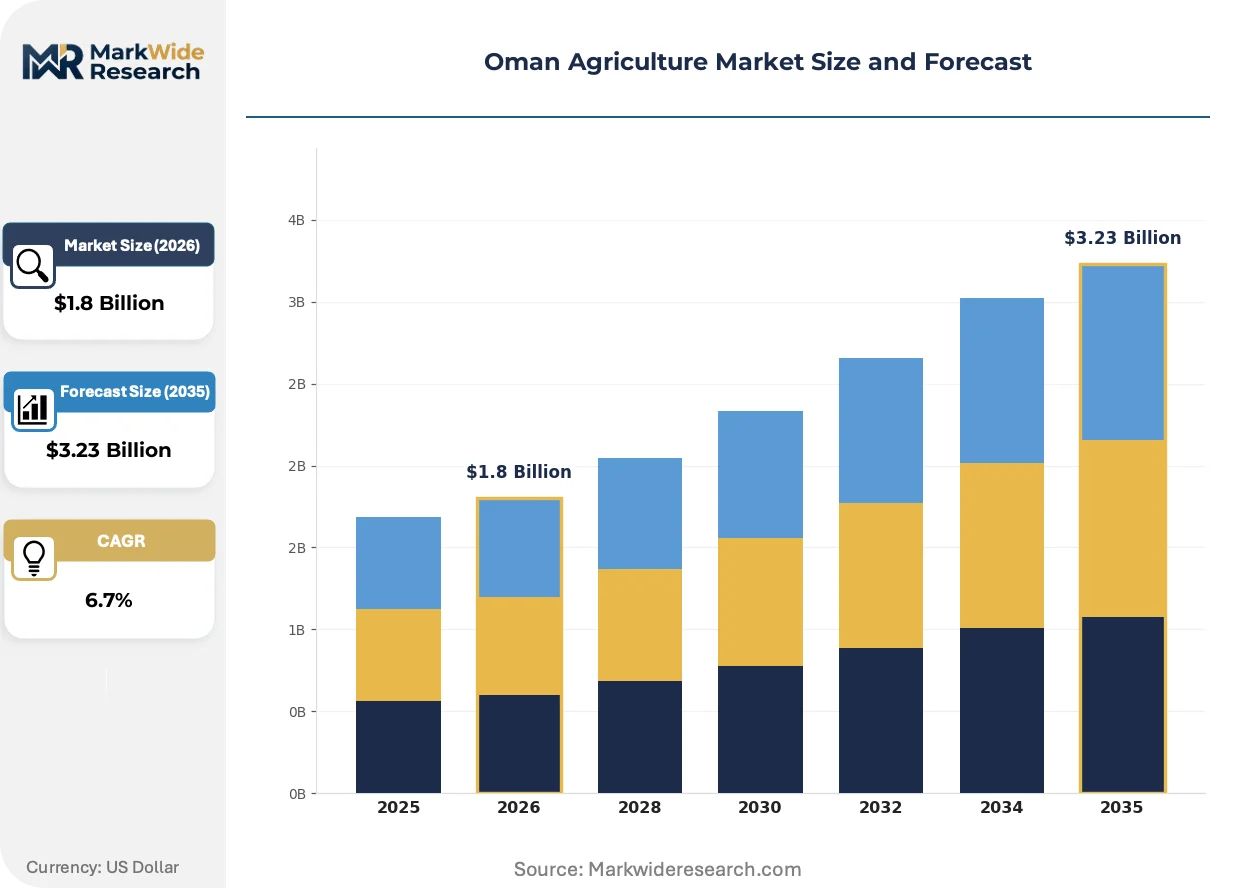
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crops, Livestock, Horticulture, Aquaculture End Use Industry: Food Processing, Export, Local Consumption, Agrochemicals Distribution Channel: Wholesale, Retail, Online, Cooperative Packaging Type: Bags, Boxes, Bulk, Containers |
| Companies Covered | Gulf Mushroom Products Company SAOG, Oman Agriculture Development Company, Oman Fisheries, Omaid Bahar LLC, Oman Flour Mills Company, A'Safwah Dairy, Dhofar Cattle Feed Co SAOG, Saham Agricultural City, Al Zain Farms, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Agriculture Market Trends and Innovations
Protected agriculture infrastructure is modularizing across Oman's coastal plains, with standardized greenhouse components enabling rapid deployment and technology transfer from established horticulture clusters.
Containerized hydroponic units are modularizing farm establishment in Al Batinah South Governorate, allowing food processing buyers to pre-qualify multiple small suppliers without committing to single large-scale offtake agreements. Hotel procurement managers are piloting these systems for on-site herb production, compressing the traditional farm-to-fork supply chain into direct cultivation contracts.
Ministry of Agriculture and Fisheries planting calendar reforms are tightening irrigation quota enforcement, forcing open-field operators toward deficit irrigation strategies or crop switching to lower water-demand species. The Public Authority for Water and Wastewater Services extraction monitoring now requires flow meters on all agricultural boreholes, with non-compliance penalties affecting date palm expansion in Al Dakhiliyah Governorate.
Retail channel consolidation is concentrating produce buying power among three supermarket chains controlling Muscat's fresh vegetable distribution. Independent greengrocers in interior towns are responding through cooperative aggregation models that pool harvests to meet minimum volume thresholds for direct processor sales, bypassing traditional wholesale souk intermediaries in Seeb and Salalah.
Oman Agriculture Market Segmentation
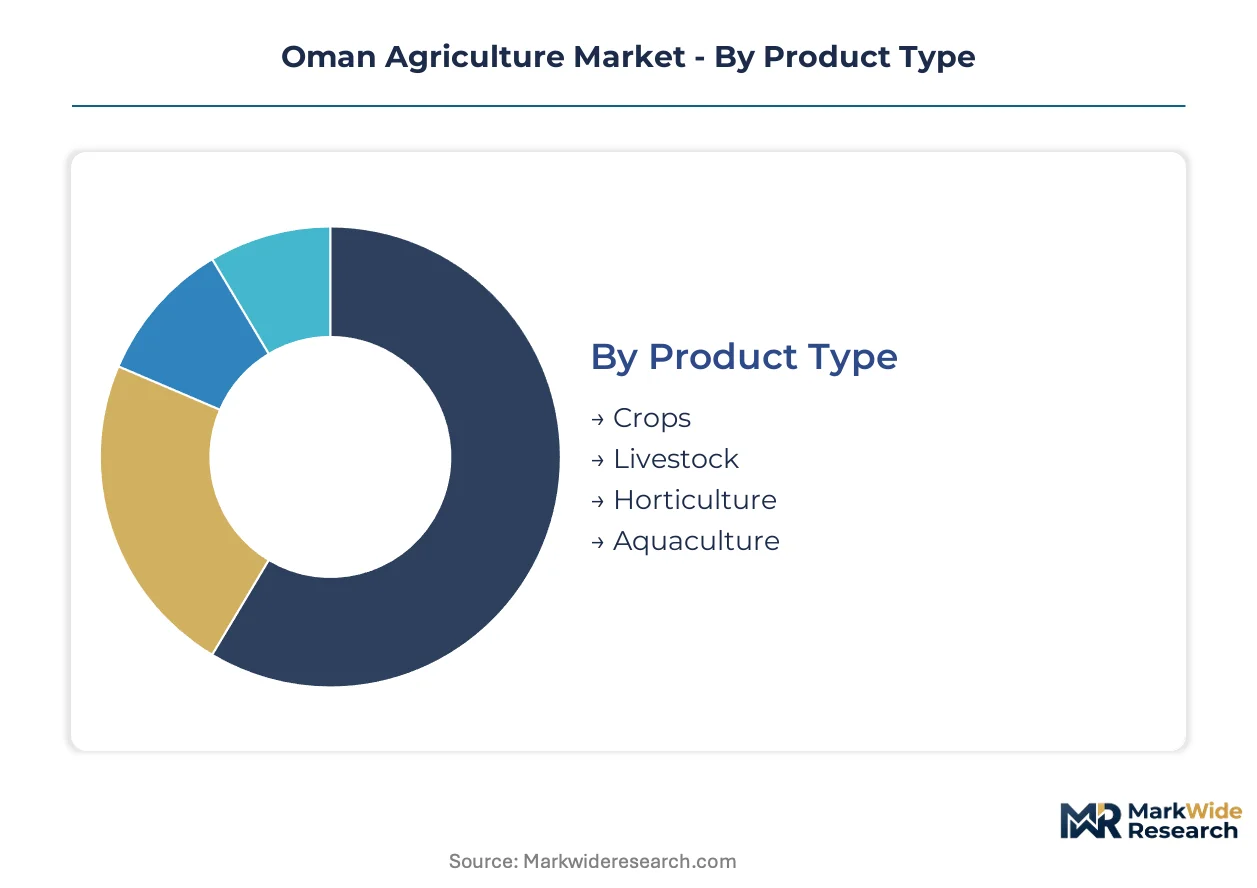
Omani agriculture segments by production system, buyer channel, and logistics format. Water access and subsidy eligibility create sharp divides between capital-intensive greenhouse operations and open-field cultivation. Each segment carries distinct margin profiles and regulatory exposure.
Product Type:
Standalone crop systems dominate interior governorates while integrated aquaculture-horticulture clusters concentrate along Al Batinah and Dhofar coasts.
- Crops:Field-grown cereals and fodder occupy the largest planted area under deficit irrigation regimes. Al Dakhiliyah Governorate hosts concentrated sorghum and barley cultivation for Dhofar Cattle Feed Co operations, constrained by Public Authority for Water and Wastewater Services extraction quotas.
- Aquaculture:Industrial shrimp farms and seabream cage systems anchor the steepest expansion trajectory, licensed by Ministry of Agriculture and Fisheries in Al Wusta waters. Foreign technical partnerships supply intensive marine production expertise for Gulf export markets.
- Livestock:Camel, cattle, and small ruminant herds graze rangelands and supplemented feedlots across interior governorates, tethered to imported grain supply chains.
- Horticulture:Protected-structure cherry tomatoes, capsicum, and leafy greens command premium margins through supermarket retail channels in Muscat.
Crops lead volumes today; aquaculture is gaining share fastest.
End Use Industry:
Cost tier stratification separates commodity bulk sales from certified retail and processing contracts.
- Food Processing:Hotel chains and supermarket retailers execute contracted purchase agreements with greenhouse operators for standardized vegetable specifications. Procurement managers in Muscat bypass UAE re-export intermediaries through direct cultivation contracts.
- Local Consumption:Traditional wholesale souks in Seeb and Salalah distribute open-field produce to independent greengrocers and household buyers across interior towns.
- Export:Dates, fish, and specialty vegetables ship to Saudi Arabia, UAE, and other Gulf neighbors under GCC standardization protocols.
- Agrochemicals:Fertilizer, pesticide, and veterinary product demand tracks planting calendar cycles set by Ministry of Agriculture and Fisheries.
Local consumption commands volume; food processing climbs the fastest.
Distribution Channel:
Customer type fragmentation shapes channel selection — institutional buyers favor direct contracts while fragmented retail relies on aggregation.
- Wholesale:Traditional souk intermediaries in Seeb and Salalah aggregate harvests from dispersed smallholders, facing displacement as cooperative models pool volumes for processor-direct sales.
- Cooperative:Producer associations in interior towns assemble minimum volume thresholds for direct supermarket supply, bypassing wholesale markups.
- Retail:Three supermarket chains control Muscat fresh vegetable distribution, consolidating produce buying power through centralized procurement.
- Online:Digital platforms emerge for specialty produce and aquaculture products, constrained by cold chain infrastructure gaps outside coastal corridors.
Wholesale leads volumes today; cooperative channels expand most quickly.
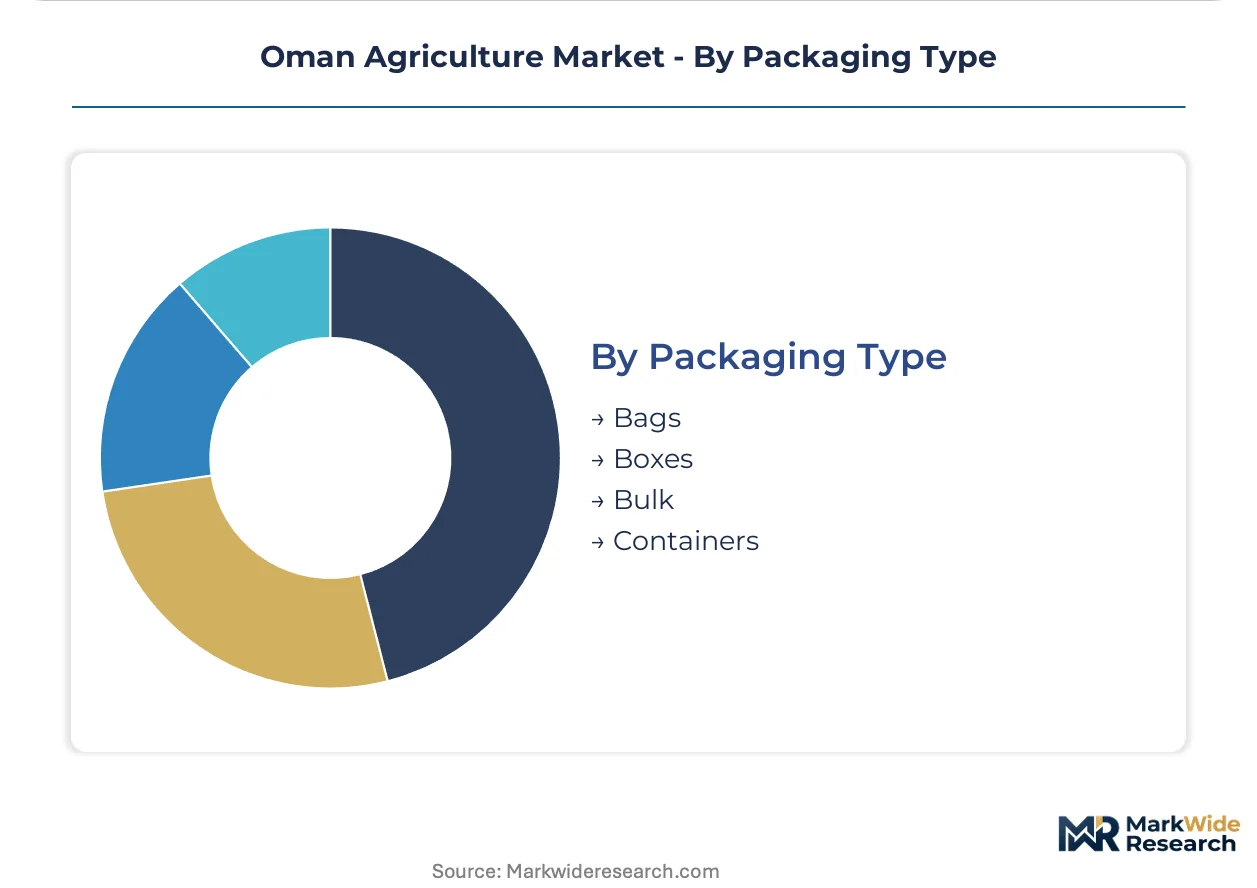
Packaging Type:
Supply concentration in processing and export segments drives standardized container adoption over flexible formats.
- Bulk:Unpacked grain, fodder, and whole fish dominate commodity flows to feed mills and processing facilities, minimizing per-unit handling costs.
- Containers:Standardized refrigerated units support export-grade seafood and date shipments to GCC markets under food safety inspection regimes.
- Boxes:Corrugated packaging serves supermarket retail channels with printed origin and traceability labeling for consumer-facing produce.
- Bags:Flexible packaging handles lower-value grains, fertilizers, and veterinary supplies across wholesale distribution networks.
Bulk leads volumes today; containerized formats show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and the UAE outpace Oman in absolute agricultural output, yet Oman's coastal aquaculture licensing framework and Dhofar's monsoon-fed production cycles create distinctive competitive positioning within Gulf food security strategies.
Al Batinah South Governorate
Coastal water access and logistics corridors support intensive horticulture clustering. The Ministry of Agriculture and Fisheries subsidizes protected-structure construction, accelerating farmer migration to hydroponic systems. Greenhouse cherry tomatoes and capsicum command premium margins through Muscat supermarket retail channels.
Dhofar Governorate
Seasonal monsoon rainfall enables off-cycle vegetable production for Gulf markets during northern hemisphere summer supply contractions. Dhofar Cattle Feed Co SAOG anchors integrated feed milling that ties coastal grain imports to livestock finishing programs. The Public Authority for Water and Wastewater Services enforces extraction monitoring on all agricultural boreholes.
Muscat Governorate
Three supermarket chains consolidate fresh vegetable distribution, driving contracted purchase agreements with greenhouse operators. Municipal food safety inspection regimes model GCC standardization protocols. Desalination cost volatility compresses margins for periphery smallholders dependent on reverse osmosis irrigation.
Al Wusta Governorate
Industrial shrimp farm permits attract foreign technical partnerships for intensive marine production. Seabream cage operations expand in licensed coastal waters. The Ministry of Agriculture and Fisheries directs aquaculture licensing toward export-grade seafood for Saudi Arabia and UAE markets.
Al Dakhiliyah Governorate
Date palm expansion faces Public Authority for Water and Wastewater Services pumping limits on fossil aquifers. Deficit irrigation regimes constrain sorghum and barley cultivation for interior feed supply chains. Groundwater extraction quotas force crop switching to lower water-demand species.
Oman Agriculture Market Competitive Landscape
Top-tier vendors anchor controlled-environment expertise and integrated feed milling, while mid-scale operators cluster around cooperative aggregation and regional distribution. The competitive structure stratifies across capital-intensive greenhouse specialists, aquaculture license-holders, and diversified agro-industrial conglomerates. Two dominant competitive moves are reshaping positioning: backward integration into captive supply chains and direct cultivation contracts that bypass traditional wholesale intermediaries.
Within the controlled-environment tier, Gulf Mushroom Products Company SAOG and Oman Agriculture Development Company exemplify divergent specialization strategies—one leveraging protected-structure expertise for specialty crop supply, the other anchoring large-scale date palm and fodder operations across interior governorates. Dhofar Cattle Feed Co SAOG occupies a position linking coastal grain imports to livestock finishing infrastructure. These three entities represent the archetype spectrum spanning horticulture premiumization, commodity scale operations, and vertically integrated feed-livestock systems.
| Leading Market Players |
|---|
| Gulf Mushroom Products Company SAOG |
| Oman Agriculture Development Company |
| Oman Fisheries |
| Omaid Bahar LLC |
| Oman Flour Mills Company |
| A'Safwah Dairy |
| Dhofar Cattle Feed Co SAOG |
| Saham Agricultural City |
| Al Zain Farms |
| Others |
Pricing and Supply Chain Analysis
Backward integration into captive water infrastructure anchors both supply security and margin control for Omani greenhouse operators investing under Ministry of Agriculture and Fisheries subsidy programs. This integration choice separates price-setters with desalination assets from price-takers exposed to diesel-powered pumping volatility across Muscat periphery.
Pricing Analysis
Capacity additions in Al Batinah South Governorate are reshaping price floors for protected-structure vegetables as standardized greenhouse components enable rapid technology transfer. Contract-based long-term offtake agreements dominate food processing procurement, with price differentiation separating GlobalGAP-certified supply for supermarket chains from ungraded open-field produce flowing through Seeb wholesale souks. Cost compression in desalination-dependent operations is intensifying because diesel price fluctuations directly reverse osmosis irrigation economics, making smallholders in Muscat periphery the most price-sensitive segment while integrated operators with solar pumping arrays command premium stability.
Supply Chain Analysis
Specialty seedstock supply rests on Dutch and Israeli breeding houses for greenhouse tomato and capsicum varieties, with fodder grain imports drawing from Australia, Argentina, and Black Sea origins. Aquaculture feed formulations hinge on Peruvian fishmeal and Southeast Asian soy protein concentrate. Single-source vulnerability concentrates in Dutch propagator networks for high-yielding greenhouse cultivars, with distribution running through cooperative aggregation models that pool smallholder harvests for direct processor sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Omani agriculture reads as a late-cycle quality story where food processing buyers are redirecting procurement toward premium-grade domestic supply with traceability certification. This demand-shift toward GlobalGAP specifications rewards operators who have already invested in controlled-environment infrastructure.
For Market Incumbents: Acquire marginal groundwater extraction rights in Al Dakhiliyah Governorate before Public Authority for Water and Wastewater Services tightens allocation ceilings. Consolidate cooperative aggregation networks in interior towns to secure volume commitments from dispersed smallholders, defending against containerized hydroponic entrants that bypass traditional wholesale intermediaries through direct cultivation contracts.
For New Entrants and Emerging Players: Direct-to-hotel digital procurement platforms offer the most penetrable route for specialty herb supply, compressing farm-to-fork chains into on-site cultivation contracts. Target Dhofar Governorate off-cycle production windows when northern hemisphere vegetable supply contracts, using Salalah's monsoon-fed growing conditions as the geographic wedge against Al Batinah incumbents.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale greenhouse operators with existing Ministry of Agriculture and Fisheries subsidy compliance because protected-structure licensing creates artificial scarcity in water-constrained coastal zones. Platform consolidation across 5-10 hectare units achieves procurement scale for seedstock and technical service negotiations. Watch desalination cost trajectories as the inflection indicator for margin sustainability across Muscat periphery operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Protected-Structure Capacity Expansion | Ministry of Agriculture and Fisheries subsidies accelerate farmer migration from open-field to hydroponic systems in Al Batinah South. |
| Backward Integration into Water Assets | Captive desalination and solar pumping arrays insulate margin stability from diesel price volatility in Muscat periphery. |
| Cooperative Aggregation Network | Pooled harvest volumes from interior towns bypass Seeb wholesale markups to meet supermarket minimum thresholds. |
| Monsoon Production Window Capture | Dhofar's seasonal rainfall enables off-cycle vegetable supply to Gulf markets during northern hemisphere summer contractions. |
| Aquaculture Licensing Partnership | Foreign technical partnerships for Al Wusta shrimp farms transfer intensive marine production expertise for export-grade seafood. |
Research Methodology
Multiple input streams — structured interviews with greenhouse operators and feed mill procurement managers, customs records for grain and seedstock imports, and Ministry of Agriculture and Fisheries licensing databases — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured planting calendar compliance and irrigation quota enforcement patterns from Public Authority for Water and Wastewater Services borehole monitoring data. Secondary validation drew from GCC standardization protocol documentation, cooperative aggregation volume reports, and desalination cost structure disclosures from Ministry of Energy and Minerals rural electrification programs.
Data-stream reconciliation applied across the analysis window modeled segmentation dimensions spanning production system type, buyer channel tier, and logistics format with regional governorates as the geographic cluster. CAGRs were derived from trajectory fitting against subsidy program disbursement schedules and aquaculture license issuance rates. Forecast inputs incorporated groundwater extraction quota enforcement intensity and renewable-powered pumping adoption curves under Ministry of Energy and Minerals programs.
The model assumes a particular technology adoption path; alternative pathways for solar photovoltaic integration with groundwater extraction would alter the outlook for smallholder viability in interior governorates. Forecasts reflect assumptions around desalination cost stabilization and GlobalGAP certification timeline compression. A small set of named triggers — desalination energy price spikes, borehole meter enforcement acceleration, and Dutch propagator supply disruptions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Frozen Egg Market
Agriculture and Agri Products
Asia-Pacific Rapeseed Oil Market
Agriculture and Agri Products
Feed Grade Oils Market
Agriculture and Agri Products
Global Palm Oil Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Rice Straw Market
Agriculture and Agri Products
Uncaria Tomentosa Market
Agriculture and Agri Products
United States Alfalfa Market
Agriculture and Agri Products
Bee Pollen Market
Agriculture and Agri Products
United Kingdom Commercial Greenhouse Market
Agriculture and Agri Products
Plant Breeding Market
Agriculture and Agri Products
Non GMO Soybean Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Philippines Feed Industry Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
Italy Alfalfa Market