
 Global Palm Oil Market | 2026-2036
Global Palm Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Palm Oil Market Intelligence
Indonesian plantation expansion is rewriting supply geography across edible oil value chains. Wilmar International leverages integrated crushing and refining assets across Sumatra and Kalimantan to sustain cost leadership in bulk exports. Golden Agri-Resources anchors its position through traceable supply chain certification covering upstream estates and downstream processing. IOI Corporation competes on specialty fat fractions for confectionery and bakery applications.
Palm oil denotes the triglyceride-rich mesocarp extract from Elaeis guineensis fruit, containing roughly 50% saturated palmitic acid and 40% monounsaturated oleic acid, recovered through steam sterilization, pressing, and solvent extraction for food manufacturing and oleochemical feedstock. Crude palm oil dominates volume flows into bulk refining and biodiesel conversion, while derivatives command margin concentration in personal care and industrial lubricant formulations. Refined palm oil leads food and beverage application value given its oxidative stability and neutral flavor profile.
Indonesia's Ministry of Environment and Forestry enforces mandatory ISPO certification on domestic producers, while the EU Deforestation Regulation shapes market access conditions for European-bound shipments. Malaysia's MSPO standard and the Roundtable on Sustainable Palm Oil framework collectively determine eligibility for premium-tier procurement contracts. Stakeholders must monitor evolving traceability requirements and biodiesel blending mandates to calibrate capacity allocation between food-grade refining and renewable fuel output.
Market Dynamics
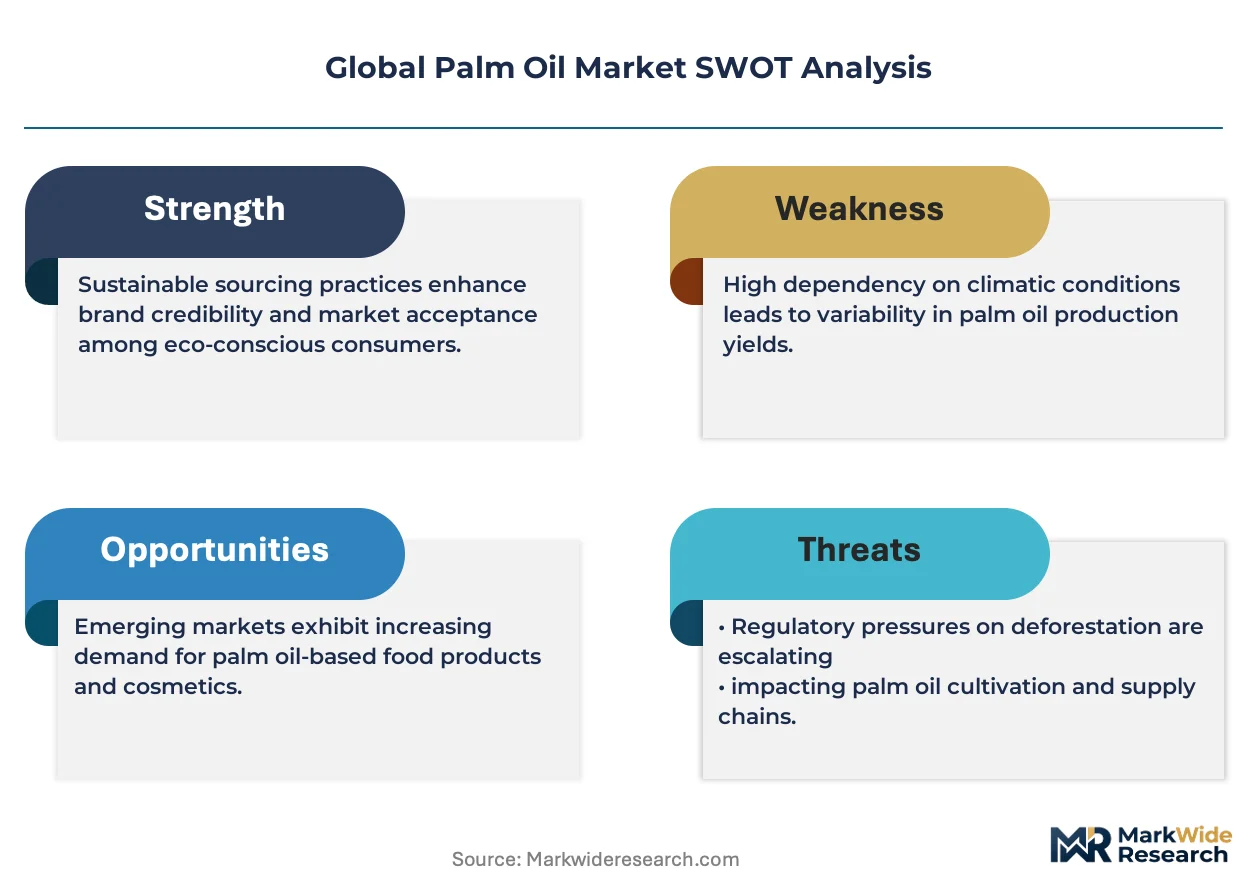
Indonesia's ISPO certification mandate is compressing supply timelines and forcing consolidation among mid-tier estates that lack capital for traceability infrastructure. This regulatory pressure is redrawing competitive boundaries between integrated majors and fragmented smallholders.
Growth Catalysts
- EU Deforestation Regulation:European procurement rules now require geolocation verification for every shipment, pulling certified Indonesian and Malaysian volumes into premium contract tiers.
- Biodiesel blending mandates:Indonesia's B40 program and Malaysia's B20 requirements are absorbing surplus CPO into domestic fuel pools, tightening export availability.
- Oleochemical feedstock demand:Personal care and industrial lubricant manufacturers are substituting petrochemical bases with palm-derived fatty alcohols and esters.
Market Restraints
- Labor cost volatility:Malaysian estate wages are rising faster than mechanization can offset, squeezing processing margins at independent mills.
- Upstream concentration risk:Kalimantan and Sumatra supply basins face recurrent haze-related export suspensions that disrupt just-in-time refining schedules.
- Substitution threat from shea and coconut oils:Cosmetics formulators are diversifying tropical fat sources to reduce single-origin dependency.
Strategic Opportunities
- India's untapped food processing sector:Bakery and confectionery manufacturers in Maharashtra and Gujarat are expanding capacity without secured long-term supply contracts.
- Specialty fat fractionation:High-value olein and stearin outputs for chocolate and pastry applications command pricing multiples over bulk refined grades.
- Blockchain-enabled traceability:Integrated platforms linking plantation GPS data to refinery certificates are unlocking preferential financing terms from sustainability-linked lenders.
Industry Challenges
- ISPO compliance timelines:Smallholder cooperatives face 18-month certification windows that delay market access.
- Legacy mill automation gaps:Mid-scale processors in Borneo lack capital to retrofit pressing and clarification systems for yield optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Palm Oil Market |
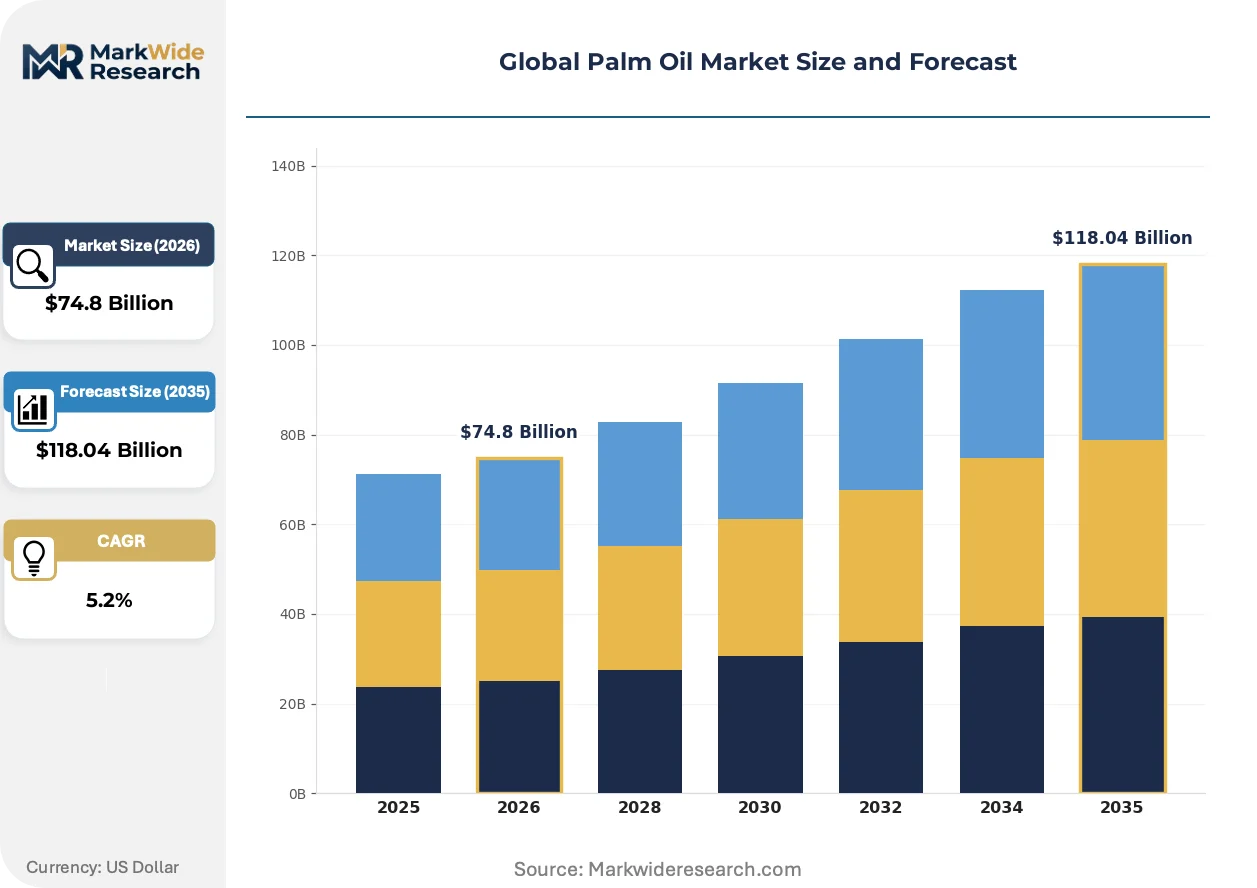
| Market Size in 2026 | $74.8 Billion |
| Market Size in 2035 | $118.04 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Palm Oil, Refined Palm Oil, Palm Kernel Oil, Derivatives Application: Food & Beverage, Biofuel, Personal Care, Animal Feed, Industrial Lubricants End User Industry: Food Processing, Cosmetics Manufacturers, Renewable Energy Providers, Animal Nutrition Companies Packaging Type: Bulk Containers, Bottles, Pouches, Drums |
| Companies Covered | Wilmar International Ltd., Golden Agri-Resources Ltd., IOI Corporation, Kuala Lumpur Kepong Berhad, Musim Mas Group, Cargill, Archer Daniels Midland Company, FGV Holdings Berhad, Louis Dreyfus Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Palm Oil Market Strategic Shifts & Innovations
Digital traceability infrastructure is displacing paper-based chain-of-custody systems across Southeast Asian supply networks. Satellite monitoring and IoT sensors are becoming baseline requirements for accessing European and North American procurement channels.
Remote sensing combined with machine learning is digitizing deforestation risk assessment for financial institutions and buyers. Major plantation groups in Riau and Central Kalimantan are deploying drone-mounted multispectral cameras to detect illegal clearing within concession boundaries. This technology is compressing due diligence cycles from quarterly audits to real-time alerts, enabling faster trade finance approvals.
REACH and the EU Deforestation Regulation are tightening chemical disclosure and origin verification requirements for oleochemical imports. European formulators must now document every processing step from fresh fruit bunch to refined derivative. Specialty chemical distributors are responding by pre-certifying entire product lines, shifting procurement risk upstream to Indonesian and Malaysian refiners.
Buyer concentration among multinational food manufacturers is forcing estate groups to unbundle traditional long-term offtake contracts. Nestlé and Unilever are consolidating supplier panels and demanding segregated supply chains with dedicated refining capacity. This pattern is most visible in Johor and Rotterdam, where dedicated tankage and processing lines are being constructed to serve single-buyer volumes.
Global Palm Oil Market Segmentation
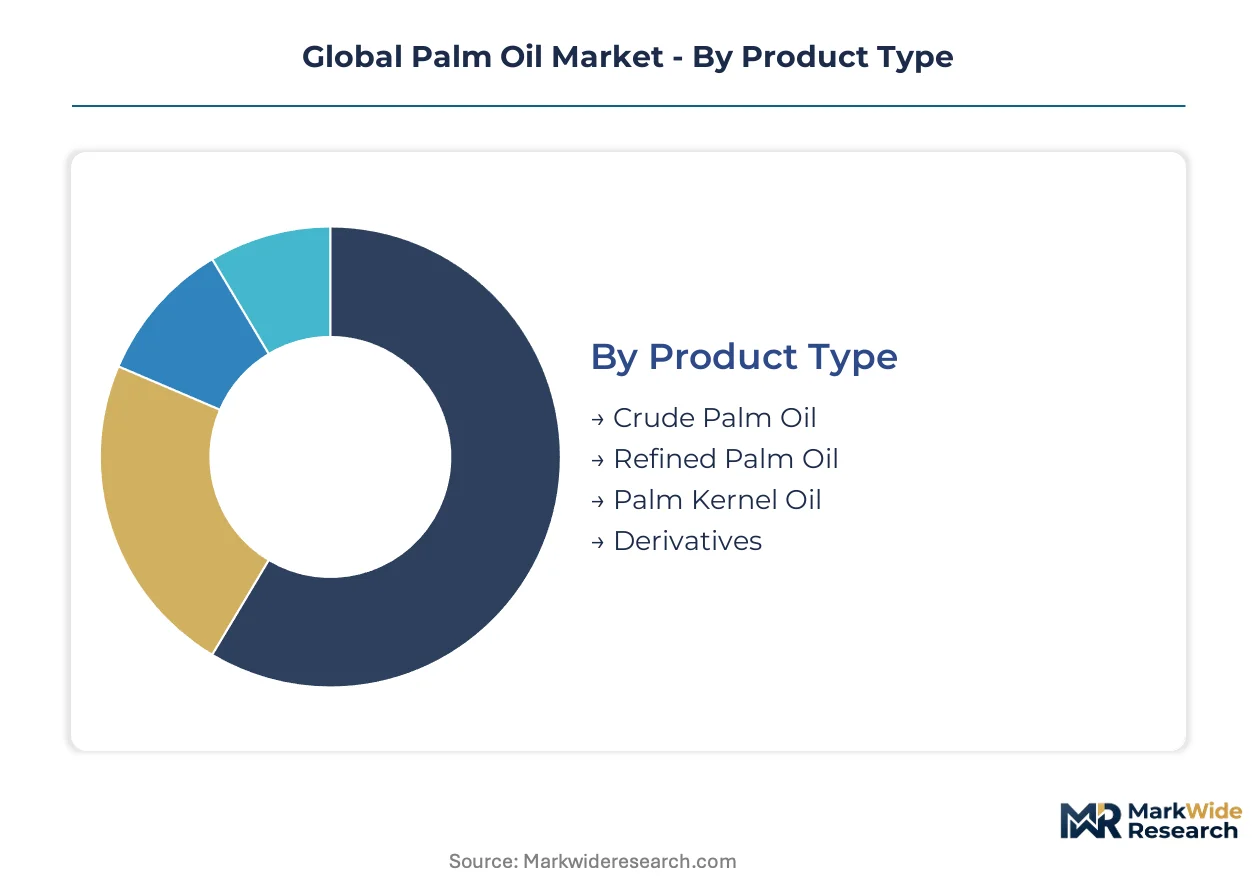
Palm oil segmentation reflects divergent margin structures across the value chain. Product grade determines processing intensity and certification requirements. Application mix shifts with biodiesel policy and oleochemical substitution trends.
Product Type:
Cost tier separates commodity flows from value-added derivatives. Each grade carries distinct capital requirements and margin profiles.
- Crude Palm Oil:Unrefined mesocarp extract containing carotenoids and free fatty acids. Indonesian biodiesel mandates absorb Kalimantan and Sumatra output into domestic B40 blending pools, tightening export availability for refiners.
- Refined Palm Oil:Bleached and deodorized product meeting food-grade specifications for oxidative stability. Malaysian refineries in Johor and Port Klang serve Nestlé and Unilever under segregated supply contracts with dedicated tankage.
- Palm Kernel Oil:Endosperm extract with higher lauric acid content for soap and surfactant feedstock. Processing concentrates in integrated complexes with shared crushing infrastructure.
- Derivatives:Fractionated olein, stearin, and distilled fatty acids for specialty applications. Personal care formulators in Europe specify RSPO-certified grades under REACH disclosure rules.
Refined palm oil commands the established base. The steepest expansion runs through derivatives.
Application:
End-use maturity varies sharply across sectors. Food processing represents embedded demand while biofuel absorbs policy-driven volume swings.
- Food & Beverage:Bakery, confectionery, and frying applications requiring stable crystallization behavior. Indian processors in Maharashtra and Gujarat expand capacity without long-term supply security.
- Biofuel:Biodiesel and renewable diesel meeting blending mandates. Indonesia's B40 program and Malaysia's B20 requirements divert CPO from export channels.
- Personal Care:Fatty alcohols and esters replacing petrochemical bases. European formulators face EU Deforestation Regulation geolocation verification for every shipment.
- Animal Feed:Palm kernel expeller as protein supplement. Demand tracks livestock production in Southeast Asian poultry operations.
- Industrial Lubricants:Biodegradable base stocks for marine and hydraulic applications. Oleochemical producers in Rotterdam and Hamburg pre-certify product lines for REACH compliance.
Food and beverage maintains volume leadership. Biofuel is climbing the fastest as policy absorption tightens export balances.
End User Industry:
Customer type determines procurement sophistication and contract structure. Multinationals impose traceability requirements that fragment supplier panels.
- Food Processing:Integrated manufacturers from bakery to snack segments. ISPO and MSPO certification gates access to European and North American procurement channels.
- Cosmetics Manufacturers:Formulators seeking RSPO segregated supply with blockchain-verified chain of custody. L'Oréal and Unilever consolidate supplier relationships around dedicated refining capacity.
- Renewable Energy Providers:Fuel blenders operating under Indonesia's B40 and Malaysia's B20 mandates. Domestic absorption reduces exportable surplus.
- Animal Nutrition Companies:Compound feed producers integrating palm kernel expeller into ruminant and poultry rations. Price sensitivity favors spot procurement over long-term contracts.
Food processing anchors procurement volume. Cosmetics manufacturers are gaining share fastest through sustainability premium structures.
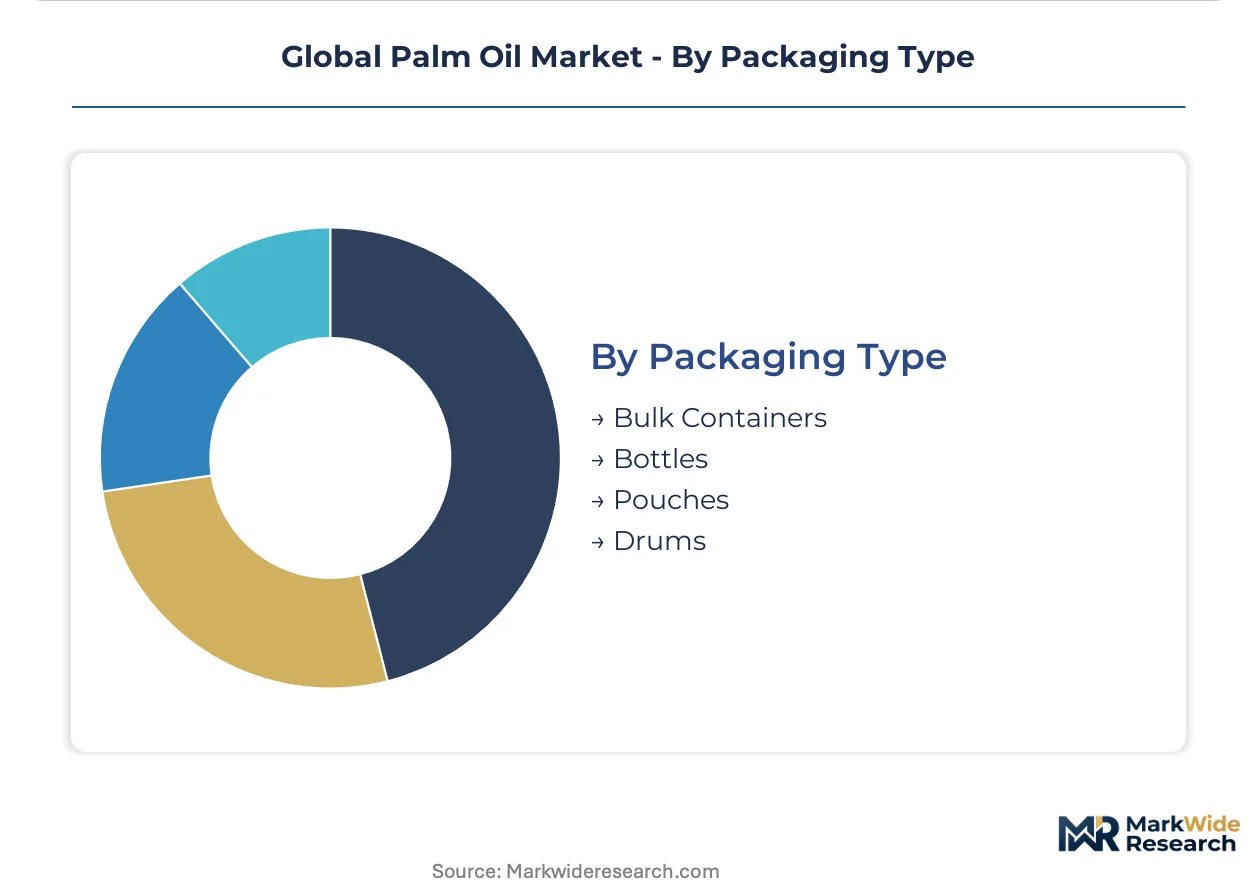
Packaging Type:
Volume scale dictates logistics configuration. Bulk dominates intercontinental flows while retail formats serve fragmented downstream channels.
- Bulk Containers:ISO tank containers and flexitanks for refinery-to-refinery transfers. Rotterdam and Singapore serve as consolidation hubs for European and Asian distribution.
- Bottles:Consumer retail formats for cooking oil segments. Malaysian and Indonesian brands compete in Middle Eastern and African markets.
- Pouches:Single-serve and household units for price-sensitive buyers. Indian and Nigerian markets favor this format for affordability.
- Drums:Intermediate industrial packaging for oleochemical and food ingredient customers. Just-in-time delivery requirements favor regional drum-filling operations.
Bulk containers handle the foundational throughput. Pouches are expanding most quickly in emerging market retail penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia channels nearly two-thirds of its palm oil into domestic biodiesel pools, whereas India and China prioritize food-grade imports for processed food manufacturing. This consumption-mix differential shapes infrastructure investment patterns across origin and destination markets.
Indonesia
Kalimantan and Sumatra estates feed integrated refining complexes serving export markets. The Ministry of Environment and Forestry enforces mandatory ISPO certification, compressing supply timelines for uncertified smallholders. Riau province hosts the densest concentration of traceability-enabled crushing operations supplying European food manufacturers.
Malaysia
Johor and Port Klang refining clusters specialize in segregated supply contracts for multinational food processors. The Malaysian Sustainable Palm Oil (MSPO) standard gates access to premium procurement tiers. Peninsular Malaysia's estate sector faces accelerating wage pressure as mechanization lags labor cost inflation.
India
Maharashtra and Gujarat food processors expand bakery and confectionery capacity without secured long-term supply contracts. FSSAI food safety standards govern refined oil import quality specifications. Mumbai and Ahmedabad serve as consolidation hubs for bulk shipments redirected from Indonesian biodiesel diversion.
China
Guangdong and Fujian provinces absorb crude palm oil for food manufacturing and oleochemical feedstock. SAMR food safety regulations align with import quality protocols. Ningbo and Guangzhou ports handle the largest CPO discharge volumes for domestic refining and re-export processing.
Netherlands
Rotterdam functions as Europe's primary refining and distribution gateway for RSPO-certified volumes. The EU Deforestation Regulation mandates geolocation verification for every shipment entering European customs territory. Dedicated tankage and processing lines serve single-buyer contracts from segregated supply chains.
Global Palm Oil Market Key Industry Players
Capability concentration sits with integrated plantation-to-refinery groups; scale advantage sits with global trading houses with multi-origin sourcing networks. The market structures around three tiers: upstream estate owners with captive crushing capacity, midstream refiners serving branded food customers, and commodity traders arbitraging regional price differentials. Consolidation pressures favor backward integration into plantation assets and forward integration into specialty oleochemical derivatives.
Among Singapore-based integrated groups, Wilmar International Ltd. and Golden Agri-Resources Ltd. exemplify the plantation-to-refinery archetype with traceable supply chain certification covering upstream estates. IOI Corporation occupies a position within the specialty derivatives tier, competing on fractionated fat outputs for confectionery and bakery applications. These three anchors illustrate how certification compliance and refining specialization determine contract access in procurement channels governed by European sustainability mandates.
| Leading Market Players |
|---|
| Wilmar International Ltd. |
| Golden Agri-Resources Ltd. |
| IOI Corporation |
| Kuala Lumpur Kepong Berhad |
| Musim Mas Group |
| Cargill |
| Archer Daniels Midland Company |
| FGV Holdings Berhad |
| Louis Dreyfus Company |
| Others |
Cost & Logistics Intelligence
Undercapacity in Malaysian peninsular estates is compressing supplier bargaining power while amplifying price volatility for spot CPO purchases. This utilization squeeze forces integrated groups to prioritize long-term offtake commitments over discretionary export sales, tightening availability for independent refiners.
Pricing Analysis
Long-term offtake contracts dominate volume flows between Indonesian plantation groups and European food manufacturers, while spot markets absorb residual CPO diverted from biodiesel pools. Price differentiation rests on ISPO-RSPO certification tiers and dedicated tankage access at Rotterdam and Johor. Pricing pressure stems from Malaysian wage inflation outpacing mechanization gains, eroding processing margins at independent mills. Smallholder cooperatives exhibit highest price sensitivity due to fragmented selling power, while Nestlé and Unilever leverage consolidated procurement panels to lock in segregated supply premiums.
Supply Chain Analysis
Tariff exposure between EU customs territory and Indonesian export channels is reshaping sourcing patterns as the EU Deforestation Regulation mandates geolocation verification for every shipment. Supply concentrates in Indonesia, Malaysia, and increasingly India as a demand hub. Raw material flows draw from fresh fruit bunches in Kalimantan and Sumatra estates, with lauric acid feedstock tethered to Malaysian palm kernel crushing. Single-source vulnerability runs through Rotterdam as Europe's sole major refining gateway. Distribution runs through bulk ISO tank containers and flexitanks from Singapore consolidation hubs to Ningbo and Mumbai discharge ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled traceability infrastructure is transforming this market into a platform-economy inflection where data interoperability between plantation GPS systems and refinery certificates unlocks preferential financing terms. This ecosystem shift rewards early movers who embed digital infrastructure across upstream-downstream boundaries.
For Market Incumbents: Entrench control over segregated supply chains by constructing dedicated tankage and processing lines for single-buyer contracts at Rotterdam and Johor. Deepen backward integration into Riau and Central Kalimantan estates to secure traceable feedstock against ISPO compliance timelines. Certification investment remains the critical lever as EU Deforestation Regulation enforcement tightens market access gates. For New Entrants and Emerging Players: Establish a beachhead in India's Maharashtra and Gujarat food processing corridor where bakery and confectionery capacity expands without secured long-term supply contracts. Target specialty oleochemical derivatives for personal care formulators seeking REACH-compliant fatty alcohol substitutes. A go-to-market angle anchored in pre-certified product lines shifts procurement risk upstream while capturing sustainability premium structures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across traceability infrastructure and segregated refining capacity as compliance requirements harden. Mid-scale processors in Borneo with legacy mill automation gaps represent viable acquisition targets for consolidation plays. The signal to watch is biodiesel blending mandate expansion in Indonesia and Malaysia, which diverts CPO from export channels and tightens refined product availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captures ISPO-compliant feedstock in Riau and Central Kalimantan for European contract eligibility. |
| Blockchain-Enabled Traceability Deployment | Links plantation GPS data to refinery certificates for sustainability-linked lender financing. |
| Specialty Oleochemical Capacity Expansion | Captures margin multiples in fractionated olein and stearin for chocolate and pastry applications. |
| Segregated Supply Chain Construction | Builds dedicated tankage at Rotterdam and Johor for Nestlé and Unilever single-buyer volumes. |
| Indian Market Distribution Partnership | Secures channel access in Maharashtra and Gujarat for bakery and confectionery processor demand. |
Research Approach
Initial hypotheses were tested against primary input from plantation operations managers, refinery procurement leads, European food manufacturer sustainability officers, and oleochemical R&D directors and refined through secondary validation. Trade flow data from Indonesian customs records, Malaysian Palm Oil Board statistics, EU import disclosure filings, and RSPO certification databases anchored supply-side quantification. Bottom-up estate production estimates and top-down regional consumption models were triangulated to reconcile volume figures.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning product grade tiers, application mix shifts between food and biofuel, end-user industry procurement sophistication, and regional regulatory clusters. CAGRs were derived from modeled production capacity additions against policy-driven absorption rates. Biodiesel blending mandate trajectories and EU Deforestation Regulation implementation timelines served as key forecast inputs.
Stress conditions across haze-related export suspensions, labor cost inflation trajectories, and substitution elasticity for shea and coconut oils were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification penetration rates and mechanization adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Cameroon Agriculture Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Floriculture Market
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
US Greenhouse Horticulture Market
Agriculture and Agri Products
Kuwait Poultry Meat Market
Agriculture and Agri Products
Rice Straw Market
Agriculture and Agri Products
Asia Pacific Poultry Feed Market
Agriculture and Agri Products
Africa Compound Feed Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
Poultry Processing Product Market
Agriculture and Agri Products
Italy Animal Protein Market