
 Green Power Market | 2026-2036
Green Power Market Size, Share, and Industry Trends Forecast 2026-2036
Green Power Market Intelligence
Multi-source procurement of solar modules and wind turbines is rebalancing supply relationships across the green power value chain. NextEra Energy anchors its position through captive project development pipelines in North America. LONGi Green Energy dominates crystalline silicon wafer manufacturing through backward integration into polysilicon refining. Vestas Wind Systems competes on turbine platform specialization for both onshore and offshore environments.
Green power encompasses electricity generated from renewable sources with near-zero operational carbon emissions, typically harnessing photovoltaic conversion, aerodynamic rotor capture, gravitational water flow, or organic combustion with carbon-neutral feedstock cycles. Solar photovoltaic systems convert sunlight at 18-22% cell efficiency into direct current for grid injection or behind-the-meter consumption. Wind and solar installations lead capacity additions globally, while hydropower retains the largest installed base and most stable capacity factor. Industrial end users represent the fastest-growing demand pool as corporations execute power purchase agreements to meet scope-two emission targets.
The EU Green Deal and F-Gas Regulation constrain refrigerant emissions in heat pumps paired with renewable generation, while China's MIIT enforces GB standards for grid-interactive inverter performance. The US IRA production tax credits reshape project finance structures for utility-scale developers. Stakeholders must monitor how interconnection queue reforms and storage co-location mandates alter project economics and delivery timelines.
Market Dynamics
Data center operators now account for the largest incremental electricity demand growth in developed economies, forcing renewable developers to co-locate generation with high-load facilities and reconfigure interconnection strategies around latency-sensitive compute clusters.
Growth Catalysts
- Corporate Scope-Two Targets:Heavy manufacturing and technology sectors execute power purchase agreements to neutralize operational emissions, pulling forward utility-scale solar and wind deployment timelines.
- EU Green Deal Mandates:National carbon budgets in Germany, France, and Spain enforce clean electricity quotas for steel, cement, and chemical producers, creating guaranteed offtake pools.
- Grid-Interactive Inverter Standards:China's MIIT enforces GB performance requirements that accelerate distributed generation integration and stabilize voltage profiles across provincial networks.
Market Restraints
- Polysilicon Supply Concentration:Crystalline silicon wafer production depends on refining capacity clustered in specific provinces, exposing module manufacturers to input cost volatility and trade policy disruptions.
- Interconnection Queue Congestion:US FERC Order 2023 reforms aim to reduce study backlogs, but regional transmission organizations still impose multi-year delays on utility-scale project energization.
- Land-Use Competition:Utility-scale solar and onshore wind projects face siting opposition from agricultural interests and conservation groups, compressing developable acreage in high-resource zones.
Strategic Opportunities
- Storage Co-Location Mandates:Several US state public utility commissions now require battery pairing for new renewable interconnection, creating integrated project development opportunities.
- Green Hydrogen Feedstock:Electrolyzer deployments for ammonia and steel production create baseload demand profiles that stabilize revenue streams for isolated wind and solar assets.
- Behind-the-Meter Industrial:Manufacturing clusters in India and Southeast Asia underutilize captive renewable potential, opening direct PPA structures that bypass regulated utility tariffs.
Industry Challenges
- Specialized Technician Scarcity:High-voltage DC converter stations and offshore turbine maintenance require certified electricians and marine crews that training pipelines have failed to replenish.
- Supply Chain Reconfiguration:Module and inverter manufacturers face forced localization requirements under US IRA domestic content rules, demanding capital-intensive facility relocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Power Market |
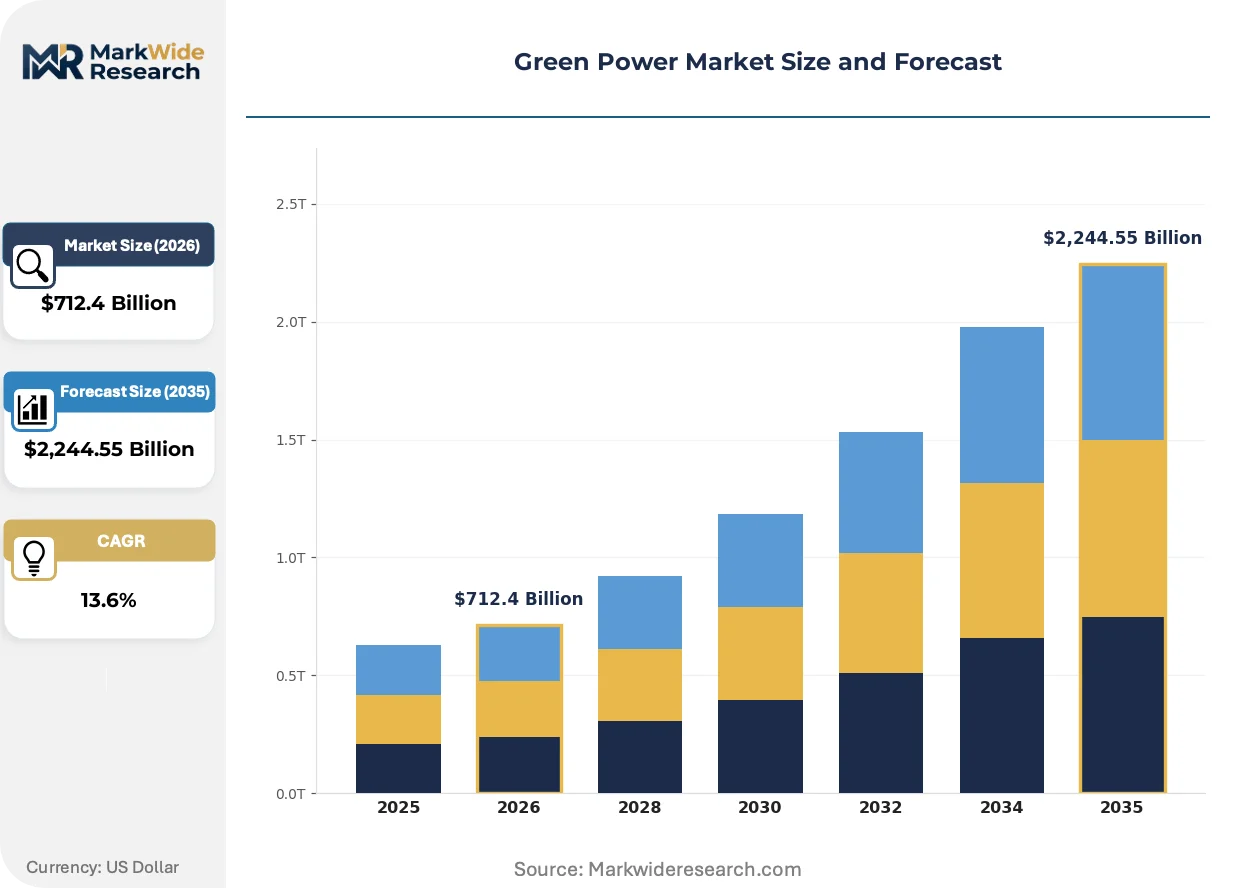
| Market Size in 2026 | $712.4 Billion |
| Market Size in 2035 | $2,244.55 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Hydropower, Biomass End User: Residential, Commercial, Industrial, Utilities Power Source: Renewable, Non-renewable, Geothermal, Tidal Installation Type: On-grid, Off-grid, Hybrid, Distributed |
| Companies Covered | NextEra Energy, Sungrow Power Supply, ACWA Power, Vestas Wind Systems, Adani Green Energy, LONGi Green Energy, Brookfield Renewable Partners, First Solar, China Three Gorges Renewables, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Power Market Strategic Shifts & Innovations
Technological convergence between generation assets and digital control systems is compressing dispatch response times and enabling synthetic inertia services that replace retiring thermal plant capabilities.
Bifacial photovoltaic modules with tracking systems is expanding into utility-scale deployments across high-irradiance regions. Independent power producers in Spain, Chile, and Australia adopt these configurations to capture albedo reflection and extend productive hours. The technology is expanding into markets previously dominated by fixed-tilt installations, compressing levelized cost benchmarks and forcing EPC contractors to retrain installation crews.
The US Inflation Reduction Act production tax credits reshape project finance structures for utility-scale developers. Transferability provisions allow tax-equity partnerships to monetize credits without traditional sponsor tax appetite, broadening capital access. Renewable developers in Texas, California, and the Midwest restructure ownership vehicles to capture full incentive value while navigating IRS guidance on domestic content bonuses.
Large energy buyers now consolidate procurement through centralized sustainability offices rather than fragmented facility-level decisions. Technology corporations and data center operators in Northern Virginia, Frankfurt, and Singapore establish dedicated renewable energy teams that negotiate multi-gigawatt portfolios directly with developers. This concentration of purchasing power compresses developer margins while accelerating contract standardization across jurisdictions.
Green Power Market Segmentation
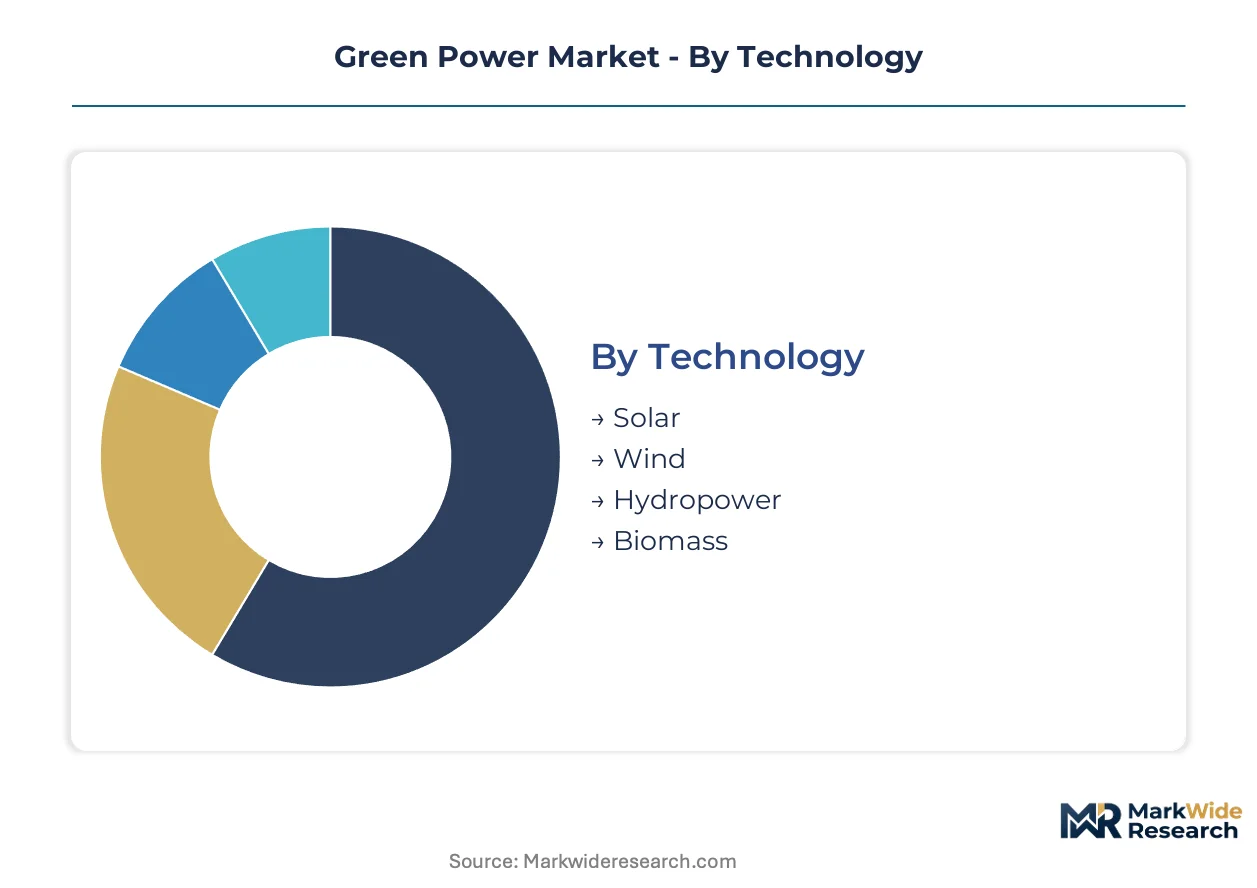
Green power market segmentation reveals how technology choices, end-user profiles, and installation configurations create divergent certification pathways and capital intensity requirements. Understanding these divisions helps developers align project structures with regulatory incentives and offtake risk profiles.
Technology:
Solar and wind installations face distinct equipment certification regimes under IEC standards and national grid codes, while hydropower and biomass confront lengthier environmental permitting cycles.
- Solar:Photovoltaic systems convert sunlight through crystalline silicon or thin-film cells at 18-22% efficiency, with module-level power electronics enabling rapid shutdown compliance. Utility-scale deployments in Spain and Australia increasingly pair bifacial panels with single-axis tracking to capture albedo reflection and extend productive hours.
- Wind:Aerodynamic rotor systems span onshore turbines up to 6 MW and offshore platforms exceeding 15 MW, requiring type certification under IEC 61400 and marine-specific approvals for substructures. Demand concentrates in the North Sea and Chinese coastal provinces where water depth and wind resource density justify capital-intensive foundation engineering.
- Hydropower:Gravitational water flow systems retain the largest installed base globally, with run-of-river configurations facing fewer resettlement concerns than large reservoir projects.
- Biomass:Organic combustion with carbon-neutral feedstock cycles requires air quality permits and sustainable sourcing certification under EU sustainability criteria.
Solar sits at the top of the volume ranking, with wind climbing the fastest as offshore installations expand into deeper waters.
End User:
Customer scale determines contract structures, with industrial offtakers commanding bilateral PPA negotiations while residential segments depend on standardized net metering frameworks.
- Residential:Behind-the-meter rooftop systems under 20 kW rely on simplified interconnection protocols and consumer financing products, with installation growth concentrated in states with favorable net metering policies.
- Commercial:Mid-scale deployments from 100 kW to 5 MW serve retail chains and corporate campuses, with C&I buyers in Northern Virginia and Frankfurt consolidating procurement through centralized sustainability offices.
- Industrial:Heavy manufacturing and data center operators execute multi-gigawatt portfolios to neutralize scope-two emissions, with steel and chemical producers in Germany and Spain responding to EU Green Deal clean electricity quotas.
- Utilities:Regulated and competitive power suppliers procure renewable capacity through integrated resource planning processes, with US utilities navigating FERC interconnection queue reforms.
Utilities dominate current capacity additions, though industrial offtakers are gaining share fastest as corporate sustainability targets harden into procurement mandates.
Power Source:
Source classification shapes eligibility for production tax credits, renewable portfolio standards, and green certificate trading schemes across jurisdictions.
- Renewable:Solar, wind, and qualifying biomass feedstocks qualify for US IRA production tax credits and EU guarantee of origin schemes, creating standardized revenue stacking opportunities.
- Non-renewable:Fossil and nuclear generation remains relevant for grid balancing and baseload provision, though carbon pricing erodes competitiveness in covered markets.
- Geothermal:Heat extraction from subsurface reservoirs provides dispatchable renewable output, with enhanced geothermal systems expanding resource availability beyond traditional hydrothermal zones.
- Tidal:Gravitational capture from marine currents offers predictable generation profiles but requires site-specific environmental assessments and specialized turbine mooring approvals.
Renewable sources command the largest development pipeline, with geothermal expanding most quickly as drilling technology unlocks previously inaccessible resources.
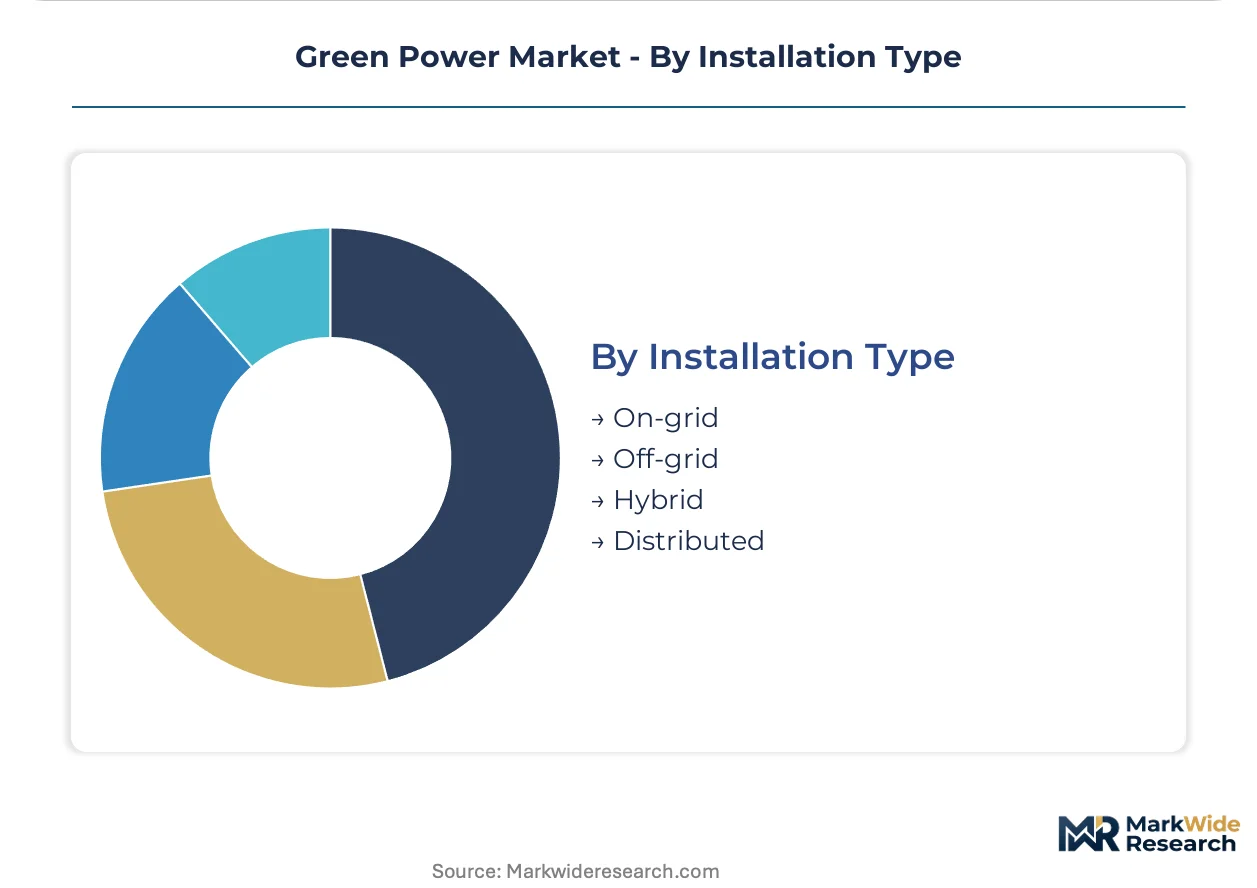
Installation Type:
Grid connection status determines inverter standards, storage co-location requirements, and revenue model complexity for project developers.
- On-grid:Grid-connected systems inject power at distribution or transmission voltage levels, with China's MIIT enforcing GB standards for grid-interactive inverter performance to stabilize voltage profiles across provincial networks.
- Off-grid:Standalone systems serve remote industrial sites and rural electrification programs, with diesel displacement economics driving adoption in mining and agricultural applications.
- Hybrid:Renewable-plus-storage configurations meet emerging mandates from US state public utility commissions requiring battery pairing for new interconnection, creating integrated project development opportunities.
- Distributed:Small-scale generation located near consumption points reduces transmission losses and defers grid upgrades, with virtual power plant aggregation enabling participation in wholesale markets.
On-grid installations retain the largest cumulative capacity, with hybrid configurations showing the steepest expansion trajectory as storage economics improve and mandate coverage spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Inner Mongolia anchors renewable deployment through state-backed wind and solar corridors that feed coastal demand centers. Provincial renewable portfolio standards accelerate utility-scale construction across high-resource zones.
United States
Data center operators in Northern Virginia and Texas account for the largest incremental electricity demand growth, forcing developers to co-locate generation with latency-sensitive compute clusters. FERC Order 2023 reforms target interconnection queue congestion, though regional transmission organizations still impose multi-year delays. ERCOT and CAISO markets see accelerated solar-plus-storage proposals as developers restructure ownership vehicles to capture IRA production tax credits.
China
Provincial renewable portfolio standards in Inner Mongolia, Xinjiang, and Gansu accelerate utility-scale deployment through state-backed project pipelines. MIIT enforces GB standards for grid-interactive inverter performance that stabilize voltage profiles across provincial networks. Yangtze River Delta manufacturing clusters absorb clean electricity quotas mandated under dual carbon goals.
Germany
National carbon budgets under the EU Green Deal enforce clean electricity quotas for steel, cement, and chemical producers in the Ruhr and Bavarian industrial corridors. The F-Gas Regulation constrains refrigerant emissions in heat pumps paired with renewable generation. Offshore wind auctions in the North Sea attract developers seeking long-term offtake certainty.
Spain
Solar irradiance in Extremadura and Andalusia drives bifacial photovoltaic deployment with single-axis tracking configurations. Independent power producers adopt these systems to capture albedo reflection and extend productive hours. EU guarantee of origin schemes create standardized revenue stacking opportunities for utility-scale assets.
India
Gujarat and Rajasthan host the largest concentration of utility-scale solar parks under central government auction mechanisms. Manufacturing clusters in Maharashtra and Tamil Nadu underutilize captive renewable potential, opening direct PPA structures that bypass regulated utility tariffs. CEA guidelines shape interconnection standards for distributed generation integration.
Green Power Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue integrated project development and storage co-location opportunities. The vendor base stratifies across three maturity tiers: vertically integrated manufacturers controlling polysilicon-to-module value chains, independent power producers with captive development pipelines, and technology-agnostic EPC contractors. Competitive positioning hinges on backward integration into critical inputs, multi-gigawatt portfolio aggregation, and strategic partnerships with data center operators. Geographic expansion and technology licensing represent the dominant competitive moves as firms navigate forced localization requirements.
Within the integrated manufacturing tier, LONGi Green Energy and First Solar exemplify divergent technology pathways. NextEra Energy and Vestas Wind Systems anchor the project development and turbine supply segments respectively. Brookfield Renewable Partners occupies a position in the institutional capital tier, while Adani Green Energy represents emerging market consolidation. China Three Gorges Renewables and Sungrow Power Supply sit within the state-affiliated and power electronics archetypes. ACWA Power anchors Middle Eastern project development.
| Leading Market Players |
|---|
| NextEra Energy |
| Sungrow Power Supply |
| ACWA Power |
| Vestas Wind Systems |
| Adani Green Energy |
| LONGi Green Energy |
| Brookfield Renewable Partners |
| First Solar |
| China Three Gorges Renewables |
| Others |
Cost & Logistics Intelligence
Data center operators and industrial offtakers now concentrate procurement decisions through centralized sustainability offices, shifting contract structures toward long-term power purchase agreements with fixed-price escalators rather than spot-indexed tariffs.
Pricing Analysis
Input-cost pass-through from polysilicon refining and rare-earth magnet processing shapes module and turbine pricing, with crystalline silicon wafer producers indexing contracts to metallurgical-grade silicon spot benchmarks. Price differentiation rests on IEC certification tier and domestic content compliance under US IRA rules, with premium-tier modules commanding spreads for bifacial glass-glass construction and enhanced degradation warranties. Cost compression in standard-tier products is intensifying as Chinese manufacturers expand ingot pulling capacity. Industrial offtakers exhibit lowest price sensitivity due to scope-two compliance mandates, while distributed residential segments remain most responsive to upfront capital cost.
Supply Chain Analysis
Single-source vulnerability sits with Xinjiang-origin polysilicon and Malaysian wafer dicing capacity, exposing module assemblers to forced labor due diligence requirements and tariff exposure. Geographic supply concentration centers on China for ingot pulling and cell metallization, Vietnam for module assembly, and Germany for inverter power electronics. Raw material dependencies draw from metallurgical-grade silicon, high-purity silver paste, and neodymium-iron-boron magnets. Supply chain risk manifests through logistics chokepoints at Rotterdam and Long Beach for European and North American project delivery. Distribution runs through EPC contractors with captive installation crews rather than merchant wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The green power market has entered a late-cycle quality phase where premium-tier bifacial modules with tracking systems capture disproportionate developer attention as data center load growth hardens procurement specifications around capacity factor guarantees.
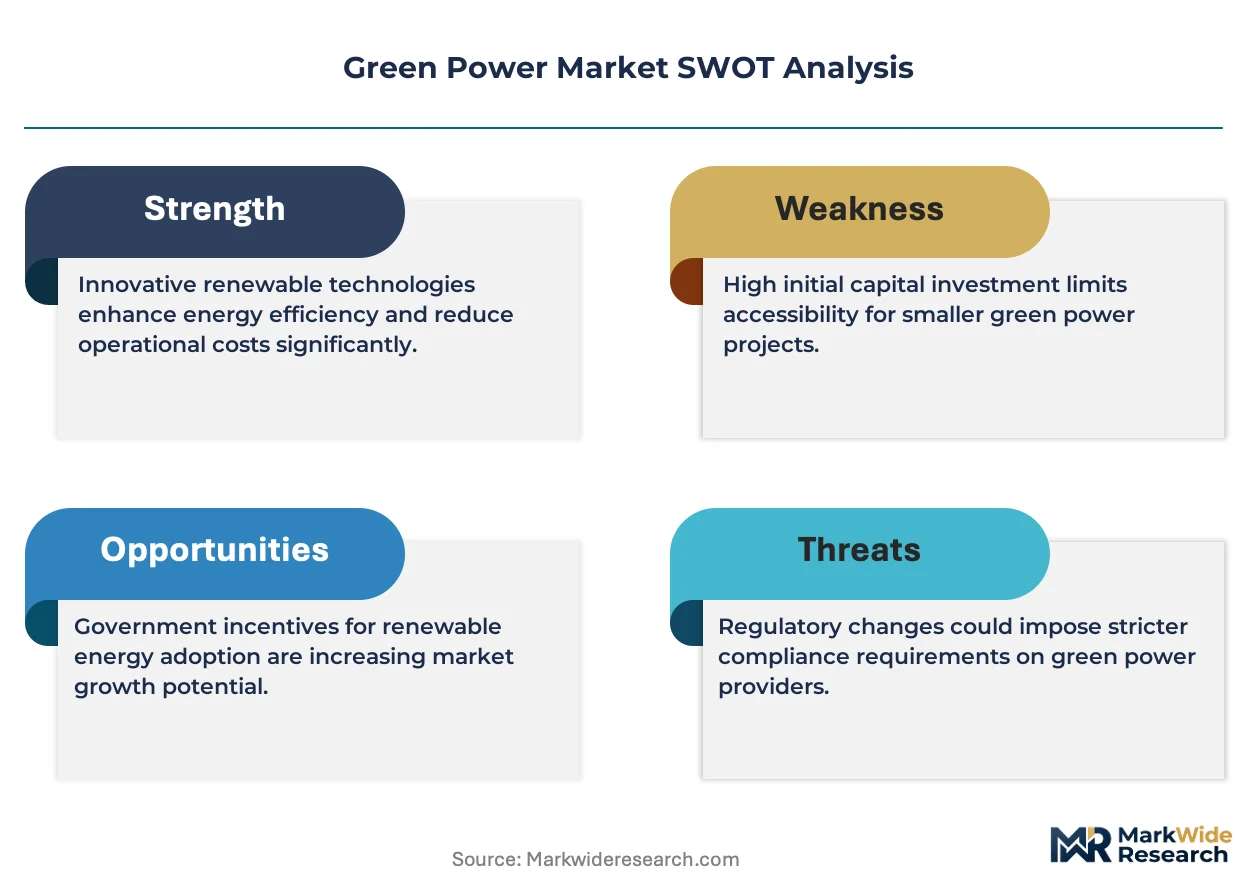
For Market Incumbents: To counter emerging entrant pressure from state-backed Chinese manufacturers expanding into European project development, established IPPs should deepen backward integration into polysilicon refining and secure captive inverter supply through strategic partnerships with power electronics specialists. Certification investment in IEC 61215/61646 tier-1 bankability status remains essential for accessing institutional tax-equity capital. For New Entrants and Emerging Players: The price-point gap between premium bifacial-tracker configurations and fixed-tilt economy installations creates entry space for mid-tier module suppliers targeting India's manufacturing clusters with direct PPA structures bypassing regulated utility tariffs. White-space targets include behind-the-meter industrial deployments in Maharashtra and Tamil Nadu, plus hybrid renewable-plus-storage proposals in ERCOT and CAISO markets where state mandates require battery co-location. For Investors and Strategic Acquirers: Data center operators are the most active acquirer in this space, consolidating development pipelines to match latency-sensitive compute load growth with dedicated generation assets. Long-term viability favors vertically integrated developers controlling land positions and interconnection rights in high-resource zones. The signal to watch is FERC Order 2023 implementation velocity, as accelerated interconnection study timelines would unlock stranded project backlogs and revalue development-stage pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive refining capacity insulates module margins from Xinjiang supply disruptions and trade policy volatility. |
| Power Purchase Agreement Consolidation | Multi-gigawatt portfolio aggregation by data center operators in Northern Virginia compresses developer margins while accelerating contract standardization. |
| Storage Co-location Mandate Compliance | Battery pairing requirements from state public utility commissions create integrated project development opportunities with enhanced revenue stacking. |
| Grid-Interactive Inverter Certification | GB standards enforcement by China's MIIT stabilizes voltage profiles and accelerates distributed generation integration across provincial networks. |
| Green Hydrogen Feedstock Positioning | Electrolyzer deployments for ammonia and steel production stabilize revenue streams for isolated wind and solar assets. |
Research Approach
Bottom-up industrial offtaker and utility procurement modeling reconciled against top-down module and turbine manufacturing capacity tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators were combined with secondary validation from EIA generation data, IEA renewable market reports, FERC interconnection filings, and project development databases to triangulate supply-demand balances across technology segments.
Historical trendline analysis of capacity additions, equipment pricing, and interconnection queue durations established baseline growth patterns across the projection horizon. The analytical framework modeled segmentation dimensions including generation technology, end-user scale, installation configuration, and regional regulatory framework. CAGRs were derived from regression analysis of deployment trajectories against policy incentive schedules and corporate procurement commitments, with specific inputs from IRA production tax credit transferability provisions and EU Green Deal carbon budget enforcement timelines.
The model assumes a particular technology adoption path; alternative pathways for enhanced geothermal systems or floating offshore wind would alter the outlook if drilling or substructure engineering achieves cost breakthroughs. Forecasts reflect assumptions around interconnection reform implementation, storage cost decline curves, and trade policy continuity that could revise projections through supply chain reconfiguration or tariff escalation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Renewable Energy in South America Market
Renewable Energy
Uzbekistan Renewable Energy Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Biomethane Certificate Trading Platform Market
Renewable Energy
Renewable Heating Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
Wave Energy Market
Renewable Energy
Solar Watch Market
Renewable Energy
Australia Renewable Energy Market
Renewable Energy
Wind Turbine Automation Market
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
LAMEA Ocean Power Market