
 Southern Africa Renewable Energy Market | 2026-2036
Southern Africa Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Southern Africa Renewable Energy Market Analytics
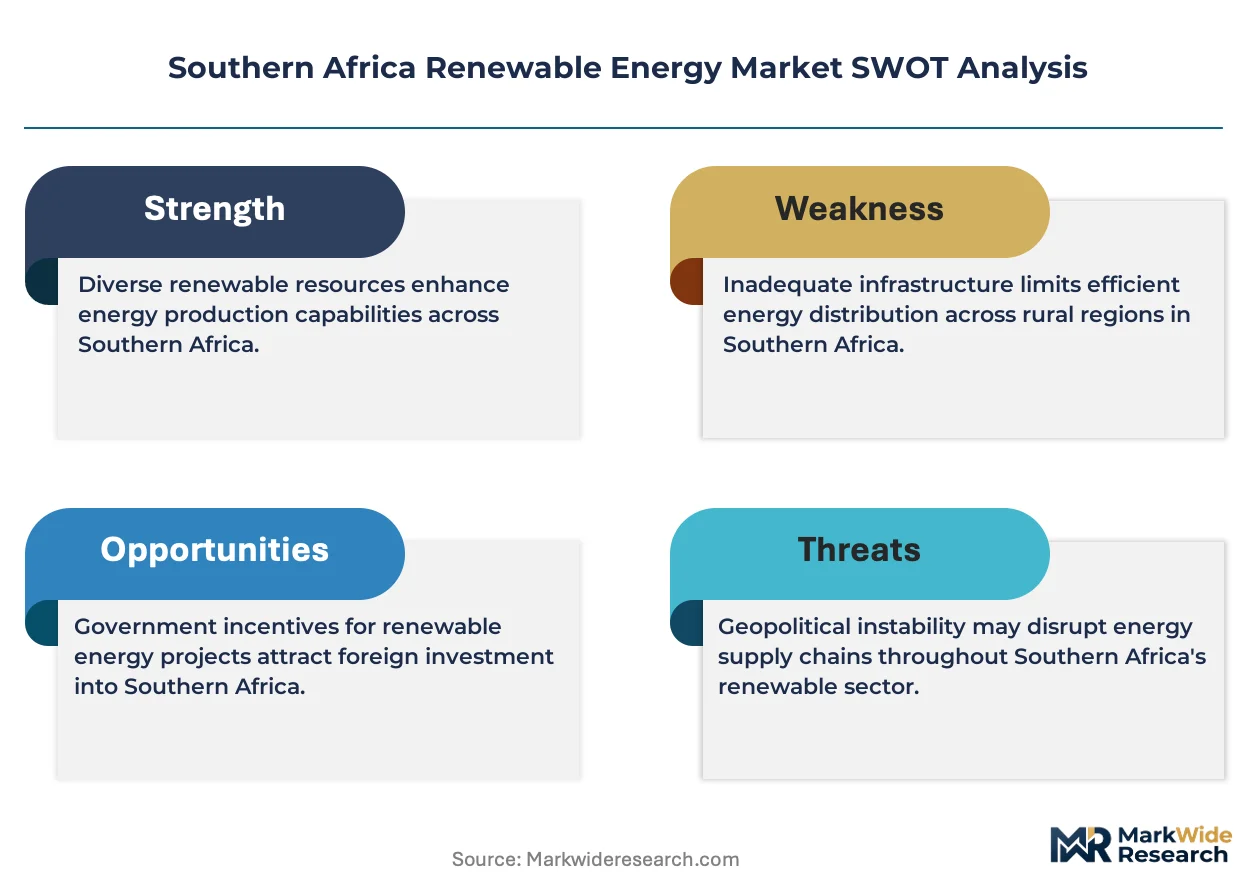
A capital-intensity divergence between integrated developers and specialized EPC contractors is reorganizing competitive dynamics across Southern Africa. Mainstream Renewable Power leverages its balance-sheet scale to anchor utility-scale wind and solar pipelines in South Africa and Mozambique. Scatec ASA sustains a development-to-own model that controls project returns across multiple jurisdictions. Juwi AG specializes in engineering execution, competing on construction velocity rather than long-term asset ownership.
Southern Africa renewable energy encompasses solar photovoltaic, onshore wind, biomass combustion, run-of-river hydropower, and hybrid storage systems engineered to convert natural resources into grid-stable electricity for industrial, commercial, and residential consumption. Solar dominates capacity additions due to irradiation levels exceeding kilowatt-hour thresholds across the Kalahari and Karoo basins, while off-grid and microgrid system types address rural electrification gaps in Zimbabwe and Malawi where transmission infrastructure remains sparse. Hydropower retains baseload significance through legacy assets on the Zambezi River, though seasonal rainfall variability constrains expansion.
South Africa's National Energy Regulator and the Renewable Energy Independent Power Producer Procurement Programme shape market access through auction design and grid connection standards, while Zimbabwe's Zimbabwe Energy Regulatory Authority and Zambia's Energy Regulation Board administer licensing frameworks that determine developer timelines. Regional power pool arrangements under the Southern African Power Coordinating Committee influence cross-border wheeling protocols. Stakeholders must monitor grid investment commitments and regulatory harmonization across member states before committing capital to multi-country portfolios.
Market Dynamics
South Africa's Renewable Energy Independent Power Producer Procurement Programme is compressing project development timelines from feasibility to financial close, while auction price floors collapse and grid connection queues extend to 36 months.
Growth Catalysts
- Industrial offtake agreements:Mining houses in Zambia and South Africa are executing 15-25 year power purchase agreements that bypass utility intermediaries. Anglo American and First Quantum Minerals anchor demand for 500MW-plus installations.
- Grid modernization mandates:South Africa's National Energy Regulator has accelerated embedded generation licensing thresholds to 100MW, unlocking commercial and industrial self-supply.
- Kalahari irradiation economics:Solar photovoltaic capacity factors exceeding 30% in Northern Cape province are decomposing levelized cost structures below combined-cycle gas alternatives.
Market Restraints
- Transmission infrastructure deficits:Eskom's grid investment backlog exceeds 14,000km of high-voltage line requirements, stranding generation assets in Eastern Cape wind corridors.
- Foreign exchange procurement exposure:Equipment imports denominated in USD and EUR create margin volatility for rand-based developers when the South African currency depreciates.
- Seasonal hydropower variability:Zambezi River flow fluctuations constrain baseload reliability from Kariba Dam, forcing thermal backup procurement.
Strategic Opportunities
- Zimbabwe rural electrification gap:Off-grid solar-diesel hybrid systems address 60% of unelectrified households outside Harare and Bulawayo transmission reach.
- Battery storage convergence:Lithium-ion and vanadium redox flow technologies are pairing with solar assets to capture evening peak pricing in South Africa's time-of-use tariff structure.
- Regional wheeling protocols:Southern African Power Pool arrangements enable Mozambique gas-to-power exports to South African mining load centers.
Industry Challenges
- Grid code compliance timelines:Connection studies and fault-ride-through certification for inverter-based resources extend project schedules 8-14 months beyond construction completion.
- Specialized EPC labor scarcity:High-voltage substation commissioning engineers and utility-scale solar construction managers command 40% wage premiums across the region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southern Africa Renewable Energy Market |
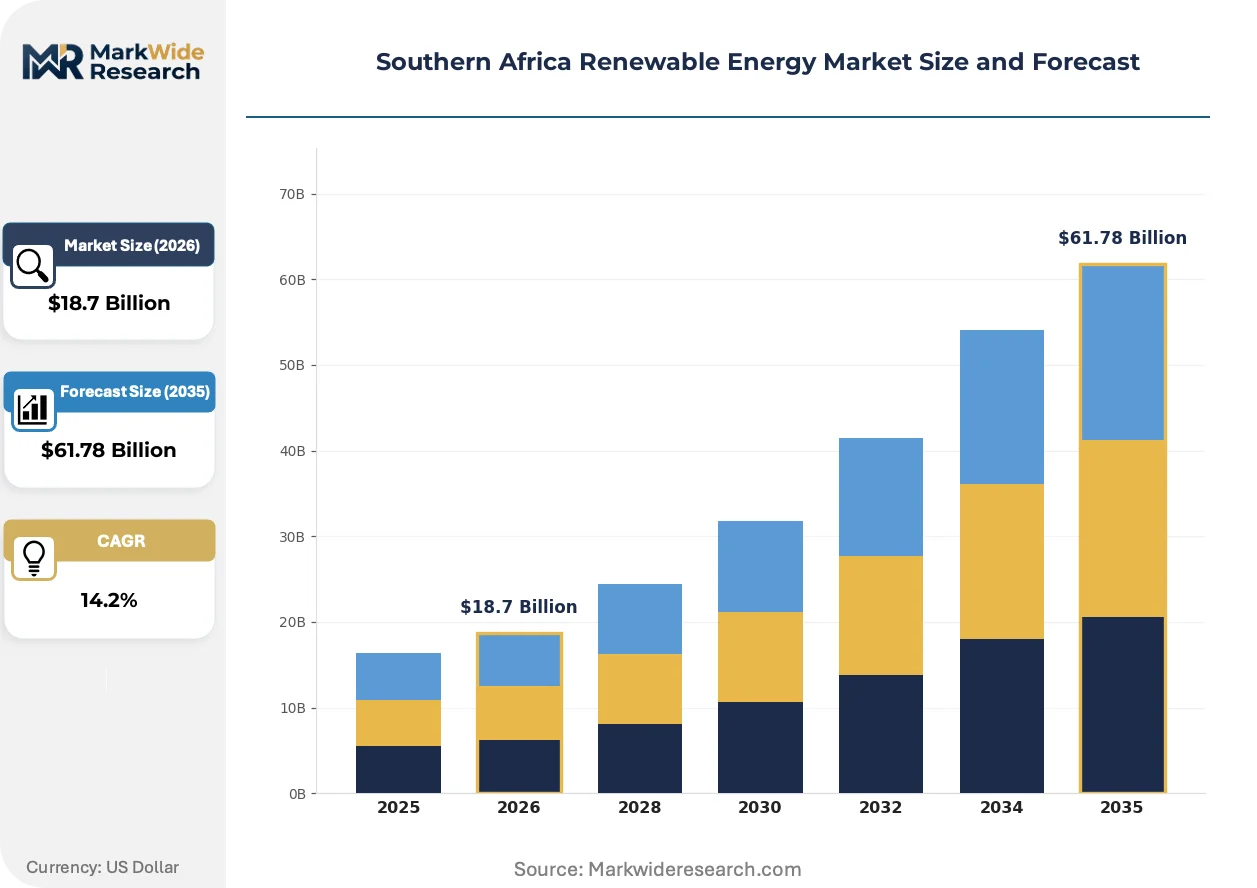
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydropower End User: Commercial, Residential, Industrial, Government Service Type: Installation, Maintenance, Consulting, Financing System Type: Off-Grid, Grid-Connected, Hybrid, Microgrid |
| Companies Covered | Mainstream Renewable Power, Scatec ASA, EDF Renewables, Enel Green Power South Africa, BTE Renewables, ACWA Power, Sola Group, Juwi AG, Anthem, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southern Africa Renewable Energy Market Evolving Landscape
Technology cost curves and procurement model experimentation are restructuring how renewable electrons reach industrial offtakers across the region.
Bifacial photovoltaic modules with tracking systems are decomposing single-axis fixed-tilt economics in South Africa's Northern Cape. Mining operators now specify these configurations in 200MW-plus tenders. The technology is compressing land-use intensity and balance-of-system costs per megawatt-hour delivered.
South Africa's National Energy Regulator has eliminated licensing requirements for generation projects below 100MW, triggering a surge in commercial and industrial embedded generation applications. Industrial parks in Gauteng and Western Cape provinces are aggregating multiple behind-the-meter installations. This regulatory relaxation is fragmenting procurement away from centralized utility auctions.
Corporate power purchase agreements now dominate mining sector procurement, displacing traditional utility tariff negotiations. Anglo American, Sibanye-Stillwater, and Vedanta are executing direct contracts with independent power producers. This buyer behavior shift concentrates in South Africa's platinum and manganese belts where grid reliability failures have imposed production losses.
Southern Africa Renewable Energy Market Segmentation
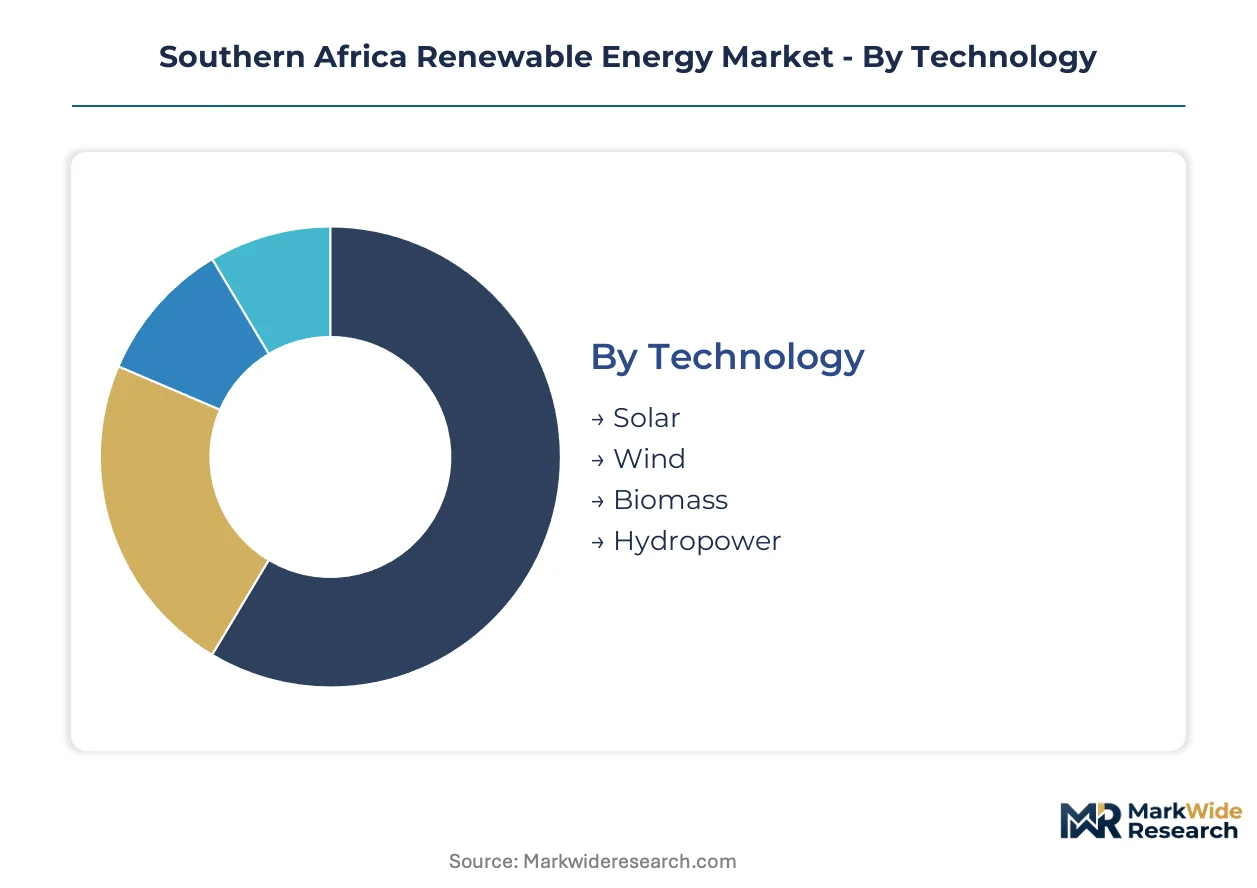
Technology choices across Southern Africa track irradiation maps and grid proximity, with procurement patterns diverging between export-oriented mining load centers and domestic consumption clusters. End-user segmentation reveals how industrial offtakers bypass utilities while rural electrification gaps sustain off-grid system demand.
Technology:
Solar and wind deployments concentrate in South Africa's Northern Cape and Eastern Cape provinces, while hydropower and biomass serve localized baseload needs in Zimbabwe and Zambia.
- Solar:Photovoltaic installations leverage Kalahari irradiation levels exceeding 2,200 kWh/m² annually. Mining houses in South Africa's platinum belt and Zambia's Copperbelt execute direct power purchase agreements for 100MW-plus ground-mount arrays, bypassing Eskom and ZESCO intermediaries.
- Wind:Onshore turbines cluster in Eastern Cape corridor zones with consistent wind shear profiles. Grid connection queues extending 36 months strand completed projects, forcing developers into corporate offtake structures that finance dedicated transmission spur lines.
- Biomass:Agricultural residue combustion plants serve sugar mill cogeneration needs in Eswatini and Mozambique's Maputo province.
- Hydropower:Run-of-river schemes on Zambezi tributaries face seasonal flow constraints that limit capacity factors below 45%.
Solar holds the largest share; momentum sits with wind as Eastern Cape grid upgrades advance.
End User:
Industrial procurement dominates capital deployment, while commercial and residential segments respond to regulatory licensing thresholds.
- Industrial:Mining operators Anglo American and First Quantum Minerals anchor 500MW-plus installations through 15-25 year power purchase agreements. Load certainty and dollar-denominated revenue streams attract international project finance.
- Commercial:Embedded generation licensing thresholds at 100MW unlock self-supply for Gauteng industrial parks and Western Cape manufacturing facilities. Aggregation models pool multiple behind-the-meter installations.
- Residential:Rooftop solar penetration concentrates in South African urban centers with net metering availability.
- Government:Public procurement through South Africa's Renewable Energy Independent Power Producer Procurement Programme compresses development timelines from feasibility to financial close.
Industrial offtakers command the largest procurement volumes; commercial embedded generation is expanding most quickly.
Service Type:
Installation margins compress as EPC competition intensifies, while financing and maintenance services capture recurring revenue streams.
- Installation:Engineering-procurement-construction contracts for utility-scale solar and wind face 40% wage premiums for high-voltage substation commissioning engineers. Scatec ASA and Mainstream Renewable Power anchor pipelines through balance-sheet scale.
- Maintenance:Long-term service agreements cover inverter replacement cycles and tracker system calibration. Mining operators prioritize uptime guarantees over lowest-bid procurement.
- Consulting:Grid code compliance studies and connection queue management extend project schedules 8-14 months.
- Financing:Development capital structures blend rand-denominated debt with dollar-linked equipment leases to manage currency exposure.
Installation commands the largest revenue pool; financing services are gaining share fastest as procurement models shift toward merchant and corporate structures.
System Type:
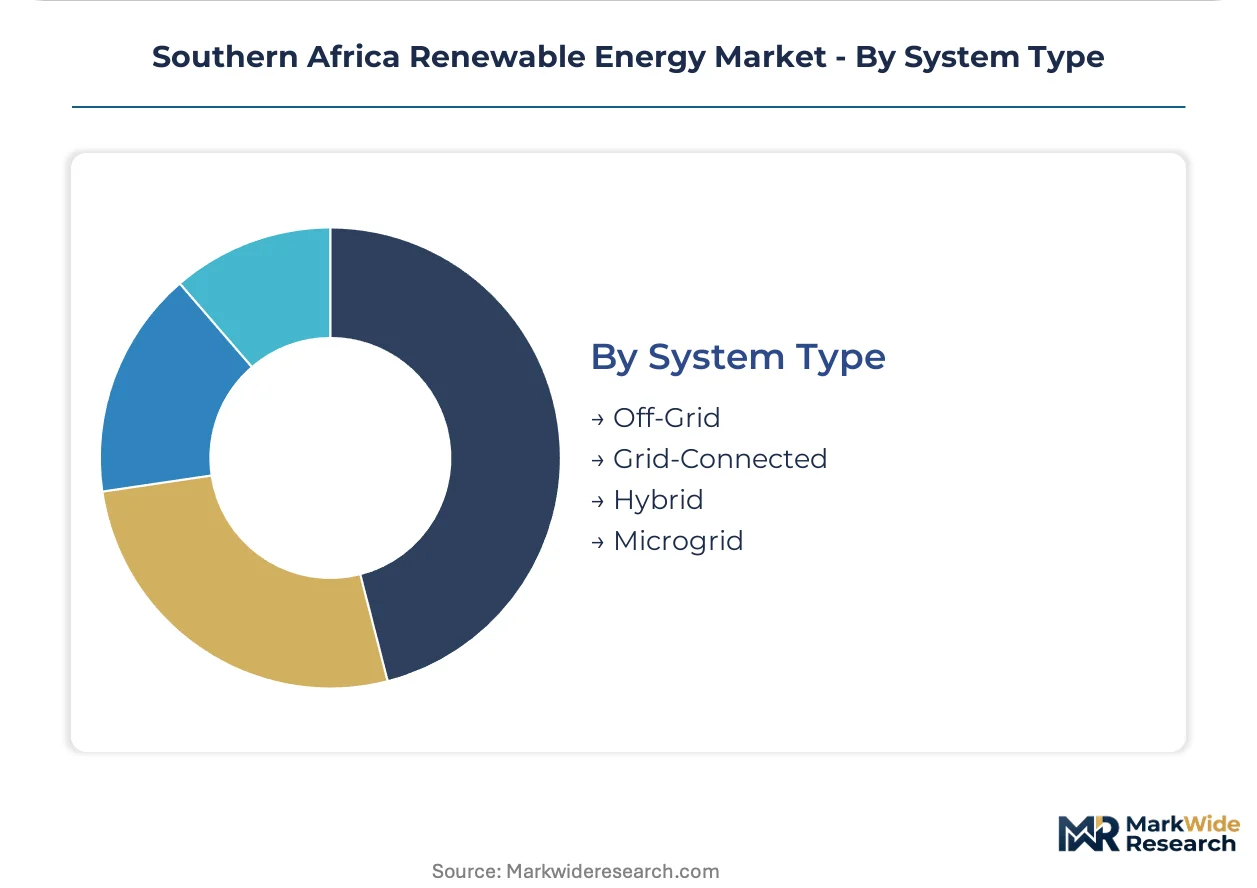
Grid-connected projects face transmission constraints, while off-grid and hybrid configurations address infrastructure gaps.
- Grid-Connected:Utility-scale solar and wind feed into Eskom's national network under power purchase agreements. Northern Cape and Eastern Cape concentration strains high-voltage line capacity.
- Off-Grid:Solar-diesel hybrid systems serve Zimbabwean mining camps and Malawian agricultural processing facilities beyond transmission reach. Diesel price volatility drives lithium-ion storage pairing.
- Hybrid:Solar-plus-battery configurations capture evening peak pricing in South Africa's time-of-use tariff structure. Vanadium redox flow technology competes with lithium-ion for 4-8 hour discharge durations.
- Microgrid:Village-scale systems in Zimbabwe's rural provinces outside Harare and Bulawayo address 60% of unelectrified households.
Grid-connected systems retain the largest installed base; off-grid deployment shows the steepest expansion trajectory as rural electrification gaps persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa commands pricing power through auction-scale procurement volumes, while Zimbabwe and Malawi absorb cost premiums on off-grid diesel-solar hybrids. This asymmetry concentrates project finance flows in Pretoria's regulatory orbit while peripheral markets depend on development capital subsidies.
South Africa
Mining houses in the platinum and manganese belts anchor 500MW-plus installations through direct power purchase agreements. The National Energy Regulator's 100MW embedded generation licensing threshold unlocks commercial self-supply for Gauteng industrial parks. Northern Cape province hosts bifacial solar arrays leveraging Kalahari irradiation exceeding 2,200 kWh/m² annually.
Zambia
Copperbelt mining operations execute 15-25 year dollar-denominated contracts that bypass ZESCO utility intermediaries. The Energy Regulation Board administers licensing frameworks determining developer timeline certainty. Run-of-river hydropower on Zambezi tributaries faces seasonal flow constraints limiting capacity factors below 45%.
Zimbabwe
Sixty percent of unelectrified households outside Harare and Bulawayo transmission reach sustain demand for solar-diesel hybrid systems. The Zimbabwe Energy Regulatory Authority governs rural electrification concession awards. Agricultural processing facilities in Manicaland province deploy off-grid microgrids beyond national grid extension timelines.
Mozambique
Gas-to-power export capacity feeds South African mining load centers through Southern African Power Pool wheeling protocols. Maputo province biomass combustion plants serve sugar mill cogeneration requirements. Northern corridor transmission investments remain contingent on regional development finance commitments.
Malawi
Rural electrification gaps sustain village-scale solar microgrid deployment across central and northern provinces. Agricultural processing cooperatives anchor demand for 50-200kW hybrid systems beyond ESCOM grid reach. Lake Malawi shoreline wind resource assessments remain pre-feasibility stage due to transmission infrastructure deficits.
Southern Africa Renewable Energy Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Southern Africa renewable energy market. Integrated developers with balance-sheet scale anchor utility-scale pipelines through development-to-own models that capture full project returns. Specialized EPC contractors compete on construction velocity and engineering execution rather than long-term asset ownership. The competitive terrain rewards two dominant moves: strategic partnerships that secure mining sector offtake agreements, and backward integration into high-voltage substation commissioning capabilities.
Within the integrated developer tier, Mainstream Renewable Power and Scatec ASA exemplify archetypes controlling multi-jurisdictional pipelines through capital deployment scale. Among specialized engineering contractors, Juwi AG occupies a position competing on EPC execution timelines rather than asset ownership duration. EDF Renewables and Enel Green Power South Africa represent European utility-backed entrants leveraging parent balance sheets to absorb currency exposure on rand-denominated procurement.
| Leading Market Players |
|---|
| Mainstream Renewable Power |
| Scatec ASA |
| EDF Renewables |
| Enel Green Power South Africa |
| BTE Renewables |
| ACWA Power |
| Sola Group |
| Juwi AG |
| Anthem |
| Others |
Value Network & Pricing Analysis
Long-term power purchase agreements with mining houses lock in both equipment procurement visibility and tariff certainty for independent power producers across South Africa's platinum belt and Zambia's Copperbelt. These bilateral contracts spanning 15-25 years anchor developer cash flows while insulating offtakers from Eskom and ZESCO tariff volatility.
Pricing Analysis
Corporate power purchase agreement premiums over utility tariffs reflect customization depth and offtaker credit quality. Anglo American and First Quantum Minerals accept 10-15% pricing premiums for dedicated transmission infrastructure and uptime guarantees, while smaller commercial embedded generators compete on standard tariff avoidance. Cost compression in utility-scale solar EPC contracts is intensifying because Chinese module imports and local construction labor arbitrage erode developer margins. Mining operators demonstrate lowest price sensitivity due to production loss exposure from grid failures, whereas agricultural processors in Malawi and Zimbabwe exhibit highest sensitivity to diesel-solar hybrid system capex.
Supply Chain Analysis
Equipment lead times for bifacial photovoltaic modules and lithium-ion battery containers have extended from 8 months to 14 months as Chinese and South Korean manufacturers prioritize European and North American order books. Module supply concentrates in China, inverter manufacturing in Germany and China, and battery cell production in South Korea and China. Foreign exchange exposure on USD-denominated equipment purchases creates margin volatility for rand-based developers when the South African currency depreciates. Distribution runs through Durban and Richards Bay port corridors with final-mile logistics to Northern Cape and Eastern Cape project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Southern Africa renewable energy market is recovering from a cyclical trough driven by Eskom's grid investment backlog compression and the Renewable Energy Independent Power Producer Procurement Programme auction restart. Procurement volume normalization through mining sector direct contracting provides the cyclical justification.
For Market Incumbents: Shield installed capacity positions by securing exclusive EPC partnerships with high-voltage substation commissioning specialists commanding 40% wage premiums. Backward integration into grid code compliance capabilities defends against schedule overruns that extend project timelines 8-14 months beyond construction completion. Capacity addition in Zimbabwe's rural electrification gap leverages existing Southern African Power Pool relationships.
For New Entrants and Emerging Players: Lead with vanadium redox flow battery technology to capture evening peak pricing in South Africa's time-of-use tariff structure, where lithium-ion supply constraints create procurement windows. Zimbabwe's solar-diesel hybrid microgrid segment outside Harare and Bulawayo transmission reach offers the most penetrable geography with 60% of households unelectrified. Direct sales to agricultural processing cooperatives bypass centralized utility procurement complexity.
For Investors and Strategic Acquirers: Specialized EPC contractors with captive high-voltage commissioning labor pools represent the highest-conviction acquisition archetype given scarcity-driven wage inflation. Long-term viability hinges on regulatory harmonization progress across Southern African Power Pool member states over the coming decade. Monitor Eskom's transmission investment commitment announcements as the primary inflection indicator for Eastern Cape wind project financial close velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Execution | Anglo American's 500MW-plus contracts validate mining sector procurement bypassing utility intermediaries. |
| Backward Integration into Storage | Vanadium redox flow technology captures evening peak pricing under South Africa's time-of-use tariffs. |
| Grid Code Compliance Investment | In-house fault-ride-through certification reduces project schedule extensions by 8-14 months. |
| Regional Wheeling Protocol Utilization | Southern African Power Pool arrangements enable Mozambique gas-to-power exports to South African mining load centers. |
| Embedded Generation Licensing Expansion | South Africa's 100MW threshold unlocks commercial self-supply aggregation for Gauteng industrial parks. |
Research Methodology
Cross-validation between developer interviews and regulatory filing analysis anchors the qualitative findings on auction design evolution and grid connection queue dynamics. Primary discussions with independent power producer project developers, EPC contractor engineering directors, Eskom grid planning officers, and mining house energy procurement leads combined with secondary validation through FERC-style regulatory databases, IEA country reports, and Southern African Power Pool transmission planning documents. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling provide triangulation.
Sensitivity analysis on currency depreciation scenarios and commodity price volatility frames the quantitative outputs across the analysis window. The analytical framework models segmentation dimensions including technology type, end-user category, system configuration, and regulatory framework cluster. CAGRs derive from installed capacity build-up assumptions and levelized cost trajectory modeling. Key forecast inputs include Kalahari irradiation measurements and Zambezi River hydrological flow patterns.
The analysis sits within stated boundaries; outcomes outside sustained mining sector capital expenditure commitment or accelerated transmission infrastructure deployment would require recalibration. Forecasts reflect documented assumptions on auction price floor trajectories and equipment import tariff stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Autoclave Market
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
North Africa Renewable Energy Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Wind Turbine Foundation Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
Composite Materials in Renewable Energy Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
Solar Farm Market
Renewable Energy
Renewable Energy in South America Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
India Renewable Energy Market