
 Mini Excavators Market | 2026-2036
Mini Excavators Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Excavators Market Outlook
Equipment leasing and project-based financing is rewriting competitive dynamics in the mini excavator sector. Caterpillar leverages its captive finance arm to anchor fleet deployments for mid-tier contractors. Komatsu competes through vertical integration into hydraulics and powertrain manufacturing. Yanmar specializes in sub-40 HP diesel engines that dominate Japanese and European rental pools.
Mini excavators are compact tracked or wheeled earthmoving machines with operating weights below 6 metric tons, boom swing arcs under 90 degrees, and hydraulic systems rated for bucket breakout forces between 15 and 45 kN; they perform trenching, grading, and material handling in confined spaces inaccessible to standard excavators. Crawler type units lead volume due to flotation advantages on undeveloped sites, while wheeled type configurations are gaining share in European urban utilities work where road speed reduces trailer dependency. The 20-40 HP engine power band captures the largest margin pool because it balances fuel efficiency with hydraulic performance for rental fleet standardization.
EPA Tier 4 Final in the United States, EU Stage V in Europe, and China's MEE emission enforcement are tightening particulate and NOx limits, compelling manufacturers to develop electric and hybrid powertrains or risk market exclusion. Japan's METI energy efficiency benchmarks and ISO 6393 noise standards further constrain conventional diesel architectures. Stakeholders must monitor battery energy density trajectories and charging infrastructure buildouts to time platform transitions before regulatory deadlines eliminate internal combustion options in key municipalities.
Market Dynamics
The mini excavator sector is pivoting on emission compliance deadlines that are forcing simultaneous platform electrification and diesel engine refinement across all major manufacturing bases.
Growth Catalysts
- Urban densification:Japanese and German municipalities are mandating compact equipment for utility corridors under 2.5 meters width, accelerating crawler unit deployment in metropolitan trenching contracts.
- EPA Tier 4 Final retrofit cycles:US rental fleets face 2027 equipment turnover deadlines that are pulling forward replacement demand into current procurement windows.
- Lithium iron phosphate battery packs:Energy density improvements above 160 Wh/kg are enabling 4-hour continuous operation in sub-3-ton electric models for indoor demolition and tunnel maintenance.
Market Restraints
- Steel and hydraulic component volatility:Boom cylinder and track roller input costs fluctuate with scrap metal and alloy pricing, compressing margin predictability for mid-tier assemblers.
- High-voltage battery supply concentration:Cell manufacturing for 48V and 400V architectures clusters in East Asian supply bases, exposing European and North American OEMs to logistics bottlenecks and tariff exposure.
- Range and charging infrastructure gaps:Electric mini excavators lack standardized fast-charging protocols at undeveloped construction sites, limiting adoption to grid-connected urban projects.
Strategic Opportunities
- Indian urban infrastructure buildout:Smart Cities Mission funding is creating demand for sub-2-ton units in congested metro utility networks where full-size equipment cannot maneuver.
- Telematics-integrated rental platforms:IoT-enabled fleet management systems allow hour-by-hour utilization tracking, unlocking usage-based billing models for contractor cash flow optimization.
- EU Green Deal construction equipment incentives:Member state subsidies for zero-emission machinery are narrowing total cost of ownership gaps between electric and diesel platforms in French and Dutch municipal procurement.
Industry Challenges
- High-voltage technician certification:Electric platform maintenance requires specialized training that rental fleet service departments lack at scale, delaying field repair turnaround times.
- Dual powertrain inventory complexity:OEMs must maintain parallel diesel and electric component stocks, straining working capital and forecasting accuracy during regulatory transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Excavators Market |
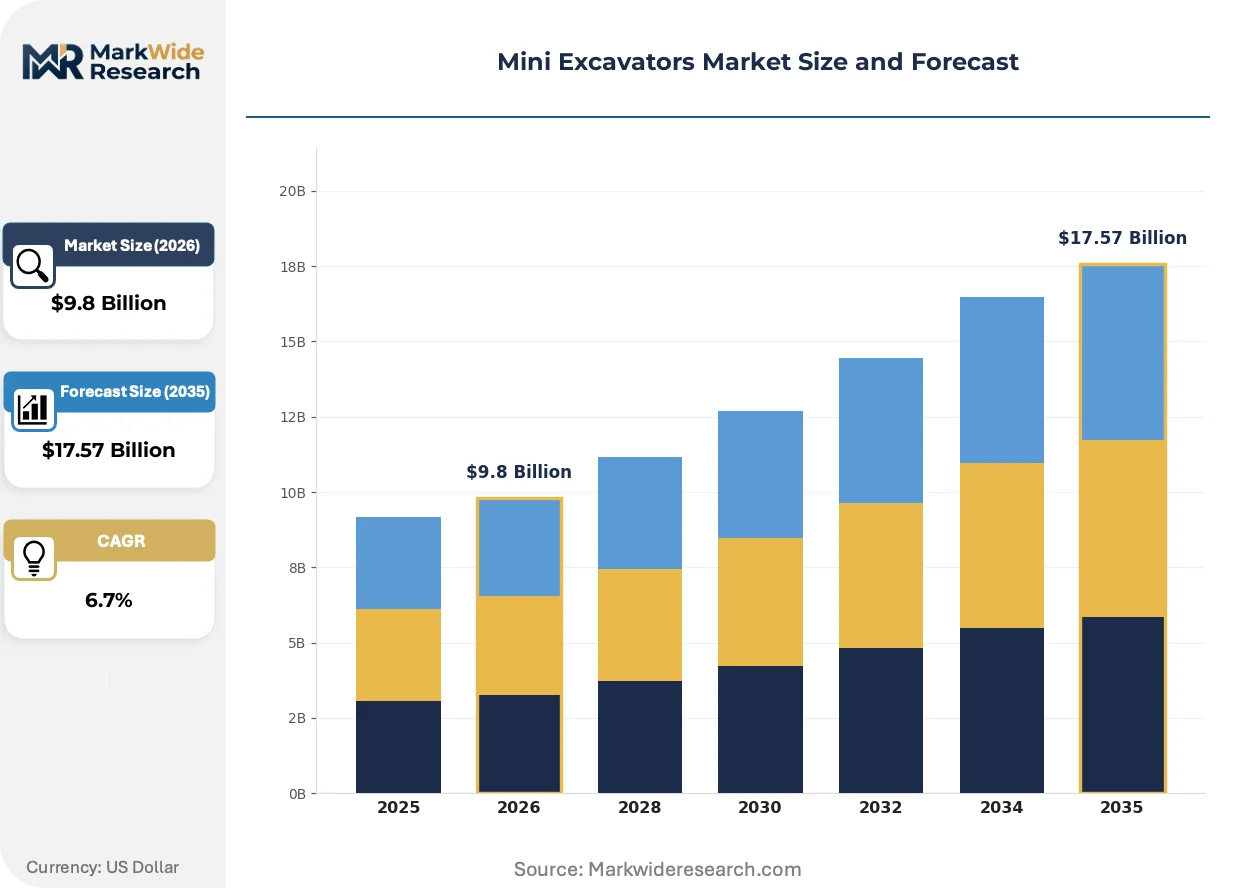
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crawler Type, Wheeled Type, Hybrid Type, Mini Loader Engine Power: Below 20 HP, 20-40 HP, 40-60 HP, Above 60 HP Application: Construction, Landscaping, Agriculture, Demolition End User: Construction Companies, Rental Services, Government, Private Contractors |
| Companies Covered | Deere & Company, Yanmar, Caterpillar, Volvo Construction Equipment, Takeuchi, Komatsu, Bobcat, XCMG, Kubota, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Excavators Market Strategic Shifts
Electrification architectures and connected fleet systems are compressing product lifecycles and rewriting equipment ownership economics across contractor segments.
Permanent magnet synchronous motors paired with onboard battery thermal management are rendering obsolete the hydraulic pump-and-engine marriage that has defined mini excavator design since the 1980s. European rental consortiums in the Netherlands and Denmark are specifying electric-only fleet additions for 2025-2028 procurement tranches. This powertrain shift is collapsing the traditional 7-10 year model refresh cycle as battery chemistry improvements outpace mechanical durability benchmarks.
EU Stage V particulate matter limits and Japan's METI energy efficiency benchmarks are tightening simultaneously, forcing engine suppliers to deploy dual-stage aftertreatment systems that add weight and cost to sub-40 HP diesel architectures. The industrial consequence is a narrowing window where conventional combustion platforms remain economically viable against electric alternatives. German and Japanese OEMs are responding by accelerating in-house battery pack integration to preserve margin control as engine sourcing becomes commoditized.
Equipment-as-a-service contracting is displacing outright purchase in mid-tier contractor segments, particularly in French and UK markets where project financing constraints favor operating expense treatment. Rental platforms are unbundling maintenance and insurance from base hourly rates, creating transparent cost structures that favor newer, lower-failure-rate electric units. This procurement evolution is most visible in urban utilities verticals where municipality-mandated emission zones already exclude diesel equipment from central business district work.
Mini Excavators Market Segmentation
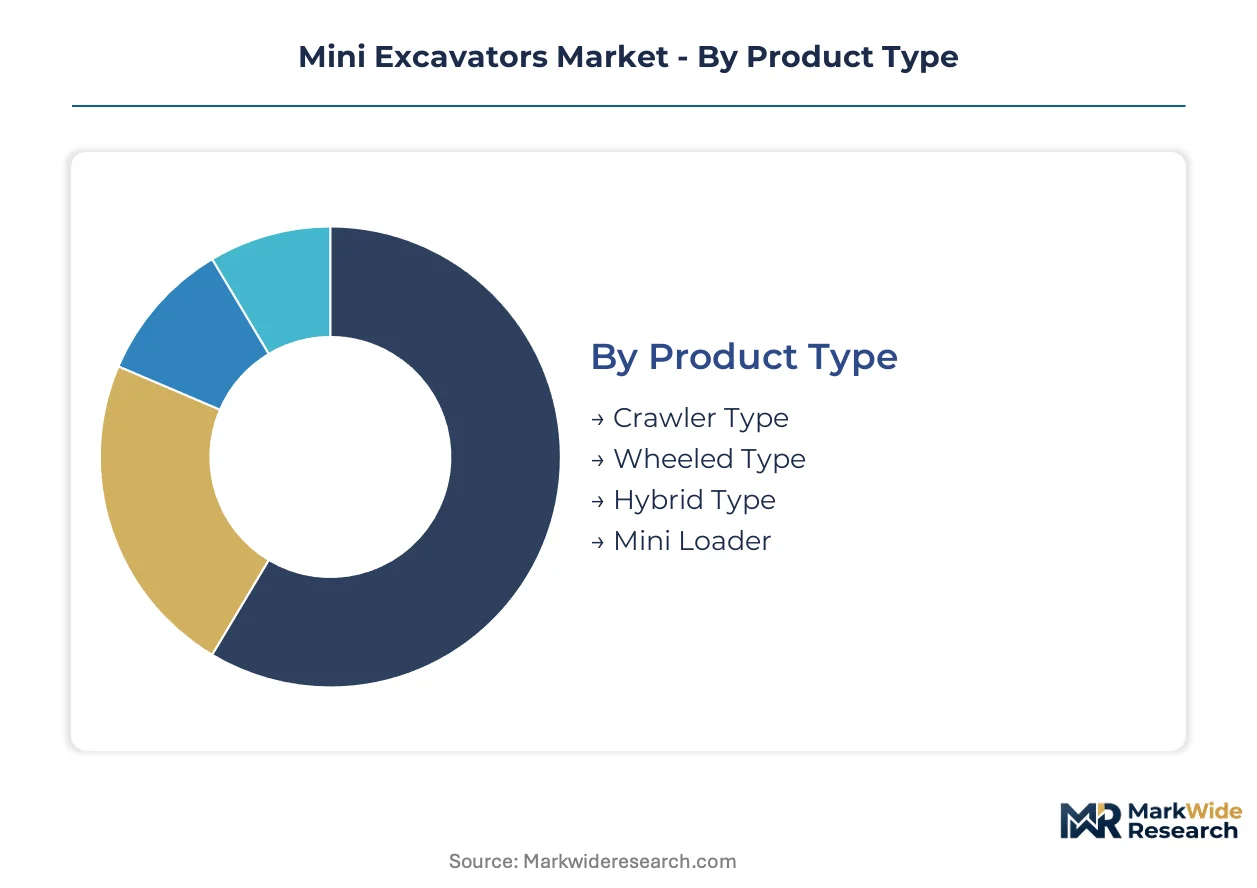
Mini excavator segmentation reveals distinct performance envelopes across mobility platforms, power bands, and user economics. Each dimension carries regulatory and operational implications that shape procurement patterns across municipal, commercial, and agricultural verticals.
Product Type:
Mature configurations dominate rental fleet standardization while emerging hybrid architectures respond to emission zone restrictions.
- Crawler Type:Tracked undercarriage systems distribute ground pressure below 35 kPa for undeveloped terrain access. Japanese and German metropolitan trenching contracts specify crawler units for utility corridors under 2.5 meters width where flotation prevents surface damage.
- Wheeled Type:Rubber-tired configurations achieve 25-35 km/h road speeds that eliminate trailer transport for European urban utilities work. Dutch and French municipal fleets are standardizing on wheeled platforms to reduce mobilization costs between dispersed job sites.
- Hybrid Type:Diesel-electric architectures combine combustion range with electric zero-emission zones.
- Mini Loader:Articulated bucket configurations extend material handling versatility for landscaping contractors.
Crawler type handles the majority of throughput; hybrid type is the fastest mover on share.
Engine Power:
Cost tier stratification separates rental fleet workhorses from specialized high-output applications.
- 20-40 HP:Four-cylinder diesel or permanent magnet electric motors deliver hydraulic flow rates of 50-80 L/min for standard bucket breakout. This band captures the largest margin pool by balancing fuel efficiency with performance for rental fleet standardization across US and European markets.
- Below 20 HP:Single-cylinder or battery-electric units under 1.5 tons serve indoor demolition and tunnel maintenance where ventilation constraints prohibit combustion.
- 40-60 HP:Turbocharged diesels or high-voltage electric systems power 4-6 ton units for heavy trenching in rocky substrate.
- Above 60 HP:High-displacement or dual-motor electric configurations approach standard excavator performance in compact footprints.
The 20-40 HP segment anchors rental procurement volumes; below 20 HP is expanding most quickly on emission zone enforcement.
Application:
Volume concentration follows infrastructure spending cycles while margin profiles diverge by project duration and equipment utilization intensity.
- Construction:Residential foundation excavation, utility trenching, and site preparation consume the highest machine hours per unit. Chinese urban densification and Indian Smart Cities Mission funding are concentrating demand for sub-3-ton units in congested metro corridors.
- Demolition:Selective deconstruction and interior gutting operations require zero-emission electric platforms for enclosed spaces. Battery thermal management and onboard charging are critical specifications for continuous shift operations.
- Landscaping:Tree planting, grading, and hardscape installation favor sub-2-ton wheeled configurations for residential property access.
- Agriculture:Orchard maintenance, drainage ditching, and livestock facility construction use compact excavators for seasonal task flexibility.
Construction absorbs the dominant equipment hours; demolition is climbing the fastest on indoor emission regulations.
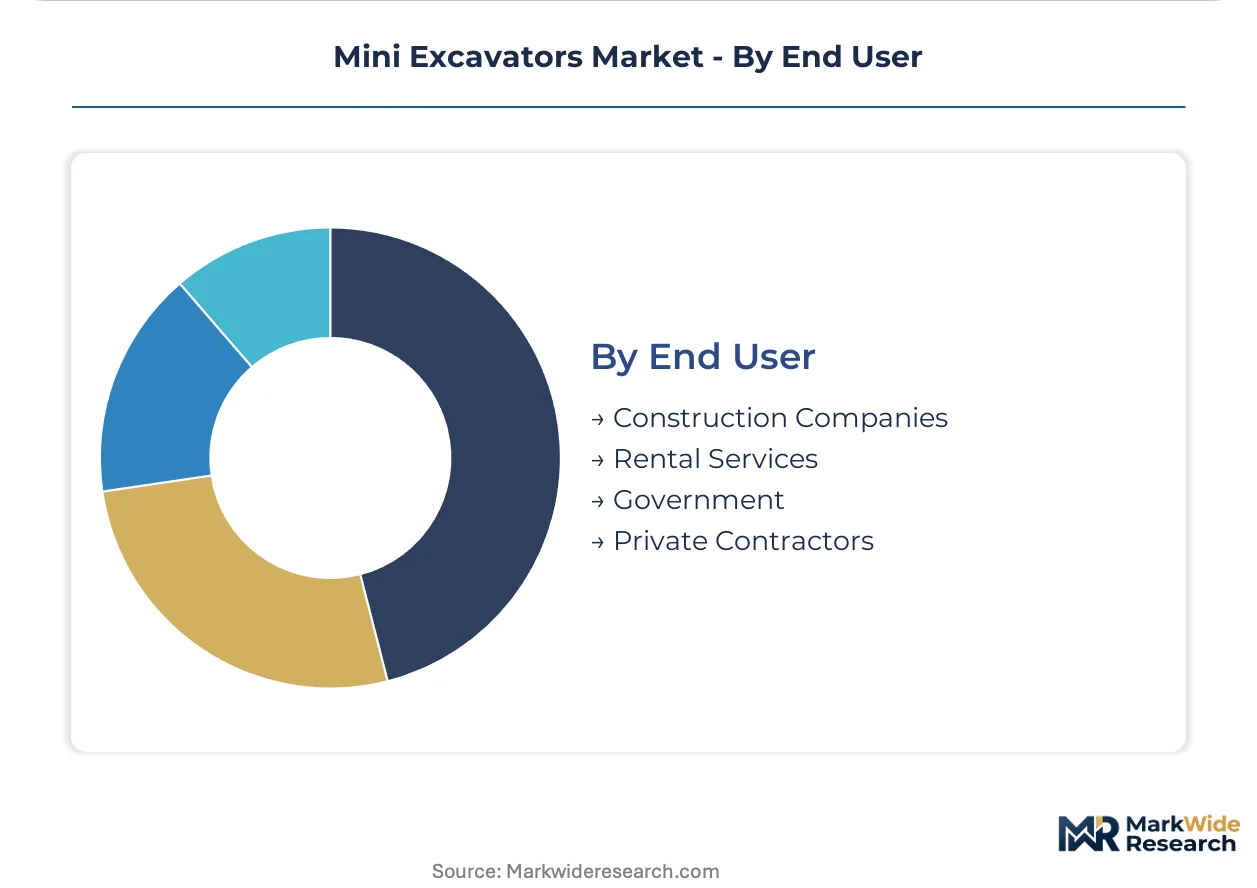
End User:
Customer type determines ownership model, financing structure, and service support requirements across the equipment lifecycle.
- Rental Services:Fleet operators prioritize standardization on 20-40 HP crawler units for cross-customer utilization. Telematics-integrated hour tracking enables usage-based billing models that optimize contractor cash flow in French and UK markets.
- Construction Companies:Mid-tier contractors balance owned fleet core with rental surge capacity for project peak demands.
- Government:Municipal procurement mandates EU Stage V or electric platforms for central business district work in Netherlands and Denmark.
- Private Contractors:Independent operators favor sub-2-ton units for residential landscaping and light utility work with trailer-towable mobility.
Rental services command the largest procurement volumes; government buyers are gaining share fastest on zero-emission procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers extract pricing premiums from EU Stage V compliance integration while Chinese producers compete on volume through domestic MEE enforcement scale. This asymmetry shapes procurement patterns across municipal fleets and rental consortia.
United States
Rental fleet operators dominate equipment procurement volumes. EPA Tier 4 Final retrofit deadlines compress replacement cycles through 2027. Texas and Florida infrastructure corridors concentrate crawler unit deployment for utility trenching.
Germany
Municipal emission zones in Berlin and Hamburg mandate electric platforms for central business district work. EU Stage V particulate limits force dual-stage aftertreatment integration. Bavarian manufacturing clusters anchor hydraulic component supply for European OEMs.
China
Urban densification in Shanghai and Shenzhen drives sub-3-ton unit demand for metro utility networks. MEE enforcement tightens NOx limits on compact diesel engines. Xuzhou and Changzhou industrial bases concentrate final assembly capacity for domestic and export markets.
Japan
METI energy efficiency benchmarks constrain conventional diesel architectures in Tokyo and Osaka metropolitan zones. Compact equipment dominates tight-access construction corridors under 2.5 meters width. Nagoya and Osaka manufacturing hubs specialize in sub-40 HP engine production for rental pools.
India
Smart Cities Mission funding channels equipment procurement into congested metro utility networks. BIS certification requirements shape import compliance for foreign OEMs. Maharashtra and Karnataka urban infrastructure projects concentrate demand for sub-2-ton wheeled configurations.
Mini Excavators Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on hydraulics and powertrain modules. Market structure consolidates around five to seven full-line manufacturers with captive distribution networks. Strategic archetypes separate engine-house integrators from hydraulic subsystem specialists and rental fleet service providers. Competitive moves concentrate on battery pack integration partnerships and telematics platform licensing.
Among Japanese and European manufacturers, Yanmar, Komatsu, and Volvo Construction Equipment occupy distinct positions across the powertrain spectrum. Yanmar anchors the sub-40 HP diesel engine tier through captive supply relationships. Komatsu exemplifies full-system integration from hydraulics through fleet telematics. Volvo Construction Equipment represents the emission-compliant platform transition through electric architecture development.
| Leading Market Players |
|---|
| Deere & Company |
| Yanmar |
| Caterpillar |
| Volvo Construction Equipment |
| Takeuchi |
| Komatsu |
| Bobcat |
| XCMG |
| Kubota |
| Others |
Value Chain & Pricing Dynamics
Tariff exposure between Chinese battery cell manufacturers and European OEMs compresses margin predictability across electric platform tiers while simultaneously forcing dual-source procurement strategies that reshape inventory economics for rental fleet operators.
Pricing Analysis
Rental fleet operators anchor three-tier pricing structure across premium, standard, and economy levels based on engine power band and telematics integration depth. Price differentiation hinges on EPA Tier 4 Final or EU Stage V certification status plus aftermarket service bundling for hydraulic component coverage. Cost compression in the sub-20 HP electric tier is intensifying because lithium iron phosphate cell sourcing concentrates in East Asian supply bases. Small private contractors exhibit highest price sensitivity, while municipal government buyers prioritize emission compliance over acquisition cost.
Supply Chain Analysis
Logistics bottlenecks between Chinese cell manufacturing hubs and European final assembly plants dominate supply chain risk profiles for electric mini excavator platforms. Component sourcing draws from Japan for sub-40 HP diesel engines, Germany for hydraulic valve systems, and China for battery pack integration. Steel and alloy pricing volatility for boom cylinders and track rollers feeds margin uncertainty for mid-tier assemblers. Distribution runs through captive dealer networks for full-line OEMs and independent rental consortia for fleet procurement standardization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-enabled usage-based billing models expand recurring revenue per unit faster than hardware margins, transforming fleet operators into service platforms with attached maintenance and insurance unbundling.
For Market Incumbents: Entrench defensible positions through backward integration into battery pack assembly and captive finance arms for contractor project-based procurement. Komatsu's full-system integration from hydraulics through fleet telematics demonstrates the lever. Counter emerging electric-only entrants by accelerating EU Stage V compliance integration ahead of regulatory deadlines that exclude non-compliant equipment from municipal contracts.
For New Entrants and Emerging Players: Indian Smart Cities Mission utility corridors represent the most penetrable entry point for sub-2-ton wheeled configurations where congestion excludes established full-size equipment. Dutch and French municipal emission zones offer secondary white-space for electric-only fleet procurement mandates. Pursue telematics-integrated rental platform partnerships as the go-to-market angle rather than direct OEM distribution investment.
For Investors and Strategic Acquirers: EU Green Deal construction equipment incentives reshape the acquisition landscape by narrowing total cost of ownership gaps and accelerating electric platform viability windows. Target component specialists with high-voltage battery integration capabilities and established rental fleet service relationships. Watch battery energy density trajectories above 160 Wh/kg as the signal indicating platform transition timing before municipal combustion bans take effect.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Pack Integration Partnership | Preservation of margin control as engine sourcing commoditizes under EPA Tier 4 Final and EU Stage V pressure. |
| Telematics Platform Licensing | Enables hour-by-hour utilization tracking for usage-based billing models in French and UK rental markets. |
| Captive Finance Arm Expansion | Anchors fleet deployments for mid-tier contractors facing project financing constraints and cash flow optimization needs. |
| Dual Powertrain Inventory Rationalization | Reduces working capital strain during regulatory transition periods when diesel and electric stocks must parallel. |
| High-Voltage Technician Certification Program | Addresses service department capability gaps that delay electric platform field repair turnaround times. |
Study Parameters
Initial hypotheses were tested against primary input from rental fleet operations directors, municipal procurement officers, OEM platform engineers, and aftermarket service heads, then refined through secondary validation against SEC 10-K filings, customs and trade data for hydraulic component flows, EPA and EU Stage V regulatory filings, and equipment registration databases. Bottom-up unit economics from individual machine-hour utilization rates were triangulated against top-down infrastructure spending projections across municipal verticals.
Demand-supply balance modeling across the projection horizon incorporated segmentation by mobility platform, engine power band, application vertical, and end-user archetype. CAGRs were derived from regression analysis against urban densification indices, emission regulation enforcement timelines, and battery chemistry improvement curves. Industry-specific forecast inputs included lithium iron phosphate energy density trajectories and charging infrastructure buildout rates for grid-connected construction sites.
Macroeconomic conditions sit as an overlay; deviation in steel and alloy commodity pricing, East Asian logistics capacity, or municipal infrastructure appropriation cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and battery cost decline curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Construction Equipment Market
Construction Equipment
Hydraulic Intensifiers Market
Construction Equipment
India Construction Equipment Rental Market
Construction Equipment
Extrusion Machinery Market
Construction Equipment
Truck Crane Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Middle East Flexible Concrete Vibrator Market
Construction Equipment
Europe Excavator and Loaders Market
Construction Equipment
Commercial Sanitizing Equipment Market
Construction Equipment
Industrial Agitators Market
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
Backhoe Bucket Market
Construction Equipment
Trash Rack Cleaning Machine Market