
 China Construction Equipment Market | 2026-2036
China Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
China Construction Equipment Market Analysis
Modular equipment bundling is pivoting how Chinese contractors configure fleet purchases, shifting from single-machine transactions to integrated packages combining excavators, loaders, and telematics subscriptions. Sany Group leverages its vertical manufacturing footprint to anchor bundled offerings across tier-one cities. Xuzhou Construction Machinery Group sustains dominance in hydraulic component supply, while Zoomlion Heavy Industry Science and Technology Co., Ltd. differentiates through crane specialization and intelligent control systems.
China construction equipment encompasses powered machinery engineered for earthmoving, material handling, and vertical lifting on civil engineering and resource extraction sites, typically rated by operating weight, bucket capacity, or lift load moment and manufactured through welded high-strength steel chassis assembly, powertrain integration, and hydraulic system calibration. Excavators occupy the largest volume position due to versatility across urban demolition and foundation work, while electric technology within the technology segment is expanding fastest as municipal projects impose emission restrictions on diesel units. The deployment model dimension shows rental penetration deepening among mid-sized contractors seeking to avoid capital commitment on cyclical projects.
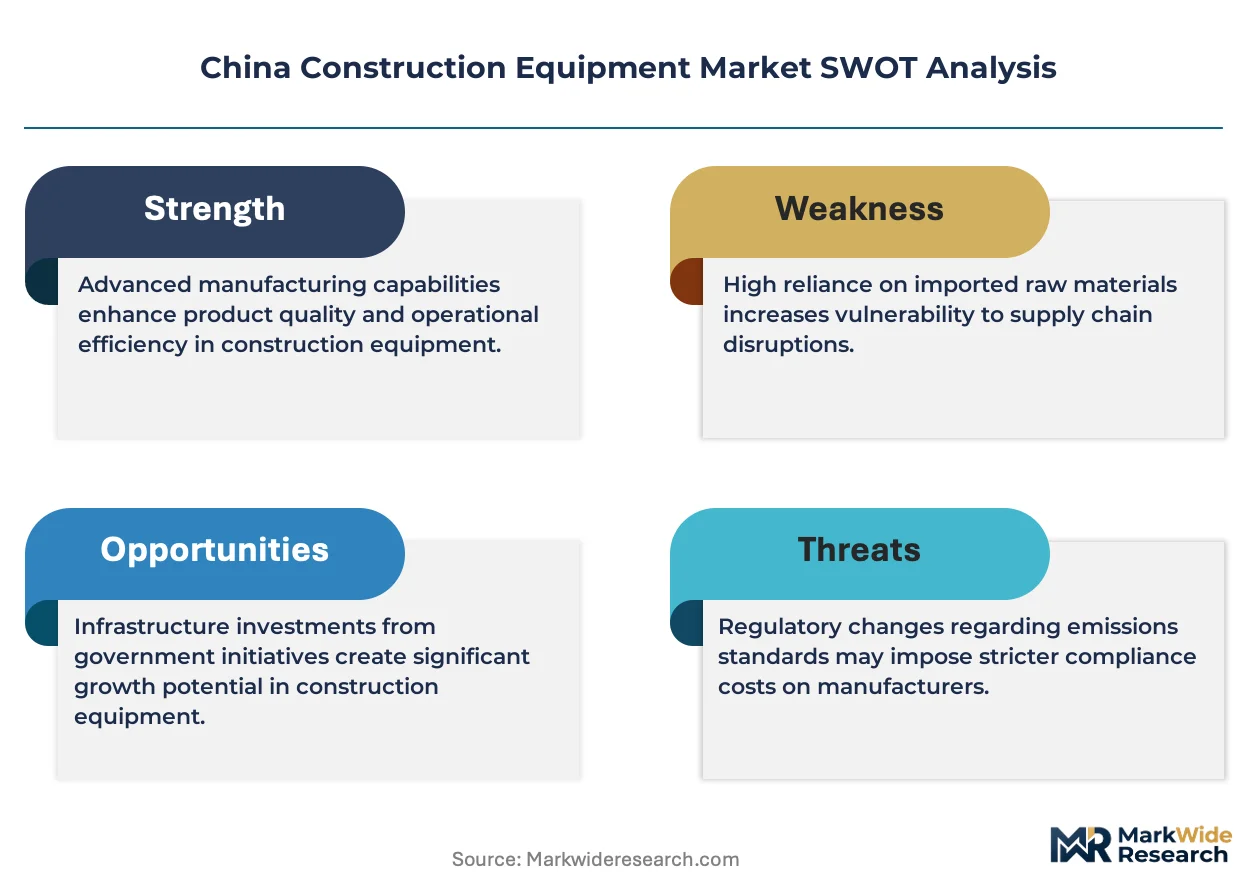
China's Ministry of Ecology and Environment enforces emission tier standards that compel domestic manufacturers to redesign engine architectures, while MIIT certification requirements for telematics integration reshape product development roadmaps. GB standards for construction machinery safety and SAMR market access protocols collectively elevate compliance costs for imported equipment. Stakeholders must monitor how provincial subsidy programs for new energy equipment intersect with tightening carbon intensity targets in the Pearl River Delta and Beijing-Tianjin-Hebei corridor.
Market Dynamics
China's dual carbon goals are compressing the diesel-to-electric transition timeline across construction equipment fleets, forcing manufacturers to redesign powertrain architectures while municipal buyers rewrite procurement specifications to favor zero-emission units.
Growth Catalysts
- MIIT Telematics Mandates:Certification requirements for connected machinery are pulling embedded IoT modules into standard equipment configurations, expanding recurring software revenue streams for domestic manufacturers.
- Yangtze River Economic Belt Infrastructure:State-directed investment in rail corridors and port modernization is sustaining fleet renewal cycles among tier-one contractors concentrated in Jiangsu and Hubei provinces.
- High-Strength Steel Advancements:Domestic metallurgy improvements are reducing chassis weight while maintaining load ratings, enabling larger operating envelopes for compact excavator categories.
Market Restraints
- Lithium Supply Concentration:Battery-grade lithium processing capacity clusters in Qinghai and Sichuan, exposing electric equipment manufacturers to input bottlenecks when extraction quotas tighten.
- GB Emission Tier Compliance Costs:Engine redesign requirements under Ministry of Ecology and Environment protocols are elevating R&D burdens for domestic diesel powertrain suppliers without equivalent scale advantages.
- Used Equipment Arbitrage:Depreciated diesel excavators from coastal provinces are migrating inland, undercutting new equipment pricing in secondary markets and extending replacement cycles.
Strategic Opportunities
- Pearl River Delta Electrification Subsidies:Guangdong provincial programs for new energy construction machinery are creating first-mover advantages for manufacturers with certified electric loader portfolios.
- Rental Channel Expansion:Asset-light procurement models are penetrating mid-sized contractor segments in Sichuan and Shandong, opening fleet management service revenue pools.
- Hydrogen Fuel Cell Convergence:Integration of fuel cell stacks with electric drivetrains is emerging as a range-extension pathway for heavy crane applications in port logistics corridors.
Industry Challenges
- Power Electronics Talent Scarcity:Electric drivetrain engineering expertise concentrates in automotive and consumer electronics sectors, forcing equipment manufacturers to compete for inverter and motor control specialists.
- Telematics Platform Integration:SAMR data localization requirements are complicating cloud architecture choices for multinational suppliers seeking to unify fleet management systems across China operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Construction Equipment Market |
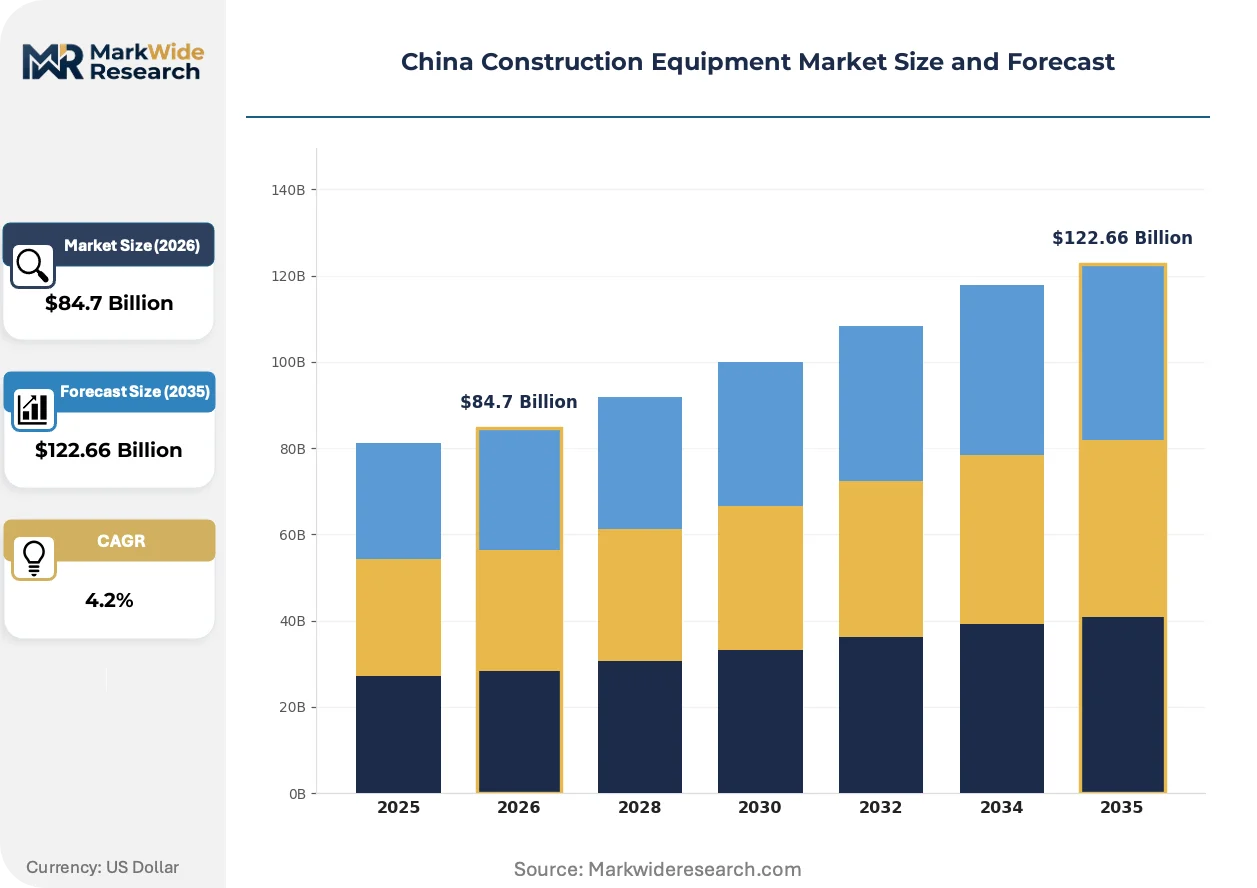
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $122.66 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Loaders, Cranes, Bulldozers End User: Contractors, Construction Firms, Government Bodies, Mining Companies Deployment Model: Rental, Purchase, Financing, Leasing Technology: Telematics, Autonomous Machine Control, Electric, Diesel |
| Companies Covered | LiuGong Machinery Co., Ltd., Caterpillar Inc., Sany Group, Hitachi Construction Machinery, Komatsu Ltd., Xuzhou Construction Machinery Group Co., Ltd., Shantui Construction Machinery Co., Ltd., Shandong Lingong Construction Machinery, Zoomlion Heavy Industry Science and Technology Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Construction Equipment Market Emerging Trajectories
Electrification architectures are rewriting equipment design priorities while digitalization mandates reshape how manufacturers monetize machinery beyond the initial sale.
Battery-electric powertrains are consolidating around standardized pack geometries that accommodate both excavator and loader form factors without chassis redesign. Municipal contractors in Beijing-Tianjin-Hebei corridor are specifying these platforms for urban demolition contracts facing diesel restrictions. The technology is consolidating supplier tiers by rewarding manufacturers with captive battery assembly capacity over those dependent on third-party module sourcing.
GB standards for construction machinery safety are mandating redundant sensor arrays and automated emergency braking for equipment above specified operating weights. Domestic manufacturers are redesigning hydraulic control systems to accommodate these electronic interventions, elevating bill-of-materials complexity. Tower crane categories face the steepest compliance timelines given their deployment density in dense urban construction zones.
Equipment-as-a-service contracting is displacing traditional ownership models among state-owned construction enterprises seeking to offload residual value risk. Leasing platforms in Chongqing and Chengdu are bundling maintenance and telemalytics subscriptions into hourly rate structures. This shift concentrates procurement authority with fleet management specialists rather than project-level equipment managers, altering sales engagement protocols for manufacturers.
China Construction Equipment Market Segmentation
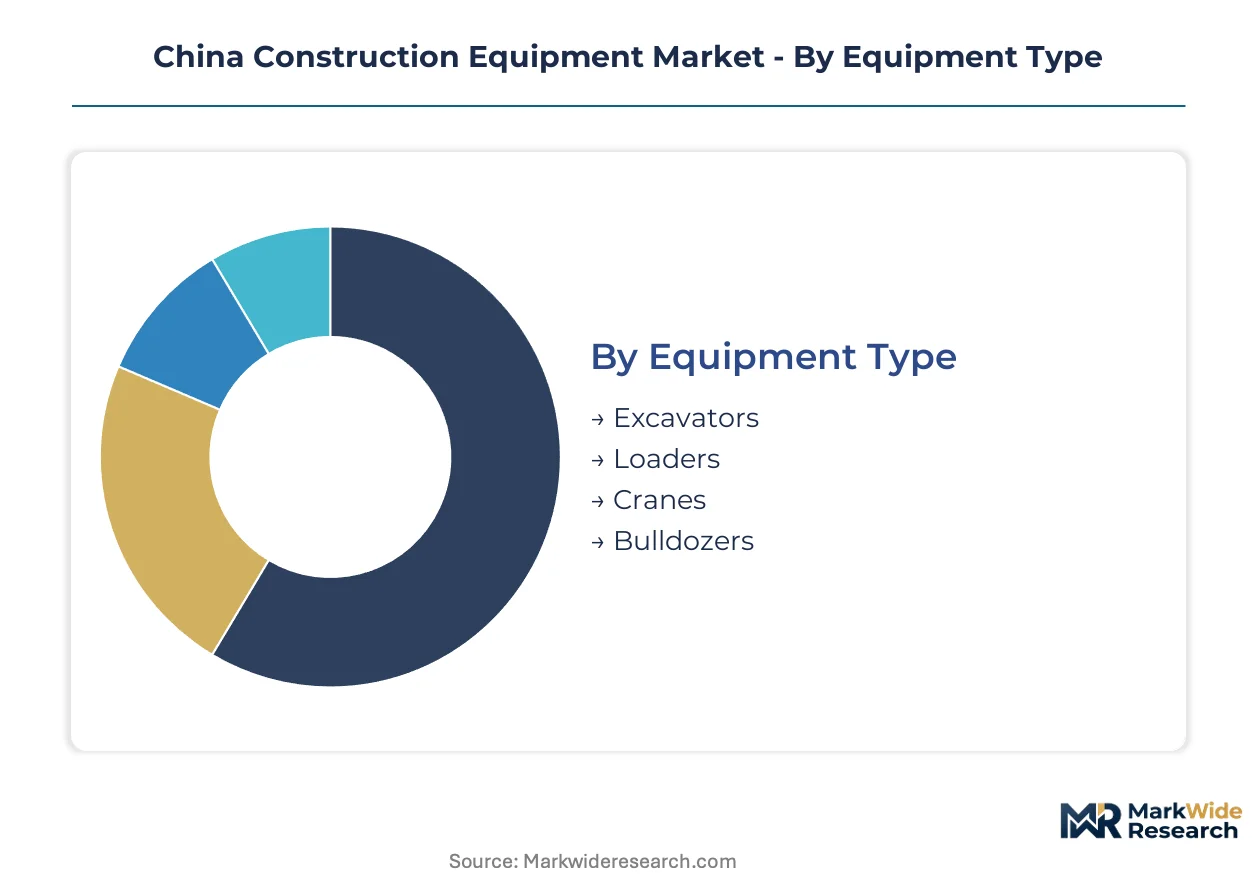
Equipment classification in China construction machinery reflects divergent powertrain architectures, procurement risk appetites, and project-scale requirements. Segment boundaries are blurring as electric platforms and subscription-based deployment reshape traditional category definitions.
Equipment Type:
Hydraulic system specifications and chassis load ratings define the technical axis for this foundational category.
- Excavators:Tracked and wheeled variants rated by operating weight and bucket breakout force dominate urban demolition and foundation excavation. Municipal contractors in Jiangsu province specify compact electric models for rail corridor projects facing MEE emission restrictions.
- Loaders:Articulated chassis designs with hydrostatic transmissions handle bulk material movement across port logistics and aggregate processing. Guangdong infrastructure agencies are accelerating wheel loader electrification through provincial subsidy programs targeting Pearl River Delta construction zones.
- Cranes:Mobile and tower configurations rated by lift load moment serve vertical construction in dense urban cores.
- Bulldozers:Crawler-mounted blade systems with torque converter powertrains grade earthworks and maintain haul roads in mining and highway applications.
Excavators lead on scale; electric loaders lead on momentum.
End User:
Procurement authority and project duration cycles segment demand by capital commitment capacity and fleet management sophistication.
- Contractors:Tier-one construction enterprises with state-backed project pipelines deploy mixed fleets across Yangtze River Economic Belt infrastructure corridors. These buyers favor bundled equipment packages integrating maintenance and telematics subscriptions.
- Construction Firms:Mid-sized private operators concentrate in Sichuan and Shandong provinces where rental penetration is deepening.
- Government Bodies:Provincial transport and housing authorities specify emission-compliant equipment for publicly funded rail, port, and municipal housing developments.
- Mining Companies:Resource extraction operators in inland provinces source heavy-duty excavators and bulldozers with extended warranty coverage for high-utilization environments.
Contractors dominate procurement volume; construction firms are expanding most quickly as rental channels mature.
Deployment Model:
Balance sheet treatment and residual value risk allocation distinguish how equipment enters productive use.
- Rental:Hourly-rate fleet access with bundled maintenance is penetrating mid-sized contractor segments in Chongqing and Chengdu. Asset-light procurement allows project-level equipment managers to match capacity with cyclical demand without capital commitment.
- Purchase:Direct ownership with full residual value exposure remains preferred by state-owned enterprises with predictable multi-year project pipelines.
- Financing:Equipment-backed credit structures with title retention clauses spread capital expenditure across depreciation-matched repayment schedules.
- Leasing:Operating lease structures with return conditions and usage-based rate adjustments concentrate procurement authority with fleet management specialists.
Purchase retains the largest installed base; rental claims the steepest expansion trajectory.
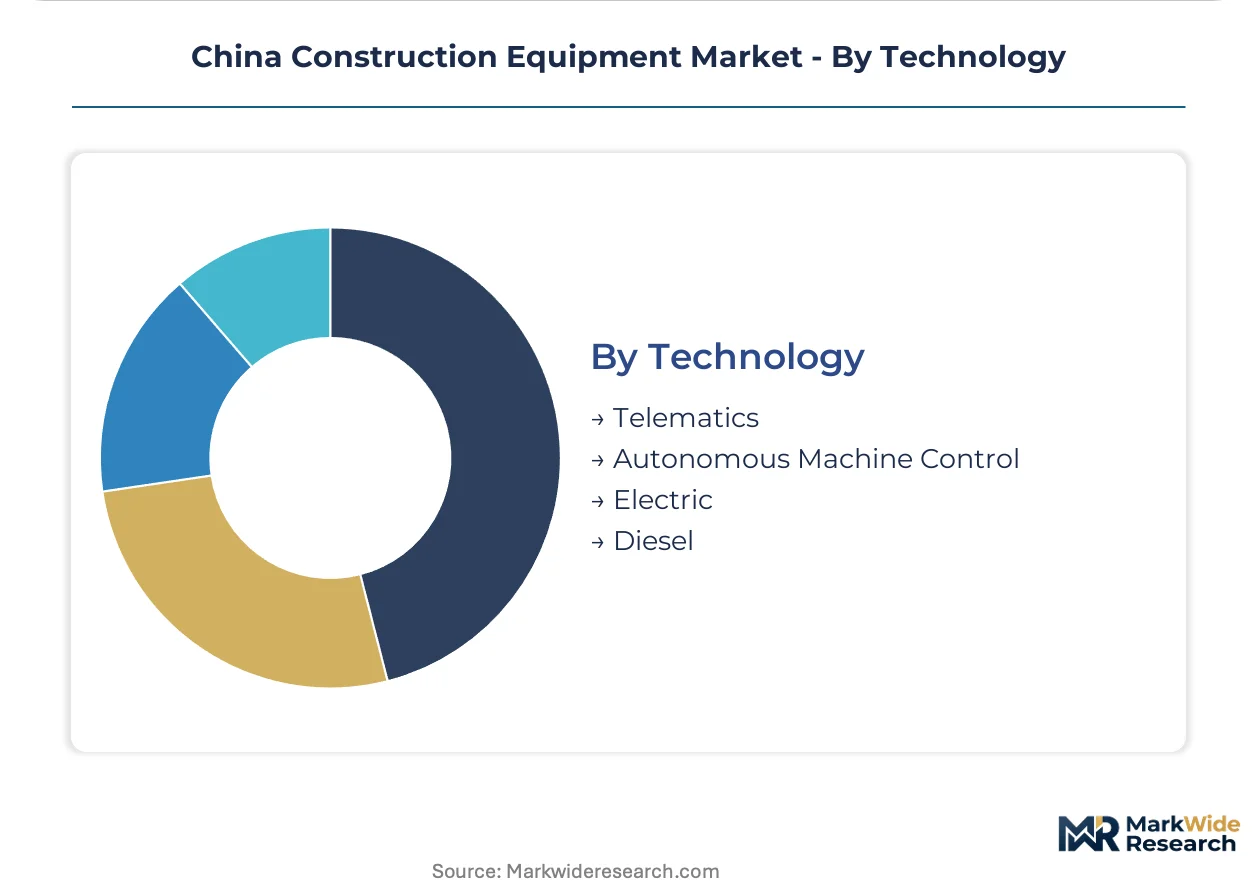
Technology:
Powertrain architecture and embedded intelligence systems differentiate equipment platforms facing divergent regulatory timelines.
- Electric:Battery-electric powertrains with standardized pack geometries accommodate excavator and loader form factors without chassis redesign. Beijing-Tianjin-Hebei corridor contractors specify these for urban demolition contracts under diesel restrictions.
- Telematics:MIIT-mandated connected machinery modules enable remote diagnostics, usage tracking, and predictive maintenance scheduling. Certification requirements are pulling embedded IoT into standard configurations.
- Autonomous Machine Control:Sensor fusion and GPS-guided blade control systems reduce operator skill requirements for grading and excavation precision.
- Diesel:Tier-compliant internal combustion powertrains face compressed replacement cycles as dual carbon goals accelerate fleet turnover.
Diesel maintains current fleet dominance; electric platforms are gaining share fastest as municipal procurement specifications rewrite.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's construction equipment industry traces its modern scaling to the 1950s establishment of state-owned heavy machinery complexes in Xuzhou and Luoyang, foundations that enabled subsequent export competitiveness through the 1990s and 2000s.
Yangtze River Delta
Jiangsu province drives excavator demand through rail corridor expansion and port modernization projects concentrated in Nanjing and Suzhou industrial zones. MIIT telematics mandates accelerate connected machinery procurement specifications for municipal contractors. Shanghai's Lingang equipment leasing clusters anchor rental channel penetration among mid-sized construction enterprises.
Pearl River Delta
Guangdong infrastructure agencies prioritize electric loader procurement through provincial new energy equipment subsidies targeting Shenzhen and Dongguan construction zones. Dual carbon goals compress diesel replacement timelines for urban demolition fleets. Foshan's equipment financing platforms deepen asset-light procurement among private contractors.
Beijing-Tianjin-Hebei Corridor
Municipal housing and transit projects in Hebei province specify emission-compliant machinery under MEE enforcement protocols tightening around Tianjin port logistics. XCMG manufacturing bases in Xuzhou supply standardized electric powertrain platforms for northern urban demolition contracts. Langfang's equipment distribution hubs coordinate fleet renewal cycles for state-owned construction enterprises.
Sichuan-Chongqing
Chongqing's mountainous terrain drives demand for compact excavator categories suited to foundation work in constrained urban sites. SAMR data localization requirements reshape telematics cloud architectures for multinational suppliers operating western China fleets. Chengdu's rental platform clusters expand hourly-rate procurement among mid-sized contractors seeking cyclical capacity matching.
Shandong Peninsula
Qingdao and Yantai port logistics corridors sustain wheel loader demand for bulk material handling and container yard operations. GB standards for construction machinery safety elevate sensor array requirements for equipment above specified operating weights. Weifang's hydraulic component manufacturing clusters supply domestic chassis assembly operations.
China Construction Equipment Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with connected machinery and electric powertrain capabilities commanding pricing separation from conventional diesel configurations. Domestic state-affiliated manufacturers consolidate around captive component production and provincial procurement relationships. Three archetypes dominate: vertically integrated steel-to-software conglomerates, hydraulic system specialists with backward component control, and multinational assemblers leveraging global platform architectures. Competitive moves concentrate on telematics platform standardization and battery pack geometry unification across excavator and loader form factors.
Among Chinese equipment manufacturers, Sany Group and Xuzhou Construction Machinery Group Co., Ltd. exemplify the integrated conglomerate archetype through upstream control over critical component supply chains. Zoomlion Heavy Industry Science and Technology Co., Ltd. occupies a specialization position within crane categories and intelligent control systems. These domestic anchors compete against multinational assemblers including Caterpillar Inc. and Komatsu Ltd., which represent global platform strategies adapted to MIIT certification requirements and SAMR data localization protocols. LiuGong Machinery Co., Ltd. and Shandong Lingong Construction Machinery sit within the mid-tier segment, while Hitachi Construction Machinery and Shantui Construction Machinery Co., Ltd. exemplify regional market penetration approaches through distinct technology licensing and distribution configurations.
| Leading Market Players |
|---|
| LiuGong Machinery Co., Ltd. |
| Caterpillar Inc. |
| Sany Group |
| Hitachi Construction Machinery |
| Komatsu Ltd. |
| Xuzhou Construction Machinery Group Co., Ltd. |
| Shantui Construction Machinery Co., Ltd. |
| Shandong Lingong Construction Machinery |
| Zoomlion Heavy Industry Science and Technology Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed manufacturers anchor supply discipline through state-directed procurement relationships, compressing margin flexibility for private competitors while MIIT telematics mandates embed fixed-cost IoT modules across all pricing tiers. This ownership structure concentrates pricing power with domestic conglomerates controlling captive steel foundries and hydraulic component production, forcing independent assemblers to absorb input volatility or cede share.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales bundling intensity. Premium tiers command separation through GB standard compliance depth and telematics subscription integration, while economy configurations compete on bare chassis pricing for inland contractors. Cost compression in diesel equipment is intensifying because used machinery arbitrage from coastal provinces floods secondary markets. State-owned enterprises show least price sensitivity due to budgetary cycle insulation, whereas mid-sized private contractors in Sichuan and Shandong exhibit acute elasticity driving rental channel expansion.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Xuzhou and Changsha manufacturing clusters to provincial equipment yards in Jiangsu and Guangdong. Supply concentrates in China for high-strength steel chassis fabrication and hydraulic system calibration, with battery-grade lithium processing anchored in Qinghai and Sichuan. Raw material dependencies span welded steel plate, rare-earth magnet motors, and lithium iron phosphate cells. Single-source vulnerability runs through domestic lithium extraction quotas controlled by provincial resource bureaus. Distribution runs through manufacturer-owned financing subsidiaries and third-party leasing platforms concentrated in Chongqing and Chengdu.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's construction equipment market functions as a regulatory compounder where MEE emission tier enforcement and dual carbon goals continuously refresh equipment replacement demand. MIIT telematics mandates represent the most durable demand driver, mandating connected machinery modules that expand addressable revenue per unit.
For Market Incumbents: Lock in component supply security through backward integration into battery pack assembly and permanent magnet motor production, insulating margin structures from lithium price swings. Deepen captive financing capacity to match state-owned contractor procurement cycles, defending against emerging rental platforms eroding ownership models. Prioritize GB standard certification depth as the priority lever for pricing separation.
For New Entrants and Emerging Players: Digital rental platform routes offer lowest friction entry into mid-sized contractor segments in Sichuan and Shandong provinces where asset-light procurement is displacing direct purchase. Target electric loader categories in Guangdong's Pearl River Delta, where provincial subsidies compress payback periods for municipal buyers. Pursue telematics-native equipment configurations as the primary go-to-market angle, avoiding legacy diesel platform R&D burdens.
For Investors and Strategic Acquirers: Valuations sit cheapest among hydraulic component specialists with backward integration into high-strength steel processing but limited electric powertrain exposure. Long-term viability framing centers on manufacturers with captive battery assembly capacity and MIIT certification pipelines extending through the projection horizon. Monitor lithium extraction quota announcements from Qinghai and Sichuan provincial authorities as the critical inflection signal for input cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Powertrain Platform Standardization | Unifies battery pack geometries across excavator and loader form factors, reducing SKU complexity for XCMG and Sany. |
| Telematics Module Certification | MIIT mandates pull embedded IoT into standard configurations, creating recurring software revenue streams for domestic manufacturers. |
| Provincial Financing Subsidiary Expansion | Captive credit structures concentrate procurement authority with fleet management specialists in Yangtze River Delta state enterprises. |
| Hydrogen Fuel Cell Range Extension | Integration with electric drivetrains addresses heavy crane applications in Tianjin port logistics corridors under MEE enforcement. |
| Rental Platform Technology Stack | Hourly-rate bundling in Chongqing and Chengdu displaces traditional ownership among cyclical project contractors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with equipment procurement directors at state-owned construction enterprises, fleet managers at Chongqing rental platforms, hydraulic component engineers at Xuzhou manufacturing bases, and aftermarket service heads at Guangdong distribution hubs. Secondary validation drew from MIIT certification databases, SAMR market access filings, GB standards documentation, and provincial infrastructure budget disclosures. Bottom-up unit economics modeling triangulated against top-down provincial spending aggregates.
Segment-weighting approaches distributed value and volume across equipment type, powertrain architecture, deployment model, and end-user procurement authority. Excavator, loader, and crane categories received distinct elasticity assumptions reflecting urban demolition versus bulk material handling utilization patterns. CAGRs derived from equipment replacement cycle analysis intersecting with dual carbon policy timelines, with electric platform adoption curves calibrated to municipal procurement specification shifts in Beijing-Tianjin-Hebei and Pearl River Delta corridors.
The model assumes a particular technology adoption path; alternative pathways for hydrogen fuel cell convergence in heavy crane applications would alter the outlook for battery-electric platform dominance. Forecasts reflect documented assumptions around lithium supply elasticity and provincial subsidy continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Concrete Pumps Market
Construction Equipment
Stamping Machines Market
Construction Equipment
Ground Engaging Tools (GET) Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Hydroforming Press Market
Construction Equipment
Compact Loaders Market
Construction Equipment
Fogging Machine Market
Construction Equipment
Hydraulic Cylinders Market
Construction Equipment
Compaction Equipment Market
Construction Equipment
Italy Construction Equipment Market
Construction Equipment
Europe Crane Market
Construction Equipment
Dust Suppression Fog Cannon Market
Construction Equipment
Press Fit Machines Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Hydraulic Press Machine Market