
 Asia-Pacific Hydraulic Equipment Market | 2026-2036
Asia-Pacific Hydraulic Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hydraulic Equipment Market Outlook
ISO 4406 cleanliness-grade specifications for hydraulic fluids is unwinding legacy equipment replacement cycles across the Asia-Pacific basin. Bosch Rexroth AG leverages its integrated drive and control portfolio to dominate high-precision manufacturing applications in Japan and South Korea. KYB Corporation anchors construction OEM supply chains through dedicated cylinder production facilities in Thailand and Indonesia. Daikin Industries Ltd. specializes in compact power unit designs for mobile equipment where space constraints dictate system architecture.
Hydraulic equipment encompasses pumps, cylinders, valves, and motors that transmit power through pressurized fluid, typically operating at pressures from 3,000 to 6,000 psi in industrial settings and enabling precise force control for heavy-load operations. Hydraulic pumps and cylinders constitute the largest product segments by installed base, though digital controls and electro-hydraulic technology are capturing disproportionate margin expansion as OEMs retrofit legacy fleets. End-user demand from construction and power generation channels exhibits the strongest structural momentum, driven by hydropower expansion in Laos and Vietnam plus metro rail tunneling projects across multiple ASEAN states.
Japan's METI enforces JIS B 8361 standards for hydraulic cylinder safety and performance testing, while China's SAMR administers GB/T compliance mandates for energy-efficient hydraulic systems under national dual carbon goals. India's BIS certification requirements for construction machinery hydraulics create non-tariff barriers that favor suppliers with local assembly presence. Stakeholders must monitor how ASEAN harmonization of machinery safety directives affects cross-border component sourcing and service network economics.
Market Dynamics
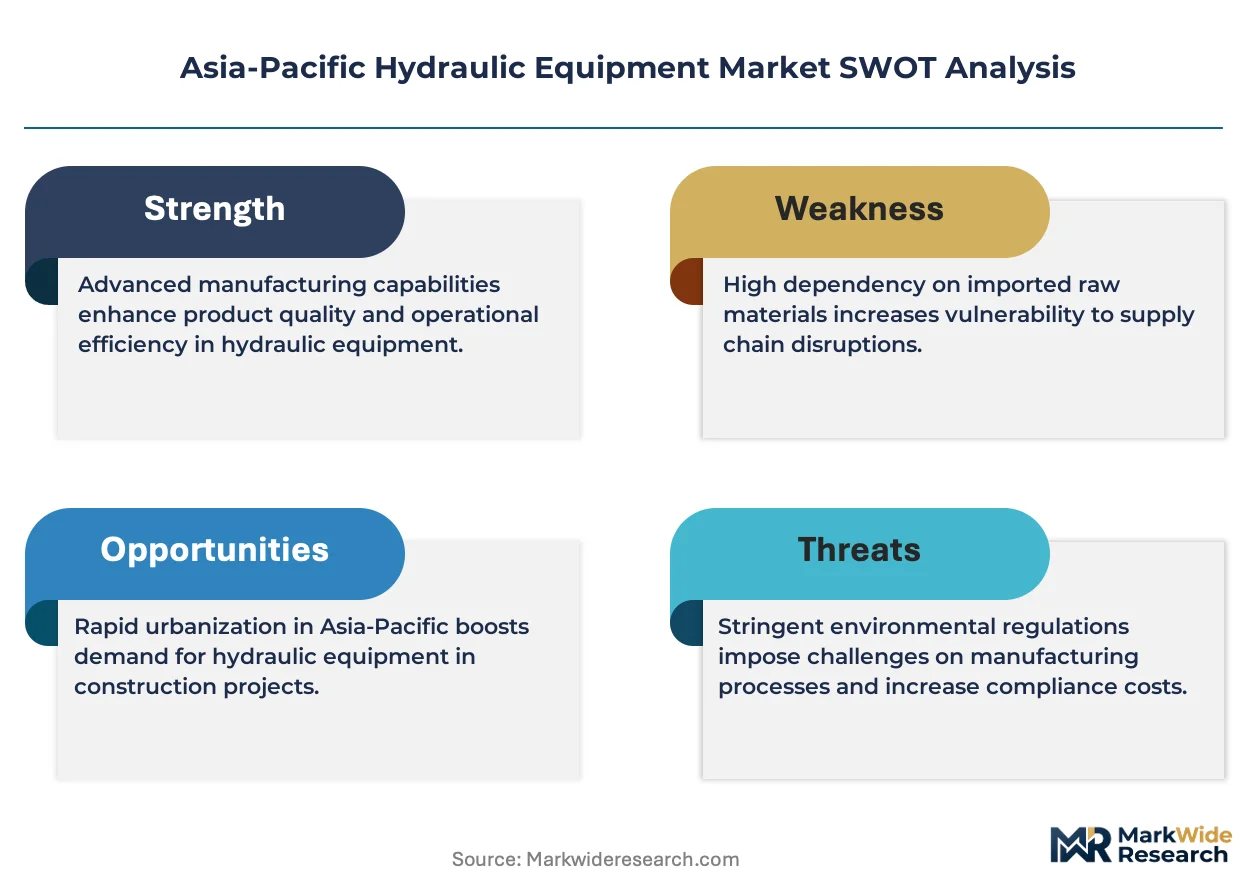
China's dual carbon goals are forcing industrial machinery fleets toward electro-hydraulic architectures, compressing replacement cycles for conventional pump-motor-valve assemblies across the Asia-Pacific basin. This regulatory pressure cascades through supply chains, reshaping component sourcing and service network economics.
Growth Catalysts
- GB Energy-Efficiency Standards:China's SAMR mandates accelerate factory retrofits from fixed-displacement to variable-speed hydraulic drives, creating pull-through demand for power-dense pump technologies.
- Metro Rail Tunneling:ASEAN infrastructure corridors in Thailand, Vietnam, and the Philippines specify high-pressure cylinder systems for tunnel-boring machines, concentrating procurement volumes.
- ISO 4406 Cleanliness Grades:Fluid contamination specifications are unwinding legacy equipment replacement cycles as operators abandon non-compliant fleets.
Market Restraints
- Specialized Steel Input Volatility:Chrome-plated rod and honed tube pricing fluctuates with regional alloy supply, squeezing cylinder manufacturer margins.
- Japan-South Korea Component Concentration:Precision servo valves and smart position sensors concentrate among a narrow supplier base, creating single-source vulnerability.
- Electromechanical Substitution:Linear electric actuators displace hydraulics in sub-50 kW precision positioning applications, capping addressable market expansion.
Strategic Opportunities
- India's Infrastructure Corridors:Mumbai-Delhi-Bangalore project clusters lack established hydraulic service density, creating first-mover channel advantages.
- Remanufacturing Services:Extended producer responsibility frameworks in Japan and South Korea incentivize OEM-controlled rebuild programs for cylinders and pumps.
- Electro-Hydraulic Convergence:Integration of servo drives with proportional valve technology opens precision manufacturing applications previously served by pure electromechanics.
Industry Challenges
- Fluid Power Engineering Talent Scarcity:Universities across Southeast Asia have de-emphasized hydraulics curricula, constraining system design and commissioning capacity.
- JIS B 8361 Certification Timelines:Japan's cylinder safety testing protocols extend product approval cycles, delaying revenue recognition for new designs.
- Legacy Fleet Integration Complexity:Retrofitting analog-controlled machinery with digital electro-hydraulic architectures requires custom manifold engineering that fragments project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hydraulic Equipment Market |
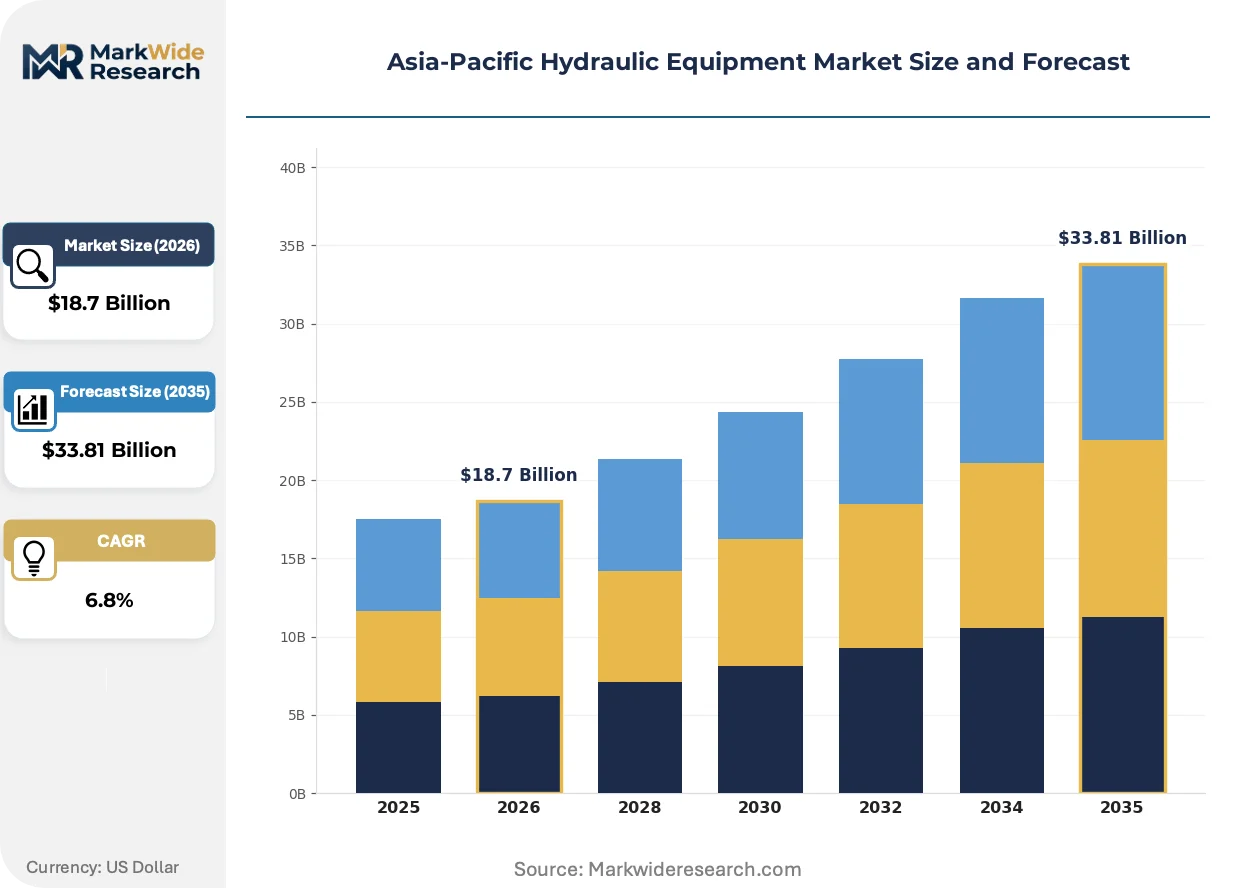
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Pumps, Hydraulic Cylinders, Hydraulic Valves, Hydraulic Motors End User: Construction, Agriculture, Manufacturing, Power Generation Technology: Electro-Hydraulic, Pneumatic-Hydraulic, Hybrid Systems, Digital Controls Application: Material Handling, Dozing, Excavation, Lifting |
| Companies Covered | Danfoss Power Solutions, KYB Corporation, Bosch Rexroth AG, Daikin Industries Ltd., HYDAC International GmbH, Kawasaki Heavy Industries Ltd., Eaton Corp. Plc, Emerson Electric Co., Parker Hannifin Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hydraulic Equipment Market Strategic Shifts
Digitalization is compressing the boundary between fluid power hardware and control electronics, enabling predictive maintenance architectures that reshape aftermarket revenue models. Three developments are redefining competitive positioning.
Compact power units with integrated variable-frequency drives are miniaturizing traditional pump-reservoir-valve assemblies into envelope dimensions previously reserved for electromechanical alternatives. Mobile equipment OEMs in Indonesia and Thailand are specifying these designs for excavators and aerial work platforms where engine compartment space constraints previously dictated architecture. This miniaturization is enabling hydraulic system penetration into equipment categories that historically excluded fluid power on packaging grounds.
China's GB/T energy-efficiency compliance mandates for industrial machinery are accelerating factory audits and equipment replacement timelines under national dual carbon goals. Manufacturers must document hydraulic system efficiency ratings or face production quota restrictions. The construction machinery segment is responding fastest, with provincial fleet operators in Guangdong and Jiangsu pre-emptively retiring non-compliant excavators ahead of enforcement deadlines.
After-sales service unbundling is fragmenting traditional OEM-captive maintenance relationships as independent hydraulic repair specialists capture cylinder rebuild and fluid analysis revenue. Construction contractors in Australia's mining regions and India's infrastructure corridors are disaggregating procurement—buying components from distributors while sourcing field service from third-party technicians. This behavior is most visible in high-downtime-cost applications where rapid response trumps brand loyalty.
Asia-Pacific Hydraulic Equipment Market Segmentation
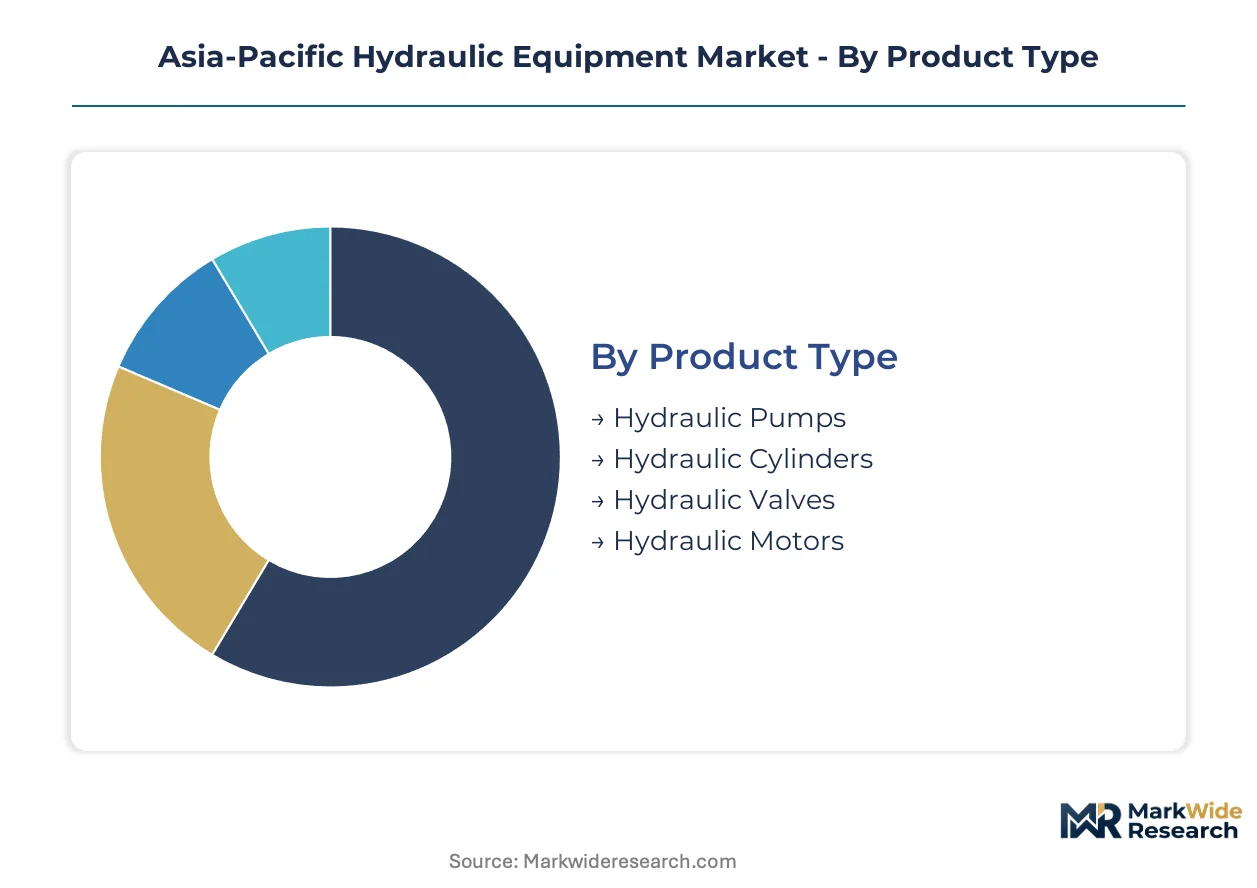
Channel economics across the Asia-Pacific hydraulic equipment market diverge sharply by product complexity and service intensity. Construction contractors favor distributor networks for standardized pumps and motors, while precision manufacturing segments demand direct OEM relationships for integrated electro-hydraulic systems.
Product Type:
Channel-mix patterns concentrate high-volume pumps and cylinders through construction equipment OEMs and aftermarket distributors, whereas specialized valves and motors flow through system integrators serving precision manufacturing.
- Hydraulic Pumps:Variable-displacement axial piston designs dominate industrial applications above 3,000 psi operating pressure. Demand clusters in China's Guangdong and Jiangsu provinces where factory retrofit programs under SAMR energy-efficiency mandates are accelerating replacement timelines.
- Hydraulic Cylinders:Chrome-plated rod and honed tube assemblies enable precise force transmission for heavy-load operations. Metro rail tunneling projects across Thailand, Vietnam, and the Philippines specify high-pressure cylinder systems for tunnel-boring machines, concentrating procurement volumes.
- Hydraulic Valves:Proportional and servo valve technologies interface with digital control architectures.
- Hydraulic Motors:Orbital and piston motor configurations power mobile equipment drivetrains.
Hydraulic pumps dominate installed base. Electro-hydraulic convergence in digital controls is where expansion concentrates.
End User:
Cost-tier stratification separates premium-specification systems for power generation from standard-grade equipment serving agricultural mechanization, with construction occupying the volume-driven middle tier.
- Construction:Excavators, loaders, and aerial platforms require high-pressure systems operating at 3,000-6,000 psi with contamination resistance to ISO 4406 standards. India's infrastructure corridor projects spanning Mumbai, Delhi, and Bangalore lack established hydraulic service density, creating first-mover channel advantages for suppliers with local assembly presence.
- Power Generation:Hydropower turbine governor systems and thermal plant valve actuation demand precision force control with extended maintenance intervals. Laos and Vietnam hydropower expansion drives structural momentum for high-reliability cylinder and pump technologies.
- Agriculture:Tractor implements and harvester hydraulics prioritize cost-optimized gear pumps and single-acting cylinders.
- Manufacturing:Press brakes, injection molding, and machine tool applications favor compact power units with integrated variable-frequency drives.
Construction commands the largest revenue pool. Power generation offers the steepest expansion trajectory as ASEAN hydropower capacity accelerates.
Technology:
Application requirements dictate technology selection, with mobile equipment favoring compact electro-hydraulic architectures while stationary industrial systems adopt hybrid configurations for energy recovery.
- Electro-Hydraulic:Servo-driven proportional valve technology enables closed-loop position and force control with diagnostic feedback. China's GB/T energy-efficiency compliance mandates are accelerating factory audits and equipment replacement timelines under national dual carbon goals.
- Digital Controls:Embedded sensors and edge computing modules enable predictive maintenance architectures that reshape aftermarket revenue models. Japan and South Korea precision manufacturing applications are capturing disproportionate margin expansion as OEMs retrofit legacy fleets.
- Hybrid Systems:Energy recovery accumulators and regenerative drives reduce input power requirements.
- Pneumatic-Hydraulic:Intensifier systems leverage shop air for localized high-pressure generation.
Conventional pneumatic-hydraulic systems retain niche presence. Electro-hydraulic convergence is gaining share fastest as efficiency regulations tighten.
Application:
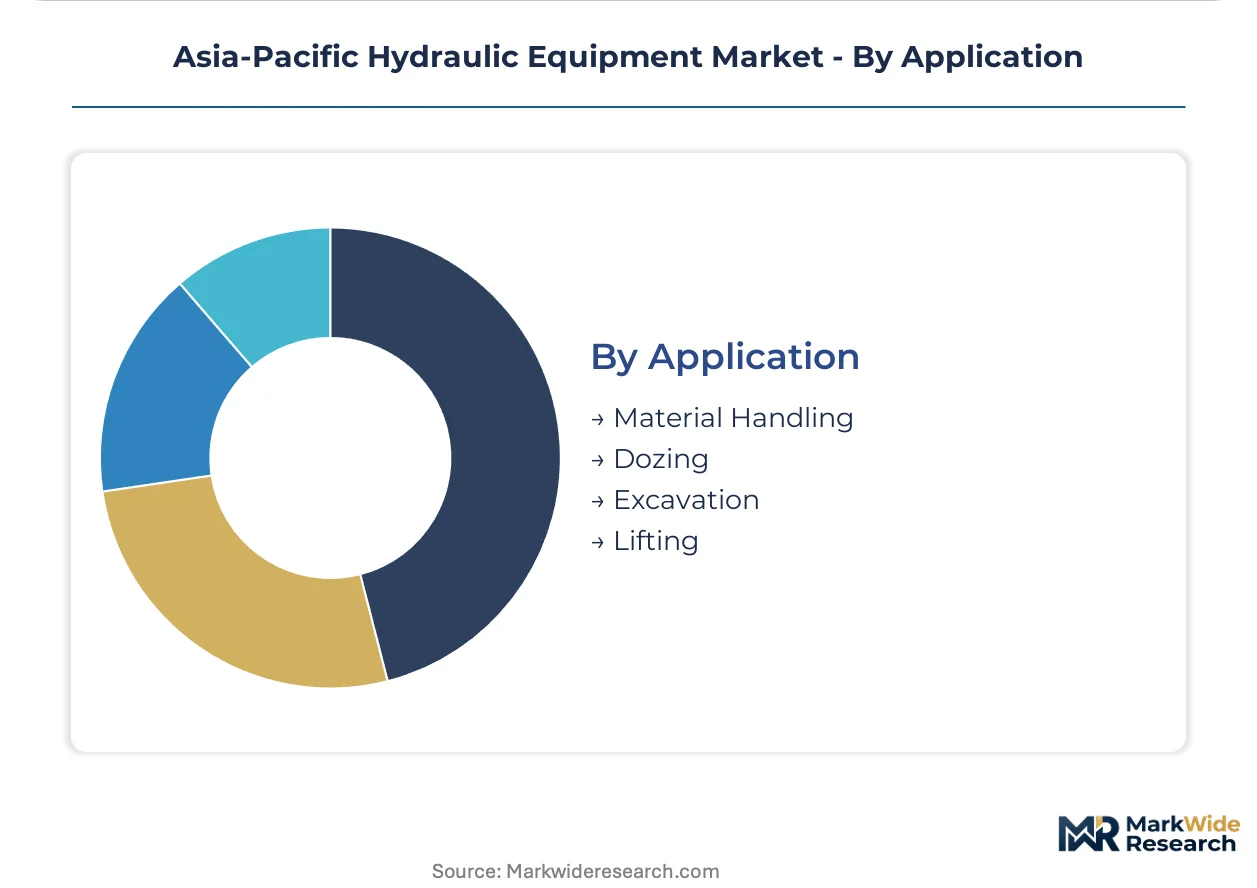
Volume concentration in excavation equipment contrasts with margin-rich lifting applications where safety certification and precision positioning command pricing premiums.
- Excavation:Crawler and wheeled excavators utilize multi-circuit systems for boom, arm, and bucket articulation. Provincial fleet operators in China's Guangdong and Jiangsu are pre-emptively retiring non-compliant machines ahead of SAMR enforcement deadlines.
- Lifting:Crane and aerial work platform hydraulics require load-holding valves and precise metering for personnel safety. Indonesia and Thailand mobile equipment OEMs are specifying compact power units where engine compartment space constraints previously dictated architecture.
- Material Handling:Forklift mast and attachment systems prioritize fast cycle speeds.
- Dozing:Bulldozer blade control emphasizes high-force, low-speed operation.
Excavation anchors unit volume. Lifting applications are climbing the fastest as infrastructure safety standards intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports precision hydraulic components to South Korean and Chinese manufacturing clusters, while Australian mining operators source cylinder rebuild services from Southeast Asian service hubs. This trade architecture concentrates high-value production in Northeast Asia and distributes aftermarket capacity across ASEAN states.
China
Guangdong and Jiangsu provincial fleets are pre-emptively retiring non-compliant excavators ahead of SAMR enforcement deadlines under GB/T energy-efficiency mandates. The dual carbon goals compress replacement cycles for fixed-displacement pump-motor-valve assemblies. Factory retrofit programs in the Pearl River Delta create concentrated demand for power-dense variable-speed hydraulic drives.
Japan
Precision manufacturing applications in Nagoya and Osaka command disproportionate margin expansion as OEMs retrofit legacy fleets with electro-hydraulic architectures. METI enforces JIS B 8361 standards for hydraulic cylinder safety testing, extending product approval cycles. Kanto-based fabricators supply servo valve technologies to South Korean and Taiwanese system integrators.
India
Mumbai-Delhi-Bangalore infrastructure corridor projects lack established hydraulic service density, creating first-mover channel advantages. BIS certification requirements for construction machinery hydraulics favor suppliers with local assembly presence. Maharashtra and Karnataka state governments are fast-tracking metro rail tunneling contracts that specify high-pressure cylinder systems.
South Korea
Smart position sensors and precision servo valves concentrate among a narrow supplier base in the Seoul Capital Area, creating single-source vulnerability for regional OEMs. MFDS-equivalent industrial safety frameworks align with Japanese JIS standards, facilitating cross-border component trade. Busan-Ulsan manufacturing clusters import Japanese cylinder technologies for shipbuilding and heavy equipment applications.
Thailand
Bangkok metro expansion and Laem Chabang port modernization are specifying tunnel-boring machine hydraulics and container handling systems. KYB Corporation anchors construction OEM supply chains through dedicated cylinder production facilities in the Eastern Economic Corridor. Thai distributors are capturing aftermarket revenue from Indonesian and Vietnamese fleet operators seeking faster field service response.
Asia-Pacific Hydraulic Equipment Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The vendor base organizes into three tiers: integrated drive-and-control conglomerates, component-focused cylinder and pump fabricators, and regional service specialists capturing aftermarket rebuild revenue. Consolidation pressure concentrates among mid-scale cylinder manufacturers facing chrome-plated rod input volatility. Dominant competitive moves include backward integration into specialized steel supply and strategic partnerships with construction OEMs for co-development of compact power units.
Within the integrated systems tier, Bosch Rexroth AG and Danfoss Power Solutions occupy positions spanning high-precision manufacturing and mobile equipment applications. KYB Corporation exemplifies the component-specialist archetype with dedicated production infrastructure in Southeast Asia. Daikin Industries Ltd. represents compact power unit design capabilities for space-constrained mobile architectures. These three anchors illustrate how geographic production placement and product envelope specialization determine competitive positioning across the Asia-Pacific basin.
| Leading Market Players |
|---|
| Danfoss Power Solutions |
| KYB Corporation |
| Bosch Rexroth AG |
| Daikin Industries Ltd. |
| HYDAC International GmbH |
| Kawasaki Heavy Industries Ltd. |
| Eaton Corp. Plc |
| Emerson Electric Co. |
| Parker Hannifin Corporation |
| Others |
Value Chain & Pricing Dynamics
China's SAMR-administered GB/T energy-efficiency compliance gates both supplier qualification and price differentiation simultaneously, as OEMs must document certified efficiency ratings to access provincial procurement pools while non-compliant equipment faces quota restrictions that compress residual value.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with premium tiers commanded by JIS B 8361-certified cylinders and ISO 4406-compliant fluid systems. Price differentiation rests on certification grade and after-sales service bundling, with rebuild-included contracts capturing 40% margin premiums over transactional component sales. Cost compression in economy-tier gear pumps is intensifying because Indonesian and Thai mobile equipment OEMs are consolidating supplier panels. Construction contractors exhibit highest price sensitivity, while power generation utilities prioritize extended maintenance intervals over unit cost.
Supply Chain Analysis
Extended cylinder lead times stretching to 16 weeks signal supply-side strain concentrated in Japan, South Korea, and China's Jiangsu province. Chrome-plated rod and honed tube supplies draw from regional alloy mills in Northeast Asia, with servo valve production hinging on precision machining capacity in the Seoul Capital Area. Single-source vulnerability in smart position sensors creates systemic risk for ASEAN system integrators. Distribution runs through construction equipment OEM captive networks for high-complexity electro-hydraulic systems, while standardized pumps flow via distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity crystallizes as after-sales service unbundling fragments traditional OEM-captive maintenance relationships, creating niche entry points for independent repair specialists and component distributors across Australia's mining regions and India's infrastructure corridors.
For Market Incumbents: Shield installed base revenue by backward integration into specialized steel supply for chrome-plated rod and honed tube production, reducing exposure to regional alloy price volatility. Accelerate certification investment in JIS B 8361 and GB/T compliance to preempt regulatory displacement of legacy architectures. Channel control through exclusive service partnerships with metro rail tunneling contractors in Thailand and Vietnam defends margin position against independent hydraulic repair specialists capturing cylinder rebuild revenue. For New Entrants and Emerging Players: BIS certification fast-tracks for construction machinery hydraulics unlock first-mover channel advantages in India's Mumbai-Delhi-Bangalore infrastructure corridor projects, where established hydraulic service density remains underdeveloped. Target compact power unit designs for Indonesian and Thai mobile equipment OEMs facing engine compartment space constraints. Go-to-market angle should emphasize rapid field service response capabilities that outpace incumbent OEM-captive maintenance networks in high-downtime-cost applications. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming hydraulic component divisions lacking electro-hydraulic convergence capabilities. Long-term viability favors suppliers with captive Southeast Asian production infrastructure and demonstrated compliance navigation across China's SAMR, Japan's METI, and India's BIS frameworks. Monitor ASEAN harmonization of machinery safety directives as inflection indicator for cross-border component sourcing economics consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialized Steel Supply | Captive chrome-plated rod production insulates margin from regional alloy price volatility. |
| Electro-Hydraulic System Certification Investment | GB/T and JIS B 8361 compliance unlocks provincial procurement pools in China and Japan. |
| Compact Power Unit Design Development | Miniaturized pump-reservoir-valve assemblies penetrate mobile equipment categories previously excluding fluid power. |
| Remanufacturing Service Network Expansion | Extended producer responsibility frameworks in Japan and South Korea incentivize OEM-controlled rebuild programs. |
| ASEAN Service Hub Establishment | Thai distributors capture aftermarket revenue from Indonesian and Vietnamese fleet operators seeking faster response. |
Study Parameters
Initial hypotheses were tested against primary input from maintenance directors at construction and mining operators, OEM procurement teams specifying hydraulic systems, aftermarket service heads managing cylinder rebuild programs, and plant engineers overseeing factory retrofit programs, then refined against secondary validation from customs and trade data, SEC 10-K filings of listed hydraulic equipment manufacturers, SAMR and METI regulatory disclosure databases, and construction machinery production statistics. Bottom-up demand modeling across end-use segments triangulated with top-down supply-side capacity assessments.
Variance decomposition across product type, end-user industry, technology architecture, and application intensity shaped the analytical framework throughout the projection horizon. CAGRs were derived from segment-level demand build-ups incorporating equipment replacement timelines under GB/T energy-efficiency mandates and infrastructure project procurement schedules across ASEAN states. Industry-specific forecast inputs included hydropower capacity expansion timelines in Laos and Vietnam and metro rail tunneling contract awards in Thailand and the Philippines.
The analysis sits within stated boundaries; outcomes outside sustained enforcement of China's dual carbon goals and ASEAN infrastructure commitment levels would require recalibration. Forecasts reflect assumptions regarding regulatory compliance timelines and alloy supply stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Asia-Pacific Road Marking Machine Market
Construction Equipment
Boom Lifts Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
Laser Beam Welding Equipment Market
Construction Equipment
Global Riveting Equipment Market
Construction Equipment
Static Crane Market
Construction Equipment
Crane Rail Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Global Light Towers Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Global Construction Industry Core Drill Market
Construction Equipment
Welding Fume Extraction Equipment Market