
 Asia Pacific Silage Additives Market | 2026-2036
Asia Pacific Silage Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Silage Additives Market Outlook
Australia's commercial silage additive production base is narrowing as domestic formulators consolidate manufacturing around Melbourne and Sydney hubs. Nutreco leverages its regional premix network to distribute specialized inoculant blends across Southeast Asian dairy operations. BASF SE sustains technology leadership through microbial strain development programs targeting tropical fermentation conditions. Chr. Hansen anchors its position with dairy-focused technical service teams stationed in New Zealand and Japan.
Asia Pacific silage additives comprise microbial inoculants, organic acids, enzymes, and sorbate-based preservatives applied to fresh forage to accelerate lactic acid fermentation, suppress spoilage organisms, and stabilize crude protein content for ruminant feed. These formulations typically deliver colony-forming units exceeding one hundred billion per gram for bacterial inoculants, with application rates calibrated to moisture content and crop type. Inoculants dominate product-type revenue due to established efficacy data and farmer familiarity, while enzymes capture faster growth as operations seek fiber digestibility improvements in corn silage and whole crop systems. Liquid delivery modes lead volume share among large dairy farms with mechanized application equipment, though dry and granular forms penetrate smaller agricultural producers lacking precision spraying infrastructure.
China's SAMR enforces GB standards for feed additive labeling and microbial strain registration, while India's FSSAI mandates contaminant limits and manufacturing facility audits for silage preservative distribution. Japan's MAFF and Australia's APVMA maintain separate biosecurity and residue testing protocols that shape import requirements and local formulation strategies. Stakeholders must monitor evolving strain approval timelines and cross-border equivalence agreements that determine competitive access across national dairy sectors.
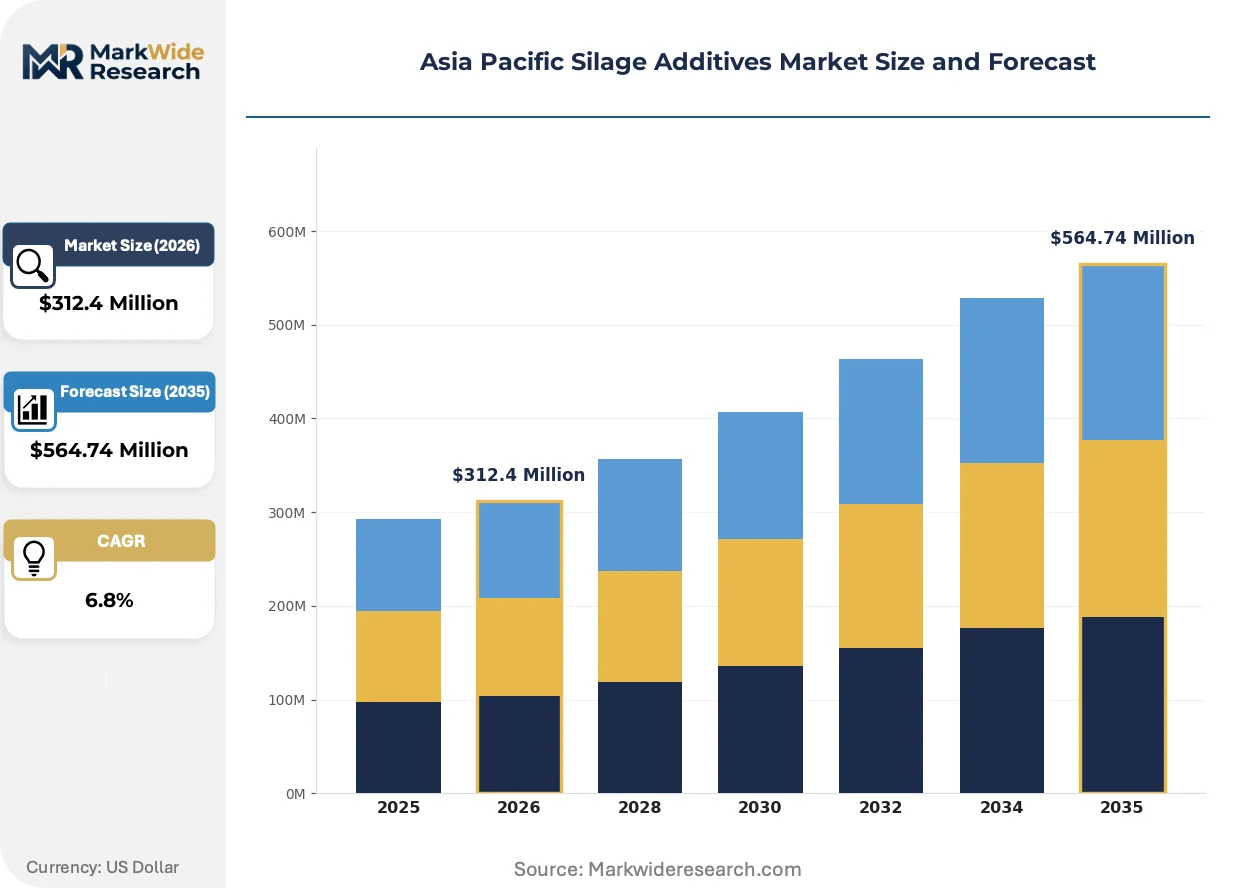
Market Dynamics
Intensive dairy corridor expansion across eastern China is compressing application windows and forcing rapid adoption of precision inoculant dosing systems calibrated to tropical moisture profiles.
Growth Catalysts
- China's SAMR strain registration protocols:Accelerated approval timelines for tropical-adapted bacterial inoculants are clearing commercial pathways for specialized microbial formulations targeting high-humidity fermentation environments.
- Whole-crop cereal silage systems:Southeast Asian dairy cooperatives are expanding acreage under corn and sorghum silage to secure year-round roughage supply, driving inoculant volume through mechanized harvest operations.
- FSSAI contaminant limit enforcement:India's tightened mycotoxin thresholds for dairy feed inputs are pushing commercial farms toward acid-based preservatives with documented antifungal efficacy data.
Market Restraints
- Lactic acid bacteria culture supply concentration:Strain banking and master cell line maintenance cluster in Australian and Japanese bioreactor facilities, creating cross-border dependency for Southeast Asian formulators.
- Propionic acid feedstock volatility:Crude oil derivative pricing swings directly compress margin structures for organic acid preservative blends, forcing reformulation toward microbial alternatives.
- Japan's MAFF biosecurity protocols:Extended quarantine requirements for novel microbial strains delay product registration by 18-24 months versus regional peers, constraining innovation pipeline velocity.
Strategic Opportunities
- Vietnam's emerging intensive dairy belt:Greenfield farm construction around Ho Chi Minh City corridor creates first-mover positioning for technical service-intensive inoculant suppliers with local agronomy support.
- Dual carbon policy alignment:China's provincial agricultural bureaus are piloting silage additive subsidies tied to methane reduction metrics, opening public procurement channels for verified low-emission formulations.
- Enzyme-inoculant co-formulation:Fiber-degrading cellulase blends combined with homofermentative bacteria are penetrating corn silage segments where digestibility premiums justify higher per-ton application costs.
Industry Challenges
- Application equipment calibration expertise:Large-scale Vietnamese and Indonesian operations lack technical staff capable of matching inoculant dilution rates to real-time moisture testing, causing efficacy variance and farmer skepticism.
- Cross-border strain equivalence documentation:Australian APVMA and Chinese SAMR maintain non-harmonized microbial characterization standards, forcing duplicate stability testing for regional product registration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Silage Additives Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inoculants, Enzymes, Sorbates, Acids Application: Corn Silage, Grass Silage, Whole Crop Silage, Legume Silage Delivery Mode: Liquid Form, Dry Form, Powder Form, Granular Form End User: Dairy Farms, Feedlots, Agricultural Producers, Others |
| Companies Covered | Nutreco, Cargill Inc., BASF SE, Alltech, BIOMIN Holding GmbH, Archer Daniels Midland Company, DSM-Firmenich, Chr. Hansen, Lallemand Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Silage Additives Market Strategic Shifts
Precision fermentation monitoring and automated dosing hardware are converging to transform silage additive application from calendar-based routines to real-time biological intervention protocols.
Multi-strain bacterial consortia engineered for tropical temperature tolerance are collapsing the performance gap between ambient-condition storage and climate-controlled bunker systems. Thai and Malaysian dairy operations with limited capital for infrastructure upgrades are adopting these enhanced inoculants at twice the pace of conventional single-strain products. The technology is collapsing the historical trade-off between preservation reliability and infrastructure investment for mid-scale farms across Southeast Asia.
China's SAMR implemented revised GB standards for feed additive microbial labeling in 2023, mandating strain-level identification and minimum viable count guarantees at point-of-use rather than manufacture. This regulatory shift forces formulators to reformulate for extended shelf stability or invest in cold-chain distribution infrastructure. Domestic Chinese producers with integrated bioreactor-to-farm logistics networks are capturing share from import-reliant competitors unable to meet documentation burdens.
Dairy cooperatives in Indonesia and the Philippines are consolidating procurement decisions at regional hub level, displacing individual farm purchasing and compressing supplier count per territory. These buyer groups now demand bundled technical service packages including forage testing, application training, and fermentation outcome guarantees. The shift is most visible in East Java and Luzon where processor-linked farm clusters coordinate additive selection to meet unified milk quality specifications.
Asia Pacific Silage Additives Market Segmentation
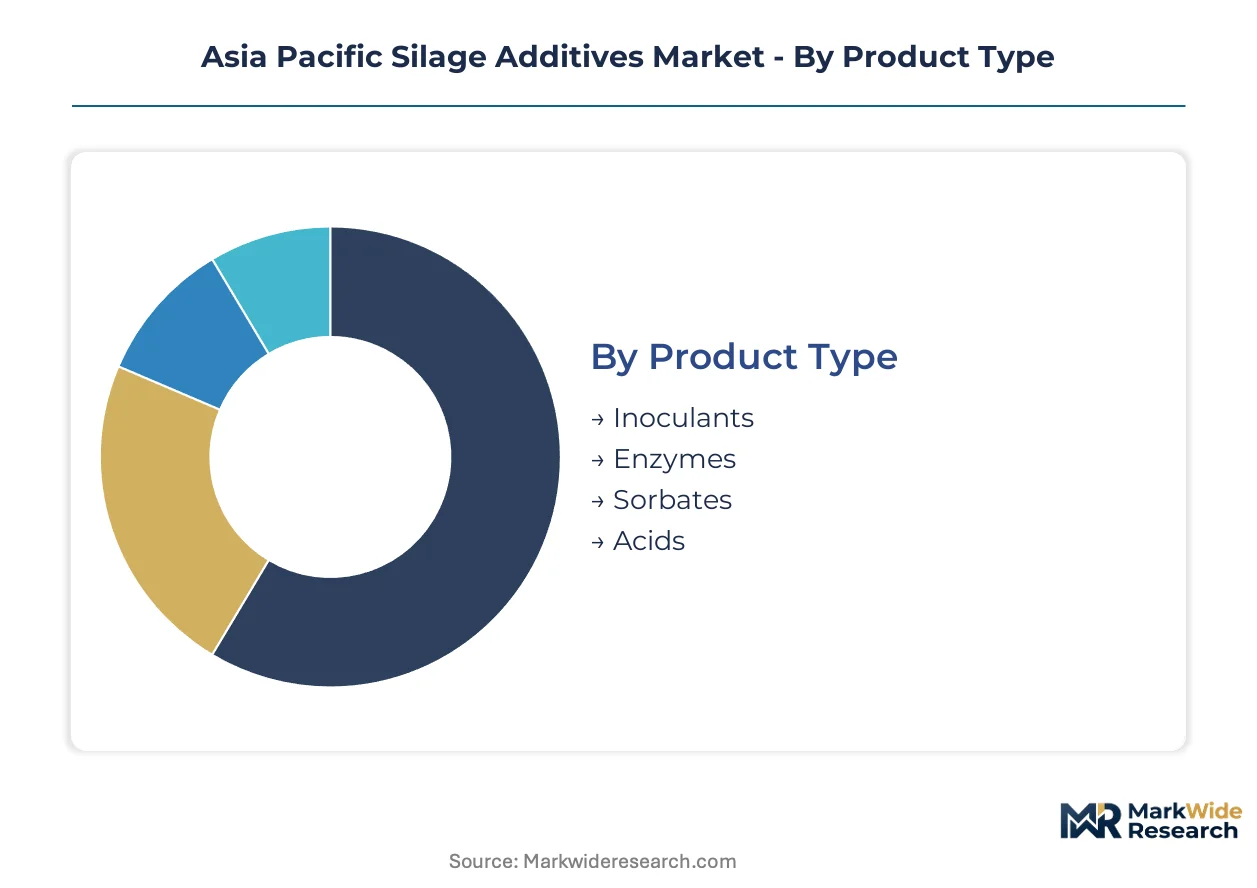
Segmentation in the Asia Pacific silage additives market reveals how product selection tracks farm infrastructure, crop systems, and regulatory exposure across diverse national dairy sectors. Understanding these splits exposes where technical service investments yield procurement influence and where commodity positioning dominates.
Product Type:
Use-case spectrum spans from precision microbial interventions for large commercial dairies to commodity acid preservatives for cost-sensitive cooperatives managing mycotoxin risk.
- Inoculants:Bacterial formulations delivering colony-forming units exceeding one hundred billion per gram dominate procurement volumes across eastern China's intensive dairy corridors where fermentation consistency under tropical humidity commands premium positioning. Dairy operations in Vietnam's Ho Chi Minh City belt are compressing application windows and forcing rapid adoption of precision dosing systems calibrated to these live-culture specifications.
- Enzymes:Fiber-degrading cellulase blends target digestibility improvements in corn silage and whole crop systems, capturing expanding share where milk yield premiums justify higher per-ton application costs. Thai and Malaysian operations with limited climate-controlled bunker infrastructure are adopting enhanced enzyme-inoculant co-formulations at accelerated pace.
- Sorbates:Potassium sorbate-based preservatives suppress yeast and mold proliferation in high-moisture forage, finding placement where SAMR and FSSAI contaminant enforcement tightens.
- Acids:Propionic and formic acid blends deliver documented antifungal efficacy for Indian commercial farms responding to FSSAI mycotoxin thresholds, though crude oil derivative volatility compresses margin structures.
Established volume favors inoculants; emerging adoption favors enzymes.
Application:
Crop-type segmentation maps directly onto regional feed sourcing strategies and harvest mechanization levels across Southeast Asian dairy belts.
- Corn Silage:Dominant roughage source for Southeast Asian cooperatives expanding acreage under mechanized harvest operations, driving additive volume through processor-linked farm clusters in East Java and Luzon coordinating selection to meet unified milk quality specifications.
- Grass Silage:Temperate-zone staple for New Zealand and Australian pastoral systems where seasonal growth patterns dictate preservation priorities.
- Whole Crop Silage:Cereal-based systems capturing share in Vietnam and Indonesia where year-round roughage security outweighs nutritional optimization.
- Legume Silage:Alfalfa and clover preservation for high-protein ration formulations, concentrated in Japanese and South Korean intensive operations.
Corn silage anchors current procurement volumes; whole crop systems are climbing the fastest as greenfield construction accelerates.
Delivery Mode:
Physical form selection bifurcates along mechanization gradients separating large commercial operations from smaller agricultural producers.
- Liquid Form:Leads volume share among large dairy farms with precision spraying infrastructure, requiring calibrated dilution rates matched to real-time moisture testing protocols that Vietnamese and Indonesian operations often lack.
- Dry Form:Penetrates mid-scale farms lacking liquid handling systems, offering shelf stability advantages under SAMR's revised labeling standards.
- Powder Form:Compact packaging for smallholder cooperatives with limited storage capacity.
- Granular Form:Spreading-compatible applications for operations with basic mechanization.
Liquid delivery commands premium positioning; dry forms are gaining share fastest where cold-chain infrastructure gaps constrain live-culture distribution.
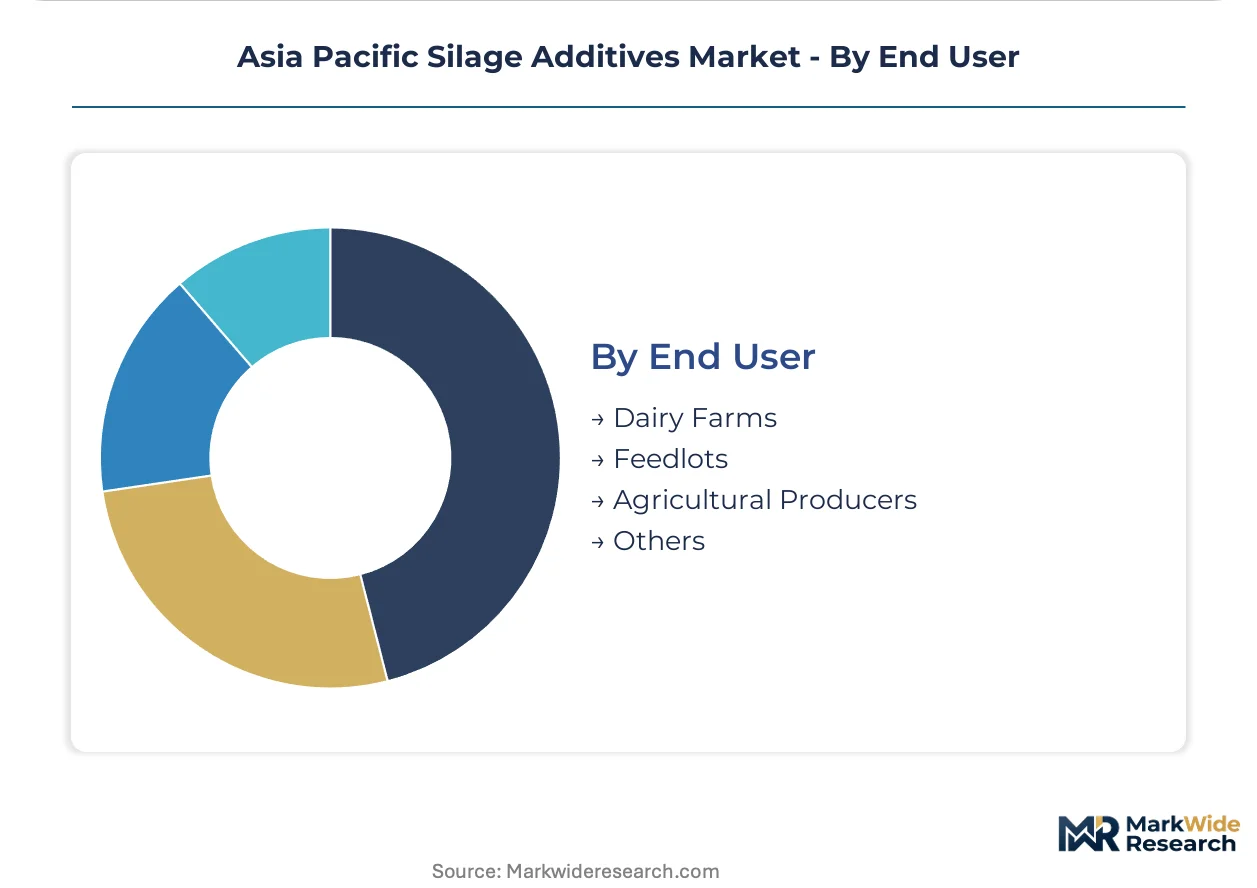
End User:
Customer-type segmentation concentrates decision authority and technical service requirements across divergent operational scales.
- Dairy Farms:Primary demand concentration in eastern China's intensive corridors and Vietnam's emerging belt, where regional procurement hubs now displace individual farm purchasing and demand bundled technical service packages.
- Feedlots:Cattle finishing operations in Australia and India with distinct preservation priorities focused on dry matter retention rather than milk quality optimization.
- Agricultural Producers:Diversified crop-livestock operations supplying regional dairy processors, concentrated in Philippines and Indonesia.
- Others:Research institutions and government extension programs piloting methane-reduction formulations under China's provincial subsidy schemes.
Dairy farms anchor commercial investment; feedlots represent the steepest expansion trajectory as beef finishing intensifies across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR anchors regulatory momentum across the region, with GB standards for feed additive labeling and microbial strain registration reshaping commercial pathways. Intensive dairy corridor expansion in eastern provinces and Vietnam's emerging belt compress application windows and accelerate precision dosing adoption.
China
Eastern China's intensive dairy corridors concentrate additive demand as large-scale operations require consistent forage quality under tropical humidity. SAMR's revised GB standards mandate strain-level identification and minimum viable count guarantees at point-of-use, forcing cold-chain infrastructure investments. Provincial agricultural bureaus in Jiangsu and Shandong pilot silage additive subsidies tied to methane reduction metrics.
Vietnam
Greenfield farm construction around the Ho Chi Minh City corridor creates first-mover positioning for technical service-intensive suppliers. Dairy cooperatives expanding whole-crop cereal silage systems drive inoculant volume through mechanized harvest operations. Commercial operations in the Mekong Delta lack technical staff capable of matching inoculant dilution rates to real-time moisture testing.
India
Commercial farms responding to FSSAI's tightened mycotoxin thresholds push toward acid-based preservatives with documented antifungal efficacy data. Feedlots in Punjab and Haryana represent distinct preservation priorities focused on dry matter retention. Manufacturing facility audits mandated by national feed safety guidelines constrain import-reliant competitors.
Japan
Intensive dairy operations in Hokkaido and Tohoku concentrate demand for legume silage preservation in high-protein ration formulations. MAFF biosecurity protocols impose extended quarantine requirements for novel microbial strains, delaying product registration by 18-24 months versus regional peers. Technical service teams stationed domestically anchor supplier positioning.
Australia
Temperate-zone pastoral systems in Victoria and New South Wales dictate seasonal grass silage preservation priorities. APVMA maintains separate biosecurity and residue testing protocols that shape local formulation strategies. Commercial production base consolidation around Melbourne and Sydney hubs narrows domestic formulator networks.
Asia Pacific Silage Additives Market Competitive Environment
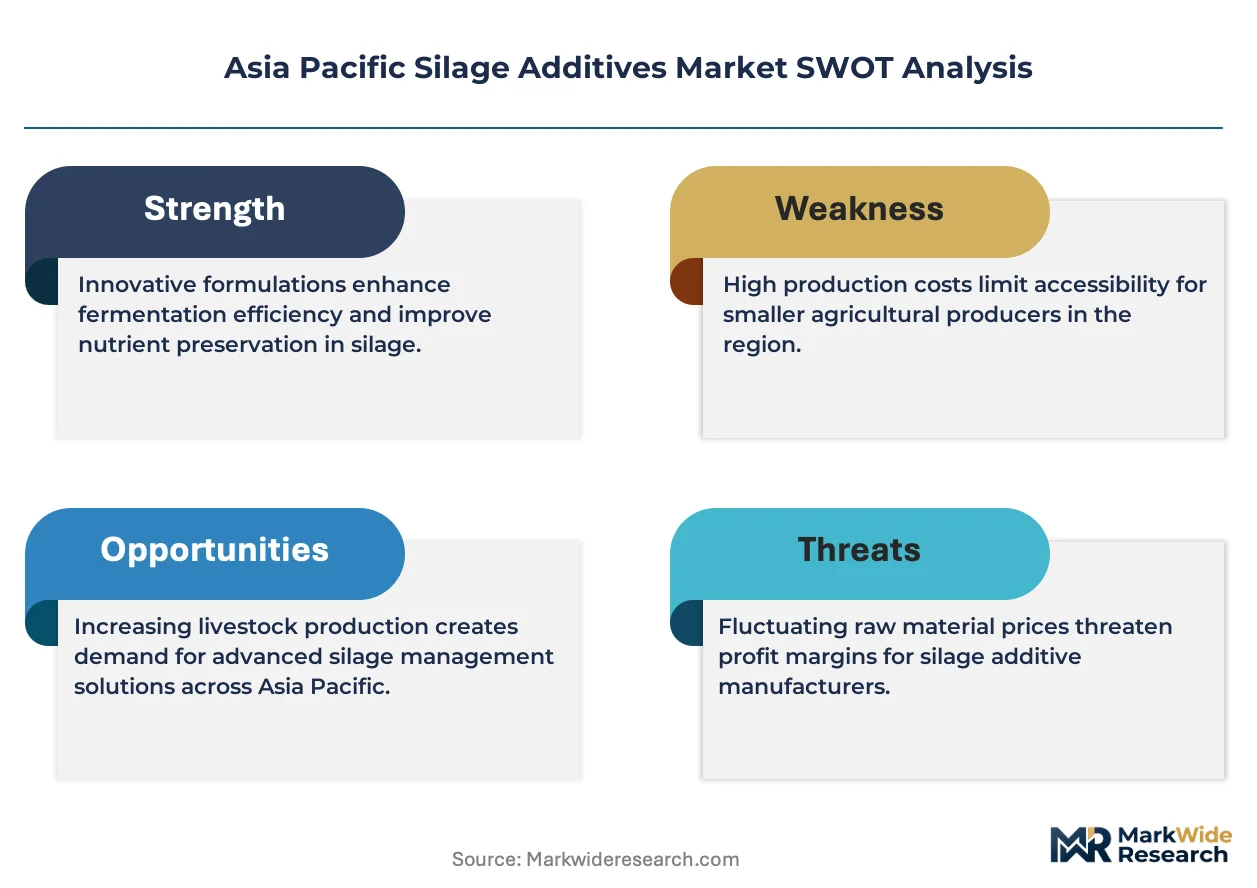
Multinational nutrition conglomerates and specialized microbial technology developers split the market along technical service intensity and strain development capability lines. The vendor base concentrates around established premix networks and regional bioreactor facilities, with cross-border dependencies for Southeast Asian formulators. Three archetypes dominate: integrated animal nutrition platforms with distribution scale, dedicated microbial science specialists with strain banking assets, and regional premix formulators with local agronomy presence. Competitive moves center on M&A to secure tropical-adapted strain portfolios and capacity expansion into Vietnamese and Indonesian dairy belts.
Among European-anchored nutrition platforms, Nutreco and DSM-Firmenich occupy positions exemplifying integrated premix-to-farm distribution scale, while BASF SE and Chr. Hansen represent specialized microbial technology archetypes with strain development programs targeting tropical fermentation conditions. These entities anchor competitive positioning through technical service infrastructure and regulatory navigation capability across divergent national approval timelines.
| Leading Market Players |
|---|
| Nutreco |
| Cargill Inc. |
| BASF SE |
| Alltech |
| BIOMIN Holding GmbH |
| Archer Daniels Midland Company |
| DSM-Firmenich |
| Chr. Hansen |
| Lallemand Inc. |
| Others |
Value Chain & Pricing Dynamics
Propionic acid feedstock volatility compresses margin structures for organic acid preservative blends, forcing reformulation toward microbial alternatives while simultaneously widening price spreads between premium inoculant tiers and commodity acid-based preservatives across Southeast Asian procurement channels.
Pricing Analysis
Price spreads between Australian-manufactured inoculants and Indian acid preservatives exceed threefold across Vietnam's Ho Chi Minh City dairy belt. Three-tier pricing structure across premium, standard, and economy levels stratifies by strain certification tier and bundled technical service intensity. Cost compression in acid-based tiers is intensifying because crude oil derivative pricing swings feed directly into propionic and formic acid blend economics. Smallholder cooperatives in Indonesia and the Philippines exhibit highest price sensitivity, while eastern China's intensive dairy corridors prioritize fermentation outcome guarantees over per-ton application costs.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now anchor supplier relationships across Southeast Asian distribution networks. Strain banking and master cell line maintenance cluster in Australian and Japanese bioreactor facilities, creating cross-border dependency for Vietnamese and Indonesian formulators. Live-culture inoculants draw from tropical-adapted bacterial consortia development programs, while organic acid blends rest on petrochemical feedstock channels. Single-source vulnerability concentrates in lactic acid bacteria culture supply from Melbourne and Sydney hub facilities. Distribution runs through Nutreco's regional premix network and Chr. Hansen's technical service infrastructure anchored in New Zealand and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific silage additives market sits at a platform-economics inflection where fermentation monitoring hardware and automated dosing systems are converging to create integrated solution ecosystems that displace standalone product procurement.
For Market Incumbents: Build technical service moats through embedded agronomy teams stationed across Vietnam's emerging dairy belt and eastern China's intensive corridors. Incumbent suppliers should secure tropical-adapted strain portfolios through selective capacity expansion into Indonesian bioreactor facilities. Chr. Hansen's dairy-focused technical service infrastructure in New Zealand and Japan exemplifies the channel control lever that constrains price-based substitution. For New Entrants and Emerging Players: Mid-scale Vietnamese operations lacking precision application equipment calibration expertise represent the most penetrable entry point for dry-form inoculant suppliers with simplified dosing protocols. Thailand's enzyme-inoculant co-formulation segment offers white-space positioning where fiber digestibility premiums justify higher per-ton economics. A go-to-market angle anchored to provincial agricultural bureau subsidy programs tied to methane reduction metrics unlocks public procurement channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated animal nutrition platforms with captive strain development capabilities. Long-term viability across the analysis window hinges on regulatory navigation assets spanning SAMR, FSSAI, and MAFF approval timelines. Acquisition targets should demonstrate established master cell line maintenance infrastructure. The signal to watch as inflection indicator is cross-border strain equivalence agreement harmonization between Australian APVMA and Chinese SAMR protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Portfolio Acquisition | Tropical-adapted bacterial consortia development collapses the performance gap between ambient storage and climate-controlled systems. |
| Technical Service Infrastructure Expansion | Embedded agronomy teams in Vietnam's Ho Chi Minh City belt address application equipment calibration expertise gaps. |
| Cold-Chain Distribution Investment | SAMR's revised GB standards for point-of-use viable count guarantees force shelf stability infrastructure. |
| Enzyme-Inoculant Co-Formulation Development | Fiber-degrading cellulase blends penetrate corn silage segments where digestibility premiums justify higher per-ton costs. |
| Provincial Subsidy Program Alignment | China's dual carbon policy pilots for methane reduction metrics open public procurement channels for verified low-emission formulations. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with industry stakeholders and systematic secondary validation across regulatory and trade databases. Primary fieldwork encompassed dairy farm operations managers, silage additive formulator technical directors, feed mill procurement leads, and provincial agricultural extension officers across China, Vietnam, India, and Australia. Secondary sources included SAMR strain registration filings, FSSAI manufacturing facility audit records, APVMA biosecurity protocol documentation, and customs trade data tracking inoculant and organic acid preservative flows. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Forecast inputs span product type segmentation across inoculants, enzymes, sorbates, and acids; application segmentation across corn silage, grass silage, whole crop, and legume systems; delivery mode differentiation between liquid, dry, powder, and granular forms; and end-user concentration across dairy farms, feedlots, and agricultural producers. CAGRs were derived from trend extrapolation calibrated to regulatory approval timeline acceleration and tropical dairy corridor expansion patterns across the projection horizon. Industry-specific forecast inputs include mechanization penetration rates in Vietnamese harvest operations and FSSAI mycotoxin threshold enforcement intensity in Indian commercial farm procurement.
Practitioners should monitor SAMR strain approval velocity, propionic acid feedstock pricing volatility, and cross-border equivalence agreement negotiations for early signals of forecast revision. The analysis reflects assumptions regarding continued intensive dairy corridor expansion and sustained regulatory tightening across national feed safety frameworks. Macroeconomic deviation in crude oil derivatives, unanticipated regulatory harmonization failure, or breakthrough precision fermentation monitoring adoption would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Metal Scavenging Agents Market
Additives
Sodium Citrate Anhydrous Market
Additives
Citric Acid Market
Additives
Foundry Additives Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
Glycol Acetate Market
Additives
Biosaccharide Gum Market
Additives
Caustic Sulphite Caramel Market
Additives
Choline Chloride Market
Additives
Anti Crystallizing Agents Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Microcrystalline Cellulose (MCC) Market
Additives
Disodium Guanylate Market
Additives
Defoaming Coating Additives Market
Additives
Lecithin and Phospholipids Market
Additives
Octane Improver Fuel Additives Market