
 Global UV Absorbers Market | 2026-2036
Global UV Absorbers Market Size, Share, and Industry Trends Forecast 2026-2036
Global UV Absorbers Market Outlook
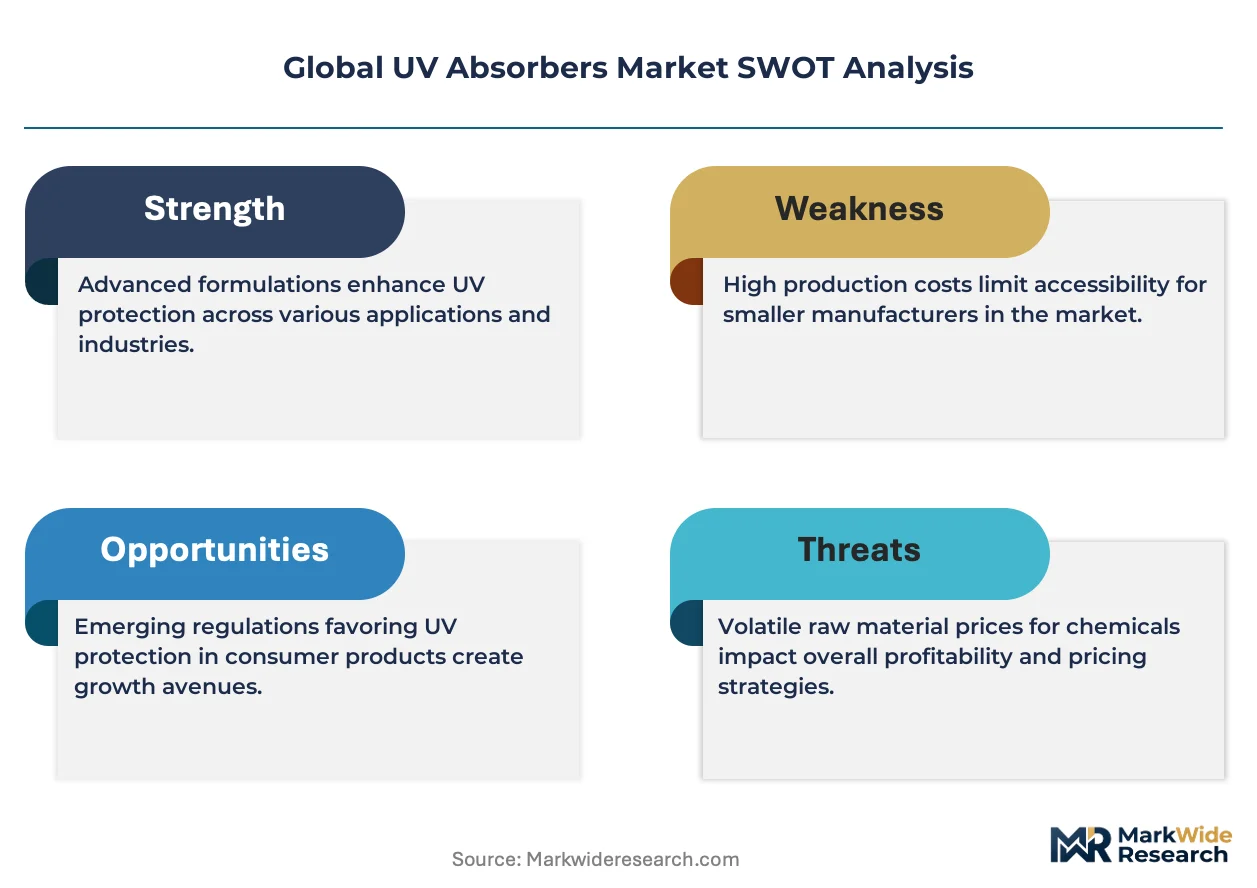
Pharmaceutical-grade specification upgrades is redrawing competitive boundaries in UV absorbers. BASF SE leverages its integrated antioxidant-UV stabilizer portfolio to sustain premium positioning across European personal care supply chains. Songwon Industrial Group anchors volume production through backward integration into phenolic intermediates in South Korea.
UV absorbers are organic compounds, typically benzotriazoles, benzophenones, or triazines, that selectively absorb ultraviolet radiation in the 280–400 nm range and dissipate energy as heat to prevent photodegradation of substrates. Triazines now lead growth in plastics and coatings applications due to superior thermal stability and low volatility under processing temperatures exceeding 300°C. Benzophenones retain dominant share in mass-market cosmetic formulations where cost sensitivity outweighs performance premiums.
REACH registration requirements in Europe, EPA chemical substance evaluations in the United States, and China's MEE environmental compliance protocols are collectively elevating purity documentation burdens and restricting market access for non-compliant suppliers. EMA and FDA guidance on photostability testing for pharmaceutical packaging further tightens specification windows for UV absorber grades destined for drug-contact applications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation reformulation costs and supply chain disqualification.
Market Dynamics
REACH registration deadlines and China's GB cosmetic safety standards are compressing supplier qualification timelines while concentrating procurement among certified manufacturers with documented purity chains.
Growth Catalysts
- High-SPF formulation demand:Personal care manufacturers across Asia-Pacific are expanding triazine-class UV absorber procurement for sun care products requiring thermal stability above 300°C processing thresholds.
- REACH compliance deadlines:European ECHA registration requirements are disqualifying uncertified suppliers and consolidating market access among documented producers with full substance dossiers.
- Pharmaceutical packaging specifications:EMA and FDA photostability testing mandates for drug-contact materials are creating qualified demand for pharmaceutical-grade UV absorber grades with narrow specification windows.
Market Restraints
- Phenolic intermediate cost volatility:Backward-integrated producers in South Korea and Germany maintain cost advantages against non-integrated competitors exposed to spot phenol markets.
- Supply concentration in China's coastal clusters:Zhejiang and Jiangsu provinces control bulk benzophenone capacity, creating geographic single-point vulnerability for mass-market cosmetic formulations.
- Substitution by inorganic mineral blockers:Zinc oxide and titanium dioxide nanoparticles are capturing share in natural-positioned cosmetic segments where organic UV absorbers face consumer perception headwinds.
Strategic Opportunities
- Underpenetrated Indian personal care market:BIS certification alignment with international cosmetic safety standards is opening formal channels for imported UV absorber grades into domestic sunscreen manufacturing.
- Regulatory tailwind from EU Green Deal:Biodegradability requirements for rinse-off cosmetics are creating preference for specific triazine derivatives with demonstrated aquatic toxicity profiles.
- Technology convergence with antioxidant stabilizers:Combined UV absorber-antioxidant masterbatches are capturing specification wins in automotive interior plastics requiring dual protection against photodegradation and thermal oxidation.
Industry Challenges
- Photostability testing protocol complexity:Divergent EMA, FDA, and NMPA guidance on pharmaceutical packaging validation is forcing suppliers to maintain multiple analytical method certifications.
- Process analytical technology capex requirements:Real-time purity monitoring systems for continuous manufacturing are demanding capital deployment that mid-scale producers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global UV Absorbers Market |
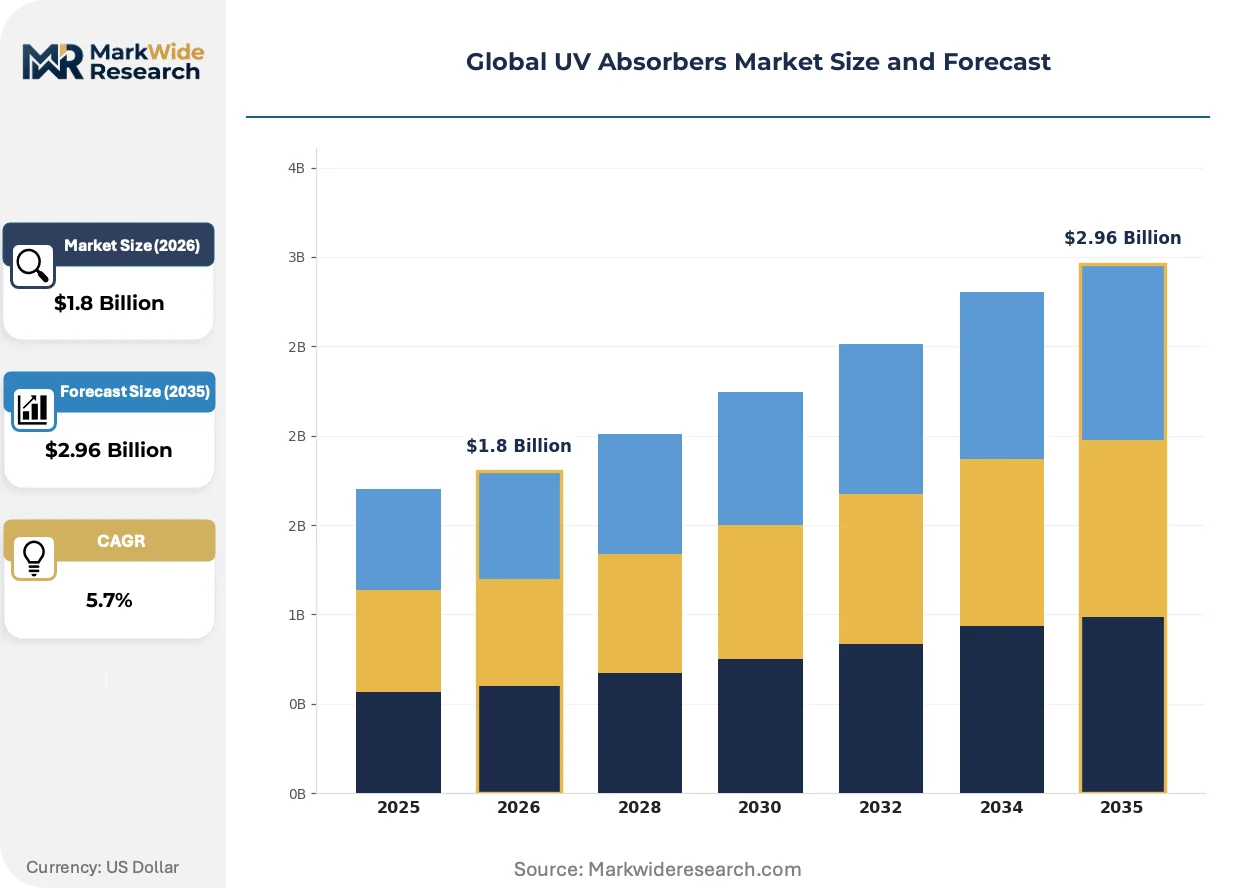
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homosulfone, Benzophenones, Triazines, Salicylates Application: Plastics, Coatings, Cosmetics, Textiles End User: Construction, Automotive, Pharmaceuticals, Personal Care Distribution Channel: Online, Direct Sales, Wholesalers, Retail |
| Companies Covered | BASF SE, Songwon Industrial Group, Clariant AG, Syensqo SA, Adeka Corporation, Everlight Chemical Industrial Co., SABO S.p.A., Rianlon Corporation, BYK-Chemie GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global UV Absorbers Market Strategic Shifts
Formulation science is pivoting toward hybrid protection systems that combine organic UV absorbers with mineral blockers, while regulatory pressure on aquatic toxicity is filtering molecule selection at the R&D stage.
Triazine-class UV absorbers are miniaturizing into high-performance cosmetic serums and clear-finish sunscreens where transparency and non-greasy aesthetics command formulation priority. Premium personal care brands in Japan and South Korea are specifying these molecules for cushion compact and essence formulations. The technology is miniaturizing particle dispersion requirements and compressing the addressable market for older benzotriazole alternatives in prestige segments.
China's MEE environmental compliance protocols are tightening wastewater discharge standards for phenolic intermediate production, forcing coastal manufacturers to upgrade treatment infrastructure or exit. This regulatory friction is elevating production costs for benzophenone derivatives disproportionately. Domestic suppliers are responding by accelerating migration toward triazine chemistry with cleaner synthesis profiles.
Direct specification relationships between personal care brands and UV absorber producers are displacing traditional distributor channels for qualified pharmaceutical and cosmetic grades. Large sunscreen manufacturers in Germany and France are building technical partnerships with certified suppliers for co-development of proprietary formulations. This channel restructuring is most visible in European markets where REACH documentation transparency enables direct audit and qualification workflows.
Global UV Absorbers Market Segmentation
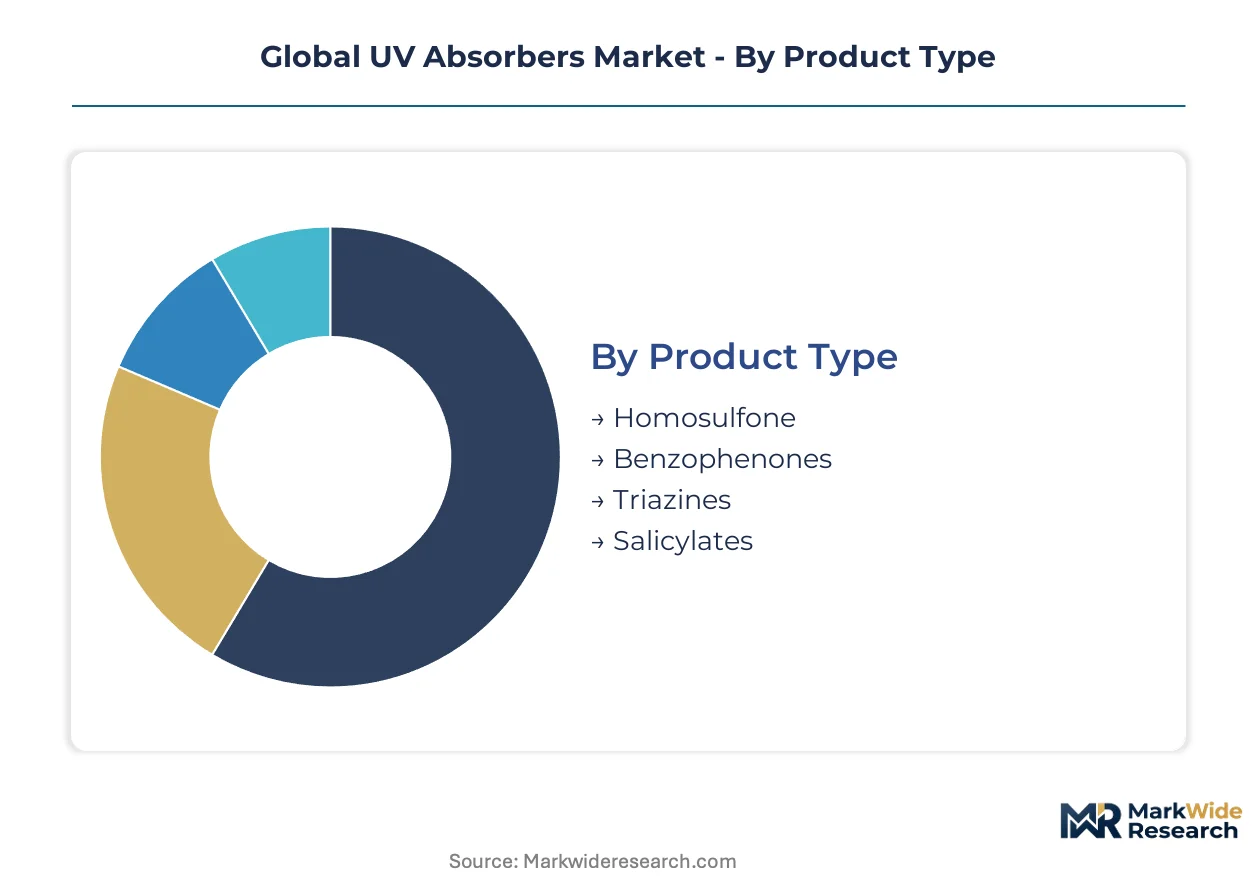
Segmentation in UV absorbers reveals divergent supply chain configurations across chemistry classes and end-use specifications. Product type determines manufacturing geography, while application segments impose distinct purity and regulatory documentation burdens.
Product Type:
Domestic production clusters in Germany and South Korea serve regional pharmaceutical and automotive demand, while China's coastal manufacturers dominate export volumes for mass-market cosmetic and plastics applications.
- Benzophenones:These aromatic ketones absorb UV-B and UV-A radiation through excited-state proton transfer mechanisms. Demand concentrates in China's Zhejiang and Jiangsu provinces for cost-sensitive cosmetic formulations, though REACH documentation gaps are disqualifying uncertified exporters from European personal care supply chains.
- Triazines:Heterocyclic compounds with superior thermal stability above 300°C and minimal volatility under extrusion conditions. Japanese and South Korean personal care manufacturers specify these molecules for high-SPF cushion compacts and clear-finish serums where transparency aesthetics command premium positioning.
- Homosulfone:Specialized sulfone derivative with narrow application in pharmaceutical packaging photostability compliance.
- Salicylates:Ester-based UV-B absorbers common in mass-market sunscreen formulations with lower thermal stability requirements.
Benzophenones command the established base. The steepest expansion runs through triazines.
Application:
Cost tier stratification separates specification-grade pharmaceutical and automotive applications from commodity cosmetics and construction coatings.
- Cosmetics:Formulation-grade absorbers must demonstrate photostability under ICH Q1B guidelines and aquatic toxicity profiles for EU Green Deal biodegradability compliance. Direct technical partnerships between certified producers and German sunscreen manufacturers are displacing traditional distributor channels.
- Plastics:Processing temperatures exceeding 300°C in automotive interior and exterior components demand triazine-class thermal stability. Combined UV absorber-antioxidant masterbatches are capturing specification wins for dual protection against photodegradation and thermal oxidation.
- Coatings:Architectural and industrial protective layers requiring solvent compatibility and migration resistance.
- Textiles:Functional fabric treatments for outdoor apparel with wash durability specifications.
Cosmetics maintains volume leadership. Plastics applications are climbing the fastest on automotive interior specification upgrades.
End User:
Customer type determines procurement channel structure, with pharmaceutical and personal care segments demanding direct supplier qualification while construction and automotive flow through formulated systems distributors.
- Personal Care:Sunscreen and daily skincare manufacturers in Japan, South Korea, and Germany specify pharmaceutical-grade purity with full REACH substance dossiers. EMA and FDA photostability testing mandates for drug-contact packaging materials are narrowing qualified supplier pools.
- Pharmaceuticals:Drug-contact packaging applications require dedicated analytical method certifications under divergent EMA, FDA, and NMPA guidance protocols, forcing suppliers to maintain multiple validation frameworks.
- Automotive:Tier-1 interior component suppliers specifying combined thermal-UV stabilization systems.
- Construction:Exterior coatings and glazing interlayers with cost-optimized benzophenone formulations.
Personal Care anchors current procurement volumes. Pharmaceutical packaging requirements are gaining share fastest on regulatory tightening.
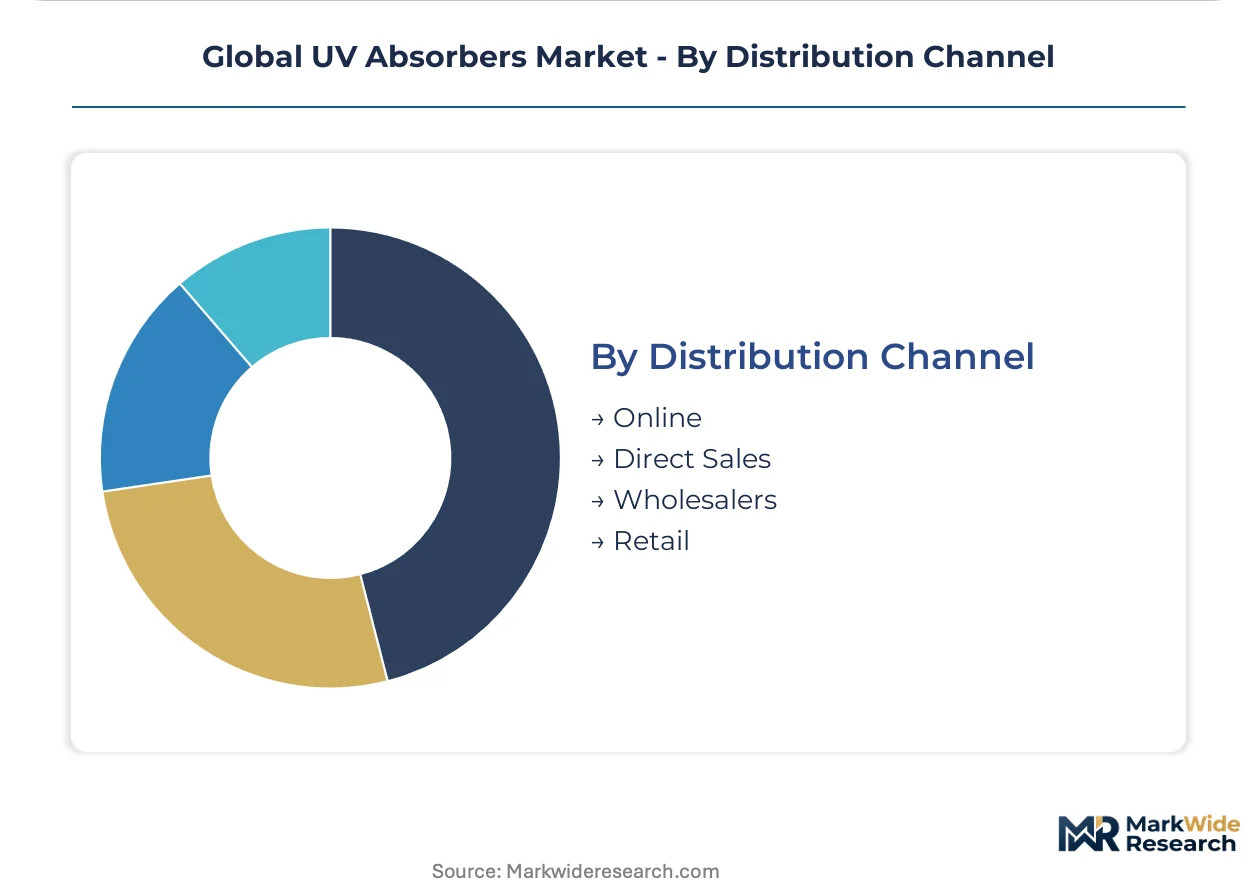
Distribution Channel:
Channel selection correlates with end-user scale and documentation intensity, with qualified grades consolidating toward direct relationships while commodity volumes persist through wholesale networks.
- Direct Sales:Technical partnership models dominate pharmaceutical-grade and qualified cosmetic segments, enabling co-development of proprietary formulations with full audit transparency. Large European sunscreen manufacturers are building dedicated supply relationships with certified producers.
- Wholesalers:Bulk benzophenone derivatives for mass-market cosmetics and construction coatings flow through regional chemical distributors in China and India.
- Online:Sample procurement and small-volume technical grades for R&D formulation development.
- Retail:Limited channel for consumer-facing sunscreen end-products rather than raw absorber materials.
Wholesalers retain volume throughput. Direct sales channels are expanding most quickly on qualification documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal chemical manufacturing clusters in Zhejiang and Jiangsu provinces control bulk benzophenone capacity, while Germany and South Korea anchor regional supply for pharmaceutical-grade specifications. REACH compliance in Europe and China's GB standards are tightening purity thresholds and compressing supplier qualification timelines.
China
Personal care manufacturers in Shanghai and Guangdong are expanding triazine-class UV absorber procurement for high-SPF cushion compact formulations. China's MEE environmental compliance protocols are tightening wastewater discharge standards for phenolic intermediate production in Zhejiang province. Coastal manufacturers in Jiangsu are upgrading treatment infrastructure or accelerating migration toward triazine chemistry with cleaner synthesis profiles.
Germany
Large sunscreen manufacturers in Germany are building direct technical partnerships with certified suppliers for co-development of proprietary formulations. ECHA registration requirements under REACH are disqualifying uncertified suppliers and consolidating market access among documented producers. BASF SE leverages its integrated antioxidant-UV stabilizer portfolio to sustain premium positioning across European personal care supply chains.
South Korea
Premium personal care brands in Seoul are specifying triazine molecules for essence formulations where transparency aesthetics command priority. MFDS cosmetic safety standards align with international protocols, opening formal channels for domestic UV absorber grades. Songwon Industrial Group anchors volume production through backward integration into phenolic intermediates in the country's chemical manufacturing belt.
United States
EMA and FDA photostability testing mandates for drug-contact packaging materials are narrowing qualified supplier pools for pharmaceutical-grade grades. EPA chemical substance evaluations are elevating purity documentation burdens and restricting market access for non-compliant suppliers. Formulation-grade procurement concentrates among certified manufacturers with documented purity chains serving the Northeast pharmaceutical corridor.
India
BIS certification alignment with international cosmetic safety standards is opening formal channels for imported UV absorber grades into domestic sunscreen manufacturing. The underpenetrated personal care market presents procurement expansion opportunities for triazine-class molecules. Mumbai and Gujarat-based formulators are qualifying new supply relationships as regulatory frameworks mature.
Global UV Absorbers Market Competitive Environment
Concentration sits with diversified chemical conglomerates and specialized stabilizer producers. The market structure reflects tiered capabilities across integrated multinational suppliers and regional specialists. Three archetypes dominate: backward-integrated phenolic intermediate producers, diversified additive portfolio suppliers, and focused UV stabilizer specialists. Competitive moves center on REACH dossier completion and direct technical partnerships with personal care formulators.
Within the integrated chemical conglomerate tier, BASF SE and Clariant AG exemplify diversified positioning across antioxidant-UV stabilizer combinations. Songwon Industrial Group anchors the Asia-Pacific supply base through captive phenolic intermediate production. Among specialized stabilizer producers, Adeka Corporation and Everlight Chemical Industrial Co. occupy positions serving high-specification personal care and electronics applications. SABO S.p.A. and BYK-Chemie GmbH represent European specialists with formulated systems capabilities. Rianlon Corporation and Syensqo SA sit within the emerging competitive set addressing pharmaceutical-grade qualification requirements.
| Leading Market Players |
|---|
| BASF SE |
| Songwon Industrial Group |
| Clariant AG |
| Syensqo SA |
| Adeka Corporation |
| Everlight Chemical Industrial Co. |
| SABO S.p.A. |
| Rianlon Corporation |
| BYK-Chemie GmbH |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization rates above 85 percent in China's Zhejiang and Jiangsu phenolic intermediate clusters compress marginal cost curves for benzophenone derivatives, anchoring global price floors while REACH compliance costs in Europe sustain premium spreads for certified grades.
Pricing Analysis
REACH registration dictates the pricing tier structure across European supply chains, forcing three-tier pricing stratification across pharmaceutical-grade, cosmetic-grade, and industrial-grade certification levels. Price differentiation hinges on ECHA dossier completeness and photostability testing protocol coverage, with German and French personal care manufacturers showing lowest sensitivity due to formulation co-development partnerships. Cost compression in mass-market benzophenone tiers intensifies as China's MEE wastewater standards elevate phenolic intermediate production costs. Spot-market buyers in Indian and Southeast Asian cosmetic manufacturing exhibit highest price sensitivity, prioritizing volume scale over thermal stability specifications.
Supply Chain Analysis
Phenolic intermediate production in China's coastal chemical manufacturing belt underwrites global benzophenone supply, with Zhejiang and Jiangsu provinces feeding mass-market cosmetic and plastics applications. Raw material flows draw from captive phenol crackers in South Korea and Germany, where Songwon and BASF maintain backward-integrated cost positions. Single-source vulnerability concentrates in triazine-class molecule synthesis, with Japanese and South Korean personal care brands relying on limited qualified suppliers for high-SPF essence formulations. Distribution runs through direct technical partnerships for pharmaceutical and premium cosmetic grades, while regional chemical wholesalers handle commodity benzophenone volumes across India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV absorber procurement cycles track personal care formulation refresh rates and automotive interior specification upgrades, positioning the market for cyclical recovery as Asia-Pacific sunscreen demand rebounds and European REACH enforcement tightens supplier pools.
For Market Incumbents: Shield premium positioning by completing ECHA substance dossiers ahead of registration deadlines and deepening backward integration into phenolic intermediates to offset MEE compliance cost inflation in China. BASF's integrated antioxidant-UV stabilizer portfolio demonstrates how certification anchoring defends margin structure against commodity benzophenone substitution. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade qualification capabilities to capture EMA and FDA photostability testing mandates narrowing qualified supplier pools for drug-contact packaging. Target India's underpenetrated personal care market through BIS certification alignment, leveraging technical partnership models that bypass established distributor channels serving commodity cosmetic tiers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated specialists with captive phenolic intermediate supply and documented REACH compliance, as regulatory documentation burdens consolidate market access among certified producers. The signal to watch is divergence between EMA, FDA, and NMPA photostability testing protocols, which would force multi-certification capital deployment and disqualify single-market qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Completion | ECHA registration secures European market access against uncertified competitors. |
| Backward Integration into Phenolic Intermediates | Captive phenol supply hedges MEE wastewater cost inflation in China. |
| Triazine Chemistry Migration | Cleaner synthesis profiles align with EU Green Deal biodegradability mandates. |
| Direct Technical Partnerships | Co-development models with German sunscreen manufacturers displace distributor channels. |
| Pharmaceutical-Grade Qualification | FDA and EMA photostability certifications open drug-contact packaging applications. |
Study Parameters
A spread of perspectives from plant managers at Chinese coastal chemical manufacturers, procurement leads at European personal care OEMs, distribution channel partners in India, and technical R&D directors at stabilizer specialists converged on the working assumptions. These primary insights combined with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and ECHA registration databases. Bottom-up capacity and utilization estimates triangulated against top-down consumption projections across the analysis window.
Segmentation dimensions modeled include chemistry class, application grade tier, end-use industry, and regional production hub. CAGRs were derived from demand elasticity analysis against personal care formulation refresh cycles and automotive interior specification upgrade timelines. The forecast framework incorporates phenolic intermediate cost trajectories, REACH registration progression curves, and triazine-class substitution rates in high-SPF cosmetic applications throughout the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity or accelerated MEE environmental compliance timelines would require recalibration. Forecasts reflect assumptions on regulatory divergence between EMA, FDA, and NMPA protocols and substitution elasticity of mineral blockers in natural-positioned cosmetic segments. Practitioners should keep alternative scenarios live as phenolic intermediate cost volatility and triazine synthesis capacity expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Americas Coating Additives Market
Additives
Printing Ink Additives Market
Additives
Global Caprylhydroxamic Acid Market
Additives
Global Polyurethane Additives Market
Additives
Pectin Market
Additives
Feed Additive Nosiheptide Premix Market
Additives
Asia-Pacific Water Enhancer Market
Additives
Antimicrobial Ingredients Market
Additives
Micronized Powder Market
Additives
Additives for Metalworking Fluids Market
Additives
Texture Modifier Market
Additives
China Sodium Reduction Ingredient Market
Additives
South America Sodium Reduction Agents Market
Additives
Encapsulated Citric Acid Market
Additives
Lubricant Additives Market
Additives
Cement Grinding Aid and Performance Enhancers Market