
 Sorbitan Oleate Market | 2026-2036
Sorbitan Oleate Market Size, Share, and Industry Trends Forecast 2026-2036
Sorbitan Oleate Market Analytics
Buyer concentration among cosmetic manufacturers is expanding as mid-tier personal care brands consolidate supplier rosters toward fewer, qualified emulsifier vendors. BASF leverages its integrated oleochemical feedstock network to secure cost-advantaged sorbitan oleate supply across European and Asian manufacturing sites. Croda International Plc anchors its position through specialty-grade emulsifier portfolios targeting premium skin-care applications. Protameen Chemicals differentiates via regional distribution density and responsive technical service for North American compounders.
Sorbitan oleate is a non-ionic surfactant synthesized through the esterification of sorbitan with oleic acid, yielding a lipophilic emulsifier with an HLB value near 4.3 that stabilizes water-in-oil dispersions across food, cosmetic, and pharmaceutical matrices. The compound functions primarily as a co-emulsifier and dispersing agent where oil-continuous phases require controlled viscosity and extended shelf stability. Emulsifiers command the deepest margin pools within product type segments due to formulation-critical performance requirements and customer stickiness in validated processes. Personal care applications outpace food industry demand growth as clean-label and naturally derived positioning drives reformulation cycles among cosmetic manufacturers. Direct sales channels dominate volume for pharmaceutical companies and agrochemical firms where technical specification alignment and audit trails outweigh spot-market procurement.
REACH registration mandates through ECHA govern sorbitan oleate import and manufacture across Europe, enforcing comprehensive toxicological dossiers that elevate compliance costs for non-integrated suppliers. FDA food additive regulations under CFR 21 establish purity thresholds for sorbitan oleate in edible applications, while EPA frameworks influence agricultural chemical adjuvant classifications in the United States. ISO standards for non-ionic surfactant analytical methods provide cross-border quality benchmarks that facilitate trade but require ongoing laboratory certification investments. Stakeholders must monitor regulatory divergence between regional purity standards and emerging biobased certification schemes to align product development with diverging compliance pathways.
Market Dynamics
Personal care formulators are consolidating supplier rosters toward fewer qualified emulsifier vendors, concentrating purchasing power and compressing margins for non-specialized producers.
Growth Catalysts
- Clean-label cosmetic reformulation:Mid-tier personal care brands are replacing synthetic surfactants with sorbitan oleate in water-in-oil emulsion systems.
- REACH registration compliance:ECHA mandates enforce comprehensive toxicological dossiers that favor established European manufacturers with integrated oleochemical networks.
- Pharmaceutical grade demand:FDA purity thresholds under CFR 21 for food-grade surfactants are elevating quality benchmarks across North American supply chains.
Market Restraints
- Oleic acid feedstock volatility:Crude palm oil and tallow price swings directly compress sorbitan oleate production economics for non-integrated compounders.
- Supplier concentration in China:Domestic cosmetic and pharmaceutical ingredient sourcing is consolidating around state-backed chemical conglomerates with captive sorbitol supply.
- Biobased surfactant substitution:Alkyl polyglucosides and sucrose esters are displacing sorbitan oleate in premium natural-positioned personal care lines.
Strategic Opportunities
- Underpenetrated Indian pharmaceutical sector:CDSCO registration pathways for excipient-grade emulsifiers remain underutilized by foreign suppliers.
- EU Green Deal biobased certification:Emerging sustainability labeling schemes create premium positioning for mass-balance certified sorbitan oleate.
- Direct technical service models:Responsive formulation support for North American compounders bypasses distributor markups and locks in multi-year supply agreements.
Industry Challenges
- REACH dossier maintenance costs:ECHA requires ongoing laboratory certification investments for toxicological data updates that strain mid-cap supplier resources.
- ISO analytical method harmonization:Cross-border quality benchmarks for non-ionic surfactant testing create compliance friction between European and Asian manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sorbitan Oleate Market |
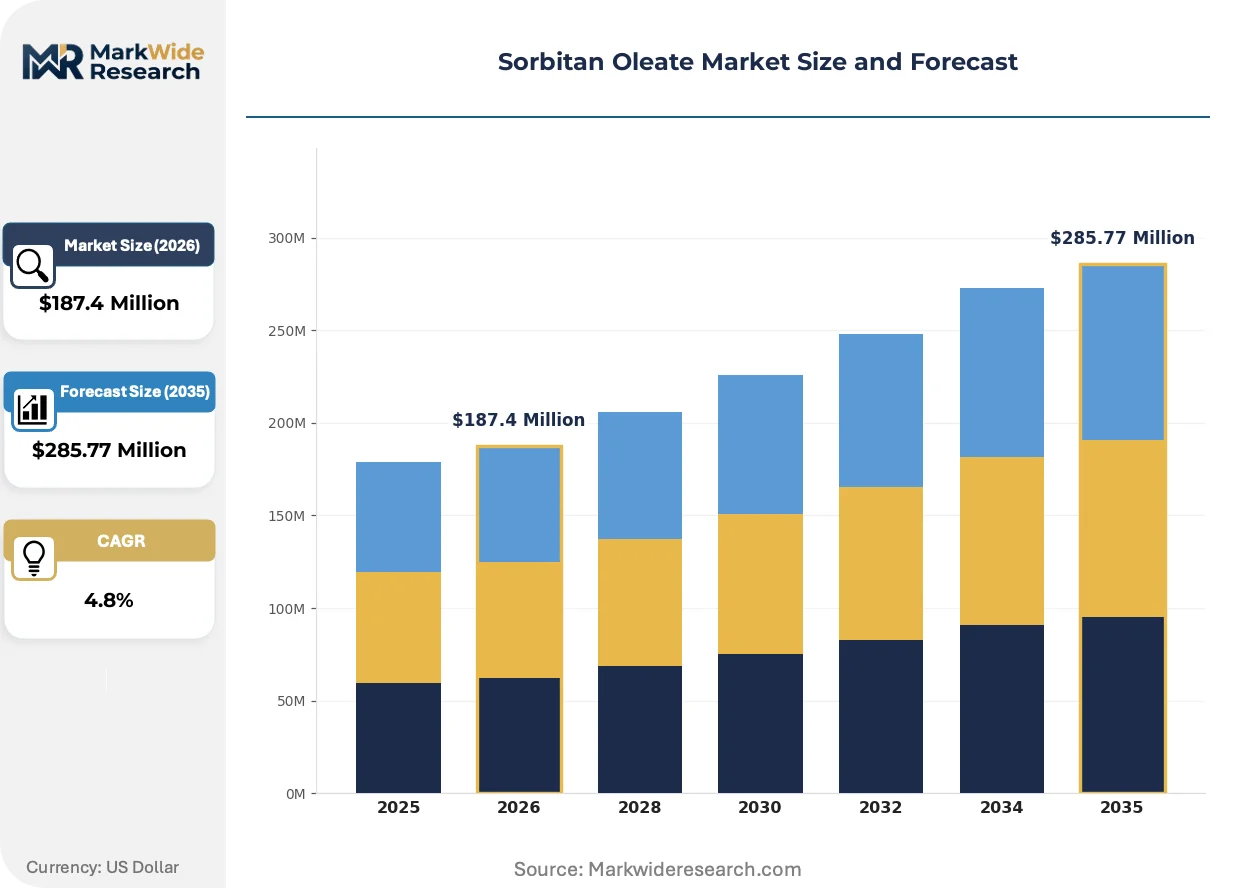
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-ionic Surfactants, Emulsifiers, Stabilizers, Thickening Agents Application: Food Industry, Personal Care, Pharmaceuticals, Agricultural Chemicals End User: Cosmetic Manufacturers, Food Processors, Pharmaceutical Companies, Agrochemical Firms Sales Channel: Direct Sales, Distributors, Online Retail, Specialty Stores |
| Companies Covered | Kao Chemicals, Protameen Chemicals, BASF, Zschimmer and Schwarz, The Herbarie, Croda International Plc, Taiwan Surfactant, ErcaWilmar, Vantage Specialty Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sorbitan Oleate Market Evolving Landscape
Enzymatic esterification processes are displacing conventional acid-catalyzed production, lowering energy intensity while enabling tighter HLB value control for specialty emulsifier grades.
Biocatalytic synthesis routes using immobilized lipase enzymes are expanding into commercial-scale sorbitan oleate manufacturing. European oleochemical producers are retrofitting batch reactors with continuous enzymatic systems to serve cosmetic manufacturers demanding batch-to-batch consistency. This technology is expanding into premium skin-care applications where HLB precision determines formulation stability.
REACH registration mandates through ECHA are tightening purity specifications for imported sorbitan oleate into European cosmetic and pharmaceutical supply chains. Comprehensive toxicological dossiers now require substance identity testing down to 0.1% impurity thresholds. Personal care compounders with validated European suppliers are locking in three-to-five-year supply agreements to avoid requalification costs.
Buyer concentration among mid-tier personal care brands is compressing procurement cycles and demanding unbundled technical service from emulsifier vendors. Spot-market procurement is giving way to direct manufacturer relationships where formulation alignment and audit trails outweigh price competition. This pattern is most visible in North American cosmetic manufacturing clusters where qualified supplier lists have shrunk by half over the past qualification cycle.
Sorbitan Oleate Market Segmentation
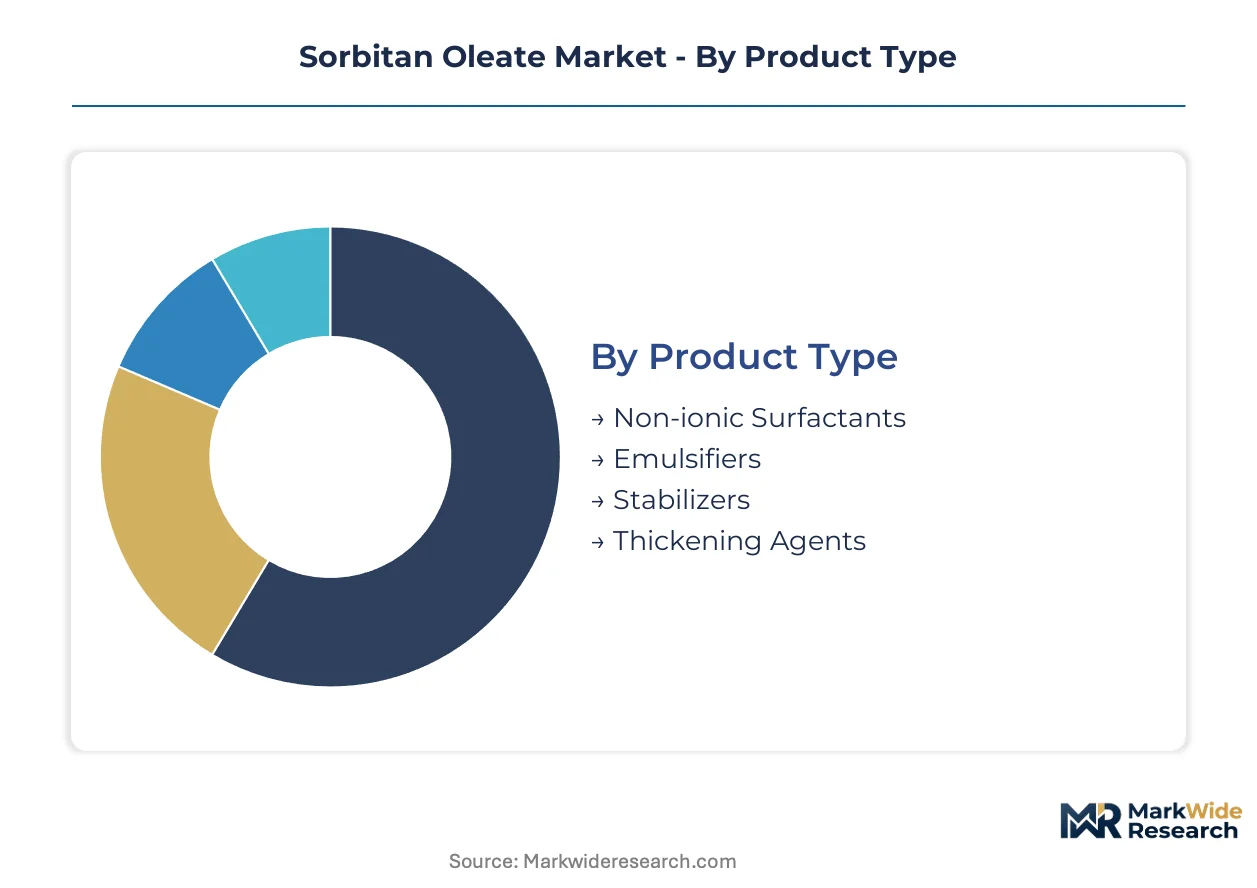
Sorbitan oleate performance varies sharply across grade specifications and end-use requirements, forcing suppliers to maintain parallel production lines for pharmaceutical purity versus industrial emulsifier grades. Segmentation discipline separates margin-accretive specialty positions from commodity surfactant competition.
Product Type:
Standardization dominates high-volume surfactant grades while specialty emulsifier variants command customization premiums for validated pharmaceutical processes.
- Non-ionic Surfactants:Hydrophobic-lipophilic balance values near 4.3 define water-in-oil emulsion stability for food-grade and cosmetic applications. Demand concentrates in European personal care compounders reformulating away from ethoxylated alternatives under ECHA scrutiny.
- Emulsifiers:Lipophilic ester functionality stabilizes dispersed-phase systems across prolonged shelf-life requirements. Pharmaceutical manufacturers in Germany and Switzerland specify sub-0.1% impurity thresholds for parenteral-grade formulations.
- Stabilizers:Viscosity control in oil-continuous matrices serves processed food manufacturers.
- Thickening Agents:Rheology modification supports topical dermatological preparations.
Leading the category by volume: Non-ionic Surfactants. Growing fastest: Emulsifiers.
Application:
Cost tier stratification separates premium pharmaceutical positioning from price-sensitive agricultural adjuvant markets.
- Personal Care:Clean-label positioning drives replacement of synthetic ethoxylates in water-in-oil skin creams and sun care formulations. Mid-tier cosmetic brands in France and Italy consolidate supplier rosters toward mass-balance certified sorbitan oleate with full REACH dossier transparency.
- Food Industry:CFR 21 compliance for edible surfactant purity enables beverage clouding agents and confectionery coatings. FDA inspection cycles elevate documentation burdens for imported oleochemical derivatives.
- Pharmaceuticals:Excipient-grade specifications for oral and topical drug delivery systems.
- Agricultural Chemicals:Adjuvant functionality in pesticide emulsion concentrates.
Personal Care captures the steepest expansion trajectory. Food Industry maintains the largest installed base.
End User:
Customer type determines procurement modality — direct technical service for pharmaceutical auditors versus distributor efficiency for fragmented food processors.
- Cosmetic Manufacturers:Formulation-critical performance requirements create stickiness in validated emulsifier supply relationships. North American skin-care compounders demand batch-to-batch HLB consistency for premium product lines.
- Pharmaceutical Companies:Multi-year supply agreements with audit trail documentation dominate procurement patterns.
- Food Processors:Volume-scale procurement through distributor networks.
- Agrochemical Firms:Spot-market flexibility for seasonal adjuvant formulation.
Cosmetic Manufacturers anchor volume concentration. Pharmaceutical Companies expand most quickly.
Sales Channel:
Supply concentration shapes channel selection — integrated oleochemical producers favor direct relationships while specialized distributors serve geographic fragmentation.
- Direct Sales:Technical specification alignment and regulatory audit support lock in pharmaceutical and agrochemical procurement. BASF and Croda leverage direct channels to bypass distributor markups in validated European supply chains.
- Distributors:Regional inventory positioning serves mid-tier cosmetic manufacturers.
- Online Retail:Small-batch procurement for independent formulators.
- Specialty Stores:Technical ingredient sourcing for research and development laboratories.
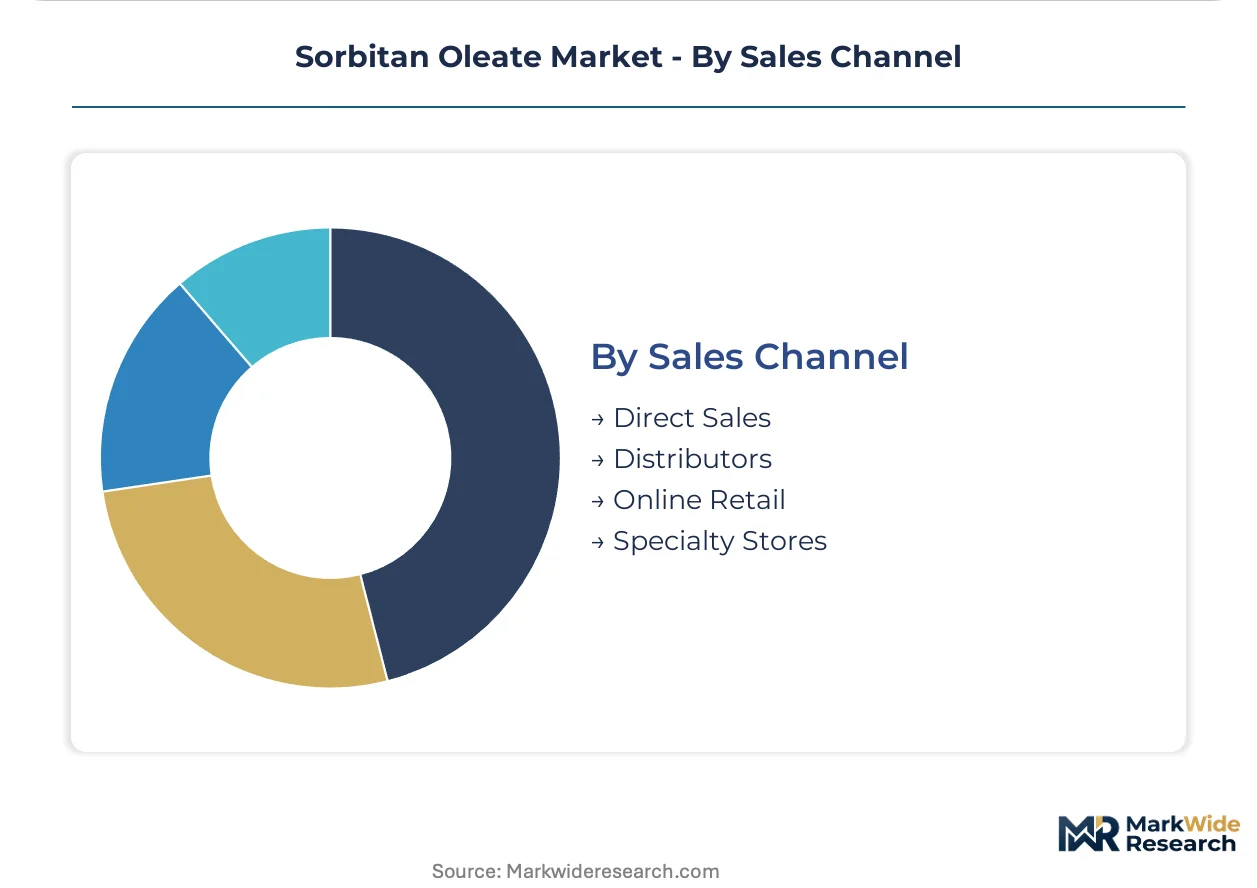
Direct Sales leads volume for regulated applications. Distributors retain relevance in fragmented regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic formulators in France and Germany are consolidating supplier rosters toward REACH-compliant emulsifier vendors, while Chinese pharmaceutical manufacturers scale domestic sorbitan oleate sourcing. This demand-side concentration is reshaping trade flows across three continents.
United States
Mid-tier skin-care brands in New Jersey and California are replacing ethoxylated surfactants with sorbitan oleate in clean-label reformulations. FDA maintains CFR 21 purity thresholds for food-grade applications that elevate documentation burdens for imported oleochemical derivatives. The New Jersey pharmaceutical corridor locks in multi-year supply agreements with audit-trail documentation for excipient-grade emulsifiers.
Germany
BASF leverages its integrated oleochemical network across Ludwigshafen to supply cost-advantaged sorbitan oleate for European cosmetic manufacturers. ECHA REACH mandates enforce comprehensive toxicological dossiers that favor established producers with captive sorbitol supply. The Rhine-Neckar chemical cluster retrofits batch reactors with continuous enzymatic systems for premium skin-care applications.
China
Domestic pharmaceutical and cosmetic ingredient sourcing is consolidating around state-backed chemical conglomerates with captive feedstock positions. NMPA registration pathways for excipient-grade emulsifiers are tightening purity benchmarks for imported alternatives. The Yangtze River Delta manufacturing belt scales enzymatic esterification capacity to serve regional formulators demanding batch-to-batch HLB consistency.
India
CDSCO registration pathways for excipient-grade emulsifiers remain underutilized by foreign suppliers, creating whitespace for qualified entrants. FSSAI food additive regulations establish purity thresholds that parallel FDA frameworks for edible surfactant applications. Maharashtra-based pharmaceutical compounders are qualifying European and Asian sorbitan oleate sources for oral and topical drug delivery systems.
Switzerland
Swissmedic pharmaceutical standards drive sub-0.1% impurity specifications for parenteral-grade sorbitan oleate used in sterile formulations. The country's precision chemical sector imports specialty emulsifier grades from integrated European producers with full REACH dossier transparency. Basel's pharmaceutical manufacturing cluster validates suppliers through three-to-five-year agreements to avoid requalification costs.
Sorbitan Oleate Market Competitive Landscape
European producers anchor one tier through integrated oleochemical networks; Asian specialists hold cost-advantaged positions in high-volume surfactant grades. The vendor base splits between consolidated multinational chemical conglomerates and regional distributors with responsive technical service capabilities. Three archetypes dominate: integrated oleochemical producers with captive feedstock, specialty emulsifier formulators targeting pharmaceutical purity tiers, and regional distributors serving fragmented cosmetic compounders. Competitive moves center on enzymatic process licensing for HLB precision and direct technical service models that bypass distributor markups in validated supply chains.
Among integrated chemical conglomerates, BASF and Croda International Plc exemplify the European archetype of backward integration into oleochemical feedstocks. Protameen Chemicals occupies a position within the North American distributor-specialist tier, representing regional density and formulation support capabilities. These three anchors illustrate the geographic and structural segmentation that defines competitive positioning across premium pharmaceutical, standard cosmetic, and economy industrial emulsifier grades.
| Leading Market Players |
|---|
| Kao Chemicals |
| Protameen Chemicals |
| BASF |
| Zschimmer and Schwarz |
| The Herbarie |
| Croda International Plc |
| Taiwan Surfactant |
| ErcaWilmar |
| Vantage Specialty Ingredients |
| Others |
Value Network & Pricing Analysis
Crude palm oil and tallow feedstock costs cascade through sorbitan oleate pricing tiers, with integrated European producers capturing margin advantage while non-integrated compounders in Asia absorb volatility. Pharmaceutical-grade specifications command premium positioning against commodity surfactant grades, with REACH dossier transparency becoming a price discriminator.
Pricing Analysis
Volume-scale surfactant grades trade on thin margins while specialty emulsifier variants capture customization premiums for validated pharmaceutical processes. Price differentiation rests on certification tier—REACH-registered versus non-registered—and volume commitment scale, with cosmetic manufacturers locking multi-year agreements. Cost compression in standard grades is intensifying as Chinese state-backed conglomerates expand captive sorbitol capacity. Food processors show highest price sensitivity; pharmaceutical compounders prioritize batch consistency over unit cost.
Supply Chain Analysis
REACH registration and FDA food-grade qualification requirements gate supplier access to premium-tier procurement channels, filtering out non-compliant producers. Manufacturing concentrates in Germany, China, and Switzerland, with feedstock dependencies on Malaysian and Indonesian palm oil derivatives plus tallow streams. Single-source vulnerability runs through oleic acid supply from Southeast Asian oleochemical complexes. Distribution runs through direct manufacturer relationships for pharmaceutical auditors and regional distributors for fragmented cosmetic compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sorbitan oleate supply is consolidating around integrated producers with captive feedstock and regulatory dossiers, as REACH maintenance costs and enzymatic process investments force sub-scale competitors toward exit.
For Market Incumbents: Acquire enzymatic esterification technology assets to secure HLB precision capabilities for premium skin-care formulations. BASF and Croda should expand backward integration into Southeast Asian oleochemical feedstock to offset palm oil volatility. Lock in three-to-five-year supply agreements with Swiss and German pharmaceutical manufacturers before requalification cycles close. For New Entrants and Emerging Players: Direct technical service platforms offer the lowest-friction route to bypass distributor markups and capture North American mid-tier cosmetic compounders. Target CDSCO registration pathways for excipient-grade emulsifiers in India, where foreign supplier penetration remains underdeveloped. Lead with responsive formulation support rather than price competition to secure initial qualification. For Investors and Strategic Acquirers: Consolidation of supplier rosters among European cosmetic manufacturers is the leading indicator that mid-cap specialty emulsifier assets will command scarcity premiums. Five-to-ten-year viability favors producers with mass-balance certification and enzymatic process scale. Monitor ECHA substance identity testing threshold adjustments as the signal for compliance-cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Licensing | Immobilized lipase systems enable HLB precision for premium cosmetic validation. |
| Backward Integration into Oleochemical Feedstock | Captive palm oil and tallow supply insulates margin from commodity volatility. |
| REACH Dossier Expansion | Full toxicological transparency unlocks European pharmaceutical procurement channels. |
| Direct Technical Service Model | Bypassing distributor markups locks multi-year agreements with North American compounders. |
| Mass-Balance Certification | EU Green Deal alignment commands premium positioning in clean-label personal care. |
Research Methodology
Document review covered ECHA registration databases, FDA CFR 21 filings, and oleochemical trade flows, complemented by interviews with European cosmetic formulators, Asian plant managers, and North American pharmaceutical procurement leads. Secondary validation drew from customs records, SEC 10-K disclosures, and ISO analytical method standards. Bottom-up segment sizing and top-down industry consensus triangulated volume and value estimates.
Cross-referencing historical capacity expansion patterns against expert panel input shaped the projection framework. Segmentation modeling spanned grade tier, end-use application, and regional regulatory cluster across the analysis window. CAGRs derived from elasticity-adjusted demand curves and feedstock cost trajectory assumptions. Forecast inputs incorporated enzymatic process adoption rates and REACH compliance cost escalations.
The model holds under stable oleochemical feedstock availability and current regulatory enforcement intensity; deviation in palm oil supply disruptions or ECHA impurity threshold tightening would shift trajectory. Forecasts reflect documented assumptions regarding cosmetic reformulation velocity and pharmaceutical qualification cycle timing. A model refresh is warranted upon material change in EU biobased certification scheme adoption or Chinese state-backed capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Antiscalants/Scale Inhibitors Market
Additives
Citrate Ester Market
Additives
Organic Friction Modifier Additives Market
Additives
Anti-Foaming Agent Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Europe Choline Chloride Market
Additives
Encapsulated Citric Acid Market
Additives
Defoaming Coating Additives Market
Additives
Guanylic Acid Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Volatile Corrosion Inhibitors Market
Additives
Americas Coating Additives Market
Additives
Potassium Nitrate Market
Additives
Amino Acids Premixes Market
Additives
Global Butyric Acid Derivatives Market
Additives
Apocarotenal Market