
 Medical Grade Zinc Sulfate Market | 2026-2036
Medical Grade Zinc Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Grade Zinc Sulfate Market Insights
Pharmaceutical parenteral nutrition is pivoting toward higher-purity zinc sulfate inputs as clinicians expand micronutrient therapy for critical care patients. Merck KGaA leverages its European pharmacopeial certification network to sustain premium positioning across hospital procurement channels. Balaji Industries anchors its competitive stance through cost-optimized bulk production serving generic injectable manufacturers in South Asia. Changsha Haolin Chemicals Co., Ltd. specializes in low-impurity crystalline grades that meet revised USP monograph specifications.
Medical grade zinc sulfate denotes a purified zinc salt meeting pharmacopeial standards for human therapeutic use, typically manufactured through controlled acid leaching of zinc oxide followed by multi-stage crystallization to achieve heavy metal limits below 10 ppm. The powder segment dominates current volume as compounding pharmacies and API manufacturers prefer dry-form flexibility for tablet compression and capsule filling, while the solution segment commands margin premiums in ready-to-use parenteral applications. Injectable delivery mode requirements are tightening impurity thresholds, pushing suppliers toward dedicated GMP lines that separate medical-grade output from agricultural or feed-grade production.
The US FDA enforces USP-NF monograph compliance for zinc sulfate used in prescription drug products, while the European EMA references Ph. Eur. standards that recently narrowed acceptable lead and cadmium specifications. India's CDSCO aligns with IP standards but accelerates local testing capacity through regional pharmacopeial laboratories, reducing import dependency for reference materials. Stakeholders must monitor evolving pharmacopeial harmonization between FDA, EMA, and ICH guidelines, as diverging heavy metal limits could fragment formulation strategies and force dual-sourcing qualification programs.
Market Dynamics
Pharmacopeial harmonization pressures are compressing supplier margins while fragmenting qualification requirements across FDA, EMA, and IP jurisdictions, forcing dedicated GMP line investments that separate medical-grade output from agricultural production.
Growth Catalysts
- EMA Heavy Metal Specification Tightening:The European regulator's narrowed lead and cadmium limits are compelling pharmaceutical manufacturers to upgrade to higher-purity zinc sulfate inputs, expanding addressable premium grade volume.
- India's Nutritional Supplementation Programs:Government-mandated micronutrient fortification initiatives are accelerating domestic API production and medical-grade consumption across public health distribution channels.
- Parenteral Nutrition Formulation Expansion:Critical care clinicians are expanding micronutrient therapy protocols, pulling crystalline zinc sulfate demand through hospital procurement systems.
Market Restraints
- Input Cost Volatility:Zinc oxide feedstock prices fluctuate with London Metal Exchange benchmarks, compressing margin predictability for crystallization-stage producers.
- Supply Concentration Risk:Bulk medical-grade production clusters in South Asian contract manufacturers, creating single-source vulnerability for European and North American formulators.
- Technical Limitation:Heavy metal reduction below 10 ppm requires multi-stage purification that extends batch cycle times and limits throughput scalability.
Strategic Opportunities
- Brazil's ANVISA Alignment:The national regulator's pharmacopeial convergence with USP standards creates qualification pathway for suppliers seeking Latin American hospital channel access.
- Ready-to-Use Parenteral Applications:Solution-form zinc sulfate commands margin premiums as compounding pharmacies outsource sterile preparation to specialized manufacturers.
- PLI Scheme Incentives:India's production-linked incentive framework for active pharmaceutical ingredients subsidizes domestic medical-grade zinc sulfate capacity expansion.
Industry Challenges
- Analytical Chemistry Skill Gap:Pharmacopeial testing for trace heavy metals requires ICP-MS expertise that concentrates in regional reference laboratories, creating certification bottlenecks.
- Capex Intensity:Dedicated GMP line construction for medical-grade separation from feed-grade output demands cleanroom infrastructure and validated equipment trains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Grade Zinc Sulfate Market |
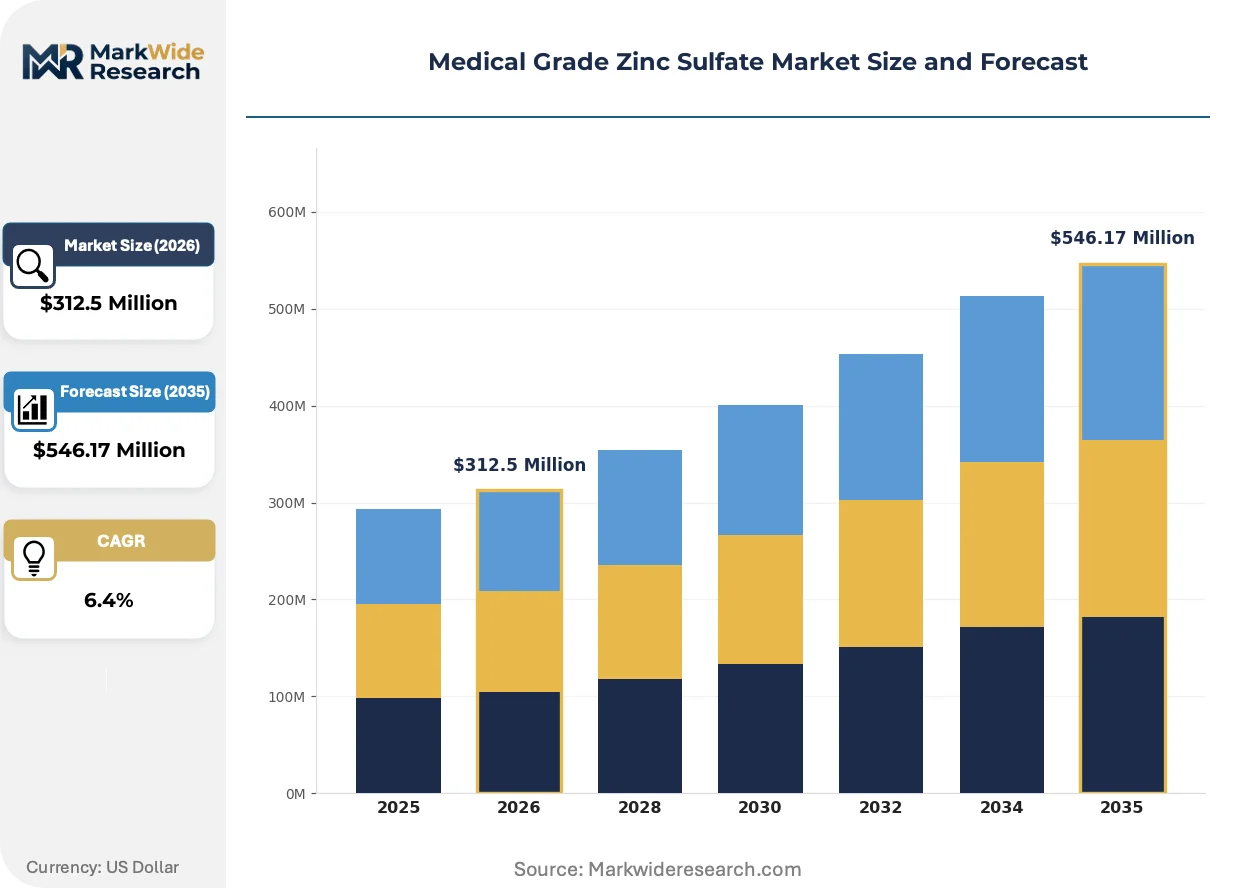
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granule, Solution, Tablet Application: Nutritional Supplement, Pharmaceutical, Agriculture, Personal Care Delivery Mode: Oral, Topical, Injectable, Infusion End User: Hospitals, Clinics, Pharmacies, Health Food Stores |
| Companies Covered | Merck KGaA, Sigma-Aldrich, Balaji Industries, Changsha Haolin Chemicals Co., Ltd., Old Bridge Chemical, Inc., Rech Chemical Co. Ltd, Tianjin Topfert Agrochemical Co., Zinc Nacional, Ravi Chem Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Grade Zinc Sulfate Market Trends and Innovations
Continuous crystallization technology and real-time release testing are compressing batch variability while pharmacopeial divergence between jurisdictions is fragmenting formulation strategies.
Continuous flow crystallization systems are integrating into zinc sulfate production trains to replace batch-wise cooling crystallization. European API manufacturers are adopting these systems to reduce solvent consumption and heavy metal carryover. The technology is integrating process analytical technology sensors that enable real-time purity verification, compressing quality control timelines from days to hours.
REACH authorization requirements for nickel catalyst residues are extending raw material qualification protocols for European zinc sulfate suppliers. The ECHA framework now demands supply chain documentation for catalytic hydrogenation precursors used in zinc oxide reduction. Injectable-grade manufacturers in Germany and Switzerland are responding by dual-qualifying Asian and domestic feedstock sources to mitigate authorization delays.
Hospital procurement consortia are consolidating micronutrient purchasing through centralized pharmacy networks, displacing traditional distributor relationships. Large academic medical centers in the United States are negotiating direct supply agreements with GMP-certified zinc sulfate manufacturers, bypassing wholesale intermediaries. This concentration is most visible in the parenteral nutrition segment, where formulary standardization across health system networks is reducing supplier fragmentation.
Medical Grade Zinc Sulfate Market Segmentation
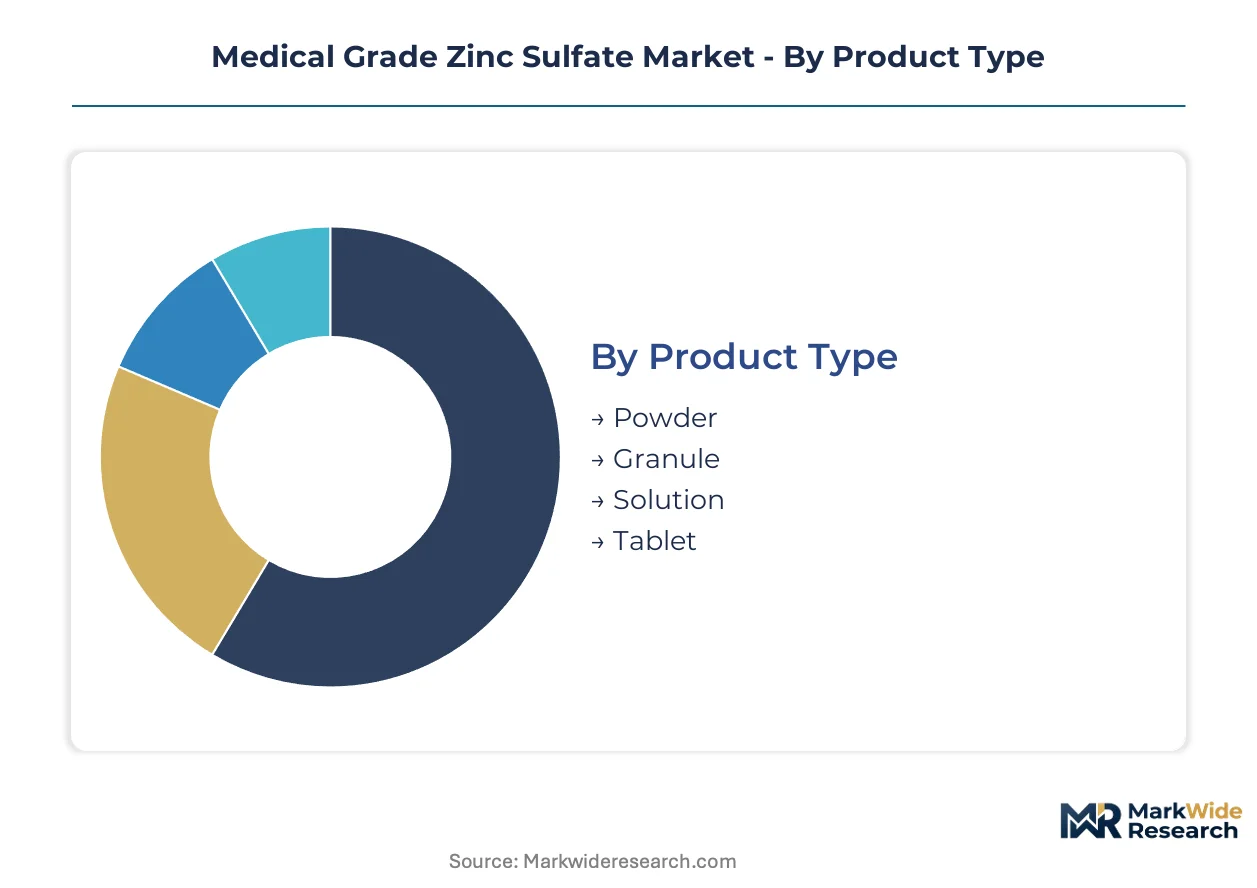
Segmentation in medical grade zinc sulfate reveals how pharmacopeial purity tiers map to distinct manufacturing investments and customer qualification requirements. Each dimension—physical form, therapeutic application, delivery route, and procurement channel—carries separate regulatory burdens and margin structures that reshape supplier competitive positioning.
Product Type:
Upgrade cycles in crystallization technology are fragmenting the product mix as European and North American formulators replace legacy powder inventories with lower-impurity alternatives.
- Powder:Crystalline heptahydrate powder remains the baseline specification for tablet compression and capsule filling at compounding pharmacies. Demand clusters in Indian API manufacturing zones where bulk procurement from Balaji Industries and Changsha Haolin Chemicals feeds generic injectable producers seeking cost-optimized pharmacopeial compliance.
- Solution:Ready-to-use sterile solutions command premium positioning through hospital pharmacy networks that outsource parenteral preparation. US academic medical centers are consolidating micronutrient purchasing through direct manufacturer agreements, bypassing wholesale distribution for this high-margin format.
- Granule:Intermediate particle size enables rapid dissolution for effervescent formulations and sachet-based nutritional interventions. CDSCO-aligned Indian manufacturers dominate bulk granule supply for government supplementation programs.
- Tablet:Direct-compression grade requires specialized flow properties and binding characteristics that narrow qualified supplier pools. European Ph. Eur. certification requirements constrain tablet-grade sourcing to GMP-certified crystallization facilities with validated heavy metal testing protocols.
Volume placements concentrate in Powder; the faster expansion belongs to Solution.
Application:
Cost tier differentiation separates commodity nutritional inputs from pharmaceutical-grade certifications that demand dedicated production lines and traceability documentation.
- Pharmaceutical:Parenteral nutrition formulations require USP-NF or Ph. Eur. certified zinc sulfate with heavy metal limits below 10 ppm, validated through ICP-MS testing. Clinicians expanding critical care micronutrient protocols are pulling crystalline demand through hospital procurement systems in Germany, Switzerland, and the United States.
- Nutritional Supplement:Oral zinc formulations for deficiency correction operate under less stringent purity thresholds, enabling multi-source procurement from Indian and Chinese manufacturers. India's government-mandated fortification initiatives are accelerating domestic API consumption across public health channels.
- Agriculture:Animal feed and fertilizer applications utilize technical-grade material excluded from medical-grade production facilities to prevent cross-contamination. This segment remains segregated from pharmaceutical supply chains under FDA and EMA GMP separation requirements.
- Personal Care:Dermatological formulations incorporate zinc sulfate for astringent and antimicrobial properties at cosmetic-grade purity levels. REACH authorization for nickel catalyst residues extends raw material qualification timelines for European personal care manufacturers.
Revenue concentration sits with Pharmaceutical; Nutritional Supplement is climbing the fastest as government programs scale.
Delivery Mode:
Customer type stratification across hospital networks, outpatient clinics, and retail channels determines packaging, sterility assurance, and documentation requirements.
- Injectable:Direct intravenous or intramuscular administration demands endotoxin-controlled, sterile-grade zinc sulfate with validated pyrogen testing. EMA's narrowed lead and cadmium specifications are compelling formulators to upgrade input purity, expanding addressable premium volume.
- Oral:Capsule, tablet, and liquid oral formulations represent the highest volume placement across pharmacy and health food store distribution. Compounding flexibility favors powder and granule inputs that enable customized dosing.
- Infusion:Large-volume parenteral bags for total parenteral nutrition require pre-mixed micronutrient solutions with extended stability data. Hospital procurement consortia are consolidating infusion-grade purchasing through centralized pharmacy networks.
- Topical:Dermatological creams and wound care preparations utilize zinc sulfate at concentrations requiring local tolerability testing rather than systemic pharmacokinetic validation.
Volume dominance rests with Oral; Infusion is gaining share fastest through health system formulary standardization.
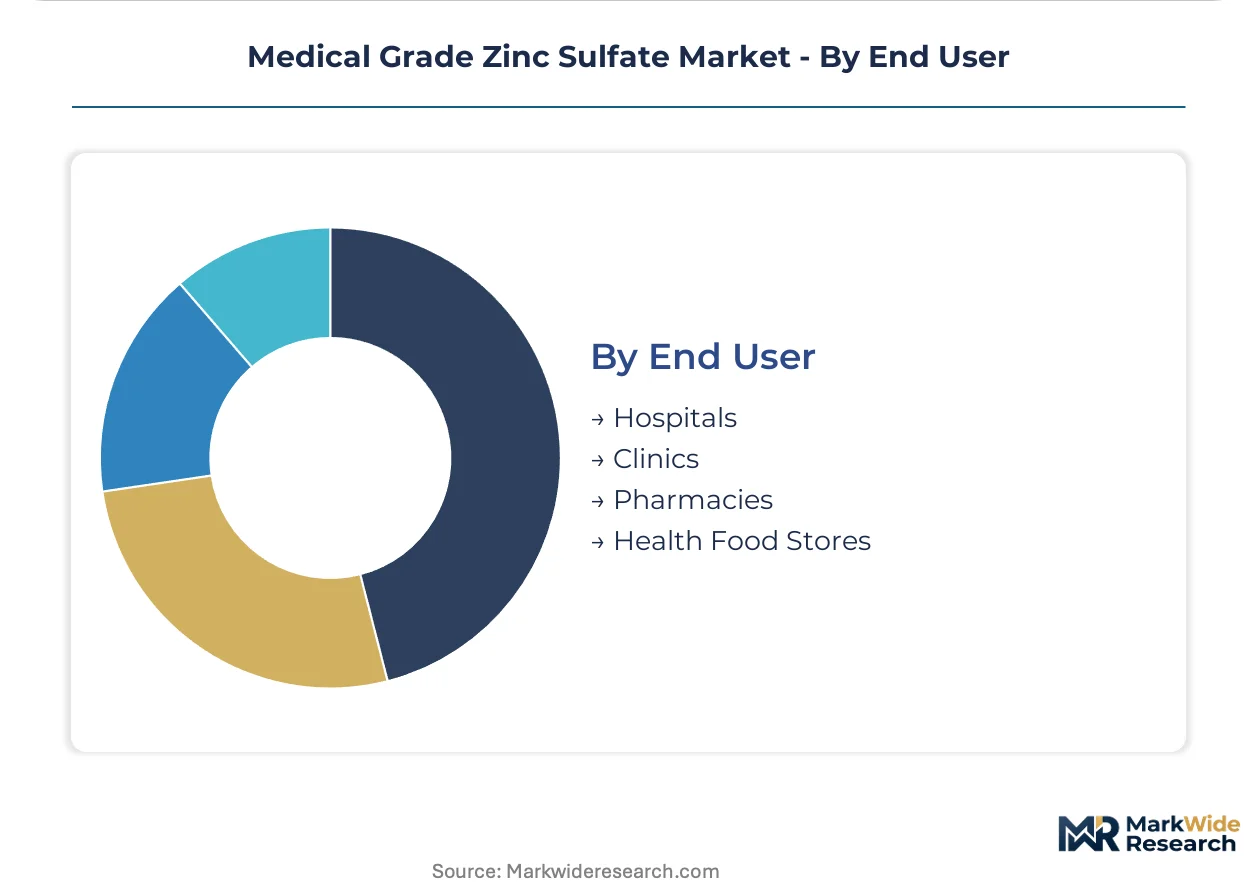
End User:
Supply concentration in South Asian contract manufacturers creates channel-specific vulnerability as European and North American formulators seek qualification diversity.
- Hospitals:Academic medical centers and health system networks negotiate direct supply agreements with GMP-certified manufacturers, displacing traditional distributor relationships. Parenteral nutrition standardization across US hospital systems is reducing supplier fragmentation.
- Pharmacies:Retail and compounding pharmacies source powder and granule formats for customized patient formulations, with USP-NF compliance enabling prescription product dispensing.
- Clinics:Outpatient infusion centers and specialty care facilities procure ready-to-use solutions under group purchasing organization contracts.
- Health Food Stores:Direct-to-consumer nutritional supplements operate outside prescription drug regulations, enabling broader supplier qualification and lower purity tier acceptance.
Procurement gravity centers on Hospitals; Pharmacies show the steepest expansion trajectory as compounding outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in South Asia while consumption concentrates in North American and European hospital networks, creating a trade-dependent structure shaped by pharmacopeial divergence and GMP certification requirements.
United States
FDA-enforced USP-NF monograph compliance drives hospital procurement of injectable-grade zinc sulfate through academic medical centers. The agency's tightened endotoxin and heavy metal specifications compel formulators to maintain dual-qualified supplier relationships. Direct manufacturer agreements in the Northeast Corridor and California health systems are displacing traditional wholesale distribution channels for parenteral nutrition inputs.
Germany
EMA pharmacopeial standards and REACH authorization requirements concentrate demand among GMP-certified crystallization facilities serving critical care micronutrient therapy. Bavarian and North Rhine-Westphalia API manufacturers are upgrading purification systems to meet narrowed lead and cadmium specifications. Hospital procurement consortia in the Frankfurt-Rhine-Main region are consolidating micronutrient purchasing through centralized pharmacy networks.
India
CDSCO-aligned IP standards and government nutritional supplementation programs accelerate domestic API production across Maharashtra and Gujarat manufacturing zones. The PLI scheme subsidizes medical-grade capacity expansion for export-qualified suppliers. Hyderabad and Mumbai clusters host bulk crystallization facilities serving generic injectable manufacturers seeking cost-optimized pharmacopeial compliance.
Switzerland
Swissmedic certification requirements and proximity to German hospital networks position the Basel-Zurich corridor as a premium-grade distribution hub. Injectable manufacturers maintain dual-qualified Asian and European feedstock sources to mitigate REACH authorization delays for nickel catalyst residues. The country's precision chemical sector specializes in low-impurity crystalline grades for parenteral applications.
Brazil
ANVISA pharmacopeial convergence with USP standards creates qualification pathways for suppliers seeking Latin American hospital channel access. São Paulo and Rio de Janeiro health systems are expanding micronutrient therapy protocols for critical care patients. Regional distributors are consolidating procurement relationships with GMP-certified manufacturers to serve outpatient infusion centers and public health networks.
Medical Grade Zinc Sulfate Market Competitive Landscape
Top-tier vendors anchor European and North American pharmacopeial certification networks, while mid-scale South Asian producers compete on cost-optimized bulk output for generic injectable manufacturers. The structure fragments across three strategic archetypes: GMP-certified crystallization specialists, multi-product chemical conglomerates with dedicated medical-grade lines, and regional bulk suppliers serving domestic fortification programs. Competitive moves concentrate on dedicated production line investments that separate medical-grade output from agricultural or feed-grade manufacturing, alongside pharmacopeial qualification expansion across FDA, EMA, and CDSCO jurisdictions.
Among European-based operators, Merck KGaA exemplifies the premium-tier archetype through its pharmacopeial certification network sustaining hospital procurement channel access. Balaji Industries and Changsha Haolin Chemicals Co., Ltd. occupy positions within the cost-optimized bulk supply tier, serving generic injectable manufacturers and compounding pharmacies across South Asian and export markets. These three entities represent the dominant geographic and strategic positioning vectors—European certification-driven, Indian scale-driven, and Chinese crystalline specialization—that define supplier competitive dynamics.
| Leading Market Players |
|---|
| Merck KGaA |
| Sigma-Aldrich |
| Balaji Industries |
| Changsha Haolin Chemicals Co., Ltd. |
| Old Bridge Chemical, Inc. |
| Rech Chemical Co. Ltd |
| Tianjin Topfert Agrochemical Co. |
| Zinc Nacional |
| Ravi Chem Industries |
| Others |
Pricing and Supply Chain Analysis
Captive GMP line investments by European crystallization specialists anchor both supply security and premium pricing power, separating medical-grade output from agricultural production through validated heavy metal testing protocols that EMA's narrowed specifications now mandate. This vertical separation creates a cost barrier that Indian bulk manufacturers exploit through scale-driven cost optimization serving generic injectable producers.
Pricing Analysis
Short lead-time premiums for USP-NF certified crystalline grades command substantial markups over standard pharmacopeial inventory as hospital procurement consortia prioritize formulary continuity over spot-price savings. Three-tier pricing structure across GMP-certified premium, standard pharmacopeial, and technical-grade economy levels reflects certification burden and batch validation documentation. Cost compression in the standard tier intensifies because South Asian producers expand crystallization capacity under India's PLI scheme. Generic injectable manufacturers in Gujarat and Maharashtra exhibit highest price sensitivity; Swiss and German critical care formulators show least sensitivity due to patient safety liability exposure.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale academic medical center demand through validated manufacturer agreements that bypass wholesale distribution for parenteral nutrition inputs. Supply concentrates in India, China, and Germany, with Hyderabad and Mumbai clusters feeding global generic injectable demand while Bavarian facilities serve European premium-grade requirements. Zinc oxide feedstock, sulfuric acid reagents, and nickel catalyst precursors constitute critical input dependencies. Single-source vulnerability pervades the structure as European formulators rely disproportionately on South Asian crystallization output. Distribution runs through hospital procurement consortia consolidating micronutrient purchasing through centralized pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EMA's narrowed lead and cadmium specifications erect a barrier-to-entry moat favoring GMP-certified crystallization specialists with validated ICP-MS testing infrastructure.
For Market Incumbents: Anchor pharmacopeial certification expansion across FDA, EMA, and CDSCO jurisdictions to sustain hospital procurement channel access against emerging Indian scale players. Defend margin position by constructing dedicated GMP lines that segregate medical-grade output from feed-grade production, eliminating cross-contamination risk that regulators increasingly scrutinize. Capacity addition in Switzerland and Germany reinforces premium positioning as REACH authorization delays disrupt Asian feedstock qualification timelines. For New Entrants and Emerging Players: E-commerce platform qualification pathways enable rapid supplier registration with hospital procurement consortia seeking secondary source diversity for parenteral nutrition inputs. Target Brazil's ANVISA-aligned hospital networks where pharmacopeial convergence with USP standards creates accessible entry points without European certification burden. Compounding pharmacy outsourcing represents the most penetrable segment, with ready-to-use sterile solutions commanding margin premiums through direct manufacturer agreements. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to pharmaceutical conglomerates seeking backward integration into critical mineral supply chains. Long-term viability hinges on regulatory certification durability rather than commodity scale, positioning GMP-certified crystallization specialists with multi-jurisdictional pharmacopeial approvals as prime acquisition targets. Monitor ICP-MS testing capacity bottlenecks at regional pharmacopeial laboratories as an inflection indicator for certification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Line Segregation | Dedicated medical-grade crystallization infrastructure prevents cross-contamination with agricultural output under FDA separation requirements. |
| Pharmacopeial Certification Expansion | Multi-jurisdictional USP-NF, Ph. Eur., and IP alignment sustains hospital procurement access across North American and European channels. |
| Backward Integration into Zinc Oxide | Captive feedstock supply from qualified smelters mitigates London Metal Exchange price volatility and REACH authorization delays. |
| Continuous Crystallization Technology Adoption | Process analytical technology integration enables real-time release testing that compresses quality control timelines from days to hours. |
| Direct Hospital Supply Agreements | Bypassing wholesale distribution captures margin premiums through academic medical center procurement consortia standardizing parenteral nutrition formularies. |
Research Methodology
Independent corroboration across primary interviews with pharmaceutical manufacturing executives, hospital procurement managers, regulatory affairs leads, and compounding pharmacy operators underwrites the qualitative findings in this study. Secondary validation draws from FDA drug master file submissions, EMA marketing authorization databases, USP-NF monograph revisions, and Indian customs export records for zinc sulfate API shipments. Bottom-up crystallization capacity estimates from Maharashtra and Gujarat manufacturing zones triangulate against top-down parenteral nutrition formulation demand projections.
Rate-of-change decomposition across the analysis window separates volume growth from price realization effects, with CAGRs derived from segmented modeling of powder, solution, granule, and tablet format trajectories. Segmentation dimensions include product type, therapeutic application across pharmaceutical and nutritional supplement tiers, delivery mode stratification between injectable and oral routes, and end-user channel concentration in hospitals versus pharmacies. Forecast inputs incorporate pharmacopeial harmonization momentum between FDA, EMA, and ICH guidelines alongside government micronutrient fortification program scale-up rates.
The model holds under stable regulatory convergence assumptions; deviation in heavy metal specification divergence or REACH authorization timeline extension would shift supplier competitive positioning. Forecasts reflect base-case assumptions regarding crystallization technology adoption rates and hospital procurement consolidation trajectories. Periodic stress-testing of base assumptions is recommended given input cost volatility tied to London Metal Exchange zinc benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
South America Surface Treatment Chemicals Market
Chemicals
Global Waterproofing Chemicals Market
Chemicals
Aluminium Chloride Market
Chemicals
Phosgene Market
Chemicals
Phenothiazine Market
Chemicals
Global Pine Chemicals Market
Chemicals
Acrylic Acids and Esters Market
Chemicals
Paint Remover Market
Chemicals
Benzhydrol Market
Chemicals
Mercury (I) Sulphate Market
Chemicals
Paint Stripper Market
Chemicals
Isooctyl Alcohol Market
Chemicals
Valeronitrile Market
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Global N-Butanol Market