
 Global Phenoxyethanol Market | 2026-2036
Global Phenoxyethanol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Phenoxyethanol Market Foresight
Specialty chemical distribution networks serving cosmetic ingredient buyers is rewriting procurement patterns across the phenoxyethanol supply base. BASF SE leverages its integrated aromatics chain to sustain cost-competitive phenoxyethanol supply into European personal care markets. Clariant AG anchors its position through specialized preservative blends that compete on formulation compatibility rather than commodity pricing. Dow differentiates via technical service capabilities that help North American cosmetics manufacturers navigate preservative efficacy testing requirements.
Phenoxyethanol is a glycol ether compound with the molecular formula C8H10O2, typically manufactured through the reaction of phenol with ethylene oxide in alkaline conditions, functioning primarily as a broad-spectrum antimicrobial preservative effective against gram-negative bacteria in aqueous formulations. Cosmetic preservatives command the largest share of product type demand due to phenoxyethanol's established safety profile and broad compatibility with anionic, cationic, and nonionic surfactant systems. Personal care applications generate the fastest growth trajectory as formulators replace paraben systems with phenoxyethanol-phenoxyethanol combinations to meet clean-label consumer preferences while maintaining microbial stability.
The European Chemicals Agency enforces REACH registration requirements that govern phenoxyethanol import volumes and purity specifications, while the FDA maintains preservative concentration limits in cosmetic formulations through its cosmetic safety guidance framework. China's National Medical Products Administration implements cosmetic ingredient safety assessments that determine market access for imported phenoxyethanol batches. Stakeholders must monitor regulatory divergence between preservative approval pathways in the European Union, United States, and China to anticipate supply chain qualification costs and reformulation demands.
Market Dynamics
Paraben replacement mandates across cosmetic formulating hubs are compressing preservative selection cycles and elevating phenoxyethanol qualification volumes as manufacturers race to reformulate existing product lines.
Growth Catalysts
- REACH registration pathways:European phenoxyethanol suppliers leverage completed dossier registrations to accelerate customer onboarding versus competitors still navigating data gap closures.
- Clean-label consumer preferences:Personal care brands in Germany and France explicitly exclude paraben systems from marketing claims, directing R&D budgets toward phenoxyethanol-based preservation.
- Biocide product-type approvals:ECHA's PT6 framework for in-can preservatives creates regulatory clarity that reduces customer uncertainty in industrial coating applications.
Market Restraints
- Phenol feedstock volatility:Benzene derivative pricing swings transmit directly to phenoxyethanol manufacturing economics, compressing margin buffers for non-integrated producers.
- Concentration limit ceilings:FDA guidance restricting phenoxyethanol to one percent in leave-on cosmetics caps formulation flexibility for high-water-content serums.
- Ethylene oxide supply concentration:Three Gulf Coast petrochemical complexes supply the majority of North American ethylene oxide, creating geographic single-point vulnerability.
Strategic Opportunities
- India's cosmetic manufacturing expansion:CDSCO's streamlined cosmetic ingredient notification process opens qualification pathways for phenoxyethanol suppliers serving Mumbai and Ahmedabad formulators.
- Preservative blend innovation:Combining phenoxyethanol with ethylhexylglycerin addresses gram-positive coverage gaps while maintaining clean-label positioning.
- Direct technical service models:Bypassing traditional distribution layers to embed microbiologists within customer R&D labs accelerates formulation validation timelines.
Industry Challenges
- Microbiological testing capacity:Preservative efficacy screening backlogs at third-party laboratories extend product launch timelines by four to eight weeks.
- Dual-registration complexity:Maintaining separate REACH and NMPA dossier versions requires dedicated regulatory affairs headcount that mid-size suppliers struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Phenoxyethanol Market |
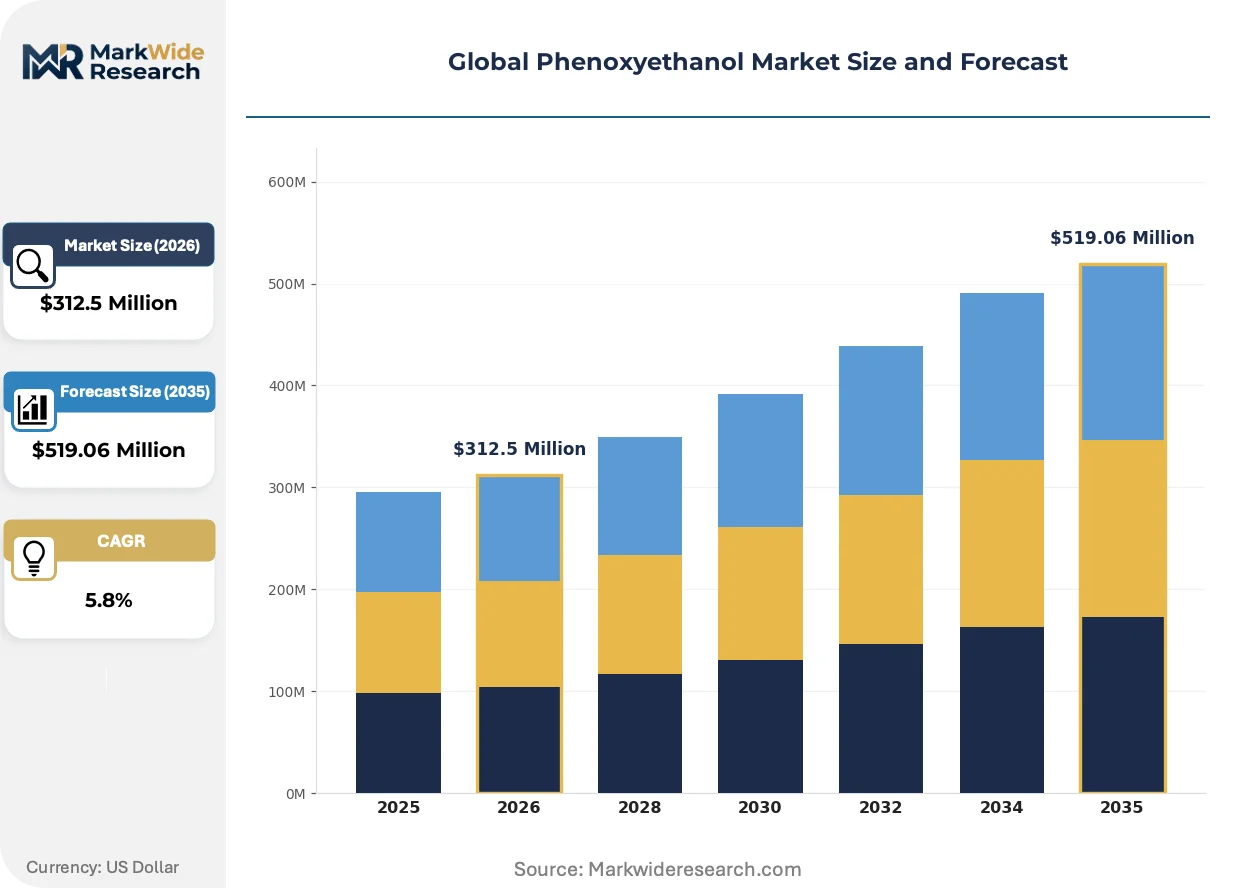
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In Cosmetic Preservatives, Industrial Solvents, Pharmaceutical Additives, Chemical Intermediates, Others Application: Personal Care, Household Products, Agrochemicals, Paints & Coatings, Lubricants End User: Cosmetics Manufacturers, Pharmaceutical Companies, Agriculture Firms, Paint Producers, Lubricant Makers Packaging Type: Drums, Totes, IBC Containers, Bottles, Barrels |
| Companies Covered | BASF SE, Clariant AG, Dow, DuPont, Ashland Global Holdings Inc., Galaxy Surfactants, Lonza Group Ltd., Symrise AG, Penta International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Phenoxyethanol Market Shifts & Advancements
Formulation science advances and regulatory data requirements are converging to reshape how preservative suppliers compete on technical credibility rather than commodity availability.
Continuous phenoxyethanol synthesis using microreactor technology is collapsing batch-to-batch variability that previously required extensive post-manufacturing quality adjustment. German specialty chemical producers adopting these flow chemistry systems report reduced solvent waste profiles that align with EU Green Deal manufacturing expectations. The compression of purity variation bands is enabling just-in-time delivery contracts that were previously unworkable due to release testing delays.
China's NMPA implemented strengthened cosmetic ingredient safety assessment requirements that mandate full toxicological data packages for imported preservative raw materials. Domestic phenoxyethanol manufacturers in Shandong and Jiangsu provinces are capturing share previously held by European suppliers as local registration expertise becomes a decisive qualification factor. Multinational cosmetics brands operating Chinese manufacturing subsidiaries are accelerating dual-source qualification to mitigate import approval timeline uncertainty.
Ingredient procurement teams at mid-size personal care brands are consolidating supplier panels from twelve to four active relationships, prioritizing vendors with integrated regulatory dossier management. This concentration is displacing spot-market purchasing that previously characterized preservative buying patterns. The shift is most pronounced in California and New York state cosmetics clusters where clean-label marketing claims require documented supply chain transparency that fragmented sourcing cannot support.
Global Phenoxyethanol Market Segmentation
Phenoxyethanol procurement patterns diverge sharply across product grades and packaging formats, with cosmetic manufacturers demanding certified purity documentation that industrial buyers rarely require. Technical service intensity and regulatory dossier management separate premium suppliers from commodity traders in each segment category.
Product Type:
After-sales service intensity peaks in cosmetic preservative grades, where suppliers embed microbiologists within customer R&D labs to validate formulation compatibility and navigate preservative efficacy testing protocols.
- In Cosmetic Preservatives:USP-grade material meeting purity specifications above 99% serves skin creams, serums, and aqueous formulations. German and French personal care brands drive qualification volumes as they replace paraben systems to support clean-label marketing claims while maintaining microbial stability through phenoxyethanol-phenoxyethanol combinations.
- Industrial Solvents:Technical-grade phenoxyethanol functions as a coalescing agent and viscosity modifier in coating formulations. Chinese paint manufacturers in Guangdong and Jiangsu provinces concentrate demand as water-based industrial coatings expand to meet domestic environmental compliance timelines.
- Pharmaceutical Additives:GMP-compliant material supports parenteral drug formulations and vaccine preservation. US FDA and EMA inspection requirements elevate supplier qualification barriers beyond standard industrial grades.
- Chemical Intermediates:Feedstock material for downstream glycol ether synthesis and specialty ester production. Indian chemical manufacturers in Gujarat and Maharashtra represent emerging offtake as domestic pharmaceutical intermediate capacity expands.
- Others:Niche applications including fragrance fixatives and textile processing aids. Japanese fragrance compounders in Kanagawa Prefecture sustain specialized demand for low-odor specifications.
Cosmetic preservatives hold the largest share; momentum sits with pharmaceutical additives as injectable drug volumes climb.
Application:
Cost tier differentiation separates mass-market household products from premium personal care formulations, with price sensitivity inversely correlating with regulatory documentation requirements.
- Personal Care:Skin creams, lotions, and color cosmetics represent the steepest expansion trajectory. Formulators in California and New York state cosmetics clusters consolidate supplier panels to four active relationships, prioritizing vendors with integrated REACH and NMPA dossier management for documented supply chain transparency.
- Household Products:Surface cleaners and laundry formulations employ phenoxyethanol as a secondary preservative alongside isothiazolinone systems. Brazilian and Mexican home care manufacturers drive volume as Latin American wet wipe production scales.
- Agrochemicals:In-can preservation for pesticide emulsions and fertilizer suspensions. Australian and Brazilian agricultural chemical blenders concentrate demand during seasonal application windows.
- Paints & Coatings:ECHA's PT6 biocide framework provides regulatory clarity for in-can preservation in water-based architectural and industrial coatings. German specialty coatings producers adopting EU Green Deal manufacturing standards favor suppliers with reduced solvent waste profiles.
- Lubricants:Metalworking fluid preservation against bacterial degradation. US Midwest automotive supplier parks and German automotive OEM tier networks sustain steady offtake.
Personal care commands premium pricing; household products deliver volume scale through contract manufacturing arrangements.
End User:
Customer type determines procurement modality, with multinational cosmetics manufacturers demanding dual-source qualification while regional lubricant blenders rely on distributor inventory programs.
- Cosmetics Manufacturers:Multinational brands operating Chinese manufacturing subsidiaries accelerate dual-source qualification to mitigate NMPA import approval timeline uncertainty. Direct technical service models that bypass traditional distribution layers are compressing formulation validation timelines.
- Pharmaceutical Companies:Sterile injectable and ophthalmic formulation producers require endotoxin-tested material with batch-specific CoA documentation. Swiss and German CDMOs sustain qualification rigor that mid-size suppliers struggle to justify.
- Agriculture Firms:Seasonal procurement patterns concentrate demand during Northern Hemisphere planting preparation periods. Indian and Brazilian agrochemical formulators represent emerging volume as domestic crop protection manufacturing expands.
- Paint Producers:Water-based coating specialists in Italy's Lombardy region and China's Pearl River Delta cluster drive preservative specification evolution. Microbiological testing capacity constraints at third-party laboratories extend product launch timelines.
- Lubricant Makers:Regional blenders in Texas and Rotterdam prioritize just-in-time drum delivery over bulk tote commitments. Metalworking fluid reformulation cycles align with automotive OEM specification updates.
Cosmetics manufacturers concentrate value capture; pharmaceutical companies impose the steepest qualification barriers.
Packaging Type:
Supply concentration in ethylene oxide manufacturing shapes packaging economics, with Gulf Coast petrochemical complex proximity favoring bulk tote and IBC container deployment for North American customers.
- Drums:Standard 200-liter steel and HDPE containers serve mid-volume cosmetics and pharmaceutical manufacturers. German and French formulators prefer drum delivery for flexible batch sizing.
- Totes:Intermediate bulk containers reduce per-unit logistics costs for high-volume household product and lubricant blenders. US Midwest and Chinese Yangtze River Delta manufacturing clusters favor tote delivery for just-in-time inventory programs.
- IBC Containers:Reusable intermediate bulk systems support closed-loop supply arrangements with major coatings producers. Dutch and Belgian chemical distribution hubs maintain IBC cleaning and recertification infrastructure.
- Bottles:Laboratory and pilot-scale packaging for R&D sampling and preservative efficacy screening. California and Massachusetts biotechnology clusters sustain niche demand.
- Barrels:Traditional wooden and fiber packaging for heritage fragrance and specialty chemical applications. Italian and French perfume compounders in Grasse maintain aesthetic packaging requirements.
Totes dominate volume throughput; bottles sustain premium positioning through technical service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals anchor European phenoxyethanol distribution into German and French cosmetics manufacturing clusters. Rail links from Rotterdam's chemical parks to Ludwigshafen and Frankfurt enable just-in-time preservative delivery for formulators replacing paraben systems.
United States
Gulf Coast ethylene oxide production complexes supply feedstock for phenoxyethanol manufacturing serving California and New York cosmetics clusters. FDA concentration limits for leave-on cosmetics drive reformulation activity among Los Angeles-based personal care brands. The Port of Houston's chemical terminals handle bulk phenoxyethanol imports for Midwest household product manufacturers.
Germany
REACH registration completion accelerates customer onboarding for phenoxyethanol suppliers serving Frankfurt and Hamburg formulators. EU Green Deal manufacturing standards favor producers adopting microreactor technology with reduced solvent waste profiles. BASF SE's Ludwigshafen complex sustains integrated aromatics chain cost advantages for European personal care markets.
China
NMPA cosmetic ingredient safety assessments determine market access for imported phenoxyethanol batches serving Shanghai and Guangzhou manufacturers. Shandong and Jiangsu province domestic producers capture share from European suppliers through local registration expertise. Yangtze River Delta cosmetics manufacturing subsidiaries accelerate dual-source qualification to mitigate import approval timeline uncertainty.
India
CDSCO streamlined cosmetic ingredient notification opens qualification pathways for phenoxyethanol suppliers targeting Mumbai and Ahmedabad formulators. Domestic pharmaceutical intermediate capacity expansion in Gujarat and Maharashtra generates feedstock demand for chemical-grade material. India's cosmetic manufacturing expansion concentrates preservative procurement decisions in Maharashtra's industrial corridors.
France
ANSM cosmetic safety guidance aligns with ECHA biocide frameworks governing phenoxyethanol use in Paris-based luxury personal care brands. Grasse fragrance compounders sustain specialized demand for low-odor phenoxyethanol specifications in heritage perfume applications. Clean-label marketing claims from French skincare exporters drive phenoxyethanol-phenoxyethanol combination formulations.
Global Phenoxyethanol Market Competitive Landscape
On the supply side, the industry is consolidating around integrated petrochemical majors and specialized preservative blenders with regulatory dossier capabilities. Three strategic archetypes dominate: integrated aromatics producers leveraging backward feedstock control, formulation-focused specialists competing on technical service intensity, and regional manufacturers capturing share through local registration expertise. Competitive moves concentrate on dual-source qualification partnerships and microreactor technology licensing to compress batch variability.
Within the integrated producer tier, BASF SE anchors European supply through its Ludwigshafen aromatics complex, while Clariant AG occupies a position emphasizing specialized preservative blends over commodity positioning. Dow exemplifies the technical service archetype through North American cosmetics manufacturer support capabilities. These three companies represent the dominant competitive positioning vectors: captive feedstock integration, formulation compatibility specialization, and embedded regulatory navigation support.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Dow |
| DuPont |
| Ashland Global Holdings Inc. |
| Galaxy Surfactants |
| Lonza Group Ltd. |
| Symrise AG |
| Penta International Corporation |
| Others |
Supply & Pricing Matrix
Ethylene oxide supply concentration across three Gulf Coast petrochemical complexes determines both pricing tier spreads and supply chain shape for phenoxyethanol manufacturers. This geographic single-point vulnerability compresses margin buffers for non-integrated producers while elevating premium pricing for suppliers with captive feedstock security.
Pricing Analysis
Volume-discount tiering structures separate cosmetic-grade USP material from technical-grade industrial supply. Pricing stratifies across premium, standard, and economy tiers based on purity certification and regulatory dossier completeness. Cost compression in standard grades is intensifying because Shandong and Jiangsu province domestic producers capture share through local registration expertise. Household product manufacturers in Brazil and Mexico exhibit highest price sensitivity, while Swiss and German pharmaceutical CDMOs accept premium positioning for endotoxin-tested material.
Supply Chain Analysis
Phenol and ethylene oxide feedstock sourcing draws from Germany, the United States, and China as dominant production locations. Manufacturing rests on benzene derivative availability, ethylene oxide allocation, and alkaline catalyst supply. Single-source vulnerability concentrates in Gulf Coast ethylene oxide complexes. Distribution runs through Rotterdam's liquid bulk terminals for European cosmetic clusters and Yangtze River Delta hubs for Asian formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement panels as mid-size personal care brands reduce supplier relationships from twelve to four active vendors. This concentration elevates qualification requirements while displacing spot-market purchasing.
For Market Incumbents: Pre-empt NMPA registration expertise gaps by embedding regulatory affairs headcount dedicated to dual REACH and China dossier maintenance. Backward integration into phenol feedstock secures margin buffers against benzene derivative volatility. Capture formulation validation timelines by deploying microbiologists directly within customer R&D laboratories.
For New Entrants and Emerging Players: India's CDSCO-streamlined cosmetic ingredient notification represents the most penetrable entry point for phenoxyethanol suppliers targeting Mumbai and Ahmedabad formulators. Pharmaceutical additive grades for injectable drug volumes offer qualification pathways with lower incumbent saturation. Technical service bundling with preservative efficacy testing accelerates customer onboarding versus commodity positioning.
For Investors and Strategic Acquirers: ECHA's PT6 biocide framework reshapes the acquisition landscape toward suppliers with completed dossier registrations and microreactor manufacturing capabilities. Long-term viability centers on regulatory navigation assets rather than commodity scale. Watch NMPA import approval timeline uncertainty as the signal for dual-source qualification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Microreactor Technology Licensing | German specialty chemical producers report reduced solvent waste profiles aligning with EU Green Deal expectations. |
| Dual-Source Qualification Partnerships | Multinational cosmetics brands operating Chinese subsidiaries accelerate supplier onboarding to mitigate NMPA timeline risk. |
| Preservative Blend Innovation | Combining phenoxyethanol with ethylhexylglycerin addresses gram-positive coverage gaps while maintaining clean-label positioning. |
| Direct Technical Service Deployment | Bypassing distribution layers to embed microbiologists within customer R&D labs compresses formulation validation timelines. |
| Regulatory Dossier Consolidation | Integrated REACH and NMPA management capabilities displace fragmented spot-market purchasing in California and New York clusters. |
Research Methodology
A standing panel of cosmetic formulators, pharmaceutical quality directors, industrial coatings procurement leads, and specialty chemical distribution managers provided ongoing calibration across primary fieldwork. Secondary validation drew from ECHA registration databases, FDA cosmetic safety guidance, NMPA cosmetic ingredient safety assessments, CDSCO notification records, and customs trade flow data. Bottom-up volume modeling and top-down value triangulation anchored market size estimation.
Scenario-bracketing framed projections across the analysis window through sensitivity testing of regulatory approval timelines and feedstock cost trajectories. Segmentation dimensions included product grade tier, end-use industry cluster, packaging format, and regional manufacturing hub. CAGRs were derived from fitted growth curves applied to validated baseline volumes, incorporating phenol pricing volatility indices and cosmetic formulation substitution rates as industry-specific inputs.
Practitioners should monitor NMPA import approval timeline shifts and ethylene oxide supply disruption events for early signals requiring forecast revision. Cross-checking against ECHA registration completion rates and CDSCO notification processing volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Hydrazine Market
Chemicals
Benzhydrol Market
Chemicals
Copper Oxychloride Market
Chemicals
Thioacetic Acid Market
Chemicals
Fluorochemicals Market
Chemicals
Hydrogen Fluoride Pyridine Market
Chemicals
Negative Photoresist Chemicals Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
Cupric Chloride Market
Chemicals
Hydroxyethyl Methyl Cellulose Market
Chemicals
Glyoxylic Acid Market
Chemicals
Amine Oxide Market
Chemicals
Diphenyl Sulfone Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
North America Isopropyl Alcohol Market