
 Flooring Chemicals Market | 2026-2036
Flooring Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Flooring Chemicals Market Analysis
ISO 14001 environmental management certification is rotating as a baseline qualifier for tier-one specification in commercial and industrial flooring projects. BASF SE leverages its integrated polyurethane precursor chain to sustain supply security for large-scale epoxy and polyaspartic installations. Sika AG anchors its position through specialized mortar and leveling compound portfolios that dominate European infrastructure refurbishment. RPM International Inc competes via differentiated brand architecture spanning industrial coatings through consumer-grade garage floor systems.
Flooring chemicals encompass binders, resins, hardeners, and additives formulated to adhere, seal, coat, or finish substrate surfaces, with epoxy systems typically requiring amine-functional curing agents at specific mix ratios to achieve compressive strengths exceeding 10,000 psi for industrial duty. These formulations serve primarily to protect concrete and other substrates from mechanical abrasion, chemical attack, and moisture ingress while providing aesthetic and hygienic surface properties. Adhesives and coatings command the largest value pools within product type segmentation, driven by high-specification commercial and industrial application volumes. Solvent-based formulations retain share in heavy-duty industrial settings where rapid cure and chemical resistance outweigh VOC constraints, though aqueous and UV-cured systems are gaining specification in residential and light commercial segments where regulatory pressure and installer safety standards are tightening fastest.
EPA VOC regulations in the United States restrict solvent content in architectural coatings, while REACH and the EU Green Deal in Europe mandate progressive reduction of hazardous substance classifications in construction chemicals. ECHA substance evaluation processes are directly influencing reformulation timelines for isocyanate-containing polyurethane systems across both regions. Stakeholders must monitor evolving chemical hazard classifications and certification migration patterns to anticipate which formulation platforms will retain specification access in priority end-use segments.
Market Dynamics
Formulation chemistry is pivoting under dual pressure from REACH solvent restrictions and infrastructure build-out in Asia-Pacific, compressing specification windows for legacy epoxy systems while expanding volumes for low-VOC alternatives in commercial flooring.
Growth Catalysts
- REACH solvent limits:European ECHA substance evaluations are forcing reformulation of high-VOC epoxy systems, opening specification gates for aqueous and polyaspartic alternatives in commercial and healthcare flooring.
- Polyurethane precursor integration:Captive supply of isocyanate and polyol streams is securing availability for large-scale industrial installations in manufacturing corridors.
- China infrastructure acceleration:Manufacturing facility construction and logistics hub development are pulling industrial-grade epoxy and polyurethane volumes into specification pipelines.
Market Restraints
- Bisphenol A feedstock volatility:Epoxy resin cost structures fluctuate with benzene and propylene chain pricing, compressing margin stability for coating formulators.
- Isocyanate supply concentration:MDI and TDI production clusters in specific coastal manufacturing zones create vulnerability for polyurethane flooring system availability.
- Cure temperature limitations:Ambient-cure polyaspartic systems face technical constraints in cold-climate application windows, restricting year-round installation capacity.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives and dedicated manufacturing zones are creating specification demand for chemical-resistant flooring in automotive and electronics assembly.
- UV-cured system convergence:Combination of LED curing hardware and cationic epoxy chemistry is opening residential garage and light commercial segments previously closed to site-applied coatings.
- Installer certification platforms:Manufacturer-controlled training and application credentialing is creating channel capture mechanisms that lock out unqualified competitors.
Industry Challenges
- Skilled applicator scarcity:Proper epoxy and polyurethane installation demands certified technicians for surface preparation, mix ratio accuracy, and cure monitoring, constraining project throughput.
- ISO 14001 certification timelines:Environmental management system documentation and third-party audit cycles create 12-18 month qualification delays for tier-one commercial specification access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flooring Chemicals Market |
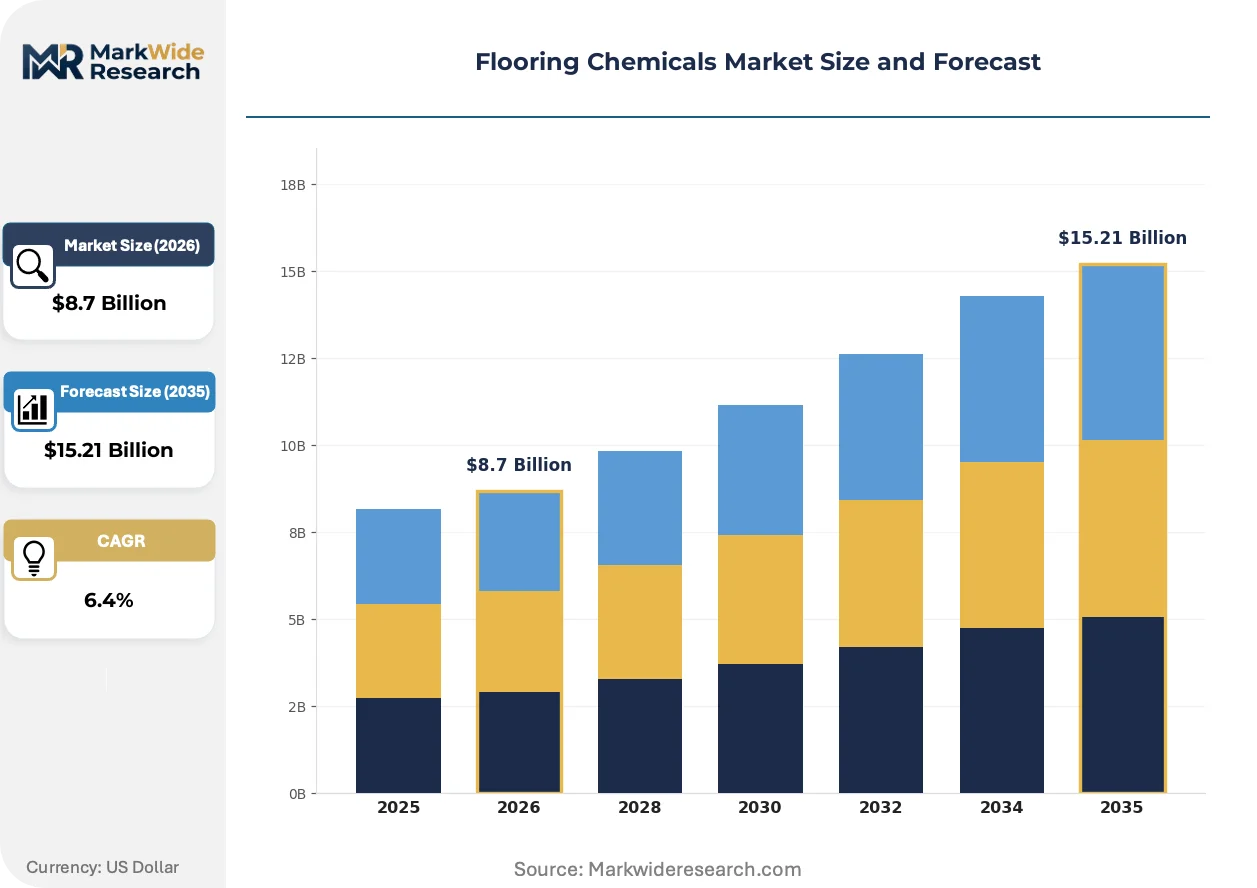
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Sealants, Coatings, Finishes Application: Residential, Commercial, Industrial, Institutional Formulation: Aqueous, Solvent-Based, Hybrid, UV-Cured End User: Contractors, Distributors, Manufacturers, DIY Consumers |
| Companies Covered | BASF SE, Sika AG, RPM International Inc, The Dow Chemical Company, PPG Industries Inc, The Sherwin-Williams Company, MAPEI S.p.A., AkzoNobel N.V., LyondellBasell Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flooring Chemicals Market Emerging Trajectories
Active reformulation is compressing the solvent-based coating share as regulatory thresholds tighten and application technology advances, with three convergent developments reshaping competitive positioning in industrial and commercial flooring.
Waterborne epoxy technology is displacing solvent-based systems in high-traffic commercial installations where EPA VOC limits and installer safety protocols have tightened fastest. Property managers and facility operators in healthcare and education verticals are specifying these formulations for occupied-space renovations. The shift is compressing demand for conventional high-solids epoxies in segments previously dominated by rapid-cure solvent chemistry.
ECHA substance evaluation under REACH is reclassifying isocyanate hazards and mandating enhanced respiratory protection protocols for polyurethane flooring application across European member states. Industrial contractors are responding by accelerating specification of low-isocyanate or isocyanate-free polyaspartic alternatives in warehouse and logistics environments. The regulatory friction is creating competitive advantage for formulators with advanced curing agent portfolios that maintain performance without triggering the new hazard classifications.
Specification decisions are migrating from general contractors to specialized flooring consultants and directly to end-user facility engineering teams, compressing traditional distribution channels. Large retail and industrial occupiers are developing internal standards documents that pre-qualify approved systems and installers, bypassing architect specification in favor of direct procurement relationships. This pattern is most pronounced in North American big-box retail and food processing verticals where standardized flooring performance across multi-site portfolios drives centralized decision-making.
Flooring Chemicals Market Segmentation
Specification decisions in flooring chemicals fragment across four distinct dimensions, each carrying unique margin profiles and regulatory exposure. Product chemistry and formulation type determine VOC compliance pathways, while application context and procurement channel dictate volume concentration and price realization.
Product Type:
Substitution pressure from adjacent construction chemical categories reshapes competitive boundaries most acutely in protective coatings and joint sealants.
- Adhesives:Polyurethane and epoxy-based bonding systems anchor substrate attachment for vinyl, rubber, and carpet tile installations. Demand concentrates in commercial office fit-outs across Germany and France where rapid-cure specifications compress installation schedules.
- Sealants:Elastomeric polyurethane and silicone formulations accommodate thermal expansion in large-format concrete slabs. Industrial logistics facilities in China's Yangtze River Delta specify high-movement-capability grades for automated warehouse flooring.
- Coatings:Epoxy and polyaspartic film-forming systems deliver chemical resistance and abrasion protection.
- Finishes:Polyurethane and acrylic topcoats provide gloss control and wear-layer renewal.
Coatings retain volume leadership; finishes hold the steepest expansion curve as refurbishment cycles accelerate.
Application:
Cost tier stratification separates specification-grade industrial systems from commodity residential offerings.
- Residential:Waterborne polyurethane and acrylic finishes dominate garage floor and basement sealing projects. DIY consumers in US suburban markets drive volume through big-box retail channels where application simplicity outweighs durability ratings.
- Commercial:Low-VOC epoxy and polished concrete densifiers serve high-traffic retail and healthcare environments. REACH-compliant aqueous systems are gaining specification in UK and Netherlands hospital renovations.
- Industrial:Heavy-duty epoxy and polyurethane mortar systems resist chemical attack in manufacturing corridors.
- Institutional:Slip-resistant and antimicrobial formulations address safety and hygiene mandates.
Industrial applications retain volume leadership; commercial flooring holds the steepest expansion curve as VOC regulations tighten.
Formulation:
Technology maturity curves separate established aqueous platforms from emerging UV-cured alternatives.
- Aqueous:Water-dispersed epoxy and polyurethane systems achieve sub-100 g/L VOC content for EPA-compliant commercial application. Facility managers in California and New York specify these formulations for occupied-space renovations where solvent odor is unacceptable.
- Solvent-Based:High-solids epoxy and polyurethane retain industrial preference for rapid cure and chemical resistance. Cold-climate contractors in Canada and Russia specify solvent carriers where ambient temperature falls below aqueous system minimums.
- Hybrid:Water-reducible and high-solids blends balance performance and compliance.
- UV-Cured:Cationic epoxy chemistry combined with LED curing hardware enables instant return-to-service.
Solvent-based formulations retain volume leadership; UV-cured systems hold the steepest expansion curve as curing equipment costs decline.
End User:
Procurement concentration patterns separate volume-aggregating distributors from specification-controlling contractors.
- Contractors:Certified installation firms specify systems based on cure window, substrate compatibility, and warranty terms. Large flooring contractors in Texas and Florida maintain approved vendor lists that lock out unqualified competitors.
- Distributors:Regional construction supply houses aggregate demand across multiple contractor accounts. Distributor networks in India's Maharashtra and Gujarat states are expanding industrial chemical inventories to serve automotive corridor growth.
- Manufacturers:Prefabricated flooring producers integrate in-house coating and adhesive operations.
- DIY Consumers:Home improvement retailers and e-commerce channels serve residential project demand.
Contractors retain volume leadership; manufacturers hold the steepest expansion curve as prefabrication scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH solvent restrictions and China's infrastructure stimulus are redistributing specification authority across manufacturing corridors and commercial construction zones. Facility engineering teams in high-growth economies are developing internal standards that bypass traditional architect specification. Regulatory divergence between EPA VOC limits and ECHA hazard reclassifications is fragmenting formulation platforms by geography.
China
Manufacturing facility construction in the Yangtze River Delta and Pearl River Delta is accelerating demand for industrial-grade epoxy and polyurethane systems. MEE enforcement of dual carbon goals is tightening permissible solvent content in floor coatings for new logistics hubs. Zhejiang and Jiangsu provinces concentrate specification activity for chemical-resistant flooring in electronics assembly plants.
Germany
Automotive corridor refurbishment in Bavaria and Baden-Württemberg is driving specification of low-VOC aqueous epoxy systems for occupied-space renovations. ECHA substance evaluations under REACH are reclassifying isocyanate hazards and mandating enhanced respiratory protection for polyurethane application. Industrial contractors in North Rhine-Westphalia are accelerating adoption of polyaspartic alternatives in warehouse environments.
United States
Big-box retail and food processing verticals are centralizing flooring procurement decisions through internal standards documents that pre-qualify approved systems. EPA VOC regulations in California and New York restrict solvent content in architectural coatings for commercial renovations. Texas and Florida maintain dense networks of certified installation firms with approved vendor lists that control specification access.
India
PLI scheme incentives for automotive and electronics manufacturing are creating specification demand for chemical-resistant flooring in dedicated industrial zones. BIS certification requirements are tightening quality standards for imported resin systems. Maharashtra and Gujarat distributor networks are expanding industrial chemical inventories to serve corridor growth in Pune and Ahmedabad.
Japan
Healthcare facility renovation in Tokyo and Osaka is specifying low-odor aqueous systems for occupied-space applications. METI guidance on construction chemical emissions is accelerating reformulation timelines for epoxy and polyurethane platforms. Chubu region manufacturing plants are upgrading flooring systems to meet revised JIS standards for chemical resistance and durability.
Flooring Chemicals Market Vendor Landscape
Player mix skews toward diversified chemical conglomerates with captive resin supply chains and specialized construction chemical houses with regional installation networks. The market structure favors scale-driven formulators with backward integration into polyurethane precursors and application-certified specialists with channel capture through installer training platforms. Strategic moves concentrate on portfolio diversification into low-VOC aqueous systems and geographic expansion through distributor network consolidation in Asia-Pacific manufacturing corridors.
Among European-based chemical conglomerates, BASF SE and Sika AG exemplify divergent competitive archetypes. BASF SE occupies a position defined by integrated polyurethane precursor chains that secure supply security for large-scale installations. Sika AG anchors its market presence through specialized mortar and leveling compound portfolios that dominate infrastructure refurbishment cycles. RPM International Inc represents the diversified brand architecture approach, spanning industrial coatings through consumer-grade application systems without reliance on single technology platforms.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| RPM International Inc |
| The Dow Chemical Company |
| PPG Industries Inc |
| The Sherwin-Williams Company |
| MAPEI S.p.A. |
| AkzoNobel N.V. |
| LyondellBasell Industries |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day inventory cycles for epoxy resin precursors expose formulators to benzene and propylene price swings, compressing margin buffers for coating producers while amplifying pricing power for backward-integrated chemical conglomerates with captive isocyanate supply.
Pricing Analysis
Certification level (ISO 14001/REACH-compliant) creates the primary spread between specification-grade industrial systems and commodity residential offerings. Project-based contracting dominates, with price differentiation driven by formulation chemistry complexity and installer certification tier. Pricing pressure stems from bisphenol A feedstock volatility, squeezing mid-tier formulators lacking long-term offtake agreements. DIY consumers exhibit highest price sensitivity; industrial facility engineering teams prioritize performance guarantees over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites MDI and TDI movement from Northeast Asian production clusters to Southeast Asian application sites. Manufacturing concentrates in China, Germany, and the United States. Raw material flows draw from benzene crackers, propylene oxide facilities, and amine-functional curing agent specialists. Single-source vulnerability concentrates in coastal isocyanate plants vulnerable to weather disruption. Distribution runs through certified contractor networks with approved vendor lists controlling specification access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as big-box retail and food processing verticals centralize procurement through internal standards documents, fragmenting traditional architect-driven specification channels.
For Market Incumbents: Consolidate installer certification platforms to lock out unqualified competitors and defend specification access against emerging aqueous system specialists. Deepen backward integration into polyurethane precursor chains to insulate margin structures from isocyanate supply shocks. Prioritize REACH-compliant reformulation timelines to maintain European commercial flooring access. For New Entrants and Emerging Players: Lead with UV-cured system offerings targeting residential garage and light commercial segments where LED curing hardware costs are declining fastest. Penetrate India's PLI-driven automotive corridors through distributor partnerships in Maharashtra and Gujarat. Position around application simplicity for contractor segments frustrated by polyaspartic cure temperature limitations. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification authority is migrating from general contractors to specialized flooring consultants and end-user engineering teams. Target mid-cap formulators with aqueous epoxy technology portfolios and established ISO 14001 certification. Watch ECHA substance evaluation timelines as inflection indicators for isocyanate-free system adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursors | Captive MDI supply secures availability for large-scale industrial installations in China's manufacturing corridors. |
| Low-VOC Reformulation Investment | REACH-compliant aqueous systems retain specification access in European healthcare and education verticals. |
| Installer Certification Platform Buildout | Manufacturer-controlled training creates channel capture mechanisms that pre-qualify approved vendors. |
| UV-Cured System Portfolio Expansion | LED curing hardware convergence opens residential garage segments previously closed to site-applied coatings. |
| Distributor Network Consolidation | Regional construction supply aggregation captures volume across India's PLI-driven automotive corridor growth. |
Methodological Framework
Desk research of customs trade data, SEC filings from coating conglomerates, and ECHA substance evaluation databases preceded structured interviews with plant managers at industrial flooring contractors, procurement leads at big-box retail facility engineering teams, distribution channel partners, and technical R&D directors at resin formulators. Primary fieldwork combined with secondary validation from ACC and Cefic industry reports. Bottom-up volume modeling triangulated against top-down market sizing across product chemistry, application context, and regional regulatory clusters.
Variance decomposition across segmentation dimensions—product type, formulation technology, end-use vertical, and procurement channel—shaped projection outputs throughout the forecast period. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and infrastructure investment cycles. Specific inputs included MEE enforcement timelines for China's dual carbon goals and ECHA isocyanate reclassification schedules.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure stimulus in Asia-Pacific or accelerated REACH solvent restriction timelines would require recalibration. Forecasts reflect assumptions about skilled applicator availability and certification platform penetration rates. Revision becomes warranted when bisphenol A feedstock volatility crosses thresholds that trigger widespread reformulation toward alternative resin platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Perchloric Acid Market
Chemicals
Aluminum Chemicals Market
Chemicals
Power Plant Chemicals Market
Chemicals
Calcium Borate Market
Chemicals
Global N-Butanol Market
Chemicals
Hydrophobing Agents Market
Chemicals
Pyrogallol Market
Chemicals
Iscotrizinol Market
Chemicals
India Methanol Market
Chemicals
Global Bleaching Agents Market
Chemicals
Acetic Ether Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Sodium Methoxide Market
Chemicals
White Phosphorus Market
Chemicals
Middle East Construction Chemicals Market