
 Canada Dairy Market | 2026-2036
Canada Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Dairy Market Insights
Western Canada is rewriting production economics for the national dairy sector. Saputo Inc. leverages its integrated processing network across prairie provinces to secure milk supply volumes. Agropur Dairy Co-operative anchors its cooperative model through farmer-owned procurement, sustaining price stability for member producers. Gay Lea Foods specializes in value-added butter and cream products, occupying a differentiated niche in Ontario's manufacturing corridor.
Canada dairy encompasses fluid milk, fermented products, and fat-based derivatives standardized under federal compositional criteria for butterfat content and protein ratios. Industrial processors convert raw milk through pasteurization, homogenization, and enzymatic treatment into ingredients for retail and food manufacturing applications. Cheese commands the largest value pool among product type segments, while yogurt maintains faster velocity through health-positioned innovation. The organic quality grade segment attracts premium positioning, though conventional production retains volume dominance across supermarket and wholesaler channels.
Health Canada governs nutrition labeling and compositional claims under the Food and Drugs Act, while the Canadian Food Inspection Agency enforces grade standards and interprovincial trade compliance. The Dairy Farmers of Canada administers supply management quotas that directly constrain production volumes and stabilize farmgate pricing. Provincial milk marketing boards in Quebec and Ontario allocate processor licenses, shaping market access for new entrants. Stakeholders must monitor quota allocation debates and potential trade agreement modifications that could reshape the supply management architecture.
Market Dynamics
Supply management quotas administered by the Dairy Farmers of Canada constrain production volumes while stabilizing farmgate pricing, creating a rigid production ceiling that processors navigate through quota trading and interprovincial allocation negotiations.
Growth Catalysts
- Health Canada's nutrition labeling updates:Tightened compositional standards for fluid milk and cheese categories are compelling processors to upgrade quality control systems, opening premium positioning for compliant producers.
- Food service channel expansion:Ontario and Quebec operators are expanding dairy procurement for premium menu applications, pulling higher-margin butter and cream volumes through institutional supply chains.
- Grass-fed production systems:Alberta and British Columbia ranchers are converting pasture infrastructure to capture organic price premiums in retail channels.
Market Restraints
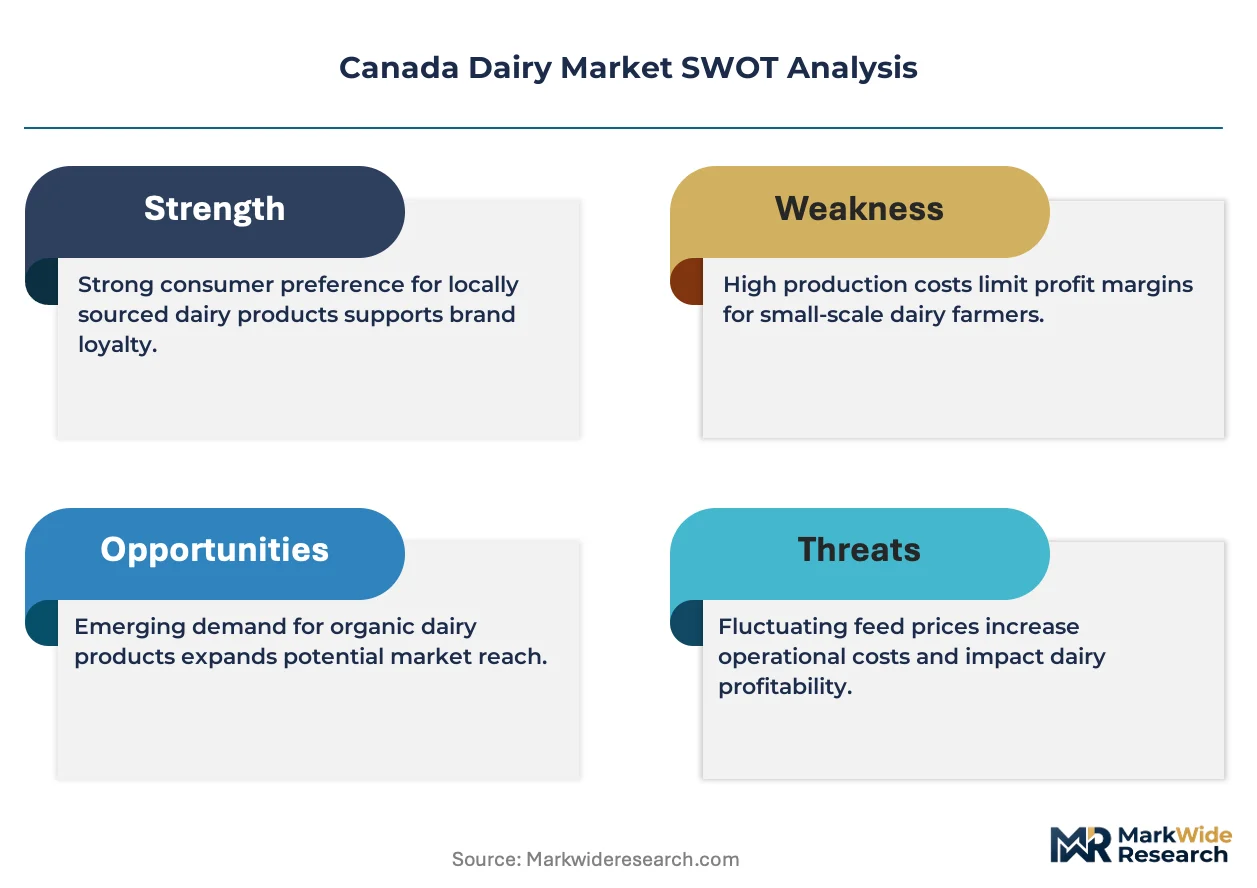
- Feed cost volatility:Prairie grain price swings directly compress margins for quota-holding producers dependent on purchased rations.
- Quota allocation concentration:Quebec and Ontario marketing boards control processor licensing, creating structural barriers for new entrants seeking market access.
- Plant-based substitution:Oat and almond beverage categories are capturing shelf space in supermarket dairy aisles, constraining fluid milk volume growth.
Strategic Opportunities
- Underpenetrated organic segments:British Columbia and Alberta retail channels show whitespace for certified grass-fed butter and aged cheddar variants.
- Fermented product innovation:Kefir and skyr formats are attracting health-positioned consumers seeking probiotic functionality beyond conventional yogurt.
- Direct-to-foodservice channels:Bypassing traditional wholesaler tiers allows processors to capture margin from Ontario and Quebec restaurant operators demanding traceable provenance.
Industry Challenges
- Skilled technician scarcity:Dairy processing automation requires mechatronics expertise that technical colleges in prairie provinces are not graduating at replacement rates.
- Legacy system integration:Quota tracking databases at provincial marketing boards resist interoperability with modern ERP platforms deployed by multi-site processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Dairy Market |
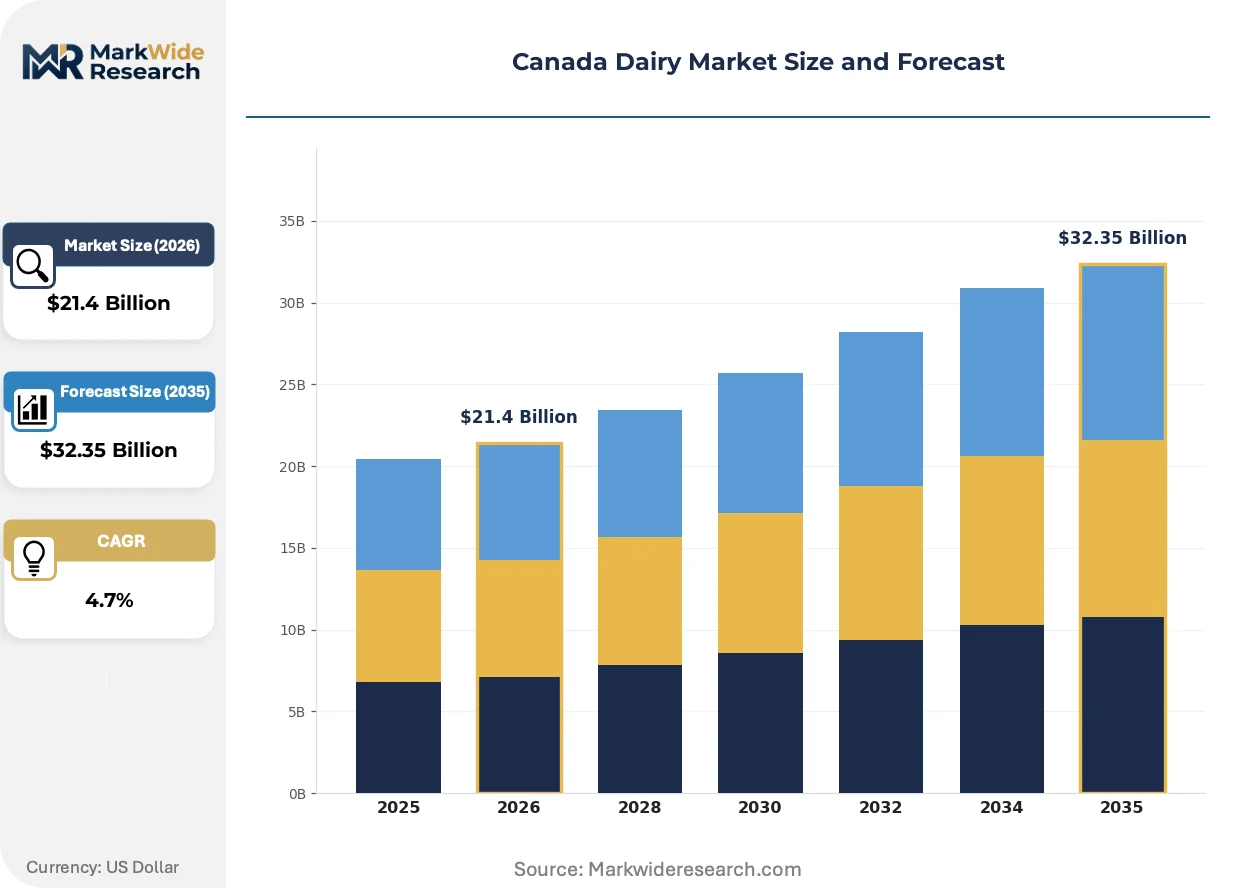
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $32.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter End User: Households, Food Service, Retailers, Manufacturers Distribution Channel: Supermarkets, Wholesalers, Convenience Stores, Online Quality Grade: Organic, Grass-fed, Conventional, Specialty |
| Companies Covered | Danone S.A., Kraft Heinz, Saputo Inc., Organic Meadow, St-Albert Cheese, Agropur Dairy Co-operative, Gay Lea Foods, Mariposa Dairy, Groupe Lactalis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Dairy Market Trends and Innovations
Precision fermentation and enzymatic processing technologies are compressing production timelines while enabling novel protein structures that traditional culturing cannot achieve.
Precision fermentation platforms using microbial hosts to produce dairy-identical proteins are rendering obsolete conventional whey and casein extraction from raw milk. Ingredient manufacturers in Ontario's manufacturing corridor are piloting these systems at commercial scale. The technology is compressing capital requirements for protein isolation while eliminating herd-dependent supply volatility.
Health Canada's updated nutrition labeling requirements under the Food and Drugs Act are mandating front-of-package sodium and saturated fat disclosures. Cheese processors are reformulating recipes to maintain retail placement compliance. The fluid milk category faces particular pressure as Health Canada tightens compositional claim thresholds.
Foodservice buyers in Toronto and Montreal are unbundling dairy procurement from broadline distributor contracts to secure direct relationships with butter and cream specialists. This disintermediation is compressing wholesaler margins while rewarding processors with provenance documentation and flexible volume commitments. Quebec's restaurant association reports accelerating adoption of this procurement model among independent operators.
Canada Dairy Market Segmentation
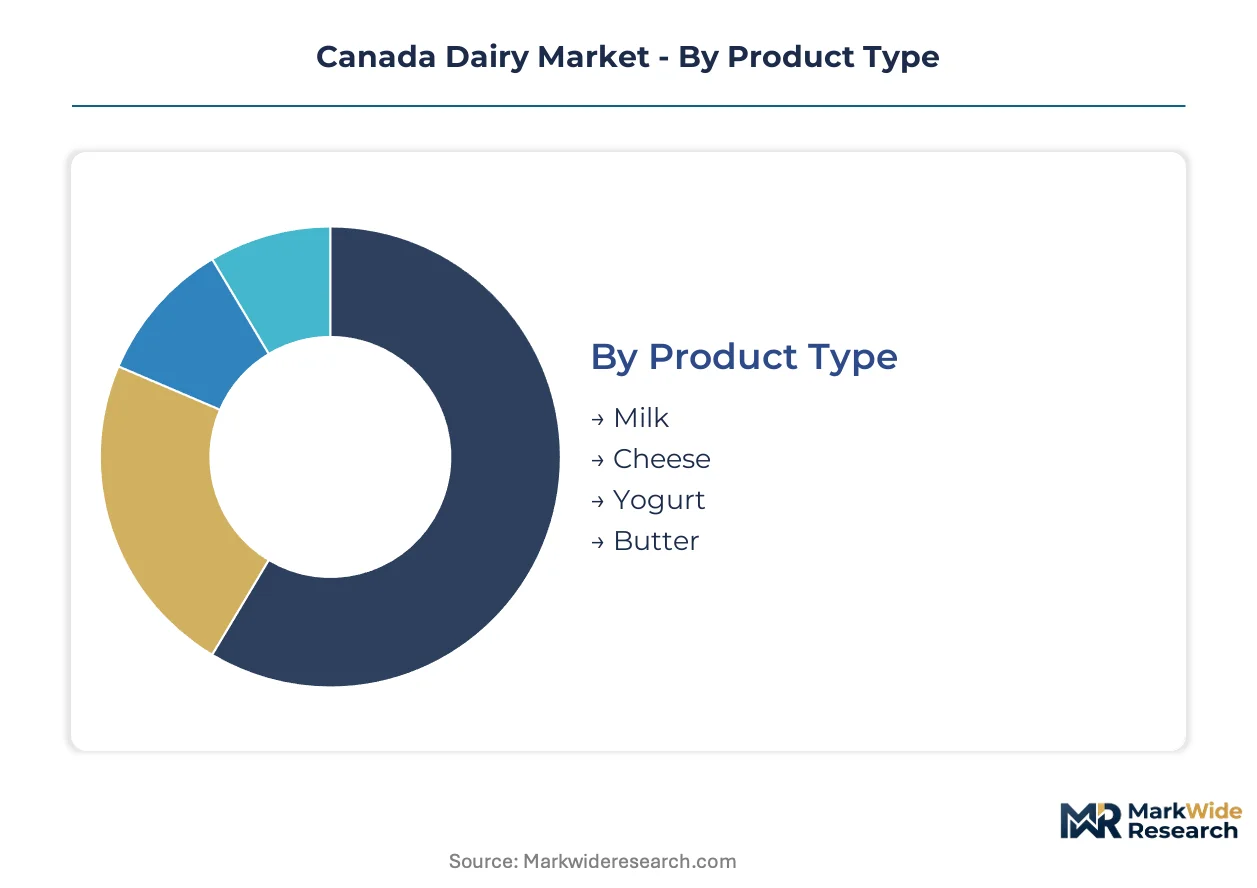
Canada's supply-managed dairy architecture fragments procurement decisions across quota-holding producers, provincial marketing boards, and processor licensing tiers. Segmentation reveals where pricing power concentrates and which channels bypass traditional wholesaler structures.
Product Type:
Cost tier differentiation separates commodity fluid volumes from value-added derivatives commanding margin premiums.
- Cheese:Aged cheddar and specialty varieties dominate value pools through extended maturation cycles and controlled moisture content specifications. Quebec and Ontario food service operators are pulling premium artisanal volumes through direct procurement relationships, bypassing traditional distributor markups.
- Butter:Churned fat derivatives with standardized butterfat content between 80-84% anchor industrial baking and retail spread applications. Alberta and British Columbia ranchers converting to grass-fed pasture systems are capturing organic price premiums in supermarket channels.
- Milk:Fluid pasteurized volumes standardized under federal compositional criteria for protein ratios and vitamin fortification.
- Yogurt:Fermented cultured products with live probiotic cultures, positioned through health-functional claims in retail dairy aisles.
Cheese holds installed capacity. Yogurt is rotating up the share rankings.
End User:
Customer type determines volume commitment structures and traceability documentation requirements.
- Food Service:Restaurant and institutional operators in Toronto and Montreal are unbundling dairy procurement from broadline contracts to secure direct processor relationships. This disintermediation rewards suppliers with flexible volume commitments and provenance documentation while compressing traditional wholesaler margins.
- Manufacturers:Industrial ingredient buyers convert butter, cream, and milk powders into processed food applications requiring consistent butterfat specifications and batch-scale reliability.
- Households:Individual consumers purchasing through retail channels for direct consumption.
- Retailers:Supermarket and convenience store chains managing private label and branded dairy assortments.
Food service is expanding most quickly. Manufacturers defend volume baselines.
Distribution Channel:
Supply concentration varies by channel control over shelf placement and promotional funding.
- Supermarkets:Dominant retail format controlling category management and planogram allocation for fluid milk, cheese, and yogurt assortments. Health Canada's front-of-package labeling mandates are forcing reformulation compliance to maintain placement access.
- Wholesalers:Traditional broadline distributors facing margin compression as Ontario and Quebec food service operators adopt direct procurement models.
- Convenience Stores:Limited assortment outlets prioritizing extended-shelf-life fluid milk and single-serve yogurt formats.
- Online:E-commerce platforms building subscription models for organic and grass-fed specialty grades.
Supermarkets anchor volume throughput. Online is climbing the fastest.
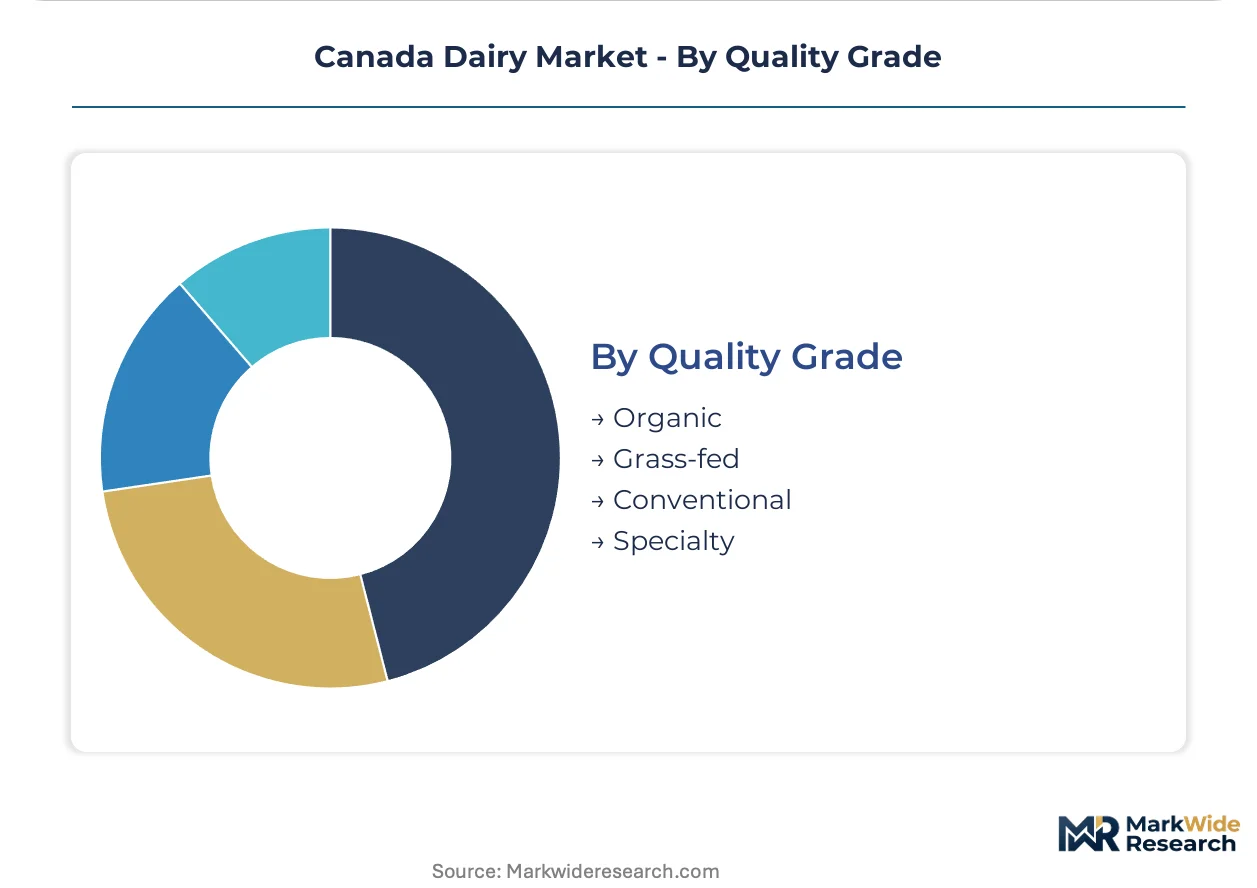
Quality Grade:
Certification tier creates pricing stratification across production method verification costs.
- Organic:Certified production excluding synthetic pesticides and antibiotics, commanding retail premiums in British Columbia and Alberta channels. Prairie pasture infrastructure conversions are expanding certified herd volumes to meet supermarket allocation growth.
- Grass-fed:Seasonal pasture-based systems with butterfat profiles distinct from grain-finished herds, attracting specialty cheese and butter applications.
- Conventional:Standard production under supply management quota systems, retaining volume dominance across institutional and value-tier retail.
- Specialty:A2 protein variants, raw milk cheeses, and regional terroir-designated products targeting differentiated positioning.
Conventional retains volume dominance. Organic is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quota allocation under supply management concentrates processing capacity in Ontario and Quebec, while Alberta and British Columbia ranchers convert pasture systems to capture organic premiums. Provincial marketing boards shape procurement economics through interprovincial licensing tiers.
Ontario
Foodservice operators in Toronto unbundle dairy procurement from broadline distributors to secure direct butter and cream relationships. Health Canada's front-of-package labeling mandates under the Food and Drugs Act pressure cheese processors to reformulate sodium content. The Golden Horseshoe manufacturing corridor hosts precision fermentation pilots targeting dairy-identical protein isolation.
Quebec
Artisanal cheese maturation facilities around Montreal pull premium volumes through restaurant direct procurement channels. The province's milk marketing board allocates processor licenses that constrain new entrant market access. St-Albert Cheese anchors cooperative production models in the Ottawa Valley, sustaining farmgate price stability for member producers.
Alberta
Prairie grain price volatility compresses margins for quota-holding producers dependent on purchased rations. The Canadian Food Inspection Agency enforces grade standards for fluid milk compositional claims across Calgary and Edmonton distribution hubs. Ranchers converting to grass-fed pasture systems capture organic price premiums in supermarket retail channels.
British Columbia
Retail channels in Vancouver and Victoria show whitespace for certified grass-fed butter variants. Health Canada tightens nutrition labeling thresholds for saturated fat disclosures in fermented product categories. The Okanagan Valley hosts expanding organic herd volumes to meet supermarket allocation growth.
Canada Dairy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient isolation and artisanal maturation. The vendor base clusters around three structural tiers: national cooperatives with farmer-owned procurement, integrated multinationals with cross-border processing networks, and regional specialists in differentiated fat-based derivatives. Two dominant competitive moves shape positioning: cooperative members defending quota allocation through provincial board engagement, and integrated processors expanding direct-to-foodservice channels to bypass wholesaler markups.
Among cooperative-structured operators, Agropur Dairy Co-operative and Gay Lea Foods exemplify the farmer-owned procurement archetype, anchoring price stability through membership-based milk supply agreements. Saputo Inc. represents the integrated multinational tier, leveraging cross-province processing networks to secure volume commitments from quota-holding producers. These three entities collectively illustrate how supply management architecture fragments competitive positioning between cooperative governance and integrated scale.
| Leading Market Players |
|---|
| Danone S.A. |
| Kraft Heinz |
| Saputo Inc. |
| Organic Meadow |
| St-Albert Cheese |
| Agropur Dairy Co-operative |
| Gay Lea Foods |
| Mariposa Dairy |
| Groupe Lactalis |
| Others |
Pricing and Supply Chain Analysis
Feed cost volatility in prairie grain markets compresses margins for quota-holding producers dependent on purchased rations, determining both the spread between organic and conventional pricing tiers and the geographic clustering of processing capacity near supply-managed production zones. This input cost instability cascades through supply chain configuration, concentrating value-added processing in Ontario and Quebec while pushing grass-fed premium production toward Alberta and British Columbia pasture systems.
Pricing Analysis
Health Canada's Food and Drugs Act dictates the pricing tier structure through tightened compositional standards and front-of-package labeling mandates. Three-tier pricing structure across premium, standard, and economy levels separates certified organic grass-fed products from conventional supply-managed volumes and private-label economy tiers. Cost compression in the conventional fluid milk segment is intensifying because oat and almond beverage categories capture supermarket shelf space. Food service operators demonstrate the least price sensitivity, paying premiums for traceable provenance and flexible volume commitments.
Supply Chain Analysis
Export-control regimes on precision fermentation technologies and enzymatic processing equipment limit flows of novel protein isolation systems into Ontario's manufacturing corridor. Geographic supply concentration centers on Canada for raw milk under supply management, with equipment and specialized cultures drawing from the United States and European biotechnology suppliers. Raw material dependencies include prairie grain for feed rations, packaging materials, and live cultures for fermented products. Single-source vulnerability runs through provincial marketing board quota allocation systems. Distribution runs through supermarket chains for retail volume, direct procurement channels for food service, and broadline wholesalers facing margin compression.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's dairy market fragments along quality-grade and channel lines, with disintermediation in Ontario and Quebec food service procurement creating specialist niches alongside cooperative-dominated commodity flows.
For Market Incumbents: Insulate quota-backed supply relationships through deeper engagement with provincial marketing boards as plant-based substitution accelerates. Prioritize backward integration into grass-fed pasture systems in Alberta and British Columbia to capture organic price premiums. Invest in precision fermentation pilots to hedge against herd-dependent supply volatility.
For New Entrants and Emerging Players: Direct-to-foodservice channels in Toronto and Montreal represent the most penetrable entry point, bypassing wholesaler markups through provenance documentation and flexible commitments. British Columbia and Alberta retail whitespace for certified grass-fed butter variants offers secondary beachhead. Anchor go-to-market strategy on Health Canada labeling compliance as a differentiation credential.
For Investors and Strategic Acquirers: Health Canada's pending nutrition labeling enforcement reshapes the acquisition landscape toward processors with reformulation capabilities and organic certification infrastructure. Long-term viability hinges on supply management quota value and trade agreement exposure. Target acquisition archetypes include regional butter and cream specialists with food service relationships. Watch quota allocation debates and CPTPP modification signals as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pasture Systems | Alberta and British Columbia ranchers capture organic premiums through certified grass-fed production. |
| Direct-to-Foodservice Channel Development | Ontario and Quebec restaurant operators reward traceable provenance with flexible volume commitments. |
| Precision Fermentation Pilot Scale-Up | Ontario's manufacturing corridor tests microbial protein isolation to reduce herd dependency. |
| Health Canada Compliance Certification | Front-of-package labeling mandates force reformulation investment to maintain retail placement. |
| Provincial Marketing Board Engagement | Quota allocation negotiations determine processor licensing access and farmgate price stability. |
Research Methodology
Operator-level perspectives from dairy processing executives, provincial marketing board administrators, food service procurement directors, and organic certification specialists anchored the qualitative base. Secondary validation drew from Health Canada regulatory filings, Canadian Food Inspection Agency grade standards, Dairy Farmers of Canada quota allocation records, and provincial milk marketing board licensing data. Bottom-up volume modeling and top-down market sizing triangulated across these sources.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions including product type, end user channel, distribution format, and quality grade tier. CAGRs derived from trend extrapolation of supply-managed production volumes, organic conversion rates, and food service channel penetration. Industry-specific inputs encompassed quota trading prices, prairie grain cost indices, and precision fermentation technology readiness levels.
Practitioners should monitor quota allocation policy shifts, trade agreement modifications affecting supply management, and precision fermentation commercialization milestones for early signals. Forecasts reflect documented assumptions regarding supply management continuity and organic certification growth trajectories. Material shifts in CPTPP dairy access provisions or Health Canada labeling enforcement timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Plain Yogurt Market
Dairy Products
Sour Milk Drinks Market
Dairy Products
North America Flavored Milk Market
Dairy Products
Enzyme Modified Cheese Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Latin America Cheese Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Sweetened Condensed Milk Market
Dairy Products
Lactose-Free Sour Cream Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Gruyere Market
Dairy Products
North America Yogurt Market
Dairy Products
Cultured Whey Products Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Global Cream Cheese Market