
 Low Cholesterol Cheese Market | 2026-2036
Low Cholesterol Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Low Cholesterol Cheese Market Analytics
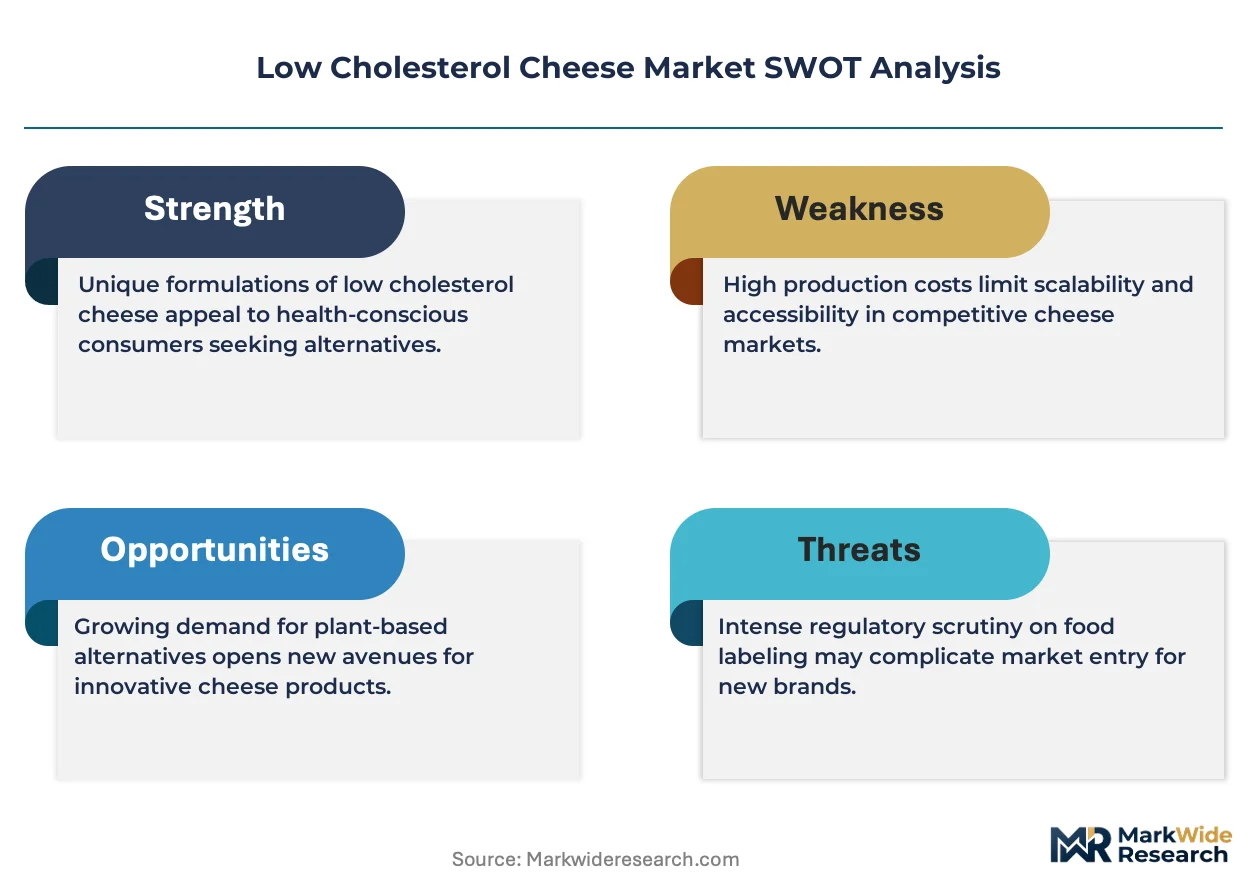
Asset-light co-manufacturing and private-label leasing arrangements are narrowing the capital barrier for mid-tier entrants in low cholesterol cheese production. Lactalis Group leverages its captive dairy supply network across European sourcing regions to sustain cost advantages in reduced-fat curd processing. Kraft Heinz Company anchors North American retail distribution through controlled shelf-space agreements with mass-market grocers. Arla Foods differentiates via specialized whey protein separation technology that preserves texture in lower-cholesterol formulations.
Low cholesterol cheese denotes dairy products manufactured with reduced saturated fat and cholesterol content, typically achieved through modified milk fat blending, enzymatic fat reduction, or vegetable oil substitution, yielding compositions under 2% milk fat for standardized variants. The primary commercial purpose centers on delivering familiar cheese functionality—melt, stretch, and flavor release—to consumers managing cardiovascular risk or adhering to clinician-advised dietary protocols. Cream cheese and mozzarella variants command the largest current volume positions within the product type dimension, while shredded and spreadable forms capture disproportionate margin pools due to convenience premiums and food service procurement scale. Snacking and cooking applications drive the fastest application-segment expansion, as health-positioned retail brands reformulate portable cheese formats for single-occasion consumption.
The FDA governs cholesterol labeling claims through its nutrient content regulations, while the USDA oversees Grade A dairy plant inspections that affect low-fat cheese production eligibility. EFSA's health claim assessments in Europe shape which cardiovascular benefit statements manufacturers may deploy on packaging, directly influencing consumer pull-through effectiveness. Stakeholders must monitor evolving sodium reduction mandates alongside cholesterol targets, as dual-nutrient reformulation will determine next-generation product viability and clean-label positioning.
Market Dynamics
Dual-nutrient reformulation pressure is compressing formulation timelines as manufacturers simultaneously target cholesterol reduction and sodium limits mandated by divergent regulatory frameworks across major dairy markets.
Growth Catalysts
- Preventive Cardiology Protocols:Clinician-advised dietary interventions for cardiovascular risk management are expanding patient eligibility for reduced-fat dairy recommendations in outpatient settings.
- EFSA Health Claim Pathways:Approved cardiovascular benefit statements on packaging are accelerating consumer pull-through effectiveness in European retail channels.
- Enzymatic Fat Modification:Advanced lipase applications now enable cholesterol reduction without compromising melt functionality in processed cheese matrices.
Market Restraints
- Butterfat Supply Concentration:Modified milk fat sourcing depends on concentrated dairy cooperative networks in Wisconsin and Normandy, creating input vulnerability.
- Texture Degradation Thresholds:Current whey protein separation methods hit organoleptic limits below 1.5% milk fat, constraining ultra-low cholesterol positioning.
- Vegetable Oil Substitution Caps:FDA standards of identity restrict non-dairy fat incorporation in standardized cheese categories, blocking hybrid formulation routes.
Strategic Opportunities
- Food Service Direct Procurement:Healthcare and corporate cafeteria operators are establishing bypass relationships with reduced-fat curd processors, disintermediating traditional distribution.
- Single-Occasion Format Expansion:Portable snacking applications in portion-controlled packaging command margin premiums absent from bulk commodity cheese sales.
- Clean-Label Convergence:Fermentation-derived cholesterol reducers paired with natural sea salt replacers satisfy simultaneous clean-label and dual-nutrient targets.
Industry Challenges
- Dairy Protein Specialist Scarcity:Formulation chemists with simultaneous expertise in enzymatic fat modification and texture science command compensation premiums that strain R&D budgets.
- Dual Certification Timelines:Parallel FDA cholesterol claim verification and USDA Grade A plant recertification extend product launch windows by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Cholesterol Cheese Market |
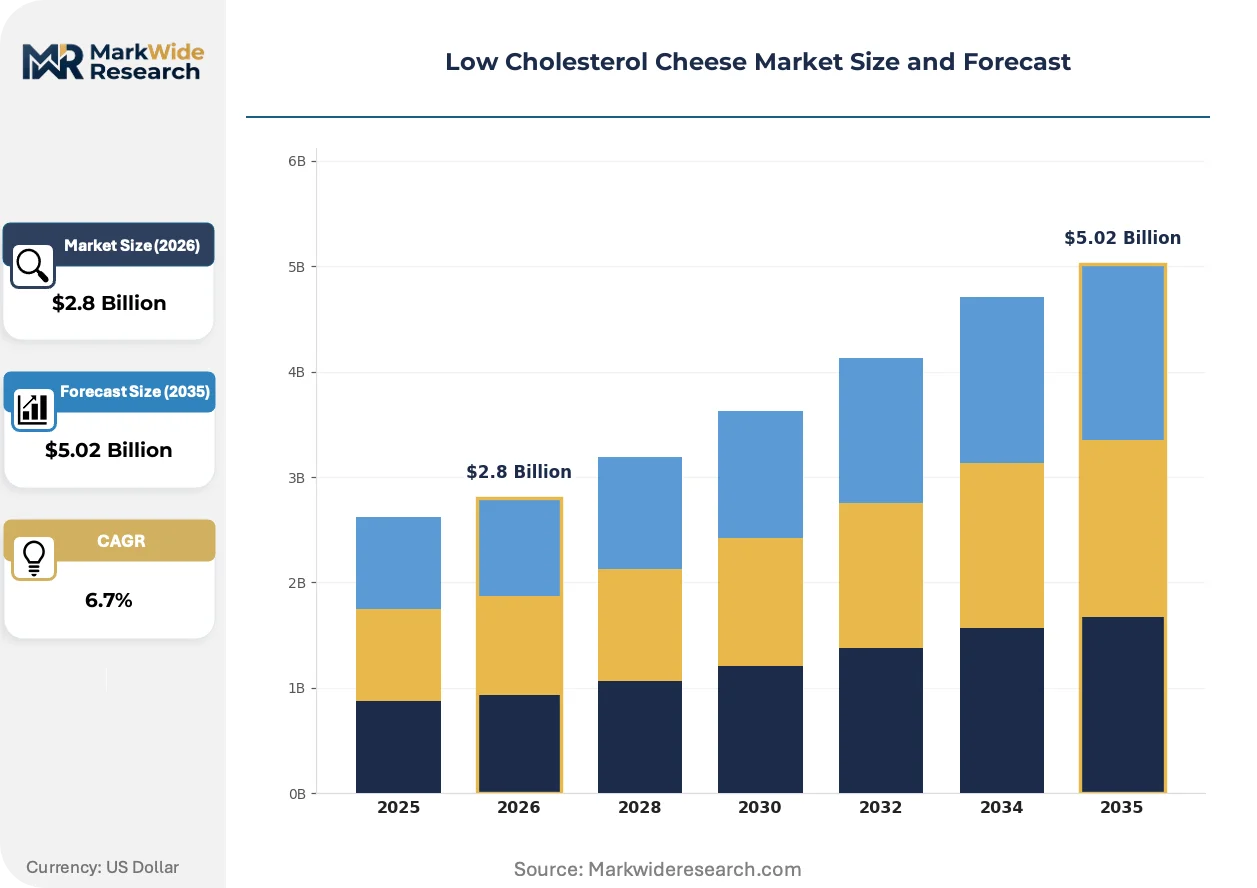
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream Cheese, Cottage Cheese, Cheddar, Mozzarella Application: Snacking, Cooking, Baking, Spreads End User: Health-Conscious Consumers, Restaurants, Retailers, Food Service Form: Block, Sliced, Shredded, Spreadable |
| Companies Covered | Kraft Heinz Company, Arla Foods, Lactalis Group, Saputo Inc., Dairy Farmers of America, Bel Group, FrieslandCampina, Nestlé S.A., Fonterra Co-operative Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Cholesterol Cheese Market Evolving Landscape
Formulation science is pivoting toward biomimetic approaches that replicate full-fat sensory profiles through structural engineering rather than simple fat replacement, reshaping competitive investment priorities.
Microencapsulated omega-3 enrichment is migrating from premium positioning toward mass-market mozzarella and cream cheese variants. Mid-tier retail brands in Germany and the Netherlands are adopting this technology at compressed three-year adoption cycles. The shift is enabling cardiovascular-positioned products to compete on price parity with conventional reduced-fat alternatives while delivering differentiated nutrient density claims.
EFSA's 2023 updated guidance on saturated fat health claims is forcing reformulation of products previously marketed on cholesterol reduction alone. Manufacturers must now demonstrate compositional thresholds for both nutrients to retain packaging permissions. French and Italian processors face the steepest compliance burden given their legacy reliance on single-nutrient positioning in export markets.
Hospital procurement consortia are consolidating vendor panels for patient feeding programs, compressing supplier counts from twelve to three in major US metropolitan systems. Group purchasing organizations now mandate dual-nutrient compliance as a qualification threshold, not a preference. This concentration is most visible in the Northeast corridor, where aging demographics have expanded institutional demand for cardiac-appropriate menu options.
Low Cholesterol Cheese Market Segmentation
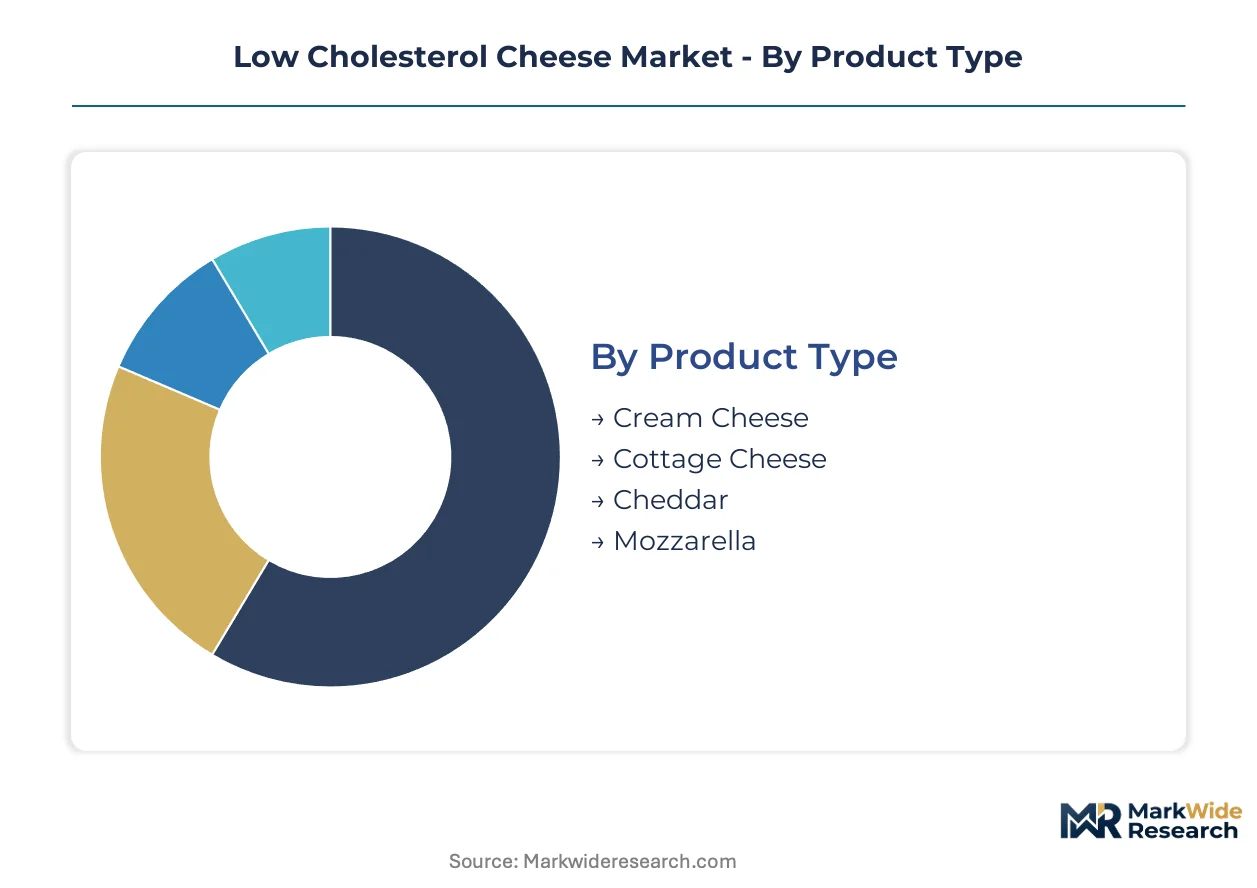
Segmentation in low cholesterol cheese reveals how formulation constraints and consumption occasions fragment commercial opportunity. Each dimension carries distinct margin profiles, regulatory exposure, and supply chain requirements that reshape competitive priorities.
Product Type:
After-sales service intensity varies sharply across product types, with spreadable formats demanding technical support for texture stability while block formats require minimal intervention.
- Cream Cheese:Spreadable matrix stabilized through modified whey protein concentrates achieves under 2% milk fat while preserving mouthfeel. Demand clusters in United States retail channels where aging demographics and clinician-advised dietary protocols drive refrigerated section placement.
- Mozzarella:Shredded variants for food service applications employ enzymatic fat modification to maintain melt stretch below standard cholesterol thresholds. Hospital procurement consortia in the Northeast corridor specify this format for cardiac-appropriate patient menus, creating institutional volume concentration.
- Cheddar:Aged profiles face organoleptic limits when milk fat drops below 1.5%, constraining ultra-low positioning.
- Cottage Cheese:Curd-based structure accommodates fat reduction through skim milk sourcing without enzymatic intervention.
By volume, Mozzarella leads. By growth pace, Cream Cheese is ahead.
Application:
Cost tier differentiation separates commodity bulk sales from premium-positioned convenience formats commanding disproportionate margins.
- Snacking:Single-occasion portion packaging captures premium pricing absent from bulk commodity channels. Portable formats reformulated for cardiovascular-positioned retail brands concentrate demand in German and Dutch markets where EFSA health claim permissions accelerate consumer pull-through.
- Cooking:Shredded and block forms for home meal preparation balance functionality against cholesterol targets. United States mass-market grocers drive volume through controlled shelf-space agreements that prioritize dual-nutrient compliant SKUs.
- Baking:Melt performance requirements constrain formulation flexibility more severely than snacking applications.
- Spreads:Texture degradation thresholds below 1.5% milk fat limit ultra-low cholesterol positioning in this application.
Snacking commands the steepest price premiums. Cooking generates the largest absolute tonnage.
End User:
Customer type determines procurement pathway complexity, with institutional buyers imposing certification burdens that exclude smaller processors.
- Health-Conscious Consumers:Retail purchasers responding to FDA-updated nutrition labeling requirements for cholesterol claims drive reformulation investment. Preventive cardiology protocols in United States outpatient settings expand patient eligibility for reduced-fat dairy recommendations.
- Food Service:Healthcare and corporate cafeteria operators establish direct procurement relationships with reduced-fat curd processors, disintermediating traditional distribution. Group purchasing organizations mandate dual-nutrient compliance as qualification threshold in major metropolitan systems.
- Restaurants:Menu labeling requirements in select jurisdictions create compliance fragmentation across operating regions.
- Retailers:Private-label leasing arrangements narrow capital barriers for mid-tier entrants seeking shelf placement.
Food Service exhibits the most rapid procurement consolidation. Health-Conscious Consumers represent the broadest addressable base.
Form:
Supply concentration in modified milk fat sourcing from Wisconsin and Normandy dairy cooperative networks shapes form-specific production economics.
- Shredded:Food service procurement scale and convenience premiums combine to capture disproportionate margin pools. EFSA's updated saturated fat health claim guidance forces reformulation of products previously marketed on cholesterol reduction alone, with French and Italian processors facing steepest compliance burden in export markets.
- Spreadable:Cream cheese and processed variants employ specialized whey protein separation technology to preserve texture in lower-cholesterol formulations. Arla Foods anchors European supply through captive technology deployment.
- Block:Standardized cheese categories face FDA standards of identity restrictions on non-dairy fat incorporation.
- Sliced:Deli counter applications require melt functionality that enzymatic fat modification now enables without matrix compromise.
Shredded forms dominate food service volume. Spreadable formats climb the fastest in retail premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortia and aging demographics concentrate buyer power in the United States, while EFSA health claim permissions accelerate retail pull-through in German and Dutch markets. Preventive cardiology protocols and clinician-advised dietary interventions reshape demand geography across developed dairy markets.
United States
FDA-updated nutrition labeling requirements for cholesterol claims drive reformulation investment among domestic processors. Preventive cardiology protocols in outpatient settings expand patient eligibility for reduced-fat dairy recommendations. Hospital procurement consortia in the Northeast corridor consolidate vendor panels from twelve to three suppliers, mandating dual-nutrient compliance for cardiac-appropriate patient menus.
Germany
EFSA health claim assessments determine which cardiovascular benefit statements manufacturers deploy on packaging, directly influencing consumer pull-through effectiveness. Mid-tier retail brands adopt microencapsulated omega-3 enrichment technology at compressed three-year adoption cycles. The country's dairy processing clusters concentrate reformulation expertise for enzymatic fat modification applications.
France
EFSA's 2023 updated guidance on saturated fat health claims forces reformulation of products previously marketed on cholesterol reduction alone. French processors face the steepest compliance burden given legacy reliance on single-nutrient positioning in export markets. Normandy dairy cooperative networks supply modified milk fat inputs that sustain cost advantages in reduced-fat curd processing.
Netherlands
Specialized whey protein separation technology preserves texture in lower-cholesterol formulations, anchoring European supply capabilities. Portable snacking formats reformulated for cardiovascular-positioned retail brands concentrate demand in Dutch markets where health claim permissions accelerate category penetration. FrieslandCampina leverages captive dairy supply infrastructure across regional sourcing networks.
Canada
Health Canada oversees nutrition labeling requirements that parallel FDA cholesterol claim frameworks, creating regulatory alignment for cross-border product development. Dairy Farmers of America and Canadian cooperative networks coordinate modified milk fat sourcing across the Great Lakes processing corridor. Mass-market grocers drive volume through controlled shelf-space agreements prioritizing dual-nutrient compliant SKUs.
Low Cholesterol Cheese Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation concentrates among dairy cooperative networks and multinational packaged food conglomerates with captive refrigerated distribution infrastructure. Three archetypes dominate: scale-driven mass-market suppliers, technology-specialist texture engineers, and private-label lease operators. Competitive moves center on strategic partnerships with food service procurement consortia and portfolio diversification into single-occasion snacking formats.
Within the scale-driven tier, Kraft Heinz Company and Lactalis Group exemplify channel-controlling archetypes with mass-market retail anchoring positions. Arla Foods occupies a technology-specialist position through specialized whey protein separation capabilities. These three entities represent the competitive spectrum from North American retail dominance to European sourcing network integration and texture-preservation engineering.
| Leading Market Players |
|---|
| Kraft Heinz Company |
| Arla Foods |
| Lactalis Group |
| Saputo Inc. |
| Dairy Farmers of America |
| Bel Group |
| FrieslandCampina |
| Nestlé S.A. |
| Fonterra Co-operative Group |
| Others |
Value Network & Pricing Analysis
Modified milk fat sourcing from Wisconsin and Normandy dairy cooperative networks feeds directly into margin capture at the shredded and spreadable form tiers, where convenience premiums and food service procurement scale concentrate profitability.
Pricing Analysis
Dual-nutrient compliance certification creates the primary spread between premium-positioned and commodity-grade low cholesterol cheese offerings. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, with enzymatic fat modification and specialized whey protein separation commanding tier-one positioning. Cost compression in mid-tier private-label segments is intensifying because asset-light co-manufacturing arrangements proliferate. Health-conscious retail purchasers show highest price sensitivity, while hospital procurement consortia and corporate cafeteria operators demonstrate lowest sensitivity due to mandated dual-nutrient qualification thresholds.
Supply Chain Analysis
FDA standards of identity restrictions on non-dairy fat incorporation function as de facto export controls, limiting hybrid formulation routes for standardized cheese categories. Geographic supply concentration centers on Wisconsin and Normandy for modified milk fat inputs, with Dutch and German processing clusters for specialized whey protein separation technology. Raw material dependencies include skim milk sourcing, enzymatic fat modification inputs, and modified whey protein concentrates. Single-source vulnerability runs through concentrated dairy cooperative networks in core sourcing regions. Distribution runs through controlled shelf-space agreements with mass-market grocers and direct procurement relationships with food service operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists with simultaneous expertise in enzymatic fat modification and texture science command compensation premiums that constrain R&D bandwidth, making specialized talent retention the critical capability gap for competitive positioning.
For Market Incumbents: Build captive technology moats around specialized whey protein separation capabilities that preserve texture below 2% milk fat thresholds. Deepen backward integration into modified milk fat sourcing across Wisconsin and Normandy cooperative networks to secure input cost advantages. Defend against private-label lease operators by accelerating single-occasion format expansion in portion-controlled packaging where convenience premiums resist commodity pressure. For New Entrants and Emerging Players: Establish a beachhead in clean-label fermentation-derived cholesterol reducer applications paired with natural sea salt replacers. Target the portable snacking segment in German and Dutch markets where EFSA health claim permissions accelerate consumer pull-through effectiveness. Pursue asset-light co-manufacturing arrangements to bypass capital-intensive curd processing infrastructure and secure shelf placement through private-label leasing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier dairy processors holding FDA cholesterol claim verification but lacking USDA Grade A plant recertification for dual-nutrient compliance. Five-to-ten year viability hinges on portfolio diversification into single-occasion snacking formats and food service direct procurement relationships. Watch hospital procurement consortia vendor panel consolidation as the inflection signal for institutional demand concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Fat Modification Scale-Up | Advanced lipase applications now enable cholesterol reduction without compromising melt functionality in processed cheese matrices. |
| Single-Occasion Format Expansion | Portable snacking applications in portion-controlled packaging command margin premiums absent from bulk commodity cheese sales. |
| Food Service Direct Procurement | Healthcare and corporate cafeteria operators establish bypass relationships with reduced-fat curd processors, disintermediating traditional distribution. |
| Clean-Label Fermentation Partnership | Fermentation-derived cholesterol reducers paired with natural sea salt replacers satisfy simultaneous clean-label and dual-nutrient targets. |
| Dual-Certification Investment | Parallel FDA cholesterol claim verification and USDA Grade A plant recertification extend product launch windows, creating regulatory barrier advantages. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dairy processing plant managers, formulation chemists at reduced-fat curd processors, retail category buyers, hospital procurement consortium directors, and food service distribution executives. Secondary validation drew from FDA nutrient content regulations, USDA Grade A dairy plant inspection records, EFSA health claim assessment databases, customs and trade data on modified milk fat inputs, and SEC filings from publicly traded packaged food conglomerates. Bottom-up volume modeling and top-down value triangulation were cross-referenced to ensure consistency.
Calibration across the analysis window employed segment-level growth rate derivation from product type, application, end user, and form dimensions, with additional modeling of regulatory compliance tier and enzymatic versus non-enzymatic formulation pathways. CAGRs were computed from annualized progression rates across the projection horizon. Key forecast inputs included aging demographic penetration curves for preventive cardiology protocols and EFSA health claim permission timelines for cardiovascular benefit statements.
Stress conditions across butterfat supply concentration, dual-certification timeline extensions, and sodium reduction mandate convergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on clinician-advised dietary intervention adoption and institutional procurement consolidation trajectories. Material shifts in FDA standards of identity or EFSA saturated fat health claim thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
South America Dairy Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
US Cheese Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Condensed Milk Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
Paneer Market
Dairy Products
Condensed Whey Market
Dairy Products
Dairy Products Market
Dairy Products
Dairy Concentrates Market
Dairy Products
Global Cream Cheese Market
Dairy Products
A2 Milk Market
Dairy Products
Recombined Milk Products Market
Dairy Products
Yogurt Drink Market