
 Hyperlocal Grocery Delivery Market | 2026-2036
Hyperlocal Grocery Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperlocal Grocery Delivery Market Foresight
GDPR and the EU AI Act are shifting compliance burdens onto algorithmic routing and customer data handling, raising the cost-of-entry for new platform entrants. Blinkit leverages its dark-store density to sustain sub-15-minute fulfillment in Indian metros. Getir anchors its position through backward integration into private-label sourcing, controlling margin pools that pure intermediaries cannot match. Zepto competes by specializing in ultra-small basket economics, navigating the operational complexity of high-frequency, low-value orders.
Hyperlocal grocery delivery denotes the fulfillment of food and household essentials from proximate micro-warehouses or partner stores to consumers within radii typically under five kilometers, utilizing temperature-controlled packaging and dynamic route optimization to preserve cold-chain integrity. The primary commercial purpose is collapsing the time gap between purchase intent and product receipt, converting unplanned consumption needs into captured transactions. Scheduled delivery and on-demand delivery together occupy the structural center, though subscription services now concentrate the most predictable margin pools by locking in recurring revenue and reducing per-order acquisition costs. Fresh produce leads in volume throughput, yet packaged foods sustain higher contribution margins due to longer shelf stability and lower spoilage rates.
FDA food safety protocols, EPA last-mile emissions standards, and state-level labor classification rules in California collectively shape operational design, fleet composition, and worker cost structures across the United States. In Europe, EFSA nutritional labeling requirements and REACH-compliant packaging materials constrain product assortment and supplier eligibility. Stakeholders must monitor how evolving gig-economy legislation reclassifies delivery personnel, as this single variable threatens to restructure unit economics faster than any technology investment.
Market Dynamics
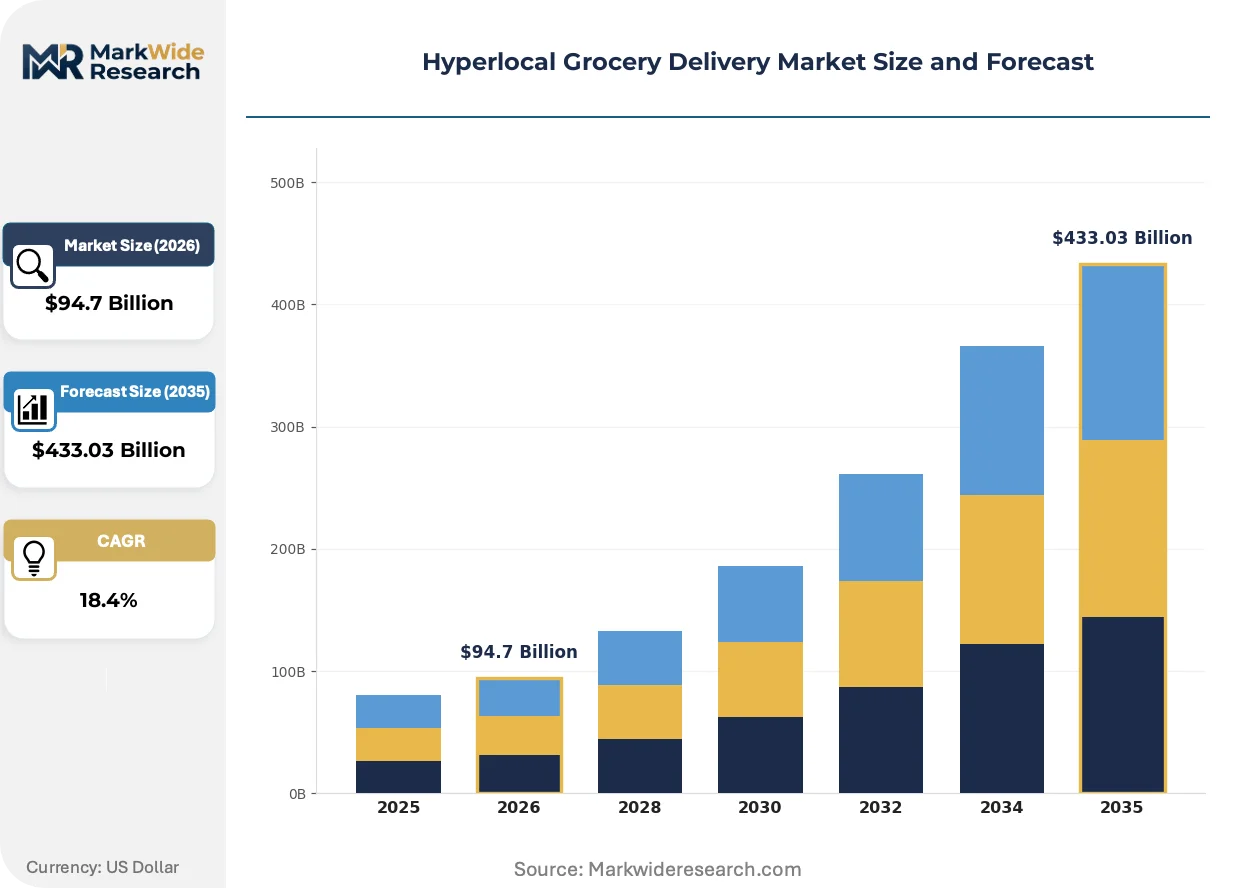
Algorithmic route optimization and dark-store densification are compressing fulfillment windows below fifteen minutes, forcing capital reallocation toward micro-fulfillment infrastructure and temperature-controlled last-mile assets.
Growth Catalysts
- EU Green Deal packaging mandates:Reusable thermal bag requirements and electric fleet quotas are accelerating fleet turnover and creating procurement scale advantages for compliant operators.
- Smartphone penetration in Indian metros:Dense urban household clustering and mobile-first ordering behavior sustain sub-10-minute delivery economics through demand pooling.
- Dynamic batching algorithms:Machine learning-powered order consolidation is raising driver utilization rates and reducing per-delivery labor costs in high-frequency zones.
Market Restraints
- Perishable spoilage rates:Fresh produce handling requirements inflate cold-chain packaging costs and compress margins on high-volume, low-ticket baskets.
- Labor reclassification risk:California AB5-style gig-worker employment rules threaten to restructure variable cost bases into fixed obligations with benefits liabilities.
- Dark-store real estate scarcity:Premium urban infill locations in London, Berlin, and Singapore command rents that erode unit economics below viability thresholds.
Strategic Opportunities
- Private-label backward integration:Captive sourcing of packaged foods and household staples captures margin pools that pure intermediary models cannot access.
- Subscription lock-in models:Recurring revenue structures reduce customer acquisition costs and stabilize demand forecasting for inventory positioning.
- India tier-2 city expansion:Nascent smartphone penetration in Pune, Hyderabad, and Ahmedabad offers first-mover density advantages before competitive saturation.
Industry Challenges
- Temperature-controlled packaging compliance:EFSA cold-chain integrity standards and FDA food safety protocols require continuous monitoring infrastructure that strains capex budgets.
- Algorithmic routing talent scarcity:Shortage of operations research specialists capable of optimizing stochastic demand patterns limits platform differentiation.
- Legacy POS integration friction:Partner grocery store inventory systems lack API standardization, causing stockout misalignments and substitution escalations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperlocal Grocery Delivery Market |
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $433.03 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Produce, Dairy Products, Packaged Foods, Snacks Delivery Mode: Scheduled Delivery, On-Demand Delivery, Subscription Service, Contactless Delivery Customer Type: Households, Businesses, Restaurants, Offices Order Size: Small Orders, Medium Orders, Large Orders, Bulk Orders |
| Companies Covered | Blinkit, Picnic, Getir, Weee!, Good Eggs, JOKR, Zapp, HappyFresh, Zepto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperlocal Grocery Delivery Market Shifts & Advancements
Electrification of last-mile fleets and AI-powered demand forecasting are restructuring capital deployment patterns, while regulatory pressure on packaging waste forces material innovation cycles.
Autonomous delivery pods are electrifying urban fulfillment networks by eliminating driver costs from short-radius routes. European operators in Amsterdam and Paris are piloting sidewalk-capable robots for sub-2-kilometer drops, compressing marginal delivery costs toward energy-only economics. This modality is electrifying the competitive calculus for dense metropolitan zones where labor availability constrains scale.
REACH-compliant packaging material mandates are eliminating single-use plastics from thermal protection systems. The EU F-Gas Regulation is simultaneously phasing out hydrofluorocarbon-based cooling units, forcing cold-chain equipment replacement cycles. European dark-store operators are responding with phase-change material trials and reusable container deposit systems that align with Extended Producer Responsibility frameworks.
Impulse-driven micro-basket purchasing is displacing weekly stock-up trips among urban millennials and dual-income households. Quick-commerce platforms are capturing unplanned consumption occasions that traditional supermarkets served through convenience proximity. This behavioral pivot is most pronounced in Mumbai, São Paulo, and Seoul, where apartment density and late-night ordering windows converge.
Hyperlocal Grocery Delivery Market Segmentation
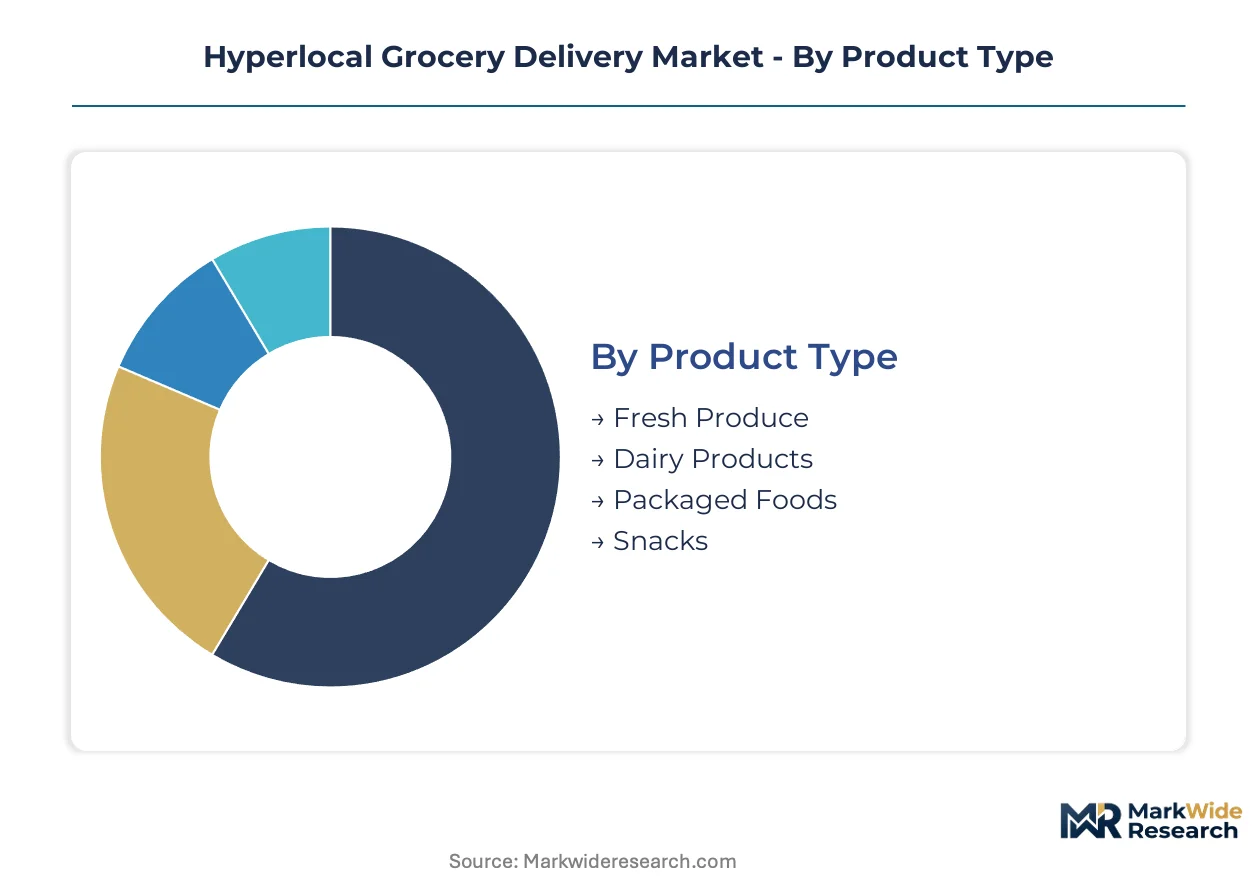
Hyperlocal grocery delivery operators calibrate inventory depth, fleet deployment, and margin targets against distinct demand profiles. Segmentation reveals where cold-chain investments concentrate and which order patterns sustain unit economics.
Product Type:
Customization intensity varies sharply across this category, from standardized packaged goods to perishables requiring temperature-controlled handling protocols.
- Fresh Produce:Fruits and vegetables demand continuous cold-chain integrity from dark-store to doorstep. Indian metros and São Paulo apartment clusters drive the highest throughput volumes, though spoilage rates compress margins on low-ticket baskets.
- Dairy Products:Milk, cheese, and yogurt require refrigerated transport with strict FSSAI and FDA temperature thresholds. Demand concentrates among dual-income households in dense European cities where subscription lock-in reduces acquisition costs.
- Packaged Foods:Shelf-stable grains, sauces, and ready meals offer longer inventory cycles and higher contribution margins. Indian quick-commerce platforms capture significant volume here through private-label backward integration.
- Snacks:Impulse-driven confectionery and savory items sustain late-night ordering windows in Seoul and Mumbai. Batched delivery algorithms improve driver utilization on these high-frequency, low-weight orders.
Most installed capacity flows through Packaged Foods. Expansion is steepest in Fresh Produce.
Delivery Mode:
Cost tier separation distinguishes premium immediacy from scheduled efficiency, with subscription models anchoring the most predictable revenue streams.
- Scheduled Delivery:Pre-booked time slots enable route consolidation and higher vehicle utilization. Berlin and London households favor this mode for weekly stock-up trips, reducing per-delivery labor costs through demand pooling.
- On-Demand Delivery:Sub-30-minute fulfillment windows command premium pricing and require dense dark-store networks. Indian operators sustain this mode through metro clustering and dynamic batching algorithms.
- Subscription Service:Recurring revenue structures lock in customer lifetime value and stabilize demand forecasting. European platforms leverage this mode to meet EU Green Deal packaging compliance through reusable container deposit systems.
- Contactless Delivery:Doorstep drop protocols reduce handoff time and labor friction. Singapore and Tokyo apartment buildings with dedicated delivery lockers enable this mode at marginal cost increments.
Scheduled Delivery carries the highest volume throughput. Subscription Service is climbing the fastest as platforms prioritize retention over acquisition.
Customer Type:
Application context determines basket composition, with commercial accounts demanding volume reliability and households driving frequency.
- Households:Individual and family consumers generate the majority of order frequency across all geographies. Indian tier-2 cities like Pune and Ahmedabad represent the steepest expansion trajectory as smartphone penetration deepens.
- Businesses:Corporate pantry replenishment and small retail stock-ups require invoicing integration and bulk handling. European operators face REACH-compliant packaging mandates on these larger-format deliveries.
- Restaurants:Just-in-time ingredient sourcing demands precise timing and quality consistency. São Paulo and Mexico City kitchen clusters sustain dedicated fleet segments for this vertical.
- Offices:Midday snack and beverage replenishment concentrates in business districts with elevator access and loading dock infrastructure. Seoul's Gangnam district exemplifies this density pattern.
Households absorb the dominant share of platform investment. Restaurants are gaining share fastest as foodservice digitization accelerates.
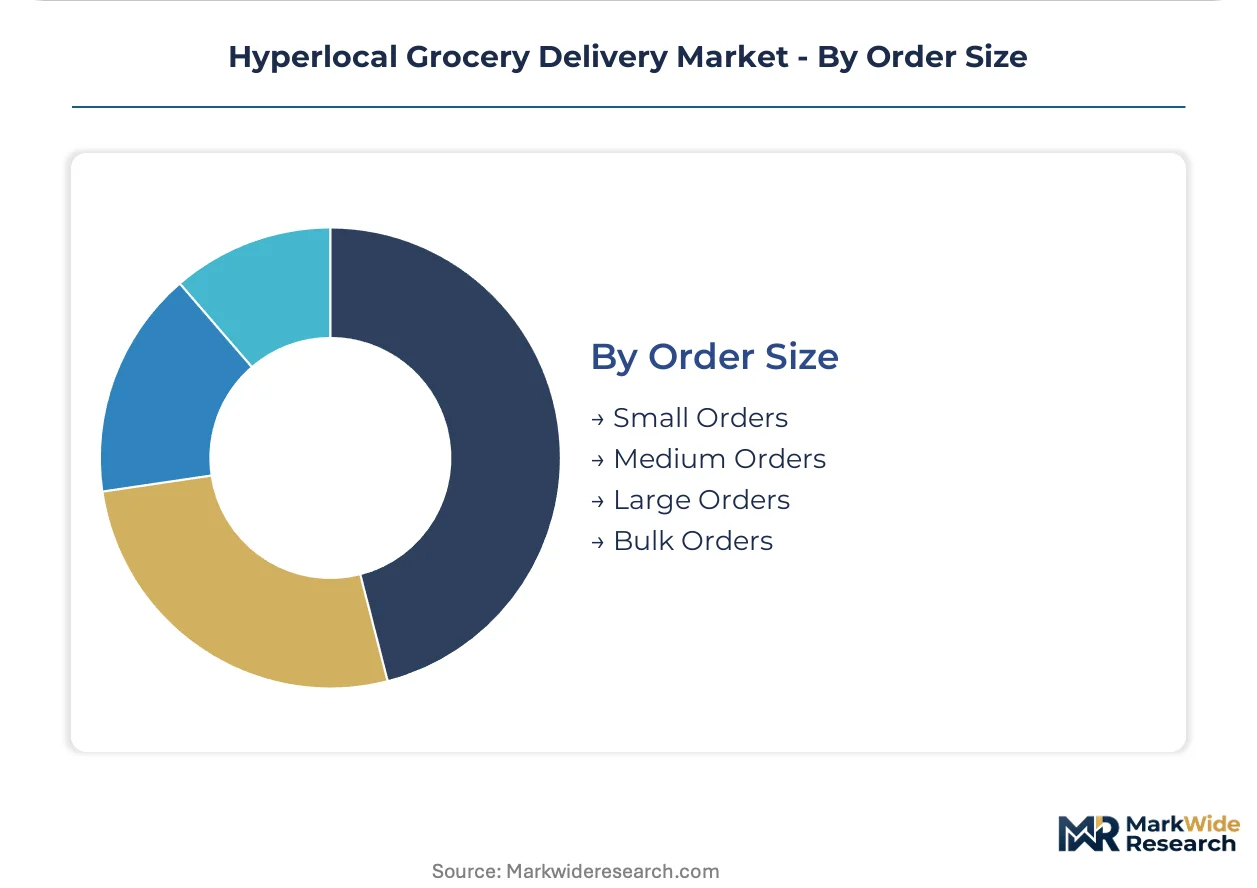
Order Size:
Volume thresholds dictate warehouse configuration, with small baskets requiring micro-fulfillment proximity and bulk orders leveraging centralized inventory.
- Small Orders:Sub-5-item baskets dominate impulse purchasing and late-night occasions. Zepto and similar specialists optimize dark-store layouts for this segment through vertical racking and picker efficiency.
- Medium Orders:Weekly replenishment trips with 10-20 items balance convenience against delivery fee tolerance. European subscription models concentrate retention efforts here.
- Large Orders:Family stock-ups and event preparation require vehicle capacity expansion and extended handling windows. Indian festival seasons drive seasonal spikes in this segment.
- Bulk Orders:Institutional and commercial volumes justify dedicated fleet allocation and palletized handling. FSSAI bulk transport regulations govern this mode in India.
Small Orders command the densest dark-store footprint. Bulk Orders are expanding most quickly as B2B channels digitize procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperlocal grocery delivery emerged from European urban density experiments in Amsterdam and Berlin, then scaled through Indian metro smartphone penetration and American coastal city convenience culture. The current footprint clusters around five national markets where regulatory frameworks and infrastructure investments now determine competitive viability.
United States
Coastal metropolitan corridors sustain the highest per-capita order frequency, with FDA food safety protocols governing cold-chain integrity across state lines. EPA last-mile emissions standards in California and New York are accelerating electric fleet procurement timelines. San Francisco Bay Area and New York City operators face AB5-style labor reclassification pressures that threaten to convert variable gig costs into fixed employment obligations.
India
Mumbai, Bangalore, and Delhi-NCR density patterns enable sub-10-minute fulfillment economics through demand pooling and dark-store proximity. FSSAI temperature thresholds for dairy and fresh produce mandate continuous monitoring infrastructure that strains capex budgets. Pune and Hyderabad represent the steepest expansion trajectory as smartphone penetration deepens in tier-2 urban clusters.
Germany
Berlin and Munich household clustering supports scheduled delivery consolidation and subscription lock-in models with superior retention metrics. REACH-compliant packaging materials and EU Green Deal electric fleet quotas are eliminating thermal bag single-use plastics and accelerating procurement scale advantages for compliant operators. The country's national environmental regulator enforces Extended Producer Responsibility frameworks on reusable container deposit systems.
United Kingdom
London's premium urban infill locations command rents that compress dark-store unit economics below viability thresholds for new entrants. GDPR and the EU AI Act shift compliance burdens onto algorithmic routing and customer data handling, raising cost-of-entry for platform operators. Manchester and Birmingham apartment density is emerging as secondary fulfillment zones with lower real estate friction.
Brazil
São Paulo apartment clustering and late-night ordering windows sustain impulse-driven micro-basket purchasing behavior distinct from weekly stock-up patterns. ANVISA nutritional labeling requirements constrain product assortment eligibility for imported packaged goods. Mexico City kitchen clusters in the Latin American corridor demonstrate dedicated fleet segmentation for restaurant ingredient sourcing verticals.
Hyperlocal Grocery Delivery Market Competitive Landscape
The competitive structure tilts toward dark-store specialists with captive sourcing capabilities rather than pure intermediary aggregators. Capital deployment now concentrates on micro-fulfillment infrastructure and temperature-controlled last-mile assets rather than customer acquisition spending. Two strategic archetypes dominate: vertically integrated operators controlling private-label margin pools, and algorithm-native platforms optimizing stochastic demand patterns through dynamic batching. Dominant competitive moves include backward integration into packaged food sourcing and geographic densification through dark-store network expansion.
Among dark-store density leaders, Blinkit and Zepto exemplify the Indian metro specialist archetype, while Getir anchors the European quick-commerce position through its integrated sourcing model. These three operators represent contrasting strategic bets on fulfillment speed versus margin capture, with each occupying a distinct position along the spectrum between pure logistics intermediation and captive retail control.
| Leading Market Players |
|---|
| Blinkit |
| Picnic |
| Getir |
| Weee! |
| Good Eggs |
| JOKR |
| Zapp |
| HappyFresh |
| Zepto |
| Others |
Supply & Pricing Matrix
EU Green Deal packaging mandates gate qualified supply and premium-tier pricing access, as REACH-compliant thermal materials and electric fleet quotas create procurement scale thresholds that only capitalized operators can clear. This environmental compliance layer stratifies the market between certified premium service tiers and cost-pressured economy offerings.
Pricing Analysis
Subscription-plus-transactional hybrid pricing stratifies across premium, standard, and economy tiers based on delivery speed guarantees and cold-chain certification grade. Price differentiation rests on dark-store proximity density and FSSAI temperature compliance investment. Cost compression in the economy tier is intensifying because Indian metro operators pool demand through dynamic batching algorithms. Small-basket impulse buyers in Mumbai and São Paulo exhibit the highest price sensitivity, while European dual-income households subscribing to scheduled delivery show the lowest.
Supply Chain Analysis
Reusable thermal bag return flows and deposit-system logistics add reverse-logistics complexity that pure forward-only operators cannot absorb. Cold-chain equipment manufacturing concentrates in China, Germany, and South Korea, with phase-change material innovation anchored in European chemical clusters. Dark-store fit-out draws from specialized urban-infill real estate brokers in London, Berlin, and Singapore. Single-source vulnerability runs through Chinese electric van battery supply. Distribution feeds from micro-fulfillment nodes through gig-driver networks to apartment clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Indian tier-2 city expansion offers lower real estate and labor costs against European regulatory compliance burdens that compress margins.
For Market Incumbents: Anticipate labor reclassification movements in California and European jurisdictions by pre-emptively piloting employment-model dark stores in Germany. Secure captive margin pools through backward integration into private-label packaged foods. Channel control through exclusive supplier agreements with FSSAI-certified dairies defends against pure-intermediary erosion. For New Entrants and Emerging Players: Begin with contactless delivery infrastructure in Singapore and Tokyo elevator-access buildings where marginal cost increments are lowest. The most penetrable white space sits in Indian tier-2 cities like Pune and Ahmedabad before competitive saturation. A subscription-first go-to-market angle stabilizes demand forecasting and reduces per-order acquisition burn. For Investors and Strategic Acquirers: Roll-up economics work for algorithm-native platforms with dynamic batching capabilities because stochastic demand optimization creates network effects that resist replication. Long-term viability favors operators controlling both dark-store density and private-label sourcing. The signal to watch is gig-worker employment rule finalization in California and EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| Dark-Store Network Densification | Micro-fulfillment proximity in Mumbai and Berlin compresses fulfillment windows below fifteen minutes. |
| Private-Label Backward Integration | Captive sourcing of packaged foods captures margin pools that pure intermediaries cannot access. |
| Electric Fleet Procurement | EPA emissions standards and EU Green Deal quotas accelerate compliant operator scale advantages. |
| Subscription Lock-In Models | Recurring revenue structures reduce customer acquisition costs and stabilize inventory positioning. |
| Algorithmic Route Optimization | Machine learning-powered demand forecasting raises driver utilization in high-frequency Indian metros. |
Research Methodology
Coverage spans the United States, India, Germany, the United Kingdom, and Brazil, with primary inputs from each market combining executive interviews and secondary validation. Dark-store operators, last-mile fleet managers, FSSAI compliance officers, and grocery category buyers provided operational data. Secondary sources include EPA emissions filings, EU ETS registry data, FSSAI temperature compliance records, and customs trade flows for cold-chain equipment. Bottom-up dark-store economics and top-down market sizing were triangulated against smartphone penetration benchmarks.
Granularity-level modeling tracked delivery mode, product type, customer segment, and order size across regional regulatory clusters. CAGRs were derived from demand-pooling elasticity in dense urban corridors and electric fleet turnover timelines. Forecast inputs incorporated EU Green Deal implementation pacing and Indian metro smartphone adoption curves throughout the projection horizon.
Several conditions sit outside the modeled scope, including unforeseen gig-worker reclassification rulings and phase-change material breakthroughs that could alter packaging cost structures. Forecasts reflect documented assumptions about urban household density patterns and cold-chain integrity standards. Practitioners should monitor California AB5-style legislation progression and EU F-Gas Regulation phase-out schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Lunch Takeout Market
Food Service
Russia Foodservice Market
Food Service
Commercial Restaurant Rangers Market
Food Service
China Online Food Delivery Market
Food Service
Catering Food Warmers Market
Food Service
United States Quick Service Restaurants Market
Food Service
India Foodservice Market
Food Service
Onboard Rail Catering Market
Food Service
United States Food Truck Market
Food Service
Commercial Kitchen Appliances Market
Food Service
Workplace Service Market
Food Service
Latin America Airport Quick Service Restaurant Market
Food Service
Restaurant Takeout Market
Food Service
Flat Top Grills Market
Food Service
Qatar Food Service Market
Food Service
North America Online Food Delivery Market