
 Saudi Arabia Camel Dairy Market | 2026-2036
Saudi Arabia Camel Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Camel Dairy Market Intelligence
Capital-intensity divergence between automated milking operations and traditional hand-milking cooperatives is bifurcating competitive dynamics across the Saudi Arabia camel dairy sector. Sawani leverages state-of-the-art rotary parlors to sustain volume leadership in fresh milk distribution. Al Wathba Camel Dairy anchors its position through integrated desert farming operations that control feed cultivation and herd genetics. Desert Farms differentiates via organic certification and direct-to-consumer subscription channels.
Camel dairy encompasses the collection, processing, and commercialization of milk derived from Camelus dromedarius, with raw milk typically containing 2.5–3.5% protein, 3–5% fat, and lower lactose than bovine alternatives, rendering it suitable for lactose-intolerant populations. The primary commercial purpose centers on delivering functional nutrition through fresh and value-added formats. Fresh milk commands the largest revenue pool among product types, while yogurt and cheese segments attract premium pricing from hospitality buyers. Supermarkets dominate distribution channel throughput, though online retail registers the fastest route expansion as cold-chain logistics mature.
SFDA pasteurization mandates and SASO quality labeling requirements shape product standards and market access for domestic processors. Halal certification protocols administered by the Saudi Ministry of Municipal and Rural Affairs further govern slaughter-free dairy sourcing claims. Stakeholders must monitor herd traceability investments and shelf-stable packaging innovations as decisive capability differentiators.
Market Dynamics
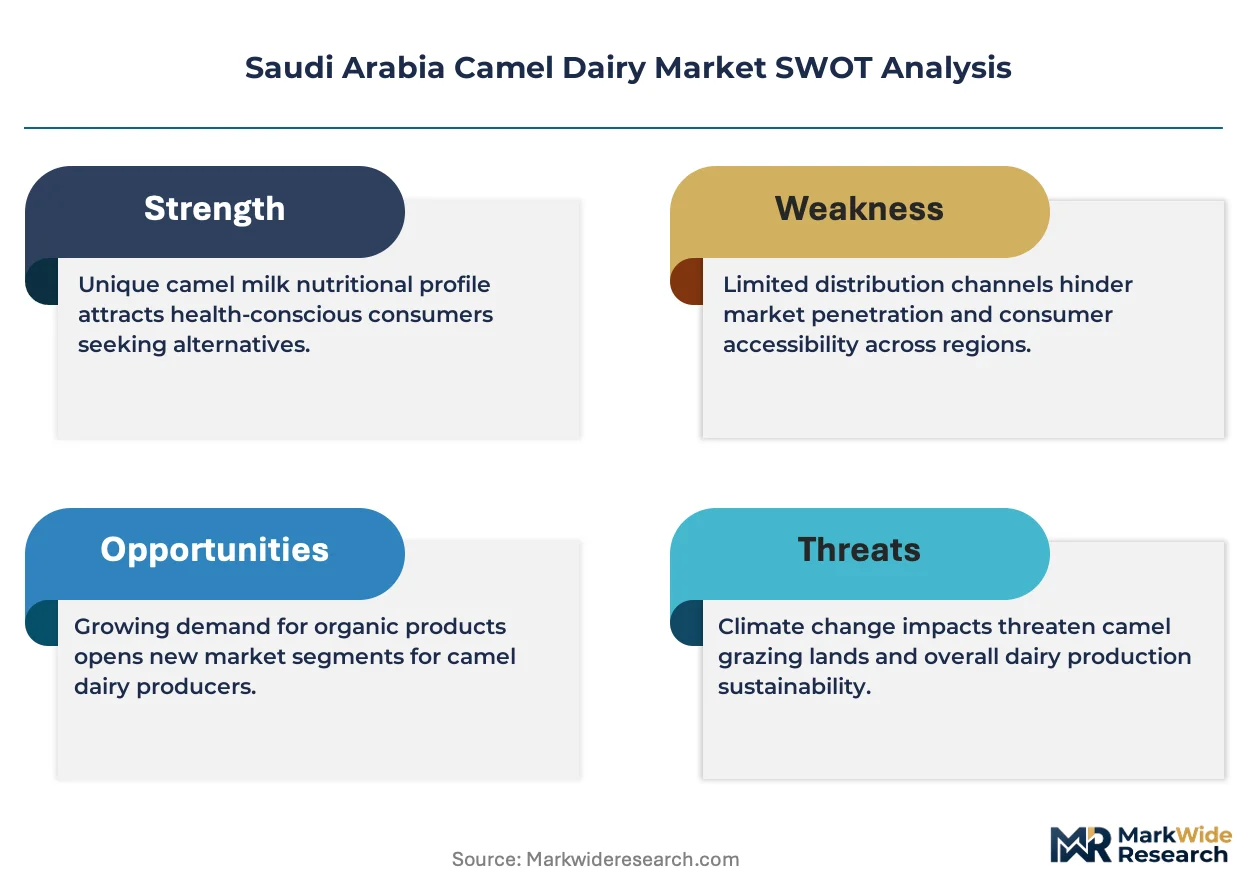
SFDA pasteurization mandates and SASO quality labeling requirements are compressing margins for smaller processors while rewarding operators with integrated cold-chain infrastructure and automated milking systems.
Growth Catalysts
- Functional Nutrition Demand:Health-conscious consumers in Riyadh's Central Region prioritize camel milk for its lower lactose content and elevated insulin-like protein concentrations.
- SFDA Regulatory Clarity:Standardized pasteurization protocols reduce consumer safety concerns and enable supermarket shelf placement for processed dairy formats.
- Hospitality Channel Expansion:Specialty cafés in Jeddah now feature camel milk beverages as signature menu items, creating premium pricing anchors for fresh milk suppliers.
Market Restraints
- Feed Input Volatility:Alfalfa and Rhodes grass prices fluctuate with groundwater allocation policies, squeezing margins for desert farming operations without captive fodder cultivation.
- Herd Genetic Bottleneck:Superior milk-yielding dromedary bloodlines concentrate among three established breeding programs, limiting expansion capacity for new entrants.
- Bovine Dairy Substitution:Cow milk maintains price advantages in institutional catering and mass retail, constraining camel dairy penetration in price-sensitive segments.
Strategic Opportunities
- Direct-to-Consumer Subscriptions:Cold-chain logistics maturation enables weekly home delivery of fresh camel milk to health-focused households in Dammam and Khobar.
- Organic Certification Differentiation:SASO organic standards create white space for pasture-raised claims that command 40% price premiums in upscale Riyadh supermarkets.
- Functional Ingredient Extraction:Lysozyme and lactoferrin isolation for nutraceutical applications opens pharmaceutical channel partnerships with Gulf-based supplement manufacturers.
Industry Challenges
- Veterinary Specialist Scarcity:Dromedary reproductive health expertise concentrates among aging practitioners, slowing herd expansion timelines for new operations.
- Halal Certification Complexity:Slaughter-free dairy sourcing claims require Ministry of Municipal and Rural Affairs verification that extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Camel Dairy Market |
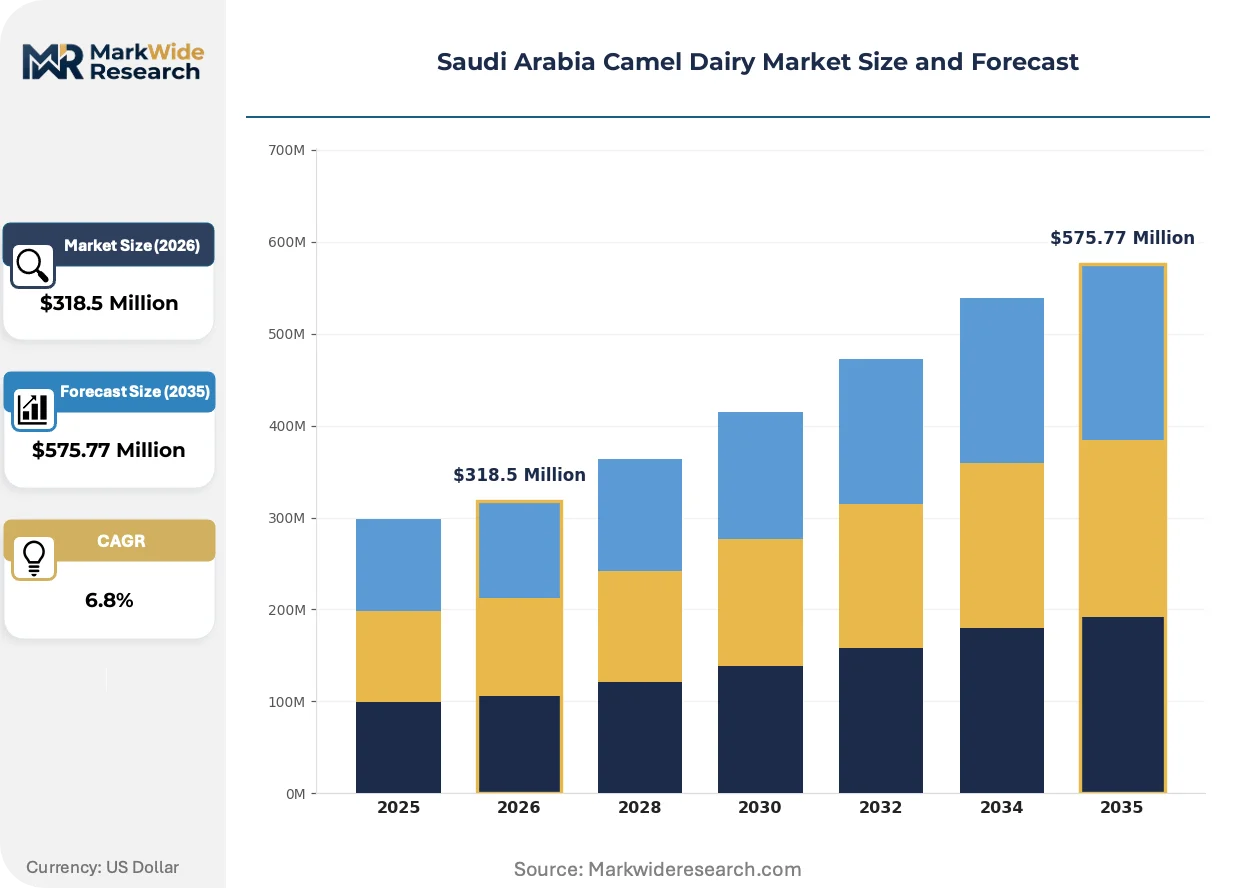
| Market Size in 2026 | $318.5 Million |
| Market Size in 2035 | $575.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Ice Cream Distribution Channel: Supermarkets, Online Retail, Farmers' Markets, Specialty Stores Customer Type: Individual Consumers, Restaurants, Cafés, Bakeries Packaging Type: Bottles, Tetra Packs, Jars, Pouches |
| Companies Covered | The Camel Milk Company, Al Mahra Camel Dairy, Sawani, Desert Farms, Al Wathba Camel Dairy, Camelicious, Al Nassma Camel Milk, Jumeirah Camel Dairy, Al Ain Dairy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Camel Dairy Market Strategic Shifts & Innovations
Automation and regulatory precision are compressing traditional operational models while opening premium positioning through traceability and functional ingredient extraction.
Automated rotary milking parlors with integrated somatic cell counting are miniaturizing the labor intensity gap between industrial operators and cooperative producers. Sawani and Al Wathba have deployed these systems across Central Region facilities, reducing per-liter labor costs by half. The technology is miniaturizing the viable scale threshold for commercial operations, enabling mid-sized entrants to achieve volume competitiveness without desert farming integration.
SFDA's 2024 tightening of pasteurization protocols requires continuous-flow thermal processing with automated temperature logging. Small processors lacking capital for equipment upgrades face market exit or contract manufacturing arrangements. Fresh milk distributors with compliant infrastructure are capturing shelf space formerly occupied by artisanal producers in Riyadh and Jeddah hypermarkets.
Subscription-based procurement is displacing traditional wholesale relationships in the premium segment. Health-conscious households in Riyadh's Diplomatic Quarter and Jeddah's Al Andalus district now schedule recurring deliveries through proprietary apps, bypassing supermarket markups. This channel shift concentrates customer data with integrated producers, enabling personalized product recommendations and loyalty pricing that supermarkets cannot replicate.
Saudi Arabia Camel Dairy Market Segmentation
Saudi Arabia's camel dairy sector fragments across product formats, procurement channels, and end-use applications that each carry distinct margin profiles and regulatory requirements. Understanding these divisions reveals where volume concentrates versus where premium pricing power accumulates.
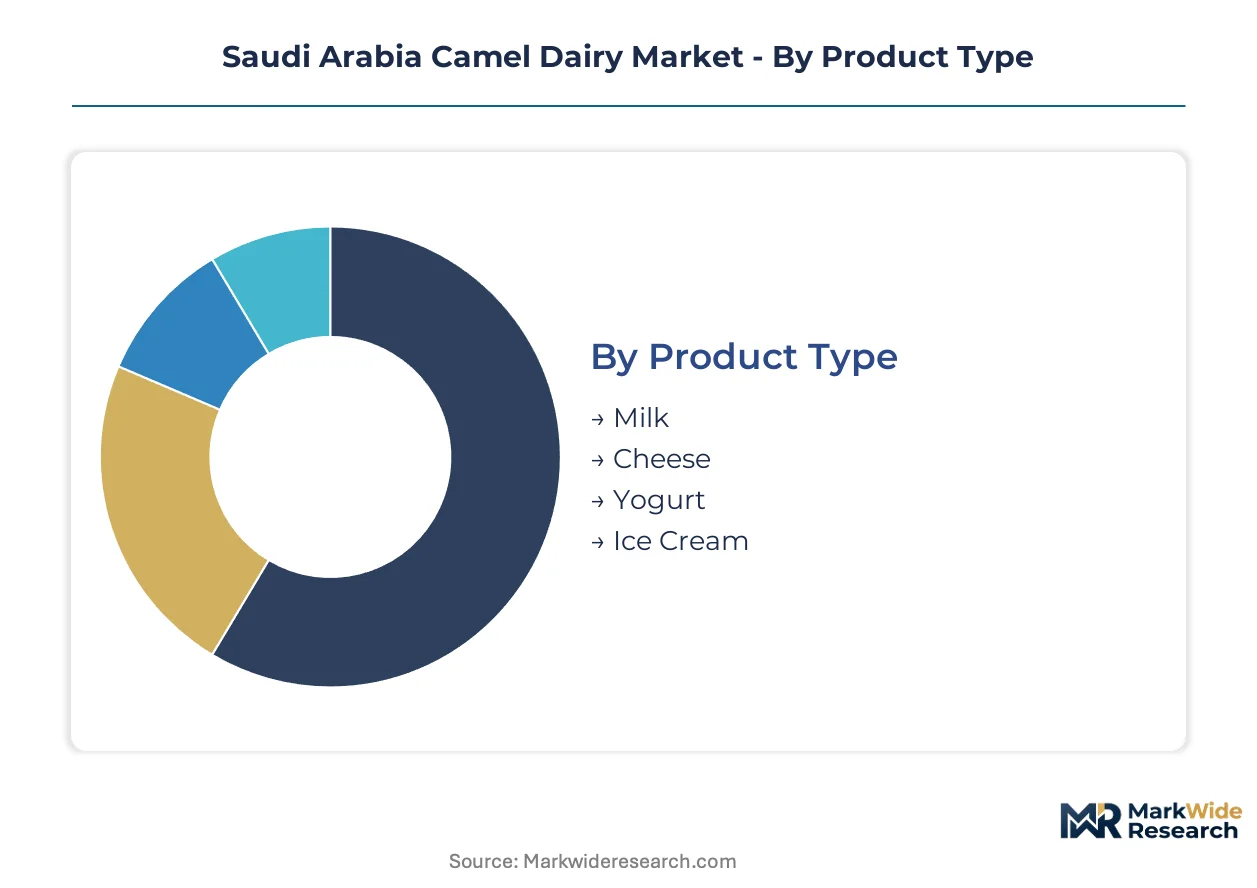
Product Type:
Fresh milk flows through supermarket cold chains and direct subscription models, while value-added formats penetrate hospitality and gift segments with differentiated margin structures.
- Milk:Raw and pasteurized liquid formats contain 2.5–3.5% protein and 3–5% fat with lower lactose than bovine alternatives. Central Region households around Riyadh drive procurement through weekly subscription deliveries and hypermarket purchases.
- Cheese:Soft and aged varieties command premium placement in Jeddah specialty stores and hotel F&B programs. Halal certification requirements from the Ministry of Municipal and Rural Affairs extend product launch timelines for new entrants.
- Yogurt:Probiotic positioning targets health-conscious consumers through pharmacy-adjacent retail and organic supermarket sections.
- Ice Cream:Novelty positioning in luxury hotel dessert menus and seasonal retail peaks during Ramadan and summer months.
By volume, Milk leads. By growth pace, Cheese is climbing the fastest.
Distribution Channel:
Channel selection determines compliance burden and customer data ownership, with integrated producers capturing margin through disintermediation.
- Supermarkets:Riyadh and Jeddah hypermarkets dominate throughput for pasteurized fresh milk and standard yogurt formats. SFDA-compliant cold-chain infrastructure serves as the gatekeeping capability for shelf access.
- Online Retail:Proprietary apps and third-party platforms enable subscription scheduling and loyalty pricing that bypass traditional wholesale markups. Dammam and Khobar households in the Eastern Province show strongest adoption for recurring delivery models.
- Farmers' Markets:Artisanal raw milk sales persist in peripheral regions with lighter regulatory enforcement.
- Specialty Stores:Organic-certified and single-origin products command 40% price premiums in upscale Riyadh districts.
Supermarkets capture the largest revenue pool. Online retail shows the steepest expansion trajectory.
Customer Type:
Procurement patterns diverge sharply between price-sensitive institutional buyers and health-motivated individual consumers.
- Individual Consumers:Central Region households prioritize functional nutrition claims and lactose tolerance benefits. Subscription retention rates concentrate in Riyadh's Diplomatic Quarter and Jeddah's Al Andalus district.
- Restaurants:Fine-dining establishments in Jeddah's corniche district feature camel milk cheese boards and dessert applications.
- Cafés:Specialty beverage programs in Riyadh and Jeddah now standardize camel milk lattes as signature menu items.
- Bakeries:Premium pastry applications remain niche, constrained by bovine dairy cost advantages in mass-production settings.
Individual consumers generate the highest per-unit margins. Cafés are gaining share fastest among commercial accounts.
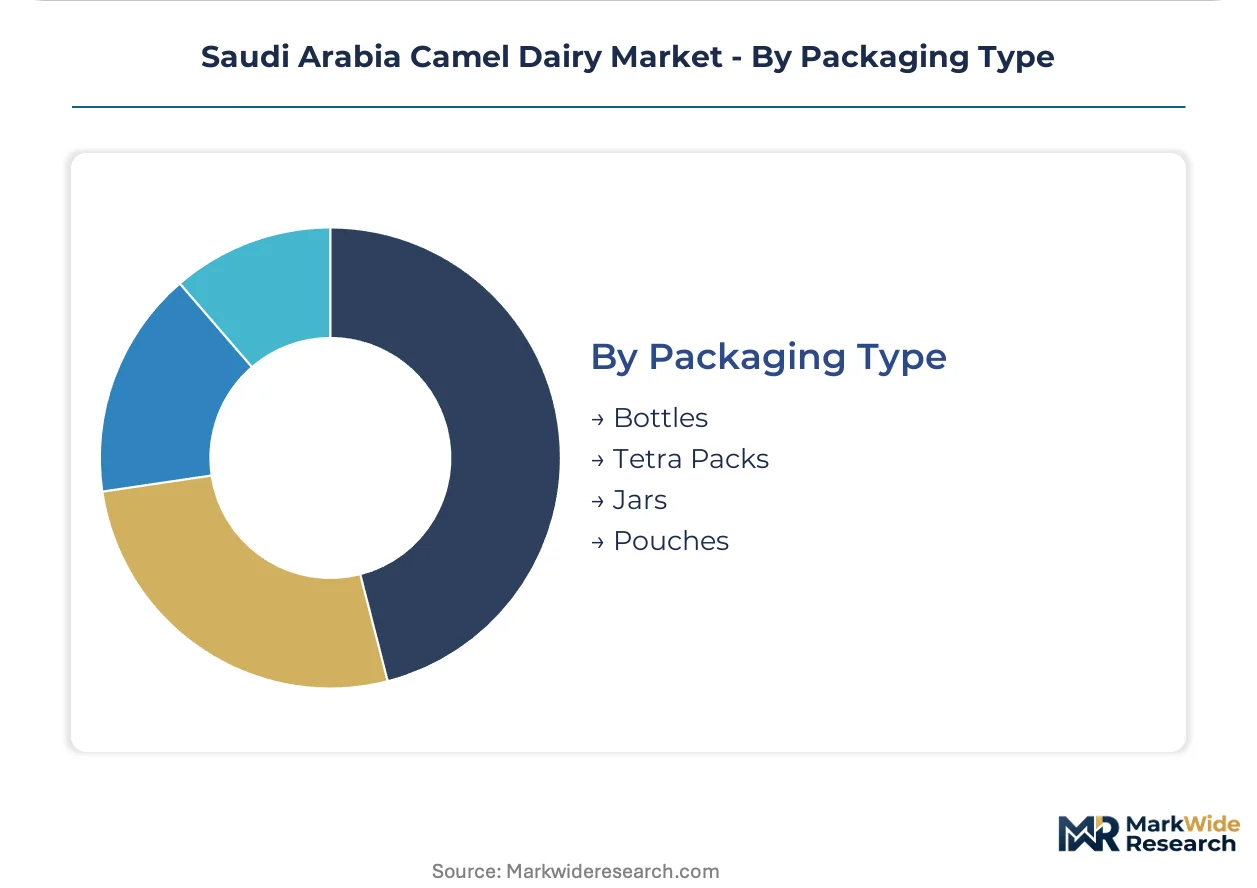
Packaging Type:
Packaging selection tracks product perishability and distribution distance, with shelf-stable formats enabling geographic expansion beyond cold-chain limits.
- Bottles:HDPE and glass formats dominate fresh milk distribution through supermarket refrigerated sections. Returnable glass programs in traditional retail corridors support circular economy positioning.
- Tetra Packs:Aseptic processing enables ambient distribution to remote regions and institutional catering accounts. UHT-treated camel milk in tetra formats penetrates GCC export markets.
- Jars:Premium yogurt and soft cheese presentations target gift-giving occasions and hotel minibar placements.
- Pouches:Flexible formats reduce logistics costs for bulk institutional deliveries and foodservice concentrates.
Bottles hold the largest installed base. Tetra Packs are expanding most quickly as UHT processing capacity comes online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Saudi Arabia diverge sharply between health-focused urban households in Riyadh and hospitality-driven demand clusters in Jeddah. Central Region households prioritize functional nutrition through subscription channels, while Western Region buyers emphasize premium positioning for café and hotel applications.
Riyadh
Health-conscious households in Riyadh's Diplomatic Quarter and Al Yasmin district drive recurring subscription deliveries of pasteurized fresh milk. SFDA pasteurization mandates have compressed margins for smaller processors lacking automated thermal processing equipment. Sawani operates rotary milking parlors across Central Region facilities, capturing supermarket shelf space formerly held by artisanal producers.
Eastern Province
Dammam and Khobar households show strongest adoption for online retail subscription models as cold-chain logistics mature. SASO quality labeling requirements govern product standards for dairy entering retail distribution. Al Wathba maintains integrated desert farming operations controlling feed cultivation and herd genetics across the province's arid interior.
Jeddah
Fine-dining establishments along Jeddah's corniche district feature camel milk cheese boards and dessert applications commanding premium placement. Halal certification protocols from the Ministry of Municipal and Rural Affairs extend product launch timelines for new entrants. Specialty cafés in Al Andalus district standardize camel milk lattes as signature menu items.
Western Region
Peripheral areas with lighter regulatory enforcement sustain artisanal raw milk sales through traditional retail corridors. Groundwater allocation policies for alfalfa and Rhodes grass cultivation create feed input volatility squeezing margins for operations without captive fodder. Returnable glass programs support circular economy positioning in heritage market clusters.
Saudi Arabia Camel Dairy Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with competitive dynamics bifurcating between automated milking operations and traditional hand-milking cooperatives. Scale advantages concentrate among operators with captive feed cultivation and rotary parlors, while differentiation premiums accrue to organic-certified and direct-to-consumer specialists. Two strategic archetypes dominate: integrated desert farming operations controlling upstream inputs, and subscription-focused brands leveraging cold-chain logistics for disintermediation. Capacity expansion and organic certification represent the dominant competitive moves.
Within the integrated farming tier, Al Wathba Camel Dairy and Sawani exemplify operations combining herd genetics control with automated processing infrastructure. Desert Farms occupies a position representing the direct-to-consumer archetype through subscription channels and organic certification differentiation. Among specialty producers, Al Mahra Camel Dairy and The Camel Milk Company sit within the artisanal segment serving hospitality buyers and heritage retail corridors.
| Leading Market Players |
|---|
| The Camel Milk Company |
| Al Mahra Camel Dairy |
| Sawani |
| Desert Farms |
| Al Wathba Camel Dairy |
| Camelicious |
| Al Nassma Camel Milk |
| Jumeirah Camel Dairy |
| Al Ain Dairy |
| Others |
Cost & Logistics Intelligence
Rotary milking parlor utilization rates above 80 percent anchor cost structures for Saudi Arabia's integrated operators, compressing per-liter labor expenses and establishing price floors that hand-milking cooperatives cannot match. This scale concentration funnels margin power toward Sawani and Al Wathba while fragmenting artisanal producers into peripheral channels with lighter SFDA enforcement.
Pricing Analysis
Subscription renewal revenue drives lifetime value for direct-to-consumer operators, with Desert Farms capturing recurring household commitments that bypass supermarket markups. Three-tier pricing structure across organic-certified premium, standard pasteurized, and raw informal tiers separates buyers by certification grade and cold-chain reliability. Pricing pressure stems from bovine dairy substitution in institutional catering, where cow milk maintains cost advantages. Individual consumers in Riyadh's Diplomatic Quarter show least price sensitivity, while mass retail buyers in Eastern Province hypermarkets prioritize unit economics.
Supply Chain Analysis
Port congestion at Jeddah Islamic Port and container availability fluctuations on Asia-Gulf trade lanes intermittently delay packaging material arrivals, squeezing just-in-time production schedules for UHT tetra pack formats. Feed cultivation concentrates in Saudi Arabia's Central Region and Eastern Province interior, with genetic stock dependencies resting on three established breeding programs. Single-source vulnerability in superior dromedary bloodlines threatens herd expansion timelines. Distribution runs through cold-chain dependent supermarket networks and proprietary subscription apps, with ambient tetra formats enabling GCC export reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary reproductive expertise for dromedary herds concentrates among aging practitioners, creating a bottleneck that slows genetic improvement and herd scaling for new operations. This capability scarcity rewards early movers who secure specialist relationships or develop in-house training pipelines.
For Market Incumbents: Fortify genetic control through captive breeding program expansion and lock in alfalfa cultivation rights under groundwater allocation policies. Automated rotary parlors at Sawani and Al Wathba demonstrate how capital deployment creates volume leadership that artisanal competitors cannot replicate. Halal certification complexity from the Ministry of Municipal and Rural Affairs extends launch timelines for challengers, preserving shelf space for compliant incumbents.
For New Entrants and Emerging Players: Lead with organic certification positioning in upscale Riyadh districts where SASO standards command 40 percent premiums over conventional products. The Eastern Province subscription corridor around Dammam and Khobar offers most penetrable geography as cold-chain logistics mature. Direct-to-consumer apps enable customer data ownership that supermarkets cannot match.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated operators combining captive feed cultivation with automated processing infrastructure. Long-term viability hinges on traceability investments and functional ingredient extraction capabilities for nutraceutical partnerships. Watch lysozyme and lactoferrin isolation partnerships with Gulf supplement manufacturers as inflection signal for premiumization trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | SASO organic standards unlock 40 percent price premiums in Riyadh's upscale supermarket channels. |
| Rotary Milking Parlor Deployment | Automated somatic cell counting at Sawani facilities halves per-liter labor costs against cooperative competitors. |
| Direct-to-Consumer Subscription Launch | Proprietary apps concentrate customer data and enable loyalty pricing beyond supermarket markups. |
| Functional Ingredient Extraction | Lysozyme isolation opens pharmaceutical channel partnerships with Gulf-based nutraceutical manufacturers. |
| Captive Fodder Cultivation Expansion | Integrated desert farming at Al Wathba insulates margins from alfalfa price volatility under groundwater policies. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SFDA regulatory filings, SASO quality standards documentation, and customs trade data for dairy equipment imports. Primary interviews engaged dairy operations managers, veterinary specialists, supermarket category buyers, and hospitality procurement directors across Riyadh, Jeddah, and Eastern Province. Bottom-up volume triangulation from herd counts and milk-yield estimates cross-validates against top-down market sizing from retail audit data and subscription platform disclosures.
Segmentation dimensions modeled span product format, distribution channel, customer type, and packaging technology across the projection horizon. CAGRs derive from regression analysis of historical volume trajectories and elasticity estimates for functional nutrition demand. Forecast inputs incorporate SFDA pasteurization compliance timelines, cold-chain logistics maturity curves, and groundwater allocation policy scenarios for feed cultivation.
The analysis sits within stated boundaries; outcomes outside sustained SFDA enforcement, stable alfalfa supply, and continued functional nutrition demand growth would require recalibration. Forecasts reflect assumptions on herd expansion rates and subscription adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Europe Dairy Based Beverages Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Condensed Whey Market
Dairy Products
North America Fluid Milk Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Paneer Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Probiotic Fermented Milk Market
Dairy Products
Global Dairy Cream Market
Dairy Products
Dairy Concentrates Market
Dairy Products
GCC Fresh Milk Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
China Milk Protein Market
Dairy Products
Asia-Pacific Casein and Caseinates Market
Dairy Products
United States Milk Protein Market