
 A2 Fresh Milk Market | 2026-2036
A2 Fresh Milk Market Size, Share, and Industry Trends Forecast 2026-2036
A2 Fresh Milk Market Insights
The gap between premium A2-certified fresh milk and conventional commodity fluid milk is recalibrating retail shelf space and margin allocation across developed dairy markets. The a2 Milk Company leverages its proprietary herd certification program to sustain price premiums in Australian and US grocery channels. Fonterra anchors Oceania's A2 supply base through farmer partnership models that control raw milk provenance. Nestlé competes in pediatric and adult nutrition segments with A2 protein formulations that extend its dairy ingredient portfolio beyond standard commodity sourcing.
A2 fresh milk denotes fluid dairy from cows selectively bred to produce beta-casein protein containing only the A2 variant, excluding the A1 beta-casein associated with digestive discomfort in some consumers; laboratory verification via ELISA or mass spectrometry confirms protein identity before bottling. Whole milk occupies the dominant revenue position among product types due to its alignment with clean-label positioning and minimal processing narratives that resonate with premium buyers. Liquid form leads volume throughput but powder form captures higher margins in export markets where cold-chain limitations constrain fresh distribution. Tetra Pak packaging dominates shelf-stable segments while glass bottles command price premiums in health stores and direct-to-subscription channels.
FDA dairy identity standards in the US require A2 claims to substantiate protein composition without implying therapeutic benefit, while Australia's FSANZ mandates beta-casein quantification on premium-labeled products. China's SAMR and GB standards for imported dairy enforce batch-level protein verification, creating compliance costs that filter smaller exporters from cross-border trade. Stakeholders must monitor evolving herd-genetics patent landscapes and regional cold-chain infrastructure investments as determinants of sustainable margin capture in premium fluid dairy.
Market Dynamics
Herd segregation infrastructure and third-party beta-casein verification protocols are compressing supply-side flexibility while amplifying price premiums for verified A2 fluid milk across Australian and North American retail channels.
Growth Catalysts
- China's NMPA protein-labeling standards:Batch-level verification mandates for imported dairy are filtering smaller exporters and consolidating procurement among certified suppliers with established assay partnerships.
- Pediatric nutrition programs:Hospital cafeteria procurement across Victoria and New South Wales is expanding A2 fresh milk volumes through institutional tender processes that prioritize digestive wellness claims.
- Herd genetics infrastructure:A2-certified dairy cooperatives in Australia's southeastern states have achieved critical mass in selective breeding programs, reducing per-unit certification costs for member farmers.
Market Restraints
- ELISA and mass spectrometry assay costs:Laboratory verification of beta-casein composition adds fixed per-batch compliance expenses that constrain margin capture for smaller fluid milk processors.
- Cold-chain infrastructure gaps:Export markets lacking refrigerated distribution networks limit fresh liquid penetration, forcing reliance on lower-margin powder formulations for cross-border trade.
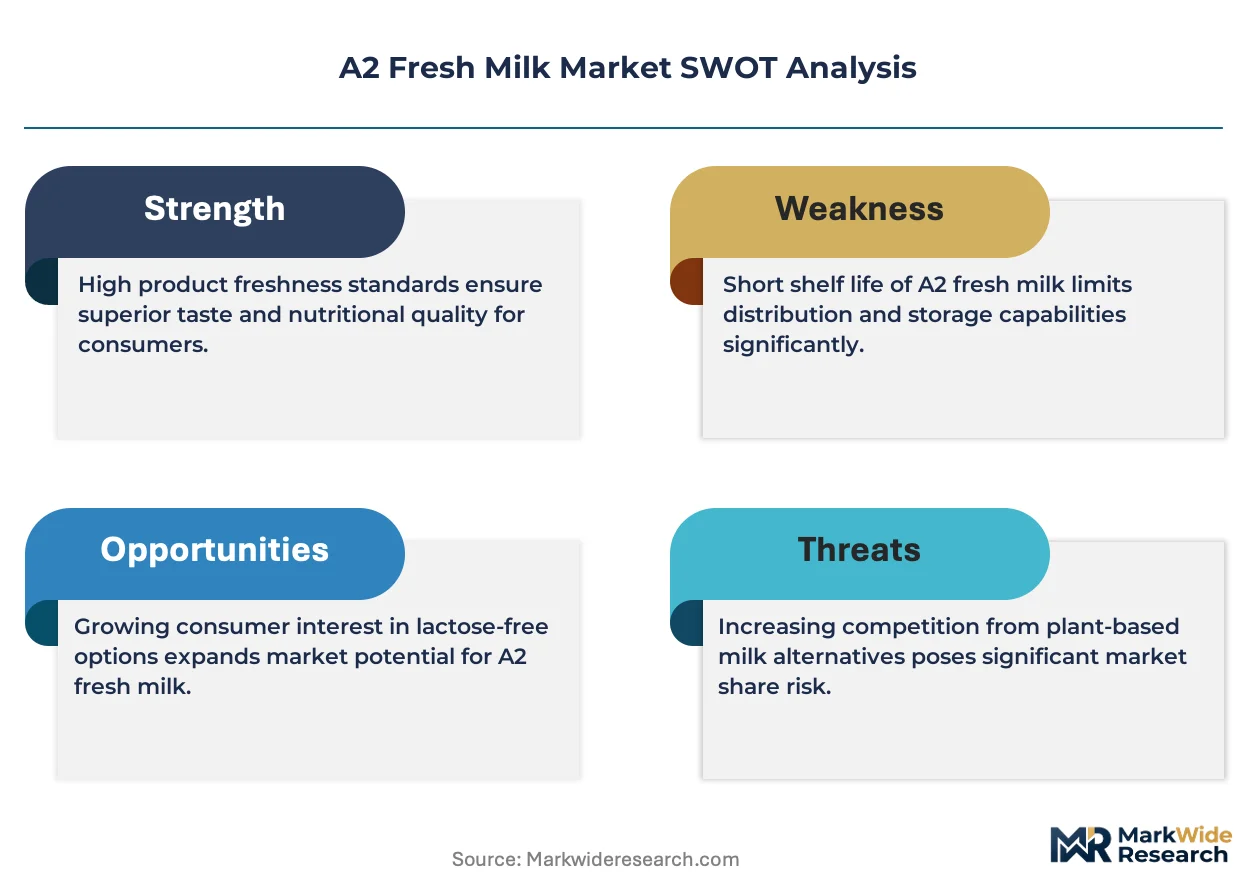
- Conventional A1 milk substitution:Commodity fluid milk at standard retail pricing captures price-sensitive household segments that do not perceive digestive discomfort differentials.
Strategic Opportunities
- Direct-to-subscription channels:Glass bottle delivery services targeting health-conscious urban households in Sydney and Melbourne are capturing recurring revenue with reduced retail slotting fees.
- US FDA identity standard clarifications:Substantiation guidelines for A2 protein claims without therapeutic implication are creating compliance pathways for premium positioning in American grocery.
- Clean-label minimal processing narratives:Whole milk variants with reduced thermal treatment are aligning with consumer preference for unaltered nutritional profiles in Australian specialty stores.
Industry Challenges
- Genetic patent landscape complexity:Proprietary herd certification programs and beta-casein testing methodologies are generating licensing disputes between technology holders and cooperative adopters.
- Segregated supply chain reconfiguration:Parallel collection, transport, and processing infrastructure for A2-only milk is requiring capital deployment that strains mid-tier dairy operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | A2 Fresh Milk Market |
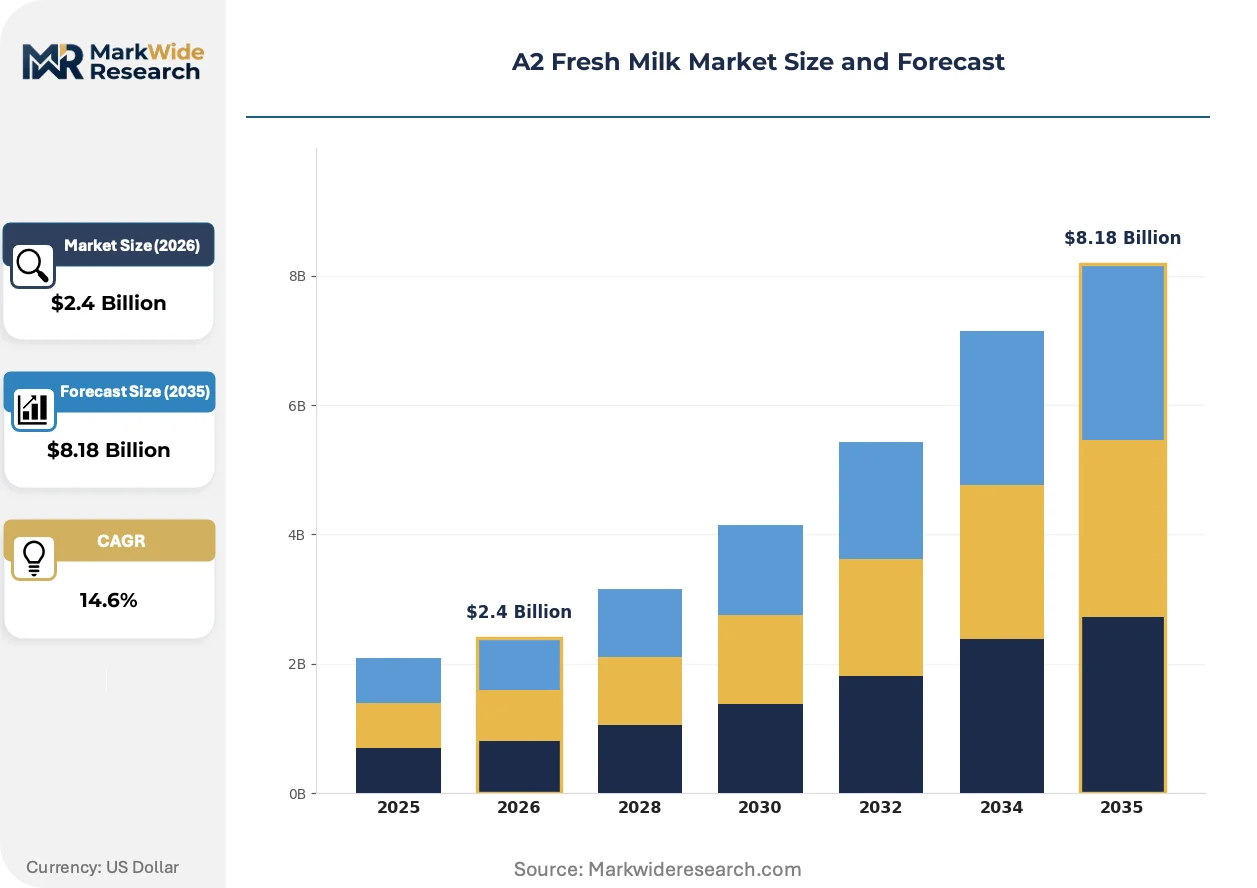
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Milk, Skim Milk, Low-Fat Milk, Flavored Milk Form: Liquid, Powder, Cream, Concentrate Packaging Type: Carton, Bottle, Pouch, Tetra Pak Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores |
| Companies Covered | The a2 Milk Company, GCMMF, Nestlé, Vinamilk, Freedom Foods Group, Provilac Dairy Farms, Fonterra, Erden Creamery, Ripley Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
A2 Fresh Milk Market Trends and Innovations
Mass spectrometry and genetic testing platforms are compressing verification timelines while reshaping how premium fluid milk demonstrates compositional authenticity to institutional buyers and regulators.
Mass spectrometry-based beta-casein identification is integrating into quality control workflows at Australian dairy cooperatives. Large-scale processors in Victoria are adopting these platforms to reduce third-party laboratory dependency. The technology is integrating batch-level protein fingerprinting with automated certification documentation, compressing time-to-shelf for export-bound fluid milk.
China's SAMR and GB standards for imported dairy are enforcing stricter batch-level protein verification protocols. Exporters must now submit third-party assay documentation demonstrating A2 beta-casein exclusivity prior to customs clearance. Powder-form A2 products face the most stringent documentation requirements, driving consolidation among suppliers with established Chinese regulatory affairs capabilities.
Subscription-based home delivery is displacing traditional retail slotting for premium fluid milk in Australian metropolitan markets. Health stores and direct-to-consumer platforms in Sydney and Melbourne are capturing recurring household purchases through glass bottle programs. This channel rotation is most visible among dual-income households with children, where convenience and packaging sustainability rank alongside digestive wellness claims in purchase decisions.
A2 Fresh Milk Market Segmentation
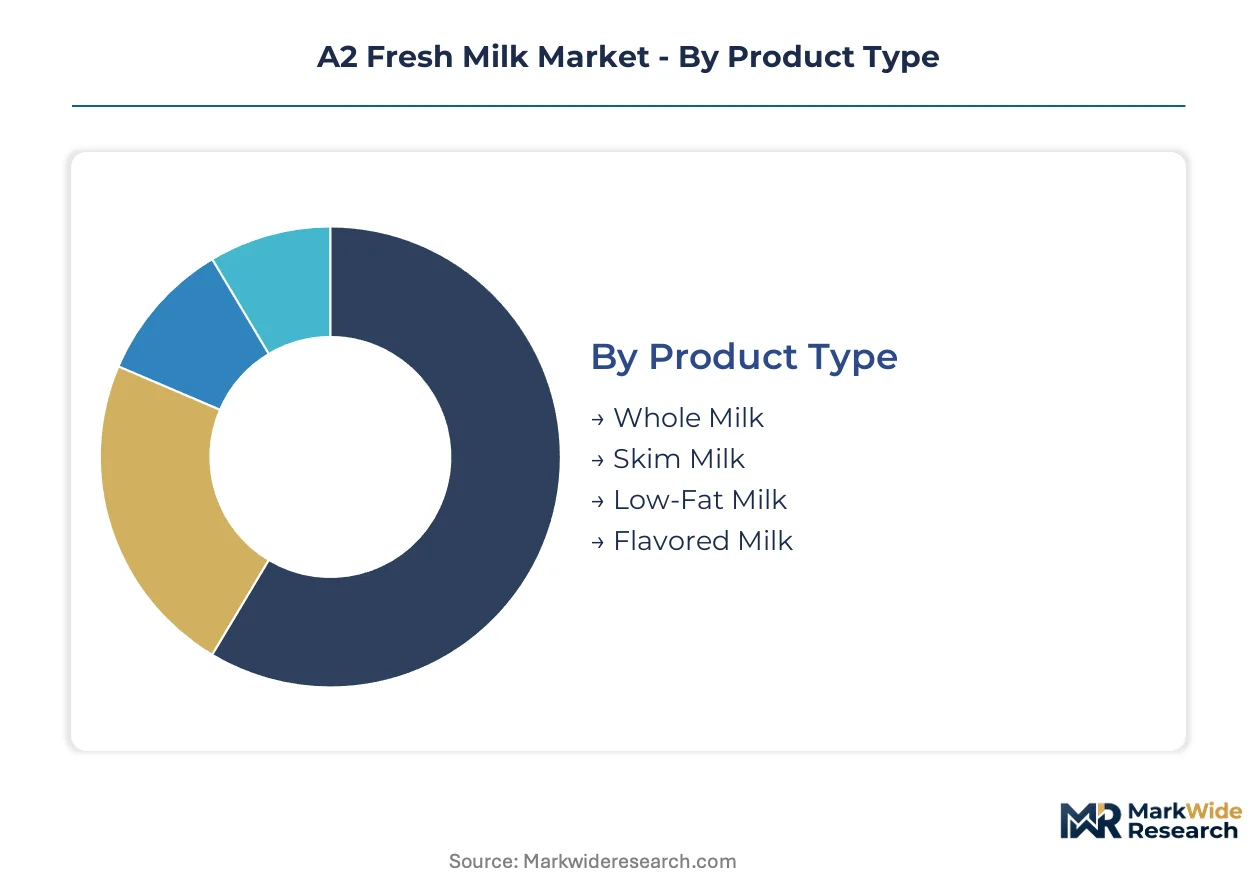
A2 fresh milk segmentation reflects divergent margin profiles across processing intensity and channel access. Product form and packaging format determine cold-chain dependency, while distribution channel selection filters which consumer segments validate beta-casein premiums.
Product Type:
Supply concentration in Australia's Victoria and New South Wales shapes which product types achieve viable scale first.
- Whole Milk:Unaltered fat content preserves native beta-casein structure without homogenization stress. Hospital cafeteria procurement across Victoria and New South Wales anchors institutional demand, though thermal treatment debates constrain clean-label positioning in specialty retail.
- Skim Milk:Fat separation requires additional processing steps that extend supply chains and compress margins. China's NMPA protein-labeling verification adds fixed costs that disproportionately burden lower-margin skim variants in cross-border trade.
- Low-Fat Milk:Mid-range fat reduction appeals to health-conscious urban households in Sydney and Melbourne subscription channels.
- Flavored Milk:Added ingredients complicate beta-casein purity claims and trigger stricter FSANZ disclosure requirements in Australian retail.
Today's leader: Whole Milk. Tomorrow's challenger: Skim Milk.
Form:
Cost tier stratification separates fresh liquid from shelf-stable alternatives, with powder commanding export premiums where refrigeration fails.
- Liquid:Cold-chain dependent distribution limits geographic reach to developed markets with intact refrigerated networks. Pediatric nutrition programs in Australian hospitals prioritize fresh liquid for digestibility claims, though perishability constrains inventory depth.
- Powder:Dehydration eliminates spoilage risk and enables China's SAMR-compliant batch documentation for customs clearance. SAMR's protein verification mandates filter smaller exporters from powder trade, consolidating procurement among assay-capable suppliers.
- Cream:Higher fat concentration amplifies A2 beta-casein purity marketing in specialty foodservice.
- Concentrate:Reduced water content lowers shipping costs for intercontinental supply to cold-chain gap markets.
Liquid dominates volume. Powder captures margin.
Packaging Type:
Volume throughput concentrates in formats that balance shelf stability with consumer perception of freshness.
- Carton:Lightweight fiber construction reduces transport emissions for subscription delivery routes in Melbourne and Sydney. Australia's health store channels favor cartons for perceived sustainability alignment with minimal-processing narratives.
- Tetra Pak:Aseptic filling extends ambient shelf life, enabling export to China's tier-two cities with intermittent cold-chain coverage. Tetra Pak's established supplier relationships with Victorian cooperatives reduce packaging procurement friction for export-bound fluid milk.
- Bottle:Glass commands subscription channel premiums; plastic dominates supermarket price competition.
- Pouch:Flexible format gains traction in convenience store impulse segments with lower per-unit price points.
Tetra Pak anchors export scale. Glass bottles defend subscription premiums.
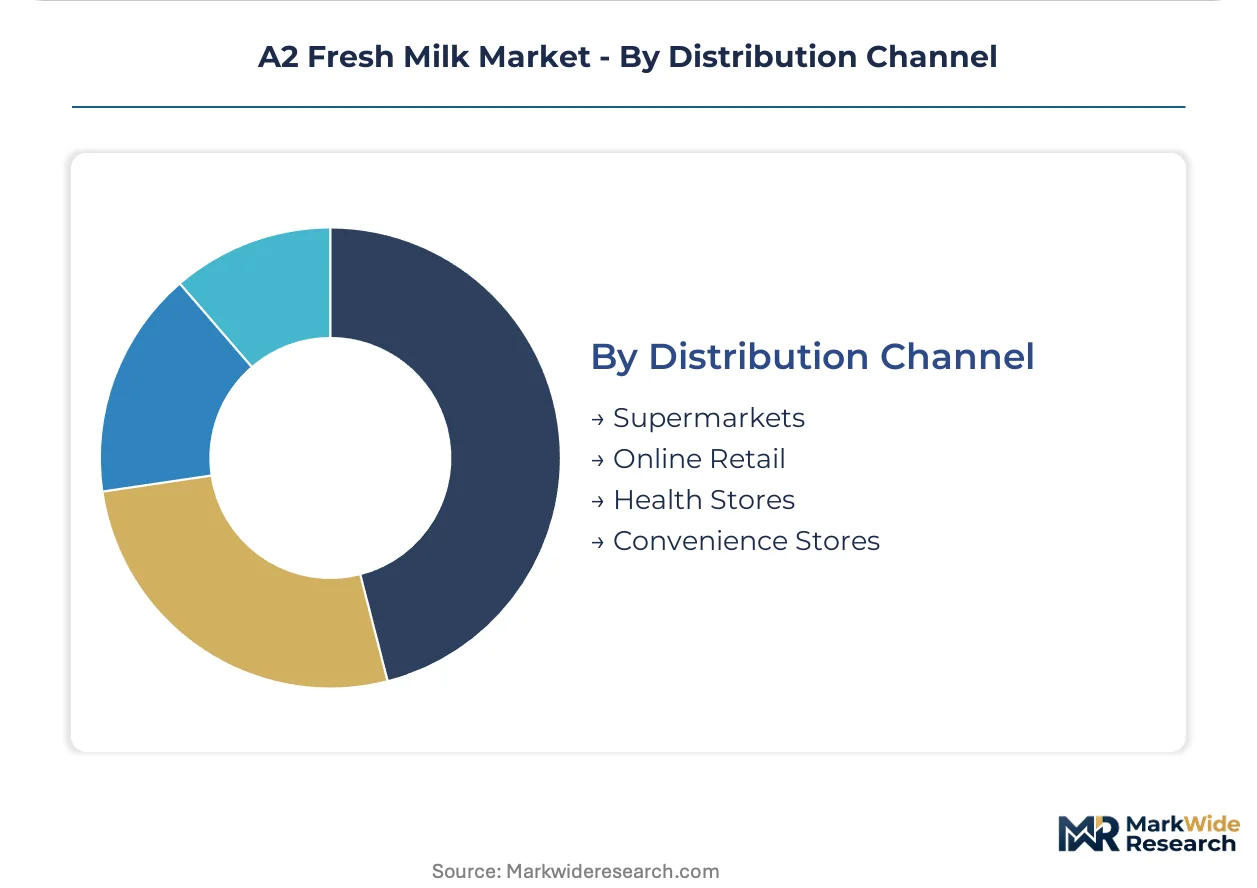
Distribution Channel:
Customer type segmentation separates institutional procurement from household purchase patterns, with divergent validation requirements for beta-casein claims.
- Supermarkets:Slotting fee structures favor established processors with herd certification scale. The a2 Milk Company's proprietary verification program secures shelf positioning in Australian and US grocery, though conventional A1 milk substitution threatens price-sensitive segments.
- Online Retail:Direct-to-subscription platforms in Sydney and Melbourne bypass retail intermediaries, capturing recurring revenue from dual-income households with children. China's cross-border e-commerce channels demand NMPA-compliant assay documentation that filters uncertified suppliers.
- Health Stores:Staff education requirements elevate A2 digestive wellness claims above commodity positioning.
- Convenience Stores:Grab-and-go occasions prioritize single-serve formats with minimal premium pricing tolerance.
Supermarkets control mass access. Online retail expands fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia commands herd certification infrastructure while China absorbs export volumes through tightened import protocols, creating divergent regulatory pressures across Pacific supply chains.
Australia
Pediatric nutrition tenders in Victoria and New South Wales drive institutional procurement volumes. FSANZ mandates beta-casein quantification on premium-labeled products, forcing processors to document protein composition. Melbourne and Sydney cooperatives have achieved critical mass in selective breeding programs, reducing per-unit certification costs for member farmers.
China
Cross-border e-commerce channels demand NMPA-compliant assay documentation that filters uncertified suppliers. SAMR and GB standards enforce batch-level protein verification for imported dairy, creating compliance costs that consolidate procurement among certified exporters. Tier-two cities with intermittent cold-chain coverage absorb Tetra Pak-stabilized liquid formats where fresh distribution fails.
United States
Health-conscious urban households in coastal metros validate digestive wellness premiums through subscription channels. FDA dairy identity standards require A2 claims to substantiate protein composition without implying therapeutic benefit. The a2 Milk Company leverages proprietary herd certification to sustain price premiums in grocery channels across California and the Northeast Corridor.
New Zealand
Farmer partnership models control raw milk provenance through cooperative structures anchored by Fonterra. Export-bound fluid milk faces SAMR documentation requirements that favor large-scale processors with established regulatory affairs capabilities. Canterbury and Waikato dairy regions concentrate herd segregation infrastructure for cross-border powder trade.
India
Urban middle-class households in Mumbai and Delhi-NCR demonstrate willingness to pay premiums for digestive wellness positioning. FSSAI labeling frameworks for specialty dairy remain less prescriptive than Chinese or Australian equivalents, creating positioning flexibility for early entrants. GCMMF and regional cooperatives test A2 variants through existing chilled distribution networks in Gujarat and Maharashtra.
A2 Fresh Milk Market Competitive Landscape
Top-tier vendors anchor premium positioning through proprietary herd certification, while mid-tier processors compete on assay-capable scale and regional cooperative membership. The vendor base stratifies across three archetypes: genetics-integrated specialists with captive breeding programs, cooperative-anchored processors controlling farmer supply bases, and diversified nutrition conglomerates extending dairy ingredient portfolios. M&A activity concentrates on assay technology capabilities and cold-chain infrastructure assets. Strategic partnerships between processors and third-party laboratories secure NMPA-compliant documentation for Chinese market access.
Among Australia and New Zealand-based operators, The a2 Milk Company, Fonterra, and Freedom Foods Group exemplify divergent approaches to premium fluid dairy. The a2 Milk Company occupies the genetics-integrated specialist position with proprietary herd certification infrastructure. Fonterra anchors cooperative-scale supply control through farmer partnership models across Oceania. Freedom Foods Group represents mid-tier assay-capable processing with health-channel distribution reach. Nestlé and Vinamilk sit within the diversified nutrition conglomerate archetype, leveraging existing pediatric and adult nutrition segments to extend A2 protein formulations without captive dairy sourcing.
| Leading Market Players |
|---|
| The a2 Milk Company |
| GCMMF |
| Nestlé |
| Vinamilk |
| Freedom Foods Group |
| Provilac Dairy Farms |
| Fonterra |
| Erden Creamery |
| Ripley Farms |
| Others |
Pricing and Supply Chain Analysis
Cooperative-anchored processors in Australia's Victoria and New South Wales concentrate herd certification infrastructure, translating supply-side discipline into sustained premium capture across retail and institutional channels while filtering smaller competitors from viable margin territory.
Pricing Analysis
Bundled subscription services targeting Sydney and Melbourne households command recurring premiums through glass bottle delivery programs, while unbundled supermarket transactions face compression from conventional A1 milk substitution. Three-tier pricing structure across premium certified, standard verified, and economy conventional levels separates A2-exclusive products from commodity fluid milk. Pricing pressure stems from ELISA and mass spectrometry assay costs that burden smaller processors. Pediatric nutrition programs in hospital cafeterias show least price sensitivity; convenience store single-serve segments tolerate minimal premiums.
Supply Chain Analysis
A2 beta-casein verification rests on laboratory assay capacity concentrated in Australia, New Zealand, and select Chinese third-party facilities. Herd genetics, segregated collection infrastructure, and cold-chain transport constitute critical input dependencies. Single-source vulnerability runs through third-party assay providers for NMPA-compliant export documentation. Distribution runs through cooperative collection networks feeding Tetra Pak-stabilized export channels and direct-to-subscription urban delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's NMPA protein-labeling standards and Australia's FSANZ beta-casein quantification mandates continuously elevate compliance barriers that consolidate procurement among certified suppliers.
For Market Incumbents: Deploy proprietary herd certification programs to deepen farmer lock-in across Victoria and New South Wales cooperative networks. Invest in mass spectrometry platform integration to reduce third-party laboratory dependency and compress verification timelines. Counter conventional A1 milk substitution threats by expanding pediatric nutrition tender participation in Australian hospital systems. For New Entrants and Emerging Players: Direct-to-subscription platforms in Indian metropolitan markets present the most penetrable white-space opportunity given FSSAI's less prescriptive specialty dairy frameworks. Target Mumbai and Delhi-NCR urban middle-class households through digestive wellness positioning. Pursue assay partnership models with established Chinese regulatory affairs capabilities to bypass NMPA documentation barriers. For Investors and Strategic Acquirers: Diversified nutrition conglomerates with pediatric segment presence represent the most active acquirer category in this space. Long-term viability hinges on regulatory affairs capabilities spanning NMPA, FSANZ, and FDA substantiation pathways. Watch herd genetics patent litigation outcomes as inflection indicators for licensing cost trajectories and cooperative adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Herd Certification Program Expansion | Proprietary verification infrastructure locks in farmer supply bases across Australia's southeastern dairy regions. |
| Mass Spectrometry Platform Integration | In-house beta-casein identification reduces third-party assay dependency and accelerates batch certification. |
| Direct-to-Subscription Channel Launch | Glass bottle delivery programs in Sydney and Melbourne capture recurring revenue with reduced retail slotting fees. |
| NMPA-Compliant Assay Partnership | Third-party laboratory relationships enable Chinese customs clearance for export-bound powder formulations. |
| Pediatric Nutrition Tender Participation | Hospital cafeteria procurement in Victoria and New South Wales anchors institutional volume with premium pricing. |
Research Methodology
Coverage spans Australia, China, the United States, New Zealand, and India, with primary inputs from each market cluster combining cooperative managers, dairy processors, regulatory affairs specialists, and hospital procurement officers with secondary validation through FSANZ disclosure records, NMPA import documentation, FDA dairy identity standards, and customs trade data. Bottom-up volume modeling triangulates against top-down value estimates derived from retail channel audits and institutional tender disclosures.
Granularity-level modeling captures product type, form, packaging format, and distribution channel dimensions at the country level, with beta-casein verification status and herd certification tier as industry-specific stratifiers. CAGRs derive from regression analysis against protein-labeling regulatory milestones and cold-chain infrastructure investment trajectories. Forecast inputs incorporate pediatric nutrition program expansion rates and cooperative membership growth across Australia's southeastern states.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA enforcement consistency, herd genetics patent litigation resolutions, and cold-chain infrastructure deployment in China's tier-two cities. A small set of triggers—assay cost trajectories, regulatory harmonization between FSANZ and NMPA standards, and cooperative consolidation rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Lactose Market
Dairy Products
GCC UHT Milk Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
Sheep Milk Cheese Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
Dairy Concentrates Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
Yogurt Drink Market
Dairy Products
Reduced Fat Cheeses Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Dairy Dessert and Yogurt Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Clotted Cream Market
Dairy Products
Whole Milk Powder Market
Dairy Products
Global Milk Protein Market