
 Laboratory Refrigerators and Ovens Market | 2026-2036
Laboratory Refrigerators and Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Refrigerators and Ovens Market Foresight
Modular cabinet configurations with swappable compressor and control modules is rebalancing procurement patterns across research facilities. Thermo Fisher Scientific leverages its vertically integrated cold chain portfolio to anchor premium positioning in biopharma accounts. Haier Biomedical competes on manufacturing scale, sustaining cost leadership across standardized product lines in academic and clinical settings. Eppendorf AG specializes in compact footprint designs, differentiating its offerings for space-constrained European laboratories.
Laboratory refrigerators and ovens comprise thermally insulated enclosures with precision control systems maintaining setpoint stability within ±1°C or narrower bands, depending on application criticality; these units employ vapor-compression, Peltier, or gravity-convection mechanisms to protect temperature-sensitive reagents, biological specimens, and analytical samples across storage, incubation, and thermal processing workflows. Refrigerators and freezers dominate installed base value, though ultra-low-temperature freezers command disproportionate margin pools due to cascade refrigeration complexity and qualification requirements. Ovens and incubators represent faster-growth categories where demand from cell therapy process development and continuous culture applications expands replacement cycles in biotechnology end users.
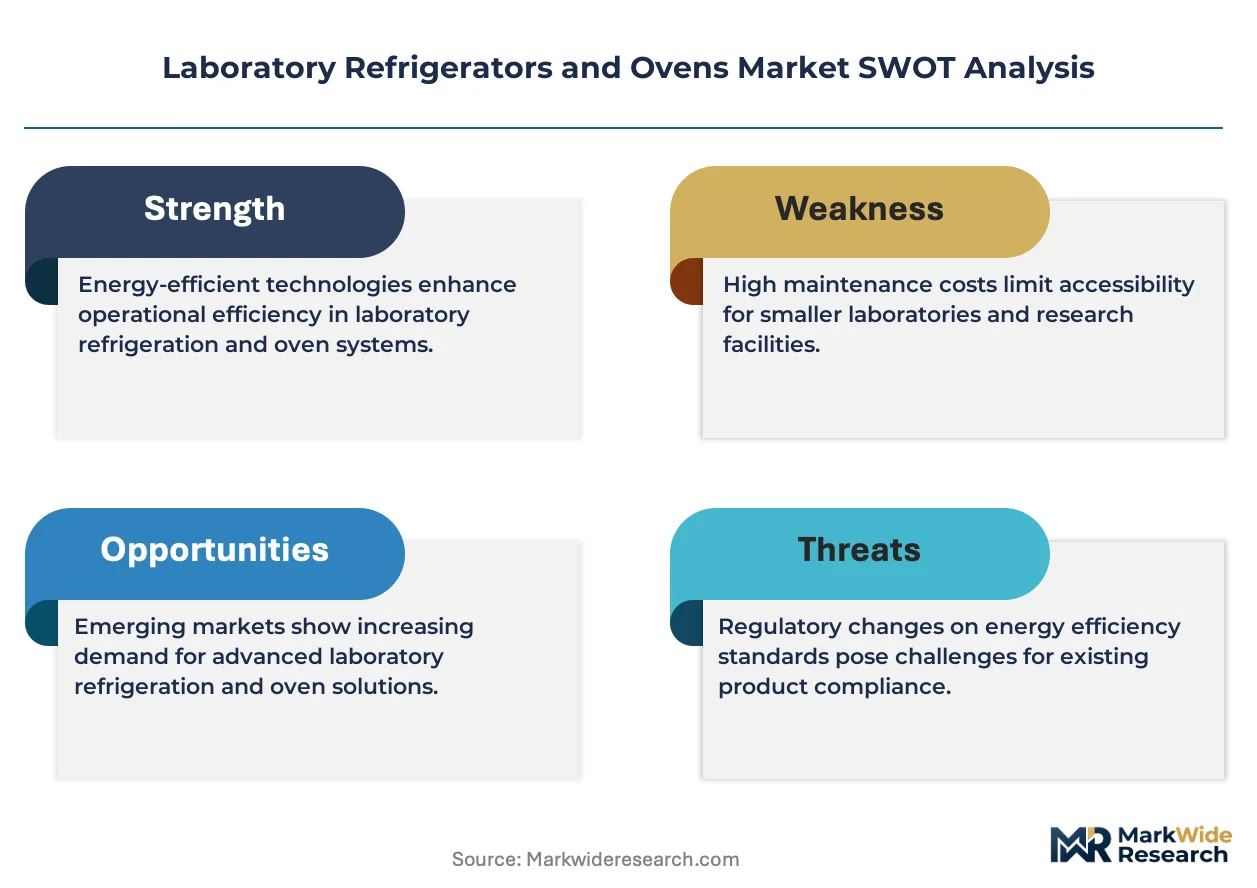
FDA 21 CFR Part 11 data integrity requirements, EPA SNAP refrigerant phase-down rules, and ISO 9001 quality management standards collectively shape product design, validation documentation, and market access protocols for equipment suppliers serving regulated industries. Energy Star certification and EU F-Gas Regulation restrictions on high-GWP refrigerants further constrain component sourcing and regional product configurations. Stakeholders must monitor evolving hydrocarbon safety standards and regional efficiency labeling expansions to anticipate redesign cycles and compliance-driven replacement demand.
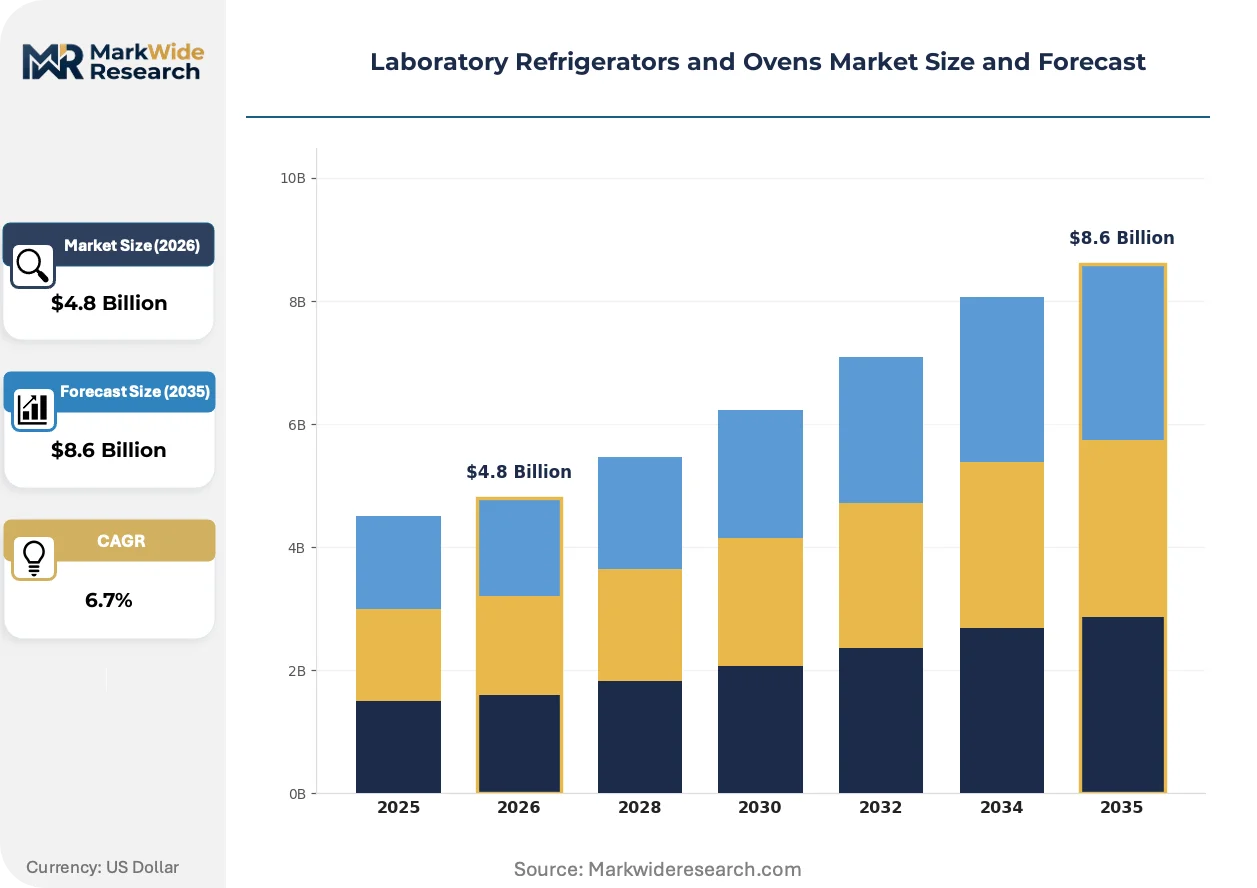
Market Dynamics
Biopharmaceutical cold chain expansion is compressing replacement cycles for ultra-low-temperature infrastructure as cell therapy manufacturing scales demand validated thermal stability across distributed production networks.
Growth Catalysts
- EPA SNAP Refrigerant Phase-Down:US hydrocarbon refrigerant transitions are accelerating equipment refresh cycles as facilities preempt compliance deadlines with next-generation cascade systems.
- Cell Culture Process Intensification:Continuous bioprocessing adoption in biotechnology end users is expanding incubator and oven capacity requirements for perfusion-based manufacturing workflows.
- Modular Cabinet Architectures:Swappable compressor and control modules are reducing total cost of ownership across academic and clinical research facilities with constrained capital budgets.
Market Restraints
- Cascade Refrigeration Complexity:Ultra-low-temperature freezer manufacturing depends on specialized compressor supply chains concentrated in Germany and Japan, creating input bottlenecks during demand surges.
- EU F-Gas Regulation Constraints:High-GWP refrigerant restrictions are limiting component sourcing flexibility and forcing regional product configuration fragmentation.
- Gravity-Convection Substitution:Mechanical convection ovens are displacing gravity-convection units in precision applications, eroding margin pools for standardized product lines.
Strategic Opportunities
- India Biopharma Infrastructure:CDSCO regulatory harmonization and PLI scheme incentives are creating white space for qualified cold chain equipment in vaccine export manufacturing.
- ISO 9001 Quality Management Integration:Validation documentation bundling is opening premium service attach rates for equipment suppliers serving regulated pharmaceutical accounts.
- Peltier-Convection Convergence:Solid-state cooling hybridization with forced-air circulation is enabling compact footprint designs for space-constrained urban laboratory clusters.
Industry Challenges
- FDA 21 CFR Part 11 Validation Expertise:Data integrity compliance documentation requires specialized quality engineering talent that equipment suppliers struggle to staff at scale.
- Legacy Control System Integration:Building management system interoperability with existing facility automation creates commissioning friction and extended deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Refrigerators and Ovens Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Freezers, Ovens, Incubators End User: Pharmaceuticals, Biotechnology, Academic Institutions, Research Labs Temperature Control: Low-Temperature, Ultra-Low-Temperature, Standard Temperature, Ambient Temperature Energy Efficiency: High Efficiency, Moderate Efficiency, Low Efficiency, Energy Star Rated |
| Companies Covered | Thermo Fisher Scientific Inc., Haier Biomedical, Eppendorf AG, Helmer Scientific Inc., Cole-Parmer Instrument Company, Carbolite GERO Limited, BINDER GmbH, Philipp Kirsch GmbH, Sheldon Manufacturing Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Refrigerators and Ovens Market Shifts & Advancements
Equipment intelligence and thermal architecture convergence are redefining competitive differentiation as buyers prioritize predictive maintenance capabilities and energy performance verification over base hardware specifications.
Variable-speed compressor technology with integrated IoT sensor arrays is electrifying predictive failure detection in ultra-low-temperature freezers. Biopharmaceutical quality assurance teams are deploying these systems at pilot scale ahead of commercial manufacturing rollouts. The technology is electrifying service contract structures toward uptime-guarantee models that compress traditional preventive maintenance revenue pools.
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are mandating hydrocarbon and natural refrigerant transitions across European laboratory equipment portfolios. Manufacturers are redesigning safety systems and ignition-source controls to accommodate flammable working fluids. Germany and Switzerland are experiencing the most acute product qualification delays as notified bodies adapt certification protocols.
Consolidated procurement through group purchasing organizations is concentrating buying power among multi-site research institutions and hospital networks. Traditional distributor relationships are yielding to direct manufacturer contracts with standardized specification frameworks. The United States academic medical center segment exhibits the most visible channel disintermediation as procurement teams centralize capital equipment decisions.
Laboratory Refrigerators and Ovens Market Segmentation
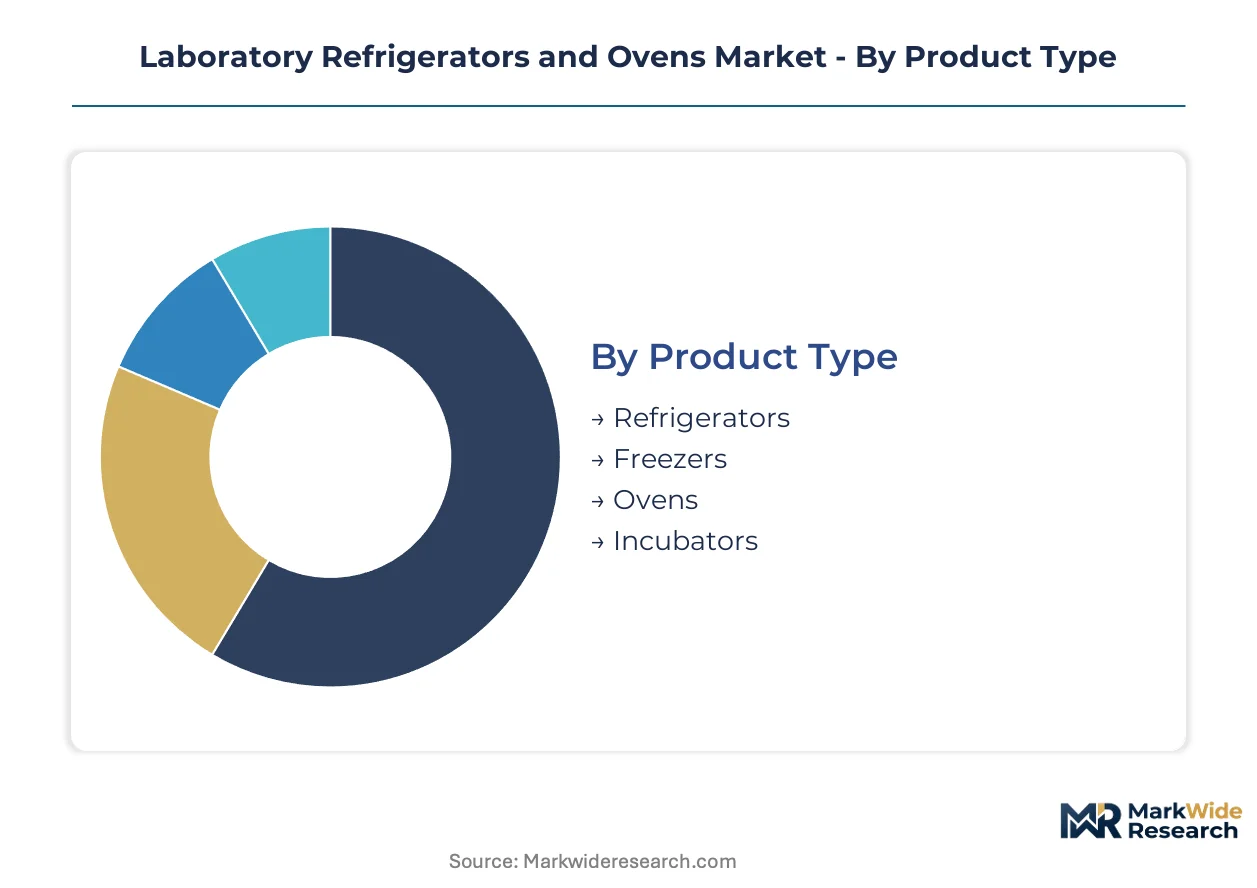
Laboratory thermal equipment procurement splits across four distinct axes, each carrying different capital burden profiles and compliance implications. Understanding these segment boundaries clarifies why biopharma facilities prioritize ultra-low-temperature infrastructure while academic buyers favor modular standard-temperature units.
Product Type:
Capital intensity peaks with cascade refrigeration systems, while gravity-convection ovens demand the lightest upfront commitment.
- Refrigerators:Vapor-compression units maintain 2°C to 8°C setpoints for vaccine and reagent storage. Pharmaceutical distribution centers in Germany and the United States are refreshing installed bases ahead of EPA refrigerant phase-down deadlines.
- Freezers:Ultra-low-temperature cascade systems reaching −80°C command the highest per-unit investment due to dual-compressor architectures and qualification documentation. Cell therapy manufacturing networks in Japan and Switzerland are compressing replacement cycles to meet validated stability requirements.
- Ovens:Gravity-convection and mechanical-convection designs serve sterilization and drying workflows. Biotechnology process development labs favor mechanical units for precise temperature uniformity.
- Incubators:CO2 and hypoxic chambers support cell culture expansion. Continuous bioprocessing adoption is expanding capacity requirements for perfusion-based manufacturing.
Most installed capacity flows through refrigerators. Expansion is steepest in freezers.
End User:
Procurement sophistication and validation burden vary sharply across customer types, with regulated manufacturers facing the steepest compliance overhead.
- Pharmaceuticals:FDA 21 CFR Part 11 data integrity mandates drive qualification documentation and service contract bundling. Multi-site manufacturing networks prioritize uptime-guarantee models over traditional preventive maintenance.
- Biotechnology:Cell therapy process development demands validated thermal stability across distributed production networks. Incubator and oven capacity requirements are climbing with continuous culture adoption.
- Academic Institutions:Capital constraints favor modular cabinet architectures with swappable compressor modules. Group purchasing organization consolidation is centralizing specification decisions at US academic medical centers.
- Research Labs:Space-constrained urban clusters in European cities drive demand for compact footprint designs with Peltier-convection hybrid cooling.
Pharmaceuticals deploy the highest-value installed base. Biotechnology is climbing the fastest.
Temperature Control:
Technical complexity and margin structure escalate as setpoint ranges extend below −40°C.
- Low-Temperature:−20°C to −40°C single-compressor systems serve routine sample preservation. Academic and clinical settings favor these units for standardized workflows.
- Ultra-Low-Temperature:Cascade refrigeration below −80°C protects cell lines and viral vectors. Specialized compressor supply chains concentrated in Germany and Japan create input bottlenecks during demand surges.
- Standard Temperature:37°C to 60°C incubation and processing ranges dominate cell culture applications. ISO 9001 validation documentation bundling opens premium service attach rates.
- Ambient Temperature:Controlled room-temperature storage for heat-sensitive reagents. EU F-Gas Regulation constraints are forcing regional product configuration fragmentation.
Standard temperature holds the broadest installed footprint. Ultra-low-temperature is gaining share fastest.
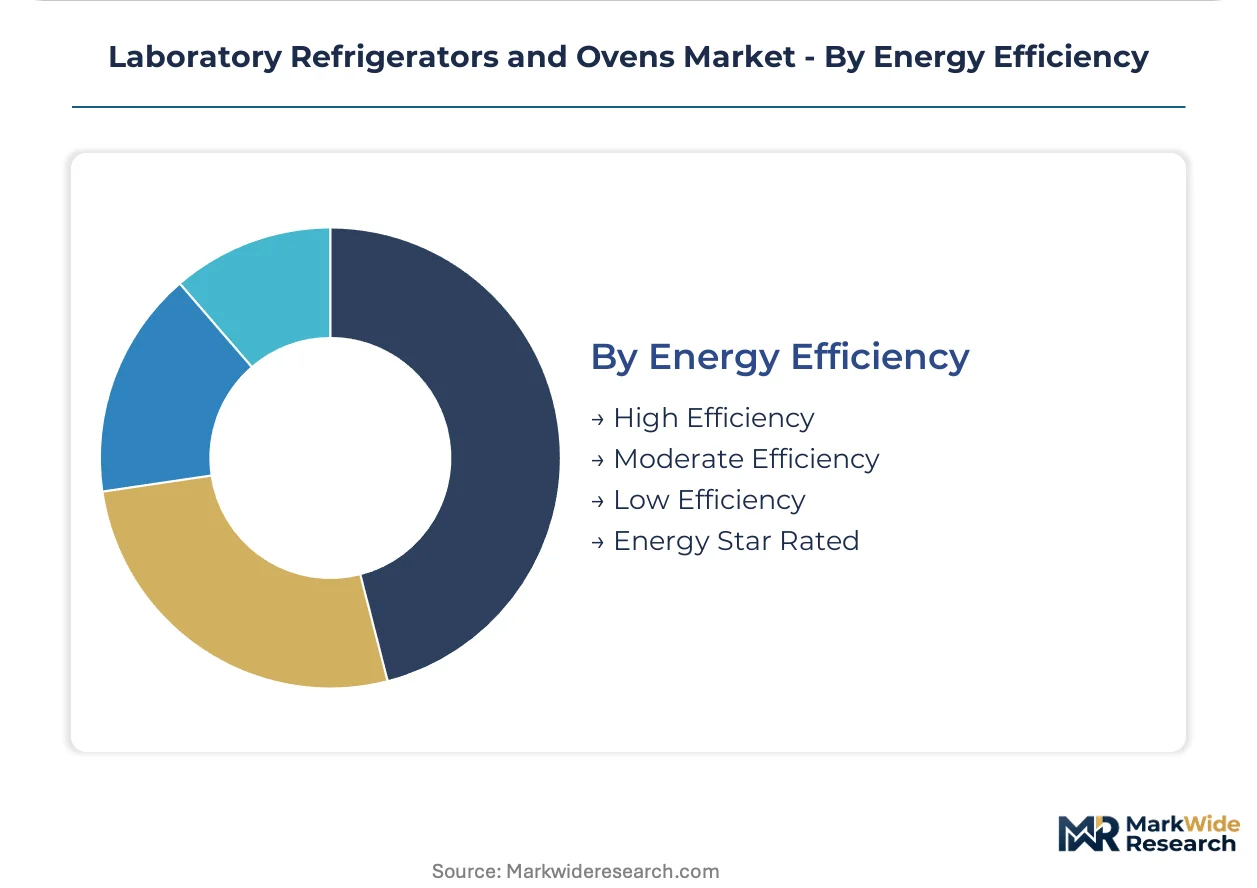
Energy Efficiency:
Regulatory pressure and operating cost sensitivity are reshaping procurement criteria across efficiency tiers.
- High Efficiency:Variable-speed compressor technology with integrated IoT sensor arrays enables predictive failure detection. Biopharmaceutical quality assurance teams are deploying these at pilot scale.
- Moderate Efficiency:Conventional fixed-speed systems dominate replacement cycles in budget-constrained academic settings.
- Low Efficiency:Legacy gravity-convection designs face displacement by mechanical convection in precision applications.
- Energy Star Rated:EPA certification requirements are accelerating equipment refresh cycles as facilities preempt compliance deadlines with next-generation systems.
Moderate efficiency still dominates unit shipments. High efficiency is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision thermal control engineering for pharmaceutical manufacturing during the 1970s cascade refrigeration revolution. The United States commercialized ultra-low-temperature infrastructure for biobanking networks. Japan refined compact incubator architectures for space-constrained urban laboratories.
United States
Academic medical centers in Boston and the Research Triangle are compressing replacement cycles for validated cold chain equipment. EPA SNAP refrigerant phase-down rules are accelerating hydrocarbon transitions in cascade freezer systems. Biopharma manufacturing clusters in San Francisco and San Diego prioritize uptime-guarantee service contracts for cell therapy production networks.
Germany
Specialized compressor supply chains concentrated in Baden-Württemberg and Bavaria create input bottlenecks during demand surges for ultra-low-temperature systems. EU F-Gas Regulation restrictions on high-GWP refrigerants are mandating safety system redesigns for hydrocarbon working fluids. Precision engineering firms in the Stuttgart region face acute product qualification delays as notified bodies adapt certification protocols.
Japan
Cell therapy manufacturing scales in the Kanto region demand validated thermal stability across distributed production networks. METI efficiency standards are pushing variable-speed compressor adoption in pharmaceutical quality assurance departments. Compact footprint designs from Nagoya-area fabricators serve space-constrained urban laboratory clusters in Osaka and Tokyo.
Switzerland
Biotechnology process development labs in Basel and Zurich are expanding incubator capacity for perfusion-based manufacturing workflows. Swissmedic qualification requirements drive premium service attach rates for validation documentation bundling. Precision equipment suppliers in the Lake Geneva region specialize in ISO 9001-integrated quality management systems for regulated pharmaceutical accounts.
India
Vaccine export manufacturing hubs in Maharashtra and Telangana are creating white space for qualified cold chain equipment. CDSCO regulatory harmonization and PLI scheme incentives are attracting biopharma infrastructure investment. Academic research institutions in Karnataka favor modular cabinet architectures with swappable compressor modules to navigate capital constraints.
Laboratory Refrigerators and Ovens Market Competitive Landscape
The competitive structure tilts toward vertically integrated conglomerates with captive cold chain portfolios. Tiered specialization separates premium precision engineering from scale-driven standardization. Three archetypes dominate: full-spectrum laboratory infrastructure conglomerates, biomedical equipment specialists with manufacturing scale advantages, and compact-design engineering houses focused on European space constraints. Strategic moves concentrate on portfolio diversification through adjacent thermal equipment categories and geographic expansion into emerging biopharma manufacturing regions.
Among North American and European equipment conglomerates, Thermo Fisher Scientific Inc. and Eppendorf AG exemplify divergent positioning strategies. Haier Biomedical anchors the scale-driven manufacturing tier with cost leadership across standardized product lines. Thermo Fisher Scientific Inc. occupies the premium infrastructure position through its integrated cold chain portfolio. Eppendorf AG represents the compact-design specialization archetype for space-constrained installations. BINDER GmbH and Philipp Kirsch GmbH sit within the German precision engineering tradition serving validated pharmaceutical applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Haier Biomedical |
| Eppendorf AG |
| Helmer Scientific Inc. |
| Cole-Parmer Instrument Company |
| Carbolite GERO Limited |
| BINDER GmbH |
| Philipp Kirsch GmbH |
| Sheldon Manufacturing Inc. |
| Others |
Supply & Pricing Matrix
Specialized refrigeration engineering talent concentrated in Baden-Württemberg and Bavaria drives labor-cost differentials that widen pricing-tier spreads between European-manufactured cascade systems and Asian-assembled standard-temperature units. This workforce geography compresses margins for mid-tier competitors while enabling German precision engineering houses to sustain premium positioning through qualification documentation bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies procurement decisions in this market. Premium tier pricing draws from ISO 9001-integrated validation documentation and uptime-guarantee service contracts demanded by FDA-regulated pharmaceutical manufacturers. Standard tier competition centers on manufacturing scale advantages serving academic group purchasing organizations. Price erosion runs through economy-tier gravity-convection ovens as mechanical convection units displace legacy designs. Academic institutions exhibit the highest price sensitivity, while cell therapy manufacturers prioritize thermal stability over capital cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized compressor suppliers concentrated in Germany and Japan for ultra-low-temperature cascade systems. Manufacturing of these critical components draws from precision-machined steel castings, hermetic motor windings, and hydrocarbon-compatible lubricant formulations. Tariff exposure on European-sourced refrigeration components creates input cost volatility for North American assembly operations. Distribution runs through direct manufacturer contracts with multi-site research institutions, bypassing traditional distributor relationships in the United States academic medical center segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Laboratory Refrigerators and Ovens Market functions as a stable compounder anchored by irreversible biopharmaceutical cold chain infrastructure buildout. Cell therapy manufacturing scale-up creates durable replacement cycle compression that sustains revenue visibility across economic cycles.
For Market Incumbents: Lock in service contract bundling with uptime-guarantee structures to preempt modular cabinet competitors from eroding aftermarket revenue pools. Deepen backward integration into hydrocarbon refrigerant safety system design to accelerate EU F-Gas compliance timelines ahead of notified body qualification bottlenecks. Prioritize validation documentation automation to offset FDA 21 CFR Part 11 quality engineering talent scarcity.
For New Entrants and Emerging Players: Solid-state Peltier-convection hybrid cooling offers a technology-first wedge into space-constrained urban laboratory clusters in Osaka and Tokyo. Target India biopharma infrastructure white space created by CDSCO regulatory harmonization and PLI scheme incentives. Deploy modular cabinet architectures with swappable compressor modules to penetrate capital-constrained academic institutions in Karnataka and Telangana.
For Investors and Strategic Acquirers: Laboratory infrastructure conglomerates are the most active acquirer in this space, consolidating precision thermal equipment portfolios to anchor biopharma account relationships. Long-term viability rests on exposure to cell therapy manufacturing network expansion rather than cyclical academic capital spending. Monitor EPA SNAP refrigerant phase-down compliance deadlines as inflection indicators for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Cabinet Architecture Launch | Reduces total cost of ownership for capital-constrained academic facilities. |
| Hydrocarbon Refrigerant Transition | Accelerates compliance with EPA SNAP phase-down and EU F-Gas restrictions. |
| Uptime-Guarantee Service Contracts | Captures recurring revenue from FDA-regulated pharmaceutical manufacturers. |
| India Biopharma Infrastructure Entry | Exploits CDSCO harmonization and PLI incentives in vaccine export hubs. |
| Compact Footprint Design Specialization | Addresses space constraints in European urban laboratory clusters. |
Research Methodology
Multiple input streams — structured interviews with biopharma quality assurance directors, academic procurement managers, and thermal equipment maintenance heads; trade data from refrigeration compressor import registries; and regulatory filing analysis from FDA and EPA dockets — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from SEC filings of laboratory infrastructure conglomerates, ISO certification body databases, and EU F-Gas Regulation compliance disclosures. Primary fieldwork captured specification decision dynamics at multi-site research institutions and cell therapy manufacturing facilities.
Data-stream reconciliation across product type, temperature control tier, end-user vertical, and regional regulatory cluster dimensions enabled segmentation-level modeling. Growth trajectory derivation incorporated replacement cycle compression from biopharmaceutical cold chain expansion, refrigerant transition compliance deadlines, and continuous bioprocessing adoption rates. Forecast outputs reflect volume and value reconciliation across the projection horizon without reliance on single-source demand assumptions.
The model holds under steady biopharma manufacturing capacity expansion; deviation in hydrocarbon refrigerant safety standard adoption timelines or compressor supply chain disruption would shift replacement cycle assumptions. Forecasts embody documented assumptions about regulatory harmonization progress and group purchasing organization consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Blood Bank Analyzers Market
Laboratory Equipment
Automated Blood Processing Equipment Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Micropipette Puller Market
Laboratory Equipment
Albumin Analyzers Market
Laboratory Equipment
Microplate Washer Market
Laboratory Equipment
Scalable Clinical Chemistry Analyzers Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Laboratory Data Loggers Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Global Laboratory Grinders Market
Laboratory Equipment
Hemostasis Analyzers Market