
 Blood Bank Analyzers Market | 2026-2036
Blood Bank Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Bank Analyzers Market Analytics
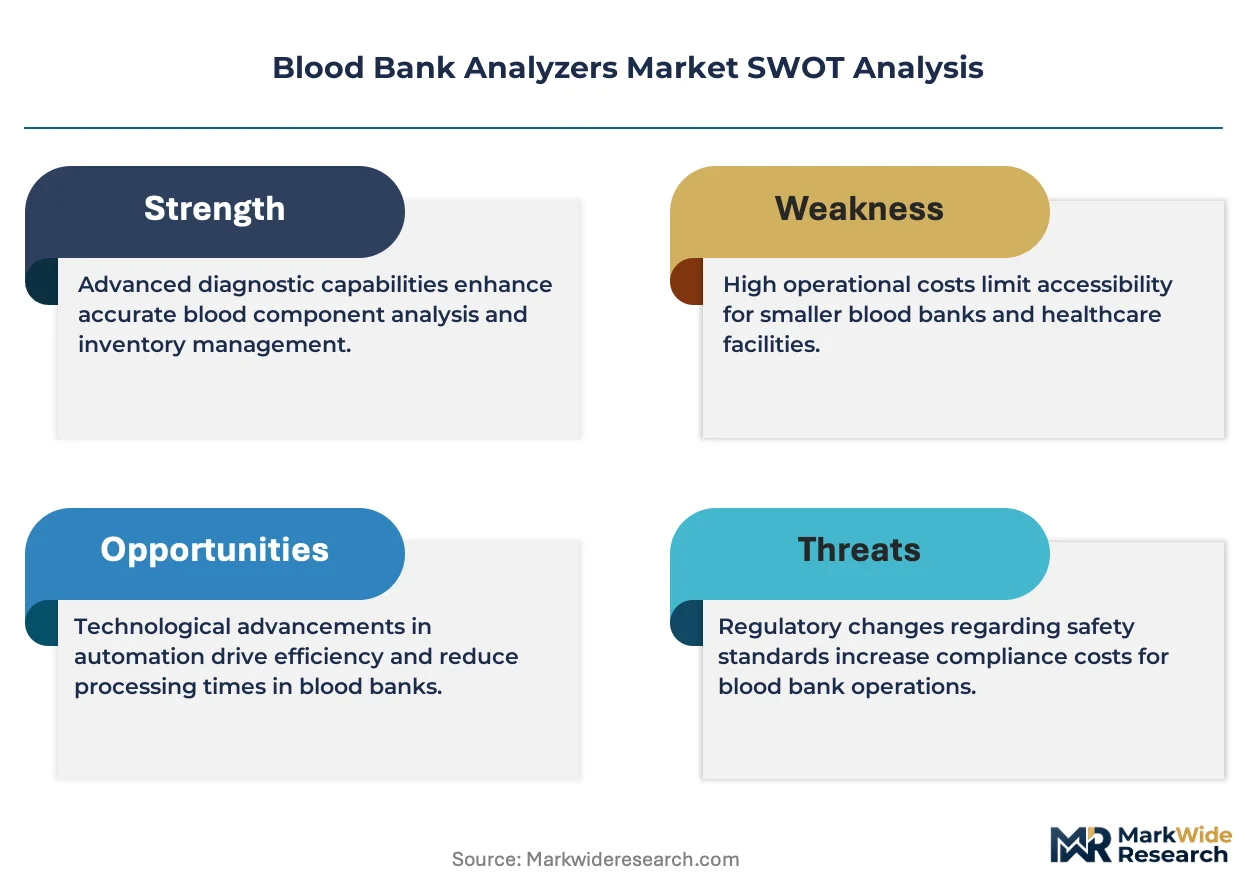
CE marking under the EU In Vitro Diagnostic Regulation is bifurcating the competitive landscape into firms with notified-body certification and those facing market exit. Thermo Fisher Scientific leverages its diagnostic instrument portfolio to sustain installed-base loyalty across European blood centers. Abbott anchors its position through integrated immunoassay-nucleic acid testing workflows that reduce hands-on time in high-volume hospital labs.
Blood bank analyzers are precision instruments that perform serological and molecular testing on donor blood to determine compatibility, detect pathogens, and ensure transfusion safety, typically processing 50-400 samples per hour depending on automation tier. Automated analyzers command the largest revenue share due to labor-cost arbitrage and error-rate reduction in hospital transfusion services, while nucleic acid testing represents the fastest-expanding technology segment as multiplex pathogen detection replaces single-marker screens. Microfluidics-based platforms are gaining share in smaller diagnostic labs where footprint constraints and lower throughput needs predominate.
The FDA governs premarket clearance and quality-system requirements for analyzers sold into US hospital and blood-donation settings, while the EU IVDR imposes stricter clinical-evidence and post-market surveillance obligations that extend product-development timelines. Blood donation centers in Germany face additional scrutiny from the Paul-Ehrlich-Institut regarding nucleic acid testing sensitivity thresholds for HIV and hepatitis C screening. Stakeholders must weigh regulatory-compliance investments against the volume economics of centralized testing hubs as procurement criteria harden around total-cost-of-ownership metrics.
Market Dynamics
The nucleic acid testing transition is compressing replacement cycles for immunoassay-heavy analyzer fleets as hospitals face simultaneous FDA infectious-disease guidance updates and labor-cost arbitrage pressures.
Growth Catalysts
- IVDR CE Marking Mandate:The EU In Vitro Diagnostic Regulation is forcing blood centers toward certified nucleic acid testing platforms, accelerating analyzer refresh rates across European hospital networks.
- Hospital Network Consolidation:Merged US health systems are standardizing on high-throughput analyzers to centralize transfusion services and capture economies of scale in multi-site operations.
- Microfluidics Miniaturization:Reduced footprint platforms are opening diagnostic lab segments previously priced out of automated serology, expanding addressable demand in smaller facilities.
Market Restraints
- Reagent Lock-In Economics:Closed-system consumable contracts tie blood centers to single-vendor analyzer ecosystems, raising switching costs and limiting price competition.
- Specialized Technician Scarcity:Molecular diagnostics expertise concentrates in urban hospital clusters, constraining nucleic acid testing rollout in rural transfusion services.
- Extended IVDR Certification Timelines:Stricter clinical-evidence requirements under the EU regulation are stretching product-development cycles and delaying new entrant market access.
Strategic Opportunities
- Point-of-Care Transfusion Testing:Emergency departments and surgical suites represent untapped demand for rapid-turnaround compatibility analyzers outside centralized blood banks.
- Multiplex Pathogen Panels:Single-run detection of HIV, hepatitis B, hepatitis C, and emerging arboviruses commands premium positioning against single-marker legacy screens.
- India's CDSCO Streamlining:Regulatory pathway improvements for IVD imports are lowering barriers for automated analyzer penetration in private hospital chains.
Industry Challenges
- LIS Integration Complexity:Analyzer middleware must map to diverse hospital information systems, extending deployment timelines and requiring site-specific customization.
- Proficiency Testing Burden:CAP and AABB accreditation mandates demand continuous external quality assessment, consuming operational bandwidth in high-volume transfusion services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Bank Analyzers Market |
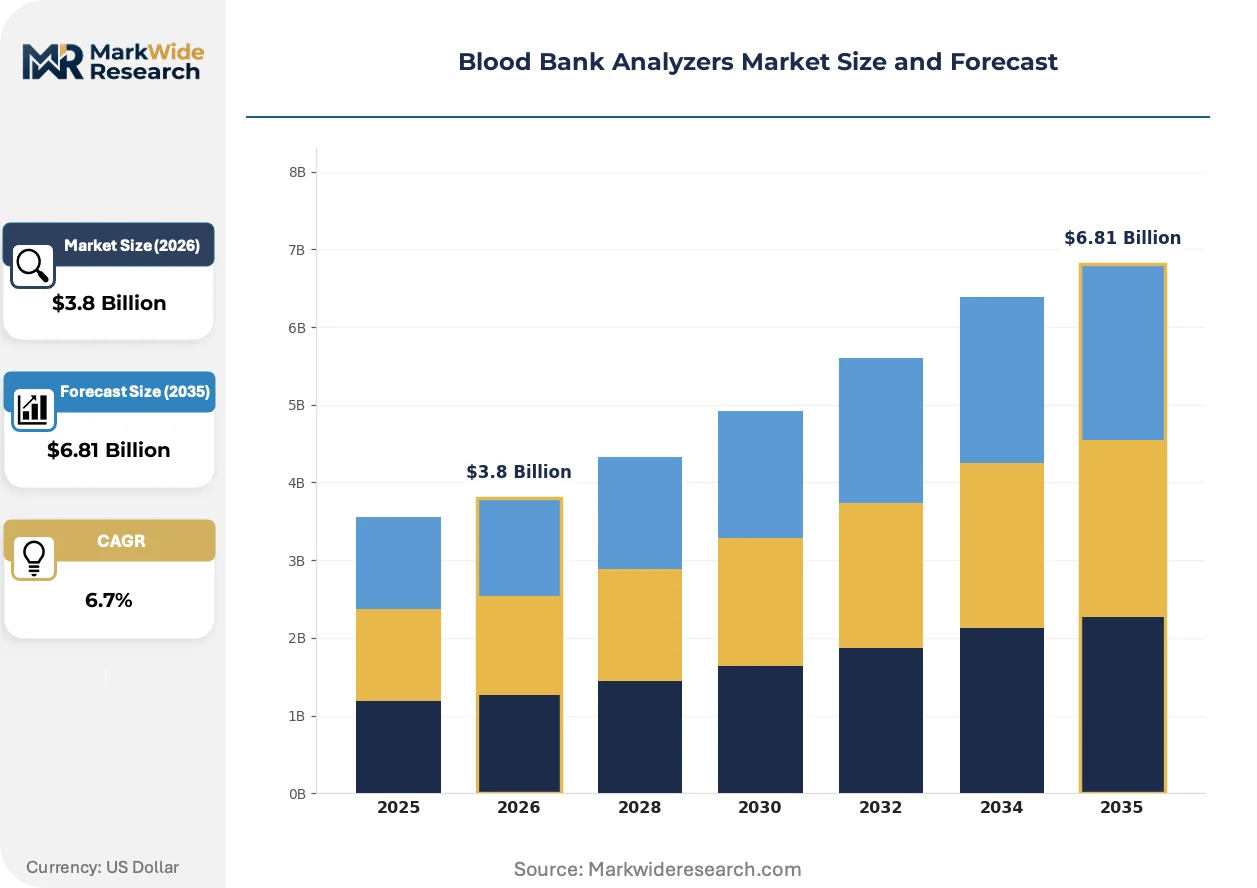
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Analyzers, Automated Analyzers, Semi-Automated Analyzers, Blood Group Testers End User: Hospitals, Blood Donation Centers, Diagnostic Labs, Research Institutions Technology: Microfluidics, Nucleic Acid Testing, Immunoassay, Mass Spectrometry Application: Transfusion Diagnostics, Infectious Disease Testing, Blood Typing, Antibody Screening |
| Companies Covered | Thermo Fisher Scientific, Ortho Clinical Diagnostics, Siemens Healthineers, Abbott, Bio-Rad Laboratories, Beckman Coulter, BioMérieux, Immucor, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Bank Analyzers Market Evolving Landscape
Automation architecture is bifurcating between centralized high-throughput hubs and distributed rapid-testing nodes, with regulatory pressure and workforce constraints driving divergent hardware specifications.
Random-access analyzer architecture is fragmenting the traditional batch-processing paradigm in hospital transfusion services. Mid-sized diagnostic labs are adopting these platforms to eliminate workflow bottlenecks during emergency demand spikes. The shift is compressing market share for fixed-schedule analyzers while expanding serviceable addressable market into previously manual-testing environments.
REACH chemical-substance restrictions are compelling manufacturers to reformulate reagent chemistries and instrument coatings, particularly affecting European analyzer production lines. Blood centers in Germany and France face additional scrutiny on nucleic acid testing sensitivity thresholds from national regulators. The compliance burden is favoring established vendors with dedicated regulatory-affairs infrastructure over smaller competitors.
Total-cost-of-ownership contracting is displacing capital-expenditure purchasing in US hospital procurement. Transfusion service directors now negotiate bundled reagent-analyzer-service agreements spanning five-to-seven-year horizons. This shift concentrates vendor selection authority in health-system supply-chain offices rather than laboratory managers, reshaping sales engagement models toward enterprise-level relationship management.
Blood Bank Analyzers Market Segmentation
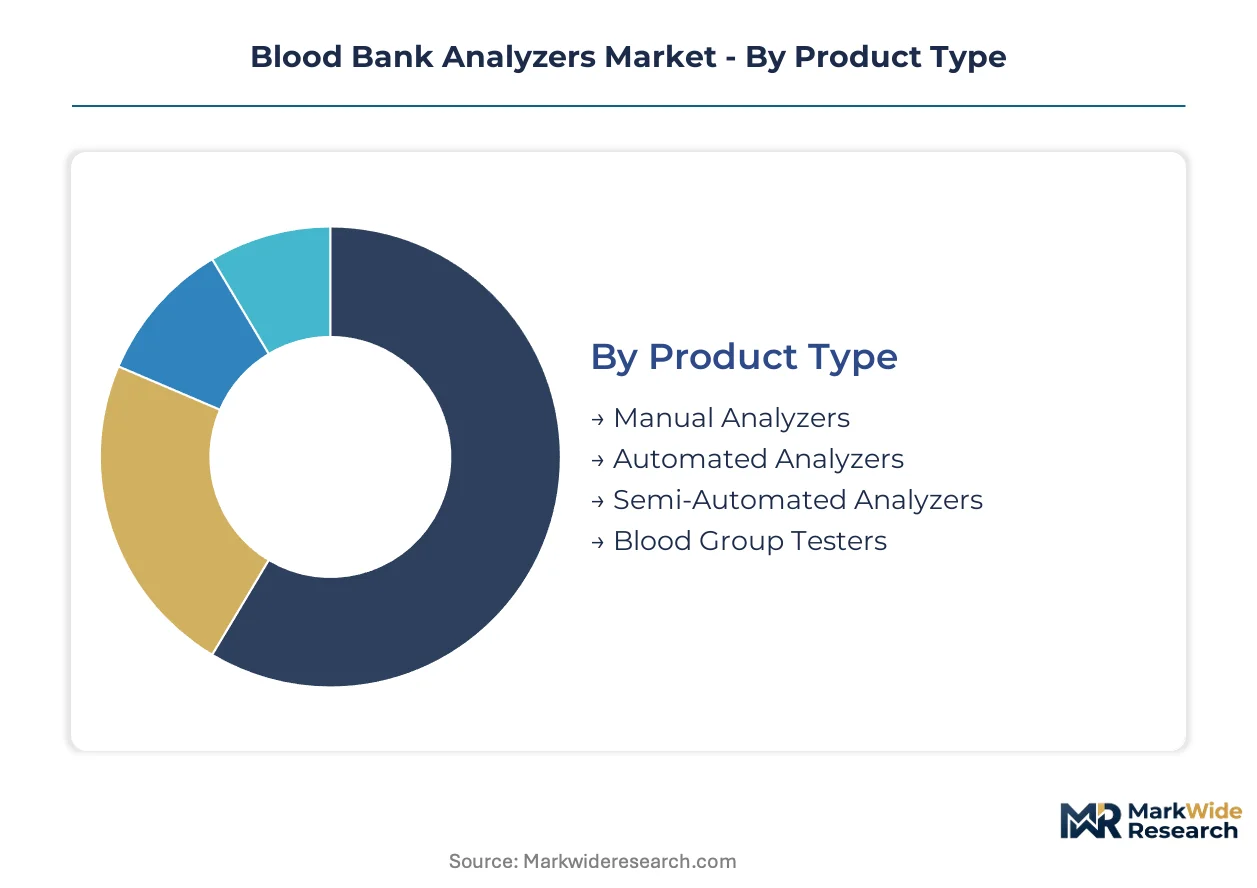
Analyzer segmentation reveals distinct margin architectures across automation tiers, technology platforms, and care settings. Procurement patterns diverge sharply between centralized hospital transfusion services and distributed diagnostic environments, with regulatory compliance costs reshaping vendor economics at each tier.
Product Type:
Margin pools concentrate in automated systems where reagent lock-in and service contracts extend revenue visibility across seven-year replacement cycles.
- Automated Analyzers:These systems process 200-400 samples per hour with walkaway workflow management and integrated LIS connectivity. US hospital networks undergoing consolidation are standardizing on high-throughput platforms from Thermo Fisher and Abbott to centralize multi-site transfusion operations. Labor-cost arbitrage and error-rate reduction drive procurement decisions in high-volume settings.
- Manual Analyzers:Benchtop units requiring technician intervention for each processing step, typically handling under 50 samples per hour. Resource-constrained blood donation centers in rural India and Southeast Asia maintain these systems where capital budgets preclude automation and sample volumes do not justify fully integrated platforms.
- Semi-Automated Analyzers:Hybrid platforms automating sample preparation while retaining manual interpretation stages. Mid-sized diagnostic labs in Germany and France deploy these units where IVDR compliance costs pressure capital expenditure but full automation remains economically unjustified.
- Blood Group Testers:Dedicated single-function devices for ABO/Rh determination with rapid turnaround capabilities. Emergency departments and surgical suites in US trauma centers utilize these for point-of-care compatibility verification outside centralized blood bank workflows.
Automated analyzers hold installed capacity. Semi-automated analyzers are rotating up the share rankings as IVDR certification timelines delay full-platform replacements.
End User:
Procurement authority is shifting from laboratory managers to health-system supply-chain offices as total-cost-of-ownshership contracting displaces capital-expenditure purchasing.
- Hospitals:Transfusion services within acute-care facilities process the highest sample volumes and face the most stringent FDA infectious-disease screening mandates. Consolidated US health systems are deploying standardized analyzer fleets across 10-50 hospital networks to capture procurement leverage and simplify proficiency testing compliance.
- Blood Donation Centers:Standalone collection facilities serving regional donor populations with continuous screening requirements. German centers face additional Paul-Ehrlich-Institut scrutiny on nucleic acid testing sensitivity thresholds for HIV and hepatitis C, favoring vendors with dedicated regulatory-affairs infrastructure.
- Diagnostic Labs:Independent testing facilities serving outpatient and referral markets with variable throughput demands. Microfluidics-based platforms are gaining penetration here where footprint constraints and lower sample volumes predominate.
- Research Institutions:Academic medical centers and blood-banking research organizations evaluating emerging assay methodologies. These sites generate limited commercial revenue but influence technology adoption patterns through clinical validation studies and guideline committee participation.
Hospitals command procurement volume. Diagnostic labs are expanding fastest as distributed testing architectures fragment the traditional centralized model.
Technology:
Platform selection increasingly hinges on multiplex detection capabilities and regulatory clearance status under evolving FDA and IVDR frameworks.
- Nucleic Acid Testing:Molecular amplification platforms detecting viral RNA/DNA with superior sensitivity versus serological methods. The FDA's updated infectious-disease guidance is accelerating hospital transitions from immunoassay-heavy fleets, compressing replacement cycles for legacy systems.
- Immunoassay:Antibody-antigen binding assays for blood typing and infectious disease screening with established regulatory pathways. These platforms retain installed base in budget-constrained settings but face share erosion as nucleic acid testing cost curves flatten.
- Microfluidics:Miniaturized fluid-handling systems integrating multiple assay steps on disposable cartridges. Smaller diagnostic labs in France and the United Kingdom adopt these where laboratory square footage carries premium real-estate costs.
- Mass Spectrometry:High-resolution molecular identification for specialized research applications and rare antigen characterization. Limited commercial deployment due to capital intensity and specialized operator requirements.
Immunoassay platforms hold installed capacity. Nucleic acid testing exhibits the steepest expansion trajectory as regulatory pressure and clinical sensitivity demands converge.
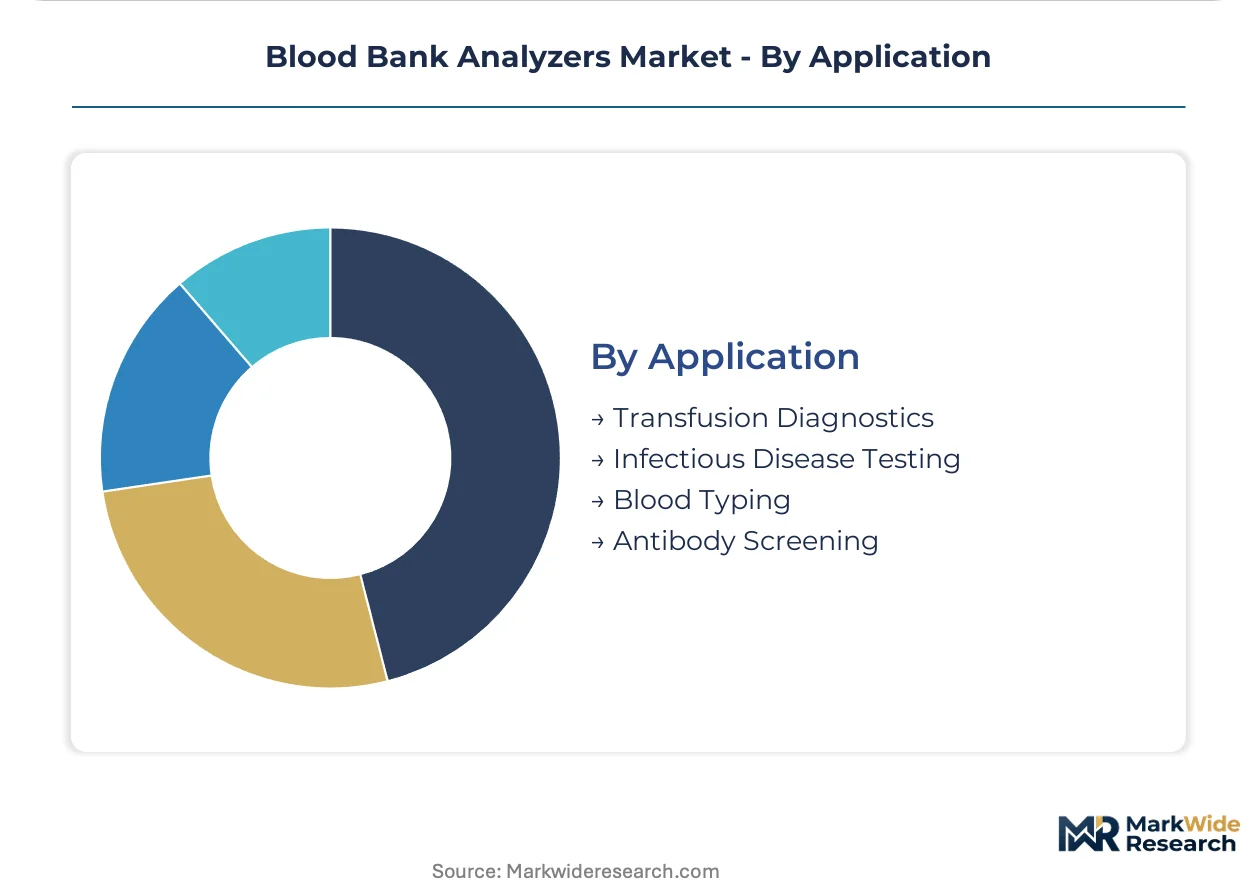
Application:
Testing workflows are fragmenting between routine high-volume screening and emergency rapid-turnaround compatibility verification.
- Infectious Disease Testing:Pathogen screening for HIV, hepatitis B, hepatitis C, and emerging arboviruses in donor blood. Multiplex panels commanding premium positioning against single-marker legacy screens are displacing sequential testing protocols in US blood centers.
- Transfusion Diagnostics:Comprehensive pre-transfusion compatibility testing including crossmatching and antibody identification. Hospital networks are consolidating these services into regional hubs to concentrate specialized technician expertise and justify high-throughput analyzer investments.
- Blood Typing:ABO/Rh determination and extended antigen profiling for donor-recipient matching. Automated platforms have largely saturated this application in developed markets, with growth shifting to emerging economies.
- Antibody Screening:Detection of unexpected erythrocyte antibodies that could trigger transfusion reactions. This application demands high analytical sensitivity and is driving adoption of gel card and solid-phase technologies in European transfusion services.
Transfusion diagnostics holds installed capacity. Infectious disease testing is rotating up the share rankings as pathogen detection panels expand beyond traditional viral targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics infrastructure underwrites Europe's role in analyzer distribution, while direct rail links from Hamburg to Central Asian markets extend German manufacturers' reach into emerging demand centers.
United States
Hospital network consolidation across 10-50 site systems is standardizing analyzer fleets for centralized transfusion services. The FDA's updated infectious-disease screening guidance accelerates nucleic acid testing adoption in high-volume blood centers. The Boston-Cambridge corridor anchors molecular diagnostics R&D, with Massachusetts General Hospital influencing national proficiency testing protocols.
Germany
Blood donation centers face Paul-Ehrlich-Institut scrutiny on HIV and hepatitis C nucleic acid testing sensitivity thresholds. The EU IVDR imposes stricter clinical-evidence requirements that extend product-development timelines for domestic manufacturers. The Rhine-Main cluster around Frankfurt concentrates regulatory-affairs expertise and notified-body relationships.
India
CDSCO streamlining of IVD import pathways is lowering barriers for automated analyzer penetration in private hospital chains. The country's national pharmaceutical regulator is harmonizing device registration with international standards. Maharashtra's Mumbai-Pune corridor hosts the densest concentration of private diagnostic lab chains expanding serology capacity.
Japan
PMDA's structured review pathways for in vitro diagnostics sustain premium pricing for validated analyzer platforms. METI's industrial policy supports domestic production of precision fluid-handling components. The Kansai region around Osaka maintains specialized manufacturing capabilities for immunoassay reagent chemistries.
United Kingdom
NHS Blood and Transplant's standardization programs favor high-throughput analyzers with integrated LIS connectivity for national screening networks. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance aligned with EU IVDR transition timelines. The Cambridge-London corridor attracts microfluidics startups targeting point-of-care transfusion testing applications.
Blood Bank Analyzers Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification capabilities and installed-base service infrastructure. The vendor landscape concentrates around three tiers: diversified life-science conglomerates with diagnostic instrument portfolios, pure-play transfusion diagnostics specialists, and emerging microfluidics platform developers. Strategic differentiation centers on nucleic acid testing workflow integration and total-cost-of-ownership contracting models. Consolidation pressure and IVDR compliance investments are driving M&A activity and partnership formations between instrument manufacturers and assay developers.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Abbott exemplify installed-base loyalty strategies across hospital and blood center networks. Siemens Healthineers occupies a position bridging imaging and laboratory diagnostics portfolios. Among transfusion specialists, Immucor and Bio-Rad Laboratories represent archetypes of reagent-lock-in economics and proficiency testing standard-setting respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Ortho Clinical Diagnostics |
| Siemens Healthineers |
| Abbott |
| Bio-Rad Laboratories |
| Beckman Coulter |
| BioMérieux |
| Immucor |
| Hologic |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for precision fluid-handling components concentrate pricing power with German and Japanese suppliers, while hospital procurement offices exploit consolidated purchasing volumes to compress analyzer margins through multi-year service bundling.
Pricing Analysis
Volume-discount tiering structures separate high-throughput hospital networks from mid-sized diagnostic labs and rural blood donation centers. Three-tier pricing stratifies across premium nucleic acid testing platforms, standard immunoassay systems, and economy manual analyzers. Price differentiation rests on IVDR certification status and installed-base service infrastructure depth. Pricing pressure intensifies as total-cost-of-ownership contracting displaces capital-expenditure purchasing, with health-system supply-chain offices driving hardest bargains. Blood donation centers in Germany and France show highest price sensitivity due to Paul-Ehrlich-Institut compliance investments, while consolidated US hospital networks leverage scale for steepest discounts.
Supply Chain Analysis
Rotterdam port pharmaceutical logistics underwrites European distribution, with single-source vulnerability concentrated in Taiwanese semiconductor foundries supplying analyzer control boards. Manufacturing draws from German precision engineering clusters for optical detection modules, Japanese suppliers for microfluidic cartridges, and US reagent chemistry production. Raw material dependencies include rare-earth magnets for sample-handling robotics, high-purity quartz for optical pathways, and specialized polymer resins for disposable consumables. Tariff exposure runs through trans-Pacific electronics lanes. Distribution feeds from regional assembly hubs through GPO contracts and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through US hospital network consolidation into 10-50 site systems, fragmenting vendor pricing autonomy and forcing concessionary service bundling.
For Market Incumbents: Shield installed-base loyalty through captive reagent supply contracts and IVDR certification acceleration ahead of smaller competitors. Deepen backward integration into nucleic acid testing assay production to offset margin compression from total-cost-of-ownership contracting. Prioritize regulatory-affairs infrastructure investment to navigate extended EU IVDR timelines that threaten market access. For New Entrants and Emerging Players: Point-of-care transfusion testing in US emergency departments represents an under-served service layer where incumbents lack rapid-turnaround portfolio depth. Target India's private hospital chains leveraging CDSCO streamlining for automated analyzer penetration. Pursue microfluidics miniaturization for diagnostic lab segments priced out of high-throughput platforms. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because IVDR compliance investments and reagent-lock-in economics favor scaled platforms with dedicated regulatory infrastructure. Acquisition target archetype: transfusion diagnostics specialists with nucleic acid testing workflow integration and established proficiency testing relationships. Watch FDA infectious-disease guidance updates as inflection signals for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | IVDR certification accelerates analyzer refresh rates across European hospital networks. |
| Hospital System Partnership | Multi-site standardization captures procurement leverage in consolidated US health systems. |
| Software Companion Development | LIS integration middleware reduces deployment friction and extends contract duration. |
| Reimbursement Strategy | Multiplex pathogen panel positioning commands premium against single-marker legacy screens. |
| Regulatory Approval Pathway | CDSCO streamlining lowers barriers for automated analyzer penetration in Indian private chains. |
Research Methodology
Operator-level perspectives from transfusion service directors, hospital procurement managers, blood center laboratory supervisors, and IVD regulatory affairs leads anchored the qualitative base. Primary interview insights triangulated against FDA 510(k) filings, EU IVDR notified-body documentation, hospital GPO contract databases, and Paul-Ehrlich-Institut technical guidance. Secondary validation drew from AABB proficiency testing records and CAP accreditation standards. Bottom-up analyzer shipment modeling converged with top-down healthcare expenditure allocation analysis.
Sensitivity analysis tested nucleic acid testing adoption velocity and IVDR certification timeline scenarios across the projection horizon. Segmentation dimensions spanned automation tier, technology platform, end-user setting, and regional regulatory cluster. CAGRs derived from installed-base replacement cycle analysis and reagent consumable attach-rate modeling. Forecast inputs incorporated hospital consolidation pace and infectious-disease screening mandate evolution.
Underlying assumptions cover nucleic acid testing cost curve flattening and IVDR transition completion, with deviation risk concentrated in regulatory timeline extensions and rural technician scarcity constraints. Practitioners should keep alternative scenarios live as FDA guidance updates and EU IVDR enforcement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Microplate System Market
Laboratory Equipment
Global Automated Analyzers Market
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
Histopathology Laboratory Equipment Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Blood Testing Equipment Market
Laboratory Equipment
Global Laboratory Grinders Market
Laboratory Equipment
Benchtop Centrifuges Market
Laboratory Equipment
Microplate Handling Instruments Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
US Cath Labs Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
Micropipette Puller Market
Laboratory Equipment
Histopathology Testing Equipment Market