
 Microplate Washer Market | 2026-2036
Microplate Washer Market Size, Share, and Industry Trends Forecast 2026-2036
Microplate Washer Market Outlook
Diagnostic testing is decoupling from research laboratory budgets as hospital-affiliated labs expand immunoassay throughput. Tecan Trading AG leverages its liquid-handling heritage to anchor automated washer placements in European diagnostic networks. BioTek Instruments specializes in multi-mode integration, while Thermo Fisher Scientific dominates aftermarket reagent and consumable pull-through across North American clinical accounts.
A microplate washer is a laboratory instrument that removes unbound reagents from assay plates through programmed wash cycles, typically delivering residual volumes below 2 microliters per well to preserve assay sensitivity in ELISA and cell-based protocols. Automated washers command the product type margin pool due to reagent lock-in and service contract attachment, whereas ultrasonic technology within the mechanical-versus-pressure segmentation attracts cytology workflows requiring gentle cell retention. Research laboratories still represent the largest end user installed base, though pharmaceutical companies generate faster replacement cycles driven by GLP audit requirements.
FDA 21 CFR Part 820 and the EU In Vitro Diagnostic Regulation impose design-control and post-market surveillance obligations that lengthen product development timelines but raise barriers against unvalidated imports. ISO 13485 certification has become a de facto market-access filter for OEM supply relationships with diagnostic instrument integrators. Stakeholders must weigh reagent ecosystem captivity against open-platform flexibility when evaluating automated washer procurement strategies.
Market Dynamics
Automated liquid-handling integration is compressing replacement cycles for standalone washers as diagnostic networks consolidate onto unified ELISA platforms. This structural force reconfigures vendor relationships around service contract bundling rather than equipment margins alone.
Growth Catalysts
- EU In Vitro Diagnostic Regulation:Post-market surveillance obligations for Class B devices mandate validated wash protocols, compelling diagnostic centers to upgrade legacy equipment. German central laboratories lead this replacement wave.
- Cell-based assay expansion:Cytology workflows requiring gentle cell retention drive ultrasonic washer adoption in pharmaceutical toxicology departments. These protocols demand residual volumes below 2 microliters per well.
- GLP audit requirements:Pharmaceutical quality units enforce documented wash validation trails, accelerating equipment refresh timelines. Auditors now trace calibration records across multi-year study archives.
Market Restraints
- Stainless steel supply concentration:Precision-grade 316L sourcing clusters in Chinese and German mills, exposing OEMs to alloy price volatility and export licensing delays.
- FDA 21 CFR Part 820 design controls:Validation protocol documentation extends product development timelines by 8-14 months for new washer platforms seeking US market entry.
- Manual washer substitution:Low-throughput research laboratories in emerging markets retain hand-held wash bottles for cost containment, capping automated system penetration.
Strategic Opportunities
- India diagnostic network expansion:The country's PLI scheme for medical devices reduces import duties on automated washer components, enabling local assembly partnerships with domestic distributors.
- Multi-mode instrument convergence:Washer-reader integration platforms address space constraints in urban hospital laboratories. Buyers seek consolidated footprints over discrete instruments.
- Reagent ecosystem captivity:Proprietary wash buffer formulations create recurring revenue streams. Vendors bundle consumable supply contracts with equipment leases.
Industry Challenges
- ISO 13485 certification timelines:OEM supply relationships with diagnostic instrument integrators require 12-18 month quality system audits, delaying new product launches.
- Legacy LIMS integration:Hospital IT departments struggle to embed washer data streams into existing laboratory information management architectures. Middleware development consumes implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microplate Washer Market |
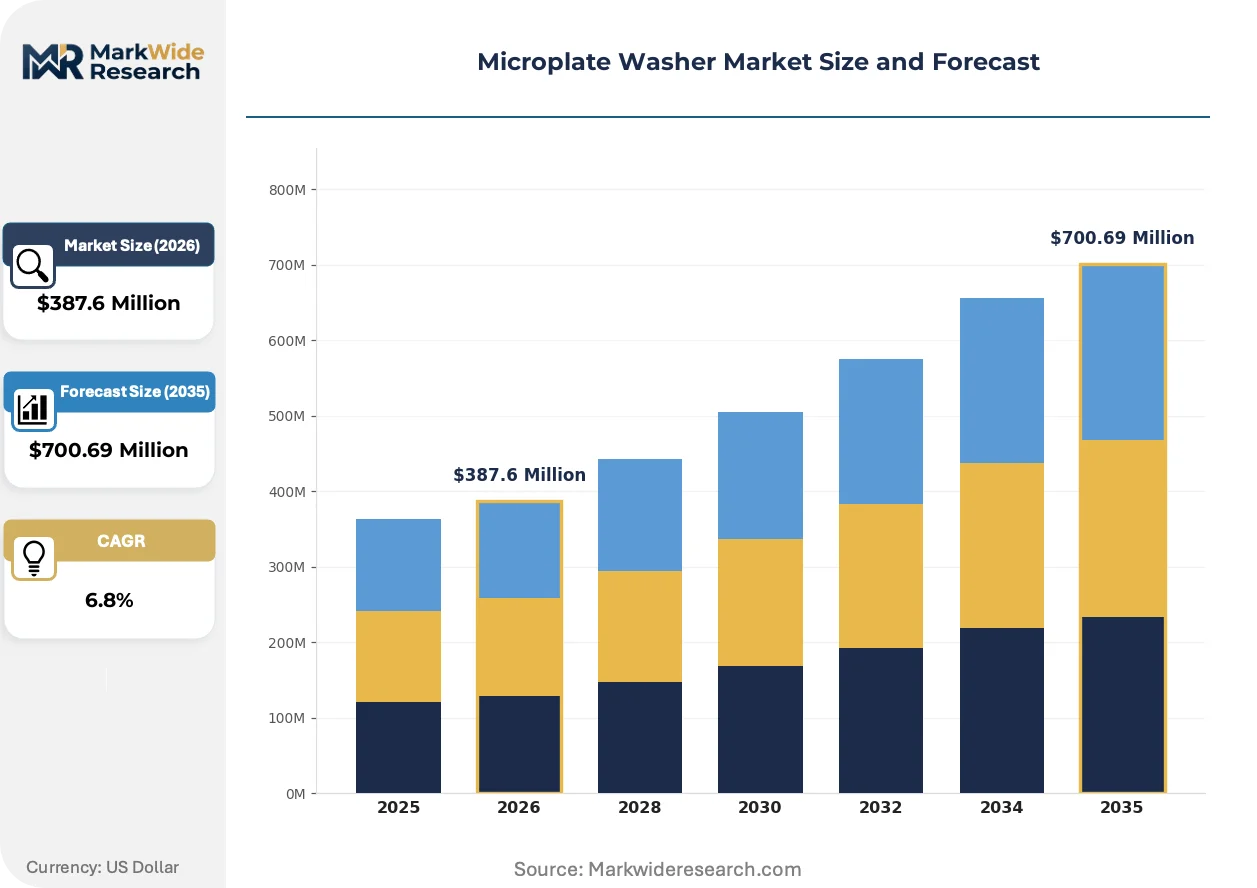
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Washers, Automated Washers, Reagents, Accessories Technology: Mechanical, Ultrasonic, Pressure-Based, Optical End User: Research Laboratories, Diagnostic Centers, Pharmaceutical Companies, Academic Institutions Application: Immunoassays, Cell Culture, Molecular Biology, Diagnostic Testing |
| Companies Covered | Tecan Trading AG, Molecular Devices, Thermo Fisher Scientific, Bio-Rad Laboratories, Agilent Technologies, BioTek Instruments, Berthold Technologies, Shenzhen Mindray Bio-Medical Electronics, Autobio Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microplate Washer Market Strategic Shifts
Microplate washer architecture is bifurcating between open-platform flexibility and closed reagent ecosystems. This divergence reflects deeper tensions between diagnostic network standardization and research laboratory customization requirements.
Ultrasonic wash technology is converging with pressure-based manifold systems in hybrid platforms. Pharmaceutical toxicology departments adopt these dual-mode instruments to handle both adherent cell monolayers and suspension assays without instrument swaps. The convergence compresses capital expenditure by eliminating redundant equipment purchases while expanding protocol versatility within single footprints.
REACH substance restrictions on perfluorinated compounds are forcing solvent-resistant seal material redesigns. European OEMs now specify FFKM or EPDM alternatives in pump and valve assemblies. Diagnostic instrument integrators in Germany and Switzerland demand material compliance certificates before qualifying new washer models for central laboratory placements.
Service contract unbundling is fragmenting traditional procurement patterns. North American hospital-affiliated laboratories now separate equipment acquisition from maintenance agreements, soliciting third-party service providers for calibration and preventive maintenance. This behavior is most visible in academic medical centers with captive biomedical engineering departments capable of in-house repair.
Microplate Washer Market Segmentation
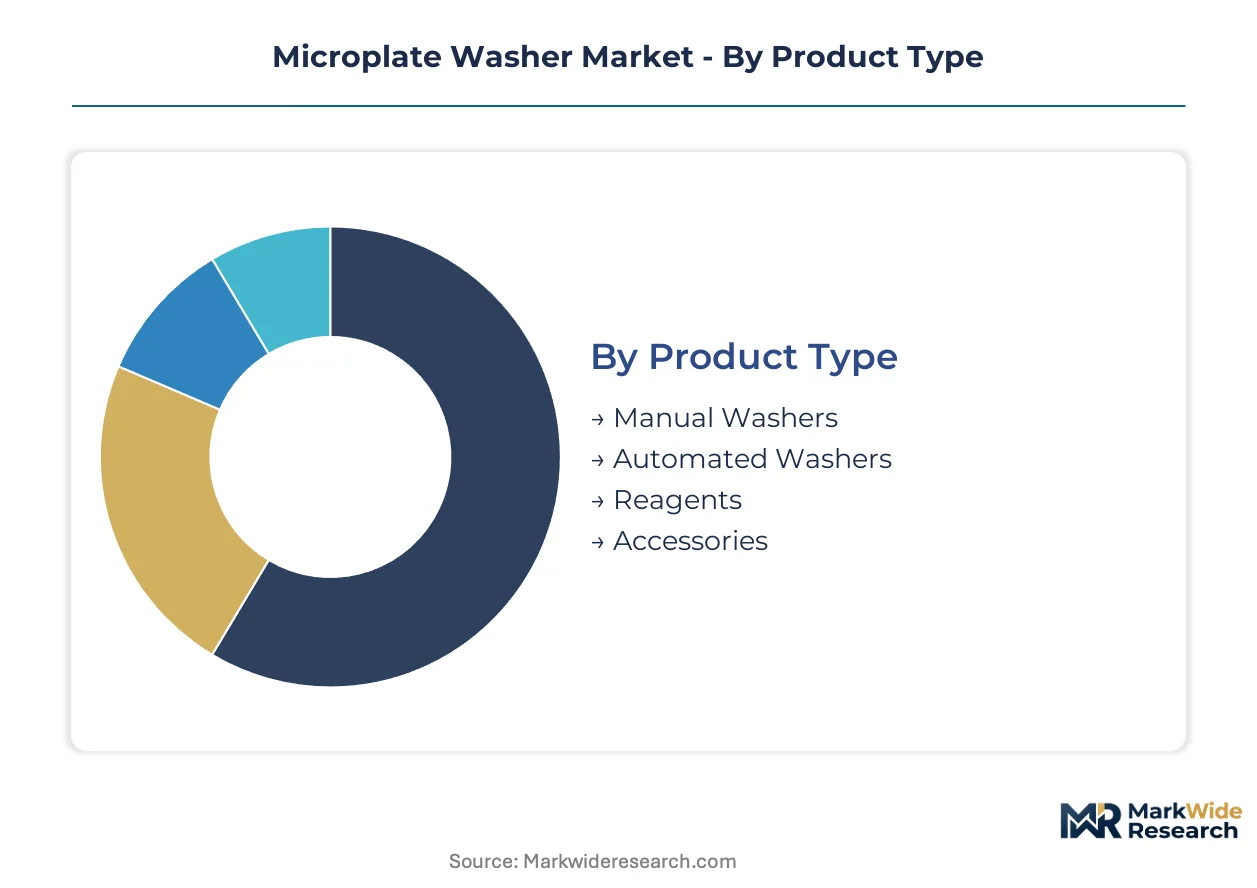
Microplate washer procurement splits sharply between regulated clinical environments demanding validated protocols and research settings prioritizing flexibility. Certification requirements cascade differently across each segment category, reshaping vendor access and pricing power.
Product Type:
FDA 21 CFR Part 820 governs automated washers as in vitro diagnostic device components, while manual systems fall outside design-control obligations. ISO 13485 certification becomes mandatory for any product category supplying OEM integrators.
- Automated Washers:These systems deliver programmed wash cycles with residual volumes below 2 microliters per well through precision manifold or ultrasonic architectures. Diagnostic centers in Germany anchor replacement demand as central laboratory consolidation eliminates legacy standalone units. Service contract bundling now dominates vendor economics.
- Manual Washers:Hand-held wash bottles and simple manifold devices serve cost-constrained research environments. Emerging market laboratories in India retain these systems for low-throughput ELISA workflows, capping automated penetration despite PLI scheme incentives for local assembly.
- Reagents:Proprietary wash buffers create recurring revenue streams through equipment-locked formulations. REACH substance restrictions on perfluorinated compounds force FFKM and EPDM seal material redesigns in European supply chains.
- Accessories:Replacement manifolds, tubing sets, and calibration standards support installed base maintenance. Aftermarket pull-through concentrates in North American hospital-affiliated laboratories with captive service capabilities.
Leading the category by volume: Automated Washers. Growing fastest: Reagents.
Technology:
Cost tiers separate mature pressure-based systems from premium ultrasonic platforms, with hybrid architectures commanding intermediate positioning. German and Swiss diagnostic networks drive specification standards through central laboratory procurement consolidation.
- Mechanical:Peristaltic pump and vacuum aspiration systems dominate legacy installed bases. Research laboratories in academic medical centers retain these workhorses for standard ELISA protocols where cell fragility is not a constraint.
- Ultrasonic:Gentle acoustic energy removes unbound reagents without shear forces that disrupt adherent cell monolayers. Pharmaceutical toxicology departments in Germany and Switzerland specify these systems for cytology workflows requiring documented validation trails under GLP audit protocols.
- Pressure-Based:Precision manifold arrays deliver uniform wash volumes across 96- and 384-well formats. Diagnostic centers favor these systems for high-throughput immunoassay standardization.
- Optical:Integrated sensors monitor wash efficiency through fluorescence or absorbance detection. Multi-mode instrument convergence drives adoption in space-constrained urban hospital laboratories.
Volume concentration: Pressure-Based. Steepest expansion trajectory: Ultrasonic.
End User:
Customer type determines replacement cycle velocity, with pharmaceutical quality units enforcing the most aggressive equipment refresh timelines. Academic institutions fragment purchasing authority across individual principal investigators.
- Pharmaceutical Companies:GLP audit requirements mandate documented wash validation trails with multi-year calibration record retention. These quality protocols compress replacement cycles to 4-6 years versus 8-10 in research settings.
- Diagnostic Centers:EU In Vitro Diagnostic Regulation post-market surveillance obligations for Class B devices compel legacy equipment upgrades. German central laboratories lead this replacement wave through consolidated procurement.
- Research Laboratories:The largest installed base by unit count, though slower replacement cycles and price sensitivity limit revenue per account. Open-platform flexibility outweighs reagent ecosystem captivity in purchasing criteria.
- Academic Institutions:Grant-funded principal investigators maintain fragmented purchasing authority. Shared core facilities increasingly consolidate washer access, mimicking diagnostic network centralization patterns.
Highest revenue per account: Pharmaceutical Companies. Fastest volume growth: Diagnostic Centers.
Application:
Application maturity varies dramatically, with immunoassay standardization enabling automation while cell culture protocols retain customization requirements. Molecular biology workflows impose nucleic acid contamination controls that reshape washer specifications.
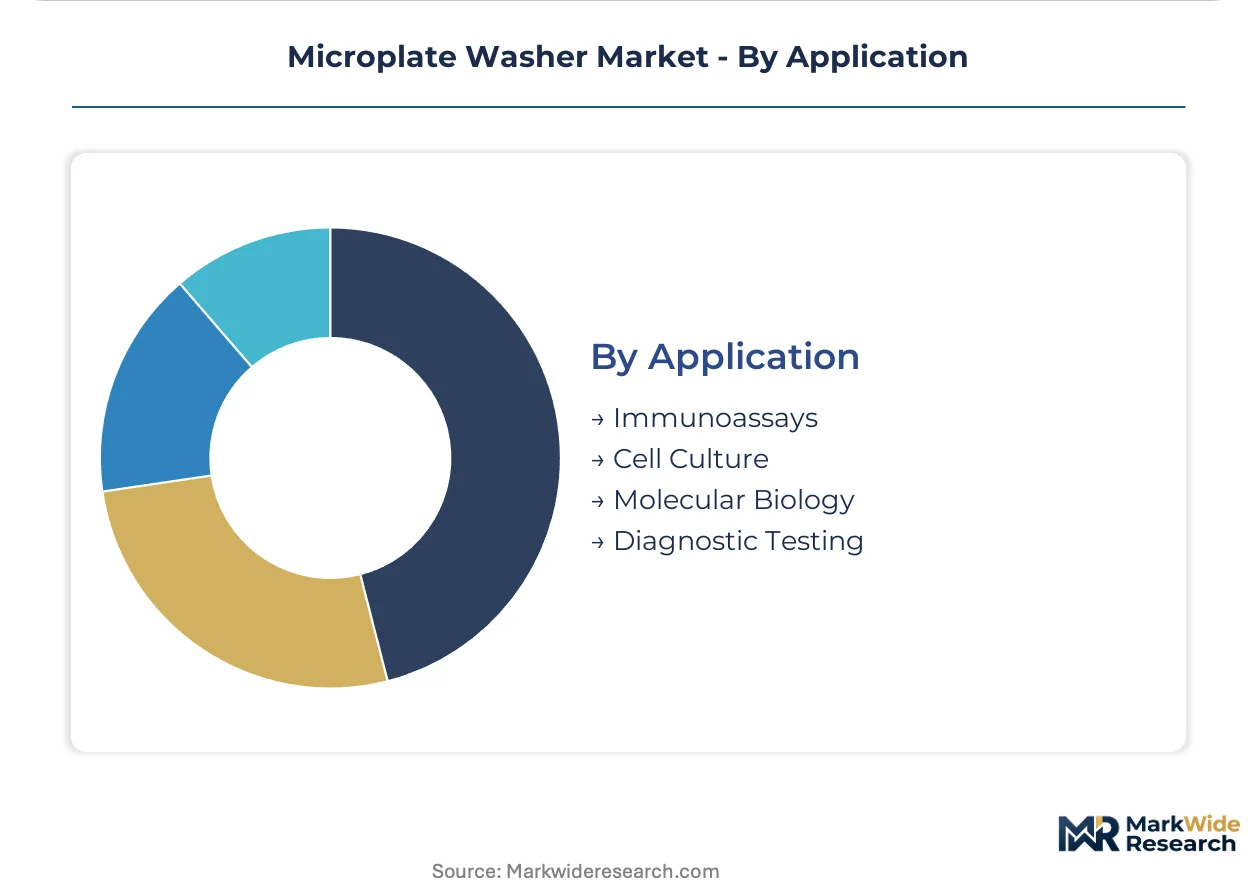
- Immunoassays:ELISA standardization drives the deepest automation penetration, with residual volume specifications below 2 microliters per well preserving assay sensitivity. Diagnostic networks consolidate onto unified platforms with locked reagent ecosystems.
- Cell Culture:Cytology workflows demand gentle cell retention through ultrasonic or low-shear pressure systems. Pharmaceutical toxicology departments adopt hybrid platforms to handle both adherent monolayers and suspension assays.
- Molecular Biology:PCR and nucleic acid detection protocols require DNase-free wash buffers and dedicated fluidic paths. Cross-contamination controls add specification complexity.
- Diagnostic Testing:Clinical chemistry and serology applications prioritize throughput and walkaway automation. FDA 21 CFR Part 820 design controls extend development timelines for new platform introductions.
Deepest automation penetration: Immunoassays. Fastest specification evolution: Cell Culture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Pudong concentrate automated washer assembly capacity through bonded logistics and duty exemptions on precision-grade 316L stainless steel imports. Diagnostic network consolidation in Germany and hospital-affiliated laboratory expansion in the United States anchor replacement demand.
United States
Hospital-affiliated laboratories expand ELISA throughput as diagnostic testing decouples from research budgets. FDA 21 CFR Part 820 design controls extend development timelines for new platform introductions. Greater Boston and Research Triangle Park clusters drive automated washer placements in academic medical centers with captive biomedical engineering departments.
Germany
Central laboratory consolidation eliminates legacy standalone units across diagnostic networks. EU In Vitro Diagnostic Regulation post-market surveillance obligations for Class B devices compel equipment upgrades. The Rhine-Ruhr metropolitan region anchors replacement cycles for high-throughput systems through consolidated procurement.
China
Domestic diagnostic instrument integrators demand ISO 13485 certification from OEM suppliers. The country's national medical products regulator enforces design-control documentation for in vitro diagnostic device components. Shenzhen Special Economic Zone concentrates automated washer assembly partnerships with precision-grade alloy sourcing from Yangtze River Delta mills.
India
The PLI scheme for medical devices reduces import duties on automated washer components. The national pharmaceutical regulator mandates quality system audits for diagnostic equipment supply relationships. Maharashtra and Gujarat host emerging local assembly partnerships with domestic distributors serving diagnostic network expansion.
Switzerland
Diagnostic instrument integrators demand REACH substance compliance certificates before qualifying new washer models. Swissmedic oversees post-market surveillance obligations for Class B in vitro diagnostic devices. Basel and Zurich clusters specify ultrasonic platforms for pharmaceutical toxicology workflows requiring documented validation trails.
Microplate Washer Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with automated system vendors capturing service contract economics while manual washer fabricators compete on landed cost. The vendor base concentrates around liquid-handling heritage, multi-mode integration capability, and reagent ecosystem captivity. Three archetypes dominate: European precision-engineering houses, North American life-science conglomerates with aftermarket pull-through, and Asia-Pacific cost-optimized assemblers. M&A activity targets reagent formulation capabilities, while strategic partnerships with diagnostic instrument integrators secure OEM placement.
Among Swiss and German precision-engineering specialists, Tecan Trading AG and Berthold Technologies exemplify the liquid-handling heritage archetype through European diagnostic network anchoring. Thermo Fisher Scientific occupies a position as a North American life-science conglomerate with consumable and reagent aftermarket economics. Shenzhen Mindray Bio-Medical Electronics represents Asia-Pacific scale-driven assembly with domestic supply chain integration.
| Leading Market Players |
|---|
| Tecan Trading AG |
| Molecular Devices |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Agilent Technologies |
| BioTek Instruments |
| Berthold Technologies |
| Shenzhen Mindray Bio-Medical Electronics |
| Autobio Diagnostics |
| Others |
Value Chain & Pricing Dynamics
Precision fluidics engineering talent clusters in southern Germany and the Swiss cantons of Basel-Stadt and Zurich, where labor-cost differentials of 40-60% versus Asia-Pacific assembly hubs sustain pricing-tier spreads between automated diagnostic platforms and manual research-grade units.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with diagnostic networks paying 15-25% premiums for validated systems available within 90-day windows versus spot-inventory discounts for research-grade units with 6-month delivery horizons. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated automated washers with ISO 13485 certification from CE-marked clinical units and unvalidated manual systems. Price differentiation hinges on reagent ecosystem captivity and service contract bundling. Pricing pressure stems from hospital-affiliated laboratories unbundling maintenance agreements and soliciting third-party calibration providers. Academic medical centers exhibit highest price sensitivity; pharmaceutical quality units demonstrate lowest sensitivity due to GLP audit non-negotiability.
Supply Chain Analysis
Precision-grade 316L stainless steel supply rests on specialty alloy mills concentrated in Germany's Ruhr region and China's Yangtze River Delta, with secondary forging capacity in Japan's Kansai industrial corridor. Critical dependencies include peristaltic pump heads, FFKM seal assemblies, and ultrasonic transducer arrays. Single-source vulnerability concentrates in German precision-manufactured manifold blocks, where export licensing delays expose OEMs to 8-14 month procurement gaps. Distribution runs through diagnostic instrument integrators in Germany and Switzerland, direct hospital system contracts in the United States, and domestic distributor partnerships in India under PLI scheme incentives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA 21 CFR Part 820 design controls and EU In Vitro Diagnostic Regulation post-market surveillance obligations erect barrier-to-entry moats favoring incumbent players with captive quality infrastructure.
For Market Incumbents: Hedge against service contract unbundling by deepening reagent ecosystem captivity through proprietary wash buffer formulations locked to equipment serial numbers. Acquire ultrasonic technology specialists to defend against hybrid-platform displacement in pharmaceutical toxicology workflows. Prioritize backward integration into precision-grade 316L sourcing to mitigate alloy price volatility exposure. For New Entrants and Emerging Players: Domestic distributors in Maharashtra and Gujarat represent the most penetrable channel archetype for local assembly partnerships under India's PLI scheme. Target cost-constrained research laboratories in emerging markets where manual washer substitution persists despite automation tailwinds. Pursue white-label OEM supply relationships with diagnostic instrument integrators lacking in-house washer fabrication capabilities. For Investors and Strategic Acquirers: The window for entry favors reagent formulation specialists with existing ISO 13485 certification infrastructure and validated buffer portfolios. Long-term viability hinges on recurring revenue economics rather than equipment margin capture. Watch for consolidation signals when central laboratory procurement in Germany shifts from replacement cycles to first-time automated platform adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Ecosystem Captivity | Proprietary wash buffer formulations lock diagnostic centers into recurring consumable contracts with 85-90% gross margins. |
| Ultrasonic Technology Acquisition | Hybrid platform capabilities address pharmaceutical toxicology demand for gentle cell retention without instrument swaps. |
| ISO 13485 Certification Investment | Mandatory quality system audits enable OEM supply relationships with diagnostic instrument integrators in Germany and Switzerland. |
| PLI Scheme Local Assembly Partnership | Reduced import duties on automated washer components enable cost-competitive positioning in India's expanding diagnostic networks. |
| Service Contract Unbundling Response | Third-party calibration provider partnerships retain hospital-affiliated laboratory relationships despite procurement pattern fragmentation. |
Study Parameters
Multi-period observation of ELISA throughput expansion, central laboratory consolidation patterns, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with diagnostic network procurement directors, biomedical engineering heads at academic medical centers, pharmaceutical quality unit managers, OEM supply chain executives, and third-party calibration service operators. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, German hospital procurement registries, and Indian PLI scheme beneficiary disclosures. Bottom-up installed base modeling and top-down diagnostic spending allocation triangulated market sizing.
Segment-weighting approaches applied differential growth coefficients across automated versus manual product types, pressure-based versus ultrasonic technology architectures, and pharmaceutical versus diagnostic center end-user categories. Modeled dimensions spanned reagent ecosystem captivity levels, validation protocol stringency tiers, and regional regulatory framework clusters. CAGRs derived from replacement cycle velocity differentials, with specific inputs including GLP audit frequency trends and EU In Vitro Diagnostic Regulation implementation pace across member states.
Caveats apply where stainless steel alloy export licensing delays, REACH substance restriction scope expansions, or diagnostic network M&A consolidation could materially shift equipment procurement timelines and vendor selection criteria. A small set of named triggers—German central laboratory procurement centralization velocity, Indian PLI scheme component localization thresholds, and FDA design-control documentation burden evolution—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Centrifuge Tubes Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Micropipette Puller Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
United States Pipette Tips Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Global Hematology Instruments and Reagents Market
Laboratory Equipment
Global Hematology Analyzers and Reagents Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Molecular Microplate Readers and Washers Market
Laboratory Equipment
Albumin Analyzers Market