
 Automated Solid Phase Extraction Systems Market | 2026-2036
Automated Solid Phase Extraction Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Solid Phase Extraction Systems Market Outlook
Consumables and service revenue is fragmenting across instrument vendors and third-party suppliers as labs seek cost containment. Gilson Incorporated anchors its position through deep specialization in liquid handling automation that extends into SPE workflows. Merck KGaA leverages its chromatography consumables portfolio to sustain recurring revenue streams alongside system placements. Biotage competes on application-specific method development support that differentiates its offering in pharmaceutical quality control.
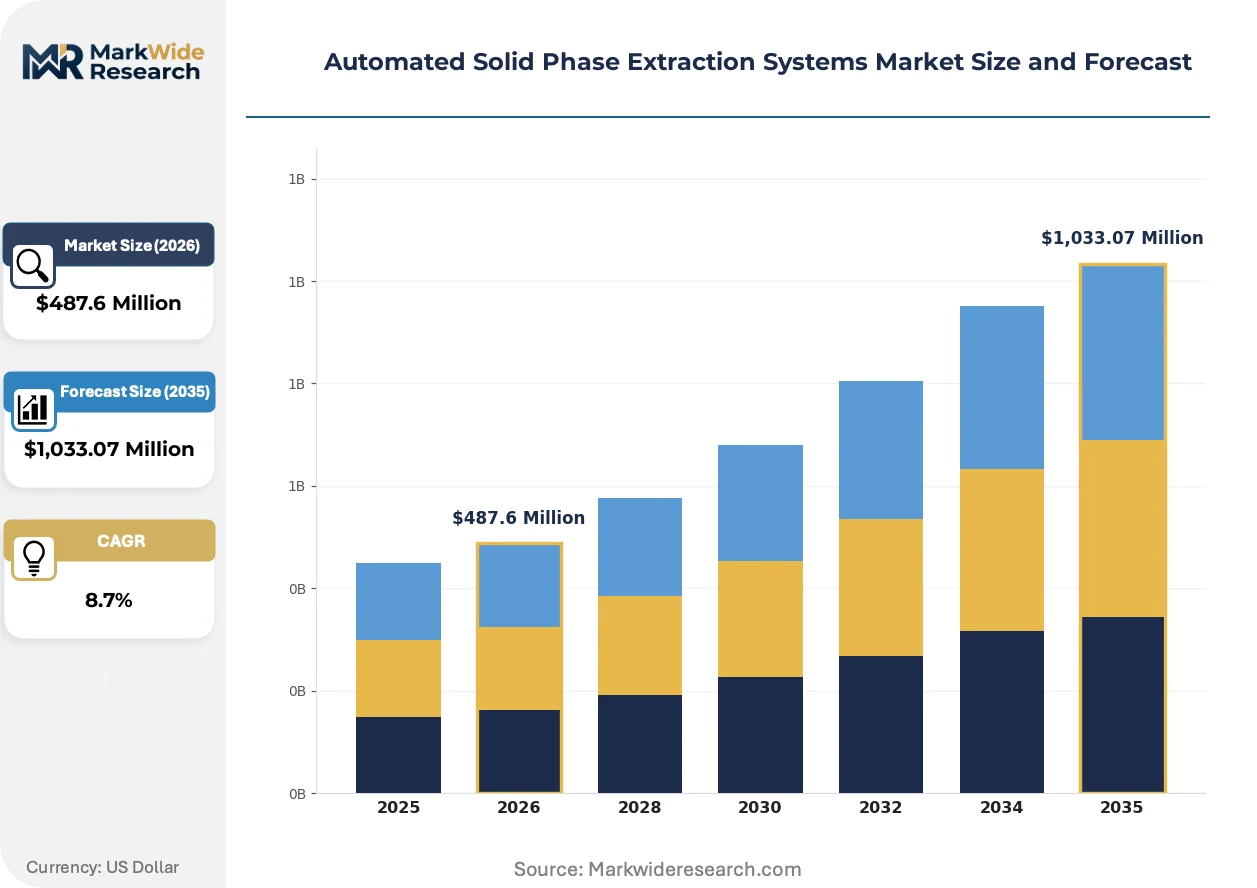
Automated solid phase extraction systems are programmable liquid-handling platforms that pass samples through conditioned sorbent cartridges to isolate target analytes, achieving recovery rates typically exceeding 85% for polar and non-polar compounds alike. Their primary purpose is eliminating manual solvent partitioning in regulated laboratories where reproducibility and traceability govern method acceptance. Benchtop systems dominate current installed bases due to throughput requirements in centralized pharmaceutical analytical labs, while modular configurations represent the fastest-growing architecture as facilities reconfigure workflows for multi-method flexibility. Environmental testing labs drive disproportionate demand growth for portable systems deployed at field sampling sites where immediate stabilization prevents analyte degradation.
FDA method validation guidelines and EPA SW-846 protocols mandate documented precision and recovery thresholds that automated SPE systems satisfy more reliably than manual alternatives. EMA's ICH Q2(R1) analytical procedure validation requirements reinforce this demand in European pharmaceutical release testing. ISO 17025 accreditation pressures on contract laboratories amplify the need for auditable automation across both jurisdictions. Stakeholders must monitor evolving PFAS regulatory expansion and corresponding method updates that will reshape cartridge chemistry requirements and system configurability demands.
Market Dynamics
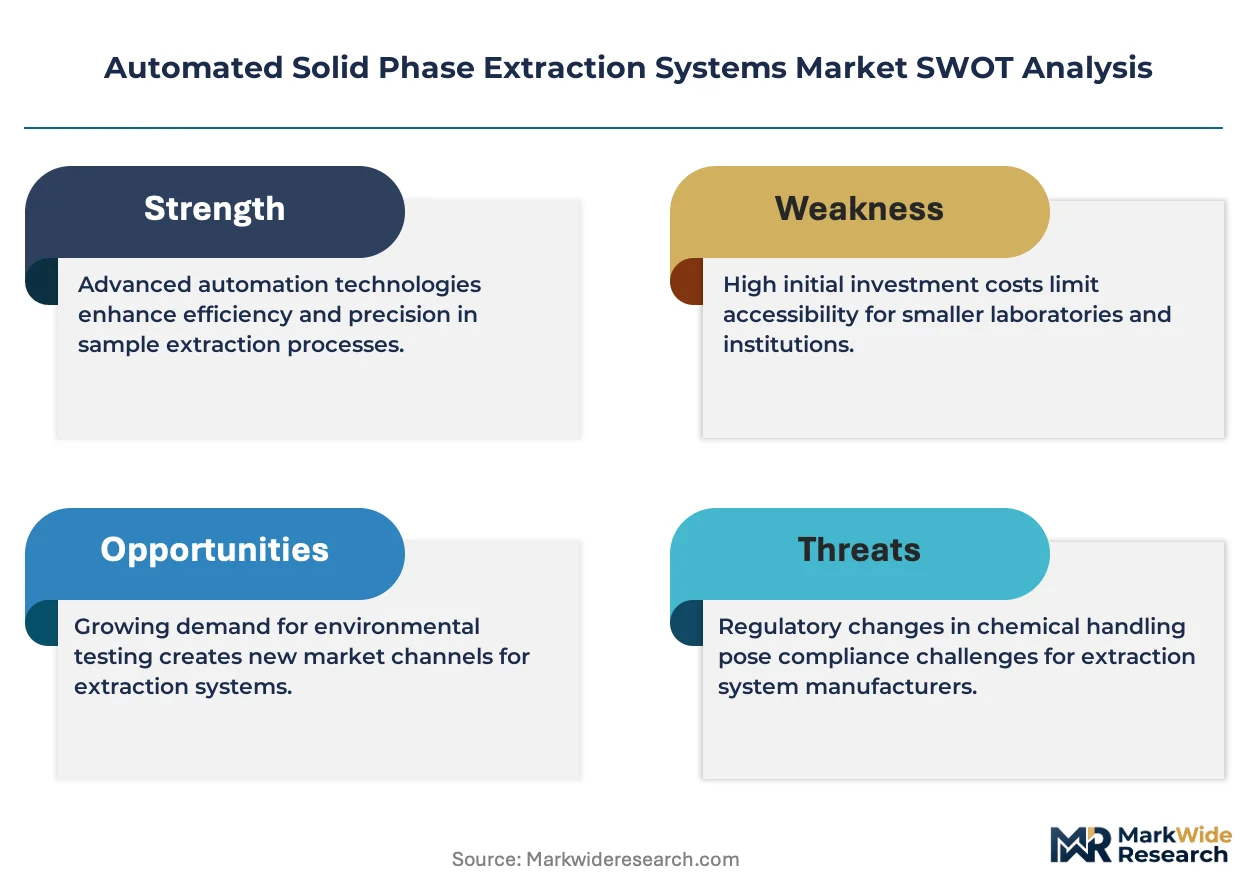
Regulatory mandates for method validation traceability are compressing replacement cycles for manual extraction workflows in pharmaceutical and environmental testing facilities.
Growth Catalysts
- EPA SW-846 protocol revisions:Updated extraction requirements for PFAS analysis are forcing environmental laboratories to automate sample preparation to meet detection limits and reproducibility thresholds.
- Pharmaceutical quality control expansion:Biologics manufacturers in the United States and Germany are deploying automated SPE to accelerate impurity profiling during release testing.
- Cartridge chemistry standardization:Universal sorbent formats are reducing method transfer friction between contract laboratories and sponsor organizations.
Market Restraints
- Capital intensity of system acquisition:Benchtop configurations require substantial upfront investment that constrains adoption in mid-sized contract research organizations.
- Consumables supply concentration:Polymer-based sorbent manufacturing clusters in Germany and Switzerland create vulnerability to input material allocation disruptions.
- Manual method persistence:Legacy solvent partitioning techniques retain foothold in academic research settings where throughput requirements remain modest.
Strategic Opportunities
- PFAS regulatory expansion:State-level drinking water mandates in the United States are creating demand for field-deployable automated extraction at municipal testing sites.
- Bioprocess analytical integration:Convergence of at-line SPE with process analytical technology is enabling real-time impurity monitoring during biologics manufacturing.
- Service revenue unbundling:Third-party method development specialists are capturing recurring revenue streams previously retained by instrument vendors.
Industry Challenges
- Cross-functional expertise scarcity:Laboratories struggle to recruit analysts proficient in both chromatography method development and liquid handling automation programming.
- ISO 17025 audit preparation:Documenting automation validation for accreditation consumes substantial technical resources at contract testing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Solid Phase Extraction Systems Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Systems, Portable Systems, Hybrid Systems, Modular Systems End User: Pharmaceuticals, Environmental Testing Labs, Food & Beverage, Academic Research Application: Drug Development, Pollutant Analysis, Quality Control, Sample Preparation Technology: SPE, SLE, LLE, Microextraction |
| Companies Covered | Gilson Incorporated, Merck KGaA, Agilent Technologies, PerkinElmer, Waters, Thermo Scientific, Tecan Trading AG, Shimadzu, Biotage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Solid Phase Extraction Systems Market Strategic Shifts
Workflow integration and regulatory method updates are reconfiguring how laboratories specify extraction platforms. Three developments are compressing competitive differentiation timelines.
Modular cartridge handling architectures are hybridizing with liquid chromatography sample managers to eliminate transfer steps between extraction and injection. Pharmaceutical quality control departments in the United States are piloting these unified workflows to reduce analyst touchpoints during release testing. The structural consequence is collapsing the distinction between sample prep and analytical instrumentation vendors.
EMA's ICH Q14 analytical procedure development guidelines are mandating enhanced method robustness documentation that automated SPE satisfies more readily than manual alternatives. European pharmaceutical manufacturers are redesignating legacy manual methods as high-risk during regulatory inspections. This pressure is accelerating replacement demand in Germany and Switzerland where centralized QC facilities dominate.
After-sales service contracts are unbundling from instrument purchases as laboratories seek specialized third-party validation support. Contract research organizations in the United States are disaggregating hardware procurement from method development and compliance documentation services. This fragmentation is most visible in the Boston and San Diego biopharma clusters where outsourcing penetration exceeds other domestic markets.
Automated Solid Phase Extraction Systems Market Segmentation
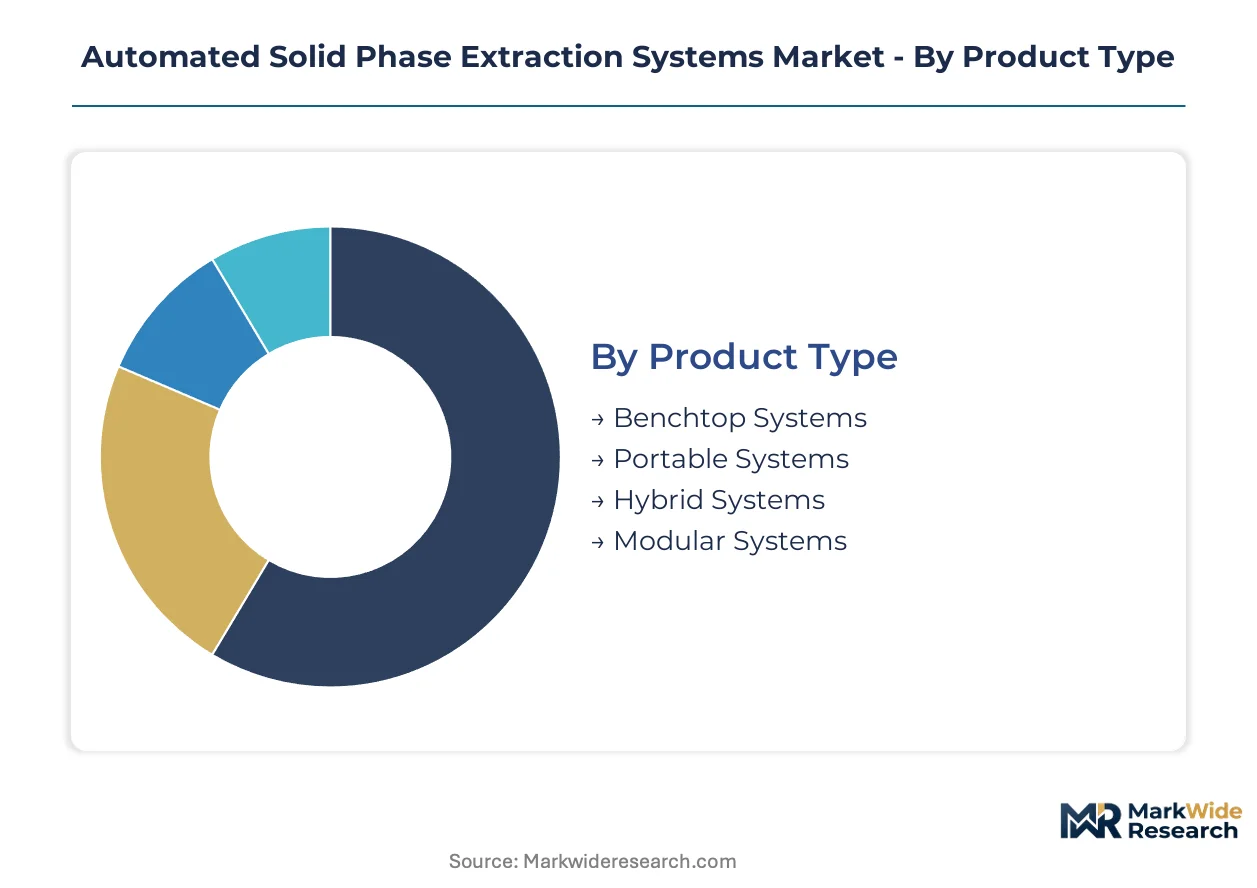
Segmentation in automated solid phase extraction systems reveals how laboratories prioritize throughput, mobility, and method flexibility against capital constraints and regulatory pressure. Distinct product architectures serve divergent operational models across pharmaceutical manufacturing, environmental compliance testing, and academic research settings.
Product Type:
Cost tier determines accessibility and feature depth across system configurations, with price-performance tradeoffs shaping adoption patterns in centralized versus distributed laboratory networks.
- Benchtop Systems:Stationary units with fixed solvent reservoirs and multi-position cartridge racks dominate pharmaceutical quality control facilities in the United States and Germany. These systems achieve the highest daily sample throughput but require dedicated laboratory infrastructure and substantial capital allocation.
- Portable Systems:Battery-powered field-deployable units with onboard solvent containment enable immediate sample stabilization at remote environmental monitoring sites. Demand concentrates in municipal water testing programs across the United States where state-level PFAS mandates require on-site extraction within hours of collection.
- Hybrid Systems:Configurations bridging laboratory precision with limited field mobility serve contract research organizations seeking dual-use flexibility.
- Modular Systems:Reconfigurable architectures with interchangeable cartridge formats and scalable solvent delivery modules are expanding most quickly as multi-method laboratories seek workflow adaptability without full system replacement.
Benchtop systems hold installed capacity. Modular systems are rotating up the share rankings.
End User:
Application maturity and regulatory stringency create divergent purchasing criteria across customer categories, with compliance-driven buyers prioritizing validation documentation over acquisition cost.
- Pharmaceuticals:Biologics manufacturers deploy automated SPE for impurity profiling during release testing, with FDA method validation guidelines mandating documented precision thresholds that manual workflows cannot reliably satisfy. United States and German facilities lead procurement volume.
- Environmental Testing Labs:Commercial and municipal laboratories face EPA SW-846 protocol revisions for PFAS analysis that compel automation to achieve required detection limits. State drinking water mandates in the United States are accelerating replacement of manual solvent partitioning.
- Food & Beverage:Quality assurance departments in regulated markets apply automated extraction for contaminant screening, though adoption lags pharmaceutical and environmental sectors due to less prescriptive method validation requirements.
- Academic Research:University laboratories retain manual methods where throughput demands remain modest and grant funding constraints limit capital equipment acquisition.
Pharmaceuticals anchor revenue concentration. Environmental testing labs are climbing the fastest.
Application:
Workflow position within analytical pipelines determines system specification requirements, with upstream sample preparation demanding different automation fidelity than downstream quality verification.
- Drug Development:Early-phase pharmaceutical research employs automated SPE for pharmacokinetic sample preparation, where reproducible recovery rates accelerate candidate screening timelines. Boston and San Diego biopharma clusters drive disproportionate demand.
- Pollutant Analysis:Environmental compliance testing for PFAS, pesticides, and industrial contaminants requires trace-level detection capabilities that automated extraction delivers consistently. German environmental laboratories face ECHA substance restriction pressures amplifying method reliability requirements.
- Quality Control:Release testing protocols in pharmaceutical manufacturing mandate auditable automation under FDA and EMA guidelines.
- Sample Preparation:General-purpose extraction workflows across multiple industries benefit from standardized cartridge chemistry reducing method transfer friction.
Quality control commands premium pricing. Pollutant analysis is gaining share fastest.
Technology:
Extraction mechanism selection reflects analyte chemistry, sample matrix complexity, and regulatory method compatibility requirements.
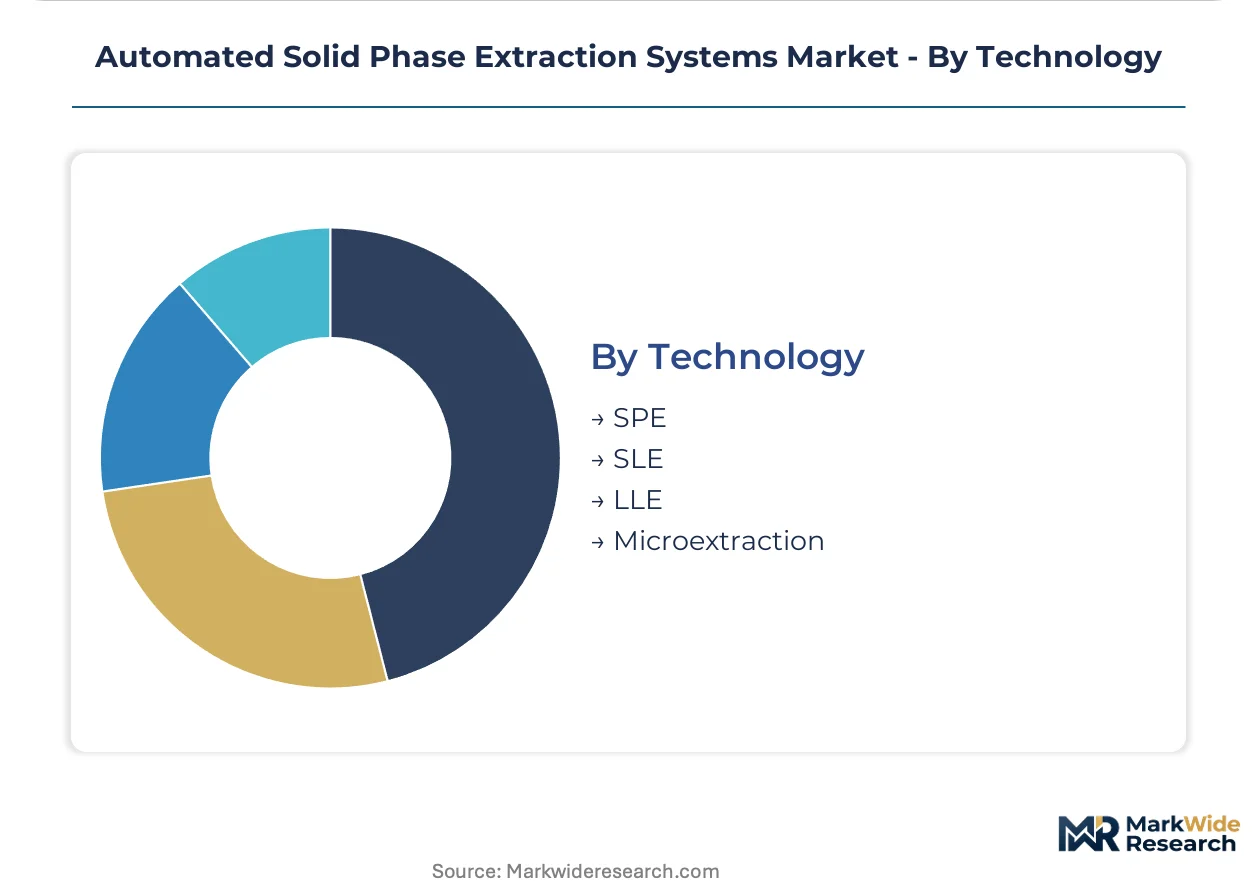
- SPE:Solid phase extraction using conditioned sorbent cartridges achieves recovery rates exceeding 85% for polar and non-polar compounds. This technology dominates pharmaceutical and environmental applications where method standardization supports regulatory compliance.
- SLE:Supported liquid extraction reduces solvent consumption compared to traditional liquid-liquid partitioning while maintaining broad analyte compatibility.
- LLE:Liquid-liquid extraction persists in legacy methods though automated SPE displaces manual partitioning in regulated settings.
- Microextraction:Miniaturized formats reduce solvent usage and waste generation for high-sensitivity applications.
SPE retains technology leadership. Microextraction is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Academic laboratories in India and Brazil resist automation due to capital constraints, while pharmaceutical manufacturers in Germany and the United States absorb premium pricing for validated compliance workflows.
United States
Environmental testing laboratories in Michigan and California face EPA SW-846 protocol revisions for PFAS analysis that mandate automated extraction to achieve detection limits. State drinking water mandates in New York and Massachusetts are accelerating municipal procurement of field-deployable systems. The Boston biopharma cluster drives disproportionate demand for modular configurations that support multi-method flexibility.
Germany
Pharmaceutical quality control facilities in Bavaria and North Rhine-Westphalia deploy automated SPE to satisfy EMA ICH Q2(R1) validation requirements for biologics release testing. ECHA substance restriction pressures on industrial chemical monitoring amplify method reliability demands. The Rhine-Main region concentrates environmental laboratory capacity where cartridge chemistry standardization reduces method transfer friction.
China
Domestic pharmaceutical manufacturers in Jiangsu and Zhejiang provinces are automating impurity profiling workflows as NMPA guidelines tighten analytical procedure documentation. The country's national environmental regulator is expanding monitoring network coverage that requires trace-level pollutant detection capabilities. Shanghai-based contract research organizations represent the fastest-growing customer segment for benchtop configurations.
Switzerland
Specialized sorbent manufacturing clusters in Basel and Zurich supply polymer-based cartridges to European pharmaceutical and environmental testing markets. Swissmedic inspection protocols emphasize auditable automation that displaces manual solvent partitioning in quality control settings. The Lake Geneva region hosts centralized analytical facilities serving multinational sponsor organizations.
India
Contract research organizations in Maharashtra and Telangana are piloting automated SPE for pharmacokinetic sample preparation to accelerate candidate screening timelines. CDSCO method validation guidelines are beginning to mirror FDA precision thresholds for export-oriented manufacturers. The Hyderabad-Visakhapatnam corridor concentrates pharmaceutical analytical capacity where throughput requirements justify capital equipment investment.
Automated Solid Phase Extraction Systems Market Competitive Environment
Capability concentration sits with specialized liquid handling automation vendors; scale advantage sits with diversified analytical instrumentation conglomerates. The market structure reflects a tiered competitive field where chromatography consumables specialists and programmable robotics developers occupy distinct strategic positions. Three archetypes dominate: precision liquid handling specialists, chromatography platform integrators, and third-party method development service providers. Competitive moves center on cartridge chemistry standardization alliances and unbundled service contract offerings that separate hardware procurement from validation support.
Within the precision liquid handling tier, Gilson Incorporated and Tecan Trading AG exemplify vendors whose deep specialization in programmable sample preparation extends naturally into SPE workflows. Among chromatography-integrated platforms, Merck KGaA occupies a position reflecting its consumables portfolio strength alongside system placements. Biotage sits within the application-specific method development tier, representing specialists who differentiate through regulatory compliance support rather than hardware scale.
| Leading Market Players |
|---|
| Gilson Incorporated |
| Merck KGaA |
| Agilent Technologies |
| PerkinElmer |
| Waters |
| Thermo Scientific |
| Tecan Trading AG |
| Shimadzu |
| Biotage |
| Others |
Value Chain & Pricing Dynamics
Basel and Zurich polymer sorbent manufacturing clusters command pricing leverage through captive cartridge chemistry production, enabling Swiss suppliers to extract premium positioning from European pharmaceutical QC facilities facing EMA validation deadlines. This geographic concentration of high-purity sorbent synthesis feeds directly into tiered system pricing that stratifies across premium, standard, and economy levels based on automation fidelity and compliance documentation depth.
Pricing Analysis
After-sales service contracts and consumables replenishment generate lifetime value exceeding initial hardware placement, with recurring revenue streams anchored in polymer cartridge replacement cycles and ISO 17025 validation support. Three-tier pricing structure across premium, standard, and economy levels reflects automation precision, software integration depth, and bundled compliance documentation. Cost compression in mid-tier benchtop configurations is intensifying because contract research organizations in the United States are disaggregating hardware procurement from method development services. Academic research laboratories exhibit highest price sensitivity due to grant funding constraints, while biologics manufacturers in Germany absorb premium pricing for validated FDA and EMA-compliant workflows.
Supply Chain Analysis
Export-control restrictions on precision liquid handling robotics limit technology transfer to certain jurisdictions, constraining vendor expansion into emerging pharmaceutical manufacturing hubs. Polymer sorbent manufacturing concentrates in Germany, Switzerland, and the United States, with specialty resin synthesis drawing from petrochemical feedstocks and pharmaceutical-grade polymer precursors. Single-source vulnerability pervades high-purity sorbent chemistry where Swiss and German suppliers dominate regulatory-grade cartridge production. Distribution runs through direct vendor sales for large pharmaceutical accounts and specialized laboratory distribution channels serving mid-sized environmental testing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated solid phase extraction systems demand is recovering from method validation backlog compression, with EPA PFAS protocol revisions and EMA biologics release testing mandates driving replacement cycle acceleration across pharmaceutical and environmental laboratory networks.
For Market Incumbents: Pre-empt modular system commoditization by deepening application-specific method development support that third-party service providers are unbundling from hardware sales. Fortify position through backward integration into polymer sorbent manufacturing to secure cartridge supply continuity against German and Swiss input material allocation disruptions. Prioritize ISO 17025 validation documentation capabilities that contract laboratories consume disproportionately during accreditation audits.
For New Entrants and Emerging Players: India's Maharashtra and Telangana contract research corridors offer white-space expansion where CDSCO guidelines are tightening analytical procedure documentation for export-oriented manufacturers. Municipal water testing programs across United States state-level PFAS mandates represent the most penetrable environmental segment for field-deployable portable system entry. Pursue third-party method development partnerships that disaggregate hardware from compliance services, mirroring Boston and San Diego biopharma cluster procurement patterns.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors application-specific method development specialists over undifferentiated liquid handling hardware vendors, as regulatory compliance complexity deepens competitive moats. Long-term viability rests on recurring consumables revenue density and service contract attach rates rather than system placement velocity. Watch for PFAS regulatory expansion into European drinking water standards as inflection indicator for cartridge chemistry demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cartridge Chemistry Standardization Alliance | Universal sorbent formats reduce method transfer friction between sponsor and contract laboratories under FDA guidelines. |
| Third-Party Validation Service Unbundling | Specialized compliance documentation providers capture recurring revenue previously retained by instrument vendors. |
| Modular Architecture Development | Reconfigurable systems enable multi-method flexibility without full replacement, accelerating replacement cycles in pharmaceutical QC. |
| Field-Deployable Portable System Launch | Battery-powered units address state-level PFAS drinking water mandates requiring immediate on-site sample stabilization. |
| Backward Integration into Sorbent Manufacturing | In-house polymer cartridge production mitigates supply concentration risk from German and Swiss manufacturing clusters. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EPA SW-846 method updates, EMA ICH guideline revisions, and pharmaceutical quality control facility inspection records. Interviews with laboratory directors, regulatory affairs specialists, chromatography method developers, and contract research organization procurement managers informed demand segmentation and purchasing criteria validation. Bottom-up triangulation across installed base estimates, consumables replenishment rates, and service contract attach rates converged with top-down analysis of pharmaceutical and environmental testing market expenditure patterns.
Forecast inputs include regulatory method update timelines, pharmaceutical manufacturing capacity expansion announcements, and environmental monitoring network procurement disclosures across the analysis window. Segmentation modeling incorporates product architecture, end-user industry, application workflow position, and extraction technology mechanism dimensions. CAGRs derive from regression analysis of historical replacement cycle compression and forward projection of EPA and EMA regulatory enforcement intensity. Industry-specific inputs encompass PFAS regulatory expansion trajectories and biologics manufacturing growth patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by chromatography conglomerates into specialized liquid handling automation would shift outcomes. Material shifts in EPA drinking water mandate enforcement timelines or EMA inspection prioritization of manual method risk classification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Continuous Flow Analyzer Market
Testing Equipment
Global Life Science and Chemical Instrumentation Market
Testing Equipment
Environmental Testing Equipment Market
Testing Equipment
Chemical Analyzer Market
Testing Equipment
Global Film Thickness Measurement Market
Testing Equipment
CHS (Carbon Hydrogen Sulfur) Analyzers Market
Testing Equipment
Elemental Analysis Market
Testing Equipment
Global Dynamic Mechanical Analyzers Market
Testing Equipment
Rheology Controller Market
Testing Equipment
Lubricant Testing Machine Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Liquid Chromatography Mass Spectrometry (LCMS) Market
Testing Equipment
Chemical Testing Services Market
Testing Equipment
Chromatography Accessories and Consumables Market
Testing Equipment
Global Insulation Testers Market
Testing Equipment
Chemical Detector Market