
 Cone Calorimeter Market | 2026-2036
Cone Calorimeter Market Size, Share, and Industry Trends Forecast 2026-2036
Cone Calorimeter Market Outlook
Modular instrument configurations is broadening buyer choice across research and industrial laboratories. Fire Testing Technology anchors its position through deep specialization in combustion science instrumentation. NETZSCH Group leverages thermal analysis synergies to extend its reach into fire testing workflows. TESTech (Suzhou) competes on manufacturing scale within Asia-Pacific supply chains.
A cone calorimeter measures heat release rate, smoke production, and mass loss from materials exposed to controlled radiant heat flux, typically operating at irradiance levels between 0 and 100 kW/m² to simulate real-fire conditions. The instrument serves as the reference apparatus for ISO 5660 and ASTM E1354 fire performance characterization. Bench-scale calorimeters dominate current procurement volumes due to their established regulatory acceptance and lower capital barrier. Modular calorimeters represent the fastest-expanding configuration category as laboratories seek upgradeable platforms that accommodate evolving test standards without full instrument replacement. Portable units occupy a narrower niche serving field validation and on-site construction material auditing.
ISO 5660, ASTM E1354, and the EU Construction Products Regulation collectively define instrument specifications and laboratory accreditation requirements across major economies. The FAA's updated flammability standards for aircraft interiors directly expand mandatory testing volumes for aerospace suppliers. Stakeholders must monitor regulatory harmonization between European EN standards and evolving Asian national fire codes to anticipate certification migration costs and instrument specification shifts.
Market Dynamics
Composite-intensive aerospace programs and tightening FAA flammability mandates are forcing materials laboratories to upgrade fire testing capacity ahead of certification deadlines.
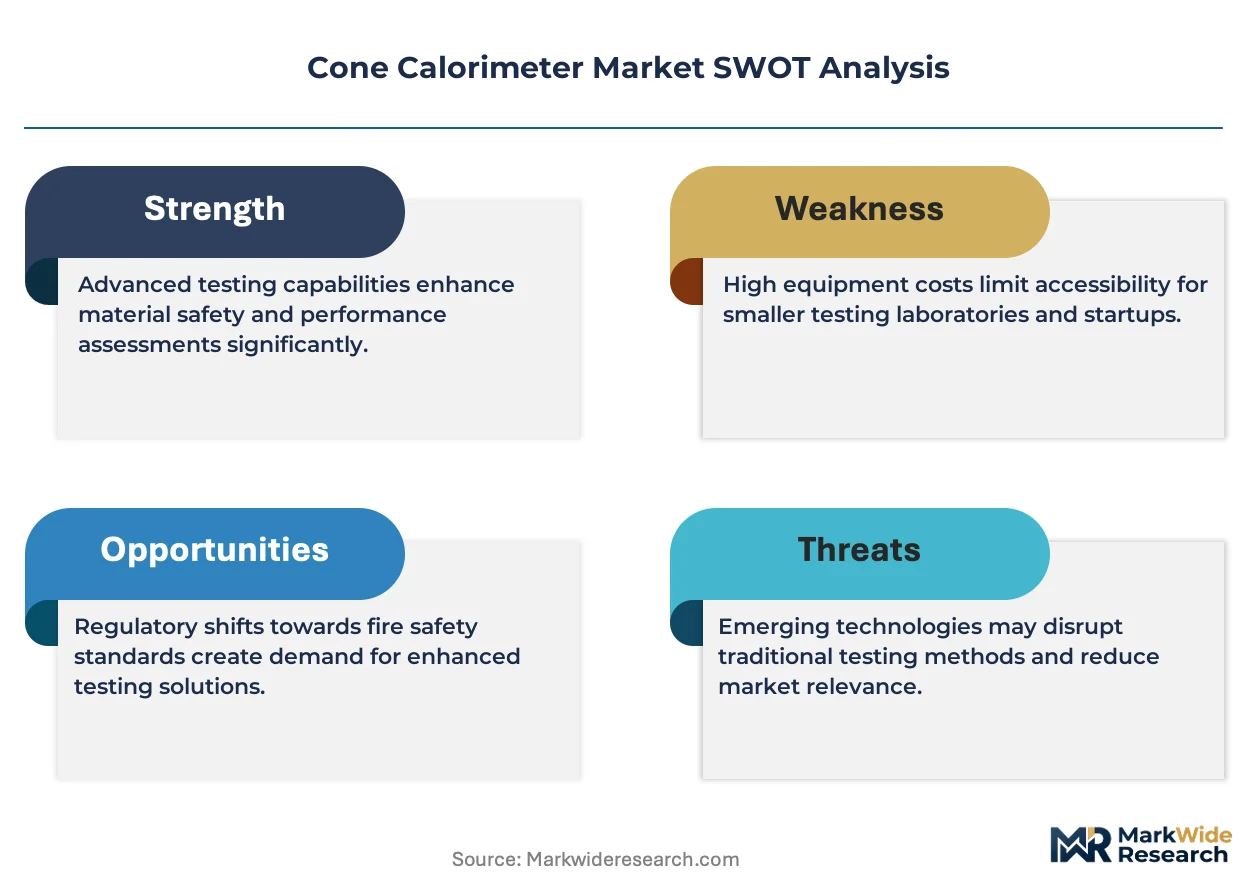
Growth Catalysts
- FAA Interior Flammability Standards:Updated aircraft cabin material protocols expand mandatory testing volumes for aerospace suppliers across North America.
- EU Construction Products Regulation:Harmonized fire performance classification drives replacement of legacy calorimeter fleets in German and French building materials laboratories.
- Automotive Lightweighting:Carbon fiber reinforced polymer adoption in electric vehicle battery enclosures creates new fire characterization requirements for tier-1 suppliers.
Market Restraints
- High-Purity Sensor Costs:Oxygen consumption and carbon dioxide measurement subsystems rely on imported infrared detectors subject to semiconductor supply volatility.
- Technical Service Concentration:Installation and ISO 17025 calibration expertise clusters in Western European and North American service networks, limiting rapid deployment elsewhere.
- Regulatory Fragmentation:Divergent national fire codes across Asian markets force manufacturers to maintain multiple instrument configurations, inflating working capital requirements.
Strategic Opportunities
- India BIS Fire Safety Mandates:Building code enforcement expansion in Maharashtra and Gujarat creates first-mover advantage for localized instrument assembly partnerships.
- Digital Twin Integration:Coupling calorimeter output with computational fluid dynamics software compresses material development cycles for polymer compounders.
- Cloud-Connected Instrumentation:Remote diagnostic and multi-site data aggregation capabilities open subscription revenue streams from multinational certification bodies.
Industry Challenges
- Combustion Science Talent Scarcity:Qualified operators capable of interpreting heat release rate curves and smoke density data remain concentrated in aging Western laboratory workforces.
- Legacy System Integration:Retrofitting modular calorimeter platforms into established ASTM E1354 and ISO 5660 workflows demands custom software bridging and extended validation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cone Calorimeter Market |
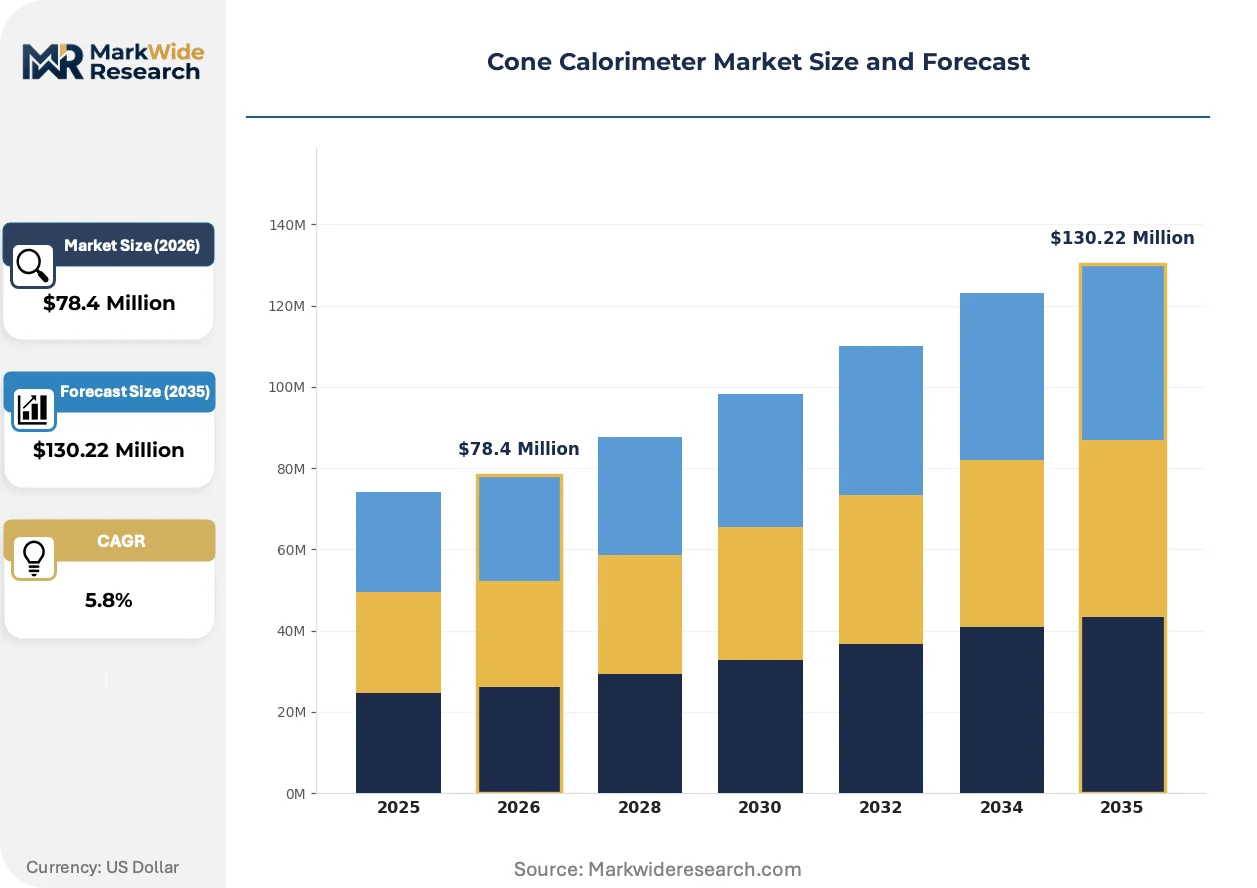
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $130.22 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchmark Calorimeter, Portable Calorimeter, Bench-Scale Calorimeter, Modular Calorimeter End User: Aerospace, Automotive, Construction, Material Manufacturing Application: Fire Safety Testing, Material Testing, Product Development, Research Applications Installation Type: Fixed Installation, Mobile Installation, Laboratory Installation, Field Installation |
| Companies Covered | Deatak, Concept Equipment, Fire Testing Technology, Toyoseiki, Ineltec, NETZSCH Group, Wazau, Motis Technology, TESTech (Suzhou), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cone Calorimeter Market Strategic Shifts
Instrumentation vendors are embedding predictive analytics and connectivity layers into fire testing hardware, shifting value capture from capital equipment toward data services.
Multi-sensor fusion architectures combining heat release, smoke obscuration, and toxic gas analysis within unified acquisition systems is overtaking discrete standalone instruments. Polymer research consortia in Germany and Japan are adopting these platforms to consolidate laboratory footprints. The convergence compresses capital budgets while elevating software and calibration services to primary revenue contributors.
REACH substance restrictions on halogenated flame retardants are compelling reformulation of certified materials across EU member states. Manufacturers must revalidate existing product lines under revised EN 13501 classification protocols. Construction materials suppliers in Italy and Spain are accelerating procurement of next-generation calorimeters capable of characterizing phosphorus and nitrogen-based alternatives.
Consolidated procurement through multinational certification bodies is displacing fragmented laboratory-level purchasing. Bureau Veritas and SGS are centralizing fire testing capacity into regional hubs equipped with identical instrument configurations. This concentration is most visible in France and the United Kingdom, where construction product manufacturers now ship samples to centralized facilities rather than maintaining in-house capabilities.
Cone Calorimeter Market Segmentation
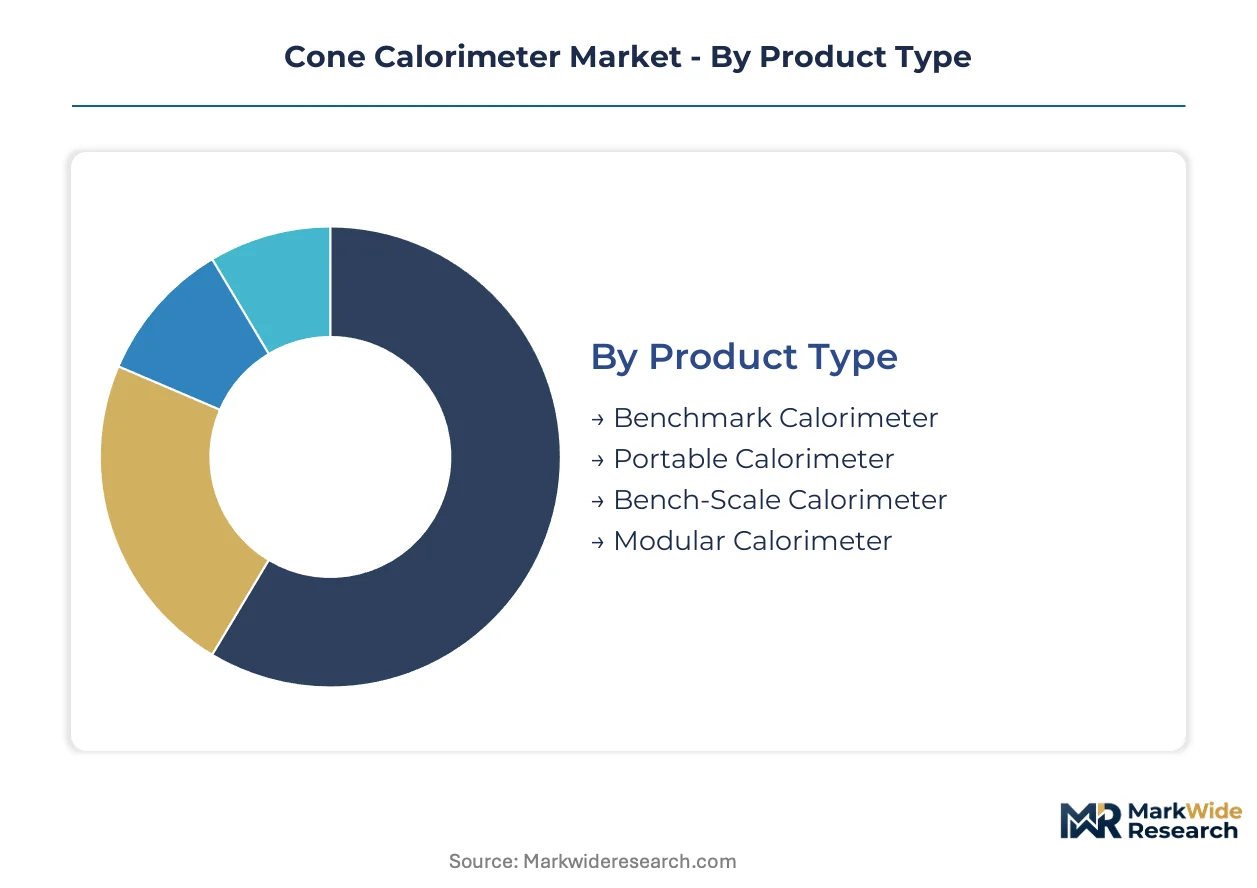
Laboratories face divergent upgrade cycles across instrument configurations, with regulatory deadlines forcing synchronized replacement decisions. Segmentation reveals how procurement priorities split between established compliance workflows and emerging modular platforms.
Product Type:
Replacement cycles vary dramatically by configuration complexity, with laboratories balancing capital recovery against evolving ISO 5660 and ASTM E1354 protocol requirements.
- Bench-Scale Calorimeter:Compact footprint units dominate current installed base, serving routine fire performance screening for construction materials suppliers. German and French building materials laboratories concentrate procurement here, driven by EU Construction Products Regulation revalidation deadlines.
- Modular Calorimeter:Upgradeable sensor architectures allow incremental capability expansion without full instrument replacement. Polymer research consortia in Germany and Japan prioritize these platforms to consolidate multiple fire characterization protocols within single laboratory footprints.
- Benchmark Calorimeter:Reference-grade systems anchor national metrology institute calibration chains.
- Portable Calorimeter:Battery-powered units serve field validation requirements for construction site auditing.
Bench-Scale Calorimeter sits at the top of the volume ranking, with Modular Calorimeter climbing the fastest.
End User:
Customer concentration patterns reflect sector-specific regulatory enforcement intensity and material innovation cycles.
- Construction:Building materials manufacturers require fire performance classification under EN 13501 and equivalent national codes. Italian and Spanish suppliers accelerate procurement following REACH-driven flame retardant reformulation mandates.
- Aerospace:Composite-intensive aircraft programs demand rigorous heat release rate validation. FAA updated flammability standards for cabin interiors directly expand mandatory testing volumes among North American tier-1 suppliers.
- Automotive:Electric vehicle battery enclosure manufacturers adopt carbon fiber reinforced polymers, creating new fire characterization requirements.
- Material Manufacturing:Polymer compounders integrate calorimetry into R&D workflows for next-generation formulations.
Construction commands the largest procurement budget, while Aerospace exhibits the steepest expansion trajectory.
Application:
Workflow integration depth determines whether instruments serve compliance verification or upstream material development.
- Fire Safety Testing:Regulatory certification workflows require traceable heat release rate measurements against ISO 5660 reference protocols. Bureau Veritas and SGS regional hubs concentrate this application category through centralized multi-site capacity.
- Material Testing:Quality control laboratories validate batch-to-batch consistency for certified product lines.
- Product Development:Formulation scientists optimize flame retardant loading levels during compound design.
- Research Applications:Academic combustion science programs investigate fundamental pyrolysis kinetics.
Fire Safety Testing anchors revenue stability, with Product Development gaining share fastest.
Installation Type:
Physical deployment constraints shape instrument specification trade-offs between measurement precision and operational flexibility.
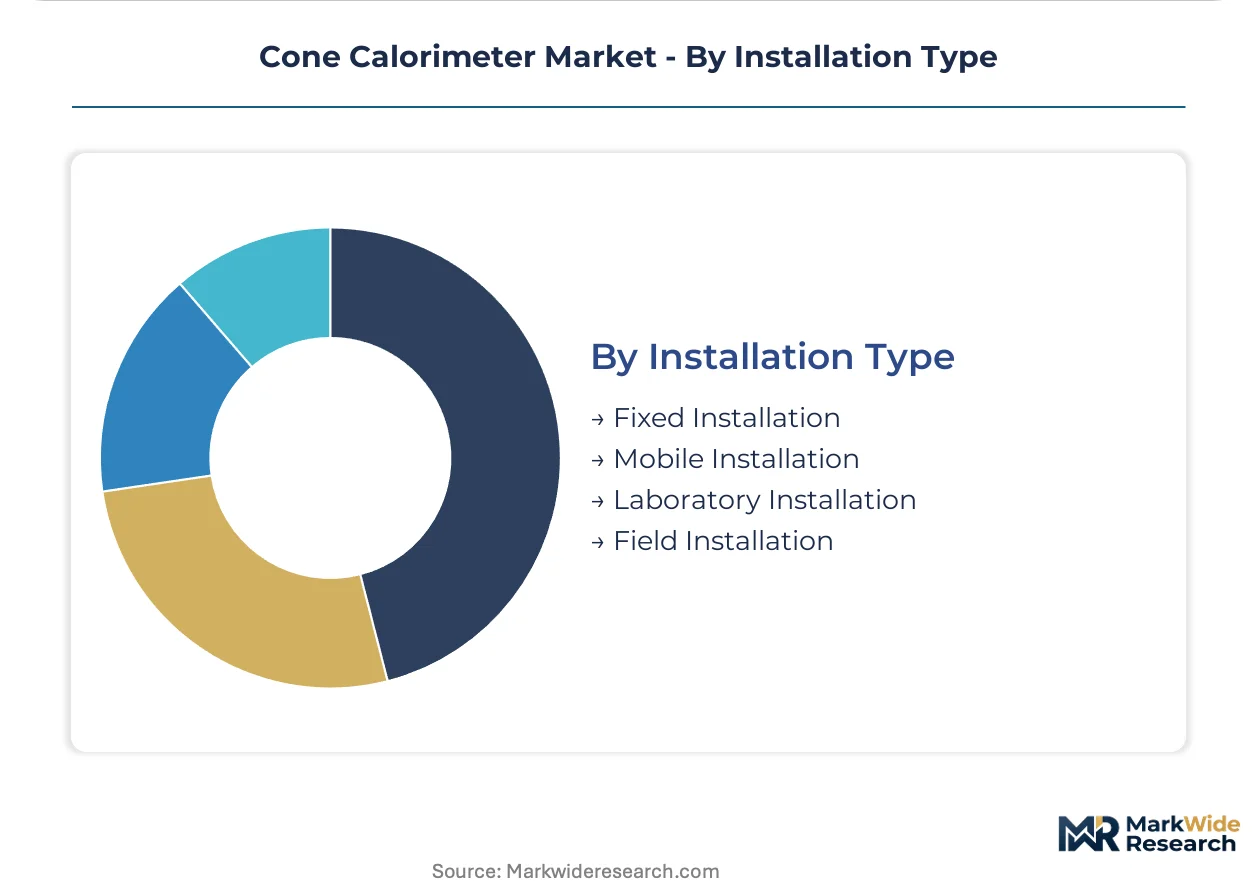
- Laboratory Installation:Climate-controlled environments enable highest-accuracy oxygen consumption calorimetry. Materials laboratories in Germany maintain the densest concentration of these permanent configurations.
- Fixed Installation:Dedicated fire testing facilities anchor regional certification capacity.
- Mobile Installation:Trailer-mounted systems serve temporary construction site validation requirements.
- Field Installation:Ruggedized units perform on-site auditing where laboratory sample transport proves impractical.
Laboratory Installation holds the dominant share position, with Mobile Installation expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cone calorimeter industry traces its commercial origins to British combustion science laboratories in the 1980s, where oxygen consumption calorimetry principles were first standardized for industrial fire testing. German materials laboratories subsequently scaled instrument production to serve automotive and aviation certification needs.
United States
Aerospace manufacturers in Seattle and Wichita drive instrument demand as FAA flammability standards for aircraft cabin materials tighten testing protocols. The FAA's updated interior fire safety mandates expand mandatory validation volumes for composite-intensive programs. Boeing suppliers in Washington State and Kansas concentrate procurement of reference-grade calorimeter systems.
Germany
Automotive lightweighting initiatives and construction materials certification sustain dense laboratory infrastructure. REACH substance restrictions on halogenated flame retardants force revalidation of certified product lines under revised EN 13501 protocols. Materials laboratories in Stuttgart and Munich anchor the highest concentration of permanent ISO 5660 installations.
China
Electric vehicle battery enclosure manufacturers adopt carbon fiber reinforced polymers, creating fire characterization requirements for tier-1 suppliers. GB standards evolution and building code enforcement expansion drive procurement of modular calorimeter platforms. Testing facilities in Shanghai and Shenzhen consolidate multi-sensor fire testing capacity.
Japan
Polymer research consortia invest in upgradeable instrument architectures to consolidate laboratory footprints. METI-supported material innovation programs emphasize predictive fire performance modeling. Academic combustion science departments in Tokyo and Osaka maintain reference apparatus for fundamental pyrolysis kinetics research.
India
BIS fire safety mandates in Maharashtra and Gujarat create first-mover opportunities for localized instrument assembly partnerships. Building code enforcement expansion in western industrial corridors accelerates laboratory accreditation requirements. Materials testing facilities in Mumbai and Ahmedabad upgrade capacity ahead of certification deadlines.
Cone Calorimeter Market Competitive Environment
Premium-margin players sit above commodity-margin players across calibration service depth and regulatory accreditation breadth. The vendor base clusters around three strategic archetypes: combustion science specialists with deep ISO 17025 service networks, thermal analysis conglomerates leveraging cross-product synergies, and manufacturing-scale fabricators competing on Asia-Pacific supply chain integration. Dominant competitive moves include modular platform development enabling incremental capability expansion and cloud-connected instrumentation shifting revenue toward subscription diagnostics.
Among European specialists, Fire Testing Technology and NETZSCH Group occupy positions at the premium-service tier, with the former exemplifying deep specialization in fire testing instrumentation and the latter representing thermal analysis conglomerate extension into combustion workflows. TESTech (Suzhou) anchors the manufacturing-scale archetype among Asia-Pacific fabricators.
| Leading Market Players |
|---|
| Deatak |
| Concept Equipment |
| Fire Testing Technology |
| Toyoseiki |
| Ineltec |
| NETZSCH Group |
| Wazau |
| Motis Technology |
| TESTech (Suzhou) |
| Others |
Value Chain & Pricing Dynamics
Consolidated procurement through multinational certification bodies is compressing pricing power for mid-tier instrument vendors while elevating premium-service providers. Bureau Veritas and SGS regional hubs now demand standardized configurations at volume scale, forcing manufacturers to absorb sensor cost volatility or cede share to combustion science specialists with deeper calibration networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 17025 accreditation depth and after-sales service bundling. Premium tiers capture reference-grade calibration chains and multi-site service contracts; economy tiers compete on capital cost alone for construction materials screening. Cost compression in the economy tier is intensifying because semiconductor supply volatility inflates infrared detector subsystem costs. Construction laboratories exhibit highest price sensitivity; aerospace tier-1 suppliers prioritize certification reliability over capital expenditure.
Supply Chain Analysis
Direct-to-laboratory channels serve research consortia and national metrology institutes with customized configurations. Manufacturing concentrates in Germany, the United Kingdom, and China. Critical inputs include high-purity infrared gas analyzers, precision radiant heat sources, and oxygen consumption sensors. Single-source vulnerability in infrared detector supply creates procurement risk for modular platform manufacturers. Distribution runs through authorized service networks with ISO 17025 accreditation rather than equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cone calorimeter market functions as a regulatory compounder where FAA flammability standard updates and EU Construction Products Regulation revalidation deadlines create synchronized replacement demand across aerospace and construction verticals.
For Market Incumbents: Hedge against modular platform disruption by deepening ISO 17025 service network density in Asia-Pacific. Acquire localized calibration expertise in India ahead of BIS mandate enforcement. Cloud-connected instrumentation subscriptions represent a margin defense lever against capital equipment commoditization. For New Entrants and Emerging Players: Launch via portable calorimeter field-validation services targeting Indian construction site auditing ahead of laboratory infrastructure buildout. White-space concentration sits with battery-powered units for temporary construction validation. Partnership with regional certification bodies accelerates accreditation credibility. For Investors and Strategic Acquirers: Asymmetric upside sits with combustion science specialists possessing dense Western European service networks and modular platform architectures. Five-to-ten-year viability favors vendors integrating predictive analytics into hardware workflows. Watch for FAA harmonization with evolving Asian national fire codes as inflection signal for certification migration tooling demand.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Development | Upgradeable sensor architectures capture polymer research consortia consolidating laboratory footprints in Germany and Japan. |
| Cloud-Connected Instrumentation | Remote diagnostic capabilities open recurring revenue streams from Bureau Veritas and SGS multi-site certification networks. |
| Localized Assembly Partnership | Indian joint ventures bypass import logistics and accelerate BIS compliance for Maharashtra and Gujarat building code enforcement. |
| Multi-Sensor Fusion Integration | Unified acquisition systems compress capital budgets while elevating software and calibration services to primary revenue contributors. |
| Digital Twin Coupling | Computational fluid dynamics integration shortens material development cycles for electric vehicle battery enclosure manufacturers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged laboratory directors at materials testing facilities, procurement leads at multinational certification bodies, combustion science researchers at academic institutions, and regulatory affairs specialists at aerospace tier-1 suppliers. Secondary validation drew from FAA airworthiness directives, ECHA REACH substance restriction updates, ISO 5660 and ASTM E1354 protocol documentation, and customs trade data for fire testing instrumentation. Bottom-up instrument shipment tracking and top-down laboratory capacity modeling were cross-referenced for triangulation.
Segment-weighted projections applied product type, end user, application, and installation type dimensions across the analysis window. CAGRs derived from instrument replacement cycle analysis, regulatory deadline clustering, and materials innovation pipeline tracking. Aerospace program launch schedules and electric vehicle platform ramp timelines informed demand-side inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or accelerated Asian fire code harmonization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Solar Testing Equipment Market
Testing Equipment
Durometers Market
Testing Equipment
Global Liquid Chromatography Systems Market
Testing Equipment
Chromatography Accessories and Consumables Market
Testing Equipment
Magnesium Testing Reagents Market
Testing Equipment
Asia-Pacific Process Analytics Market
Testing Equipment
Continuous Flow Analyzer Market
Testing Equipment
Geochemical Services Market
Testing Equipment
FTIR Fuel Analyzer Market
Testing Equipment
Cyclic Corrosion Test Chamber Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Global Adsorption Equipment Market
Testing Equipment
Viscometer Market
Testing Equipment
Chlorine Meter Market
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Water Test Kits Market