

Binary High Pressure Gradient Liquid Chromatography System Market Size, Share, and Industry Trends Forecast 2026-2036
Binary High Pressure Gradient Liquid Chromatography System Market Insights
Ultra-high pressure specifications is redrawing competitive boundaries in this market. Waters Corporation leverages its deep specialization in mass spectrometry-coupled platforms to anchor premium positioning. Agilent Technologies sustains technology leadership through intensive R&D in intelligent chromatography software. Shimadzu Corporation dominates Asian supply channels with manufacturing scale and localized service networks.
A binary high pressure gradient liquid chromatography system employs two independent solvent delivery pumps operating at pressures exceeding 600 bar, blending mobile phases through a high-pressure mixer before column introduction for precise compound separation and quantification. Analytical systems capture the largest installed base across quality control environments, though ultra-high pressure systems represent the fastest expansion trajectory as laboratories pursue shorter run times and sharper resolution. Gradient mixing technology occupies the dominant share of new instrument procurement, while dual-pump architectures gain ground in pharmaceutical analysis applications requiring exact reproducibility.
FDA method validation guidelines, EMA ICH Q2(R1) standards, and USP general chapter requirements collectively shape instrument specifications and software compliance features demanded by regulated laboratories. EPA protocols for environmental monitoring and FSSAI food safety mandates in India further broaden the regulatory footprint governing system validation and data integrity. Stakeholders must monitor evolving pharmacopeial standards and regional inspectorate emphasis on electronic records integrity when configuring next-generation platform investments.
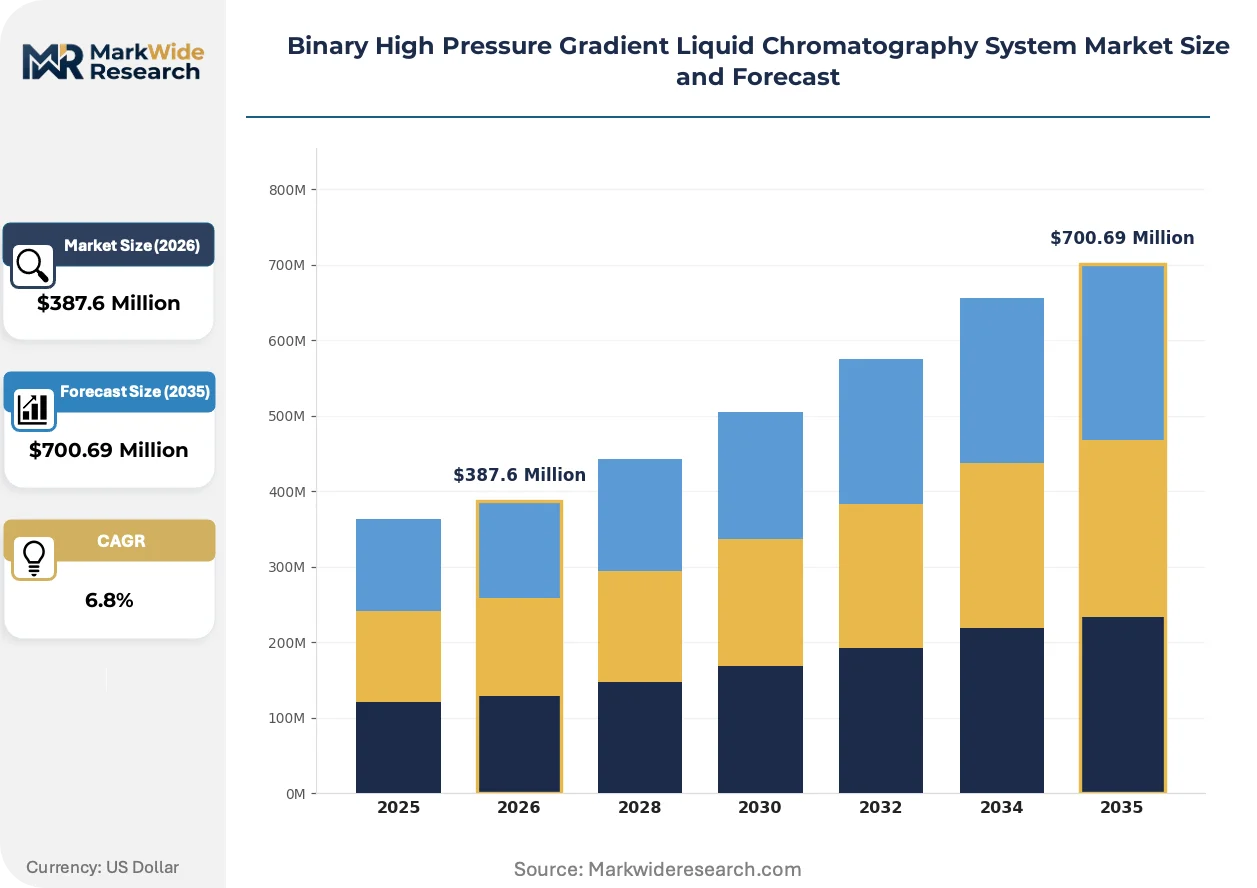
Market Dynamics
Ultra-high pressure gradient mixing is compressing method development timelines while FDA 21 CFR Part 11 enforcement tightens electronic records requirements across pharmaceutical quality control networks.
Growth Catalysts
- FDA Bioanalytical Method Validation:Tightened guidance on chromatographic data integrity is forcing quality control laboratories to upgrade legacy systems, creating replacement demand across United States pharmaceutical manufacturing facilities.
- Peptide and oligonucleotide therapeutics:Expansion of biologics pipelines requires ultra-high pressure separation capabilities that conventional isocratic systems cannot deliver, pulling investment toward binary gradient architectures.
- Continuous manufacturing adoption:Real-time release testing protocols in European pharmaceutical plants are embedding in-line high pressure LC systems directly into production workflows.
Market Restraints
- Pump seal and valve replacement costs:Consumable expenditure for ceramic piston seals and check valve assemblies at 600+ bar pressures creates lifecycle cost barriers for mid-sized contract research organizations.
- Helium scarcity:Dependence on helium carrier gas for mass spectrometry-coupled systems exposes laboratories to supply volatility from Qatar and United States federal reserve releases.
- ICH Q14 method development burden:Enhanced analytical procedure development guidelines extend validation timelines, delaying instrument commissioning and revenue recognition for vendors.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Bengaluru are scaling quality control capacity to serve export markets, creating instrument placement opportunities.
- PFAS environmental monitoring:EPA Method 1633 adoption for per- and polyfluoroalkyl substances analysis is mandating high pressure gradient systems for water testing laboratories.
- AI-driven method optimization:Integration of machine learning algorithms with chromatography data systems is reducing method development from weeks to days, creating software-subscription revenue streams.
Industry Challenges
- Metrology technician shortage:Qualified personnel for high pressure system maintenance and troubleshooting are scarce in secondary pharmaceutical markets, extending service response times.
- Legacy data system migration:Transitioning from standalone chromatography workstations to enterprise-wide data lakes requires substantial validation effort and temporary productivity loss.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Binary High Pressure Gradient Liquid Chromatography System Market Trends and Innovations
Intelligent chromatography software and modular hardware architectures are compressing the traditional seven-year instrument replacement cycle while enabling remote diagnostic capabilities.
Binary pump technology is bifurcating into two distinct performance tiers. Premium systems now operate at 1500 bar for sub-2-micron particle columns, while workhorse platforms stabilize at 600-800 bar for routine quality control. Large pharmaceutical manufacturers in Germany and Switzerland are deploying the ultra-high pressure tier for complex impurity profiling, compressing run times by sixty percent versus legacy methods.
EMA ICH Q2(R1) revision and USP general chapter updates are mandating enhanced system suitability criteria. These pharmacopeial standards now require documented evidence of gradient accuracy and dwell volume consistency, forcing vendors to embed diagnostic sensors and automated qualification protocols. European quality control laboratories are responding by prioritizing instruments with embedded compliance software over lower-cost alternatives.
Service contract unbundling is fragmenting the traditional full-service model. Pharmaceutical procurement teams in Japan and the United States are separating preventive maintenance, software support, and consumable supply into distinct purchasing decisions, pressuring vendor pricing transparency. This behavioral shift is most pronounced among top-twenty global pharmaceutical companies with centralized sourcing functions.
Binary High Pressure Gradient Liquid Chromatography System Market Segmentation
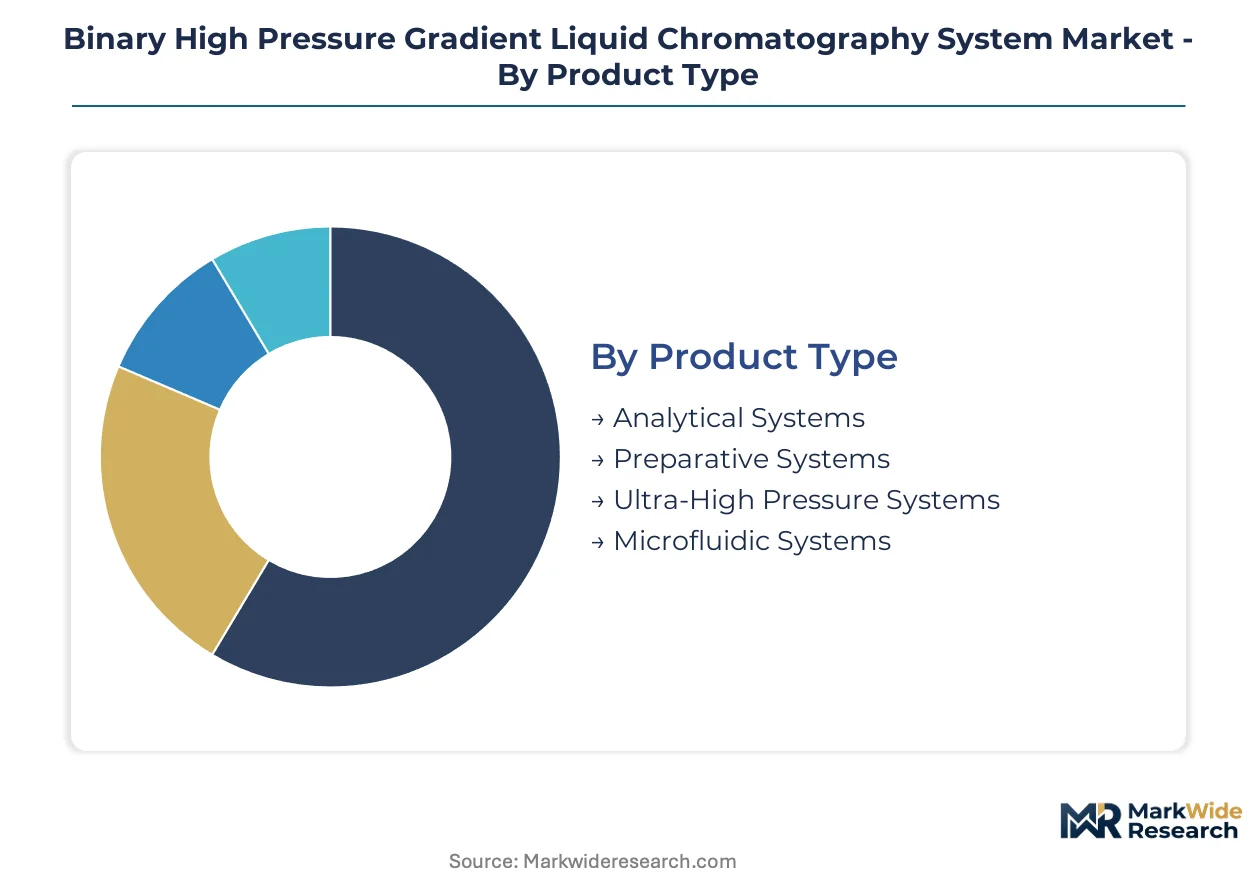
Segmentation in the Binary High Pressure Gradient Liquid Chromatography System Market reveals how regulatory pressure and application complexity fragment procurement patterns. Laboratories configure systems around specific compliance mandates rather than generalized performance metrics.
Product Type:
FDA 21 CFR Part 11 and EMA ICH Q2(R1) standards create distinct compliance tiers across instrument categories.
- Analytical Systems:These platforms operate at 400-600 bar with integrated photodiode array and mass spectrometry interfaces. Quality control laboratories in United States pharmaceutical manufacturing facilities deploy these for routine impurity profiling under tightened FDA bioanalytical method validation guidance. Established volume favors Analytical Systems; emerging adoption favors Ultra-High Pressure Systems.
- Ultra-High Pressure Systems:Capable of 1500 bar operation with sub-2-micron particle column compatibility. Large pharmaceutical manufacturers in Germany and Switzerland leverage these for complex peptide and oligonucleotide therapeutic analysis where conventional platforms fail.
- Preparative Systems:Scaled solvent delivery modules for gram-scale compound purification in contract manufacturing settings.
- Microfluidic Systems:Miniaturized flow paths for nanoliter sample volumes in proteomics research environments.
Established volume favors Analytical Systems; emerging adoption favors Ultra-High Pressure Systems.
Technology:
Cost tier differentiation separates premium gradient architectures from economy isocratic alternatives.
- Gradient Mixing:High-pressure proportional valve systems blending two solvents with programmable composition ramps. Pharmaceutical quality control networks across United States, Germany, and Japan specify these for method flexibility under USP general chapter requirements. Procurement concentrates where FDA and EMA electronic records enforcement is most stringent.
- Dual-Pump:Independent piston-driven channels enabling precise flow rate modulation with minimal pulsation. Specialty chemical plants in India and China adopt these for exact reproducibility in continuous manufacturing workflows.
- Isocratic Mixing:Single-composition delivery for routine screening applications with lower capital expenditure.
- Quaternary Pumping:Four-solvent capability for complex method development in multi-component separations.
Gradient Mixing commands the dominant procurement share; Dual-Pump architectures are climbing the fastest in pharmaceutical analysis applications.
Application:
End-use maturity determines specification intensity across regulatory jurisdictions.
- Pharmaceutical Analysis:Compendial method execution for drug substance and product release testing. Quality control laboratories in United States facilities upgrade legacy installations as FDA tightens chromatographic data integrity expectations. This segment absorbs the largest instrument placement volume.
- Environmental Monitoring:EPA Method 1633 compliance for per- and polyfluoroalkyl substances quantification in water matrices. Testing laboratories across United States states mandate high pressure gradient capability for emerging contaminant surveillance.
- Food Safety Testing:Pesticide residue and mycotoxin screening under FSSAI mandates in India and equivalent authorities elsewhere.
- Chemical Synthesis Control:Reaction monitoring and purity verification in specialty chemical production environments.
Pharmaceutical Analysis retains the deepest installed base; Environmental Monitoring is gaining share fastest from regulatory protocol expansion.
End User:
Customer type dictates service contract structure and software compliance requirements.
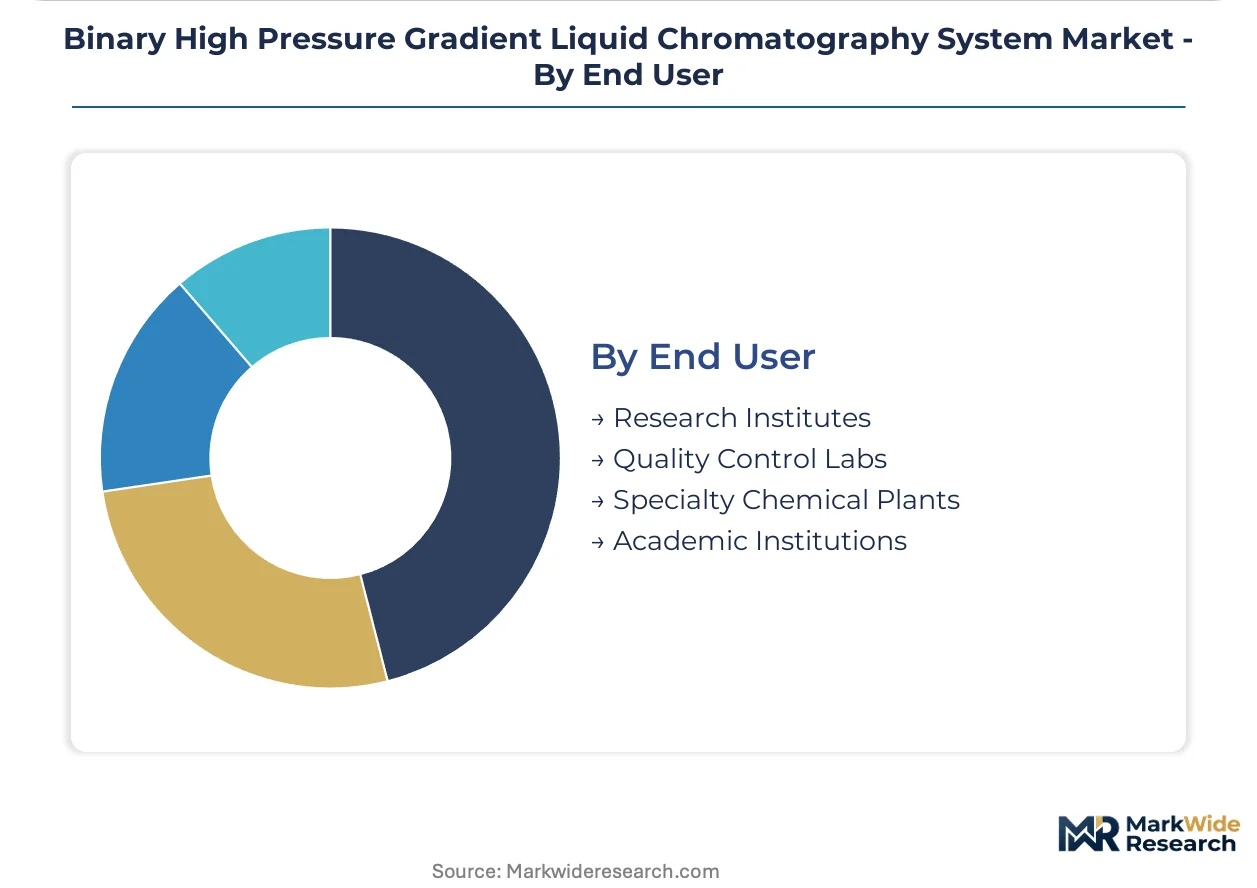
- Quality Control Labs:Validated environments requiring 21 CFR Part 11 compliant data systems with audit trail functionality. Pharmaceutical manufacturing facilities in United States, Germany, and Japan prioritize embedded qualification protocols over capital cost minimization.
- Research Institutes:Method development flexibility with modular detector configurations for exploratory separations.
- Specialty Chemical Plants:Process analytical technology integration for real-time release testing in European continuous manufacturing adoption.
- Academic Institutions:Training and fundamental research applications with reduced pressure specifications.
Quality Control Labs concentrate the premium procurement tier; Research Institutes represent the most price-sensitive segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for precision fluidics components tilts the trade balance toward manufacturing centers in Germany, Japan, and the United States, while export demand from Indian and Chinese quality control laboratories reshapes regional equipment flows.
United States
FDA bioanalytical method validation enforcement and EPA Method 1633 adoption for PFAS monitoring drive instrument procurement across pharmaceutical and environmental testing sectors. The 21 CFR Part 11 compliance burden forces legacy system replacement in quality control networks. Boston-Cambridge biotech clusters and New Jersey pharmaceutical corridors concentrate the highest upgrade velocity.
Germany
EMA ICH Q2(R1) standards and USP general chapter alignment requirements position German quality control laboratories as specification leaders for gradient accuracy validation. The country's chemical-pharmaceutical manufacturing base demands ultra-high pressure systems for complex impurity profiling. Baden-Württemberg and North Rhine-Westphalia host the densest concentration of validated analytical environments.
Japan
PMDA pharmacopeial standards and METI industrial policy support domestic instrument manufacturing while tightening import competition. Localized service networks and rapid response protocols favor domestic suppliers in quality control procurement decisions. The Kanto region around Tokyo and Osaka-Kobe pharmaceutical corridors anchor the installed base expansion.
India
FSSAI food safety mandates and CDSCO export compliance requirements pull high pressure gradient systems into Hyderabad and Bengaluru CDMO facilities. Contract manufacturing scale-up for regulated markets demands 21 CFR Part 11 compliant data systems. The Telangana and Karnataka clusters show the fastest instrument placement growth for pharmaceutical analysis applications.
Switzerland
Swissmedic inspection intensity and ICH guideline implementation create premium-tier demand for ultra-high pressure systems with embedded qualification protocols. The Basel pharmaceutical manufacturing corridor and Zurich analytical service hubs prioritize gradient precision over capital cost minimization in procurement decisions.
Binary High Pressure Gradient Liquid Chromatography System Market Competitive Landscape
Listed leaders compete with private specialists across technology specialization and geographic coverage dimensions, producing a tiered structure where scale-driven conglomerates anchor volume while focused instrument houses capture premium niches. Three archetypes dominate: diversified life science conglomerates with chromatography divisions, dedicated analytical instrument specialists, and regional manufacturing champions with localized service networks. Competitive moves concentrate on strategic partnerships for software integration and geographic expansion through distribution agreements rather than vertical integration plays.
Within the diversified conglomerate tier, Agilent Technologies and Thermo Fisher Scientific exemplify scale-driven positioning across multiple analytical modalities. Waters Corporation occupies a distinct specialist archetype, anchoring premium positioning through mass spectrometry-coupled platform integration. Shimadzu Corporation represents the regional manufacturing champion model, leveraging domestic market density and Asian supply channel control to defend service response advantages.
| Leading Market Players |
|---|
| Agilent Technologies |
| Waters Corporation |
| Thermo Fisher Scientific |
| Shimadzu Corporation |
| Bio-Rad Laboratories |
| Hitachi High-Tech Corporation |
| JASCO |
| Tosoh Bioscience |
| PerkinElmer |
| Others |
Pricing and Supply Chain Analysis
Manufacturing scale economies in precision ceramic piston production anchor both supply concentration and price floors across the binary high pressure gradient LC system market. German and Japanese component specialists leverage dedicated capacity utilization to defend margin structures while mid-sized contract research organizations face lifecycle cost barriers from consumable replacement cycles at 600+ bar operating pressures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Price differentiation rests on FDA 21 CFR Part 11 certification tier and embedded compliance software depth, with pharmaceutical quality control laboratories in the United States and Germany showing lowest price sensitivity. Cost compression in the economy tier is intensifying because Indian and Chinese CDMO procurement teams unbundle service contracts and demand component-level pricing transparency.
Supply Chain Analysis
Strait of Hormuz transit risk for helium carrier gas exposes mass spectrometry-coupled system supply chains to geopolitical volatility. Precision fluidics manufacturing concentrates in Germany, Japan, and the United States, drawing from specialized ceramic substrates, sapphire piston seals, and high-purity solvent reservoirs. Single-source vulnerability for sub-2-micron particle column substrates creates procurement risk. Distribution runs through authorized service networks with localized qualification protocols rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified metrology technicians for 1500 bar system maintenance represent the critical skill gap constraining market expansion, with secondary pharmaceutical markets experiencing extended service response times that threaten instrument uptime guarantees.
For Market Incumbents: Fortify service network density in Hyderabad and Bengaluru CDMO clusters to preempt emerging entrant channel capture. Invest in backward integration into ceramic piston seal manufacturing to defend margin structures against consumable cost transparency demands from top-twenty pharmaceutical procurement teams. For New Entrants and Emerging Players: Anchor in FSSAI-mandated food safety testing laboratories across India where incumbent service response times create white-space vulnerability. Target environmental monitoring applications under EPA Method 1633 adoption curves with PFAS-specific method packages as differentiated entry wedge. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-driven method optimization software specialists over hardware-dependent instrument houses. Long-term viability hinges on recurring revenue attachment rates from intelligent chromatography platforms. Watch FDA 21 CFR Part 11 enforcement intensity as inflection indicator for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Method Optimization Platform Launch | Machine learning integration reduces pharmaceutical method development timelines from weeks to days under ICH Q14 guidelines. |
| Backward Integration into Ceramic Component Manufacturing | In-house piston seal production defends margin structures against unbundled procurement pressure from CDMO sourcing teams. |
| Localized Service Network Expansion in India | Rapid response protocols in Telangana and Karnataka clusters capture CDMO scale-up demand for export compliance. |
| Strategic Partnership for Mass Spectrometry Coupling | Deepened Waters Corporation-style platform integration anchors premium positioning in peptide therapeutic analysis. |
| Embedded Compliance Software Development | Automated qualification protocols address EMA ICH Q2(R1) gradient accuracy documentation requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical quality control laboratories, CDMO procurement teams, and analytical instrument service engineers. Secondary validation drew from FDA bioanalytical method validation guidance documents, EMA ICH Q2(R1) revision texts, USP general chapter updates, and SEC 10-K instrument revenue disclosures. Bottom-up instrument placement tracking triangulated against top-down pharmaceutical R&D expenditure flows.
Across the analysis window, the analytical framework modeled segmentation dimensions including pressure specification tier, gradient mixing architecture, end-use application, and regional regulatory cluster. CAGRs were derived from instrument replacement cycle compression and continuous manufacturing adoption curves. Forecast inputs incorporated EPA Method 1633 protocol expansion timelines and PMDA pharmacopeial standard evolution.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA 21 CFR Part 11 enforcement and helium supply stability; material deviation in regulatory inspectorate emphasis or Qatar export policy would warrant model refresh. Practitioners should keep alternative scenarios live as ICH Q14 method development burden and AI-driven optimization penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.