
 Rheometer Market | 2026-2036
Rheometer Market Size, Share, and Industry Trends Forecast 2026-2036
Rheometer Market Analysis
Aftermarket service revenue is tilting toward calibration contracts and software upgrades as instrument lifecycles extend. Anton Paar GmbH leverages its Austrian manufacturing base to dominate high-precision rotational systems for polymer laboratories. TA Instruments sustains technology leadership through integrated thermal-rheology platforms that anchor premium positioning in North American pharmaceutical quality control. Brookfield Engineering Laboratories competes on instrument durability and channel density across food and beverage processing plants.
A rheometer measures deformation and flow response of materials under controlled shear stress or strain, typically operating across viscosity ranges from millipascal-seconds to mega-pascal-seconds with temperature control from cryogenic to 600°C for polymer melt analysis. Rotational rheometers command the largest installed base due to versatility across food, cosmetics, and polymer formulation workflows, while capillary rheometers retain dominance in high-shear polymer processing simulations where extrusion die design depends on accurate melt viscosity data. Digital rheometers are displacing manual configurations as laboratories prioritize automated data acquisition and compliance traceability.
REACH compliance in Europe and FDA 21 CFR Part 11 validation requirements in the United States shape instrument specifications, forcing vendors to embed audit-trail software and certified reference materials. ISO 17025 accreditation standards for testing laboratories further filter procurement toward suppliers with documented calibration chains. Stakeholders must weigh capital expenditure against total cost of ownership as service contracts and reagent streams claim growing shares of lifetime instrument economics.
Market Dynamics
Polymer manufacturers face intensifying pressure to document melt-flow consistency as REACH enforcement tightens material traceability requirements, forcing instrument procurement cycles to compress and calibration documentation standards to rise.
Growth Catalysts
- REACH polymer-contact rules:European chemical manufacturers must verify melt viscosity across temperature ranges, expanding rotational rheometer installations in quality control laboratories.
- Automotive lightweighting:German OEMs specify high-shear capillary rheometry for thermoplastic composite validation in electric vehicle battery housings and structural components.
- Digital audit-trail mandates:FDA 21 CFR Part 11 validation requirements compel pharmaceutical laboratories to replace manual instruments with automated data acquisition systems.
Market Restraints
- Precision sensor supply concentration:Torque transducer manufacturing concentrates in Austrian and German supplier networks, creating vulnerability to component lead time volatility.
- Capital intensity of thermal-rheology platforms:Integrated temperature control modules require substantial upfront investment, limiting adoption in mid-sized polymer compounders.
- Substitution by in-house viscometry:Food processors with less stringent regulatory exposure increasingly rely on simplified kinematic viscometers for routine batch release.
Strategic Opportunities
- India specialty chemical expansion:BIS certification requirements for industrial polymers are accelerating laboratory instrumentation investments in Mumbai and Ahmedabad manufacturing clusters.
- Biopolymer formulation workflows:PLA and PHA developers require shear-history characterization that rotational systems uniquely provide.
- Cloud-connected calibration services:Remote diagnostic platforms enable vendors to unbundle hardware sales from recurring software-enabled maintenance revenue streams.
Industry Challenges
- ISO 17025 accreditation timelines:Testing laboratories face extended validation periods when integrating new rheometric methods into certified quality systems.
- Legacy LIMS integration complexity:Digital rheometers must interface with established laboratory information management systems, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rheometer Market |
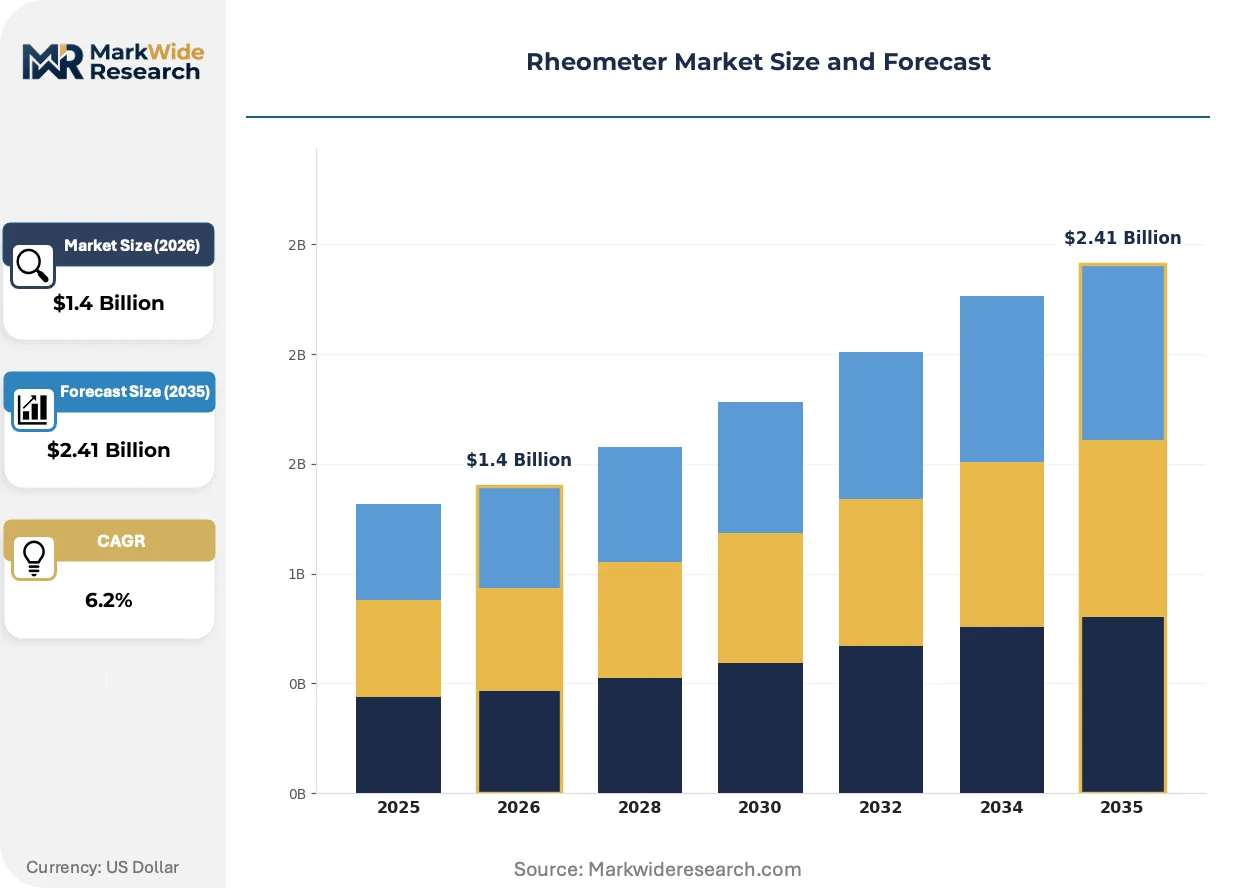
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotational Rheometers, Capillary Rheometers, Oscillatory Rheometers, High-Temperature Rheometers End User: Food and Beverage, Pharmaceuticals, Cosmetics, Polymer Industries Technology: Digital Rheometers, Manual Rheometers, Hybrid Rheometers, Lab-Scale Rheometers Application: Quality Control, Research and Development, Production Process, Material Testing |
| Companies Covered | Anton Paar GmbH, Thermo Fisher Scientific, TA Instruments, Brookfield Engineering Laboratories, Cannon Instrument Company, Goettfert GmbH, AMETEK Inc., Lamy Rheology Instruments, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rheometer Market Emerging Trajectories
Digital instrumentation is compressing traditional hardware-centric business models while regulatory digitization mandates reshape vendor service portfolios. Three developments dominate current strategic planning.
Software-defined rheometry platforms are virtualizing instrument functionality through modular measurement algorithms and cloud-based data processing. Polymer laboratories in Germany and the United States are adopting subscription-licensed rheometric workflows faster than capital purchase cycles. This architecture is virtualizing the traditional distinction between entry-level and research-grade hardware tiers.
EU F-Gas Regulation restrictions on fluorinated refrigerants are forcing thermal control system redesigns in high-temperature rheometers. Instrument manufacturers must certify alternative cooling chemistries while maintaining temperature precision across cryogenic to 600°C ranges. Capillary rheometer suppliers serving extrusion simulation markets face the steepest compliance cost adjustments.
Service unbundling is fragmenting traditional instrument sales into discrete hardware, calibration, and software upgrade transactions. Food and beverage processors increasingly procure rheometers through third-party laboratory service contracts rather than direct capital expenditure. This pattern is most visible in North American contract manufacturing organizations seeking to minimize fixed asset exposure.
Rheometer Market Segmentation
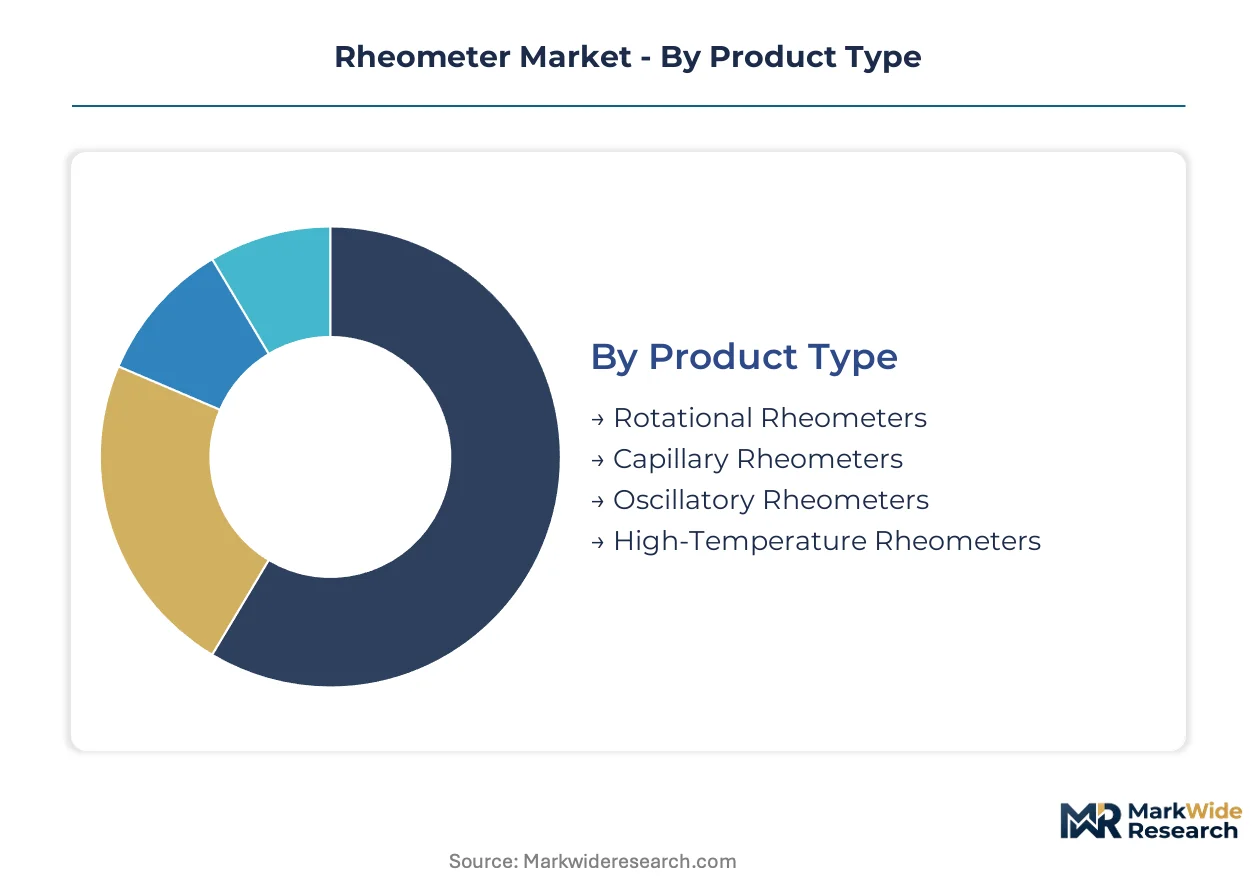
Rheometer procurement cycles vary dramatically across product tiers, with entry-level digital units refreshing every 4-6 years while high-temperature thermal-rheology platforms operate for 10-15 years. Understanding these replacement rhythms shapes vendor service strategies and laboratory capital planning.
Product Type:
Rotational systems turn over fastest due to software obsolescence pressures, while high-temperature platforms endure longest given thermal module replacement costs and calibration continuity requirements.
- Rotational Rheometers:These instruments apply controlled shear stress or strain to measure viscosity across millipascal-second to mega-pascal-second ranges with temperature control from ambient to 300°C. German polymer laboratories and food formulation centers in the United States concentrate procurement here, driven by REACH batch consistency mandates and FDA 21 CFR Part 11 audit-trail requirements. Pharmaceutical quality control workflows in Switzerland and specialty chemical R&D in Japan sustain replacement demand as software-defined measurement protocols displace legacy hardware.
- Capillary Rheometers:High-shear extrusion simulation systems operate at pressures up to 200 MPa with barrel temperatures reaching 400°C, generating apparent viscosity curves critical for die design. German automotive OEMs specify these for thermoplastic composite validation in electric vehicle battery housings, while polymer compounders in Austria rely on them for masterbatch development. EU F-Gas Regulation compliance costs for thermal control redesigns are compressing margins for suppliers serving this segment.
- Oscillatory Rheometers:Dynamic mechanical analysis capabilities characterize viscoelastic moduli across frequency sweeps for gelation and curing studies.
- High-Temperature Rheometers:Extended thermal ranges to 600°C serve polymer melt analysis and advanced ceramics processing with extended capital cycles.
Rotational rheometers anchor the volume base while capillary systems gain share at the steepest rate.
End User:
Customer procurement authority concentrates in quality control departments with ISO 17025 accreditation requirements, while R&D groups prioritize measurement flexibility over compliance documentation.
- Polymer Industries:Thermoplastic and elastomer manufacturers require melt-flow index determination, shear viscosity profiling, and extensional rheometry for extrusion and injection molding process design. German automotive suppliers and specialty chemical producers in Switzerland drive premium instrument specification, with REACH enforcement tightening documentation standards for material traceability. Integrated thermal-rheology platforms command sustained investment despite capital intensity.
- Pharmaceuticals:Parenteral formulation development, topical product rheology, and excipient characterization demand FDA 21 CFR Part 11 validation with embedded audit-trail software. Swissmedic and Health Canada inspection protocols shape instrument specification for sterile manufacturing facilities in Basel and Toronto clusters. Digital displacement of manual configurations accelerates as cloud-connected calibration services reduce validation downtime.
- Food and Beverage:Texture analysis, spreadability testing, and stability screening for sauces, dressings, and confectionery products.
- Cosmetics:Emulsion rheology, yield stress measurement, and sensory correlation for skincare and haircare formulations.
Polymer industries anchor the volume base while pharmaceuticals expand most quickly.
Technology:
Digital architectures command pricing premiums against manual alternatives, while hybrid configurations serve laboratories bridging legacy workflows with automated data acquisition.
- Digital Rheometers:Automated data acquisition, cloud-connected calibration diagnostics, and software-defined measurement algorithms eliminate transcription errors and enable remote service unbundling. Pharmaceutical laboratories in the United States and polymer quality control facilities in Germany prioritize these systems for FDA and REACH compliance traceability. Subscription-licensed rheometric workflows are compressing traditional capital purchase cycles.
- Hybrid Rheometers:Bridge configurations preserve manual sample loading familiarity while adding digital data capture and LIMS connectivity for mid-sized testing laboratories.
- Manual Rheometers:Spring-based torque measurement and analog readout systems persist in cost-constrained food processing and education markets.
- Lab-Scale Rheometers:Portable and benchtop units with reduced sample volume requirements for formulation screening and teaching laboratories.
Digital rheometers anchor the volume base while hybrid systems climb the fastest.
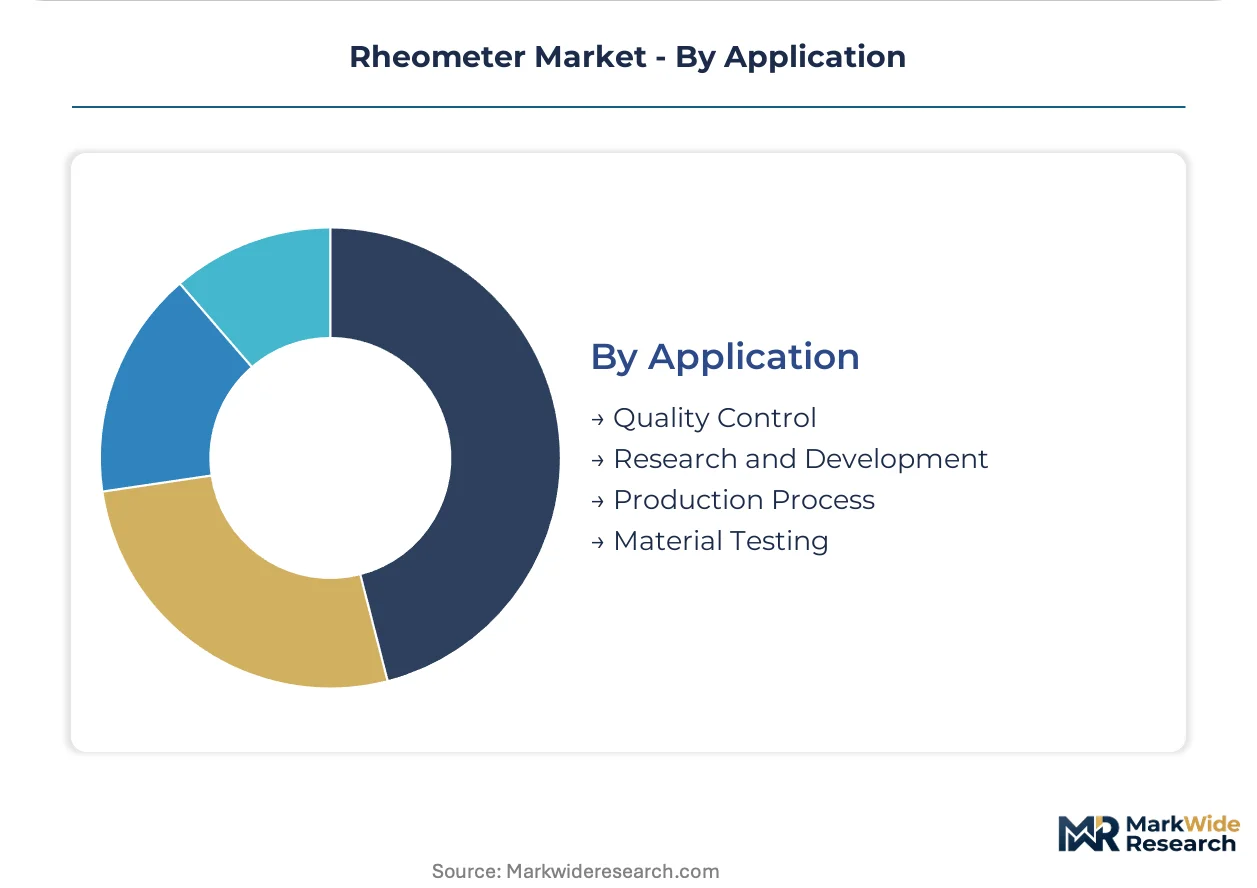
Application:
Quality control applications generate recurring consumable and calibration revenue streams, while research and development workflows prioritize measurement versatility over throughput.
- Quality Control:Routine batch release testing demands standardized methods with certified reference materials and documented calibration chains for ISO 17025 accreditation. Polymer manufacturers under REACH scrutiny and pharmaceutical facilities facing FDA inspection cycles sustain instrument utilization rates above 80 percent. Automated sample handling and pass-fail algorithm integration reduce technician intervention.
- Research and Development:Method development, novel material characterization, and publication-grade data generation require configurable measurement geometries and advanced analysis software.
- Production Process:In-line and at-line rheometric monitoring for extrusion, mixing, and coating operations with real-time process control integration.
- Material Testing:Structural adhesive characterization, asphalt binder grading, and petrochemical product specification verification.
Quality control anchors the volume base while production process applications gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs deploy capillary rheometers for thermoplastic composite validation, while pharmaceutical laboratories in the United States prioritize rotational systems for FDA compliance. This divergence in instrument preference shapes vendor regionalization strategies and service portfolio allocation.
United States
Pharmaceutical quality control laboratories in New Jersey and Massachusetts drive digital rheometer procurement for FDA 21 CFR Part 11 validation. Contract manufacturing organizations in the Research Triangle Park increasingly favor third-party laboratory service contracts over direct capital expenditure. Cloud-connected calibration services reduce validation downtime for sterile manufacturing facilities.
Germany
Automotive suppliers in Stuttgart and Munich specify high-shear capillary rheometry for electric vehicle battery housing materials. REACH enforcement tightens documentation standards for polymer traceability across the Rhine-Ruhr chemical corridor. Specialty chemical producers in Leverkusen anchor premium instrument purchasing for masterbatch development.
Japan
Cosmetics formulators in Osaka and Tokyo require oscillatory rheometers for emulsion stability screening and sensory correlation. METI guidelines on material characterization shape laboratory accreditation requirements. Polymer R&D clusters in Nagoya sustain replacement demand as software-defined protocols displace legacy hardware configurations.
India
Specialty chemical manufacturers in Mumbai and Ahmedabad accelerate laboratory instrumentation investments under BIS certification requirements for industrial polymers. Domestic compounders seek entry-level digital units with automated data acquisition. Quality control departments in Gujarat manufacturing clusters prioritize ISO 17025 accreditation compliance.
Switzerland
Pharmaceutical sterile manufacturing facilities in Basel specify validated rotational systems for parenteral formulation development. Swissmedic inspection protocols demand embedded audit-trail software with documented calibration chains. Precision instrument procurement concentrates among contract research organizations serving global drug development programs.
Rheometer Market Vendor Landscape
Capability concentration sits with Austrian and German precision engineering specialists; scale advantage sits with diversified analytical instrument conglomerates. The vendor base organizes around three strategic archetypes: high-precision rotational system specialists, integrated thermal-rheology platform providers, and durability-focused channel players. Competitive moves center on software-defined measurement licensing and service unbundling rather than hardware volume expansion.
Among Austrian and German precision specialists, Anton Paar GmbH and Goettfert GmbH occupy positions anchored in Central European manufacturing heritage. TA Instruments exemplifies the integrated platform tier through its thermal-rheology convergence strategy. Brookfield Engineering Laboratories represents the durability-focused archetype with channel density across food processing applications.
| Leading Market Players |
|---|
| Anton Paar GmbH |
| Thermo Fisher Scientific |
| TA Instruments |
| Brookfield Engineering Laboratories |
| Cannon Instrument Company |
| Goettfert GmbH |
| AMETEK Inc. |
| Lamy Rheology Instruments |
| Shimadzu Corporation |
| Others |
Supply Flow & Price Mechanics
Stuttgart and Munich manufacturing clusters concentrate precision torque transducer production, creating asymmetric pricing power for Austrian and German component suppliers serving rotational rheometer assembly. REACH documentation mandates and FDA validation requirements force buyers to absorb premium pricing for certified calibration chains, while extended instrument lifecycles compress replacement demand and intensify competition for service contract attach rates.
Pricing Analysis
Long-term service contracts dominate commercial relationships, with three-tier pricing structure across premium, standard, and economy levels tethered to calibration frequency and software upgrade entitlements. Price differentiation centers on ISO 17025 certification tier and after-sales service bundling, with pharmaceutical laboratories showing lowest sensitivity due to compliance imperatives while mid-sized polymer compounders face acute cost compression. Pricing pressure stems from software-defined measurement protocols that virtualize hardware tier distinctions and enable subscription-licensed alternatives to capital purchase.
Supply Chain Analysis
Contract manufacturing concentrates among Austrian precision engineering specialists and German thermal control module producers, with Goettfert GmbH and Anton Paar GmbH retaining captive in-house production of critical sensor assemblies. Component sourcing draws from German specialty steel suppliers for high-pressure capillary barrels, Swiss precision machining for oscillatory measurement geometries, and Japanese electronics for digital control interfaces. Single-source vulnerability concentrates in torque transducer manufacturing, with distribution running through direct vendor sales organizations and certified distributor networks serving ISO 17025-accredited laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated pharmaceutical quality control departments and polymer compounder purchasing alliances, fragmenting vendor pricing leverage as procurement centralization accelerates across German automotive supplier networks and North American contract manufacturing organizations.
For Market Incumbents:Entrench position through backward integration into precision sensor manufacturing and captive calibration service capacity in Stuttgart and Basel clusters. Cloud-connected diagnostic platforms represent the critical defensive lever against software-defined entrants unbundling hardware from recurring revenue streams. FDA 21 CFR Part 11 validation expertise and documented ISO 17025 calibration chains must deepen to sustain premium positioning against emerging Asian competitors.
For New Entrants and Emerging Players:Pursue white-space expansion in Indian specialty chemical laboratories seeking BIS-compliant entry-level digital units with automated data acquisition. Mumbai and Ahmedabad manufacturing clusters present the most penetrable geography, with mid-sized compounders prioritizing total cost of ownership over brand heritage. Go-to-market execution should leverage third-party laboratory service contracts rather than direct capital sales to minimize fixed asset exposure for risk-averse buyers.
For Investors and Strategic Acquirers:Carve-out targets emerge from diversified analytical instrument conglomerates seeking to divest non-core rheometry divisions amid portfolio rationalization pressures. Long-term viability favors platforms with embedded software-defined measurement architectures and recurring revenue attachment above sixty percent. Monitor cloud-connected calibration service penetration rates as the critical inflection signal for business model transition completion.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Measurement Licensing | Virtualizes hardware tiers and enables subscription revenue streams for polymer laboratories. |
| Backward Integration into Sensor Manufacturing | Secures torque transducer supply against Austrian and German supplier network volatility. |
| Cloud-Connected Calibration Services | Reduces validation downtime for FDA-regulated pharmaceutical sterile manufacturing facilities. |
| Thermal Control System Redesign | Addresses EU F-Gas Regulation compliance costs for high-temperature capillary platforms. |
| Third-Party Laboratory Service Contracts | Minimizes fixed asset exposure for North American contract manufacturing organizations. |
Methodological Framework
Cross-validation between primary interviews with polymer laboratory directors, pharmaceutical quality control managers, and aftermarket service heads anchors the qualitative findings against secondary validation from SEC instrument manufacturer filings, ISO 17025 accreditation databases, and REACH enforcement documentation. Bottom-up triangulation across installed base estimates and replacement cycle analysis converges with top-down expenditure tracking across German automotive supplier networks and North American pharmaceutical manufacturing clusters.
Calibration against historical instrument procurement patterns and regulatory mandate implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry concentration, technology architecture, and regional regulatory cluster intensity. CAGRs derive from weighted average of replacement cycle compression, software displacement rates, and compliance-driven upgrade propensity, with biopolymer formulation workflow adoption and cloud service attach rates as critical industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in specialty chemical capital expenditure cycles and pharmaceutical R&D budget allocations would shift the trajectory. Forecasts reflect documented assumptions regarding REACH enforcement intensity and FDA digitization mandate timelines. Quarterly review of BIS certification implementation progress in Indian manufacturing clusters and EU F-Gas Regulation thermal system redesign completion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Pellistor Bead Chemical Sensor Market
Testing Equipment
Polymer Testing Equipment Market
Testing Equipment
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market
Testing Equipment
Lactose Assay Kit Market
Testing Equipment
Geochemical Services Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Solar Testing Equipment Market
Testing Equipment
Ambient Temperature Gel Permeation Chromatography Market
Testing Equipment
Digital Shore Durometer Market
Testing Equipment
Oxidation Stability Analyzer Market
Testing Equipment
Wood Moisture Tester Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Automated Solid Phase Extraction Systems Market
Testing Equipment
Adhesive Tester Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Melting Point Apparatus Market