
 Fibrin Degradation Product (Fndp) Assays Market | 2026-2036
Fibrin Degradation Product (Fndp) Assays Market Size, Share, and Industry Trends Forecast 2026-2036
Fibrin Degradation Product (Fndp) Assays Market Foresight
Modular assay panel bundling is shifting buyer choice toward integrated coagulation diagnostic platforms. Thermo Fisher Scientific leverages its broad life sciences portfolio to anchor multi-analyte menu expansion. Roche Diagnostics differentiates through embedded assay automation on existing clinical chemistry infrastructure. Siemens Healthineers competes by extending its hemostasis testing footprint into decentralized hospital settings.
Fibrin Degradation Product assays detect plasmin-cleaved fibrin fragments through antibody-mediated recognition, typically reporting D-dimer and related neo-epitopes with ng/mL-level sensitivity for thrombotic event monitoring. The immunoassay technology segment dominates current installed bases due to established regulatory pathways and reagent recurring revenue models, while molecular diagnostics approaches gain traction in research settings seeking genetic correlates of fibrinolytic dysfunction. ELISA product configurations occupy mature, price-sensitive procurement channels, whereas high-throughput platforms capture margin pools in centralized reference laboratories processing elevated sample volumes.
FDA premarket notification requirements shape assay validation burdens for US market entrants, while the EU In Vitro Diagnostic Regulation mandates renewed conformity assessments that extend timelines for CE-marked product launches. Clinical laboratories must monitor evolving FDA guidance on fibrin degradation biomarker clinical utility to align test menu investments with reimbursement eligibility criteria.
Market Dynamics
Modular assay panel bundling is compressing standalone Fndp assay margins while redirecting procurement toward integrated coagulation platforms that consolidate multiple biomarker tests onto single instruments.
Growth Catalysts
- EU MDR compliance deadlines:The EU In Vitro Diagnostic Regulation mandates renewed conformity assessments that accelerate replacement cycles for legacy ELISA systems, creating upgrade demand for automated immunoassay platforms.
- Specialized hematology centers in Germany:These institutions drive adoption of high-sensitivity fibrin degradation assays through centralized purchasing power and standardized protocols for thrombotic event monitoring.
- Point-of-care testing expansion:Decentralized hospital settings in the United States are integrating rapid D-dimer assays into emergency department triage workflows, reducing time-to-diagnosis for suspected pulmonary embolism.
Market Restraints
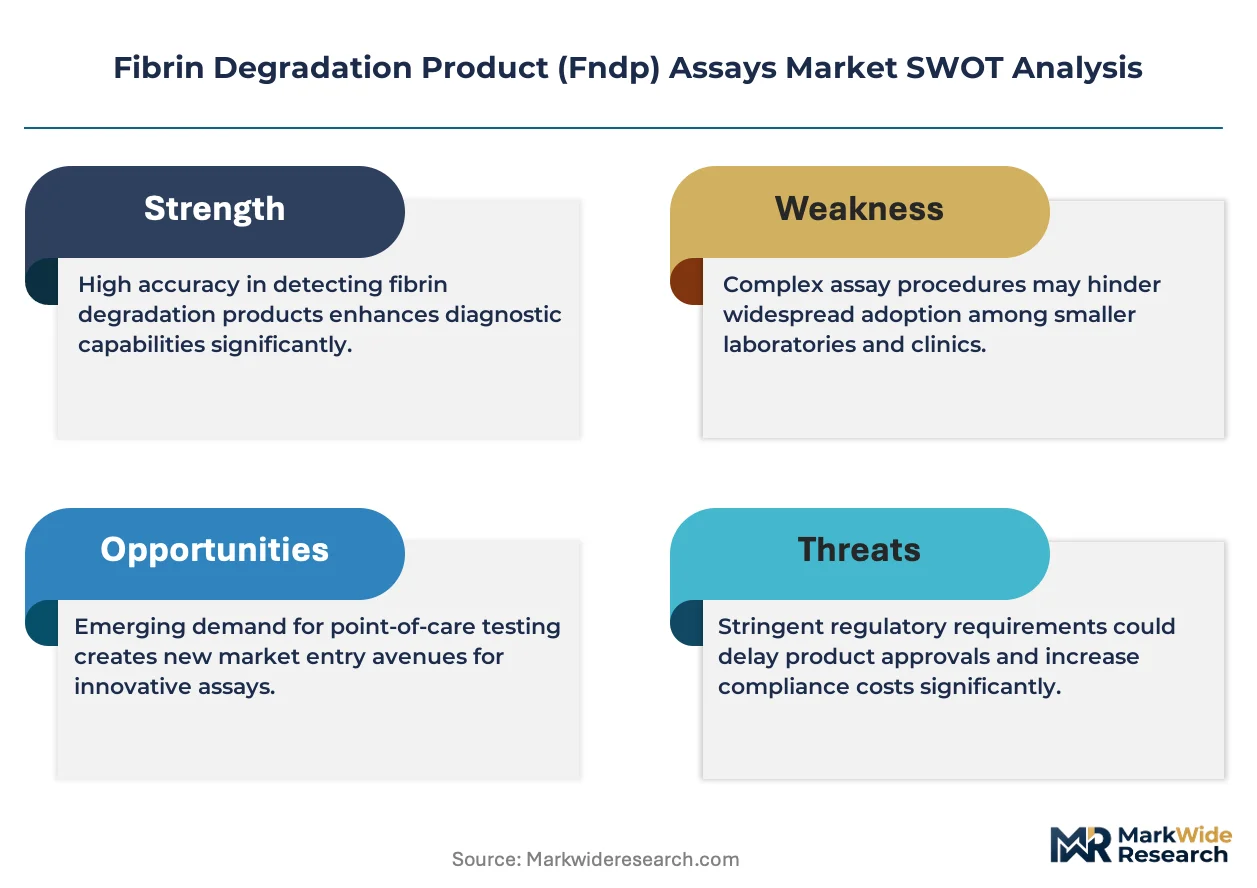
- Reagent cost volatility:Antibody production inputs face supply concentration among specialized biologics suppliers, squeezing gross margins for assay manufacturers.
- Technical limitation of cross-reactivity:Fibrin degradation product assays struggle to distinguish D-dimer from fibrinogen degradation products in certain patient populations, limiting clinical specificity.
- FDA premarket notification burden:The 510(k) pathway requires extensive predicate device comparisons and clinical validation studies that extend development timelines for novel assay formats.
Strategic Opportunities
- Underpenetrated outpatient clinics in India:The country's national pharmaceutical regulator is streamlining import licensing for IVD reagents, opening channels for mid-throughput platforms in tier-2 cities.
- Technology convergence of immunoassay and molecular diagnostics:Research settings are exploring genetic correlates of fibrinolytic dysfunction, creating hybrid product development paths.
- Japan's PMDA accelerated review pathway:The regulator's priority review designation for thrombosis-related diagnostics offers faster market access for novel biomarker combinations.
Industry Challenges
- Specialized hematopathologist shortage:Interpretation of complex coagulation profiles requires subspecialty expertise that remains concentrated in academic medical centers.
- Legacy LIS integration complexity:New assay platforms must interface with entrenched laboratory information systems that lack standardized data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fibrin Degradation Product (Fndp) Assays Market |
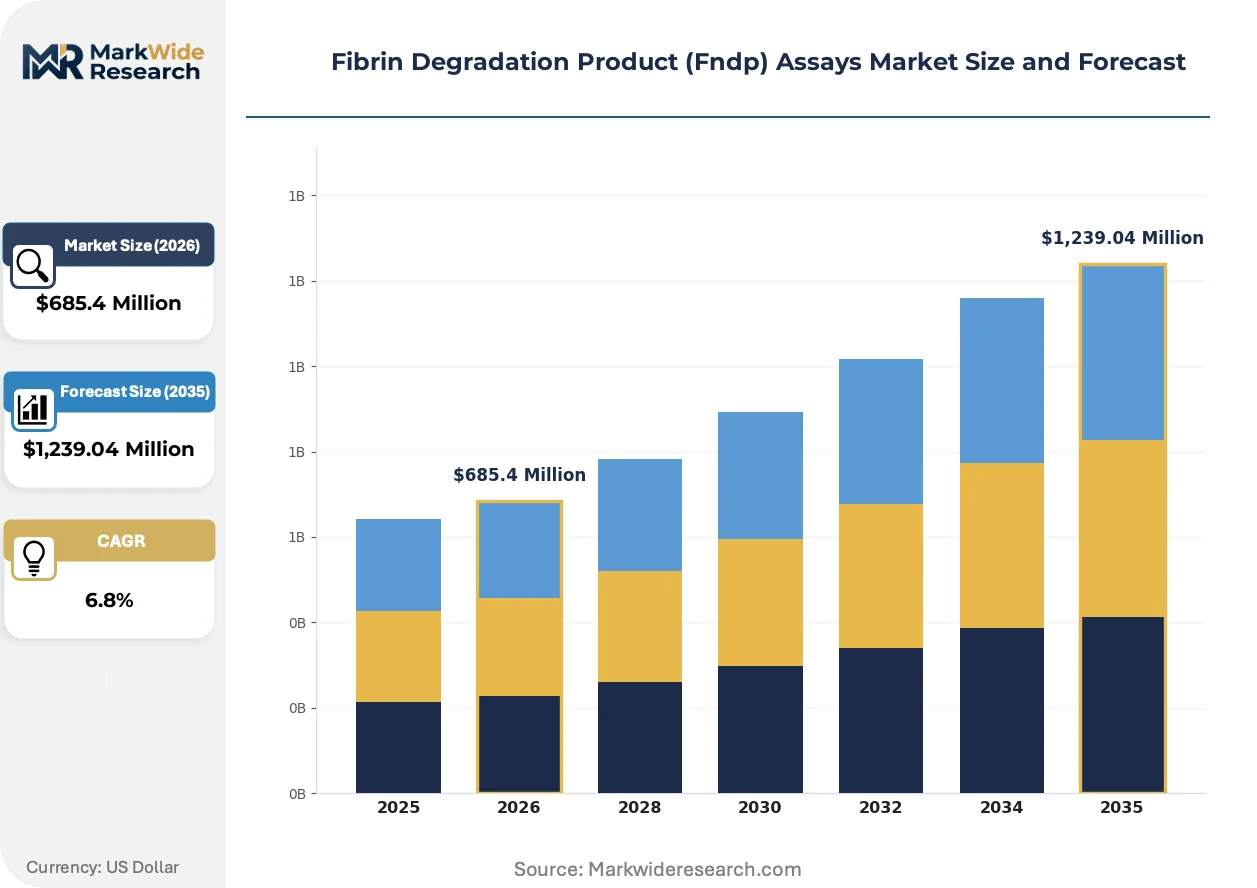
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA, Lateral Flow, High-Throughput, PCR Technology: Immunoassay, Molecular Diagnostics, Biosensors, Chromatography End User: Hospitals, Clinical Laboratories, Research Institutions, Blood Banks Application: Cardiovascular Disease, Hematology, Infectious Diseases, Oncology |
| Companies Covered | Thermo Fisher Scientific, CUSABIO, Elabscience Biotechnology, ELK Biotechnology, Abcam, Bio-Rad Laboratories, Roche Diagnostics, Siemens Healthineers, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fibrin Degradation Product (Fndp) Assays Market Shifts & Advancements
Automation architectures and regulatory recertification pressures are restructuring how Fndp assays reach clinical end-users, with three distinct vectors reshaping competitive positioning.
High-throughput chemiluminescent immunoassay platforms are overtaking traditional ELISA configurations in centralized reference laboratories processing elevated sample volumes. These systems reduce manual handling steps and improve coefficient of variation metrics. The structural consequence is margin compression for standalone ELISA suppliers while integrated platform vendors capture recurring revenue streams.
The EU In Vitro Diagnostic Regulation mandates renewed conformity assessments that extend timelines for CE-marked product launches. Manufacturers must rebuild technical documentation and clinical evidence packages under stricter performance evaluation requirements. Small-to-mid assay developers face disproportionate compliance burdens compared to diversified diagnostics conglomerates with established quality management systems.
Hospital procurement committees are consolidating vendor relationships through multi-year exclusive supply agreements that bundle Fndp testing with broader hemostasis menus. Group purchasing organizations negotiate master contracts that displace spot purchasing from individual laboratories. This concentration is most visible in Germany, where hospital network consolidation has reduced the number of independent purchasing decision points by over half in the past decade.
Fibrin Degradation Product (Fndp) Assays Market Segmentation
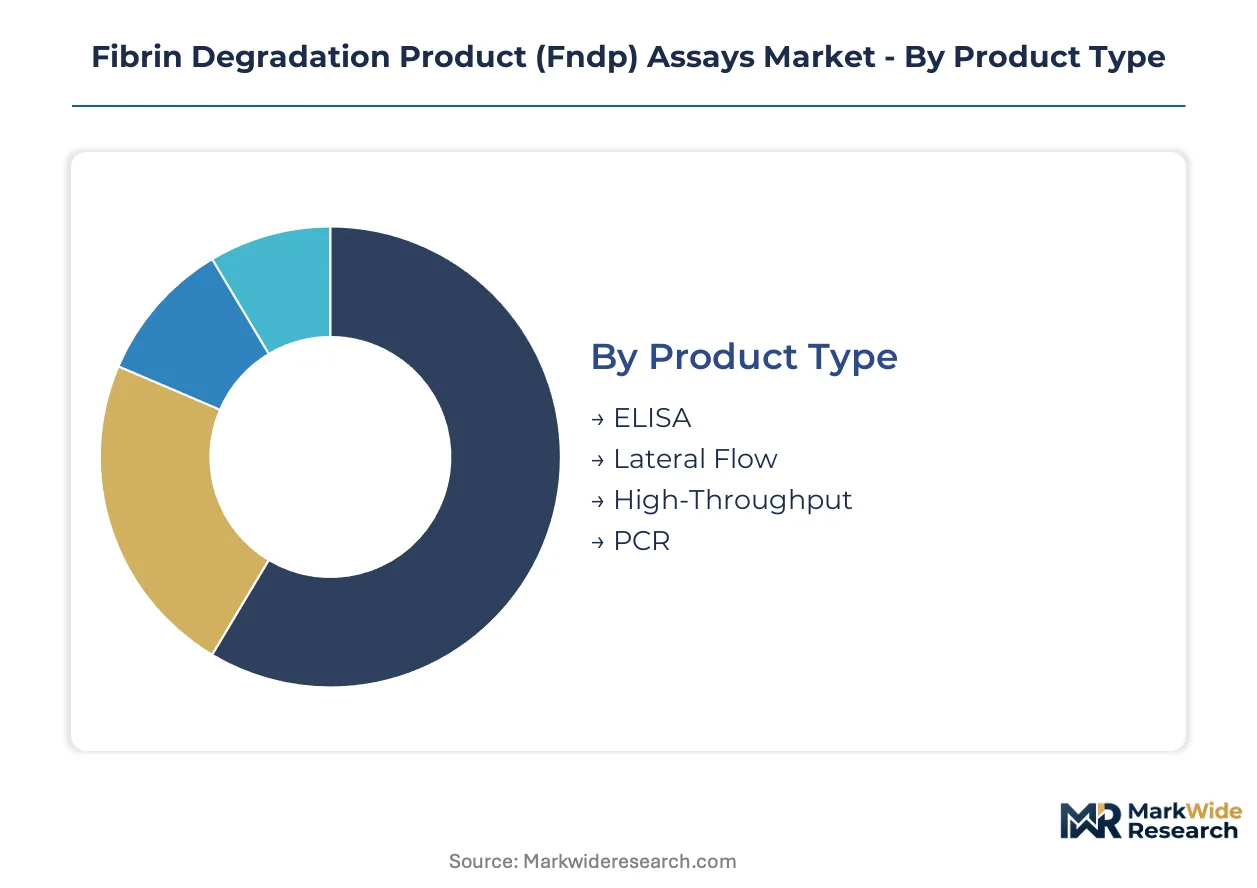
Fibrin degradation product assays serve divergent workflows across centralized laboratories, emergency departments, and research settings. Segmentation reveals how technical specifications, throughput requirements, and regulatory pathways reshape procurement decisions and vendor competitive positioning.
Product Type:
Buyers differentiate primarily by sample volume economics and regulatory validation status rather than analytical sensitivity alone.
- ELISA:Enzyme-linked immunosorbent assays employ microplate formats with colorimetric or chemiluminescent detection, requiring manual pipetting and wash steps. Procurement concentrates in price-sensitive hospital laboratories in India and Southeast Asia where capital constraints favor lower instrument costs over automation.
- High-Throughput:Random-access analyzers process 100-400 tests hourly with minimal operator intervention. Demand clusters in German reference laboratories and US health system core facilities where labor cost reduction justifies premium platform acquisition.
- Lateral Flow:Single-use immunochromatographic cassettes deliver qualitative or semi-quantitative results within 15 minutes. Emergency departments in the United States deploy these for rapid D-dimer triage of suspected pulmonary embolism.
- PCR:Polymerase chain reaction amplifies genetic markers of fibrinolytic pathway polymorphisms. Academic medical centers in Japan utilize these for pharmacogenomic research correlating genotype with thrombotic risk.
Volume sits with ELISA in emerging markets; growth tilts toward high-throughput platforms in consolidated health systems.
Technology:
Technology selection tracks the maturity of biomarker validation and the availability of predicate devices for regulatory submission.
- Immunoassay:Antibody-mediated detection of D-dimer neo-epitopes dominates clinical practice with established FDA 510(k) pathways. Siemens Healthineers and Roche Diagnostics anchor installed bases through automated chemiluminescent platforms.
- Molecular Diagnostics:Nucleic acid amplification and sequencing identify genetic variants affecting plasminogen activator inhibitor expression. Research institutions in Germany and the United States drive adoption for cohort studies of hereditary thrombophilia.
- Biosensors:Electrochemical and optical transducers enable label-free detection with reduced reagent consumption. Development-stage platforms target point-of-care deployment in decentralized Japanese clinics.
- Chromatography:Liquid chromatography-mass spectrometry delivers reference measurement procedure accuracy for assay standardization. National metrology institutes in the United States and Germany employ these for calibrator value assignment.
Revenue concentrates in immunoassay; expansion accelerates most quickly in molecular diagnostics for precision medicine applications.
End User:
End-user categories reflect divergent purchasing authority, reimbursement structures, and technical expertise requirements.
- Clinical Laboratories:High-volume testing facilities process fibrin degradation assays alongside comprehensive coagulation panels. German hospital networks consolidate procurement through centralized laboratory medicine divisions.
- Hospitals:Acute care institutions integrate rapid testing into emergency department and intensive care workflows. US health systems prioritize turnaround time reduction for pulmonary embolism rule-out protocols.
- Research Institutions:Academic and contract research organizations investigate novel fibrinolytic biomarkers and genetic correlates. Funding from the National Institutes of Health supports assay development at US universities.
- Blood Banks:Transfusion services monitor donor plasma quality and detect pathological fibrinolysis. Indian blood centers expand testing capacity under national hemovigilance program mandates.
Test volume aggregates in clinical laboratories; fastest adoption occurs in hospital point-of-care settings.
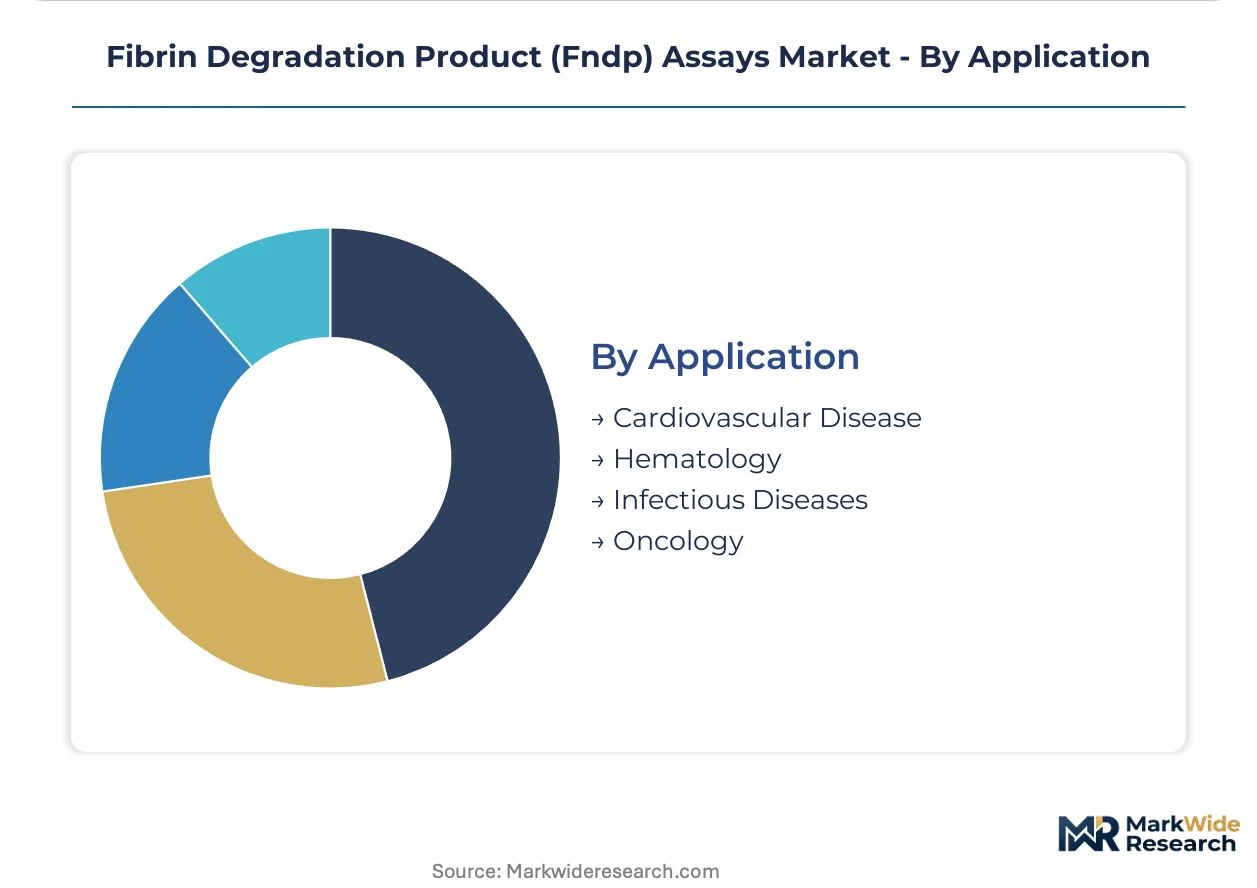
Application:
Application segmentation aligns with disease-specific reimbursement codes and clinical guideline recommendations.
- Cardiovascular Disease:D-dimer testing excludes venous thromboembolism in low-to-intermediate risk patients. US emergency medicine societies embed quantitative thresholds into pulmonary embolism decision rules.
- Hematology:Coagulation specialists monitor disseminated intravascular coagulation and fibrinolytic therapy response. German hematology centers standardize high-sensitivity assay protocols across hospital networks.
- Infectious Diseases:Sepsis-induced coagulopathy elevates fibrin degradation products as prognostic indicators. Research applications in Japan explore bacterial virulence factor interactions with host fibrinolysis.
- Oncology:Cancer-associated thrombosis and chemotherapy complications drive biomarker surveillance. US comprehensive cancer centers incorporate D-dimer into venous thromboembolism risk stratification models.
Cardiovascular applications generate the largest test volume; oncology represents the steepest expansion trajectory as cancer-associated thrombosis protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of Fndp assay platforms concentrates in Germany and the United States, while clinical consumption spreads across hospital networks in India, Japan, and European hematology centers. This geographic split shapes regulatory investment priorities and distribution channel economics.
United States
Emergency departments in US health systems deploy rapid D-dimer assays for pulmonary embolism triage, cutting time-to-diagnosis. FDA 510(k) premarket notification requirements shape validation burdens for novel assay formats. Boston and San Diego anchor development-stage biosensor research for point-of-care platforms.
Germany
Specialized hematology centers in Germany drive adoption of high-sensitivity fibrin degradation assays through centralized purchasing. EU MDR compliance deadlines accelerate replacement cycles for legacy ELISA systems. Munich and Heidelberg clusters concentrate automated immunoassay manufacturing for European hospital networks.
India
Outpatient clinics in tier-2 Indian cities expand testing capacity under national hemovigilance program mandates. The country's national pharmaceutical regulator streamlines import licensing for IVD reagents. Hyderabad and Mumbai medical device corridors attract mid-throughput platform distributors.
Japan
Academic medical centers in Japan utilize PCR-based assays for pharmacogenomic research correlating genotype with thrombotic risk. PMDA accelerated review pathways offer faster market access for novel biomarker combinations. Tokyo and Osaka metropolitan areas concentrate research institution procurement.
China
Clinical laboratories in Chinese hospital networks process elevated coagulation panel volumes for cardiovascular disease screening. NMPA registration requirements extend timelines for imported assay platform launches. Shanghai and Beijing biotech clusters drive domestic immunoassay development.
Fibrin Degradation Product (Fndp) Assays Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Fndp assays landscape. The market structure tilts toward consolidation as hospital procurement committees bundle multi-analyte menus through exclusive supply agreements. Three archetypes dominate: life sciences conglomerates with broad diagnostic portfolios, dedicated hemostasis testing specialists, and research reagent suppliers serving academic institutions. M&A activity and technology licensing agreements represent the primary competitive moves reshaping vendor positioning.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and Roche Diagnostics anchor the integrated platform tier through automated chemiluminescent systems. Siemens Healthineers occupies a position extending hemostasis testing into decentralized hospital settings. Research reagent specialists including Abcam and Bio-Rad Laboratories exemplify the focused supplier archetype serving academic and contract research organizations with antibody and ELISA catalog offerings.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| CUSABIO |
| Elabscience Biotechnology |
| ELK Biotechnology |
| Abcam |
| Bio-Rad Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Beckman Coulter |
| Others |
Supply & Pricing Matrix
Antibody production input costs cascade through three-tier pricing structures across premium, standard, and economy levels, compressing margins for standalone ELISA suppliers while integrated platform vendors capture recurring revenue through automated chemiluminescent systems. Procurement committees in German hospital networks exploit this concentration through multi-year exclusive supply agreements that bundle Fndp testing with broader hemostasis menus.
Pricing Analysis
Margin tightening in economy-tier ELISA configurations reflects reagent cost volatility from specialized biologics supply concentration. Pricing stratifies across premium, standard, and economy tiers based on automation level and FDA 510(k) validation status. Cost-down pressure on mid-throughput platforms accelerates because Indian outpatient clinics prioritize capital-constrained procurement. Reference laboratories in the United States exhibit lowest price sensitivity, while tier-2 Indian hospital laboratories drive hardest bargain negotiations.
Supply Chain Analysis
Specialized biologics manufacturing workforce availability in Germany and the United States anchors automated immunoassay platform production. Supply chains draw from monoclonal antibody production facilities in Germany, precision optics suppliers in Japan, and microfluidic component fabricators in the United States. Single-source vulnerability concentrates in specialized antibody suppliers, exposing manufacturers to input disruption. Distribution runs through group purchasing organizations negotiating master contracts that displace spot purchasing from individual laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Fndp assays market functions as a cost-of-compliance story where EU MDR recertification requirements erect barrier-to-entry moats favoring diversified diagnostics conglomerates with established quality management systems over small-to-mid assay developers.
For Market Incumbents: Deploy assay menu bundling to anchor hospital procurement committee relationships against emerging biosensor specialists. Siemens Healthineers extends hemostasis testing footprints into decentralized settings, while Thermo Fisher Scientific leverages broad life sciences portfolios to consolidate multi-analyte platform positions. Backward integration into antibody production buffers reagent cost volatility from specialized biologics suppliers. For New Entrants and Emerging Players: Enter via underpenetrated outpatient clinics in Indian tier-2 cities where streamlined CDSCO import licensing creates channel access for mid-throughput platforms. White-space concentration sits with lateral flow rapid D-dimer assays for emergency department triage workflows. Go-to-market execution should target hospital network consolidation in Germany through centralized laboratory medicine divisions seeking ELISA replacement platforms. For Investors and Strategic Acquirers: Distressed-cycle entries favor research reagent specialists with antibody catalog depth in Japan and Germany during PMDA and EU MDR compliance transitions. Long-term viability hinges on hybrid immunoassay-molecular diagnostics convergence plays. Watch PMDA accelerated review pathway designations as inflection signal for novel biomarker combination viability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Transition | Accelerated replacement cycles for legacy ELISA systems create upgrade demand for automated platforms. |
| Assay Menu Bundling | Hospital procurement committees consolidate vendor relationships through multi-year exclusive supply agreements. |
| Point-of-Care Platform Development | Emergency departments in US health systems integrate rapid D-dimer assays into pulmonary embolism triage workflows. |
| Pharmacogenomic Research Partnership | Academic medical centers in Japan utilize PCR-based assays for genotype-thrombotic risk correlation studies. |
| Mid-Throughput Distribution Expansion | Hyderabad and Mumbai medical device corridors attract platform distributors serving Indian tier-2 cities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with clinical laboratory directors, hospital procurement managers, hematopathologists, GPO contracts managers, and IVD regulatory affairs leads. FDA 510(k) premarket notification databases, EU MDR technical documentation requirements, PMDA submission records, and CDSCO import licensing registries provided validation anchors. Bottom-up test volume modeling triangulated against top-down market sizing from installed base estimates.
Data-stream reconciliation across immunoassay and molecular diagnostics technology segments, ELISA and high-throughput product configurations, and clinical laboratory versus hospital end-user categories shaped analytical framework development across the projection horizon. CAGRs derived from weighted average of segment growth trajectories calibrated to EU MDR replacement cycle timing and point-of-care expansion rates. Forecast inputs incorporated antibody production cost indices and hospital network consolidation metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory timeline slippage or antibody supply disruption scenarios. Assumptions reflect EU MDR compliance deadline adherence, PMDA accelerated review pathway utilization rates, and CDSCO import licensing streamlining progress. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Sample Preparation Market
Testing Equipment
Digital Shore Durometer Market
Testing Equipment
Next-Generation Titrators Market
Testing Equipment
Water Analysis Instruments Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Chemical Testing Services Market
Testing Equipment
FTIR Fuel Analyzer Market
Testing Equipment
Global Film Thickness Measurement Market
Testing Equipment
Chromatography Systems Market
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Chemical Reaction Monitoring Equipment Market
Testing Equipment
Membrane Osmometer Market
Testing Equipment
Europe Process Analytics Market
Testing Equipment
Global Insulation Testers Market
Testing Equipment
Solid Density Tester Market
Testing Equipment
Water Testing Equipment Market