
 Global Chromatography Instruments Market | 2026-2036
Global Chromatography Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chromatography Instruments Market Foresight
The gap between high-performance liquid chromatography and ultrahigh-performance liquid chromatography platforms is narrowing as vendors standardize column chemistries and detector interoperability across both systems. Thermo Fisher Scientific leverages its captive ion source technology to sustain premium positioning in mass spectrometry-coupled systems. Agilent Technologies anchors its installed base through compliance-ready software ecosystems that dominate regulated pharmaceutical laboratories. Waters Corporation specializes in ultra-low dispersion fluidics that differentiate its UPLC portfolio for complex bioseparations.
Chromatography instruments are analytical systems that separate, identify, and quantify chemical mixtures by passing mobile phases through stationary-phase columns, typically achieving resolution down to parts-per-billion depending on detector configuration and column length. Their primary purpose spans drug purity verification, environmental contaminant detection, and food adulteration screening across regulated industries. Liquid chromatography systems lead instrument revenue due to their dominance in pharmaceutical analysis and biopharmaceutical quality control, where gradient elution methods handle thermally labile large molecules. Gas chromatography maintains entrenched positions in environmental testing and petrochemical analysis, though its growth trails liquid-based alternatives as biological drug pipelines expand. Ion chromatography occupies a specialized niche in food safety testing and power plant water chemistry, with demand accelerating for trace anion and cation detection in clean energy supply chains.
FDA's Current Good Manufacturing Practice guidelines and EMA's analytical quality-by-design framework compel pharmaceutical manufacturers to validate chromatographic methods with documented robustness across forced-degradation studies. EPA methods 8260 and 8270 for volatile and semivolatile organic compound analysis mandate gas chromatography configurations in environmental monitoring contracts, shaping procurement specifications for municipal laboratories. China's NMPA alignment with ICH Q14 guidelines for analytical procedure development is reshaping instrument qualification requirements for domestic generic drug exporters. Stakeholders must monitor how evolving pharmacopeial standards for oligonucleotide and cell therapy analytics redirect R&D spending toward specialized column chemistries and multi-dimensional separation platforms.
Market Dynamics
Single-use chromatography systems are compressing capital deployment cycles and forcing stainless-steel incumbent vendors to reconfigure service revenue models around consumables.
Growth Catalysts
- FDA purity mandates:Biologics manufacturers face intensified forced-degradation documentation requirements, expanding instrument validation workloads and consumables throughput.
- EMA quality-by-design framework:Analytical procedure lifecycle management protocols compel pharmaceutical laboratories to upgrade method robustness capabilities.
- Cell therapy analytics:Viral vector and CAR-T process development labs require specialized multi-dimensional separation platforms for complex impurity profiling.
Market Restraints
- High-purity solvent costs:Acetonitrile and methanol price volatility compresses operating margins for high-throughput pharmaceutical QC operations.
- Detector supply concentration:Mass spectrometry ion source and time-of-flight component fabrication clusters in Germany and Massachusetts, creating single-source vulnerability.
- Method transfer friction:ICH Q12 lifecycle management guidelines create documentation burdens that delay multi-site deployment timelines.
Strategic Opportunities
- India CDMO expansion:Contract development organizations in Hyderabad and Bengaluru are building dedicated analytical centers for export-oriented generic drug manufacturers.
- Continuous processing convergence:Integrated chromatography-spectroscopy platforms enable real-time release testing for perfusion bioreactor operations.
- China NMPA ICH alignment:Domestic generic exporters must upgrade qualification protocols, opening instrument replacement cycles in Shanghai and Suzhou clusters.
Industry Challenges
- Multi-platform integration complexity:Pharmaceutical laboratories struggle to harmonize data systems across HPLC, UPLC, and mass spectrometry configurations from different vendors.
- Column chemistry standardization delays:Sub-2-micron particle batch consistency issues create method reproducibility failures during inter-laboratory validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chromatography Instruments Market |
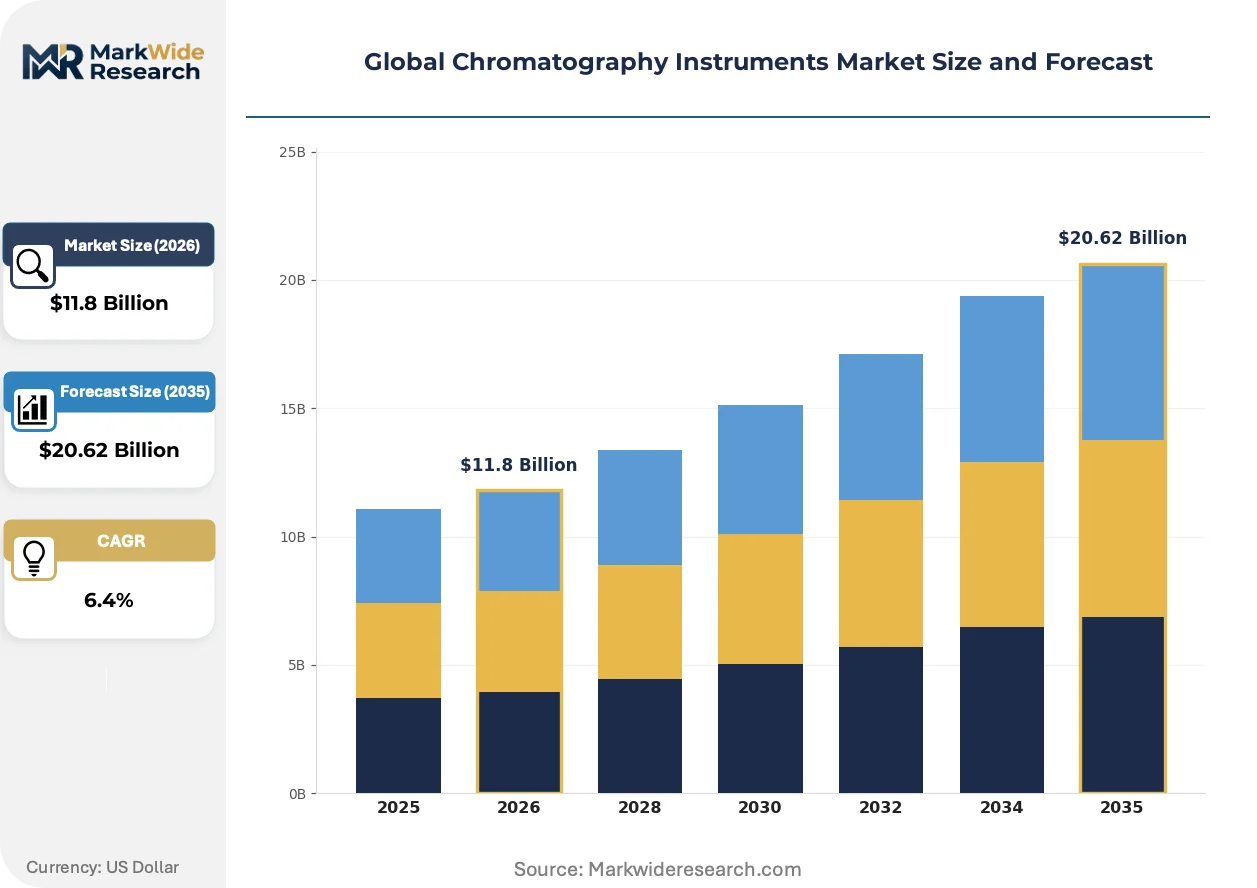
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Chromatography, Liquid Chromatography, Ion Chromatography, Thin Layer Chromatography, Supercritical Fluid Chromatography Technology: High-Performance Liquid Chromatography, Ultrahigh-Performance Liquid Chromatography, Capillary Electrophoresis, Affinity Chromatography, Size Exclusion Chromatography Application: Pharmaceutical Analysis, Food Safety Testing, Environmental Testing, Chemical Analysis, Forensic Investigation End User: Research Institutes, Quality Control Laboratories, Biotechnology Companies, Academic Institutions, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies, Inc., Waters Corporation, Shimadzu Corporation, PerkinElmer, Inc., Merck KGaA, Bio-Rad Laboratories, Inc., Sartorius AG, Restek Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chromatography Instruments Market Shifts & Advancements
Artificial intelligence and cloud-native architectures are penetrating instrument control software, compressing method development timelines and enabling remote diagnostics that reshape service delivery economics.
Machine learning algorithms embedded in chromatography data systems are automating peak integration and impurity identification workflows. Large pharmaceutical manufacturers in Basel and Boston are deploying these tools to reduce analyst intervention in routine QC release testing. The technology is digitizing compliance documentation and shifting labor allocation toward investigative analysis rather than manual data review.
REACH restrictions on per- and polyfluoroalkyl substances are forcing column manufacturers to eliminate fluorinated stationary phases from new product introductions. European environmental monitoring laboratories must validate alternative chemistries for legacy EPA methods 8260 and 8270 applications. German analytical service providers are accelerating qualification of polymer-based sorbents to maintain contract eligibility for municipal water testing programs.
Contract research organizations are unbundling instrument service contracts from capital purchases, opting for usage-based consumables agreements with embedded maintenance. This procurement restructuring concentrates negotiating leverage among multi-site CDMO operators in the United States and Switzerland. The model is most visible in San Diego and Basel clusters where dedicated biologics analytical centers negotiate enterprise-level platform standardization.
Global Chromatography Instruments Market Segmentation
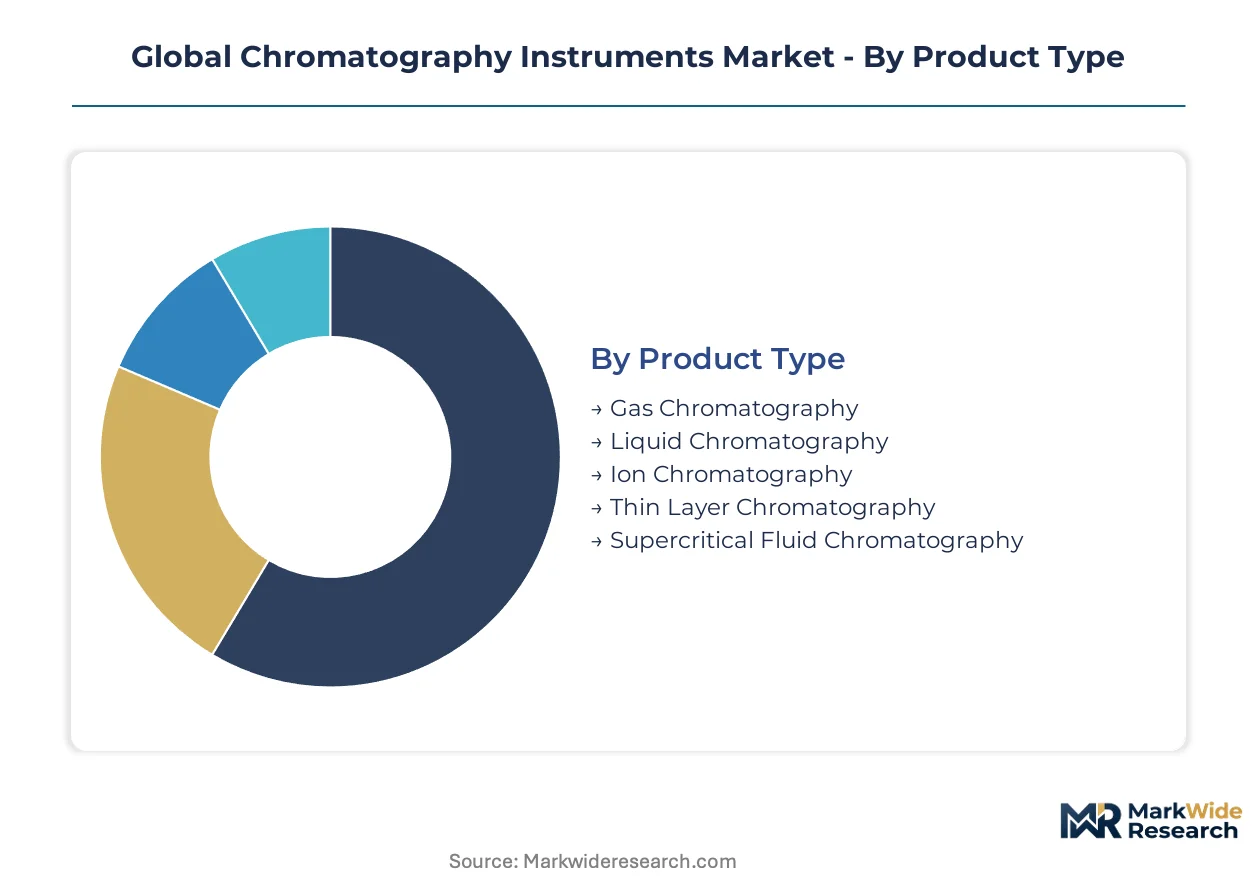
Chromatography instrument segmentation reveals how technology specialization maps onto regulatory complexity and capital deployment cycles. Each dimension—product architecture, separation mechanism, application domain, and customer type—carries distinct procurement patterns and service revenue potential.
Product Type:
Cost tier differentiation separates capital-intensive systems from benchtop configurations with compressed service margins.
- Liquid Chromatography:Gradient elution systems dominate pharmaceutical QC workflows with thermal stability for large-molecule analysis. Biologics manufacturers in Basel and Boston drive consumables throughput as FDA purity mandates intensify forced-degradation documentation.
- Gas Chromatography:Packed and capillary column configurations maintain entrenched positions in environmental monitoring and petrochemical analysis. EPA methods 8260 and 8270 for volatile organic compound detection sustain municipal laboratory procurement in the United States.
- Ion Chromatography:Specialized anion and cation detection systems serve food safety regulators and power plant water chemistry labs.
- Thin Layer Chromatography:Cost-effective qualitative screening tools support academic laboratories and field-based forensic applications.
- Supercritical Fluid Chromatography:CO2-based mobile phase systems address chiral separations in pharmaceutical development.
Liquid Chromatography holds installed capacity. Ion Chromatography is rotating up the share rankings.
Technology:
Application intensity varies by separation speed requirements and regulatory method transfer protocols.
- High-Performance Liquid Chromatography:3-5 micron particle columns with modular detector configurations serve method development laboratories. Generic drug manufacturers in Hyderabad and Shanghai prioritize HPLC platforms for ICH Q14 compliance documentation.
- Ultrahigh-Performance Liquid Chromatography:Sub-2-micron particle systems with ultra-low dispersion fluidics compress analysis timelines for complex bioseparations. CAR-T process development labs in San Diego and Basel deploy UPLC for viral vector impurity profiling.
- Capillary Electrophoresis:Electrokinetic separation methods address nucleic acid and protein charge-variant analysis.
- Affinity Chromatography:Ligand-based purification systems concentrate in monoclonal antibody capture steps.
- Size Exclusion Chromatography:Porous stationary phases quantify aggregate formation in protein stability studies.
HPLC platforms anchor the installed base. UPLC configurations are climbing the fastest as biologics pipelines expand.
Application:
Customer type concentration shapes instrument specification requirements and software compliance features.
- Pharmaceutical Analysis:Method validation and release testing workflows demand 21 CFR Part 11 compliant data systems. EMA quality-by-design frameworks compel European manufacturers to upgrade robustness documentation capabilities.
- Environmental Testing:Trace contaminant detection for water and soil matrices requires standardized EPA and REACH method adherence. German analytical service providers qualify polymer-based sorbents for municipal contract eligibility.
- Food Safety Testing:Mycotoxin and pesticide residue screening drives ion chromatography demand in import inspection laboratories.
- Chemical Analysis:Petrochemical and polymer characterization sustains gas chromatography utilization.
- Forensic Investigation:Toxicology and controlled substance identification prioritizes rapid turnaround over throughput scale.
Pharmaceutical Analysis commands the premium tier. Environmental Testing is gaining share fastest as clean energy supply chains expand.
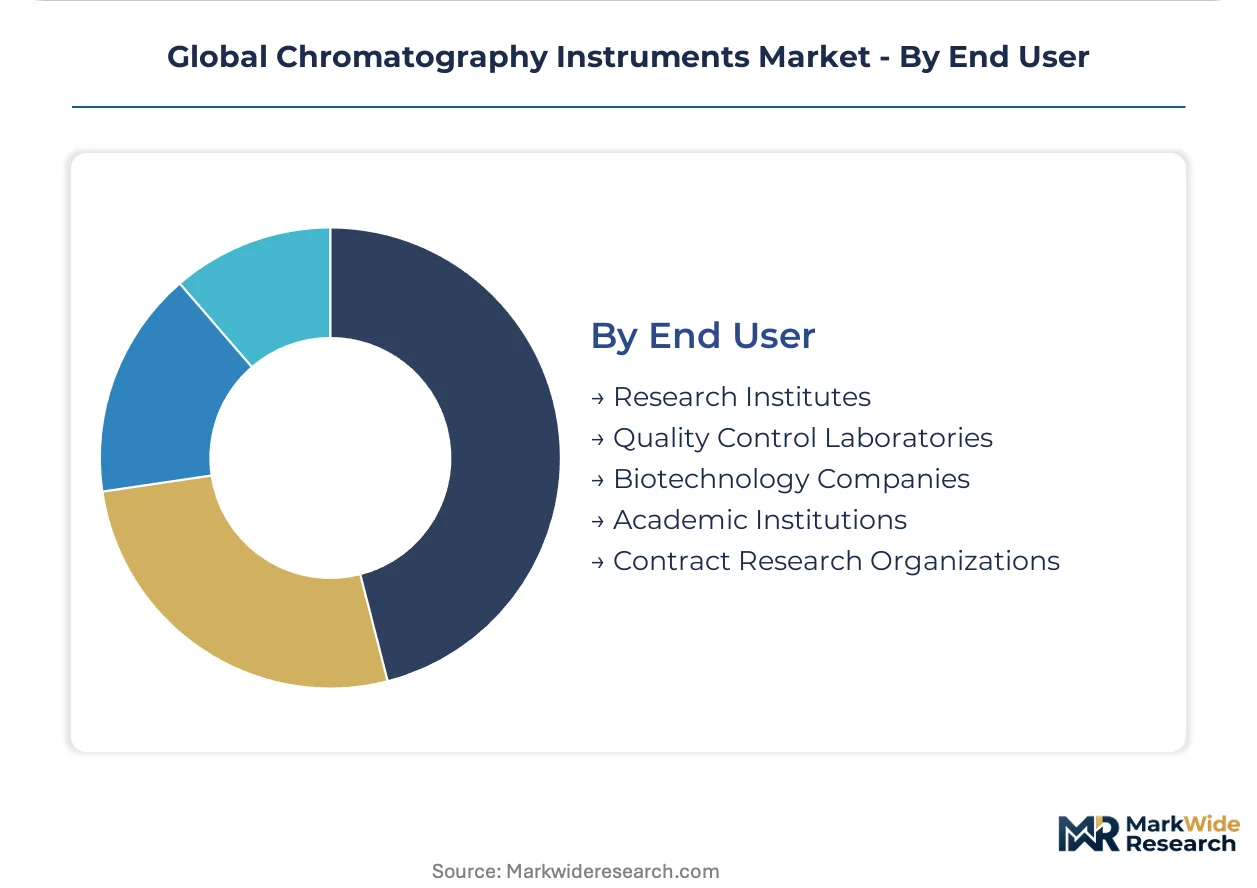
End User:
Volume concentration and procurement autonomy create distinct vendor relationship dynamics across customer categories.
- Contract Research Organizations:Multi-site operators in Switzerland and the United States negotiate enterprise platform standardization with usage-based consumables contracts. CDMO analytical centers in San Diego and Basel unbundle service agreements from capital purchases.
- Quality Control Laboratories:Regulated pharmaceutical manufacturing facilities require validated method transfer protocols and documented instrument qualification. FDA and EMA audit readiness shapes software ecosystem selection.
- Biotechnology Companies:Cell therapy developers in Boston and Basel deploy specialized multi-dimensional platforms for complex impurity profiling.
- Research Institutes:Method innovation priorities favor modular configurations with open architecture.
- Academic Institutions:Training and publication objectives prioritize cost containment over throughput specifications.
Quality Control Laboratories hold installed capacity. Contract Research Organizations are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German analytical instrument manufacturers export chromatography systems to pharmaceutical quality control laboratories across the United States, Switzerland, and China, creating a trade corridor that channels precision engineering into biologics manufacturing hubs.
United States
FDA purity mandates for biologics and biosimilars drive instrument procurement from Boston and San Diego biotech clusters. The agency's Current Good Manufacturing Practice guidelines compel pharmaceutical manufacturers to validate chromatographic methods with documented robustness. Contract research organizations in San Diego negotiate enterprise platform standardization with usage-based consumables contracts.
Germany
EMA's analytical quality-by-design framework reshapes instrument qualification requirements for domestic generic drug exporters. REACH restrictions on per- and polyfluoroalkyl substances force column manufacturers to eliminate fluorinated stationary phases. Analytical service providers in the Rhine-Ruhr region accelerate qualification of polymer-based sorbents for municipal water testing programs.
China
NMPA alignment with ICH Q14 guidelines for analytical procedure development opens instrument replacement cycles in Shanghai and Suzhou clusters. Domestic generic exporters upgrade qualification protocols to maintain access to European and North American markets. Multi-product facilities in the Yangtze River Delta displace stainless-steel setups with single-use chromatography systems.
Switzerland
Swissmedic oversight of biologics manufacturing sustains demand for compliance-ready software ecosystems in Basel pharmaceutical laboratories. Contract development organizations build dedicated analytical centers for export-oriented drug manufacturers. CDMO operators negotiate unbundled service agreements that separate instrument maintenance from capital purchases.
India
CDSCO alignment with international pharmacopeial standards drives instrument procurement from Hyderabad and Bengaluru contract development organizations. Export-oriented generic drug manufacturers invest in dedicated analytical centers to meet FDA and EMA audit requirements. Domestic laboratories prioritize HPLC platforms for ICH Q14 compliance documentation.
Global Chromatography Instruments Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where full-platform vendors anchor regulated pharmaceutical laboratories and modular specialists serve method development environments. The vendor base organizes around three strategic archetypes: integrated analytical platform providers, consumables-centric service operators, and component-specialist technology licensors. Consolidation pressure intensifies as multi-site CDMO operators concentrate negotiating leverage through enterprise procurement agreements. Competitive moves center on consumables contract restructuring and software ecosystem lock-in rather than hardware differentiation alone.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and Agilent Technologies, Inc. exemplify channel-controlling archetypes that anchor regulated pharmaceutical laboratories through compliance-ready software ecosystems. Waters Corporation occupies a position among ultra-low dispersion fluidics specialists that differentiate complex bioseparation portfolios. Shimadzu Corporation represents the scale-driven fabrication segment with broad analytical instrument portfolios spanning multiple separation modalities.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies, Inc. |
| Waters Corporation |
| Shimadzu Corporation |
| PerkinElmer, Inc. |
| Merck KGaA |
| Bio-Rad Laboratories, Inc. |
| Sartorius AG |
| Restek Corporation |
| Others |
Supply & Pricing Matrix
The Rhine-Ruhr to Rotterdam freight corridor channels German precision-engineered chromatography components into pharmaceutical manufacturing hubs, with logistics cost volatility amplifying price differentiation between captive ion source systems and modular alternatives while compressing margins for solvent-dependent operations.
Pricing Analysis
Technology-generation pricing gaps separate sub-2-micron UPLC platforms from 3-5 micron HPLC workhorses and emerging AI-embedded next-gen configurations. Three-tier pricing structure across premium, standard, and economy levels reflects detector sophistication and software compliance certification tiers. Pricing pressure stems from acetonitrile and methanol solvent cost volatility eroding high-throughput QC margins. Academic laboratories exhibit highest price sensitivity, while Basel and Boston biologics manufacturers prioritize validation documentation over capital expenditure.
Supply Chain Analysis
Upstream feedstock concentration for high-purity silica particles and specialized stationary phases centers on Germany, Japan, and the United States. Ion source fabrication for mass spectrometry detectors draws from Massachusetts and Bavarian component clusters. Single-source vulnerability pervades time-of-flight detector assembly. Distribution runs through authorized distributor networks serving pharmaceutical QC laboratories, with direct procurement emerging among multi-site CDMO operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
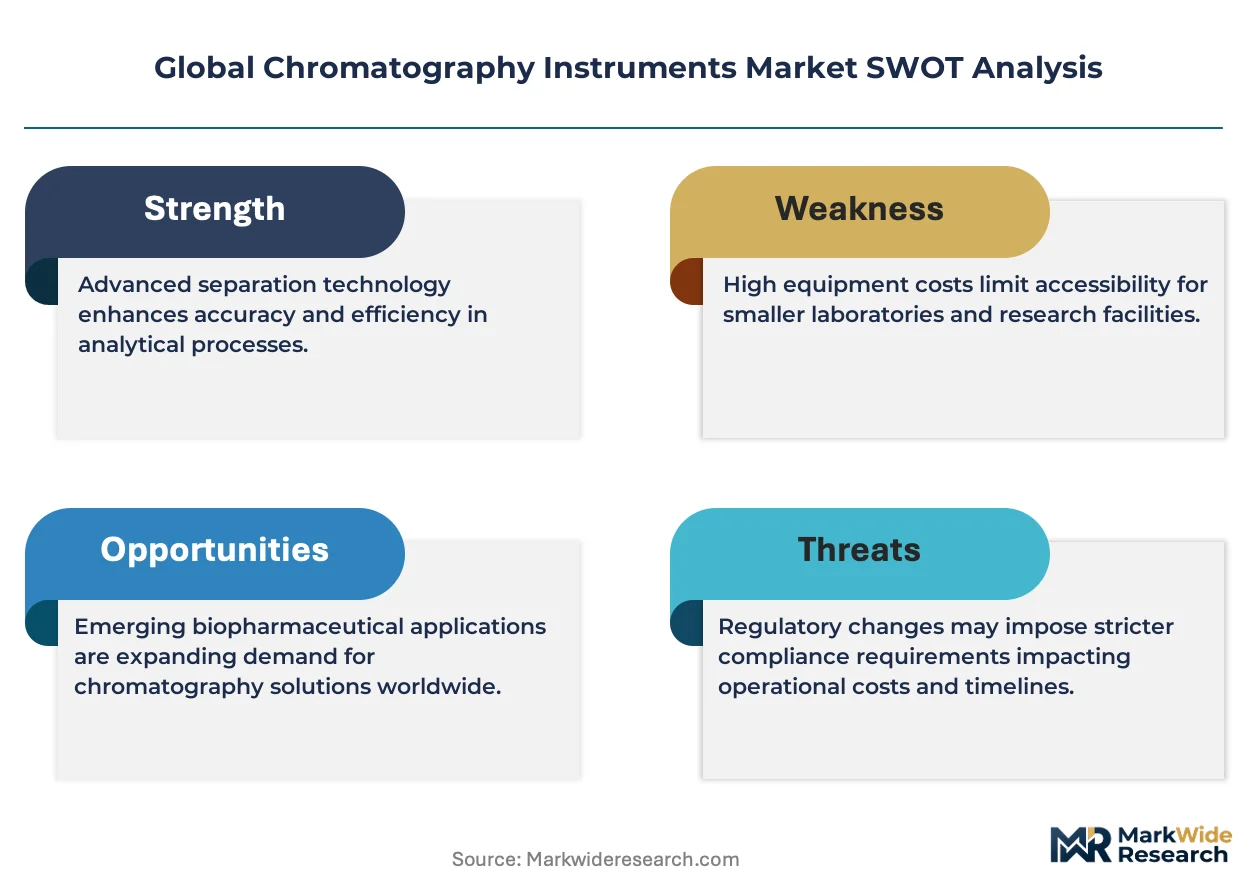
Fragmentation opportunity pervades this market as cell therapy analytics and oligonucleotide quality control create specialized niches beyond incumbent platform dominance.
For Market Incumbents: Build switching-cost moats through compliance-ready software ecosystem lock-in. Deepen captive ion source technology differentiation against modular detector competitors. Expand qualification protocol services to capture NMPA-aligned replacement cycles in Chinese generic drug clusters. For New Entrants and Emerging Players: Establish a beachhead in single-use chromatography consumables for multi-product biologics facilities. Target Hyderabad and Bengaluru CDMO analytical centers with unbundled service agreements. Deploy usage-based procurement models to bypass incumbent capital-sales relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified analytical instrument conglomerates seeking to monetize non-core chromatography divisions. Five-to-ten year viability hinges on consumables recurring revenue ratios exceeding hardware depreciation cycles. Monitor ICH Q14 implementation velocity in Chinese export-oriented laboratories as inflection indicator for instrument replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Consumables Contract Restructuring | Unbundled service agreements shift CDMO procurement toward usage-based models in San Diego clusters. |
| Software Ecosystem Lock-in | Compliance-ready data systems anchor regulated pharmaceutical laboratories against modular competitors. |
| Column Chemistry Diversification | Polymer-based sorbent qualification addresses REACH restrictions on fluorinated stationary phases. |
| Geographic Expansion | Dedicated analytical centers in Hyderabad and Bengaluru capture export-oriented generic drug demand. |
| Platform Integration Investment | Multi-dimensional separation systems serve CAR-T viral vector impurity profiling in Basel laboratories. |
Research Methodology
Cross-validation between primary interviews with instrument qualification specialists and secondary validation through FDA warning letter databases anchors the qualitative findings. Conversations with pharmaceutical QC laboratory directors, regulatory affairs managers at generic drug exporters, CDMO procurement officers, and analytical service provider technical directors inform demand-side dynamics. Bottom-up triangulation against SEC 10-K instrument revenue disclosures and top-down calibration via customs trade data for chromatography component imports complete the validation framework.
Calibration against historical instrument replacement cycles and consumables throughput ratios shapes the projection methodology. Segmentation dimensions span product architecture, separation technology, application domain, and end-user procurement autonomy across the modeling period. CAGRs derive from instrument shipment velocity correlated with regulatory mandate implementation timelines. Oligonucleotide and cell therapy pipeline expansion rates provide biologics-specific demand inputs.
Sensitivities concentrate around NMPA enforcement consistency, REACH restriction scope expansion, and solvent commodity price volatility. Forecasts embody assumptions regarding ICH guideline harmonization velocity and CDMO consolidation trajectories. Cross-checking against EMA analytical quality-by-design audit frequency data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Pellistor Bead Chemical Sensor Market
Testing Equipment
Global Chiral Chromatography Column Market
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
Material Tester Market
Testing Equipment
Global Rheometer and Viscometer Market
Testing Equipment
Materials Testing Equipment Market
Testing Equipment
Flash Point Apparatus Market
Testing Equipment
Global Laboratory Analytical Instruments and Consumables Market
Testing Equipment
Liquid Chromatography Market
Testing Equipment
Chemical Reaction Monitoring Equipment Market
Testing Equipment
Sand Testing Equipments Market
Testing Equipment
Ultrasonic Testing Market
Testing Equipment
Global Host Cell Contaminant Testing Market
Testing Equipment
Chemical Detector Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Supercritical Fluid Chromatography (SFC) System Market