
 Global Biochemical Reagents Market | 2026-2036
Global Biochemical Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biochemical Reagents Market Foresight
The gap between pharmaceutical-grade and general laboratory biochemical reagents is realigning procurement strategies across the value chain. Thermo Fisher Scientific leverages its end-to-end supply platform to dominate high-purity enzyme distribution in North America. Merck KGaA anchors European demand through its deep portfolio of GMP-certified buffers and cell-culture media. Bio-Rad Laboratories differentiates in analytical stains and substrates for quantitative PCR workflows.
Biochemical reagents are purified organic compounds or biological preparations, typically exceeding 98 percent purity for analytical applications, that catalyze, detect, or stabilize molecular reactions in laboratory and manufacturing settings. Their primary commercial purpose is to enable reproducible measurement and manipulation of biological systems across drug discovery, clinical diagnostics, and agricultural biotechnology. Enzymes command the largest revenue share among product types because proteases and polymerases remain irreplaceable in nucleic-acid amplification workflows. Pharmaceutical Research absorbs the majority of application-specific spending as biologics pipelines expand, while Contract Research Organizations represent the fastest-growing end-user channel due to outsourced validation demands.
FDA guidance on in vitro diagnostic analytical performance, EU REACH restrictions on hazardous solvent classifications, and China's NMPA biologics testing standards collectively elevate compliance costs for reagent suppliers seeking multi-regional market access. These frameworks force manufacturers to maintain parallel certification streams and region-specific documentation. Stakeholders must monitor how tightening purity specifications in major jurisdictions reshape supplier qualification timelines and inventory pooling strategies.
Market Dynamics
CRISPR-based gene-editing workflows are compressing supplier qualification timelines as pharmaceutical manufacturers demand enzyme batches with documented traceability from fermentation to final formulation.
Growth Catalysts
- Precision medicine mandates:The FDA's updated guidance on analytical method validation tightens purity thresholds for diagnostic reagents, forcing manufacturers to upgrade purification infrastructure and expand high-grade inventory.
- Cell-culture scale-up:Biopharma companies expanding biologics manufacturing are locking in multi-year enzyme supply contracts with documented absence of animal-derived components.
- China NMPA biologics testing standards:China's regulatory alignment with ICH Q5D guidelines accelerates demand for GMP-certified cell-culture media in domestic CDMO facilities.
Market Restraints
- Raw material concentration:Fermentation-grade yeast extract and recombinant protein expression systems depend on a narrow supplier base concentrated in Germany and the United States.
- EU REACH solvent restrictions:Reclassification of acetonitrile and dimethyl sulfoxide under hazardous substance frameworks elevates compliance costs for chromatography-grade solvent manufacturers.
- Biologic stability limitations:Temperature-sensitive enzymes and antibodies require cold-chain logistics that constrain distribution reach into ambient-storage markets.
Strategic Opportunities
- India's PLI scheme for biopharma:Production-linked incentives for active pharmaceutical ingredients extend to fermentation-derived enzymes, attracting contract manufacturing investment to Maharashtra and Telangana clusters.
- AI-driven formulation design:Machine learning platforms predicting protein stability are converging with automated high-throughput screening to compress reagent development cycles.
- Direct-to-laboratory distribution:E-procurement platforms bypass traditional distributor markups for academic and CRO buyers in Brazil and South Korea.
Industry Challenges
- GMP certification timelines:FDA and EMA facility inspections for enzyme manufacturing sites face 18-24 month backlogs, delaying market entry for new production capacity.
- Cross-contamination protocols:Multi-product facilities struggle to validate cleaning procedures between animal-derived and animal-free enzyme campaigns without extended downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biochemical Reagents Market |
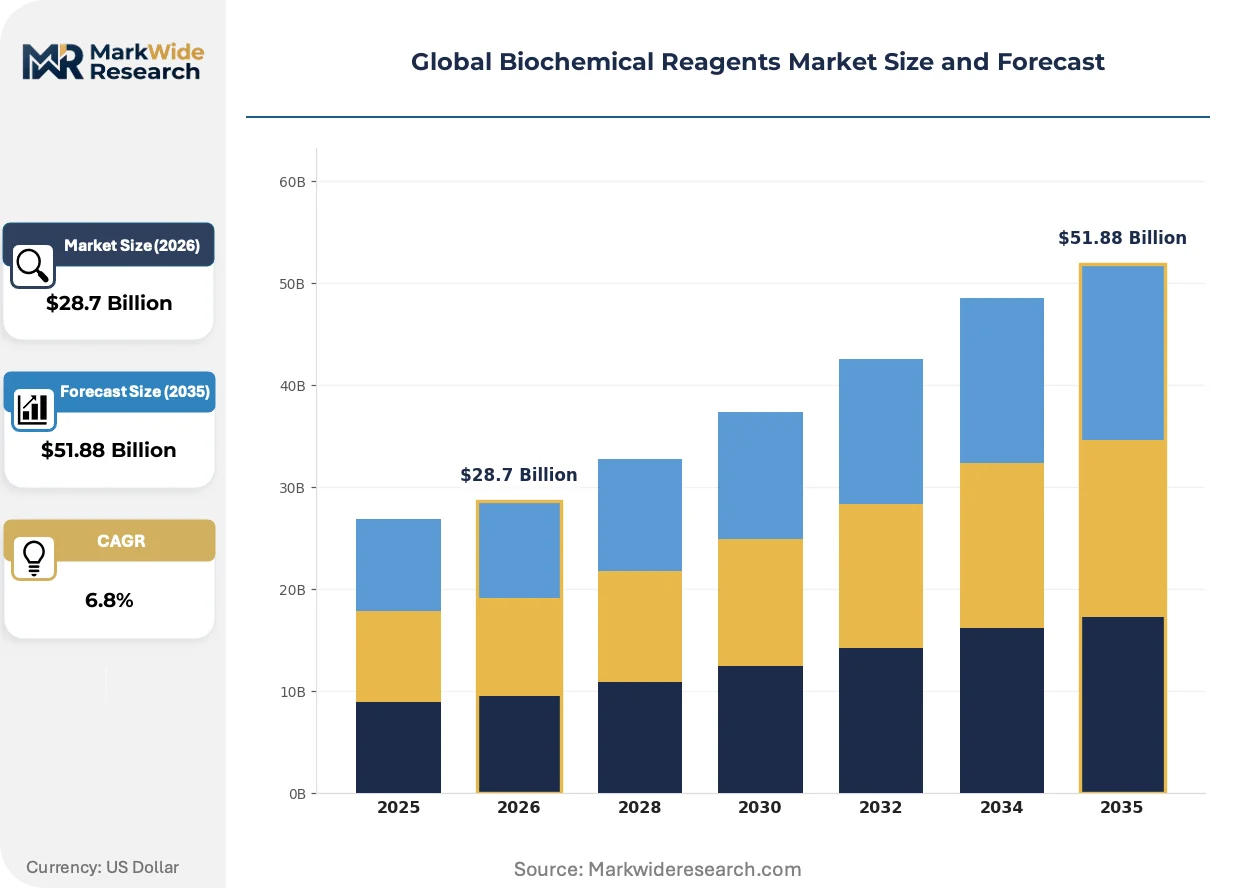
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Buffers, Stains, Substrates, Solvents Application: Pharmaceutical Research, Food Analysis, Environmental Testing, Biotechnology, Academic Research End User: Contract Research Organizations, Diagnostic Firms, Agricultural Labs, Biopharma Companies, Academic Institutions Packaging Type: Vials, Bottles, Ampoules, Sachets, Bulk Containers |
| Companies Covered | Bio-Rad Laboratories, QIAGEN N.V., Thermo Fisher Scientific, Becton, Dickinson and Company, Danaher Corporation, Merck KGaA, Agilent Technologies, Promega Corporation, F. Hoffmann-La Roche AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biochemical Reagents Market Shifts & Advancements
Synthetic biology platforms and closed-system manufacturing are collapsing the traditional separation between R&D-grade and GMP-grade reagent production, erasing historical purity-tier premiums.
Lyophilized enzyme formulations are overtaking liquid concentrates in CRISPR workflows by eliminating cold-chain dependency during international shipment. CDMOs in Singapore and Switzerland are converting liquid inventory to dry-powder formats to serve distributed biomanufacturing networks. This shift compresses working capital requirements for buyers while extending shelf stability from months to years.
ECHA's 2023 update to REACH Annex XVII restricts per- and polyfluoroalkyl substances in laboratory consumables, forcing reagent suppliers to reformulate surfactant-stabilized enzyme preparations. Manufacturers serving European diagnostic markets are accelerating substitution programs for fluorinated compounds in PCR master mixes. The transition elevates R&D spending for reformulation but opens first-mover positioning for PFAS-free certification.
Consolidated procurement by top-twenty pharmaceutical buyers is compressing supplier margins through volume-commitment contracts with penalty clauses for batch-to-batch variability. Tier-one biopharma companies in Massachusetts and Basel are unbundling reagent supply from equipment service agreements, forcing standalone reagent vendors to document analytical performance independently. This behavioral shift is most visible in nucleic-acid extraction kit purchasing, where buyers now separate consumables from platform instrumentation decisions.
Global Biochemical Reagents Market Segmentation
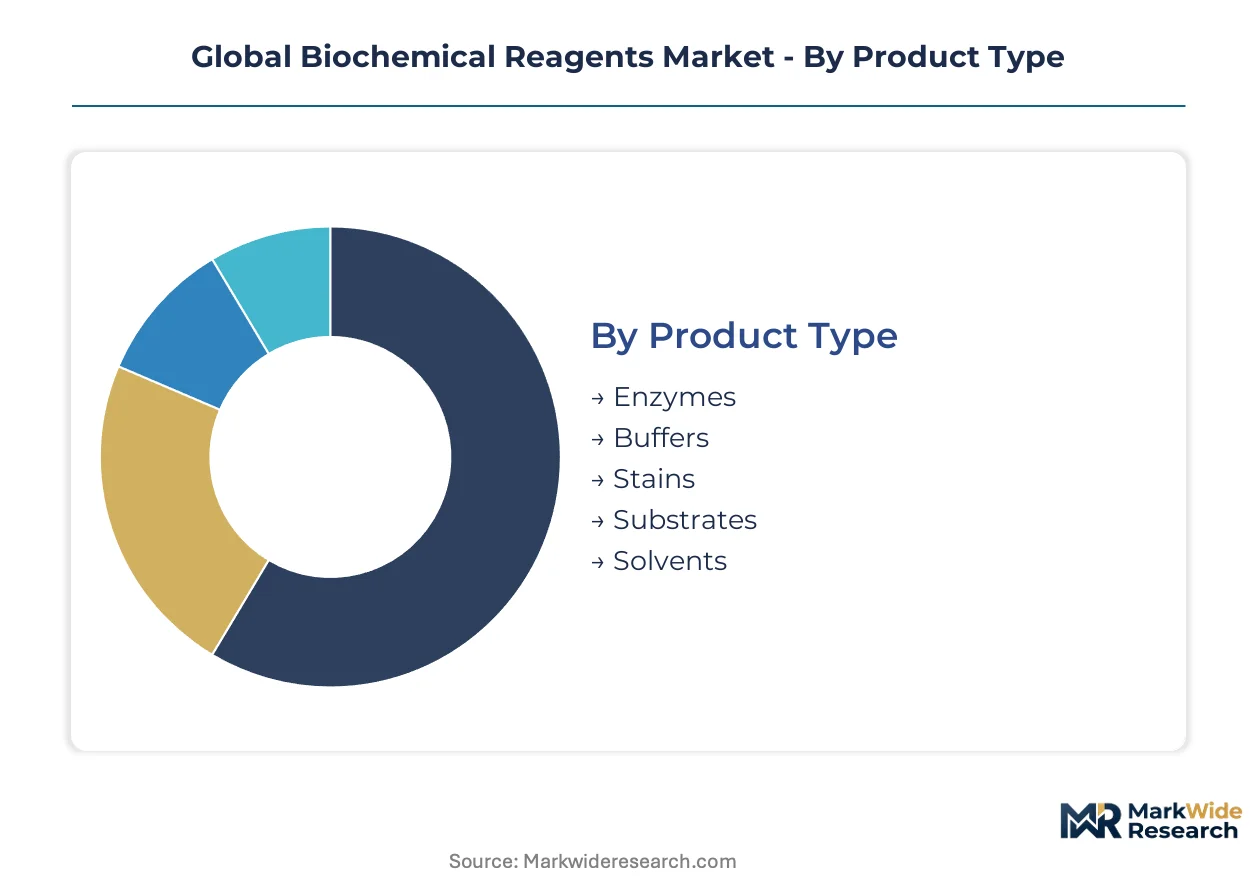
Biochemical reagents fragment across four structural dimensions that determine pricing power, regulatory burden, and distribution economics. Each category carries distinct certification requirements that reshape supplier qualification timelines and inventory pooling strategies for buyers.
Product Type:
FDA analytical method validation and EU REACH solvent classifications impose tiered compliance costs across this category, with fermentation-derived segments facing the heaviest documentation burdens.
- Enzymes:Proteases and polymerases catalyze nucleic-acid amplification workflows with documented traceability from fermentation to final formulation. Demand concentrates in United States and China as CRISPR-based research scales, with biopharma manufacturers locking in multi-year supply contracts. Enzymes sit at the top of the volume ranking, with substrates climbing the fastest.
- Buffers:GMP-certified pH-stabilizing solutions maintain cell-culture media integrity across biologics manufacturing campaigns. European CDMO facilities in Germany and Switzerland anchor demand as EMA facility inspection backlogs extend qualification timelines.
- Stains:Analytical dyes enable quantitative PCR and electrophoresis visualization with spectral specificity requirements.
- Substrates:Chromogenic and fluorogenic compounds signal enzymatic activity in diagnostic assay development.
- Solvents:Chromatography-grade acetonitrile and dimethyl sulfoxide face ECHA reclassification under hazardous substance frameworks.
Margin structures diverge sharply between animal-derived and animal-free enzyme campaigns, with cross-contamination protocols extending downtime in multi-product facilities.
Application:
End-use concentration determines whether reagents ship under ambient or cold-chain conditions, with temperature-sensitive segments commanding premium logistics infrastructure.
- Pharmaceutical Research:Biologics pipelines absorb the majority of application-specific spending as manufacturers scale antibody and cell-therapy production. United States and China precision medicine programs drive enzyme procurement with purity thresholds exceeding 98 percent for analytical applications.
- Biotechnology:Synthetic biology platforms collapse traditional separation between R&D-grade and GMP-grade production, compressing historical purity-tier premiums. Singapore and Switzerland CDMOs convert liquid inventory to lyophilized formats for distributed networks.
- Food Analysis:Pathogen detection and allergen quantification require ISO-certified reagent batches with lot-to-lot consistency documentation.
- Environmental Testing:Water and soil contaminant assays utilize enzyme-linked immunosorbent reagents with regulatory method compliance.
- Academic Research:Budget-constrained laboratories in Brazil and South Korea bypass distributor markups through e-procurement platforms.
Pharmaceutical Research commands the largest revenue share, with Biotechnology expanding most quickly as synthetic biology manufacturing matures.
End User:
Procurement sophistication varies from consolidated volume-commitment contracts with penalty clauses to fragmented spot purchasing through digital marketplaces.
- Contract Research Organizations:Outsourced validation demands make CROs the fastest-growing channel as biopharma companies externalize analytical method development. India PLI scheme incentives attract fermentation-derived enzyme manufacturing to Maharashtra and Telangana clusters.
- Biopharma Companies:Tier-one manufacturers in Massachusetts and Basel unbundle reagent supply from equipment service agreements, forcing standalone vendors to document performance independently.
- Diagnostic Firms:FDA in vitro diagnostic analytical performance guidance tightens purity specifications for assay components.
- Agricultural Labs:GMO detection and crop pathogen screening utilize PCR master mixes with PFAS-free surfactant reformulations for European markets.
- Academic Institutions:Grant-funded researchers prioritize cost efficiency over GMP certification for exploratory workflows.
Biopharma Companies retain the highest absolute spending, with Contract Research Organizations gaining share fastest through outsourced pipeline expansion.
Packaging Type:
Format selection balances shelf stability, cold-chain dependency, and working capital compression across international distribution networks.
- Bulk Containers:Industrial-scale fermentation facilities in Germany and United States receive tanker shipments of chromatography solvents and buffer concentrates. ECHA REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force surfactant-stabilized preparation reformulations.
- Vials:Single-use enzyme aliquots eliminate cross-contamination risk in multi-product analytical laboratories. Lyophilized formulations in vial format extend shelf stability from months to years while eliminating cold-chain dependency.
- Bottles:Reagent reservoirs for high-throughput screening platforms require inert gas headspace for oxygen-sensitive compounds.
- Ampoules:Hermetically sealed glass containers preserve sterility for cell-culture media applications.
- Sachets:Pre-measured powder formats simplify field-based environmental testing workflows.
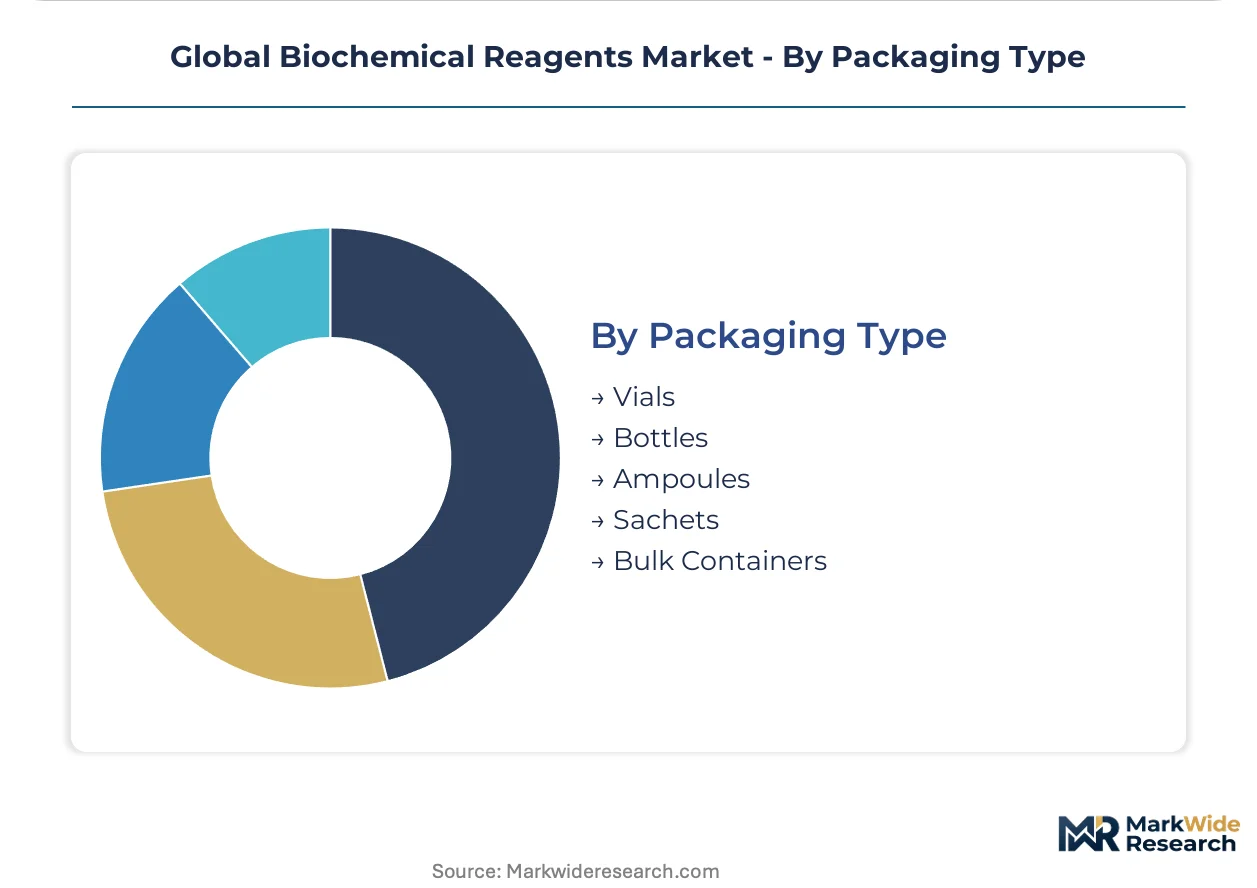
Bulk Containers dominate procurement tonnage, with vials showing the steepest expansion trajectory as lyophilization replaces liquid concentrates in international shipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PhD-level molecular biologists and fermentation specialists cluster in Massachusetts, Basel, and Shanghai, anchoring demand for GMP-certified enzymes and traceable reagent supply chains across three continents.
United States
CRISPR-based research programs at MIT and Harvard Medical School drive enzyme procurement with documented fermentation-to-formulation traceability. FDA's updated analytical method validation guidance tightens purity thresholds for diagnostic reagents used in precision medicine workflows. Greater Boston biopharma manufacturers lock in multi-year supply contracts for animal-free proteases and polymerases.
Germany
EMA facility inspection backlogs extending 18-24 months delay qualification timelines for new enzyme manufacturing capacity entering European markets. ECHA REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force reformulation of surfactant-stabilized PCR master mixes. Baden-Württemberg CDMO facilities anchor continental demand for GMP-certified cell-culture media.
China
NMPA biologics testing standards aligned with ICH Q5D guidelines accelerate demand for GMP-certified reagents in domestic contract manufacturing. Shanghai and Suzhou precision medicine programs scale CRISPR workflows requiring high-purity enzymes exceeding 98 percent analytical grade. Yangtze River Delta biologics pipelines absorb majority of regional application-specific spending.
Switzerland
Swissmedic facility certifications enable Basel-based manufacturers to serve EU and US markets with unified documentation streams. Lyophilized enzyme conversion programs in Zurich and Geneva eliminate cold-chain dependency for distributed biomanufacturing networks. Swiss CDMOs compress working capital requirements for international buyers through dry-powder formulation expertise.
India
PLI scheme production-linked incentives for active pharmaceutical ingredients extend to fermentation-derived enzymes, attracting contract manufacturing investment. CDSCO regulatory alignment with ICH guidelines supports Maharashtra and Telangana cluster development for biopharma reagent supply. Outsourced validation demands from Western biopharma companies position Indian CROs as fastest-growing end-user channel.
Global Biochemical Reagents Market Competitive Landscape
Top-tier vendors anchor high-purity enzyme distribution and GMP-certified buffer supply, while mid-scale specialists occupy analytical stains and substrate niches. The vendor base stratifies across three tiers: integrated life science conglomerates with end-to-end supply platforms, regional fermentation specialists with documented traceability protocols, and niche substrate developers serving quantitative PCR workflows. Consolidated procurement by top-twenty pharmaceutical buyers compresses margins through volume-commitment contracts with batch-to-batch variability penalties. Strategic moves center on lyophilization capacity expansion and PFAS-free reformulation programs for European regulatory compliance.
Among US-based integrated suppliers, Thermo Fisher Scientific and Bio-Rad Laboratories occupy positions representing end-to-end platform dominance and analytical workflow specialization respectively. Merck KGaA anchors European supply through its German corporate structure. These three entities exemplify the competitive archetypes shaping procurement behavior: platform-integrated conglomerates unbundling reagent supply from equipment agreements, and standalone vendors documenting independent analytical performance for nucleic-acid extraction kit purchasing decisions.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| QIAGEN N.V. |
| Thermo Fisher Scientific |
| Becton, Dickinson and Company |
| Danaher Corporation |
| Merck KGaA |
| Agilent Technologies |
| Promega Corporation |
| F. Hoffmann-La Roche AG |
| Others |
Supply & Pricing Matrix
ECHA's REACH Annex XVII restrictions on per- and polyfluoroalkyl substances gate both qualified supply and premium-tier pricing access for surfactant-stabilized enzyme preparations, forcing manufacturers to absorb reformulation costs or forfeit European diagnostic markets to PFAS-certified competitors.
Pricing Analysis
The bundled-vs-unbundled service split between reagent supply and equipment service agreements is compressing standalone vendor margins as tier-one biopharma manufacturers in Massachusetts and Basel separate consumables from platform instrumentation decisions. Three-tier pricing structure across GMP-certified, analytical-grade, and research-grade levels reflects certification burden and documented traceability from fermentation to final formulation. Cost compression in research-grade tiers is intensifying because academic buyers in Brazil and South Korea bypass distributor markups through e-procurement platforms. Contract Research Organizations exhibit highest price sensitivity due to grant-funded budget constraints, while biopharma manufacturers prioritize batch-to-batch consistency over unit cost.
Supply Chain Analysis
Certification and qualification gating through FDA and EMA facility inspections creates 18-24 month backlogs that delay market entry for new enzyme manufacturing capacity. Geographic supply concentrates in Germany, the United States, and China, with fermentation-grade yeast extract and recombinant protein expression systems drawing from a narrow supplier base anchored in Baden-Württemberg and Massachusetts clusters. Single-source vulnerability in cold-chain logistics for temperature-sensitive enzymes constrains distribution reach into ambient-storage markets. Distribution runs through integrated life science conglomerates with end-to-end supply platforms, regional fermentation specialists with documented traceability protocols, and niche substrate developers serving quantitative PCR workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Biochemical Reagents Market functions as a geographic-arbitrage play where India's PLI scheme production-linked incentives for fermentation-derived enzymes attract contract manufacturing investment at cost structures 30-40% below German and United States equivalents.
For Market Incumbents: Anchor GMP-certified capacity in Switzerland and Singapore to serve EU and US markets with unified documentation streams, compressing supplier qualification timelines for pharmaceutical buyers. Invest in lyophilization capacity expansion to eliminate cold-chain dependency and extend shelf stability from months to years. Defend against PFAS-free reformulation mandates by accelerating substitution programs ahead of ECHA enforcement timelines, securing first-mover positioning in European diagnostic markets. For New Entrants and Emerging Players: Direct-to-laboratory e-procurement platforms offer the most penetrable route to bypass traditional distributor markups and capture academic and CRO buyers in Brazil, South Korea, and India. Target animal-free enzyme campaigns for biopharma manufacturers scaling cell-culture applications, as cross-contamination protocols in multi-product facilities extend downtime for animal-derived campaigns. Pursue white-label supply agreements with CDMOs in Maharashtra and Telangana clusters to leverage PLI scheme incentives and establish fermentation traceability credentials. For Investors and Strategic Acquirers: Roll-up economics work for regional fermentation specialists with documented ICH Q5D-aligned traceability protocols because EMA and FDA facility inspection backlogs create scarcity value for qualified manufacturing assets. Mid-scale substrate developers serving quantitative PCR workflows represent attractive acquisition targets as consolidated procurement by top-twenty pharmaceutical buyers compresses standalone vendor margins. Watch for inflection in lyophilized enzyme adoption rates as CDMOs in Singapore and Switzerland convert liquid inventory to dry-powder formats for distributed biomanufacturing networks.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Dry-powder enzyme formats eliminate cold-chain dependency for CRISPR workflows across distributed networks. |
| PFAS-Free Reformulation Program | ECHA REACH Annex XVII compliance secures European diagnostic market access ahead of enforcement deadlines. |
| Multi-Year Supply Contracting | Documented animal-free protease traceability locks in biopharma cell-culture scale-up demand. |
| Direct-to-Laboratory E-Procurement | Digital platforms bypass distributor markups for academic and CRO buyers in price-sensitive geographies. |
| CDSCO Regulatory Alignment Investment | ICH Q5D-compliant documentation streams qualify Indian CDMO facilities for Western biopharma outsourcing. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study, combining primary interviews with fermentation specialists, regulatory affairs leads at reagent manufacturers, procurement managers at biopharma companies, and CDMO operations directors with secondary validation against FDA guidance documents, ECHA REACH Annex XVII updates, NMPA biologics testing standards, and customs trade data for chromatography-grade solvents.
Input-output matrices map reagent consumption across pharmaceutical research, biotechnology, food analysis, environmental testing, and academic research applications, with segmentation dimensions including product type, purity grade tier, packaging format, and regional regulatory cluster. CAGRs derive from trend extrapolation of enzyme procurement volumes, biologics pipeline expansion rates, and CRISPR workflow adoption curves across the projection horizon, with specific weighting for GMP certification timelines and cold-chain logistics constraints.
The model assumes a particular technology adoption path for synthetic biology platforms and closed-system manufacturing; alternative pathways for AI-driven protein stability prediction would alter the outlook for reagent development cycle compression and lyophilization adoption rates. Forecasts reflect assumptions about regulatory alignment timelines, inspection backlog resolution, and PFAS substitution progress that could revise projections upon material shifts in ECHA enforcement posture or FDA analytical method validation updates. A model refresh is warranted upon material change in biopharma outsourcing patterns or CDSCO regulatory harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Reagent Bottle Market
Chemical Intermediates
Preformulation Intermediates Market
Chemical Intermediates
Carboxylic Acid Chlorides Market
Chemical Intermediates
Metal Alkyls Market
Chemical Intermediates
Elemental Formula Market
Chemical Intermediates
Cytosine Market
Chemical Intermediates
Acetoacetanilide Market
Chemical Intermediates
US Acids Market
Chemical Intermediates
Refinery Process Chemicals Market
Chemical Intermediates
Potential Hydrogen (Ph) Adjusters Market
Chemical Intermediates
Hydroxyisobutyric Acid Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Potassium Benzoate Market
Chemical Intermediates
Tertiary Amines Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market