
 Roofing Chemical Market | 2026-2036
Roofing Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
Roofing Chemical Market Intelligence
Commercial building applications is consolidating as the dominant end-use vertical, pulling ahead of residential construction across North America and Western Europe. GAF Materials Corporation leverages its manufacturing scale to dominate asphalt-based roofing systems for this segment. Owens Corning anchors its position through fiberglass insulation integration with chemical roofing substrates. Sika AG specializes in polyurethane liquid-applied membranes that compete aggressively on commercial flat-roof refurbishment projects.
Roofing chemicals encompass protective and functional formulations including acrylic coatings, silicone sealants, polyurethane adhesives, bitumen membranes, and elastomeric primers designed to extend roof service life, improve thermal performance, and prevent water ingress. These materials typically achieve elongation rates of 200-800% and solar reflectance indices exceeding 29 to qualify for cool-roof certification programs. Waterproofing membranes lead product-type revenue due to their irreplaceable role in below-grade and flat-roof applications where structural failure carries catastrophic cost. Acrylic technology dominates new construction for its balance of cost and UV stability, while silicone coatings represent the fastest-growing technology segment driven by ponding-water resistance demands in humid climates. Roofing contractors remain the primary end-user channel, though building maintenance providers are expanding procurement share as predictive maintenance models replace reactive repair cycles.
EPA ENERGY STAR certification requirements, the EU Green Deal's building renovation targets, and China's GB standards for green building materials collectively elevate performance thresholds for reflective and low-VOC roofing formulations. REACH compliance in Europe and state-level Title 24 regulations in California restrict solvent-based chemistries while accelerating waterborne and high-solids alternatives. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and embodied-carbon disclosure rules reshape material sourcing decisions and supplier qualification criteria across major construction markets.
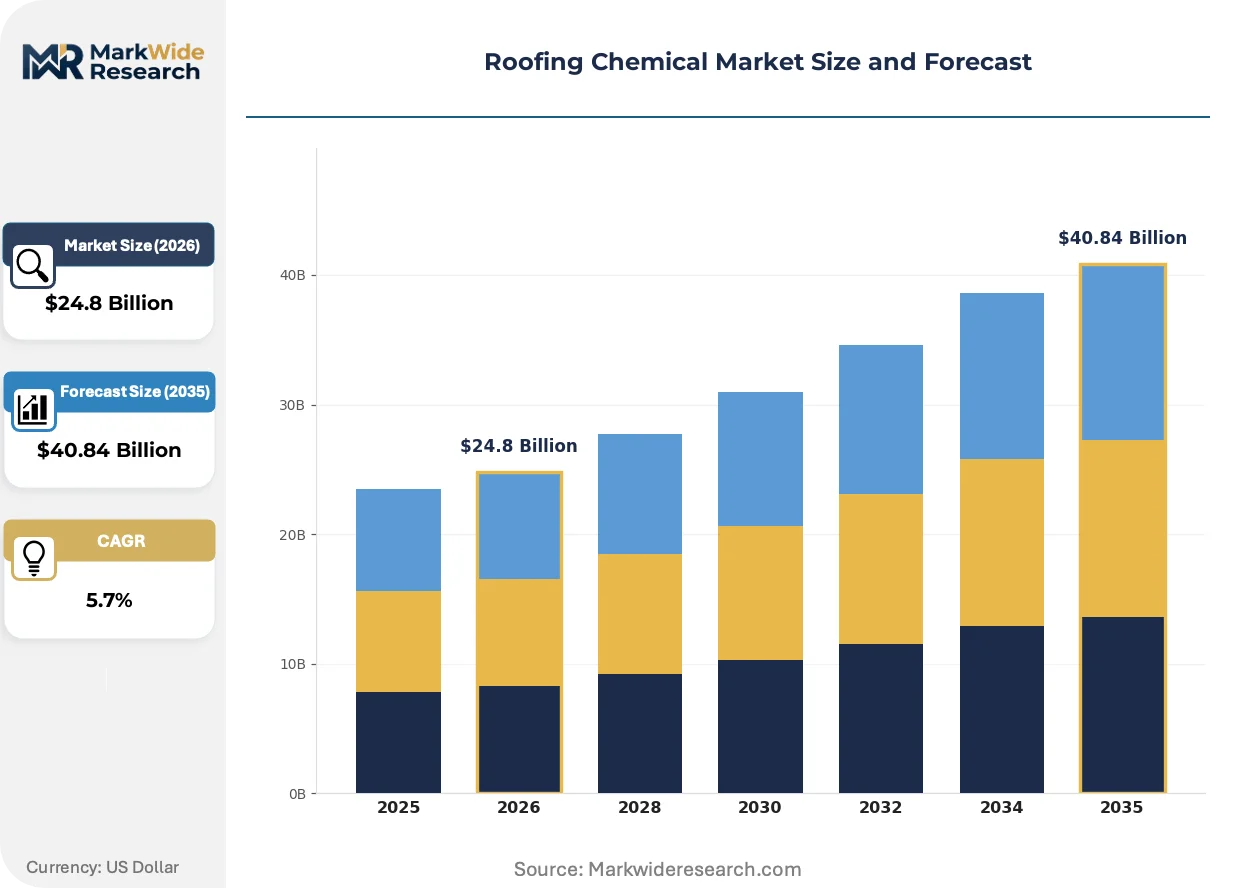
Market Dynamics
Cool roof coating specifications are hardening across multiple jurisdictions simultaneously, forcing reformulation investments and compressing margins for suppliers unable to meet reflectivity and VOC thresholds. Building code convergence between the EPA's ENERGY STAR program, California's Title 24, and the EU Green Deal is eliminating regional product variance as a competitive strategy.
Growth Catalysts
- EU Green Deal building renovation targets:Mandatory energy performance upgrades across commercial building stock are accelerating flat-roof refurbishment cycles and specification of high-reflectance membranes.
- Silicone coating chemistry:Superior ponding-water resistance in humid climates is displacing acrylic systems on low-slope commercial applications where standing water previously caused premature failure.
- China's GB standards for green building materials:National certification requirements for public construction projects are creating specification pull for low-VOC, high-solids roofing formulations.
Market Restraints
- Bitumen feedstock volatility:Asphalt-based membrane producers face margin compression from crude-derived binder cost swings that cannot be fully passed through in competitive bidding environments.
- REACH compliance burden:European formulators must maintain extensive substance registration dossiers and substitution plans for legacy plasticizers and biocides, elevating fixed compliance costs.
- Single-ply membrane substitution:TPO and PVC sheet systems are capturing share in new commercial construction by offering faster installation and lower labor content than liquid-applied alternatives.
Strategic Opportunities
- India's commercial real estate expansion:Metro corridor development in Bangalore, Hyderabad, and Mumbai is generating specification demand for polyurethane liquid membranes in high-rise construction.
- Predictive maintenance service integration:Roofing contractors are bundling IoT-enabled moisture detection with coating warranties, creating recurring revenue streams beyond material supply.
- Japan's METI energy efficiency incentives:Subsidized cool roof retrofits for existing commercial buildings are opening refurbishment channels previously dominated by reactive repair.
Industry Challenges
- Applicator certification bottlenecks:Polyurethane foam and silicone coating systems require manufacturer-trained installation crews, constraining capacity expansion in fragmented contractor markets.
- Embodied carbon disclosure gaps:Suppliers lack standardized lifecycle data for EPD submissions demanded by LEED v4.1 and BREEAM assessors, delaying qualification for premium projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roofing Chemical Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.84 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roof Coatings, Sealants, Adhesives, Waterproofing Membranes, Primers Application: Commercial Buildings, Residential Constructions, Industrial Facilities, Infrastructure Projects, Institutional Buildings Technology: Acrylic, Silicone, Polyurethane, Bitumen, Elastomeric End User: Roofing Contractors, Construction Companies, Building Maintenance Providers, Industrial Operators |
| Companies Covered | BASF SE, The Dow Chemical Company, GAF Materials Corporation, Sika AG, Owens Corning, Akzo Nobel N.V., Carlisle Companies Inc., Johns Manville, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roofing Chemical Market Strategic Shifts & Innovations
Reformulation priorities are pivoting from performance-only specifications toward dual-criteria optimization where thermal reflectance and embodied carbon compete for R&D investment. Manufacturers must now optimize across conflicting performance matrices rather than single-attribute leadership.
Self-healing polymer additives embedded in acrylic and polyurethane coatings are decentralizing maintenance responsibility from reactive contractor dispatch to autonomous material response. Commercial property managers in Florida and Singapore are piloting these systems on high-value data center roofs where access constraints magnify repair costs. The technology is decentralizing service revenue models by compressing the frequency of scheduled inspections and interventions.
California's Title 24 Part 6 cool roof mandates have tightened minimum aged solar reflectance thresholds, forcing suppliers to accelerate UV-stable pigment development and accelerated weathering validation protocols. Formulators serving the US West Coast now maintain separate product lines from Gulf Coast specifications, fragmenting production runs and elevating SKU complexity. The regulation is reshaping regional manufacturing footprints as suppliers site blending capacity closer to California distribution nodes.
Building maintenance providers are displacing traditional roofing contractors as the primary specification gatekeeper through multi-year facility management contracts that bundle coating refresh cycles with HVAC and envelope services. This channel consolidation is most visible in US healthcare and education verticals where capital project budgets have flattened and operational expenditure models dominate procurement. The shift compresses supplier sales cycles but demands price transparency across extended contract horizons.
Roofing Chemical Market Segmentation
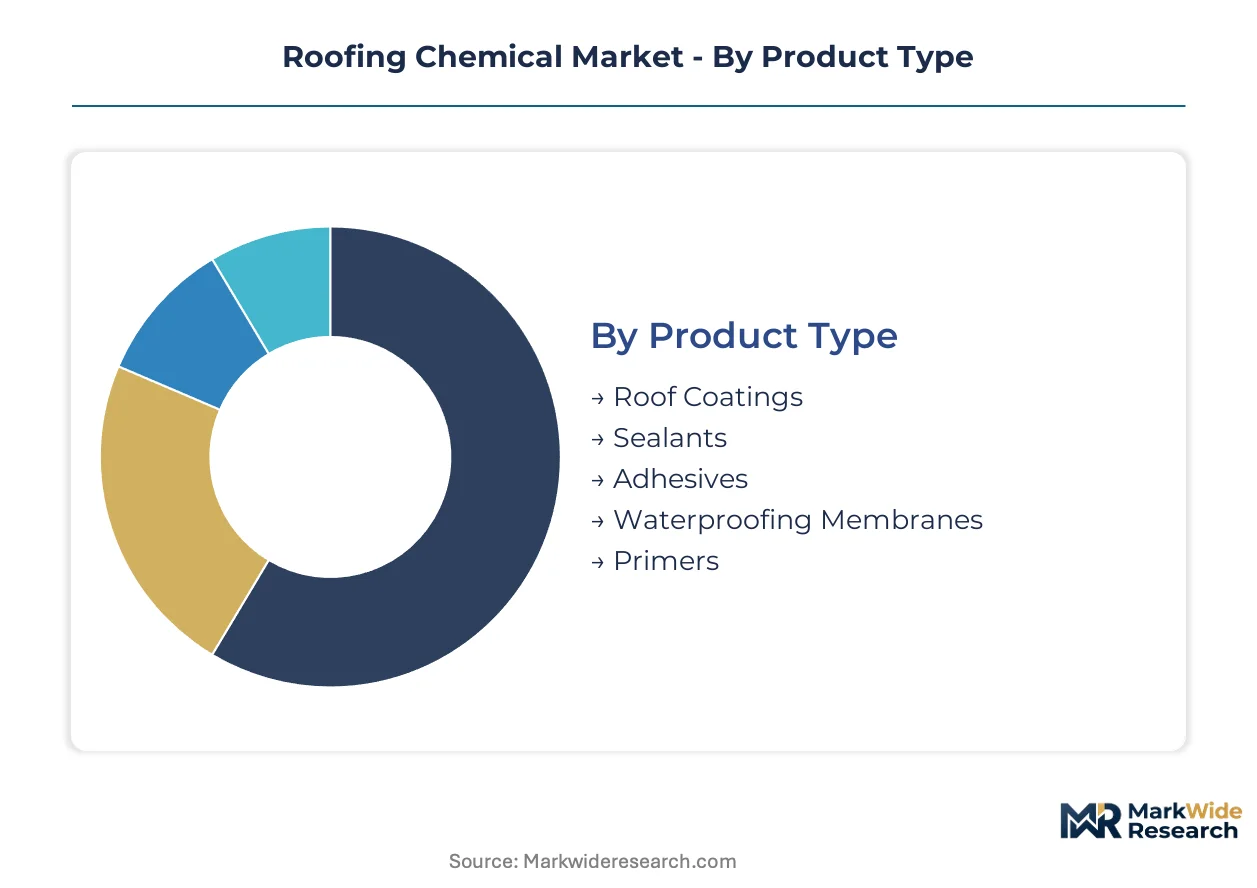
Roofing chemical segmentation reveals divergent capital requirements across formulation types and end-use channels. Product specifications vary sharply between new construction and refurbishment cycles, forcing suppliers to maintain parallel development tracks.
Product Type:
Waterproofing membranes demand the heaviest upfront manufacturing investment due to specialized extrusion and calendering equipment. Coatings and sealants require lower fixed capital but higher working capital for raw material inventory.
- Roof Coatings:Elastomeric formulations provide UV-stable surface protection with solar reflectance indices exceeding 29 for cool-roof certification. Demand clusters in California and Florida where Title 24 and hurricane-resistant specifications intersect, driven by commercial retrofit cycles and energy code compliance deadlines.
- Waterproofing Membranes:Bitumen-modified and thermoplastic sheets deliver below-grade and flat-roof moisture barriers with elongation rates of 200-800%. Specification concentrates in Germany and Japan where flat-roof commercial stock requires refurbishment under EU Green Deal and METI efficiency targets.
- Sealants:Silicone and polyurethane formulations bridge substrate gaps with movement accommodation up to 50% joint width.
- Adhesives:Pressure-sensitive and reactive chemistries bond membrane layers across varied temperature and humidity conditions.
- Primers:Surface preparation formulations enhance substrate adhesion for subsequent membrane or coating application.
Most installed capacity flows through Waterproofing Membranes. Expansion is steepest in Roof Coatings.
Application:
Commercial buildings generate the highest volume demand per project, with single flat-roof specifications often exceeding 50,000 square meters. Residential and institutional projects fragment procurement across smaller contractors.
- Commercial Buildings:Office, retail, and warehouse structures specify high-reflectance membranes and liquid-applied systems for flat-roof energy performance. Demand concentrates in the United States and China where retrofit activity and new construction codes create overlapping specification windows.
- Industrial Facilities:Manufacturing plants and logistics centers require chemical-resistant roofing withstanding aggressive exhaust and thermal cycling. Specification in Germany and Japan prioritizes polyurethane liquid membranes for complex roof geometries and equipment-intensive surfaces.
- Residential Constructions:Single-family and multi-family housing drives asphalt shingle and metal roof coating demand through regional contractor networks.
- Infrastructure Projects:Transportation terminals and utility structures specify extended-warranty systems with 20-30 year service life guarantees.
- Institutional Buildings:Healthcare and education facilities procure through multi-year facility management contracts bundling envelope maintenance.
Commercial Buildings absorb the majority of production volume. Industrial Facilities are gaining share fastest in high-specification markets.
Technology:
Polyurethane and bitumen systems require specialized reactor infrastructure and feedstock storage, elevating barriers to entry. Acrylic and silicone formulations run on more flexible batch equipment.
- Acrylic:Waterborne emulsions balance cost and UV stability for new construction sloped roofs in moderate climates. Specification dominates in the United States residential sector where cost sensitivity and contractor familiarity outweigh premium performance requirements.
- Silicone:Moisture-cure formulations deliver superior ponding-water resistance for low-slope commercial applications in humid subtropical zones. Demand accelerates in Florida and Singapore where standing water previously caused premature acrylic failure.
- Polyurethane:Two-component liquid membranes provide seamless waterproofing for complex roof geometries.
- Bitumen:Asphalt-based modified membranes dominate cost-sensitive commercial refurbishment.
- Elastomeric:High-elongation coatings accommodate structural movement in seismic zones.
Bitumen retains the largest installed base. Silicone is climbing the fastest as humid-climate specifications harden.
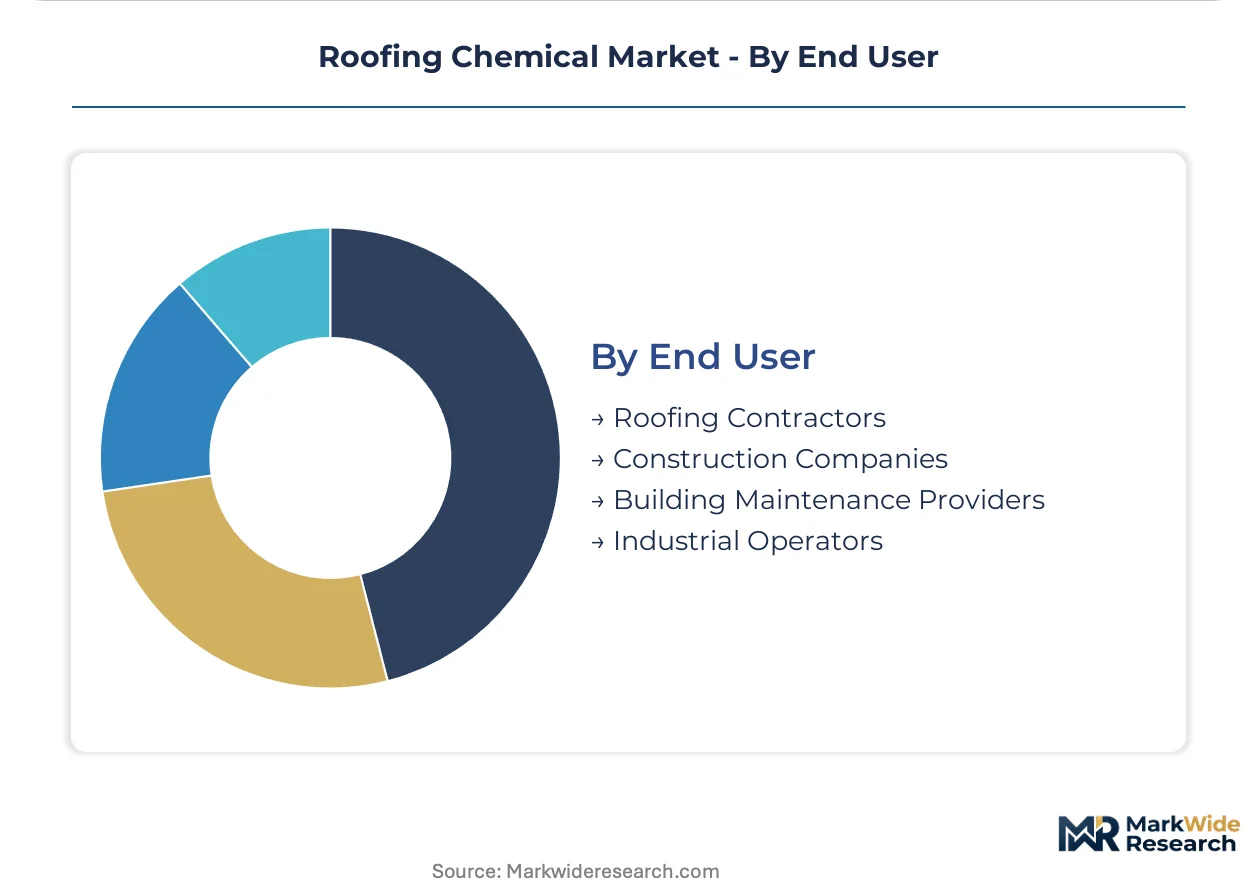
End User:
Building maintenance providers are consolidating procurement influence through multi-year service contracts, displacing traditional spot purchasing by roofing contractors. This shift elevates working capital requirements for inventory financing.
- Roofing Contractors:Specialized installation crews remain the primary specification channel for new construction and reactive repair, particularly in fragmented US and German markets. Manufacturer certification requirements for polyurethane foam and silicone systems constrain crew availability.
- Building Maintenance Providers:Facility management firms bundle coating refresh cycles with HVAC and envelope services under operational expenditure models. Procurement share expands in US healthcare and education verticals where capital budgets have flattened.
- Construction Companies:General contractors specify roofing chemicals as part of integrated building envelope packages.
- Industrial Operators:Asset owners direct procurement for in-house maintenance of manufacturing and logistics facilities.
Roofing Contractors still channel the greatest volume. Building Maintenance Providers are expanding most quickly as predictive maintenance models displace reactive repair.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting manufacturing investment toward jurisdictions with lower compliance burdens for solvent-based chemistries, while specification demand concentrates in markets with strict energy codes. Production migration patterns reflect this cost-of-compliance gap between formulation origins and end-use destinations.
United States
Commercial retrofit cycles and new construction codes drive specification for high-reflectance membranes. California's Title 24 Part 6 mandates aged solar reflectance thresholds that exceed national standards. Demand clusters in Los Angeles and San Francisco metro areas where cool roof compliance deadlines compress procurement timelines.
Germany
Flat-roof commercial refurbishment accelerates under EU Green Deal building renovation targets. REACH compliance elevates fixed costs for European formulators maintaining substance registration dossiers. Industrial activity concentrates in North Rhine-Westphalia and Bavaria where polyurethane liquid membrane specifications dominate complex roof geometries.
China
GB standards for green building materials create specification pull for low-VOC formulations in public construction projects. Metro corridor development in Beijing and Shanghai generates demand for high-rise roofing systems. Production capacity expansion tracks toward eastern coastal provinces with integrated chemical feedstock access.
Japan
METI energy efficiency incentives subsidize cool roof retrofits for existing commercial buildings. Specification shifts from reactive repair to predictive maintenance models in Tokyo and Osaka industrial corridors. Humid subtropical conditions favor silicone coating chemistry for ponding-water resistance.
India
Commercial real estate expansion across Bangalore, Hyderabad, and Mumbai drives polyurethane liquid membrane specification. National building code adoption varies by state, creating uneven enforcement of reflective roofing requirements. Manufacturing investment concentrates in Gujarat and Maharashtra with petrochemical corridor proximity.
Roofing Chemical Market Key Industry Players
Portfolio diversification dominates the current landscape as suppliers bifurcate between scale-driven commodity production and specialty formulation capabilities. The vendor base separates into three tiers: integrated chemical conglomerates with captive resin supply, regional membrane specialists with installation network control, and technology-focused coating formulators with certified applicator programs. Two competitive moves define current positioning: backward integration into bitumen and resin feedstocks to dampen crude price volatility, and strategic partnerships with facility management firms to secure multi-year service contract channels.
Among integrated chemical conglomerates, BASF SE and The Dow Chemical Company exemplify the scale-driven archetype with upstream control over polymer intermediates. Sika AG occupies a position within the specialty formulation tier, anchoring the polyurethane liquid-applied membrane segment through manufacturer-trained installation certification programs. These three entities represent divergent strategic paths: commodity chemical breadth versus application-specific technology depth versus contractor channel captivity.
| Leading Market Players |
|---|
| BASF SE |
| The Dow Chemical Company |
| GAF Materials Corporation |
| Sika AG |
| Owens Corning |
| Akzo Nobel N.V. |
| Carlisle Companies Inc. |
| Johns Manville |
| PPG Industries |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between ENERGY STAR-qualified formulations and commodity bitumen alternatives manifests in divergent margin structures and procurement channel configurations across the roofing chemical value chain. Premium-grade suppliers command specification loyalty through California Title 24 compliance dossiers while commodity producers compete on feedstock-adjacent blending economics in regional distributor networks.
Pricing Analysis
Distributor margin layers compress pricing transparency as regional building supply houses capture 15-25 point markups on liquid-applied systems before contractor-facing transactions. Project-based pricing dominates commercial flat-roof specifications where single-source warranties bundle material and labor risk, while spot purchasing persists in residential asphalt shingle replacement cycles. Price differentiation separates silicone formulations certified for ponding-water resistance from standard acrylic emulsions, with California and Florida contractors showing lowest sensitivity due to code-mandated performance floors. Cost compression in bitumen-modified membranes intensifies as crude-derived binder volatility cannot be fully passed through in competitive bidding environments.
Supply Chain Analysis
Bitumen feedstock supply rests on Gulf Coast refinery output and Middle Eastern export streams, with specialty silicone resins drawing from German and Japanese chemical producers. Acrylic emulsion polymerization concentrates in Texas and Louisiana with integrated petrochemical corridor access, while polyurethane intermediates hinge on MDI supply from Belgium, China, and the United States. Single-source vulnerability elevates risk for silicone coating formulators dependent on moisture-cure catalyst supply chains. Distribution runs through manufacturer-direct specification sales for large commercial projects and regional distributor networks for residential contractor fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as building code convergence toward cool-roof certification hardens specification floors and compresses commodity substitution elasticity. Demand is shifting toward premium silicone and polyurethane formulations that satisfy humid-climate ponding-water resistance requirements.
For Market Incumbents: Cement specification control through manufacturer-certified applicator programs that constrain crew availability for rival polyurethane foam and silicone coating systems. Deepen backward integration into bitumen and resin feedstocks to dampen crude price volatility exposure. Prioritize REACH-compliant formulation pipelines to defend European market access against substitution pressure from waterborne alternatives.
For New Entrants and Emerging Players: Launch via predictive maintenance service bundling that captures building maintenance provider procurement channels displacing traditional roofing contractors in US healthcare and education verticals. Target India's commercial real estate expansion across Bangalore, Hyderabad, and Mumbai metro corridors where polyurethane liquid membrane specification demand outpaces qualified supplier capacity. Pursue white-label partnerships with facility management firms to bypass fragmented contractor certification bottlenecks.
For Investors and Strategic Acquirers: Consolidation pressure builds where embodied carbon disclosure gaps delay EPD qualification for premium LEED v4.1 and BREEAM projects, advantaging suppliers with validated lifecycle data. Long-term viability favors specialty formulators with captive installation certification networks over commodity bitumen membrane producers facing margin compression. Watch for carbon-border adjustment mechanism implementation as inflection indicator that would reshape material sourcing economics and supplier qualification criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bitumen Feedstocks | Captive binder supply insulates margin volatility from Gulf Coast refinery output swings. |
| Manufacturer-Certified Applicator Programs | Polyurethane foam and silicone coating crew constraints lock out unqualified competitors. |
| EPD Lifecycle Data Development | Validated embodied carbon disclosure secures LEED v4.1 and BREEAM premium project qualification. |
| Predictive Maintenance Service Bundling | IoT-enabled moisture detection with coating warranties captures facility management procurement channels. |
| REACH-Compliant Formulation Pipelines | Substitution plans for legacy plasticizers and biocides defend European market access against regulatory exclusion. |
Research Approach
Bottom-up commercial building modeling reconciled against top-down resin feedstock tracking forms the analytical core of this study. Primary interviews with roofing contractors, building maintenance procurement directors, polyurethane R&D technical leads, and distributor inventory managers combined with secondary validation from customs trade data, ACC industry reports, SEC 10-K filings, and EPA ENERGY STAR certification databases. Triangulation across these sources ensures volume estimates align with actual specification flows through identified channel structures.
Historical trendline analysis across installed base refurbishment cycles and new construction permitting data informs the projection framework. Segmentation dimensions modeled include technology chemistry, application building type, end-user procurement channel, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating code adoption timelines and feedstock cost trajectories. Key forecast inputs encompass Title 24 compliance deadline clustering and EU Green Deal renovation target implementation pacing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under bitumen price spike scenarios or accelerated carbon-border adjustment mechanism adoption. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and contractor certification capacity expansion. A small set of named triggers—including REACH substance restriction updates and METI subsidy program renewals—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Aircraft Cleaning Chemicals Market
Chemicals
3-Iodoaniline Market
Chemicals
Cetostearyl Alcohol Market
Chemicals
China Methanol Market
Chemicals
Amine Oxide Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Industrial Odor Management Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Aluminum Phosphide Market
Chemicals
Europe Textile Chemicals Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
Quaternium-15 Market
Chemicals
HATU Market