
 Sodium Hydride Market | 2026-2036
Sodium Hydride Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Hydride Market Analytics
Lithium metal is broadening its displacement of sodium hydride in select battery electrolyte applications, though sodium hydride retains cost advantages in bulk organic synthesis. Albemarle Corporation leverages its integrated bromine and lithium operations to sustain raw material flexibility across its hydride portfolio. Anhui Wotu Chemical anchors its position through captive caustic soda supply and dedicated reactor capacity in Anhui province. American Elements differentiates via ultra-high-purity grades certified for pharmaceutical and semiconductor research channels.
Sodium hydride consists of sodium and hydrogen in a 1:1 ionic ratio, typically supplied as a grayish-white solid with 60% dispersion in mineral oil to mitigate pyrophoric hazard; manufacturers produce it via direct combination of molten sodium with hydrogen gas at elevated temperature, with the resulting material serving primarily as a strong base and reducing agent in condensation, alkylation, and deprotonation reactions. Powder sodium hydride dominates volume shipments due to faster dissolution kinetics favored by continuous-flow pharmaceutical processes, while granulated sodium hydride commands premium positioning in agrochemical batch operations where controlled reactivity reduces thermal runaway risk. Lithium battery manufacturing represents the fastest-growing application segment as cell producers qualify sodium hydride precursors for solid-state electrolyte development.
EPA hazardous waste regulations and OSHA process safety management standards govern sodium hydride handling, storage, and disposal in the United States, while REACH registration and CLP classification in Europe mandate extensive toxicological dossiers for import and formulation. China's SAMR enforces GB 190 and GB 13690 labeling protocols for corrosive and water-reactive substances moving through domestic chemical distribution. Stakeholders must monitor evolving solid-state battery chemistry roadmaps and regional carbon border adjustment mechanisms to calibrate capacity commitments and purity grade investments.
Market Dynamics
Solid-state battery chemistry roadmaps are compressing qualification timelines for sodium hydride precursors, forcing producers to align purity investments with cell manufacturer specifications rather than traditional pharmaceutical grades.
Growth Catalysts
- Active pharmaceutical ingredient synthesis:German and Indian pharmaceutical manufacturers are scaling sodium hydride purchases for condensation and deprotonation reactions in generic drug manufacturing.
- REACH registration compliance:ECHA mandates for CLP classification and toxicological dossiers create entry barriers that favor established EU-registered suppliers with dedicated regulatory teams.
- Jiangsu province cluster effects:Contract research and manufacturing organization concentration in eastern China generates localized demand density for mineral oil dispersions.
Market Restraints
- Molten sodium input cost volatility:Energy-intensive direct combination process exposes margins to electricity and hydrogen feedstock price swings in chlor-alkali integrated operations.
- Lithium metal substitution:Solid-state electrolyte developers in South Korea and Japan are qualifying lithium hydride alternatives for ionic conductivity performance.
- EPA hazardous waste classification:RCRA Subtitle C designation for spent mineral oil dispersions elevates disposal costs and liability exposure for US pharmaceutical formulators.
Strategic Opportunities
- Ultra-high-purity semiconductor channel:American and European materials suppliers can certify sodium hydride for EUV lithography precursor applications.
- Gujarat chemical corridor expansion:Indian agrochemical batch producers seek granulated grades with controlled reactivity profiles.
- Carbon border adjustment mechanism alignment:EU importers can capture premium positioning by documenting Scope 3 emissions from chlor-alkali feedstock through SAMR-registered Chinese suppliers.
Industry Challenges
- Pyrophoric handling certification:OSHA process safety management compliance requires specialized technician training for mineral oil dispersion repackaging operations.
- Reactor capacity lead times:Dedicated sodium hydride production vessels face 18-24 month fabrication cycles from specialized pressure equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Hydride Market |
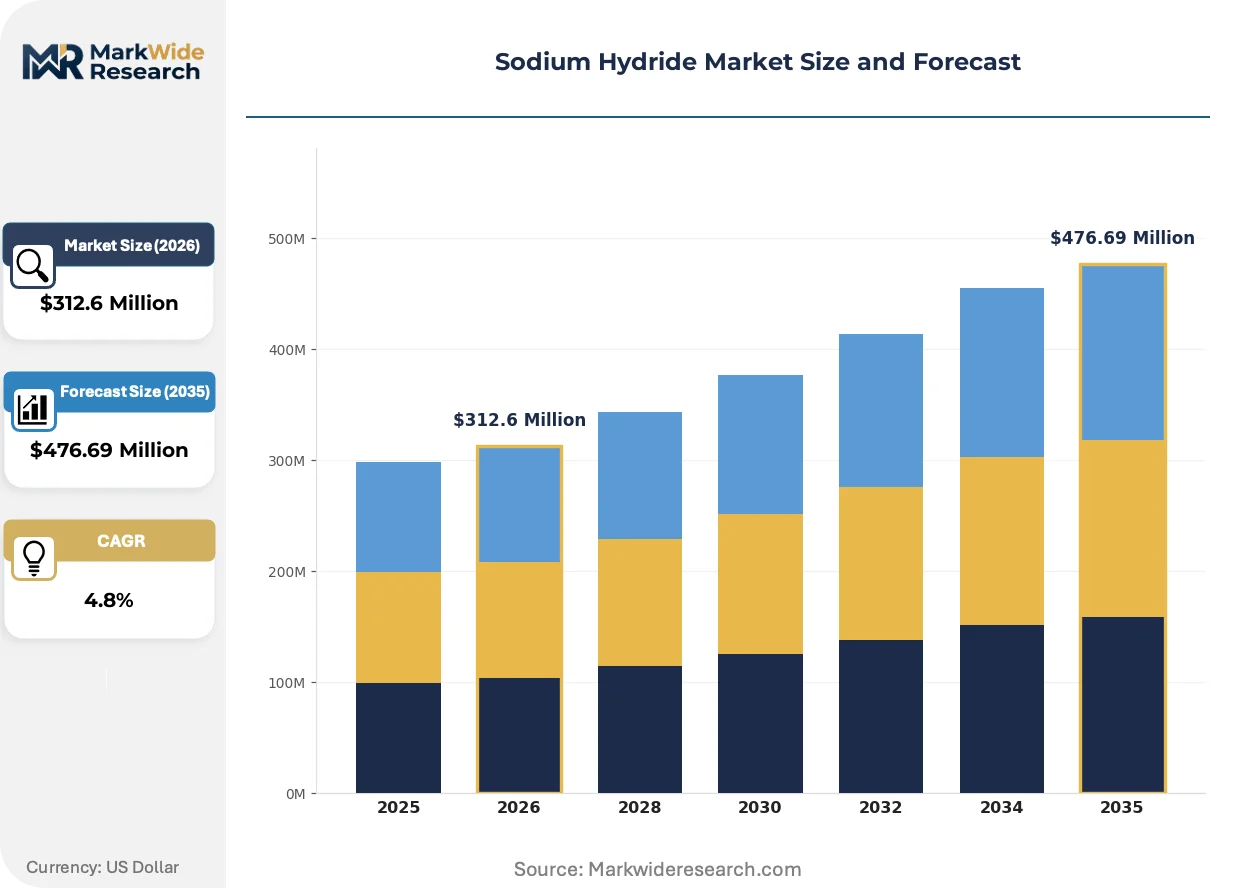
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $476.69 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated Sodium Hydride, Powder Sodium Hydride, Paste Sodium Hydride, Pellets Sodium Hydride Application: Pharmaceuticals, Organic Synthesis, Hydride Chemical Reagents, Lithium Battery Manufacturing End User: Chemical Manufacturers, Research Laboratories, Battery Producers, Agrochemical Companies Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Albemarle Corporation, Anhui Wotu Chemical, ShanDong Guobang Pharmaceutical, Dalchem, Tianjin Dipper Fine Chemical, Hebei Keyu, American Elements, Tokyo Chemical Industry Co., Ltd., Spectrum Chemical Mfg. Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Hydride Market Evolving Landscape
Continuous-flow pharmaceutical manufacturing is rewriting specification requirements for sodium hydride dissolution kinetics, while battery electrolyte research opens entirely new purity tiers.
Continuous powder dosing systems is overtaking manual batch charging in pharmaceutical active ingredient synthesis. Merck KGaA and Lonza contract manufacturing sites are installing gravimetric feeders for 60% mineral oil dispersions to achieve reproducible deprotonation kinetics. This automation is compressing batch cycle times and reducing thermal runaway incidents in multi-ton scale reactions.
EU REACH Annex XIV authorization requirements for substances of very high concern are tightening impurity disclosure obligations for sodium hydride importers. ECHA's 2024 update to guidance on metal hydrides now demands full analytical characterization of trace aluminum and iron content. German and Dutch formulators are responding by qualifying suppliers with ICP-MS certification capabilities.
Direct supplier relationships are displacing traditional chemical distributor networks for battery-grade sodium hydride. South Korean solid-state electrolyte developers are negotiating annual contracts with Chinese producers to secure lot-to-lot consistency for sulfide glass synthesis. This channel compression eliminates margin stacking but transfers specification risk to cell manufacturers.
Sodium Hydride Market Segmentation
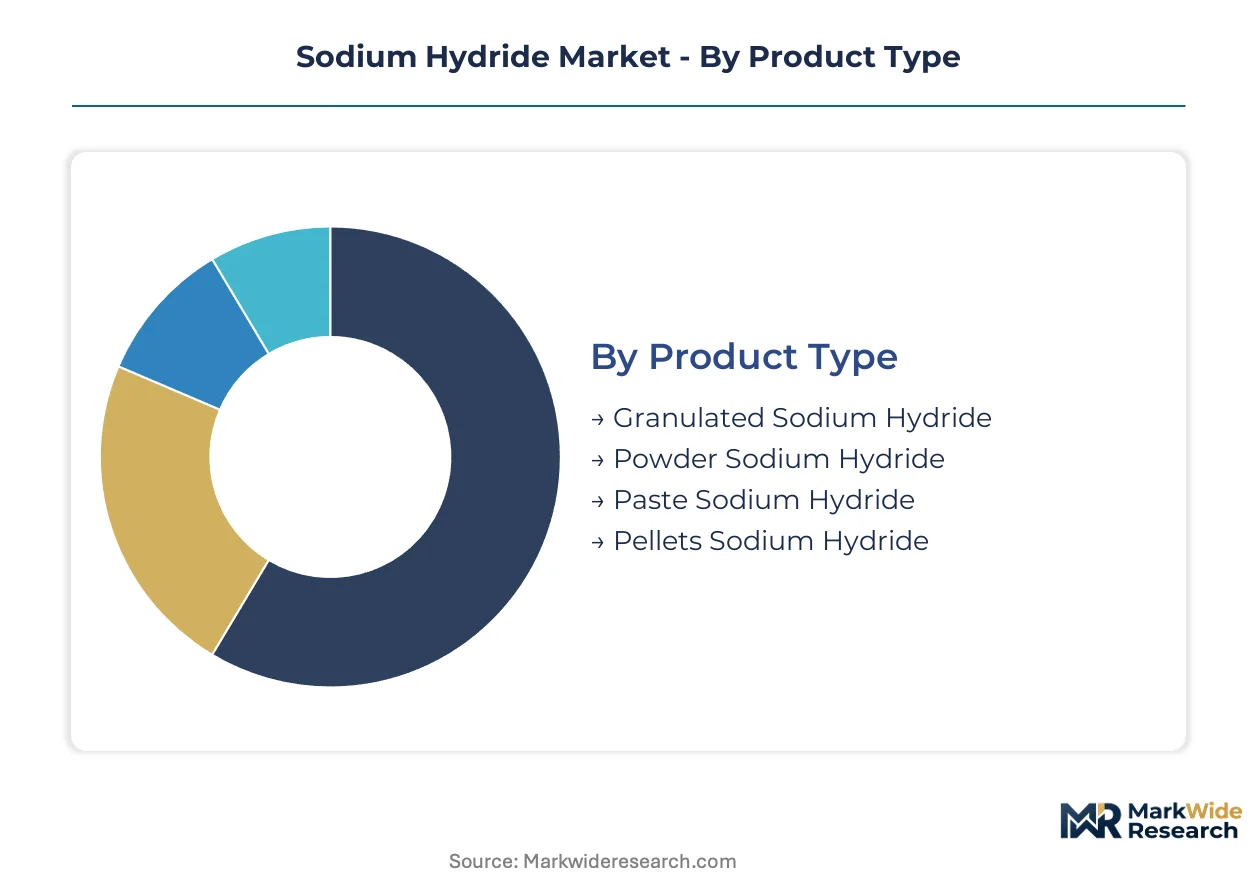
Sodium hydride's physical form, application chemistry, and customer handling capabilities create distinct specification tiers that reshape procurement patterns across pharmaceutical and battery supply chains. Each segmentation axis carries unique regulatory, logistics, and purity requirements that fragment supplier strategies.
Product Type:
Dissolution kinetics and pyrophoric handling characteristics differentiate physical forms, with mineral oil dispersion ratios and particle geometry determining end-use compatibility.
- Granulated Sodium Hydride:Larger particle geometry slows surface-area-driven reactivity, enabling controlled dosing in batch agrochemical operations where thermal management limits throughput. Gujarat corridor formulators favor this grade for condensation reactions in generic active ingredient synthesis.
- Powder Sodium Hydride:Finer particle distribution accelerates dissolution in continuous-flow pharmaceutical reactors, aligning with Merck KGaA and Lonza gravimetric feeding systems. Jiangsu province contract manufacturers specify 60% mineral oil dispersions for reproducible deprotonation kinetics in multi-ton scale reactions.
- Paste Sodium Hydride:Pre-dispersed slurry formulations reduce airborne dust exposure during manual charging operations in academic and small-batch research settings.
- Pellets Sodium Hydride:Compressed cylindrical geometry enables precise tablet-based dosing in automated solid-feed chemical processing equipment.
Powder sodium hydride leads on scale; lithium battery precursor applications drive momentum toward paste and pellet innovations.
Application:
Reaction chemistry requirements and regulatory scrutiny intensity segment demand by end-use, with pharmaceutical and battery applications diverging on purity specifications.
- Pharmaceuticals:Deprotonation and condensation reactions in generic drug manufacturing demand ICP-MS trace metal certification under ECHA REACH Annex XIV guidance. German and Indian formulators scale purchases for active pharmaceutical ingredient synthesis.
- Organic Synthesis:Broad utility as strong base and reducing agent in alkylation chemistry serves contract research organizations with flexible specification tolerances.
- Hydride Chemical Reagents:Laboratory-scale demand for analytical standards and method development supports research laboratory procurement through distributor channels.
- Lithium Battery Manufacturing:Solid-state electrolyte developers in South Korea negotiate direct annual contracts with Chinese producers for sulfide glass synthesis precursors, compressing traditional distribution margins.
Pharmaceuticals maintains volume leadership; battery manufacturing climbs fastest on chemistry roadmap acceleration.
End User:
Scale, technical capability, and regulatory compliance burden stratify customer segments, with captive chlor-alkali integration favoring large chemical manufacturers.
- Chemical Manufacturers:Integrated chlor-alkali operations with captive sodium supply and dedicated reactor capacity dominate bulk procurement, with Anhui Wotu Chemical leveraging captive caustic soda for cost positioning.
- Research Laboratories:Small-batch, high-frequency purchasing patterns prioritize packaging safety and rapid fulfillment over unit economics.
- Battery Producers:Solid-state cell developers impose lot-to-lot consistency requirements that eliminate traditional distributor intermediaries in favor of direct supplier relationships.
- Agrochemical Companies:Batch-oriented operations in India's Gujarat corridor seek granulated grades with controlled reactivity profiles to reduce thermal runaway incidents.
Chemical manufacturers command procurement scale; battery producers reshape channel economics fastest.
Distribution Channel:
Specification risk transfer and margin stacking economics determine channel selection, with high-purity grades concentrating in direct relationships.
- Direct Sales:Annual contracting for battery-grade material eliminates intermediary margin stacking while transferring lot-to-lot specification risk to South Korean and Japanese solid-state electrolyte developers.
- Distributors:Traditional chemical distribution networks retain role in pharmaceutical and research laboratory segments where fragmented demand and regulatory documentation support justify value-added services.
- Online Retail:Small-volume, catalog-standard grades for academic and pilot-scale procurement favor digital channels with rapid fulfillment.
- Wholesalers:Bulk mineral oil dispersions move through regional chemical wholesalers serving industrial manufacturing clusters with standardized handling protocols.
Direct sales captures premium positioning; distributor channels defend breadth coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province anchors sodium hydride demand density through its contract research and manufacturing organization concentration, with procurement patterns rippling across four additional national markets where pharmaceutical and battery chemistry investments concentrate.
China
Jiangsu province CROs and Anhui province chlor-alkali integrated producers drive mineral oil dispersion procurement for continuous-flow pharmaceutical synthesis. SAMR enforces GB 190 and GB 13690 labeling protocols for corrosive and water-reactive substances through domestic chemical distribution channels. South Korean solid-state battery developers negotiate direct annual contracts with Chinese producers, compressing traditional distributor margins in the Yangtze River Delta cluster.
Germany
Generic drug manufacturers in the Rhine-Ruhr and Bavaria chemical corridors scale sodium hydride purchases for condensation and deprotonation reactions in active pharmaceutical ingredient synthesis. ECHA REACH Annex XIV authorization requirements and CLP classification mandates demand full ICP-MS analytical characterization of trace aluminum and iron content. Merck KGaA contract manufacturing sites in Darmstadt install gravimetric feeders for 60% mineral oil dispersions to achieve reproducible reaction kinetics.
India
Gujarat corridor agrochemical batch producers seek granulated sodium hydride grades with controlled reactivity profiles to reduce thermal runaway incidents in generic active ingredient manufacturing. CDSCO and state-level pollution control mandates govern hazardous chemical handling across the chemical corridor. Maharashtra-based pharmaceutical formulators qualify suppliers with dedicated regulatory teams for EU-registered export compliance.
United States
Pharmaceutical formulators face RCRA Subtitle C hazardous waste classification for spent mineral oil dispersions, elevating disposal costs and liability exposure. EPA hazardous waste regulations and OSHA process safety management standards govern handling, storage, and repackaging operations. American Elements certifies ultra-high-purity grades for semiconductor research channels through specialized distribution networks.
South Korea
Solid-state electrolyte developers qualify sodium hydride precursors for sulfide glass synthesis, imposing lot-to-lot consistency requirements that eliminate traditional chemical distributor intermediaries. MFDS pharmaceutical and industrial chemical regulations align with EU REACH disclosure standards for import qualification. Direct supplier relationships with Chinese producers transfer specification risk to cell manufacturers while securing annual volume commitments.
Sodium Hydride Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and captive feedstock integration. The vendor base stratifies into three tiers: integrated chlor-alkali operators with captive sodium supply, specialty chemical houses with dedicated pharmaceutical certification, and research-grade distributors serving laboratory channels. Strategic moves concentrate on capacity expansion in Jiangsu and Anhui provinces, alongside REACH registration dossier investments for EU market access.
Within the integrated chlor-alkali tier, Albemarle Corporation and Anhui Wotu Chemical exemplify contrasting geographic anchoring strategies. Albemarle leverages its bromine and lithium operations for raw material flexibility across hydride portfolios. Anhui Wotu occupies a position defined by captive caustic soda supply and dedicated reactor capacity in Anhui province. American Elements represents the ultra-high-purity archetype, certifying material for semiconductor and pharmaceutical research channels through specialized analytical capabilities.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Anhui Wotu Chemical |
| ShanDong Guobang Pharmaceutical |
| Dalchem |
| Tianjin Dipper Fine Chemical |
| Hebei Keyu |
| American Elements |
| Tokyo Chemical Industry Co., Ltd. |
| Spectrum Chemical Mfg. Corp. |
| Others |
Value Network & Pricing Analysis
Specialized pyrophoric handling technicians concentrated in Jiangsu province and the Gujarat chemical corridor create labor-cost differentials that widen pricing-tier spreads between pharmaceutical-grade and industrial-grade sodium hydride. Chlor-alkali integrated producers leverage captive sodium supply to compress input costs, while independent formulators absorb premium wages for OSHA-certified technicians in repackaging operations.
Pricing Analysis
Input-cost pass-through from molten sodium and hydrogen feedstock volatility anchors contract-based long-term offtake agreements between chlor-alkali integrated producers and pharmaceutical formulators. Price differentiation separates ICP-MS-certified pharmaceutical grades from standard industrial dispersions, with certification level and volume scale as primary tiering mechanisms. Cost compression in battery-grade material is intensifying because South Korean cell manufacturers negotiate direct annual contracts that eliminate distributor margins. Research laboratories exhibit highest price sensitivity due to small-batch purchasing patterns, while solid-state electrolyte developers prioritize lot-to-lot consistency over unit economics.
Supply Chain Analysis
Reverse-logistics flows for spent mineral oil dispersions face RCRA Subtitle C hazardous waste classification, elevating disposal costs and liability exposure for US pharmaceutical formulators. Supply concentrates in China, Germany, and India, with raw material dependencies on chlor-alkali sodium, hydrogen feedstock, and specialized mineral oil carriers. Single-source vulnerability runs through dedicated reactor vessel fabricators facing 18-24 month lead times. Distribution runs through direct annual contracting for battery-grade material, while pharmaceutical and research segments retain traditional chemical distributor networks for regulatory documentation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with ECHA REACH Annex XIV authorization requirements for metal hydrides tightening impurity disclosure obligations and favoring established EU-registered suppliers with dedicated regulatory teams.
For Market Incumbents: Acquire dedicated reactor capacity in Anhui province to secure captive chlor-alkali integration against molten sodium input cost volatility. Strengthen ICP-MS certification capabilities to defend positioning against lithium hydride substitution in solid-state electrolyte applications. Expand backward integration into hydrogen feedstock supply to buffer margin pressure from energy-intensive direct combination processes. For New Entrants and Emerging Players: Direct-to-battery-producer digital channels offer white-space entry points for sulfide glass synthesis precursor qualification in South Korea. Target ultra-high-purity semiconductor research channels in the United States where American Elements has established certification benchmarks but volume remains fragmented. Pursue carbon border adjustment mechanism documentation partnerships with SAMR-registered Chinese suppliers to capture EU importer premium positioning. For Investors and Strategic Acquirers: Chlor-alkali integrated chemical manufacturers are the most active acquirer in this space, seeking captive sodium supply and dedicated hydride reactor assets. Long-term viability hinges on alignment with solid-state battery chemistry roadmaps and pharmaceutical regulatory compliance capabilities. Monitor ECHA guidance updates on metal hydride impurity thresholds as inflection indicators for certification investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Feedstock | Anhui Wotu Chemical leverages captive caustic soda supply to compress input costs and stabilize margins. |
| ICP-MS Certification Investment | German formulators respond to ECHA REACH Annex XIV guidance demanding full trace aluminum and iron characterization. |
| Direct Annual Contracting with Battery Producers | South Korean solid-state electrolyte developers eliminate distributor intermediaries to secure lot-to-lot consistency. |
| Gravimetric Feeder System Installation | Merck KGaA contract manufacturing sites achieve reproducible deprotonation kinetics in multi-ton pharmaceutical reactions. |
| Carbon Border Adjustment Mechanism Alignment | EU importers document Scope 3 emissions from chlor-alkali feedstock through SAMR-registered Chinese suppliers. |
Research Methodology
Coverage spans China, Germany, India, the United States, and South Korea, with primary inputs from each market combining interviews with plant managers at chlor-alkali integrated operations, procurement leads at pharmaceutical formulators, distribution channel partners handling mineral oil dispersions, and technical R&D directors in solid-state battery development. Secondary validation draws from customs and trade data, SEC 10-K filings of listed chemical producers, ECHA registration dossiers, and SAMR hazardous chemical labeling protocols. Bottom-up demand modeling triangulates against top-down capacity assessments across regional production clusters.
Rate-of-change decomposition separates volume growth from price trajectory across the analysis window, with segmentation dimensions covering physical form tier, application chemistry, end-user scale, and regional regulatory cluster. CAGRs derive from installed capacity expansion timelines, qualification cycle compression in battery applications, and pharmaceutical batch automation adoption curves. Forecast inputs incorporate solid-state electrolyte chemistry roadmaps and evolving EU carbon border adjustment mechanism implementation schedules.
The model assumes a particular technology adoption path for sulfide glass solid-state electrolytes; alternative pathways for oxide or polymer electrolyte architectures would alter the outlook for sodium hydride precursor demand. Forecasts reflect assumptions on REACH Annex XIV authorization timelines and chlor-alkali energy cost trajectories. Practitioners should monitor ECHA metal hydride guidance updates, South Korean cell manufacturer qualification announcements, and reactor vessel fabrication lead time extensions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Solder Flux Market
Chemicals
Laboratory Chemicals Market
Chemicals
Global Aldehyde Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Monoisopropanolamine (MIPA) Market
Chemicals
Europe Textile Chemicals Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Methoprene Market
Chemicals
Hydrazine Hydrate Market
Chemicals
Iscotrizinol Market
Chemicals
Concrete Surface Treatment Chemicals Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
Detergent Alcohols Market
Chemicals
SLS and LABSA Market
Chemicals
Fatty Alcohol Ethoxylates Market