
 Dicing Tapes Market | 2026-2036
Dicing Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Dicing Tapes Market Intelligence
Aftermarket wafer reclaim services is reshaping margin distribution across the dicing tapes value chain. Nitto Denko Corporation leverages its adhesive chemistry portfolio to dominate UV-curable product lines in Japanese fabs. Lintec Corporation anchors its position through backward integration into polyimide film substrates. Furukawa Electric Co., Ltd. competes on thermal management properties for power semiconductor applications.
Dicing tapes are pressure-sensitive adhesive films applied to wafer surfaces during back-grinding and dicing operations, typically comprising a polyolefin or PVC base layer coated with UV-sensitive or thermally activated adhesives rated for cleanroom Class 10 environments. Their primary purpose is to secure brittle semiconductor wafers during mechanical singulation while enabling residue-free die pickup. UV curable formulations command premium positioning in logic chip foundries where throughput requirements exceed thermal release cycles. Semiconductor wafer applications sustain the largest volume pool, though MEMS devices represent the fastest-growing segment due to heterogeneous integration trends. Acrylic adhesive chemistries occupy the mature core of the market, while silicone variants capture margin in high-temperature compound semiconductor processing.
Japan's METI enforces JIS standards on electronic material outgassing that directly constrain adhesive formulation choices for dicing tapes sold into domestic fabs. South Korea's MFDS and the country's national semiconductor regulator coordinate on chemical substance reporting for imported adhesive materials, creating compliance thresholds for non-Korean suppliers. The US EPA regulates volatile organic compound emissions from adhesive manufacturing facilities, affecting production location decisions for suppliers serving North American chip packaging operations. Stakeholders must monitor how China's NMPA and MIIT align GB standards with international semiconductor material specifications as domestic foundry capacity expands.
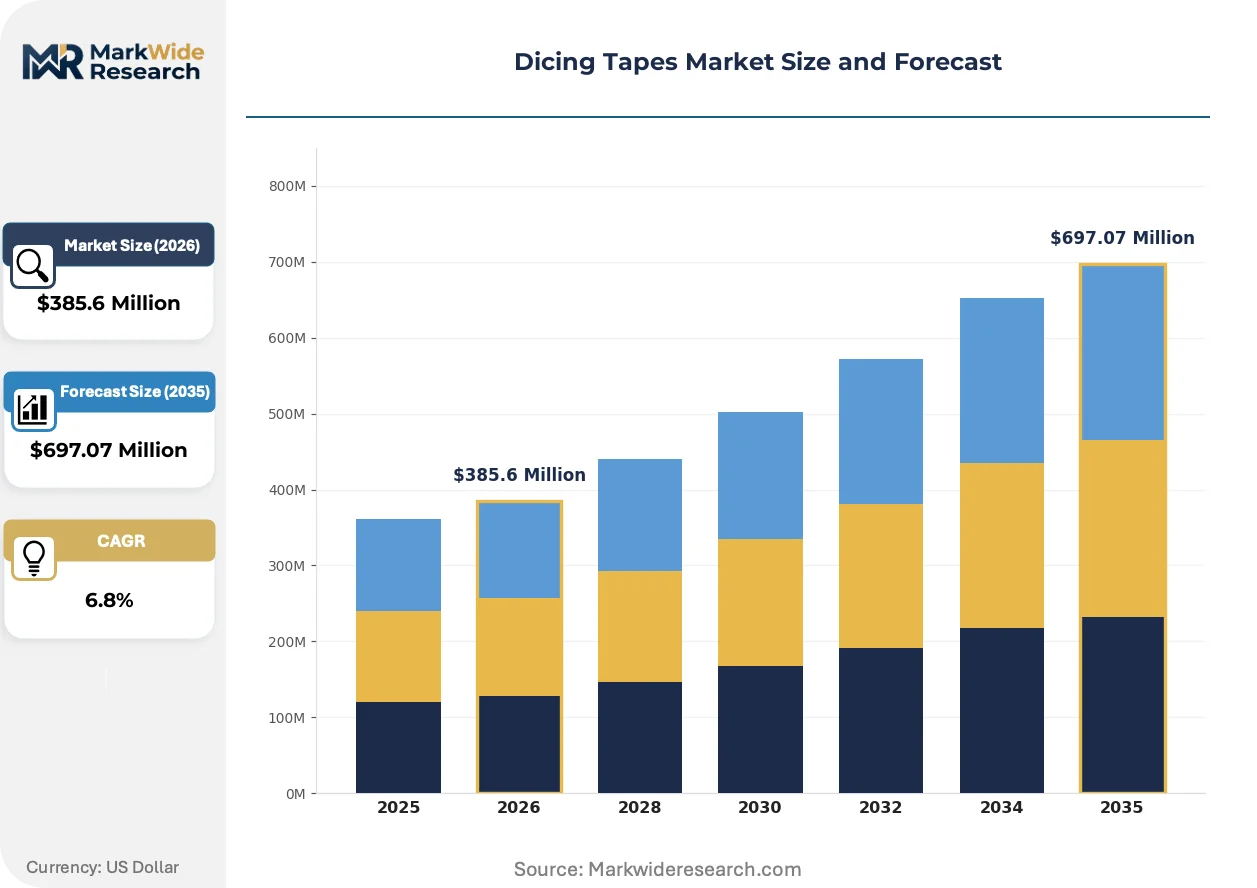
Market Dynamics
UV-curable adhesive formulations are compressing thermal-release cycle times in high-throughput foundries, forcing incumbent suppliers to reconfigure coating line investments and foundry qualification protocols around photochemical cure kinetics rather than thermal activation thresholds.
Growth Catalysts
- Heterogeneous integration in MEMS packaging:Multi-die stacking architectures require dicing tapes rated for extreme thickness variation tolerance during back-grinding of compound semiconductor wafers.
- South Korea's K-Semiconductor Belt initiative:Government-backed cluster development in Pyeongtaek and Yongin is expanding captive demand for Class 10 cleanroom-compatible adhesive films.
- UV-LED cure systems:Solid-state ultraviolet sources eliminate mercury lamp thermal drift, enabling sub-10-second tack reduction for logic chip singulation throughput gains.
Market Restraints
- Acrylic monomer price volatility:Petrochemical feedstock fluctuations for pressure-sensitive adhesive precursors compress margin predictability for tape converters.
- East Asian substrate concentration:Polyimide film supply anchors on Japanese and South Korean polymerization capacity, creating single-source vulnerability for backward-integrated tape manufacturers.
- Thermal release cycle incompatibility:Legacy batch ovens cannot retrofit UV-LED arrays without fab downtime exceeding typical qualification windows for process change authorization.
Strategic Opportunities
- Power semiconductor thermal management:Silicon carbide wafer dicing requires silicone adhesive chemistries rated for 200°C+ temporary bonding during grinding of ultra-hard substrates.
- China's GB standard alignment:Domestic foundry expansion under MIIT semiconductor self-sufficiency targets creates first-mover advantage for tape suppliers achieving NMPA chemical substance pre-registration.
- Reclaim service integration:Aftermarket wafer cleaning and tape residue removal bundling shifts margin capture from consumable sales to recurring process service contracts.
Industry Challenges
- Photoinitiator residue control:UV-curable formulations require sub-ppm radical scavenger elimination to prevent die surface contamination during pickup, demanding analytical chemistry capabilities absent from traditional tape coating operations.
- Cross-fab qualification duplication:Each foundry's distinct back-grinding spindle configuration and chuck temperature profile forces redundant mechanical testing rather than transferable product certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dicing Tapes Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Soluble, UV Curable, Silicone Adhesive, Acrylic Adhesive, Rubber Adhesive Application: Semiconductor Wafer, LED Manufacturing, Photovoltaic Cells, MEMS Devices, Microelectronics Assembly Adhesive Thickness: Ultra-Thin, Thin, Medium, Thick, Extra Thick End User: Chip Manufacturers, Electronic Assemblers, Solar Panel Producers, MEMS Fabricators, Semiconductor Foundries |
| Companies Covered | Nitto Denko Corporation, Lintec Corporation, Furukawa Electric Co., Ltd., Sumitomo Bakelite Co., Ltd., Denka Company Limited, Mitsui Chemicals, Inc., AI Technology, Inc., Pantech Tape Co., Ltd., 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dicing Tapes Market Strategic Shifts & Innovations
Adhesive formulation chemistry and cure mechanism architecture are diverging along application-specific performance vectors, fragmenting what historically operated as a standardized consumable category into process-engineered product lines.
Hybrid acrylic-silicone adhesive layers are hybridizing to combine the room-temperature tack of radical-cure acrylates with the thermal stability of condensation-cure silicones. Power semiconductor foundries processing gallium nitride and silicon carbide wafers have adopted these formulations for high-temperature grinding operations where pure acrylics soften and pure silicones exhibit excessive cold flow. The structural consequence is a bifurcation in R&D investment, with suppliers maintaining parallel formulation teams rather than unified polymer chemistry groups.
Japan's METI has tightened JIS C 60068 outgassing thresholds for electronic materials used in automotive-grade semiconductor packaging, directly constraining volatile siloxane and residual solvent specifications for dicing tapes. Automotive MCU and power module foundries in Toyota City and Hiroshima now require third-party outgassing certification as a condition of supplier qualification. Tape manufacturers serving this segment have responded by shifting from solvent-based coating to hot-melt extrusion processes that eliminate drying oven residue.
Consolidated procurement through foundry-level master service agreements is displacing individual fab purchasing autonomy for consumables. Taiwan Semiconductor Manufacturing Company and Samsung Foundry have centralized dicing tape specification authority at corporate engineering rather than site-level materials management, compressing supplier count per technology node. This concentration is most visible in the Hsinchu Science Park corridor, where three foundry groups now account for the majority of UV-curable tape volume and negotiate directly with adhesive formulators rather than distribution intermediaries.
Dicing Tapes Market Segmentation
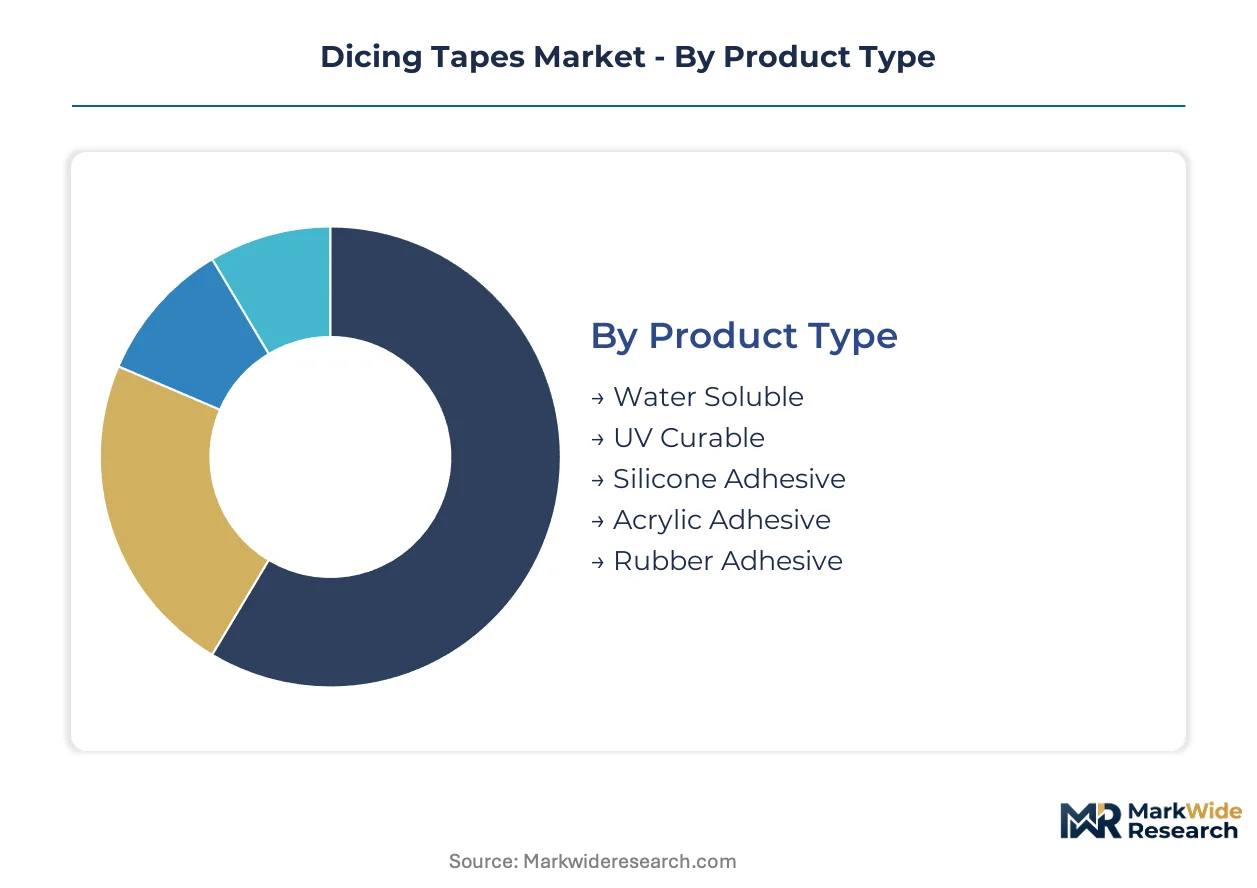
Dicing tape segmentation reflects the tension between standardized consumable economics and process-specific performance requirements. Each dimension—chemistry, application, thickness, and customer type—carries distinct margin profiles and qualification barriers that reshape supplier competitive position.
Product Type:
Cost tier stratification separates premium photochemical formulations from commodity thermal-release alternatives.
- UV Curable:Photoinitiator-loaded acrylic or epoxy adhesives cure under UV-LED exposure to enable sub-10-second tack reduction. Demand concentrates in Taiwan's Hsinchu Science Park logic foundries where throughput requirements exceed thermal release cycle capacity.
- Acrylic Adhesive:Radical-cure pressure-sensitive formulations dominate mature packaging nodes with established thermal processing infrastructure. South Korean Pyeongtaek foundries anchor volume for this cost-optimized chemistry.
- Silicone Adhesive:Condensation-cure polydimethylsiloxane systems rated for 200°C+ temporary bonding during silicon carbide wafer grinding.
- Rubber Adhesive:Natural and synthetic rubber-based pressure-sensitive tapes for legacy discrete semiconductor packaging with moderate thermal requirements.
- Water Soluble:Polyvinyl alcohol base layers with water-dispersible adhesives for environmentally constrained European packaging operations under ECHA substance restrictions.
Acrylic adhesive commands the established base. The steepest expansion runs through UV curable.
Application:
Application segmentation tracks the divergence between high-volume commodity semiconductor processing and emerging compound semiconductor architectures.
- Semiconductor Wafer:Silicon wafer back-grinding and dicing for logic, memory, and power devices represents the volume anchor, with Taiwan and South Korea fabs driving specification authority.
- MEMS Devices:Micro-electromechanical systems packaging requires extreme thickness variation tolerance during grinding of heterogeneous material stacks. Japan's automotive MEMS foundries in Toyota City are expanding specification requirements under tightened METI JIS outgassing standards.
- LED Manufacturing:Sapphire and silicon carbide substrate dicing for solid-state lighting with specialized UV-release requirements for brittle III-nitride materials.
- Photovoltaic Cells:Silicon solar wafer dicing with cost-optimized thermal release formulations serving Chinese panel producers under MIIT capacity expansion targets.
- Microelectronics Assembly:Package-level dicing and singulation for system-in-package and multi-chip module configurations.
Semiconductor wafer applications retain the volume core. MEMS devices are climbing the fastest as heterogeneous integration accelerates.
Adhesive Thickness:
Thickness selection maps directly to wafer diameter and grinding depth parameters, with process node migration reshaping specification distributions.
- Thin:50-80 micron adhesive layers for 300mm silicon wafer processing in advanced foundry nodes, balancing conformability with cleanroom particle control.
- Ultra-Thin:Sub-50 micron formulations for extreme thinning applications below 50 micron final wafer thickness, concentrated in stacked memory and image sensor packaging.
- Medium:80-120 micron general-purpose thickness for mixed-signal and power semiconductor wafer grinding.
- Thick:120-200 micron layers for compound semiconductor wafers with high topography or temporary bonding to carrier substrates.
- Extra Thick:Above-200 micron specialty grades for glass carrier and panel-level fan-out packaging processes.
Thin specifications dominate current procurement. Ultra-thin is gaining share fastest as 3D stacking architectures proliferate.
End User:
Customer type segmentation reveals the consolidation of procurement authority and the divergence between captive foundry demand and merchant assembly requirements.
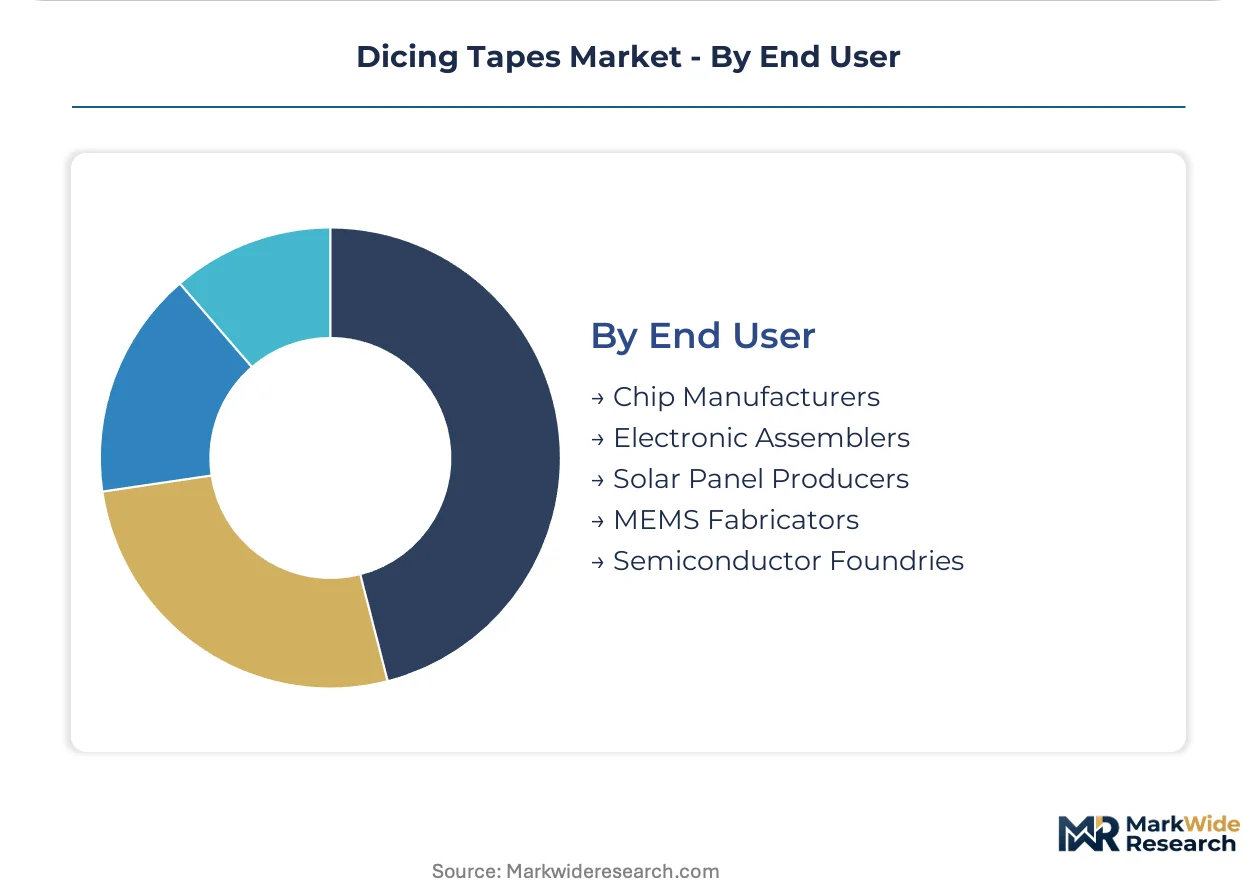
- Semiconductor Foundries:Integrated device manufacturers and pure-play foundries with centralized engineering specification authority, concentrated in Taiwan's Hsinchu-Taichung corridor and South Korea's K-Semiconductor Belt.
- Chip Manufacturers:Fabless design houses with outsourced packaging operations, requiring tape compatibility across multiple OSAT subcontractors.
- MEMS Fabricators:Specialized compound semiconductor and sensor foundries with unique thermal and outgassing requirements under automotive qualification standards.
- Electronic Assemblers:OSAT and contract packaging houses serving fragmented merchant demand with lower volume per qualification.
- Solar Panel Producers:Photovoltaic wafer dicing operations with extreme cost sensitivity and regional concentration in China.
Semiconductor foundries anchor procurement volume. MEMS fabricators show the steepest specification evolution as automotive qualification requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and South Korean buyers absorb UV-curable premiums without volume elasticity, while Chinese solar wafer producers drive thermal-release formulations toward commoditized pricing floors.
Taiwan
Logic foundry concentration in Hsinchu Science Park and Taichung Central Taiwan Science Park sustains premium UV-curable tape procurement. The National Science and Technology Council coordinates industrial park infrastructure expansion. TSMC's advanced packaging nodes anchor specification authority for sub-10-second cure cycle requirements.
South Korea
Samsung Foundry and SK Hynix captive demand in Pyeongtaek and Yongin expands Class 10 cleanroom-compatible adhesive film volume. MFDS chemical substance reporting requirements constrain non-Korean supplier market entry. The K-Semiconductor Belt initiative consolidates procurement through corporate engineering rather than site-level purchasing.
Japan
Automotive MEMS foundries in Toyota City and Hiroshima tighten METI JIS C 60068 outgassing thresholds for electronic materials. Nitto Denko and Lintec backward integration into polyimide substrates reduces foreign supplier penetration. Hybrid acrylic-silicone formulations for power semiconductor grinding command formulation premiums.
China
Photovoltaic wafer dicing operations concentrate cost-optimized thermal release demand under MIIT capacity expansion targets. NMPA chemical substance pre-registration creates compliance thresholds for imported adhesive materials. Domestic foundry buildout under semiconductor self-sufficiency programs shifts GB standard alignment priorities.
United States
Power semiconductor packaging for electric vehicle traction modules drives silicone adhesive chemistry qualification in Arizona and Texas fabs. EPA volatile organic compound emissions regulations affect adhesive manufacturing facility siting decisions. Intel's Ohio and Arizona expansion projects concentrate UV-curable specification authority at corporate engineering levels.
Dicing Tapes Market Key Industry Players
Backward-integrated chemical conglomerates and specialized adhesive film converters split the market along formulation autonomy versus application engineering vectors. The vendor base concentrates among Japanese and South Korean industrial groups with captive polymerization capacity, while North American and European participants compete through distribution partnerships rather than direct foundry qualification. Three archetypes dominate: integrated chemical-materials conglomerates controlling adhesive synthesis, substrate-specialized tape converters with polymer film expertise, and regional distributors serving fragmented OSAT demand. Competitive intensity centers on foundry-level master service agreement consolidation and UV-LED cure system compatibility certification.
Among Japanese industrial groups, Nitto Denko Corporation exemplifies the integrated chemical-materials archetype through adhesive chemistry portfolio breadth, while Lintec Corporation anchors the substrate-specialized converter position through polyimide film backward integration. Furukawa Electric Co., Ltd. occupies a distinct thermal management specialization vector for power semiconductor applications. These three entities collectively represent the premium-tier supply structure that foundry procurement consolidation increasingly favors.
| Leading Market Players |
|---|
| Nitto Denko Corporation |
| Lintec Corporation |
| Furukawa Electric Co., Ltd. |
| Sumitomo Bakelite Co., Ltd. |
| Denka Company Limited |
| Mitsui Chemicals, Inc. |
| AI Technology, Inc. |
| Pantech Tape Co., Ltd. |
| 3M Company |
| Others |
Cost & Logistics Intelligence
The Kaohsiung-Tokyo air freight corridor carries photoinitiator precursors and specialty acrylic monomers with fuel surcharge volatility that amplifies margin compression for non-integrated tape converters while enabling foundry procurement teams to extract tiered pricing concessions based on volume scale and UV-LED compatibility certification.
Pricing Analysis
Aftermarket wafer reclaim service contracts now capture lifetime value exceeding raw tape sales through recurring process engineering fees. Three-tier pricing structure across premium, standard, and economy levels separates UV-curable formulations with sub-10-second cure cycles from thermal-release alternatives and legacy rubber adhesives. Price differentiation hinges on JIS C 60068 outgassing certification grade and foundry-level master service agreement volume scale. Cost compression in thermal-release tiers is intensifying because Chinese photovoltaic producers negotiate spot-market terms for commodity dicing tapes. Solar panel producers exhibit extreme price sensitivity while automotive MEMS foundries in Toyota City absorb formulation premiums for hybrid acrylic-silicone chemistries.
Supply Chain Analysis
Extended payment terms from 60 to 90 days have become standard for foundry procurement teams in Taiwan and South Korea, straining working capital for adhesive converters without captive polymerization capacity. Polyimide film supply draws from Japan and South Korea, acrylic monomer feedstock rests on petrochemical complexes in China and Singapore, and photoinitiator production centers on German and Japanese specialty chemical plants. Single-source vulnerability pervades the polyimide substrate tier where Nitto Denko and Lintec control backward-integrated film supply. Distribution runs through direct foundry engineering relationships rather than merchant distributors, with TSMC and Samsung Foundry negotiating adhesive formulation specifications at corporate headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise for UV-curable adhesives with sub-ppm photoinitiator residue control represents the critical capability gap separating qualified foundry suppliers from commodity converters.
For Market Incumbents: Pre-empt qualification duplication burdens by securing transferable product certifications across multiple foundry spindle configurations before corporate procurement consolidation accelerates. Deepen backward integration into polyimide film substrates to reduce exposure to Japanese polymerization capacity constraints. UV-LED cure system compatibility certification serves as the priority defensive moat against emerging adhesive formulators. For New Entrants and Emerging Players: Pursue NMPA chemical substance pre-registration for China's domestic foundry buildout under MIIT semiconductor self-sufficiency targets before incumbent Japanese suppliers complete GB standard alignment. China's photovoltaic wafer dicing segment offers the most penetrable entry point given extreme cost sensitivity and limited qualification barriers. Lead with water-soluble adhesive formulations for European packaging operations under ECHA substance restrictions as a differentiated sustainability positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors adhesive formulators with in-house analytical chemistry capabilities for radical scavenger elimination and photoinitiator residue control. Long-term viability over the next decade rests on qualification density across Taiwan's Hsinchu-Taichung corridor and South Korea's K-Semiconductor Belt rather than geographic diversification. Watch for UV-LED cure system retrofit announcements at legacy foundries as the inflection signal for accelerated thermal-release displacement.| Strategic Initiative | Industry Significance |
|---|---|
| UV-LED Cure System Certification | Enables sub-10-second tack reduction for TSMC advanced packaging throughput requirements. |
| Backward Integration into Polyimide Film | Captures substrate margin and eliminates single-source vulnerability for tape converters. |
| Automotive Outgassing Certification | Qualifies suppliers for Toyota City MEMS foundries under tightened METI JIS C 60068 thresholds. |
| Reclaim Service Bundling | Shifts revenue from consumable sales to recurring process contracts with foundry customers. |
| China NMPA Pre-Registration | Creates compliance threshold for domestic foundry expansion under MIIT self-sufficiency targets. |
Research Approach
Cross-validation between primary interviews with foundry process engineers, adhesive formulator R&D directors, and OSAT procurement managers anchors the qualitative findings against secondary validation through customs trade data, SEC filings of listed tape manufacturers, JIS standard documentation, and foundry capex disclosure reports. Bottom-up demand modeling from individual fab consumption rates triangulates with top-down market sizing from adhesive precursor shipment volumes.
Calibration against historical UV-curable tape adoption curves in Taiwan's Hsinchu Science Park grounds the projection framework across the analysis window. Segmentation dimensions include adhesive chemistry type, application wafer category, adhesive thickness tier, and end-user procurement authority level. CAGRs derive from foundry capacity expansion schedules and technology node migration patterns for 300mm silicon and silicon carbide wafer processing.
Sensitivities concentrate around UV-LED cure system retrofit timelines at legacy foundries, acrylic monomer feedstock price volatility, and Chinese domestic foundry buildout pace under MIIT targets. Forecasts reflect assumptions on foundry procurement consolidation and heterogeneous integration adoption in MEMS packaging. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Global Specialty Tapes Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Holographic Tear Tape Market
Tapes
Thermal Transfer Tapes Market
Tapes
Europe Packaging Tapes Market
Tapes
Mastic Tapes Market
Tapes
Heat Sealing Tape Market
Tapes
Tape Unwinder Market
Tapes
Pipe Marking Tape Market
Tapes
Tabbing Tapes Market
Tapes
Gummed Tapes Market
Tapes
Asia-Pacific Packaging Tapes Market
Tapes
Tabletop Tape Dispensers Market
Tapes
Paper Masking Tapes Market
Tapes
Flocking Tape Market
Tapes
Vinyl Electrical Tapes Market