
 Breathable Tape Market | 2026-2036
Breathable Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Breathable Tape Market Outlook
Modular packaging configurations for wound care kits is shifting how hospitals and home care buyers evaluate breathable tape procurement, moving toward bundled dressing systems that reduce SKU complexity. 3M Company leverages its adhesive science portfolio to dominate high-performance surgical segments. Smith & Nephew Inc anchors its position through specialized hydrocolloid and silicone-based breathable technologies for chronic wounds. Medline Industries Inc competes on scale, sustaining broad distribution across acute care and long-term care channels with private-label and branded options.
Breathable tape comprises pressure-sensitive adhesive coatings applied to porous backings—nonwoven fabrics, polyurethane films, or silicone layers—that permit moisture vapor transmission while maintaining secure skin adhesion, typically measured by moisture vapor transmission rate (MVTR) exceeding 500 g/m²/24hr for clinical-grade products. Its primary purpose centers on securing dressings, devices, or closures without trapping exudate or causing maceration during extended wear. Medical adhesive products lead volume due to universal surgical and wound care consumption, while sports medicine applications represent the fastest-growing demand pool as athletic participation rises and team medical budgets expand preventive taping programs. Home care end users command expanding margin pools as direct-to-patient channels reduce intermediary costs and shift purchasing authority toward consumers.
FDA biocompatibility standards under ISO 10993, EMA medical device regulations, and Japan's PMDA quality management requirements collectively shape material selection, clinical validation burdens, and market access timelines for breathable tape manufacturers. REACH chemical restrictions in Europe further constrain solvent-based adhesive formulations, accelerating water-based and hot-melt technology transitions. Stakeholders must monitor evolving dermatological safety thresholds and regional notification requirements as skin-sensitivity claims become a primary competitive battleground.
Market Dynamics
Modular wound care kit configurations are restructuring procurement patterns across acute and home care settings, bundling breathable tapes with complementary dressings to reduce SKU complexity and streamline inventory management for hospital supply chains and direct-to-patient distributors.
Growth Catalysts
- ISO 10993 biocompatibility mandates:FDA and EMA tightening of skin-contact adhesive standards is accelerating R&D investment in hypoallergenic silicone and hydrocolloid formulations for extended-wear applications.
- Home care wound management:Aging demographics in Germany, Japan, and the United States are expanding self-treatment populations seeking breathable tape solutions for chronic wound maintenance outside clinical facilities.
- Silicone adhesive technology:Advanced low-trauma silicone coatings enable pain-free removal for fragile skin, penetrating pediatric and geriatric segments previously blocked by acrylic adhesive limitations.
Market Restraints
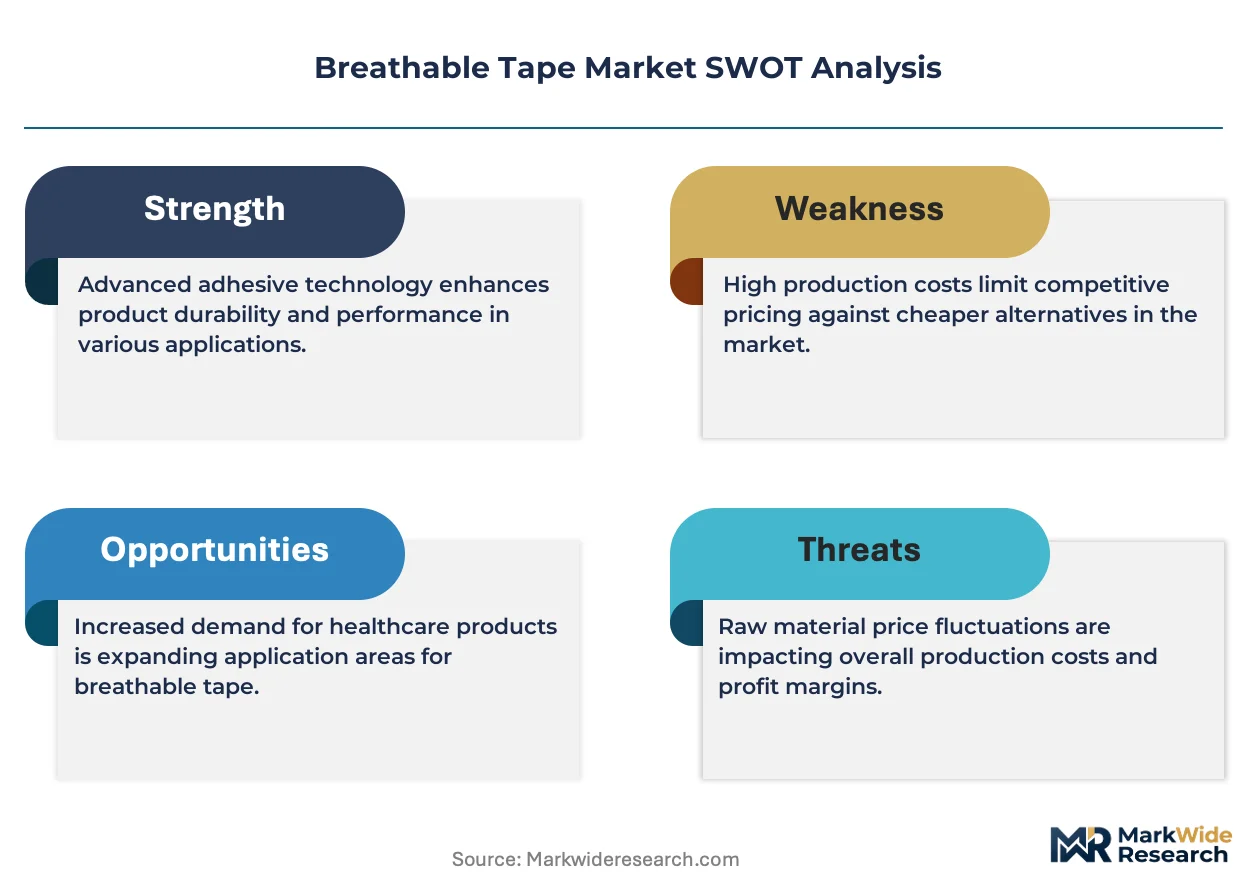
- Petrochemical feedstock volatility:Polyurethane film and synthetic rubber adhesive precursors expose manufacturers to oil price swings that compress margin predictability in quarterly planning cycles.
- REACH solvent restrictions:ECHA chemical regulations are phasing out solvent-based coating processes, forcing capital-intensive conversion to water-based or hot-melt adhesive systems with longer curing timelines.
- Film-substitution pressure:Advanced hydrocolloid and foam dressings with integrated adhesive layers are capturing indications previously served by separate breathable tape products in post-operative care.
Strategic Opportunities
- Direct-to-patient e-commerce channels:Home care consumers in the United States and Germany are bypassing traditional medical supply distributors through Amazon and specialized health platforms, capturing margin pools previously allocated to intermediaries.
- Wearable device integration:Convergence of breathable adhesive technology with continuous glucose monitors and cardiac patches opens sensor-securing applications in diabetes and remote patient monitoring verticals.
- Japan's PMDA fast-track pathway:Accelerated approval mechanisms for innovative wound care materials are shortening market access timelines for novel silicone and hybrid adhesive constructions.
Industry Challenges
- Adhesive polymer formulation expertise:Shortage of chemists specializing in pressure-sensitive adhesive rheology and MVTR optimization constrains product development velocity at mid-tier manufacturers.
- Multi-jurisdiction certification complexity:Simultaneous FDA 510(k), EMA MDR, and PMDA submissions demand dedicated regulatory affairs capacity that stretches emerging market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breathable Tape Market |
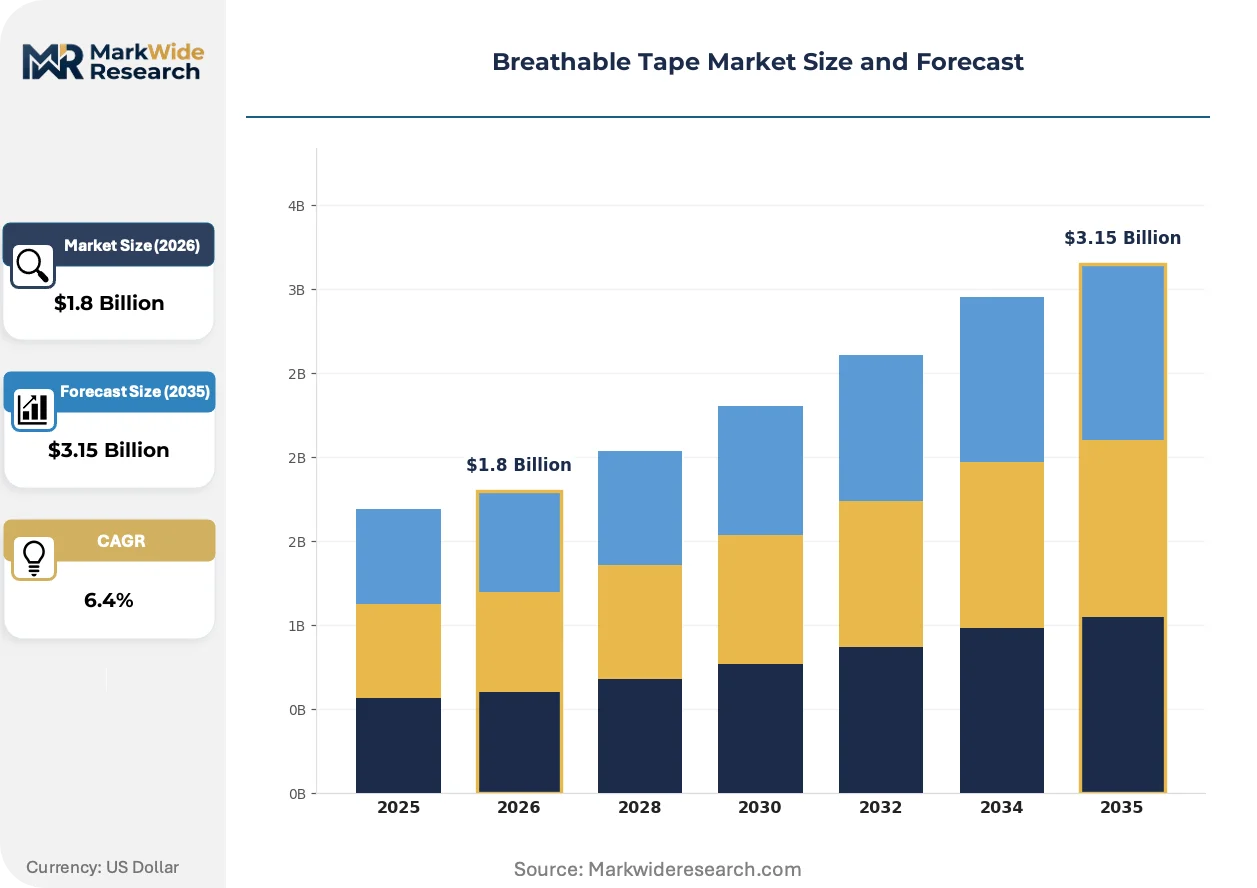
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Adhesive, Sports Tape, Wound Dressing, Surgical Tape Application: First Aid, Sports Medicine, Surgical Procedures, Dermatology End User: Hospitals, Clinics, Athletic Teams, Home Care Distribution Channel: Online Retail, Pharmacies, Medical Supply Stores, Direct Sales |
| Companies Covered | 3M Company, Smith & Nephew Inc, Johnson & Johnson Services Inc, Cardinal Health Inc, Medline Industries Inc, Avery Dennison Corporation, Nitto Denko Corporation, Lohmann GmbH & Co. KG, Paul Hartmann AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breathable Tape Market Strategic Shifts
Adhesive science convergence with digital health infrastructure is redefining performance benchmarks for breathable tape, shifting competitive advantage from basic moisture vapor transmission toward integrated biocompatibility, connectivity compatibility, and wear-time durability.
Silicone-acrylic hybrid adhesive formulations are absorbing the functional requirements previously split between separate product lines, delivering tunable adhesion strength and clean removal characteristics through phase-separated polymer architectures. Surgical departments in German university hospitals are piloting these constructions for 14-day wear protocols in closed-incision management. The technology is absorbing market share from pure acrylic tapes in indications requiring repeated dressing changes.
REACH chemical restrictions under ECHA oversight are eliminating solvent-based coating processes from European manufacturing footprints, compelling adhesive producers to retrofit production lines with hot-melt extrusion or aqueous dispersion systems. Water-based polyurethane dispersions now dominate new capacity investments in Germany and Switzerland. Medical device manufacturers serving EU markets are qualifying alternative adhesive constructions two to three years ahead of formal phase-out deadlines.
Hospital supply chain rationalization is consolidating vendor panels for wound care categories, awarding multi-year contracts to adhesive tape suppliers capable of integrating with electronic procurement platforms and consignment inventory systems. Integrated delivery networks in the United States are replacing fragmented spot purchasing with standardized formularies managed through centralized materials management. Germany's hospital procurement cooperatives are extending this consolidation logic to ambulatory surgery centers and long-term care facilities.
Breathable Tape Market Segmentation
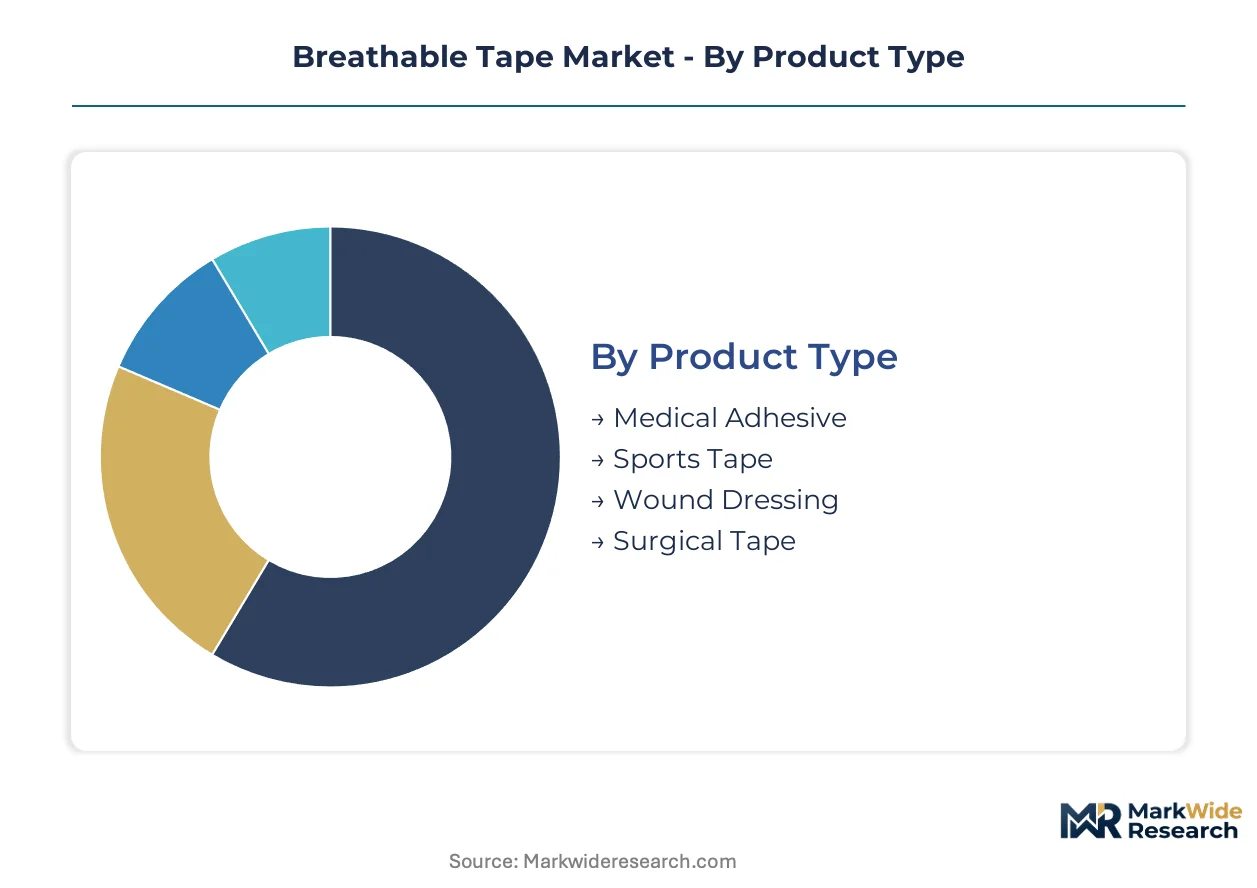
Breathable tape segmentation reveals distinct value capture patterns across standalone consumables versus integrated wound care systems. Product architecture, clinical setting, and procurement channel each reshape margin structures and competitive positioning differently.
Product Type:
Standalone adhesive formats compete against embedded tape layers within advanced dressing systems, with integration depth determining pricing power and customer switching costs.
- Medical Adhesive:Pressure-sensitive acrylic and silicone coatings on porous backings deliver moisture vapor transmission rates exceeding 500 g/m²/24hr for clinical-grade fixation. Hospital procurement panels in Germany and the United States consolidate purchasing around suppliers offering electronic data interchange compatibility and consignment inventory programs.
- Wound Dressing:Hydrocolloid and silicone-based breathable constructions integrate absorbent layers with adhesive borders for exudate management in chronic wound protocols. Aging populations in Japan and Germany drive self-managed home care applications, bypassing traditional distributor markups through direct-to-patient channels.
- Sports Tape:Elastic cotton or synthetic fabric backings with zinc oxide adhesives support athletic taping for injury prevention and joint stabilization.
- Surgical Tape:Hypoallergenic paper or transparent film constructions secure drapes, tubing, and primary closures in operating room environments.
Medical Adhesive leads volumes today; Wound Dressing is gaining share fastest.
Application:
Clinical acuity tiers separate acute intervention sites from preventive and maintenance settings, with reimbursement intensity tracking procedure invasiveness.
- Surgical Procedures:Operating room applications demand sterile, latex-free constructions with validated biocompatibility under ISO 10993 standards for extended skin contact. FDA 510(k) clearance timelines and EMA MDR conformity assessments create regulatory moats that favor established adhesive science portfolios.
- Sports Medicine:Team physician and athletic trainer protocols emphasize rapid application, sweat resistance, and pain-free removal for repeated taping cycles. Rising athletic participation rates and expanded preventive care budgets in United States collegiate and professional programs fuel volume expansion.
- First Aid:Consumer-oriented formats prioritize convenience and shelf stability for emergency supply kits and workplace safety compliance.
- Dermatology:Fragile-skin applications require low-trauma silicone adhesives validated for pediatric and geriatric populations with compromised epidermal integrity.
Surgical Procedures commands the largest revenue pool; Sports Medicine shows the steepest expansion trajectory.
End User:
Facility scale and purchasing authority concentration determine contract structures, with integrated delivery networks extracting volume discounts unavailable to fragmented buyers.
- Hospitals:Centralized materials management and standardized formularies across United States integrated delivery networks consolidate vendor panels. Multi-year agreements reward suppliers with consignment inventory capabilities and spend analytics integration.
- Home Care:Direct-to-patient purchasing through Amazon and specialized health platforms captures margin pools previously allocated to medical supply distributors. Germany's ambulatory care expansion and Japan's aging-in-place policies accelerate self-managed wound maintenance outside clinical facilities.
- Clinics:Outpatient wound care centers and dermatology practices favor flexible ordering quantities and rapid restock logistics.
- Athletic Teams:Professional and collegiate sports organizations negotiate equipment supply contracts with adhesive tape bundled into broader medical kit procurement.
Hospitals dominate absolute consumption; Home Care is climbing the fastest.
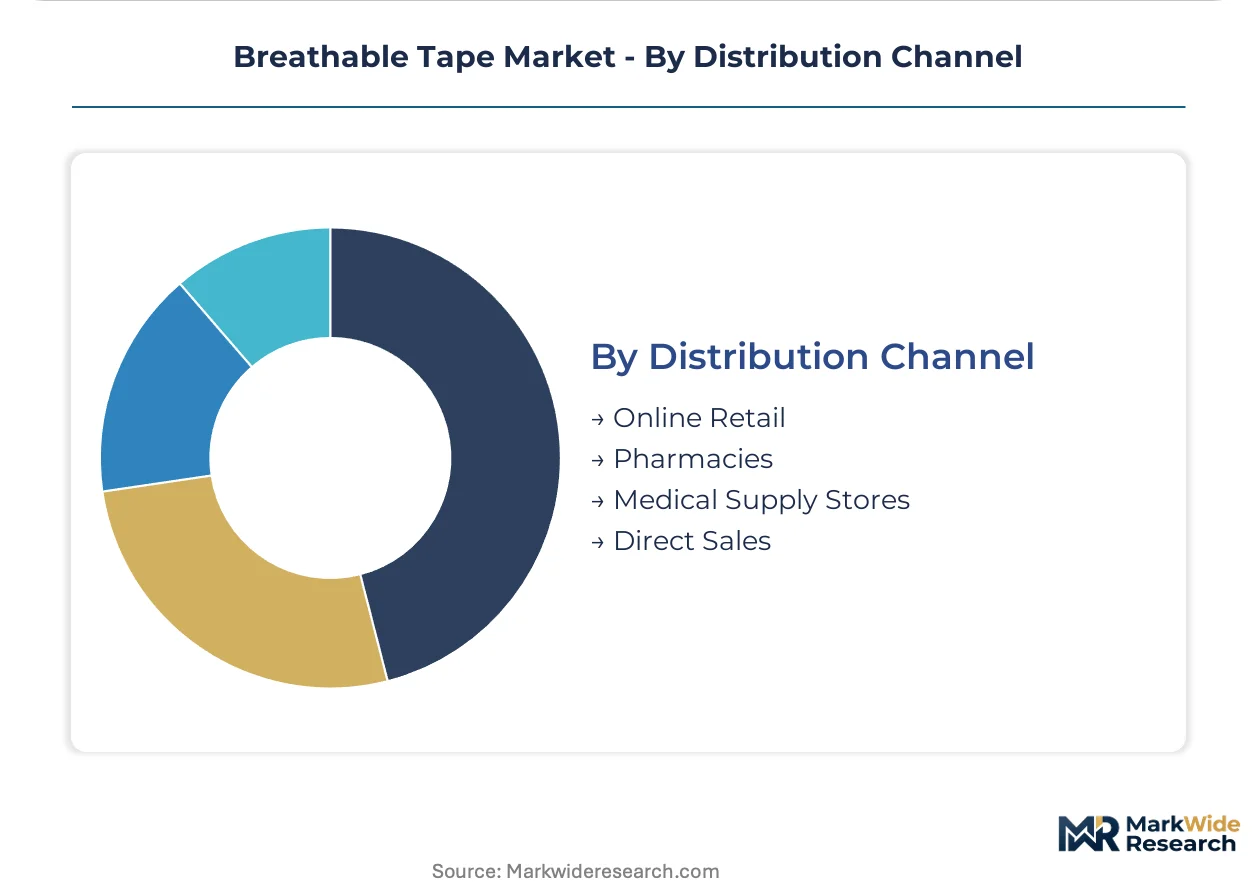
Distribution Channel:
Channel selection reflects buyer sophistication and urgency requirements, with digital penetration reshaping traditional medical supply economics.
- Online Retail:Amazon and specialized health platforms enable price transparency and subscription replenishment for chronic wound patients. Germany and United States consumers bypass distributor markups, compressing margins for traditional medical supply intermediaries.
- Direct Sales:Manufacturer field forces serve large hospital systems with customized formulary development and clinical education support. EMA MDR technical documentation requirements and FDA quality system regulations favor direct relationships for complex product qualifications.
- Pharmacies:Community and hospital outpatient dispensaries handle acute need purchases and prescription-integrated wound care recommendations.
- Medical Supply Stores:Independent durable medical equipment dealers serve long-term care facilities and home health agencies with relationship-based service models.
Direct Sales retains the highest value per transaction; Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The breathable tape industry traces its commercial origins to mid-20th century adhesive science developments in the United States and Germany, where surgical-grade pressure-sensitive tapes first achieved standardized moisture vapor transmission rates for clinical applications.
United States
Integrated delivery networks in Texas and California consolidate purchasing through centralized materials management, extracting volume discounts from adhesive tape suppliers. FDA 510(k) clearance pathways for silicone-acrylic hybrid constructions create regulatory moats favoring established manufacturers with dedicated regulatory affairs capacity. Minneapolis-St. Paul hosts concentrated adhesive science R&D clusters where major medical device manufacturers qualify next-generation constructions for 14-day wear protocols.
Germany
Hospital procurement cooperatives across Bavaria and North Rhine-Westphalia extend vendor panel consolidation to ambulatory surgery centers and long-term care facilities. REACH solvent restrictions under ECHA oversight eliminate solvent-based coating processes, compelling producers in Baden-Württemberg to retrofit production lines with hot-melt extrusion systems. The Rhine-Main industrial corridor concentrates water-based polyurethane dispersion capacity investments ahead of formal phase-out deadlines.
Japan
Aging-in-place policies accelerate self-managed wound maintenance outside clinical facilities, expanding direct-to-patient demand for chronic wound applications. PMDA fast-track approval mechanisms for innovative wound care materials shorten market access timelines for novel silicone constructions. The Kansai region around Osaka maintains specialized manufacturing clusters for hydrocolloid and silicone-based breathable technologies serving domestic and export markets.
United Kingdom
NHS supply chain rationalization consolidates wound care vendor panels, awarding multi-year contracts to suppliers with electronic procurement platform compatibility. MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR technical documentation requirements while streamlining conformity assessment procedures. The East Midlands medical technology cluster houses specialized converters serving NHS trusts with customized formulary development.
China
Domestic hospital procurement reforms centralize purchasing authority for high-value medical consumables at provincial levels, compressing margins for imported adhesive tape brands. NMPA medical device registration requirements for skin-contact adhesives mandate biocompatibility testing under GB/T 16886 standards. The Yangtze River Delta manufacturing belt concentrates contract production capacity for water-based adhesive coatings serving both domestic consumption and export markets.
Breathable Tape Market Competitive Environment
The competitive structure tilts toward diversified adhesive science portfolios rather than pure-play medical specialists. Three tiers emerge: multinational conglomerates with cross-industry adhesive platforms, mid-scale medical device specialists with wound care focus, and regional converters serving local procurement channels. Consolidation pressure intensifies as hospital supply chains demand integrated data interchange capabilities and consignment inventory systems. Strategic moves center on qualifying hybrid silicone-acrylic formulations for extended-wear indications and retrofitting European manufacturing assets for REACH-compliant water-based coating processes.
Among diversified technology conglomerates, 3M Company and Nitto Denko Corporation anchor positions through broad adhesive science portfolios spanning industrial, electronics, and medical verticals. Smith & Nephew Inc and Paul Hartmann AG exemplify the medical-specialist archetype, occupying positions defined by chronic wound care expertise and European market penetration. Medline Industries Inc represents the scale-driven distributor-converter model, sustaining broad channel coverage across acute and long-term care settings through private-label and branded options. Johnson & Johnson Services Inc and Cardinal Health Inc leverage integrated healthcare supply chain positions to secure formulary placement within United States hospital networks.
| Leading Market Players |
|---|
| 3M Company |
| Smith & Nephew Inc |
| Johnson & Johnson Services Inc |
| Cardinal Health Inc |
| Medline Industries Inc |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| Lohmann GmbH & Co. KG |
| Paul Hartmann AG |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap adhesive specialists in Germany and Japan anchor premium-tier pricing discipline through captive silicone polymer production, while private-equity-rolled-up distributors in the United States compress standard-tier margins through volume aggregation and formulary consolidation. This ownership bifurcation creates divergent supply behaviors: European and Japanese producers defend price premiums through ISO 10993 certification investments, while American intermediaries extract supplier concessions via multi-year hospital system contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates silicone-acrylic hybrid constructions validated for 14-day wear from commodity acrylic tapes and private-label alternatives. Price differentiation rests on FDA 510(k) clearance status and MVTR performance certification, with German and Japanese buyers least sensitive and American GPO-aggregated procurement most sensitive. Cost compression in standard-tier products is intensifying because REACH-compliant water-based coating retrofits raise fixed costs without commensurate performance gains.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian and Thai petrochemical feedstock suppliers for polyurethane film precursors. Manufacturing concentrates in Germany, the United States, and Japan, drawing from medical-grade nonwoven fabric inputs, silicone polymer resins, and pressure-sensitive adhesive coatings. Tariff exposure on Chinese-sourced raw materials threatens margin stability at mid-tier converters. Distribution runs through hospital procurement cooperatives, direct-to-patient e-commerce platforms, and specialized medical supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in breathable tape hinges on silicone-acrylic hybrid formulations capturing extended-wear premiums, while REACH compliance investments filter out sub-scale competitors unable to amortize water-based coating line retrofits.
For Market Incumbents: Deploy backward integration into silicone polymer production to secure supply continuity and defend margin position against petrochemical price volatility. Incumbents must accelerate PMDA fast-track submissions in Japan before mid-tier competitors qualify comparable constructions, while consolidating European manufacturing footprints to capture REACH phase-out consolidation benefits. For New Entrants and Emerging Players: Sensor-securing applications for continuous glucose monitors and cardiac patches offer the most penetrable white-space opportunity, bypassing entrenched hospital formulary relationships entirely. New entrants should target direct-to-patient channels in Germany and the United States with subscription replenishment models for chronic wound maintenance, leveraging Amazon and specialized health platforms to circumvent distributor markups. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European adhesive converters facing REACH retrofit capital demands without balance sheet capacity. Long-term viability favors targets with qualified silicone-acrylic hybrid portfolios and existing PMDA or FDA regulatory dossiers. The signal to watch is consolidation velocity among German hospital procurement cooperatives, which will determine whether scale or specialization wins formulary placement.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone-Acrylic Hybrid Formulation Development | Captures 14-day wear premiums in German university hospital pilots and displaces pure acrylic tapes. |
| Water-Based Coating Line Retrofit | Secures REACH compliance ahead of ECHA solvent phase-out deadlines and filters sub-scale competitors. |
| PMDA Fast-Track Submission | Accelerates market access timelines for novel adhesive constructions in Japan's aging-in-place wound care sector. |
| Direct-to-Patient E-Commerce Launch | Bypasses distributor markups in American and German home care markets through Amazon and health platforms. |
| Hospital System Partnership | Locks in multi-year formulary placement with integrated delivery networks requiring EDI compatibility and consignment inventory. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with adhesive R&D directors, hospital procurement managers, GPO contracts specialists, and regulatory affairs leads at major medical device manufacturers with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, PMDA approval databases, and hospital procurement cooperative contract disclosures. Bottom-up segment sizing and top-down market reconciliation ensured cross-verification across the analysis window.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions including product architecture (standalone versus integrated dressing systems), clinical setting (acute versus home care), adhesive chemistry (acrylic, silicone, hybrid), and procurement channel (direct sales, online retail, distributor). CAGRs derived from trend extrapolation moderated by regulatory event timelines and raw material cost assumptions, with silicone polymer price trajectories and REACH compliance investment cycles as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility, REACH enforcement intensity, and PMDA fast-track pathway modifications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Removal Strips Market
Tapes
Labels, Tapes and Films Market
Tapes
Spacer Tapes Market
Tapes
Metal Foil Tapes Market
Tapes
Raffia Tape Stretching Line Market
Tapes
Global Pressure Sensitive Tapes Market
Tapes
Correction Tapes Market
Tapes
India Masking Tapes Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Sterilization Tape Market
Tapes
Glue Tape Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Tape Stretching Line Market
Tapes
Hydrocolloid Tapes Market
Tapes
Foam Tape Market