
 United States End-Of-Line Packaging Tape Market | 2026-2036
United States End-Of-Line Packaging Tape Market Size, Share, and Industry Trends Forecast 2026-2036
United States End-Of-Line Packaging Tape Market Outlook
Buyer concentration among third-party logistics providers and mega-fulfillment networks is pivoting procurement toward long-term supply contracts with technical service riders. 3M leverages its materials science portfolio to sustain premium positioning in automated sealing environments. Shurtape Technologies, LLC anchors its competitive stance through specialized hot-melt formulations engineered for high-speed corrugated lines. Berry Global Inc. competes by controlling wide-format BOPP film supply chains that feed captive tape converting operations.
End-of-line packaging tape denotes pressure-sensitive or water-activated adhesive strips applied at carton sealing stations, typically manufactured from polypropylene films or reinforced paper backings coated with synthetic rubber or acrylic emulsions, designed to maintain closure integrity through distribution stresses. BOPP tape dominates volume flows due to its balance of tensile strength and cost efficiency in high-velocity automated environments. Water-activated tape occupies specialized niches where tamper evidence and fiber-reinforced security justify slower application speeds and higher unit costs. Pressure-sensitive acrylic formulations are gaining share in cold-chain pharmaceutical applications where temperature cycling degrades conventional rubber adhesives.
FDA regulations on indirect food contact materials shape substrate and adhesive selections for tape deployed in food and beverage end-of-line operations, while EPA guidelines on volatile organic compound emissions constrain solvent-based coating processes at domestic manufacturing facilities. California's Department of Toxic Substances Control maintains additional reporting requirements for adhesive formulations containing designated chemicals. Stakeholders must monitor how state-level extended producer responsibility frameworks migrate toward packaging adhesives and backing materials.
Market Dynamics
E-commerce fulfillment networks are compressing procurement cycles and demanding adhesive formulations that perform across automated sealing lines without line stoppages. This operational pressure is restructuring supplier relationships toward technical service partnerships.
Growth Catalysts
- California SB 54 Extended Producer Responsibility:The state's packaging waste law is mandating recyclable substrates and pressuring converters toward mono-material tape constructions compatible with existing recycling streams.
- Automated Corrugated Lines:High-speed carton sealing equipment in Great Lakes manufacturing corridors requires hot-melt adhesives with precise tack windows and shear resistance at elevated line speeds.
- Cold-Chain Pharmaceutical Distribution:Temperature cycling through frozen and ambient zones degrades conventional rubber adhesives, creating pull for acrylic emulsion formulations with stable viscosity profiles.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene film and synthetic rubber adhesive costs fluctuate with propylene and butadiene spot markets, compressing converter margins during price spike periods.
- Midwest Tape Converting Concentration:A significant share of domestic BOPP slitting and coating capacity clusters in Ohio and Indiana, creating geographic supply risk during regional weather disruptions or logistics bottlenecks.
- Water-Activated Tape Speed Limitations:Fiber-reinforced gummed tapes require activation dwell time incompatible with the fastest automated lines, restricting penetration beyond security-sensitive applications.
Strategic Opportunities
- Southeast Distribution Hub Expansion:Georgia and South Carolina fulfillment center construction is outpacing regional tape supply infrastructure, opening territory for localized converting operations.
- FDA Food Contact Compliance:Indirect food contact tape certifications for adhesives and backings unlock penetration into beverage multipack and produce crate sealing applications.
- Hot-Melt and Acrylic Hybrid Formulations:Convergence of pressure-sensitive convenience with water-activated tamper evidence creates premium positioning for security-focused e-commerce parcel segments.
Industry Challenges
- Adhesive Chemist Talent Scarcity:Formulation expertise spanning synthetic rubber, hot-melt, and acrylic chemistries concentrates among aging specialists with limited pipeline replacement.
- California DTSC Reporting Burden:Designated chemical disclosure requirements for adhesive formulations add compliance overhead and disclosure risk for multi-state suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States End-Of-Line Packaging Tape Market |
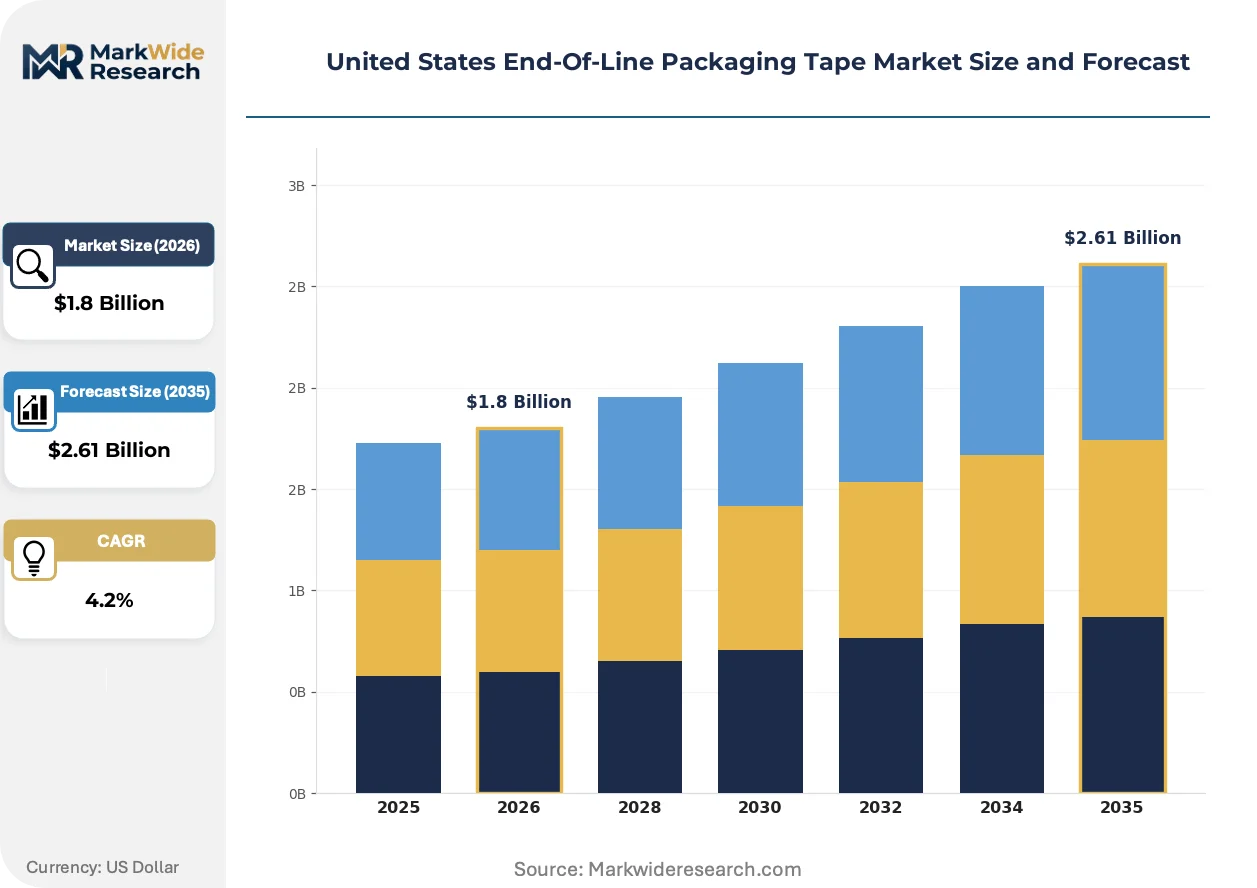
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Tape, Water-Activated Tape, PVC Tape, BOPP Tape End User: Food & Beverage, Electronics, Pharmaceuticals, Consumer Goods Thickness: Thin, Medium, Thick, Extra Thick Distribution Channel: Online Retail, Wholesale Distributors, Direct Sales, Specialty Stores |
| Companies Covered | 3M, Can-Do National Tape, Pro Tapes & Specialties Inc., U.S. Packaging & Wrapping LLC, Tesa Tape, Inc., Berry Global Inc., SWM International, Avery Dennison Corporation, Shurtape Technologies, LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States End-Of-Line Packaging Tape Market Strategic Shifts
Adhesive formulation science and substrate engineering are converging to address the tension between automated line speed demands and emerging sustainability mandates. Technical differentiation is migrating from raw tape performance to integration with sealing equipment intelligence.
Water-activated tape reinforced with fiberglass filaments is absorbing security-sensitive applications in high-value e-commerce and pharmaceutical distribution where carton integrity evidence outweighs speed requirements. Third-party logistics providers serving luxury goods and electronics verticals are adopting these formulations despite 40-60% throughput penalties versus pressure-sensitive alternatives. The technology is absorbing share from standard BOPP in segments where freight pilferage risk justifies operational friction.
EPA volatile organic compound emission guidelines are constraining solvent-based coating processes at domestic manufacturing facilities, pushing investment toward hot-melt and emulsion coating infrastructure. This regulatory pressure is elevating capital requirements for new market entrants and favoring incumbents with existing aqueous capacity. Food and beverage end-of-line operations face additional substrate scrutiny under FDA indirect food contact material regulations, particularly for tapes deployed in refrigerated distribution.
Buyer concentration among mega-fulfillment networks is consolidating purchasing authority and compressing supplier rosters toward partners offering line integration support and predictive inventory programs. Regional distributors serving mid-tier manufacturers are losing share to direct mill relationships as procurement functions centralize. This pattern is most visible in the Southwest where Arizona and Texas distribution hub construction has attracted dedicated technical service teams from major suppliers.
United States End-Of-Line Packaging Tape Market Segmentation
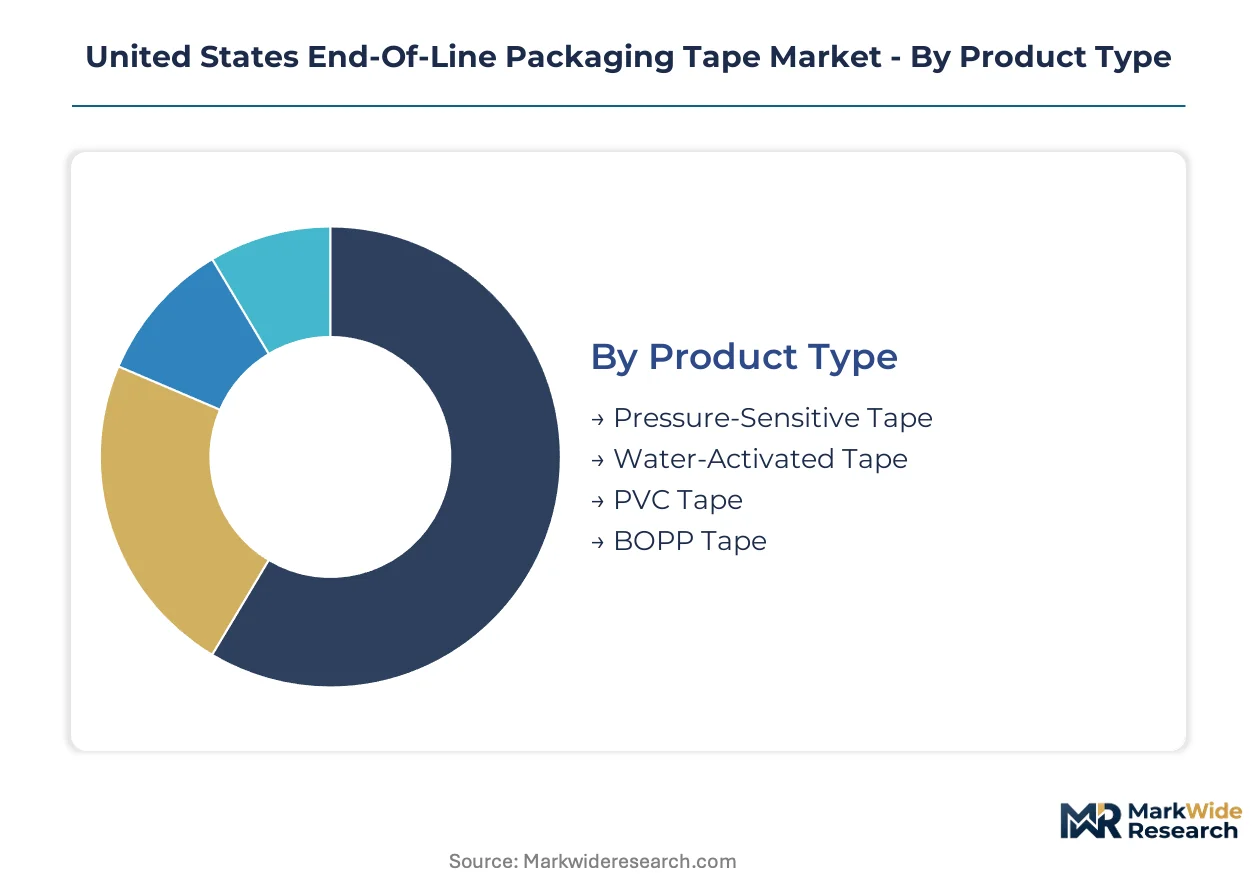
Segmentation in the United States end-of-line packaging tape market reveals how substrate chemistry, adhesive technology, and distribution economics align with distinct operational requirements across automated sealing environments. Procurement patterns diverge sharply between high-velocity corrugated lines and security-sensitive applications, driving specialized supplier relationships.
Product Type:
Upgrade cycles in automated sealing equipment are displacing legacy formulations as line speeds climb and California's SB 54 recyclability mandates force substrate redesigns.
- BOPP Tape:Biaxially oriented polypropylene film coated with hot-melt or acrylic adhesives delivers the tensile strength and cost efficiency required by Great Lakes automotive and appliance OEMs running high-velocity lines. Demand concentrates in Ohio and Indiana converting clusters where captive film supply chains feed automated sealing operations at major fulfillment networks.
- Pressure-Sensitive Tape:Synthetic rubber or acrylic emulsion adhesives on polypropylene or PVC backings enable immediate bonding without activation dwell time, suiting the compressed procurement cycles of third-party logistics providers. Cold-chain pharmaceutical distributors in the Northeast are pivoting toward acrylic formulations as temperature cycling degrades conventional rubber adhesives through frozen and ambient zones.
- Water-Activated Tape:Fiber-reinforced gummed paper tapes with starch-based adhesives require moisture activation and brief dwell periods before bonding, creating tamper-evident seals valued in high-value e-commerce and luxury goods distribution despite throughput penalties.
- PVC Tape:Polyvinyl chloride film backings with rubber-based adhesives offer conformability around irregular carton geometries and resistance to moisture ingress, serving produce crate and beverage multipack applications where FDA indirect food contact compliance shapes adhesive selection.
BOPP tape sits at the top of the volume ranking, with pressure-sensitive acrylic formulations climbing the fastest as cold-chain pharmaceutical distribution expands.
End User:
Cost tier differentiation separates commodity sealing operations from premium applications where regulatory compliance and security features justify unit price premiums.
- Food & Beverage:FDA indirect food contact regulations constrain adhesive and substrate selections for tapes deployed in refrigerated distribution of produce crates and beverage multipacks, favoring PVC and compliant BOPP constructions over standard formulations.
- Pharmaceuticals:Temperature cycling through frozen and ambient distribution zones degrades conventional rubber adhesives, creating demand pull for acrylic emulsion tapes with stable viscosity profiles across thermal extremes in cold-chain networks.
- Electronics:Anti-static formulations and clean-release adhesives prevent particulate contamination of sensitive components, with procurement concentrated among fulfillment centers serving high-value consumer electronics verticals.
- Consumer Goods:High-volume corrugated sealing operations prioritize cost efficiency and line speed compatibility, driving consolidation toward hot-melt BOPP tapes in mass-market e-commerce fulfillment.
Food and beverage applications dominate volume flows, with pharmaceutical end-use expanding most quickly as cold-chain infrastructure proliferates.
Thickness:
Application severity and carton weight determine thickness selection, with medium gauges capturing the bulk of standard corrugated operations while extreme gauges serve specialized stress environments.
- Medium:The standard specification for general-purpose carton sealing balances material cost with adequate tensile strength for typical distribution stresses, dominating procurement across e-commerce fulfillment networks.
- Thick:Reinforced constructions with elevated adhesive mass support heavy-duty applications including appliance and automotive component packaging in Great Lakes manufacturing corridors.
- Thin:Reduced gauge tapes serve lightweight consumer goods and promotional packaging where carton integrity requirements are modest and material cost minimization drives selection.
- Extra Thick:Heavy-duty reinforced tapes with fiberglass or filament cores absorb extreme tensile loads in export shipping and hazardous materials containment where seal failure carries regulatory or liability exposure.
Medium thickness commands the largest share of unit volume, with thick gauges gaining share fastest as automotive and appliance OEMs expand packaging operations.
Distribution Channel:
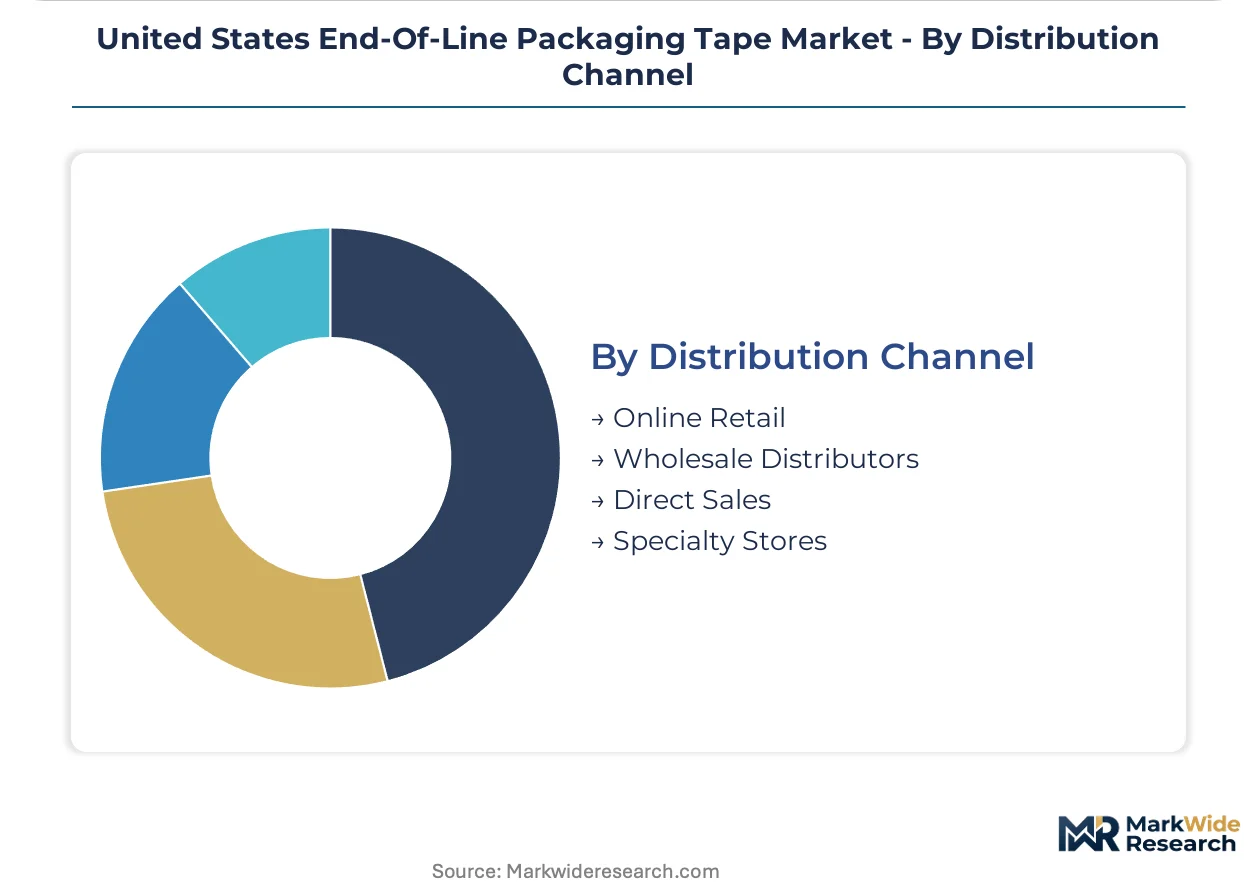
Customer scale and technical service requirements fragment channel strategy, with mega-fulfillment networks bypassing intermediaries while mid-tier manufacturers rely on distributor relationships.
- Wholesale Distributors:Regional inventory positioning and technical support services sustain relevance among mid-tier manufacturers lacking procurement scale for direct mill relationships, particularly in Southeast markets where distribution hub construction outpaces localized converting capacity.
- Direct Sales:Mega-fulfillment networks and third-party logistics providers with concentrated volume leverage long-term supply contracts with technical service riders, consolidating purchasing authority and compressing supplier rosters.
- Online Retail:E-procurement platforms serve spot purchasing needs and small-volume users with limited technical requirements, capturing share among startup e-commerce operations and seasonal demand spikes.
- Specialty Stores:Localized availability of niche formulations including water-activated and extra-thick reinforced tapes supports security-sensitive applications and emergency replenishment for operations with limited inventory carrying capacity.
Wholesale distributors retain the largest volume channel position, with direct sales climbing the fastest as buyer concentration among mega-fulfillment networks accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates North American end-of-line packaging tape consumption through its dense e-commerce fulfillment infrastructure, while Canada maintains a secondary position focused on cold-chain distribution networks serving resource extraction and pharmaceutical verticals.
California
SB 54 extended producer responsibility mandates are forcing converters toward mono-material tape constructions compatible with existing recycling streams. The California Department of Toxic Substances Control imposes additional reporting requirements on adhesive formulations containing designated chemicals. Los Angeles Basin fulfillment centers are absorbing specialized hot-melt formulations engineered for automated sealing lines running at elevated speeds.
Great Lakes Manufacturing Corridor
Automotive and appliance OEMs in Ohio and Indiana maintain high-volume packaging operations demanding thick-gauge reinforced tapes with elevated adhesive mass. EPA volatile organic compound emission guidelines constrain solvent-based coating processes at domestic manufacturing facilities clustered around Cleveland and Indianapolis. Detroit-area automotive component suppliers are expanding tape consumption as just-in-sequence packaging requirements tighten.
Southeast Distribution Hub Expansion
Georgia and South Carolina fulfillment center construction is outpacing regional tape supply infrastructure, opening territory for localized converting operations. FDA indirect food contact regulations shape adhesive selections for tapes deployed in refrigerated distribution of produce crates through Atlanta and Charleston ports. Savannah logistics corridors are attracting dedicated technical service teams from major suppliers seeking direct mill relationships with mega-fulfillment networks.
Northeast Cold-Chain Pharmaceutical Corridor
Temperature cycling through frozen and ambient distribution zones degrades conventional rubber adhesives, creating demand pull for acrylic emulsion tapes with stable viscosity profiles. FDA regulations on indirect food contact materials extend to pharmaceutical packaging adhesives through Newark and Philadelphia distribution hubs. Boston-area biologics distributors are consolidating procurement toward partners offering line integration support and predictive inventory programs.
Southwest Border Manufacturing
Texas distribution hub construction in Dallas-Fort Worth and Houston is compressing procurement cycles for adhesive formulations performing across automated sealing lines. OSHA workplace safety standards intersect with EPA emission guidelines at coating facilities serving cross-border maquiladora supply chains. El Paso and Laredo logistics corridors are absorbing pressure-sensitive acrylic formulations as cold-chain pharmaceutical distribution proliferates regionally.
United States End-Of-Line Packaging Tape Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the United States end-of-line packaging tape market. Materials science conglomerates leverage captive polymer supply chains and cross-divisional technology transfer to sustain premium positioning in automated sealing environments. Specialized adhesive formulators anchor competitive stances through hot-melt and acrylic chemistries engineered for high-velocity corrugated lines. The dominant competitive moves involve backward integration into BOPP film supply and geographic expansion toward Southeast distribution hubs.
Among diversified materials conglomerates, 3M exemplifies the science-driven archetype through its materials science portfolio spanning adhesive formulations and substrate engineering. Berry Global Inc. occupies a position within the integrated film-to-tape supply chain model, controlling wide-format BOPP film supply chains that feed captive converting operations. Shurtape Technologies, LLC represents the specialized adhesive formulator archetype, with its LLC structure indicating focused operational scope on tape-specific manufacturing.
| Leading Market Players |
|---|
| 3M |
| Can-Do National Tape |
| Pro Tapes & Specialties Inc. |
| U.S. Packaging & Wrapping LLC |
| Tesa Tape, Inc. |
| Berry Global Inc. |
| SWM International |
| Avery Dennison Corporation |
| Shurtape Technologies, LLC |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up tape specialists in the Ohio-Indiana corridor exercise disciplined capacity management that anchors pricing floors for hot-melt BOPP formulations. Their consolidated slitting and coating assets limit spot-market volatility transmission to contract buyers while California's SB 54 recyclability mandates force substrate redesign costs onto premium-tier quotations.
Pricing Analysis
Capacity additions in Georgia and South Carolina are reshaping price floors for pressure-sensitive acrylic tapes as localized converting operations challenge Midwest supply premiums. Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant food-contact formulations from commodity hot-melt grades, with certification tier and volume scale as primary differentiation drivers. Cost compression in standard BOPP intensifies because petrochemical feedstock volatility squeezes converter margins during propylene spike periods. Third-party logistics providers exhibit highest price sensitivity, while cold-chain pharmaceutical distributors accept premium acrylic pricing for temperature-stable viscosity profiles.
Supply Chain Analysis
Reverse-logistics flows for tape roll cores and liner scrap remain underdeveloped, creating latent cost recovery opportunities for converters investing in closed-loop substrate programs. Raw material supply draws from Saudi Arabian and Qatari polypropylene resin producers, South Korean BOPP film extruders, and domestic synthetic rubber adhesive compounders in Texas and Louisiana. Single-source vulnerability concentrates in wide-format BOPP film supply where Berry Global's captive production limits third-party access. Distribution runs through regional wholesale distributors serving mid-tier manufacturers, with direct mill relationships capturing mega-fulfillment network volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States end-of-line packaging tape market functions as a stable compounder anchored by e-commerce fulfillment center expansion that generates recurring adhesive consumption across automated sealing infrastructure.
For Market Incumbents: Cement technical service partnerships with Southeast distribution hub operators before regional converting capacity saturates. Defend against acrylic formulation specialists by securing captive BOPP film supply through backward integration into extrusion assets. Prioritize California DTSC compliance infrastructure to preempt disclosure risk from adhesive chemist talent scarcity. For New Entrants and Emerging Players: California SB 54 opens a window for mono-material tape constructions compatible with existing recycling streams, targeting food and beverage multipack applications where FDA indirect food contact certifications create barrier-to-entry value. Focus white-space capture on water-activated tape niches serving high-value e-commerce security segments. Pursue line integration support capabilities as primary go-to-market differentiation against commodity distributors. For Investors and Strategic Acquirers: Valuations sit cheapest among regional wholesale distributors losing share to direct mill relationships, offering roll-up platforms with embedded technical service infrastructure. Five-to-ten-year viability rests on adhesive formulation expertise pipeline replacement and geographic repositioning toward Southeast hub construction. Monitor Georgia and South Carolina fulfillment center absorption rates as inflection indicator for localized converting demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into BOPP Film Extrusion | Captive resin supply secures margin stability against propylene spot market volatility. |
| Hot-Melt and Acrylic Hybrid Formulation Development | Convergence technologies capture premium positioning in security-focused e-commerce segments. |
| Southeast Distribution Hub Technical Service Expansion | Direct mill relationships with Georgia fulfillment centers compress regional distributor relevance. |
| FDA Indirect Food Contact Certification Investment | Regulatory compliance unlocks beverage multipack and produce crate sealing applications. |
| Closed-Loop Substrate Recycling Program Implementation | California SB 54 alignment converts compliance cost into competitive differentiation. |
Study Parameters
Multiple input streams — tape converter production data, e-commerce fulfillment center procurement records, and petrochemical feedstock pricing indices — were reconciled through bottom-up and top-down triangulation. Primary interviews with adhesive formulation chemists, corrugated line maintenance engineers, third-party logistics procurement directors, and FDA regulatory affairs specialists were validated against secondary sources including EPA emission compliance filings, California DTSC designated chemical disclosures, and customs trade data on polypropylene resin imports.
Data-stream reconciliation across product type, adhesive chemistry, end-use industry, and regional distribution channel dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by automotive OEM packaging intensity, pharmaceutical cold-chain expansion, and SB 54 recyclability compliance timelines. Forecast inputs incorporated automated line speed specifications and hot-melt adhesive tack window requirements.
Revisions become necessary when California extends producer responsibility frameworks to packaging adhesives, petrochemical feedstock volatility exceeds historical bands, or Southeast distribution hub construction stalls. Practitioners should monitor adhesive chemist retirement rates and Georgia fulfillment center absorption metrics for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Freezer Tape Market
Tapes
Umbilical Tapes Market
Tapes
Moisture Barrier Tapes Market
Tapes
Foam Tape Market
Tapes
Aluminum Foil Tape Market
Tapes
Tape Unwinder Market
Tapes
Tapes Market
Tapes
Raffia Tape Stretching Line Market
Tapes
Carton Sealing Tape Market
Tapes
Application Tapes Market
Tapes
Thermoplastic Tape Market
Tapes
Tape Stretching Line Market
Tapes
Spacer Tapes Market
Tapes
Non Woven Water Blocking Tape Market
Tapes
Raffia Tapes Market
Tapes
Strapping Tapes Market