
 Tape and Label Adhesives Market | 2026-2036
Tape and Label Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Tape and Label Adhesives Market Analytics
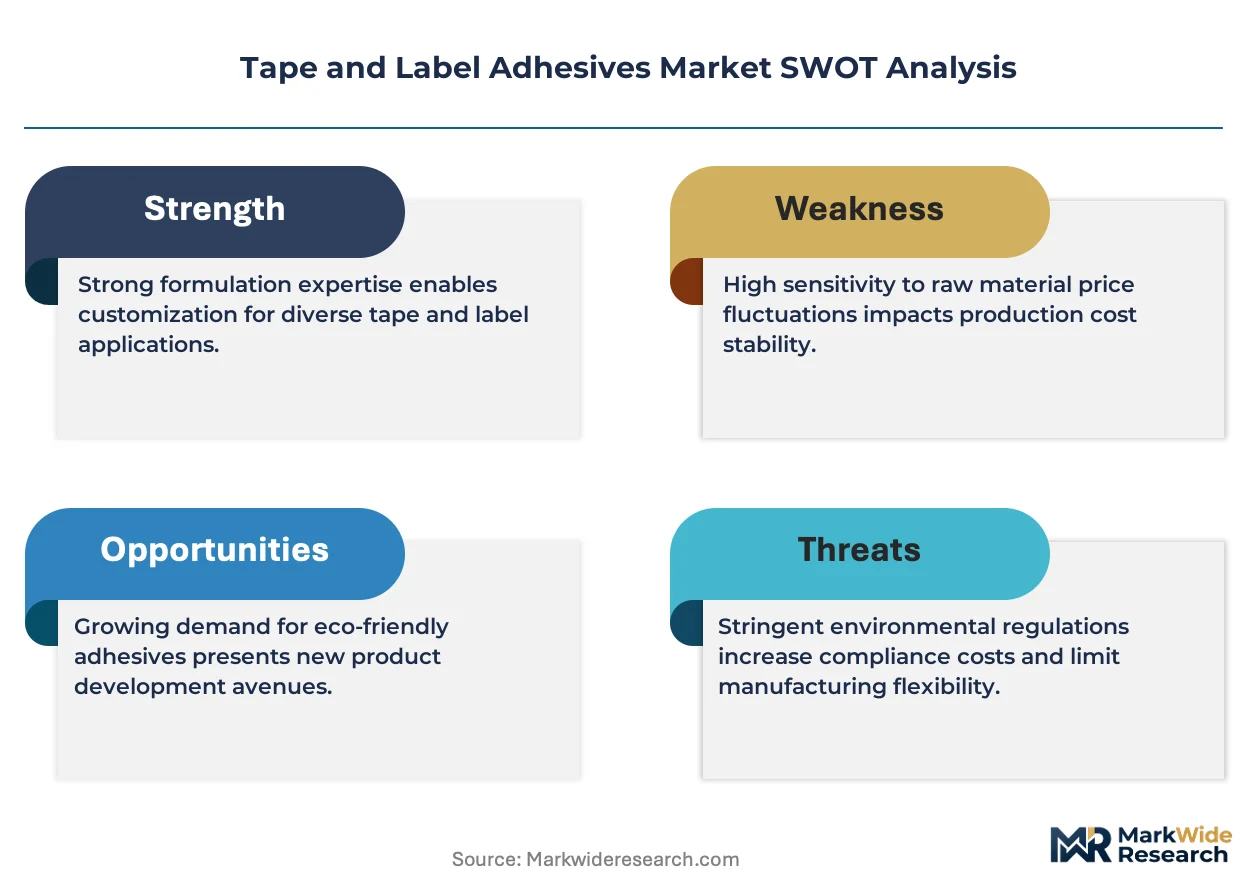
Adhesive chemist availability is bifurcating the competitive landscape as formulation expertise becomes scarcer in mature economies. Henkel AG & Co. KGaA anchors its position through captive polymer synthesis capabilities that insulate raw material access. Avery Dennison Corporation differentiates via precision coating technology leadership in thin-film pressure-sensitive constructions. 3M Company sustains broad portfolio breadth across industrial, medical, and consumer tape segments.
Tape and label adhesives comprise formulated polymeric compositions—typically acrylics, rubbers, or silicones dissolved or dispersed in solvent, water, or monomer carriers—that achieve permanent or repositionable bonding through viscoelastic flow and interfacial wetting at room temperature or elevated conditions, with peel adhesion values ranging from ounces per inch for removable labels to pounds per inch for structural mounting tapes. Their primary purpose spans temporary fixation, permanent assembly, information display, and environmental sealing across manufacturing and distribution chains. Pressure-sensitive adhesives occupy the largest volume position due to instant tack and room-temperature bonding convenience, while UV-curable technology commands premium positioning in electronics applications requiring precise placement without thermal damage. Water-based formulations are gaining share as manufacturers navigate volatile petrochemical solvent costs and workplace exposure constraints.
EPA industrial emissions standards and OSHA permissible exposure limits for volatile organic compounds constrain solvent-based adhesive production in the United States, while REACH registration requirements in Europe restrict certain isocyanate and aromatic amine chemistries used in reactive tape systems. China's GB standards on hazardous substance limits in packaging materials create parallel compliance obligations for export-oriented manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized formulation platforms or regional product variants deliver superior compliance economics.
Market Dynamics
Reformulation pressure from REACH chemical restrictions is fragmenting adhesive supply chains as European manufacturers decouple from legacy solvent-based platforms faster than capacity can realign, creating geographic asymmetry in product availability and technical service depth.
Growth Catalysts
- E-commerce logistics surge:Parcel volume expansion across fulfillment networks is consuming pressure-sensitive tapes for carton sealing and damage protection at rates outpacing industrial GDP multiples.
- REACH solvent restrictions:The EU's phased aromatic amine limitations are forcing adhesive producers to validate water-borne and UV-curable alternatives, opening specification windows for compliant formulators.
- Electronics miniaturization:Die-attach and thermal interface tapes for semiconductor packaging are demanding ultra-thin, low-outgassing constructions that command formulation premiums.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and synthetic rubber prices swing with crude oil and propylene markets, compressing margin visibility for tape producers on quarterly contracts.
- Specialty silicone concentration:Medical-grade silicone adhesive supply concentrates among a handful of polymer suppliers, exposing tape converters to allocation risk during semiconductor-driven demand spikes.
- Fluorochemical substitution limits:Per- and polyfluoroalkyl substance bans under evolving state-level US legislation are eliminating release liner coatings without drop-in alternatives for high-speed converting.
Strategic Opportunities
- India packaging material compliance:BIS hazardous substance limits for food-contact adhesives are creating first-mover advantage for solvent-free and water-based platforms validated to GB migration standards.
- Battery thermal management:EV cell-to-cell bonding and module encapsulation tapes represent unpenetrated volume as automotive OEMs qualify flame-retardant acrylic and ceramic-filled constructions.
- EU Green Deal procurement mandates:Public sector purchasing rules favoring bio-based content are steering label stock specifications toward certified renewable feedstocks.
Industry Challenges
- Adhesive polymer synthesis expertise:The retirement cohort of chemists trained in radical polymerization kinetics and tackifier compatibility is thinning technical service benches at mid-tier formulators.
- Multijurisdictional registration burden:Divergent chemical inventories between REACH, EPA TSCA, and China's IECSC are elongating new product introduction timelines and duplicating toxicology study costs.
- Legacy coating line retrofit:Converting solvent-born capacity to water-borne or UV-curable operation demands capital for drying oven replacement and inert atmosphere handling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tape and Label Adhesives Market |
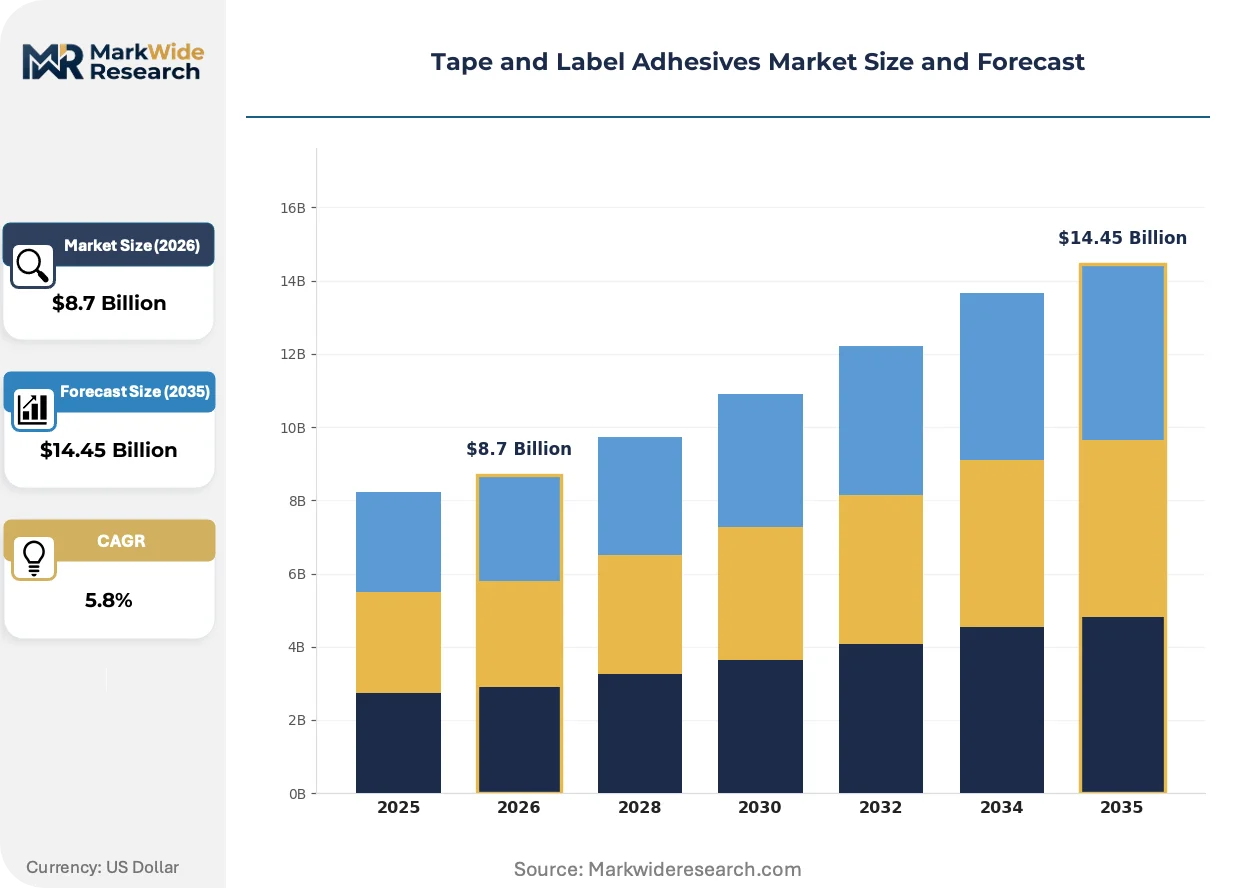
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided Tape, Pressure-Sensitive Adhesives, Hot Melt Adhesives, Water-Based Adhesives End User: Packaging Industry, Electronics, Automotive, Consumer Goods Technology: Solvent-Based, UV-Curable, Biodegradable, Reactive Adhesives Application: Labeling, Bonding, Sealing, Mounting |
| Companies Covered | 3M Company, Avery Dennison Corporation, Nitto Denko Corporation, Tesa SE, Henkel AG & Co. KGaA, Lintec Corporation, Intertape Polymer Group, Berry Global Inc., H.B. Fuller Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tape and Label Adhesives Market Evolving Landscape
Adhesive functionality is fragmenting into application-specific platforms as end-users abandon general-purpose specifications, while regulatory chemistry constraints and sustainability accounting are rewriting raw material selection criteria across the value chain.
Hot-melt pressure-sensitive adhesive technology is decomposing the historical dominance of solvent-borne tape constructions in industrial bonding applications. Automotive interior assembly teams are adopting metallocene polyolefin and styrenic block copolymer formulations for instrument panel and trim attachment, eliminating VOC emissions and flash-off time from production lines. This shift is compressing demand for toluene and ethyl acetate solvent recovery systems while expanding capacity requirements for bulk hot-melt tank and hose infrastructure.
REACH Annex XIV authorization requirements for diisocyanates used in polyurethane reactive tape systems are forcing reformulation toward blocked isocyanate and silane-terminated polymer alternatives. The restriction triggers mandatory worker training and exposure monitoring for uncured adhesive handling, raising operational compliance costs for European converters. Electronics and transportation OEMs with pan-European supply chains are accelerating qualification of moisture-cure silicone and MS-polymer platforms to decouple from authorization uncertainty.
Consolidated buying by multinational CPG and logistics platforms is compressing supplier rosters and demanding integrated label-and-adhesive performance guarantees rather than component specifications. Amazon, Walmart, and DHL procurement teams are pushing tape vendors toward outcome-based contracts covering application failure rates and line-speed optimization. This behavior is most visible in North American and Western European distribution centers where automated case sealing and print-and-apply labeling systems dominate throughput architecture.
Tape and Label Adhesives Market Segmentation
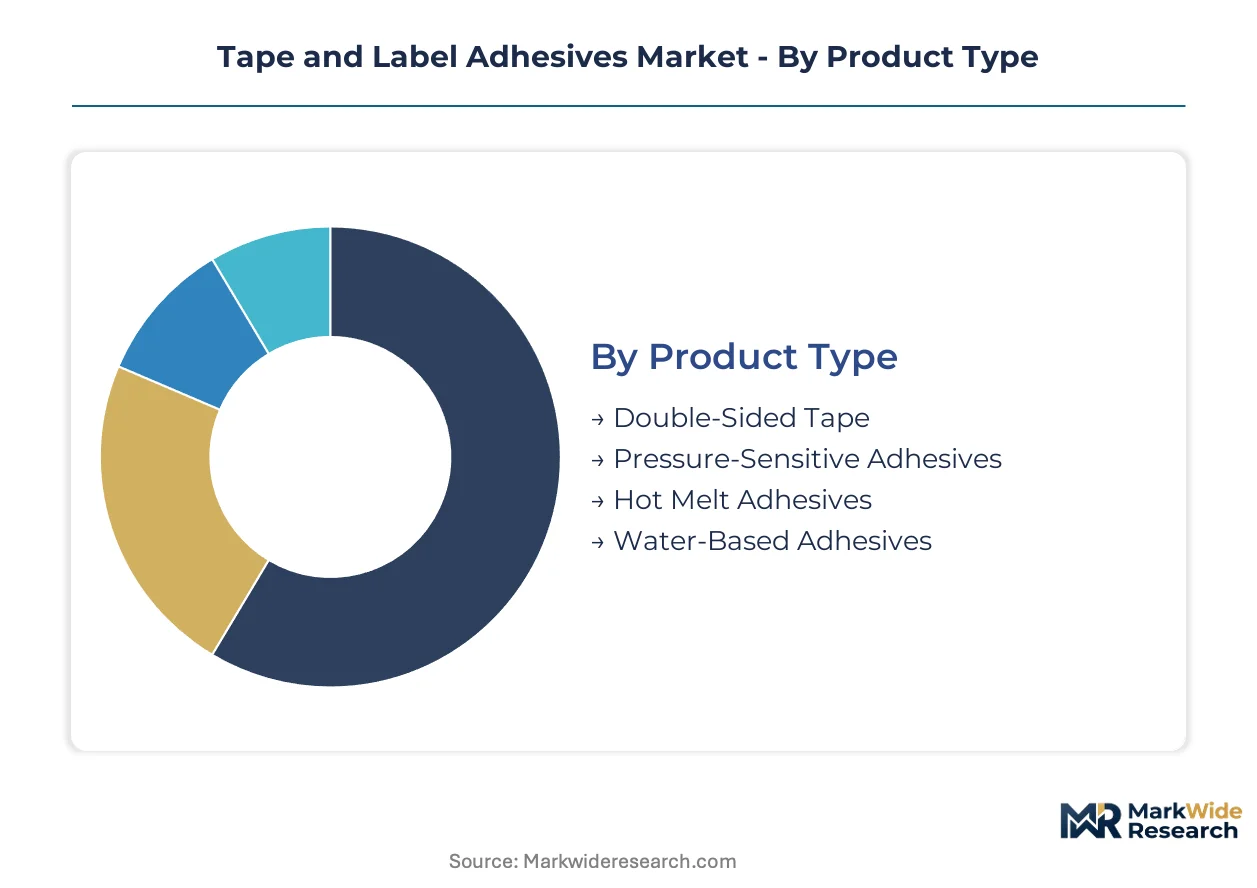
Tape and label adhesives fragment across formulation chemistry, application mechanics, and end-use performance requirements. Each segmentation axis reveals distinct supply chain configurations and margin structures that shape competitive positioning.
Product Type:
Domestic consumption dominates water-based and hot-melt platforms, while pressure-sensitive adhesives and double-sided tapes flow disproportionately through export-oriented converting operations in China and Southeast Asia.
- Pressure-Sensitive Adhesives:These viscoelastic formulations bond instantly under light pressure without activation. Electronics assembly in Shenzhen and Dongguan consumes ultra-thin acrylic constructions for flexible circuit lamination. REACH solvent restrictions are accelerating European qualification of emulsion acrylic alternatives to solvent-borne ancestors.
- Hot Melt Adhesives:Thermoplastic block copolymers and metallocene polyolefins applied molten and set by cooling. Automotive interior assembly in Stuttgart and Detroit is displacing solvent systems with VOC-free hot-melt platforms for trim attachment. Capital intensity for bulk melting infrastructure limits adoption among smaller converters.
- Double-Sided Tape:Carrier-supported adhesive constructions bonding two substrates simultaneously. Industrial mounting applications in Japanese electronics and German automotive sectors specify foam and film carriers with differential adhesion levels.
- Water-Based Adhesives:Acrylic and polyurethane dispersions in aqueous media. Food packaging converters in India and Brazil are validating these platforms against BIS and ANVISA migration limits for direct-contact applications.
Pressure-sensitive adhesives hold the largest share; momentum sits with hot-melt platforms as automotive OEMs eliminate solvent emissions from assembly lines.
End User:
Customer concentration varies sharply—packaging serves fragmented logistics and CPG accounts, while automotive and electronics consolidate purchasing among tier-one suppliers with captive specification authority.
- Packaging Industry:Carton sealing, pallet unitizing, and flexible package lamination. E-commerce fulfillment centers in the United States and Germany are consuming pressure-sensitive tapes at volumes outpacing industrial production indices. Amazon and DHL procurement teams are consolidating supplier rosters and demanding application-failure guarantees.
- Electronics:Die-attach films, thermal interface materials, and display bonding tapes. Semiconductor packaging facilities in Hsinchu and Pyeongtaek specify ultra-thin, low-outgassing constructions for memory and logic device assembly. UV-curable platforms command premium positioning for heat-sensitive component placement.
- Automotive:Interior trim bonding, wire harness wrapping, and exterior emblem attachment. EV battery module assembly is emerging as a specification battleground for flame-retardant acrylic and ceramic-filled thermal management tapes.
- Consumer Goods:Appliance assembly, furniture edge banding, and DIY retail channels. Big-box retailers in North America and Europe are private-labeling entry-grade constructions while specifying performance-tier products for house brands.
Packaging commands volume leadership; electronics represents the steepest expansion trajectory as semiconductor packaging complexity multiplies adhesive layers per device.
Technology:
Regulatory chemistry constraints are fragmenting technology adoption curves—solvent-based systems retreat in Europe while maintaining position in cost-sensitive export markets.
- Solvent-Based:Acrylic and rubber adhesives dissolved in aromatic or ester solvents. Legacy capacity in China and Southeast Asia continues serving price-sensitive industrial tape markets. EPA and OSHA exposure limits constrain US production economics.
- UV-Curable:Acrylate oligomers polymerized by ultraviolet irradiation. Precision electronics assembly in Japan and South Korea favors these platforms for instant cure without thermal damage to sensitive components.
- Reactive Adhesives:Two-component polyurethane and epoxy systems curing by chemical reaction. REACH diisocyanate authorization requirements are forcing European converters toward blocked isocyanate and silane-terminated alternatives.
- Biodegradable:Starch, protein, and bio-based polyester formulations. EU Green Deal procurement mandates are steering public-sector label specifications toward certified renewable content.
Solvent-based technology retains volume dominance in developing markets; UV-curable platforms are climbing fastest in electronics-qualified applications.
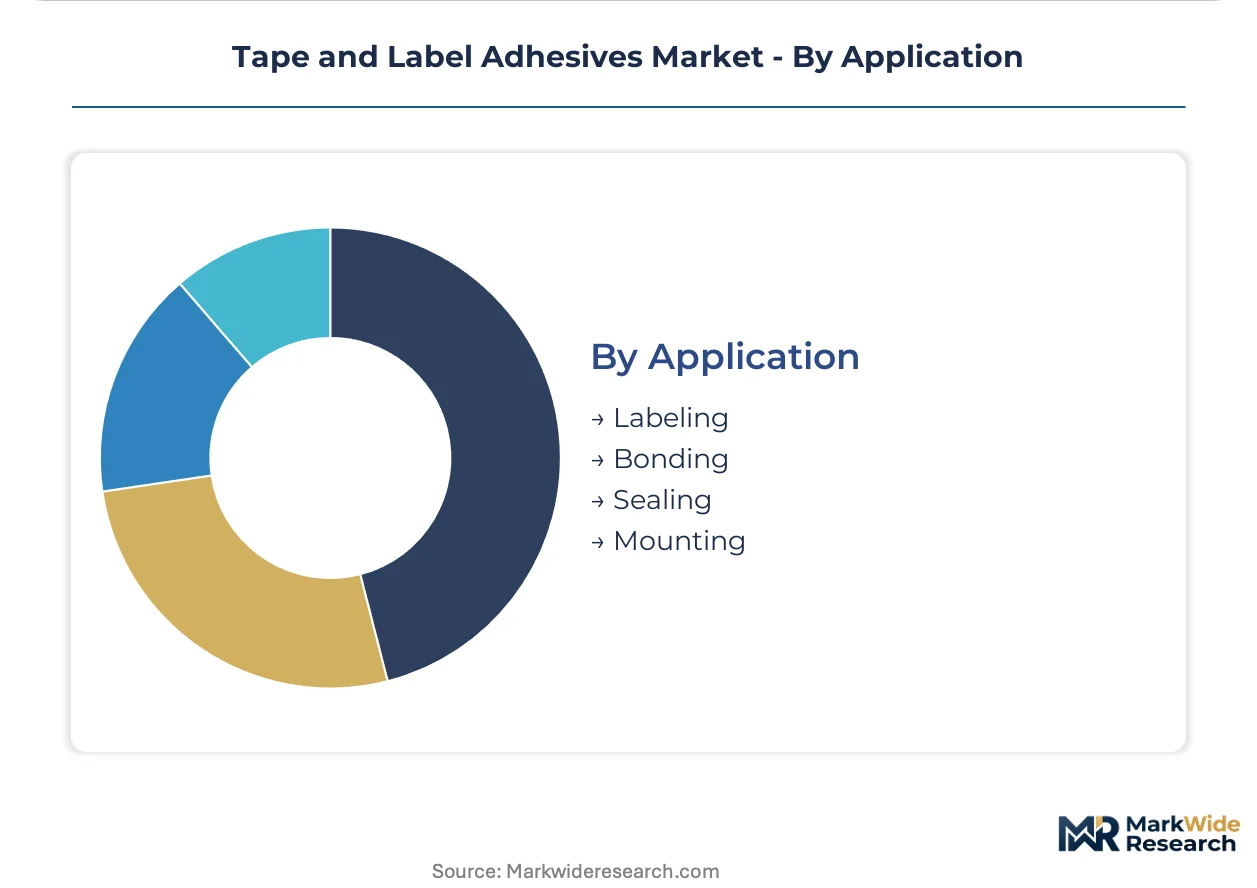
Application:
Application mechanics determine coating weight, release liner specification, and converting equipment configuration—each function carrying distinct margin and technical service requirements.
- Labeling:Information display and barcode identification on primary and secondary packaging. Logistics automation in German and US distribution centers demands print-and-apply constructions compatible with high-speed applicators.
- Bonding:Permanent structural assembly of dissimilar materials. Automotive lightweighting initiatives in Stuttgart and Detroit are specifying high-performance tapes to replace mechanical fasteners and welding.
- Sealing:Environmental protection against moisture, dust, and chemical exposure. Electronics OEMs in Taiwan and South Korea specify hermetic sealing tapes for outdoor and automotive-grade devices.
- Mounting:Temporary or permanent fixture attachment across construction and consumer applications. Removable repositionable platforms serve retail display and rental equipment markets with differential adhesion surfaces.
Labeling captures the largest application share; bonding functions are expanding most quickly as transportation OEMs qualify adhesive solutions for lightweight assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH chemical restrictions are reshaping adhesive formulation priorities across European manufacturing, while divergent regulatory timelines between jurisdictions are creating geographic asymmetry in product availability and technical service depth.
United States
EPA industrial emissions standards and OSHA permissible exposure limits for volatile organic compounds constrain solvent-based adhesive production economics. Amazon and Walmart procurement teams are consolidating supplier rosters and demanding outcome-based contracts covering application failure rates. Automated fulfillment centers in Pennsylvania and Texas consume pressure-sensitive tapes at volumes outpacing industrial production indices.
Germany
Automotive interior assembly teams in Stuttgart are adopting metallocene polyolefin hot-melt formulations for instrument panel attachment, eliminating VOC emissions from production lines. REACH Annex XIV authorization requirements for diisocyanates are forcing converters toward blocked isocyanate and silane-terminated polymer alternatives. EU Green Deal procurement mandates are steering public-sector label specifications toward certified renewable feedstocks.
China
GB standards on hazardous substance limits in packaging materials create parallel compliance obligations for export-oriented manufacturers. Electronics assembly clusters in Shenzhen and Dongguan consume ultra-thin acrylic constructions for flexible circuit lamination. Manufacturing capacity for specialized tape requirements continues expanding around semiconductor packaging and automotive production hubs.
Japan
Precision electronics assembly in Osaka and Nagoya favors UV-curable platforms for instant cure without thermal damage to sensitive components. METI industrial standards guide adhesive qualification protocols for semiconductor and display bonding applications. Die-attach films and thermal interface materials command formulation premiums as packaging complexity multiplies adhesive layers per device.
India
BIS hazardous substance limits for food-contact adhesives are creating first-mover advantage for solvent-free and water-based platforms validated to migration standards. Packaging converters in Maharashtra and Gujarat are qualifying aqueous acrylic and polyurethane dispersions against direct-contact regulatory thresholds. E-commerce logistics networks in Delhi-NCR and Bangalore are driving consumption of carton sealing and damage protection tapes.
Tape and Label Adhesives Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with competitive positioning hinging on captive polymer synthesis capabilities and precision coating technology leadership. The market structure rewards backward integration into raw material supply and in-house formulation expertise. Three archetypes dominate: diversified chemical conglomerates with adhesive divisions, precision coating specialists serving electronics and medical segments, and regional converters focused on packaging and industrial tape markets. M&A activity concentrates among mid-tier formulators seeking geographic expansion, while technology licensing agreements proliferate around UV-curable and hot-melt platform transfers.
Within the integrated chemical conglomerate tier, Henkel AG & Co. KGaA and 3M Company exemplify divergent strategic postures—one anchored in European formulation heritage and captive polymer production, the other sustaining broad portfolio breadth across industrial, medical, and consumer segments. Avery Dennison Corporation occupies a position between these poles, representing precision coating technology leadership in thin-film pressure-sensitive constructions. These three entities collectively illustrate how formulation expertise scarcity and regulatory compliance burdens are bifurcating competitive outcomes in mature economies.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| Tesa SE |
| Henkel AG & Co. KGaA |
| Lintec Corporation |
| Intertape Polymer Group |
| Berry Global Inc. |
| H.B. Fuller Company |
| Others |
Value Network & Pricing Analysis
Water-based adhesive substitution for solvent-borne systems simultaneously relocates production capacity toward coastal China manufacturing clusters and compresses margin structures for European converters facing legacy asset retrofit costs. This chemistry migration fragments pricing power across geographic tiers while rewarding backward-integrated formulators with captive acrylic emulsion supply.
Pricing Analysis
Geographic price spreads widen between German automotive-qualified hot-melt tapes and Southeast Asian commodity carton-sealing grades. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade silicone constructions certified to ISO 10993 from industrial packaging tapes and unbranded bulk supply. Pricing pressure stems from Amazon and Walmart procurement consolidation demanding outcome-based failure-rate guarantees. Small-scale Indian and Brazilian converters exhibit highest price sensitivity; electronics OEMs in Japan and South Korea prioritize performance consistency over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for acrylic monomer shipments to European coating facilities. Raw material supply concentrates in China, Germany, and the United States for acrylic polymers, tackifier resins, and silicone intermediates. Formulation depends on petrochemical feedstocks vulnerable to crude oil and propylene volatility. Single-source vulnerability concentrates among medical-grade silicone polymer suppliers serving semiconductor packaging demand spikes. Distribution runs through regional converting hubs in Stuttgart, Shenzhen, and Detroit that serve downstream automotive and electronics assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward consolidated logistics platforms and automotive OEM procurement teams, fragmenting supplier rosters and demanding integrated performance guarantees rather than component specifications.
For Market Incumbents: Compound formulation expertise scarcity into defensive moats by accelerating captive polymer synthesis investments in Germany and China. Secure REACH-compliant water-borne and UV-curable platform certifications ahead of diisocyanate authorization deadlines. Deepen technical service bench strength through apprenticeship programs addressing the retiring cohort of radical polymerization chemists. For New Entrants and Emerging Players: Anchor in India's BIS-compliant solvent-free packaging adhesive segment where first-mover validation against food-contact migration standards creates specification lock-in. Target EV battery thermal management tape qualifications as automotive OEMs qualify flame-retardant acrylic constructions for cell-to-cell bonding. Pursue joint development agreements with Tier 1 automotive suppliers rather than direct OEM penetration. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors mid-tier formulators with validated water-borne platforms and regional technical service depth. Long-term viability over the next decade hinges on compliance infrastructure rather than scale economics alone. Monitor REACH Annex XIV authorization timelines as inflection indicators for European market access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Emulsion Production | Henkel's captive polymer synthesis insulates raw material access against petrochemical volatility. |
| REACH-Compliant Platform Certification | Water-borne and UV-curable validations open specification windows as diisocyanate restrictions tighten. |
| EV Battery Thermal Management Tape Development | Flame-retardant acrylic qualifications address unpenetrated volume in automotive cell-to-cell bonding. |
| Technical Service Bench Expansion | Apprenticeship programs counter retiring polymerization chemist cohorts at mid-tier formulators. |
| India BIS Migration Standard Validation | First-mover solvent-free certifications create specification lock-in for food-contact packaging converters. |
Research Methodology
A standing panel of adhesive formulation chemists, automotive Tier 1 procurement directors, electronics assembly engineers, and packaging converter operations managers provided ongoing calibration across the study period. Primary interview insights triangulated against customs trade data, Cefic chemical industry reports, SEC 10-K filings from listed adhesive producers, and GB standards documentation from China's Standardization Administration. Bottom-up volume estimates from end-use consumption patterns reconciled with top-down value projections across formulation chemistry segments.
Consistency checks validated volume and value outputs against ACC production indices and regional automotive build rates across the modeling period. The analytical framework segmented demand by chemistry type, end-use industry, application mechanics, and regional regulatory cluster. CAGRs derived from fitted trend extrapolation adjusted for REACH implementation timelines and e-commerce logistics penetration curves. Forecast inputs incorporated semiconductor packaging complexity indices and EV battery production ramp schedules.
Decision-makers should treat outputs as directional under sustained REACH enforcement and e-commerce volume expansion assumptions; material deviation would warrant model refresh. Petrochemical feedstock disruption or accelerated PFAS substitution timelines represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Gaffers Tape Market
Tapes
Shipping Tapes Market
Tapes
Pressure Sensitive Tapes and Labels Market
Tapes
Thermal Transfer Tapes Market
Tapes
Self-Fusing Silicone Tapes Market
Tapes
Smart Card Tapes Market
Tapes
PVC Tapes Market
Tapes
Plastic Adhesive Tapes Market
Tapes
Heat Activated Tear Tape Market
Tapes
Global Electrical Tapes Market
Tapes
United States End-Of-Line Packaging Tape Market
Tapes
Packaging Tapes Market
Tapes
Tape Stretching Line Market
Tapes
Acetate Cloth Tape Market
Tapes
Freezer Tape Market
Tapes
Global Pressure Sensitive Tapes Market