
 Masking Tape Market | 2026-2036
Masking Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Masking Tape Market Outlook
Automotive refinishing is restructuring demand toward silicone-backed masking tapes rated for e-coat and powder-coat lines. 3M leverages its catalog of high-temperature automotive grades to anchor OEM specification programs across North America and Europe. Tesa SE sustains a dense patent position in precision-edge crepe tapes for robotic paint application. Shurtape Technologies, LLC competes aggressively on private-label construction masking through distributor channel control in the United States.
Masking tape is a pressure-sensitive adhesive tape engineered with crepe paper, PVC, or polyethylene backings coated with rubber-based, acrylic, or silicone adhesives, designed for temporary surface protection and clean removal without residue transfer. Its primary industrial purpose centers on defining sharp paint edges, protecting substrates during thermal processing, and enabling multi-stage coating workflows. Crepe paper formulations dominate volume in construction and general industrial use due to conformability and cost position, while silicone-adhesive grades command premium placement in automotive bake cycles where temperature exposure exceeds 150°C. Acrylic-based systems are gaining share in electronics assembly where low-outgassing and cleanroom compatibility matter more than heat tolerance.
FDA oversight of adhesive constituents in indirect food-contact applications shapes material selection for masking tapes used in packaging equipment maintenance. EPA VOC regulations and OSHA workplace exposure limits constrain solvent-based adhesive formulations, accelerating waterborne and hot-melt platform development. The EU REACH restriction on polycyclic aromatic hydrocarbons in rubber adhesives forces reformulation of legacy crepe tapes destined for European industrial users. Stakeholders must monitor adhesive chemistry transitions, as compliance-driven raw material shifts will separate suppliers with in-house resin synthesis from those dependent on merchant adhesive purchases.
Market Dynamics
Automotive OEMs are consolidating masking tape specifications around single-source silicone-adhesive platforms, compressing supplier lists while elevating technical performance thresholds for e-coat and powder-coat compatibility.
Growth Catalysts
- EV Battery Assembly Thermal Management:Electric vehicle manufacturers specify high-temperature crepe tapes for cell-to-pack bonding and thermal runaway protection, creating dedicated demand streams outside traditional automotive refinishing.
- REACH PAH Restrictions:ECHA enforcement against polycyclic aromatic hydrocarbons in rubber adhesives accelerates European converter migration toward waterborne acrylic systems with compliant resin chemistry.
- Robotic Paint Line Precision:Automotive tier-one suppliers demand laser-cut edge definition and static-dissipative backings for automated masking in Industry 4.0 paint shops.
Market Restraints
- Petrochemical Input Volatility:Crude-derived tackifier resins and synthetic rubber feedstocks expose adhesive coaters to margin compression without pass-through pricing power in distributor channels.
- Asian Masterbatch Concentration:Specialty pigment and UV-stabilizer supply concentrates in Zhejiang and Guangdong provinces, creating single-source vulnerability for European tape converters.
- Silicone Adhesive Technical Ceiling:Silicone platforms exhibit poor adhesion to low-surface-energy substrates common in EV battery housings, limiting application expansion despite heat tolerance advantages.
Strategic Opportunities
- Indian Industrial Packaging:BIS certification requirements for food-contact adhesives create first-mover advantage for compliant waterborne acrylic masking tapes in dairy and beverage processing equipment maintenance.
- CSRD Supply Chain Disclosure:EU corporate sustainability reporting mandates force OEMs to document Scope 3 emissions, advantaging tape suppliers with verified recycled-content backings and solvent-free coating processes.
- UV-Curable Adhesive Convergence:Combination of UV-LED curing hardware and cationic epoxy adhesives enables instant-tack, zero-VOC masking systems for just-in-time automotive sequencing operations.
Industry Challenges
- Adhesive Formulation Chemist Scarcity:Retirement waves among rubber-compounding specialists and limited polymer science pipeline output constrain R&D velocity for next-generation heat-resistant platforms.
- Multi-Standard Certification Timelines:Simultaneous pursuit of FDA indirect food-contact, UL flammability, and OEM automotive approvals extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Masking Tape Market |
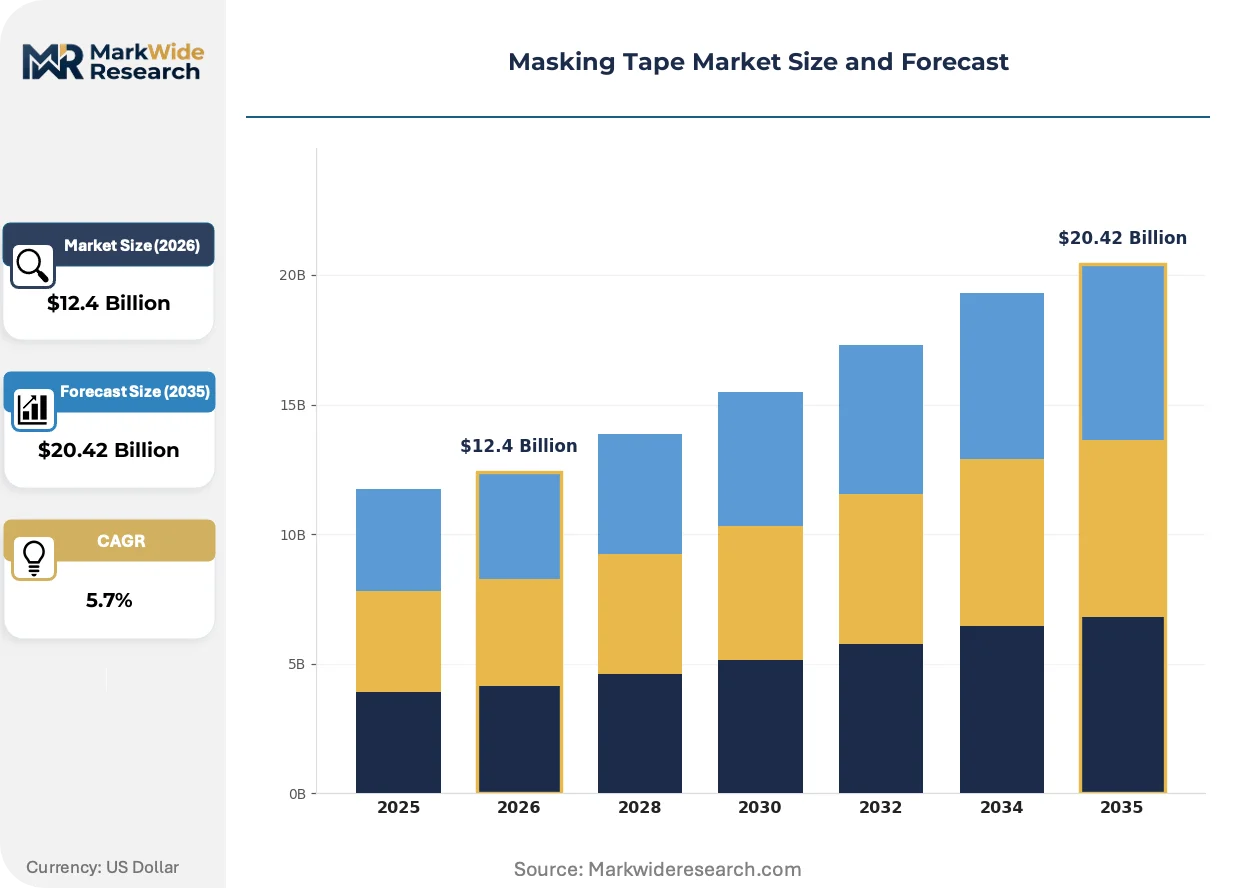
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automotive, Construction, Electronics, Arts & Crafts Material: Paper, PVC, Crepe, Polyethylene Adhesive Type: Rubber-Based, Acrylic-Based, Silicone-Based, Hot Melt End User: Residential, Commercial, Industrial, DIY Enthusiasts |
| Companies Covered | Avery Dennison Corporation, Intertape Polymer Group, 3M, Scapa Group, Shurtape Technologies, LLC, Tesa SE, Henkel AG, Lintec Corporation, Nitto Denko Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Masking Tape Market Strategic Shifts
Adhesive chemistry platforms and coating equipment architectures are fragmenting into application-specific configurations, abandoning universal-grade strategies in favor of purpose-built masking systems.
Silicone-modified polyether (MS polymer) hybrid adhesives are modularizing the traditional segmentation between rubber-based construction grades and silicone automotive bake tapes. Japanese automotive OEMs specify these intermediates for 120-150°C intermediate temperature zones where pure silicone overperforms and rubber fails. The technology is modularizing procurement decisions by collapsing two SKU categories into one qualified platform.
EPA VOC emission standards under 40 CFR Part 59 constrain solvent-borne adhesive coating operations in US tape manufacturing facilities. Industrial coaters face capital decisions between thermal oxidizer installation and waterborne line conversion. Southern California air quality management districts enforce the strictest thresholds, pushing regional suppliers toward hot-melt and UV-curable alternatives ahead of federal compliance deadlines.
Direct mill procurement by automotive OEMs is displacing distributor-mediated specification for high-temperature masking grades. Tier-one paint shops in Germany and the US Midwest now contract adhesive coaters on annual volume agreements with technical service attachments. This pattern concentrates in e-coat and powder-coat operations where line downtime costs exceed tape price differentials by orders of magnitude.
Masking Tape Market Segmentation
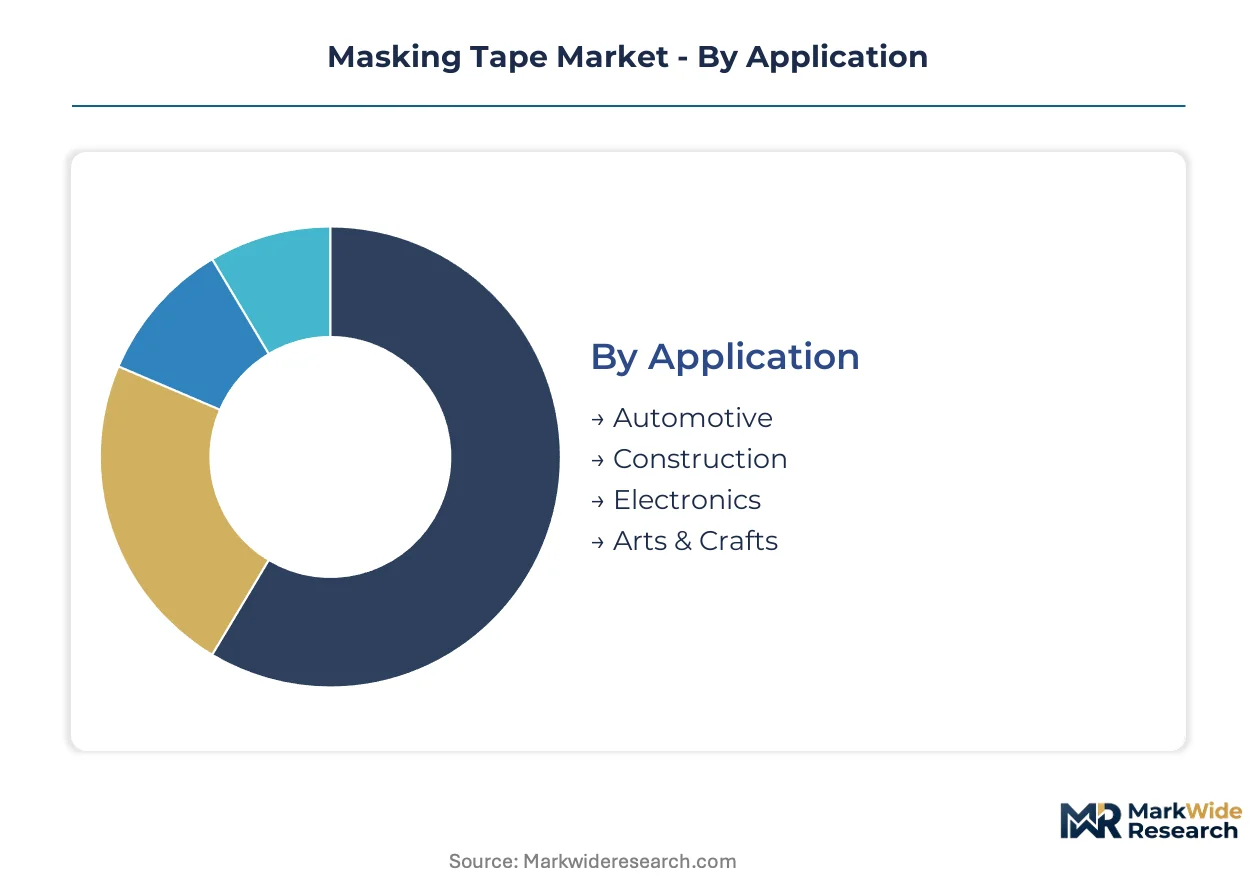
Segmentation in masking tape markets reflects divergent capital requirements across adhesive chemistry platforms and backing material processing. Precision-grade silicone systems demand cleanroom coating infrastructure and resin synthesis capabilities that commodity crepe lines cannot replicate.
Application:
Capital intensity peaks in automotive-grade production, where silicone coating lines and thermal validation equipment require dedicated facility investments.
- Automotive:High-temperature silicone and MS polymer formulations serve e-coat, powder-coat, and EV battery assembly lines. German OEM paint shops and tier-one suppliers in Stuttgart and Wolfsburg specify precision-edge grades with static-dissipative backings for robotic application.
- Construction:General-purpose crepe and PVC masking tapes dominate volume for temporary surface protection and paint edge definition. Demand concentrates in residential renovation cycles across the United States, where distributor channel control determines supplier access.
- Electronics:Low-outgassing acrylic systems protect circuit boards and display assemblies during thermal processing. Cleanroom-compatible formulations serve semiconductor fabrication equipment maintenance.
- Arts & Crafts:Washi paper and decorative crepe variants prioritize conformability and residue-free removal over thermal performance. Consumer channel placement through craft retailers and e-commerce platforms drives specification.
Most installed capacity flows through Construction. Expansion is steepest in Automotive.
Material:
Backing selection determines coating line configuration and downstream application temperature limits.
- Paper:Saturated flatback and washi formulations serve general industrial masking with moderate temperature tolerance. Japanese pulp sourcing and saturation chemistry control supply reliability for precision grades.
- PVC:Extruded film backings provide moisture resistance and conformability for curved automotive panels. Calendering equipment and plasticizer formulation expertise create regional supply concentration in Guangdong province.
- Crepe:Micro-crepe paper dominates automotive bake cycles through controlled elongation and clean removal properties. E-coat compatibility testing and OEM qualification timelines extend 18-24 months for new crepe grades.
- Polyethylene:Blown and cast film backings offer chemical resistance for industrial maintenance and marine applications. UV stabilization masterbatch sourcing from Zhejiang province creates single-source vulnerability for European converters.
Crepe commands the highest unit margins. Polyethylene is gaining share fastest in chemical-processing applications.
Adhesive Type:
Rubber-based systems require solvent recovery infrastructure that waterborne acrylic lines avoid.
- Rubber-Based:Natural and synthetic rubber tackifiers deliver aggressive initial tack for construction and general industrial masking. EU REACH PAH restrictions force European coaters toward compliant resin synthesis or platform abandonment.
- Acrylic-Based:Waterborne and solvent acrylic systems balance adhesion, temperature resistance, and regulatory compliance. Electronics assembly favors low-outgassing grades for cleanroom compatibility.
- Silicone-Based:Polydimethylsiloxane formulations tolerate continuous exposure above 150°C in automotive powder-coat and e-coat lines. In-house resin synthesis separates qualified suppliers from merchant-adhesive dependent competitors.
- Hot Melt:Block copolymer and EVA-based systems enable high-speed coating without solvent emissions. EPA VOC regulations under 40 CFR Part 59 accelerate hot-melt line investment in Southern California manufacturing facilities.
Silicone platforms carry the steepest technical qualification barriers. Acrylic systems are expanding most quickly under regulatory pressure.
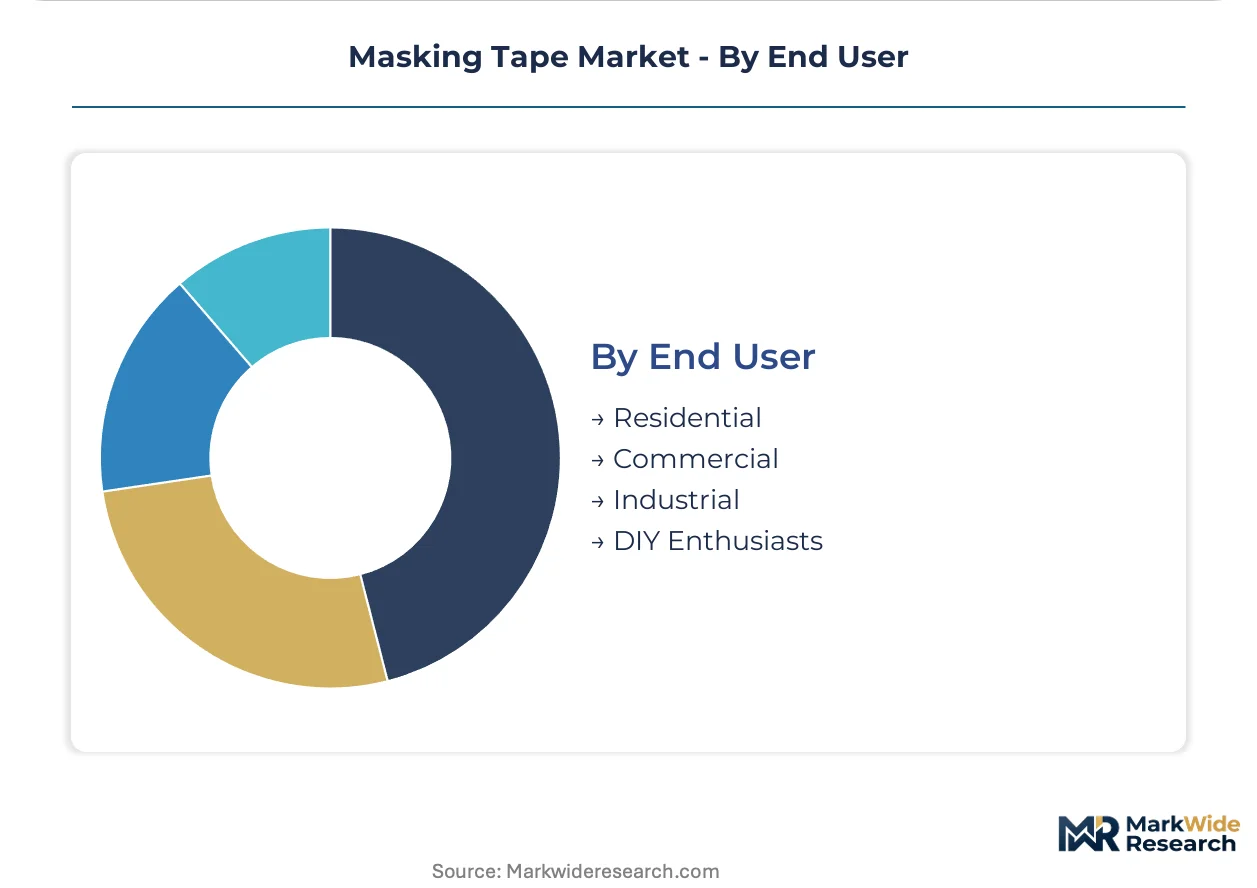
End User:
Industrial procurement patterns concentrate volume through annual agreements with technical service attachments.
- Residential:DIY renovation and home improvement projects drive volume through retail hardware channels. Price sensitivity and brand recognition determine shelf placement.
- Commercial:Facility maintenance, property management, and light construction operations specify mid-tier grades through distributor networks. Recurring purchase agreements support inventory management services.
- Industrial:Automotive OEMs, electronics manufacturers, and heavy industry operations mandate certified grades with batch traceability. Direct mill procurement is displacing distributor mediation for high-temperature masking specifications.
- DIY Enthusiasts:Hobbyist and craft segments prioritize specialty colors, widths, and decorative finishes. E-commerce direct-to-consumer channels bypass traditional distribution entirely.
Industrial users generate the highest revenue per roll. DIY Enthusiasts show the steepest channel shift toward direct digital procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors automotive-grade masking tape specification activity, with German OEM paint shops driving precision-grade demand across powder-coat and e-coat lines. Regional regulatory frameworks and industrial clustering shape procurement patterns in each major market.
United States
Automotive OEM direct procurement is displacing distributor mediation in Michigan and Ohio paint shop clusters. EPA 40 CFR Part 59 VOC regulations push Southern California adhesive coaters toward hot-melt and UV-curable platforms. Detroit-area tier-one suppliers specify silicone-adhesive grades with static-dissipative backings for robotic application lines.
Germany
REACH PAH restrictions on polycyclic aromatic hydrocarbons force rubber-adhesive reformulation across Wolfsburg and Stuttgart manufacturing zones. ECHA enforcement accelerates waterborne acrylic migration among European converters. Bavarian precision-tape specialists supply laser-cut edge definitions for Industry 4.0 paint automation.
China
EV battery assembly thermal management creates dedicated demand streams in Shenzhen and Shanghai manufacturing corridors. MIIT industrial standards for adhesive emissions shape domestic coating line investments. Zhejiang province masterbatch concentration creates single-source vulnerability for UV-stabilizer procurement.
Japan
MS polymer hybrid adhesives command specification in Nagoya automotive clusters for intermediate 120-150°C temperature zones. METI energy-efficiency guidelines influence coating equipment architecture decisions. Osaka-based electronics manufacturers drive low-outgassing acrylic demand for cleanroom-compatible masking.
India
BIS certification requirements for food-contact adhesives open first-mover positioning in Maharashtra dairy processing equipment maintenance. Central government PLI scheme incentives support domestic adhesive synthesis capability buildout. Gujarat chemical processing corridors adopt polyethylene-backed grades for solvent-resistant industrial masking.
Masking Tape Market Competitive Environment
Direct mill procurement dominates the current landscape as automotive OEMs consolidate supplier lists around single-source silicone-adhesive platforms. The vendor base structures across three tiers: multinational adhesive specialists with in-house resin synthesis, regional converters dependent on merchant adhesive purchases, and private-label distributors controlling construction channel access. Two competitive vectors define positioning: technical qualification barriers for automotive bake-cycle grades, and distributor relationship depth for construction volume. M&A activity targets adhesive synthesis capabilities, while capacity expansion concentrates in waterborne acrylic lines for regulatory compliance.
Within the multinational specialist tier, 3M and Tesa SE occupy positions anchored by automotive OEM specification programs and precision-edge patent estates. Among North American distributor-channel players, Shurtape Technologies, LLC exemplifies private-label construction masking strategies. These three entities represent divergent archetypes: resin-synthesis-integrated automotive qualification, precision-tape technology leadership, and distributor-controlled volume positioning.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Intertape Polymer Group |
| 3M |
| Scapa Group |
| Shurtape Technologies, LLC |
| Tesa SE |
| Henkel AG |
| Lintec Corporation |
| Nitto Denko Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive resin synthesis separates automotive-grade suppliers from merchant-adhesive dependent competitors, anchoring both supply security and pricing power in silicone masking tape tiers. This integration choice insulates qualified coaters from petrochemical feedstock volatility while forcing distributor-dependent converters into margin compression during crude-derived tackifier price spikes.
Pricing Analysis
Petrochemical input pass-through mechanics vary sharply by adhesive chemistry platform. Silicone-based automotive grades command contract-based long-term offtake pricing with annual volume agreements, while construction crepe tapes trade on commodity spot dynamics through distributor channels. Price differentiation hinges on OEM qualification status and REACH compliance certification, with German automotive buyers showing lowest sensitivity due to line-downtime cost exposure. Pricing pressure stems from Asian masterbatch concentration in Zhejiang province, compressing margins for European converters dependent on imported UV stabilizers.
Supply Chain Analysis
India's BIS certification requirements for food-contact adhesives are reshaping sourcing patterns, accelerating domestic coating line investments among Maharashtra-based converters. Raw material flows draw from Chinese Zhejiang masterbatch suppliers, German synthetic rubber specialists, and Japanese pulp sources for precision-grade saturation chemistry. Single-source vulnerability concentrates in specialty pigment procurement from Guangdong province. Distribution runs through tier-one automotive supplier networks in Germany and direct mill procurement channels displacing traditional distributor mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The masking tape market functions as a regulatory compounder, with EU REACH PAH restrictions on polycyclic aromatic hydrocarbons forcing platform migrations that concentrate share among compliant resin synthesizers.
For Market Incumbents: Deepen in-house silicone resin synthesis capabilities to defend against merchant-adhesive dependent competitors facing REACH reformulation deadlines. Anchor OEM specification programs through technical service attachments that extend beyond product supply into line-integration support, raising switching costs for automotive tier-one suppliers. For New Entrants and Emerging Players: UV-curable adhesive platforms offer a technology-first wedge into Southern California coating operations facing EPA 40 CFR Part 59 VOC compliance deadlines. Target waterborne acrylic migration among European rubber-adhesive converters as the most penetrable white-space, leveraging regulatory-driven procurement urgency without legacy solvent-recovery infrastructure burdens. For Investors and Strategic Acquirers: Roll-up economics work for regional adhesive coaters with captive resin synthesis because REACH compliance timelines are compressing supplier lists faster than organic capacity expansion can match. Monitor ECHA enforcement intensity against polycyclic aromatic hydrocarbons as the inflection signal determining which merchant-adhesive dependent converters face forced exit versus acquisition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | REACH PAH compliance separates captive producers from merchant-dependent coaters facing reformulation deadlines. |
| Waterborne Acrylic Line Conversion | EPA 40 CFR Part 59 VOC thresholds push Southern California facilities toward zero-emission coating platforms. |
| Direct Mill Procurement Agreements | German OEM paint shops in Stuttgart and Wolfsburg bypass distributor channels for high-temperature silicone grades. |
| UV-Curable Adhesive Platform Development | UV-LED curing hardware enables instant-tack masking systems for just-in-time automotive sequencing operations. |
| Recycled-Content Backing Certification | EU CSRD supply chain disclosure mandates advantage tape suppliers with verified Scope 3 emissions documentation. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews engaged adhesive coating plant managers, automotive OEM procurement leads, distributor channel partners, and technical R&D directors specializing in pressure-sensitive adhesive formulation. Secondary sources included customs and trade data, ECHA regulatory filings, EPA 40 CFR Part 59 enforcement records, and SEC 10-K disclosures from listed tape manufacturers. Bottom-up volume modeling triangulated against top-down market sizing across adhesive chemistry platforms.
Granularity extended to adhesive type, backing material, application segment, and end-user procurement pattern across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by regional production cluster growth rates. Industry-specific inputs incorporated EV battery assembly thermal management demand curves, REACH compliance migration timelines, and robotic paint line automation penetration rates.
The model holds under stable petrochemical feedstock availability and current regulatory enforcement intensity; deviation in crude price volatility or accelerated ECHA restriction timelines would shift competitive positioning. Forecasts reflect documented assumptions regarding OEM specification program stability and distributor channel control persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Automotive Tapes Market
Tapes
Global Adhesive Tapes Market
Tapes
Nano Tapes Market
Tapes
Metal Foil Tapes Market
Tapes
Gummed Tapes Market
Tapes
Carbon Tapes Market
Tapes
India Reflective Tapes Market
Tapes
Correction Tapes Market
Tapes
Pipe Marking Tape Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Acoustic Tape Market
Tapes
Europe Packaging Tapes Market
Tapes
Double Coated Film Tapes Market
Tapes
Global Pressure Sensitive Tapes Market
Tapes
Sterilization Indicator Tape Market
Tapes
Aerospace Tapes Market