
 Carbonate Drink Maker Market | 2026-2036
Carbonate Drink Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Carbonate Drink Maker Market Insights
Connected appliance ecosystems and smartphone-integrated carbonation control is rewriting how manufacturers design user interfaces and consumables replenishment. SodaStream International Ltd. leverages its proprietary CO2 exchange infrastructure across retail partnerships to sustain recurring revenue streams. Aarke AB differentiates through design-forward stainless-steel construction that commands premium positioning in European households. Drinkmate Inc. competes on versatility by enabling carbonation of beverages beyond water, including juices and cocktails.
A carbonate drink maker is a consumer appliance that injects food-grade carbon dioxide into still water or other liquids through pressurized chamber systems, typically operating at 30-60 psi to achieve desired effervescence levels for home or commercial beverage preparation. Soda Makers represent the established volume category where unit economics favor recurring CO2 cylinder purchases, while Online Platforms emerge as the fastest-growing distribution channel as direct-to-consumer subscription models for gas refills reduce friction in repeat purchasing. Electromechanical technology dominates household installations for convenience, though Manual systems retain niche strength among outdoor and off-grid users prioritizing portability over automation.
The US FDA governs food-contact materials and CO2 purity standards for these appliances, while the EU REACH framework restricts certain plastics and chemical additives in components touching consumable liquids, effectively filtering non-compliant suppliers from transatlantic market access. California's SB 54 extended producer responsibility rules add compliance layers for packaging and cylinder recovery programs sold into that state. Stakeholders must monitor how fragmented municipal recycling requirements across jurisdictions reshape reverse logistics costs and cylinder deposit program viability.
Market Dynamics
EU REACH restrictions on food-contact plastics and the EU's Single-Use Plastics Directive are compressing supplier margins while redirecting procurement toward stainless-steel and glass component systems that satisfy compliance without redesign cycles.
Growth Catalysts
- REACH framework compliance:Manufacturers redesigning for EU chemical safety standards gain automatic transatlantic market access, eliminating redundant certification costs for North American entry.
- Countertop electromechanical systems:Households in Germany and Scandinavia replace bottled water consumption with pressurized home carbonation at 30-60 psi operating pressure.
- Municipal recycling mandates:German cities enforce strict packaging waste sorting requirements that make single-use bottles economically punitive versus reusable cylinder exchange programs.
Market Restraints
- CO2 supply concentration:Food-grade gas production clusters with industrial gas suppliers in Central Europe, creating cylinder refill bottlenecks during peak summer demand windows.
- California SB 54 extended producer responsibility:Cylinder recovery and packaging compliance add per-unit cost layers for appliances sold into the US state, compressing distributor margins.
- Manual system substitution:Off-grid outdoor users prioritize portable hand-pump carbonators over electromechanical units, capping premium appliance penetration in recreational segments.
Strategic Opportunities
- Direct-to-consumer subscription channels:Online platforms bypass retail markups by automating CO2 cylinder replenishment through connected appliance telemetry.
- Juice and cocktail carbonation:Beverage versatility beyond still water opens household occasions previously served by pre-mixed canned drinks.
- Smartphone-integrated control systems:Connected appliance ecosystems enable precision effervescence tuning and predictive consumables ordering.
Industry Challenges
- Reverse logistics complexity:Fragmented municipal recycling requirements across US states and EU member countries force customized cylinder deposit program structures.
- Food-contact material certification timelines:FDA and EFSA approval cycles for new polymer formulations delay product refresh schedules by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbonate Drink Maker Market |
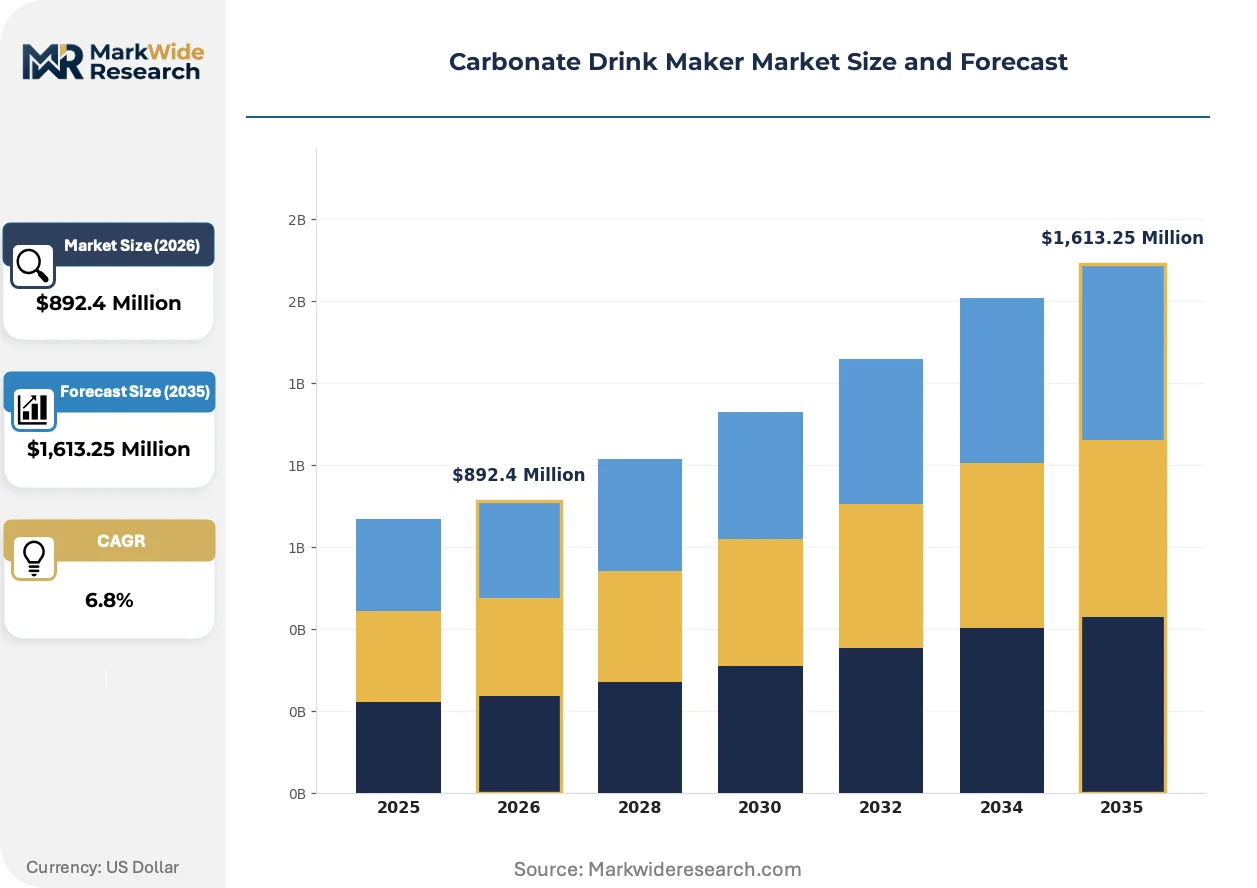
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soda Makers, Mixer Machines, Syrup Dispensers, Carbonation Bottles Technology: Electromechanical, Manual, CO2 Injection, Soda Stream End User: Households, Restaurants, Beverage Manufacturers, Catering Services Distribution Channel: Retail Stores, Online Platforms, Wholesale Distributors, Direct Sales |
| Companies Covered | SodaStream International Ltd., Drinkmate Inc., Hamilton Beach Brands Holding Company, Breville Group Ltd., Cuisinart, iSi GmbH, Aarke AB, Spärkel Beverage Systems, KitchenAid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbonate Drink Maker Market Trends and Innovations
Connected appliance architectures and material compliance requirements are rewriting design priorities across hardware, software, and consumables simultaneously.
Stainless-steel construction is hybridizing electromechanical carbonation systems with premium kitchen aesthetics. Design-conscious households in Northern Europe specify brushed metal finishes that signal durability and regulatory compliance. This material shift is hybridizing supply chains as manufacturers dual-source from appliance-grade and food-service metal fabricators.
EU REACH restrictions on phthalates and bisphenol-A in food-contact components are forcing polymer substitution in pressurized chambers. Manufacturers now specify Tritan copolyester or glass-lined reservoirs to maintain compliance. The beverage-contact subsystem segment is responding fastest, with German and French suppliers certifying alternative materials ahead of 2025 enforcement windows.
Subscription-based CO2 replenishment is compressing traditional retail cylinder exchange models. Direct-to-consumer platforms capture recurring revenue through connected appliance telemetry that triggers automatic refill shipments. This behavioral shift is most visible in US metropolitan markets where last-mile delivery density supports gas cylinder logistics economics.
Carbonate Drink Maker Market Segmentation
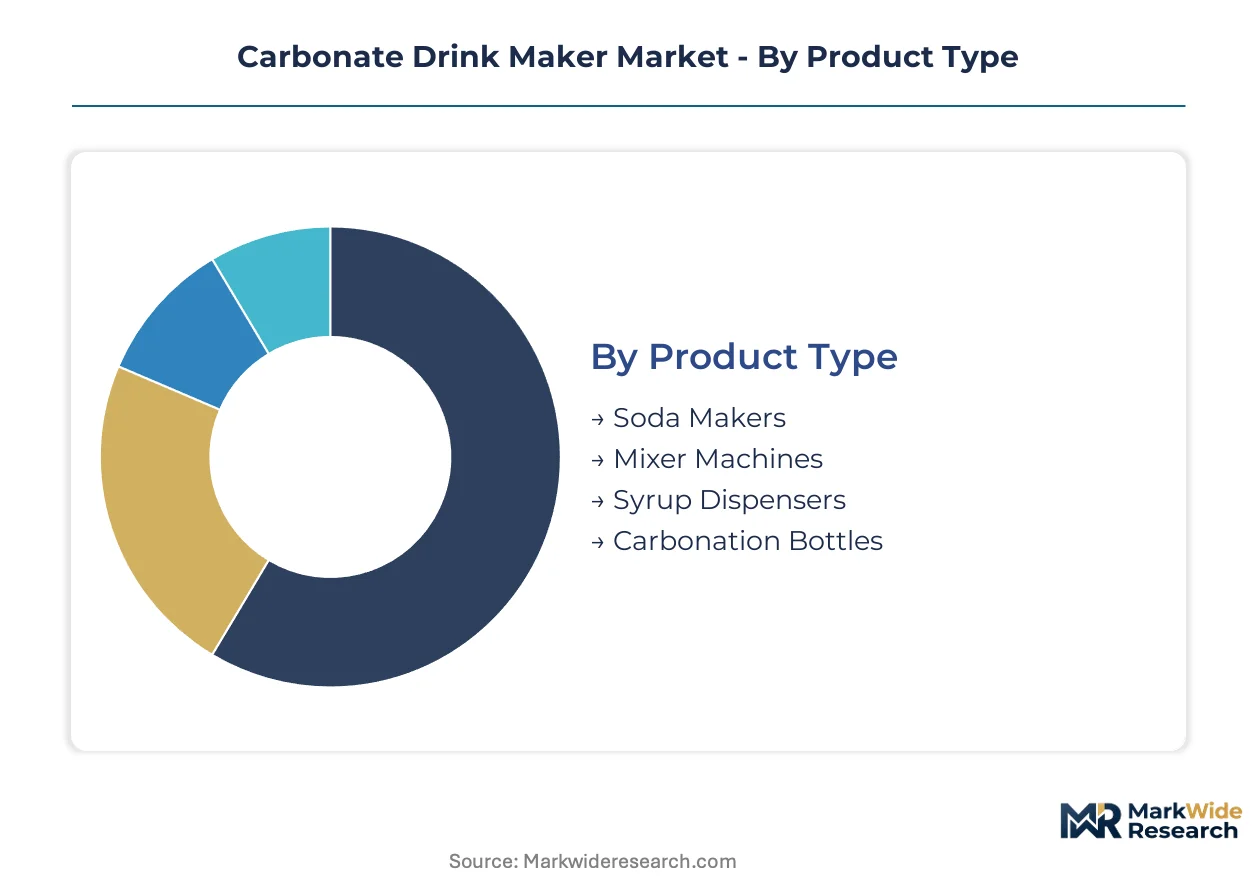
Segmentation in carbonate drink makers reveals how appliance design, channel economics, and user context fragment purchasing behavior. Manufacturers must align product specifications with distinct carbonation intensity needs and replenishment preferences across household and commercial settings.
Product Type:
Appliance architecture spans from integrated countertop systems to modular components that retrofit existing beverage infrastructure.
- Soda Makers:Self-contained countertop units combine pressurized CO2 injection with reusable bottles at 30-60 psi operating pressure. German households and Scandinavian municipalities with strict packaging waste sorting drive replacement of bottled water consumption with these systems.
- Mixer Machines:Bar-grade appliances integrate carbonation with flavor dosing and temperature control for precise cocktail preparation. Upscale restaurants in Paris and London specify these for tableside beverage service where presentation consistency commands premium pricing.
- Syrup Dispensers:Modular attachments meter concentrated flavor into carbonated base liquids. Food-service operators in Italian catering halls deploy these for rapid menu customization without dedicated bar staff.
- Carbonation Bottles:Portable pressure vessels enable carbonation of any compatible liquid without fixed appliance investment. Outdoor enthusiasts and off-grid users in rural Spain and Portugal favor these for camping and boat applications.
The dominant share belongs to Soda Makers, while Mixer Machines are closing the gap fastest.
Technology:
Power source and mechanical complexity segment users by convenience tolerance and energy access constraints.
- Electromechanical:Motor-driven compression systems automate pressure regulation and safety venting. Urban households across the Netherlands and Belgium prefer these for one-button operation with minimal user calibration.
- Manual:Hand-pump mechanisms generate pressure through physical force without electrical dependency. Remote cabins and sailing vessels in Norwegian fjords and Scottish Highlands specify these for off-grid carbonation reliability.
- CO2 Injection:Direct gas diffusion systems bypass mechanical compression for rapid saturation in commercial volumes. Beverage manufacturers in Denmark and Sweden integrate these into small-batch production lines for craft soda operations.
- Soda Stream:Proprietary cartridge interface systems lock consumables to specific hardware ecosystems. The installed base across German retail partnerships sustains recurring cylinder exchange revenue.
Electromechanical systems command the volume lead, though Manual variants gain share fastest in recreational and emergency-preparedness segments.
End User:
Carbonation demand fragments across consumption scale from individual households to industrial beverage production.
- Households:Residential purchasers prioritize countertop footprint, noise levels, and aesthetic integration with kitchen design. German environmental awareness and municipal recycling mandates accelerate adoption of reusable cylinder programs over single-use bottles.
- Restaurants:Full-service operators require NSF-certified components and rapid throughput for peak service windows. Brasseries in Lyon and bistros in Brussels specify commercial-grade systems with dual-pressure settings for water and wine spritzers.
- Beverage Manufacturers:Small-batch producers use carbonation as a process step in craft soda and sparkling wine operations. Producers in Italy's Veneto region and France's Loire Valley integrate these into traditional method alternatives.
- Catering Services:Mobile event operators demand portable systems with battery backup and rapid cylinder swap capability. Wedding and corporate event caterers across England's home counties deploy these for on-site beverage stations.
Households retain the dominant position, while Beverage Manufacturers expand most quickly as craft production scales.
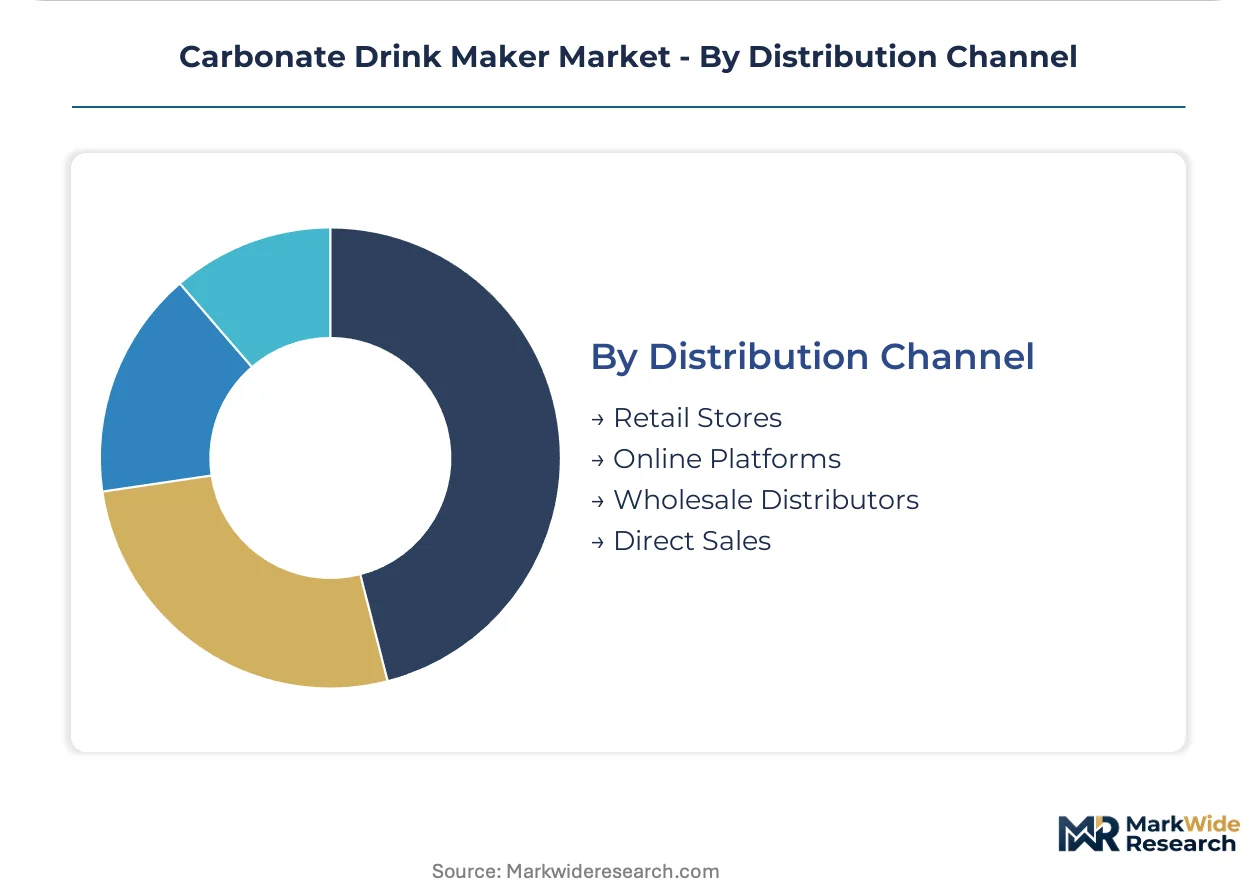
Distribution Channel:
Channel selection reflects purchase frequency, technical support needs, and replenishment logistics preferences.
- Retail Stores:Big-box and specialty kitchen retailers offer hands-on demonstration and immediate takeaway. French hypermarkets and German electronics chains move volume through seasonal promotional cycles.
- Online Platforms:Direct-to-consumer sites and marketplaces enable subscription-based cylinder replenishment with connected appliance telemetry. US metropolitan markets with dense last-mile delivery networks show strongest adoption of auto-ship gas refill programs.
- Wholesale Distributors:B2B channels supply food-service operators with volume pricing and consolidated equipment financing. Restaurant supply houses in Madrid and Milan bundle carbonation systems with beverage program consulting.
- Direct Sales:Manufacturer-owned channels capture full margin and customer relationship data. Premium brands with design-forward positioning in Scandinavia use flagship showrooms for brand experience before online conversion.
Retail Stores hold the largest share, while Online Platforms climb the fastest as subscription models reduce friction in repeat cylinder purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export countertop carbonation systems to Scandinavian households where municipal recycling mandates accelerate replacement of single-use bottles. The trade corridor funnels premium electromechanical units through Copenhagen and Stockholm distribution hubs.
Germany
Households in Bavaria and Baden-Württemberg replace bottled water with pressurized home carbonation systems at 30-60 psi operating pressure. The EU's Single-Use Plastics Directive enforces strict packaging waste sorting requirements that render disposable bottles economically punitive. Berlin's electronics retail chains move volume through seasonal promotional cycles tied to environmental awareness campaigns.
United States
Metropolitan households in New York and California adopt subscription-based CO2 cylinder replenishment through connected appliance telemetry. California SB 54 imposes extended producer responsibility rules for cylinder recovery and packaging compliance. Los Angeles and San Francisco distribution networks support dense last-mile delivery logistics for gas refill auto-ship programs.
France
Upscale restaurants in Paris and Lyon specify bar-grade carbonation systems for tableside beverage service where presentation consistency commands premium pricing. EU REACH restrictions on phthalates and bisphenol-A in food-contact components force polymer substitution in pressurized chambers. Brasseries along the Rhône-Alpes corridor integrate dual-pressure settings for water and wine spritzers.
Sweden
Design-conscious households in Stockholm and Gothenburg specify brushed stainless-steel finishes that signal durability and regulatory compliance. The EU Green Deal accelerates procurement shifts toward reusable cylinder exchange programs over single-use alternatives. Malmö's municipal recycling mandates enforce strict sorting requirements that favor home-beverage systems.
Italy
Small-batch producers in Veneto and the Loire Valley integrate carbonation into craft soda and sparkling wine operations as traditional method alternatives. EFSA approval cycles for new polymer formulations delay product refresh schedules by 12-18 months. Catering halls in Milan deploy modular syrup dispensers for rapid menu customization without dedicated bar staff.
Carbonate Drink Maker Market Competitive Landscape
Channel-controlling players compete with product-specialist players for shelf space and direct-to-consumer relationships. The vendor base clusters around three strategic archetypes: ecosystem-locked incumbents with proprietary CO2 infrastructure, design-forward premium specialists, and versatility-focused challengers. Consolidation pressure intensifies as recurring revenue models favor scale in cylinder exchange logistics. Dominant competitive moves include strategic partnerships with retail gas distributors and portfolio diversification into connected appliance architectures.
Among ecosystem-anchored players, SodaStream International Ltd. occupies a position defined by proprietary cartridge interface systems that lock consumables to specific hardware. Drinkmate Inc. exemplifies the versatility archetype through positioning that enables carbonation of beverages beyond water. Aarke AB represents the design-forward tier with premium positioning in European households. These three anchors illustrate how competitive differentiation fragments across hardware, consumables, and aesthetic vectors rather than concentrating in any single capability.
| Leading Market Players |
|---|
| SodaStream International Ltd. |
| Drinkmate Inc. |
| Hamilton Beach Brands Holding Company |
| Breville Group Ltd. |
| Cuisinart |
| iSi GmbH |
| Aarke AB |
| Spärkel Beverage Systems |
| KitchenAid |
| Others |
Pricing and Supply Chain Analysis
Regulatory chokepoint exposure in EU food-contact material certification determines both tier spreads in finished appliance pricing and the geographic shape of component sourcing. REACH compliance timelines and FDA parallel review cycles compress margin structures for non-compliant suppliers while rewarding early-certification investments with transatlantic pricing power.
Pricing Analysis
Prior-generation manual pump systems trade at entry points below electromechanical units, while next-generation connected appliances with telemetry-enabled replenishment command substantial premiums. Three-tier pricing structure across premium, standard, and economy levels separates design-forward stainless-steel finishes from polymer-based countertop units and portable hand-pump alternatives. Cost compression in economy tiers intensifies because raw material substitution toward Tritan copolyester and glass-lined reservoirs raises base manufacturing costs. Household buyers in Germany and Scandinavia show lowest price sensitivity due to municipal recycling mandate penalties on single-use alternatives, while recreational off-grid users in Southern Europe prioritize portability over feature depth.
Supply Chain Analysis
Extended payment terms from German and French appliance assemblers to Southeast Asian polymer fabricators are compressing working capital cycles for tier-two component suppliers. Food-grade CO2 production concentrates in Germany, Denmark, and the Netherlands, while precision metal fabrication for premium housings draws from Sweden and Northern Italy. Raw material dependencies span aluminum for cylinders, Tritan copolyester for compliant reservoirs, and electronic control modules for connected variants. Single-source vulnerability in food-grade gas purification equipment creates bottlenecks during peak summer demand windows. Distribution runs through retail partnerships for cylinder exchange density in European urban cores, supplemented by direct-to-consumer auto-ship platforms in US metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbonate drink maker market sits at a regulatory-technology inflection where EU packaging waste directives and smartphone-integrated appliance architectures simultaneously reshape competitive viability and consumer purchasing patterns.
For Market Incumbents: Insulate recurring revenue streams by deepening proprietary CO2 exchange infrastructure density in German retail partnerships against direct-to-consumer subscription erosion. Accelerate certification investment for REACH-compliant polymer alternatives ahead of enforcement windows to eliminate redundant redesign cycles. Channel control through flagship showroom experiences in Scandinavian design-conscious markets preserves premium positioning against design-forward challengers.
For New Entrants and Emerging Players: Mid-market beverage versatility applications in Southern European households represent the most penetrable entry point, as juice and cocktail carbonation occasions remain underserved by incumbent water-focused positioning. Portable manual systems for off-grid recreational users in rural Spain and Portugal offer white-space penetration with minimal electromechanical incumbent competition. Go-to-market execution through specialty outdoor retail partnerships rather than kitchen appliance channels captures price-insensitive adventure-segment buyers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors ecosystem-locked players with captive consumables infrastructure over pure hardware manufacturers. Long-term viability over the coming decade rests on recurring revenue attachment rates rather than one-time appliance margins. Acquisition target archetypes include connected appliance telemetry platforms and regional CO2 cylinder logistics operators. The signal to watch is subscription auto-ship penetration rates in US metropolitan markets as an indicator of channel-shift momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Connected Appliance Telemetry Integration | Enables predictive CO2 replenishment and locks households into subscription revenue streams. |
| REACH-Compliant Material Certification | Secures automatic EU market access and eliminates redundant FDA parallel review cycles. |
| Direct-to-Consumer Platform Launch | Bypasses retail markups and captures customer relationship data for personalization. |
| Retail Cylinder Exchange Partnership Expansion | Builds last-mile logistics density that sustains recurring consumables economics. |
| Beverage Versatility R&D Investment | Opens juice and cocktail carbonation occasions previously served by pre-mixed canned alternatives. |
Research Methodology
A spread of perspectives from appliance product managers, CO2 supply chain coordinators, retail category buyers, and regulatory affairs specialists converged on the working assumptions underlying demand projections. Primary interviews with kitchen electronics procurement leads at French hypermarkets and German electronics chains combined with secondary validation from EU REACH enforcement documentation, FDA food-contact material guidance, and municipal recycling mandate records. Bottom-up triangulation across household penetration rates and top-down cross-check against packaged beverage displacement volumes anchored volume estimates.
Demand-supply balance modeling across the projection horizon incorporated segmentation dimensions spanning product architecture, power source technology, end-user scale, and channel structure. CAGRs derived from fitted growth curves applied to replacement cycle analysis and new household adoption patterns. Industry-specific forecast inputs included seasonal CO2 demand cyclicality and certification timeline delays for alternative polymer formulations.
Practitioners should monitor regulatory enforcement acceleration in EU member states and connected appliance subscription cancellation rates for early signals of structural shift. Forecasts reflect documented assumptions about municipal mandate expansion and material substitution cost curves. Macroeconomic contraction in discretionary appliance spending, regulatory deviation in food-contact standards, or technological disruption in gas generation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Global Electrolyte Drinks Market
Beverages
Victorian Jars Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Beverage Cooler Market
Beverages
GCC Bottled Water Market
Beverages
Indonesia Bottled Water Market
Beverages
Caffeinated Beverage Market
Beverages
Drinking Water Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Carbonated Soft Drinks Market
Beverages
India Sports Drinks Market
Beverages
US Bubble Tea Market
Beverages
Juice Market
Beverages
Flavored Powder Drinks Market
Beverages
Solid Beverages Market
Beverages
Birch Water Market