
 Baby Drinking Water Market | 2026-2036
Baby Drinking Water Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Drinking Water Market Outlook
NSF/ANSI Standard 60 certification is reorganizing competitive access in the Baby Drinking Water Market, filtering out suppliers unable to meet strict contaminant thresholds for products marketed to infants. Nestlé Waters leverages its multi-continental bottling infrastructure to sustain shelf presence across premium retail channels. Danone Waters anchors its position through pediatric nutrition credibility that extends into water positioning. Nongfu Spring competes on domestic scale within China, where it controls distribution depth in tier-one and tier-two cities.
Baby drinking water denotes water specifically processed or sourced to meet stringent purity, mineral balance, and microbiological safety criteria suitable for infant consumption, typically achieving total dissolved solids below 100 ppm and rigorous bacterial elimination through reverse osmosis, distillation, or protected spring capture. Its commercial purpose centers on providing caregivers with a ready-to-use hydration alternative that eliminates boiling and cooling steps while mitigating risks from tap water variability. Purified water and mineral water categories dominate current volume, with purified variants leading in North American markets where zero-contaminant positioning commands premium placement, while spring water segments gain traction in European retail environments where natural source provenance drives caregiver trust. Packaging type segmentation shows bottled formats maintaining margin concentration due to material cost structures, though pouch and carton innovations are capturing growth in online retail channels where shipping weight reduction matters.
FDA bottled water standards, BIS certification mandates for imported water products, and EU Drinking Water Directive frameworks collectively elevate compliance costs while creating defensible moats for certified producers. These regulatory layers shape demand by forcing explicit infant-use labeling and periodic testing protocols that informal or regional suppliers struggle to sustain. Stakeholders must monitor evolving contaminant screening lists and packaging material restrictions, as regulatory tightening in major consumption markets will likely determine which production configurations remain economically viable.
Market Dynamics
NSF/ANSI Standard 60 certification requirements are compressing supplier participation in the Baby Drinking Water Market, creating a bifurcation between certified producers capable of sustained compliance and regional bottlers facing exclusion from premium retail channels.
Growth Catalysts
- Urban Middle-Class Expansion:China's tier-one and tier-two cities are witnessing concentrated demand substitution as households upgrade from standard bottled water to infant-formulated alternatives with verified purity credentials.
- FDA Bottled Water Standards:The United States regulator's evolving contaminant screening protocols are elevating product safety expectations, pulling caregivers toward labeled infant-use products with documented testing histories.
- Reverse Osmosis Advancement:Membrane technology improvements are reducing production energy intensity while achieving total dissolved solids below 100 ppm, expanding economically viable supply capacity.
Market Restraints
- Packaging Material Cost Volatility:Food-grade PET resin and aluminum input prices fluctuate with crude oil and bauxite markets, compressing margin stability for producers maintaining premium positioning.
- Spring Source Concentration Risk:Protected aquifer access concentrates in specific geological zones, creating supply vulnerability where single-source dependence limits geographic diversification.
- Tap Water Quality Improvement:Municipal treatment upgrades in developed economies reduce the perceived risk differential driving category substitution, threatening volume expansion in mature markets.
Strategic Opportunities
- Pouch and Carton Formats:Lightweight flexible packaging is capturing growth in e-commerce channels where shipping weight reduction directly improves unit economics and repeat purchase frequency.
- EU Drinking Water Directive Alignment:The framework's explicit infant-use labeling requirements create regulatory tailwinds for producers achieving compliance ahead of enforcement deadlines.
- Rural China Penetration:Tier-three and tier-four cities remain underpenetrated relative to urban saturation, offering whitespace for distribution infrastructure investment.
Industry Challenges
- Microbiological Testing Timeline Compression:BIS certification mandates for imported water products into India require extended laboratory validation cycles that delay market entry and working capital recovery.
- Cross-Contamination Prevention Infrastructure:Dedicated production lines for infant-formulated products demand capital-intensive facility segregation that smaller regional bottlers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Drinking Water Market |
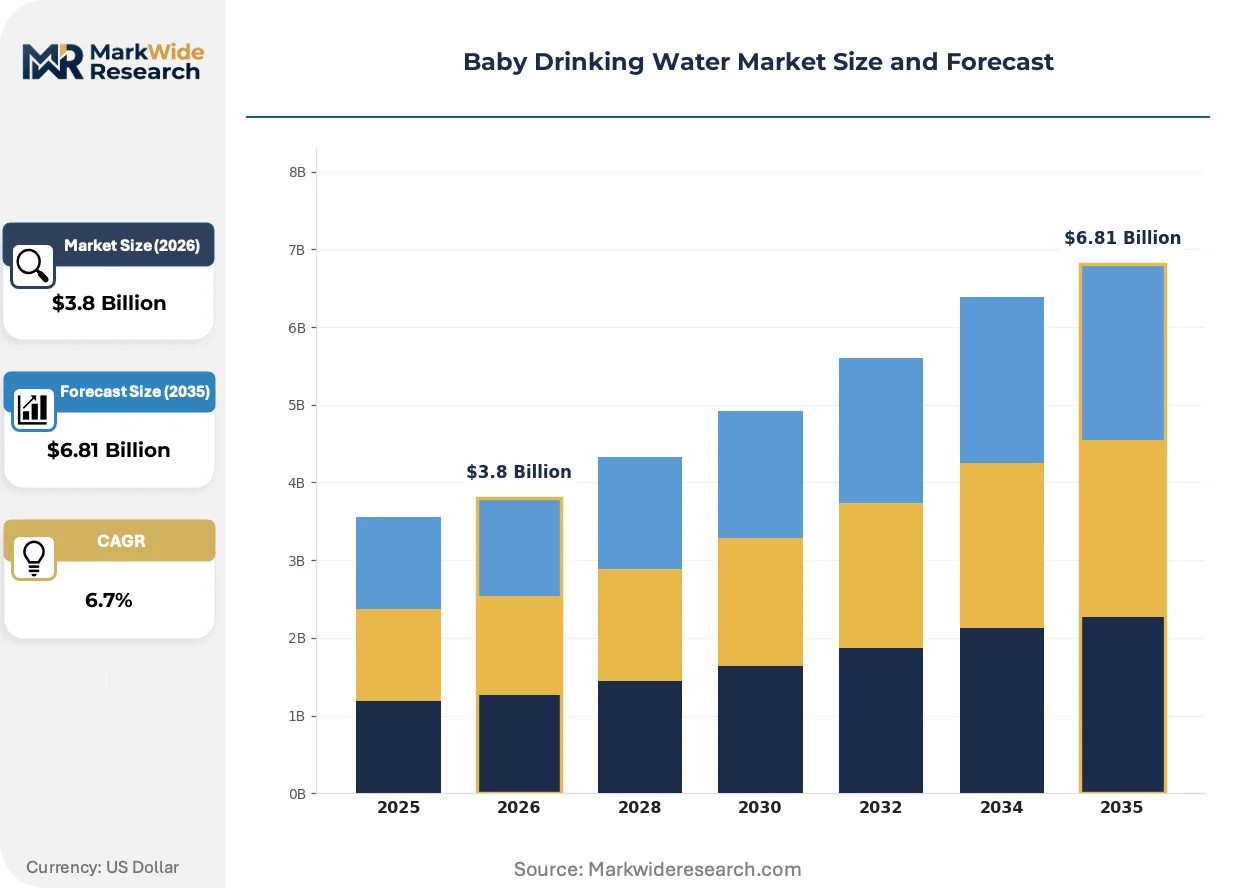
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Water, Purified Water, Spring Water, Distilled Water Packaging Type: Bottled, Carton, Pouch, Tetra Pack Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Baby Specialty Stores End User: Infants, Toddlers, Children, Caregivers |
| Companies Covered | Sant' Anna, Waiwera, Nestlé Waters, Nursery, MAHAC, Danone Waters, Nongfu Spring, PepsiCo, Eva Water, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Drinking Water Market Strategic Shifts
Technological substitution in purification methods, tightening regulatory frameworks across multiple geographies, and channel migration toward direct-to-consumer models are actively restructuring competitive access and margin distribution in the Baby Drinking Water Market.
Aseptic cold-filling technology is supplanting traditional hot-fill bottling processes in infant-formulated water production. Premium segment producers in Japan and South Korea are adopting these systems to eliminate thermal degradation of packaging integrity while maintaining sterile conditions. The shift is compressing equipment amortization timelines and raising capital barriers for new market entrants.
The EU Drinking Water Directive's expanded contaminant screening lists are forcing reformulation of mineral balance profiles in products marketed for infant consumption. Producers serving European retail channels must now document periodic testing for emerging substances including microplastics and pharmaceutical residues. Spring water segments face particular adjustment pressure as natural source variability complicates consistent compliance.
Subscription-based replenishment models are displacing traditional retail stock-up behavior among urban caregiver segments. Direct-to-consumer platforms in China and the United States are capturing recurring revenue through scheduled delivery of multi-unit packaging formats. This pattern is most visible in coastal Chinese cities where logistics density supports same-day or next-day fulfillment guarantees.
Baby Drinking Water Market Segmentation
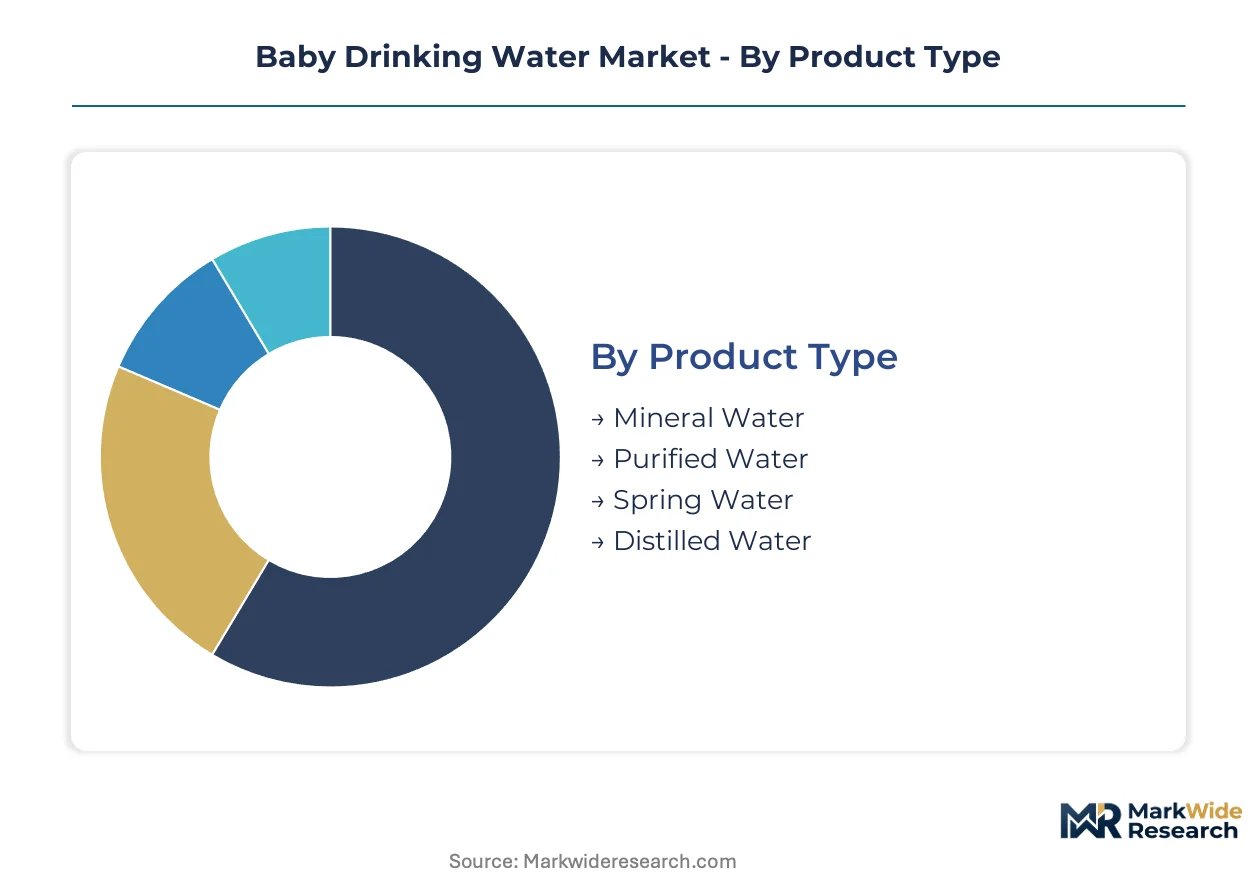
Segmentation in the Baby Drinking Water Market reveals how purity specifications, packaging convenience, and channel accessibility shape purchasing decisions across caregiver demographics. Understanding these divides exposes where premium positioning commands price acceptance versus where volume scale determines competitive survival.
Product Type:
Purified water variants dominate domestic consumption in North America and East Asia, while spring water maintains stronger export orientation toward European markets seeking natural provenance credentials.
- Purified Water:Reverse osmosis and distillation processes achieve total dissolved solids below 100 ppm, eliminating microbial and chemical contaminants through multi-stage filtration. Demand concentrates in US urban households where FDA bottled water standards elevate trust in zero-contaminant labeling. The segment commands premium shelf placement in pharmacy and grocery channels.
- Mineral Water:Controlled mineral balance profiles—typically calcium, magnesium, and potassium at infant-safe concentrations—support developmental hydration needs without renal burden. Adoption is climbing fastest in China's tier-one cities where pediatrician recommendations drive substitution from standard bottled water.
- Spring Water:Sourced from protected aquifers with natural filtration through geological strata, maintaining microbiological safety without chemical processing. European caregivers favor this format for perceived natural integrity.
- Distilled Water:Vaporization and condensation remove virtually all dissolved solids and biological material, producing the highest purity commercially available. Production energy intensity limits geographic distribution radius.
Purified water holds the largest share; momentum sits with mineral water.
Packaging Type:
Format selection tracks channel economics: rigid containers protect margin in brick-and-mortar retail while flexible formats reduce logistics cost in direct-to-consumer expansion.
- Bottled:Food-grade PET and glass formats dominate retail shelf presence with established recycling infrastructure and caregiver familiarity. The format captures highest volume in supermarket and convenience channels across all major markets.
- Pouch:Lightweight flexible film construction reduces shipping weight by 60-70% versus rigid alternatives, enabling competitive unit economics in subscription-based replenishment models. Growth concentrates in Chinese e-commerce where same-day delivery density supports frequent small-quantity orders.
- Carton:Paperboard-based packaging with aseptic lining offers sustainability positioning and efficient palletization for bulk retail distribution.
- Tetra Pack:Multi-layer carton technology provides extended shelf stability without refrigeration, suited to pharmacy and specialty retail environments.
Bottled formats retain volume leadership; pouches are expanding most quickly.
Distribution Channel:
Channel mix reflects urban density and caregiver time constraints: dense metropolitan areas shift toward online replenishment while suburban and rural markets depend on physical retail access.
- Online Retail:Subscription platforms and marketplace storefronts capture recurring revenue through scheduled delivery, reducing stock-out risk for caregivers. The channel is gaining share fastest in coastal Chinese cities and US metropolitan corridors with reliable last-mile logistics.
- Supermarkets:Mass retail chains provide discovery and impulse purchase opportunities alongside routine grocery shopping, maintaining volume concentration in developed markets.
- Baby Specialty Stores:Curated retail environments with trained staff offer education and trust transfer for first-time caregivers seeking product guidance.
- Convenience Stores:Proximity-based purchasing serves urgent replenishment needs, though limited SKU depth restricts premium product access.
Supermarkets retain the largest transaction volume; online retail shows the steepest expansion trajectory.
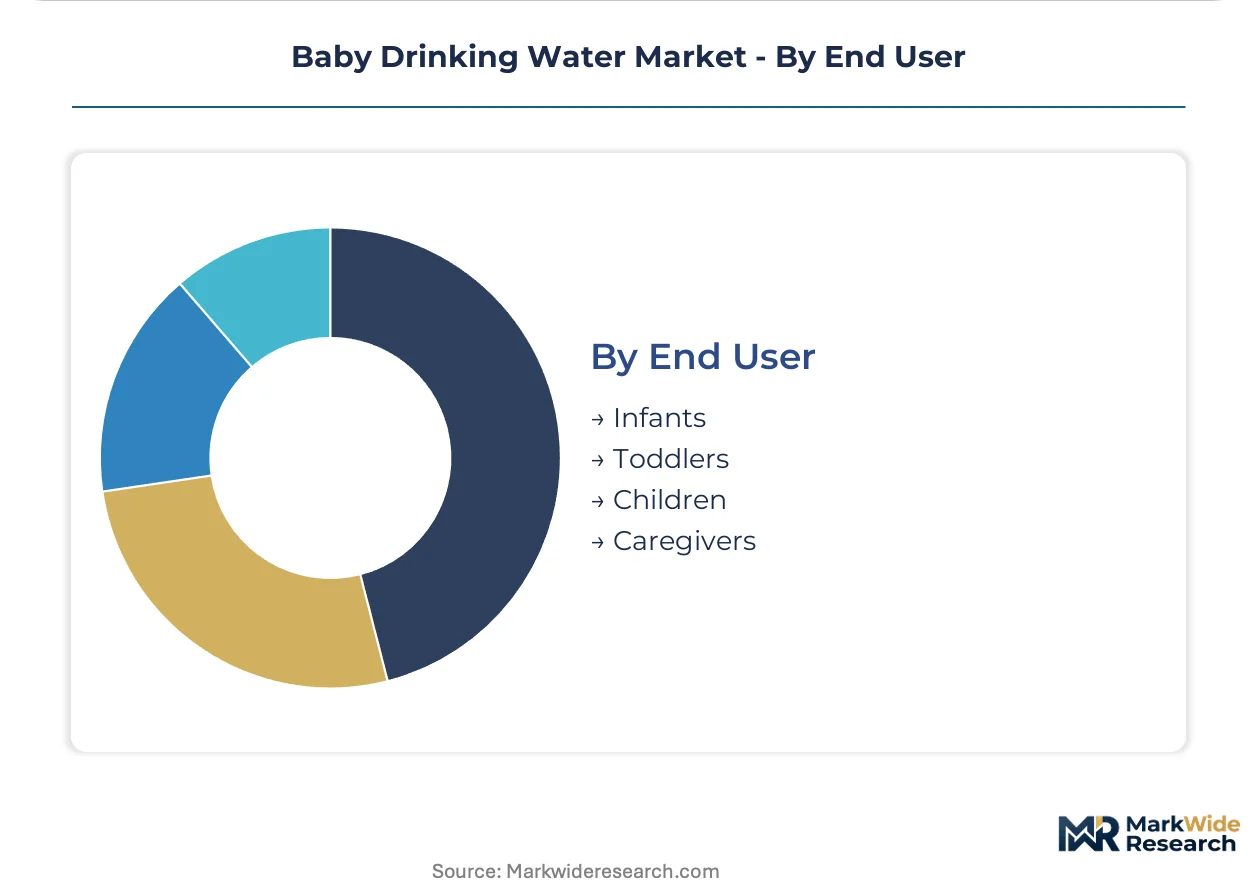
End User:
User-based segmentation aligns product specification with developmental stage: infant formulations emphasize mineral restriction while toddler variants permit broader nutritional profiles.
- Infants:Formulations targeting 0-12 month consumption require strictest purity protocols and mineral balance controls to support immature renal function. This segment commands highest per-liter pricing and drives certification investment.
- Toddlers:1-3 year consumption permits slightly expanded mineral content as physiological tolerance develops, broadening sourcing flexibility for producers.
- Children:3-12 year positioning competes more directly with standard bottled water, with differentiation relying on taste preference and parental habit persistence.
- Caregivers:Adult consumption of infant-formulated products occurs in household sharing scenarios, representing incidental volume rather than targeted demand.
Infant-targeted products generate the highest revenue per unit; toddler segments offer volume scale expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban middle-class households with infants drive geographic demand concentration, with substitution patterns varying sharply by municipal water quality perceptions and regulatory enforcement intensity across national markets.
United States
FDA bottled water standards and evolving contaminant screening protocols pull caregivers toward labeled infant-use products with documented testing histories. The agency's periodic updates to purity thresholds create compliance momentum that favors established certified producers. Demand clusters in metropolitan corridors along the East and West Coasts where tap water quality skepticism runs highest among educated caregiver demographics.
China
Pediatrician recommendations and urban middle-class expansion in tier-one and tier-two cities accelerate substitution from standard bottled water to infant-formulated alternatives. SAMR enforcement of GB standards for packaged drinking water tightens product safety expectations. Distribution depth concentrates in Shanghai, Beijing, and Guangzhou where Nongfu Spring and domestic competitors battle for shelf presence in premium retail channels.
Germany
The EU Drinking Water Directive's expanded contaminant screening lists and explicit infant-use labeling requirements reshape competitive access for producers serving European retail channels. EFSA guidance on mineral balance for infant consumption influences formulation decisions. Industrial activity clusters in Bavaria and North Rhine-Westphalia where spring water sourcing and aseptic processing infrastructure support premium product output.
India
BIS certification mandates for imported water products create extended laboratory validation cycles that delay market entry and compress supplier participation. FSSAI parallel requirements for domestic producers elevate compliance costs. Demand emergence concentrates in Mumbai, Delhi-NCR, and Bangalore where organized retail expansion exposes urban caregivers to branded infant-formulated alternatives.
Japan
METI-industry coordination on food safety standards and JIS certification for packaging materials shapes product development priorities. Aseptic cold-filling technology adoption in infant-formulated water production compresses equipment amortization timelines. Production and consumption gravity sits in the Kanto region around Tokyo where logistics density supports premium channel distribution and caregiver willingness-to-pay peaks.
Baby Drinking Water Market Competitive Environment
Player mix skews toward multinational beverage conglomerates with existing bottling infrastructure and pediatric nutrition credibility, creating a tiered structure where certification capacity separates sustainable participants from marginal regional bottlers. The competitive terrain splits between scale-driven volume players, spring-source specialists with protected aquifer access, and domestic champions leveraging distribution depth in high-growth emerging markets. Dominant competitive moves include geographic expansion through multi-channel distribution partnerships and portfolio diversification into adjacent infant nutrition categories.
Within the multinational tier, Nestlé Waters and Danone Waters occupy positions anchored by pediatric nutrition credibility that extends into water positioning. Nongfu Spring exemplifies the domestic-scale archetype, leveraging control over tier-one and tier-two city distribution networks in China where urban middle-class demand substitution accelerates fastest. These three entities represent the strategic archetypes—global infrastructure, nutrition-brand extension, and domestic scale—that structure competitive rivalry across certification-intensive regulatory environments.
| Leading Market Players |
|---|
| Sant' Anna |
| Waiwera |
| Nestlé Waters |
| Nursery |
| MAHAC |
| Danone Waters |
| Nongfu Spring |
| PepsiCo |
| Eva Water |
| Others |
Value Chain & Pricing Dynamics
Ninety-day laboratory validation cycles for BIS certification tie up working capital and compress margin buffers for entrants targeting Indian retail channels, concentrating pricing power with certified incumbents who amortize compliance costs across multi-continental volumes. This lead-time structure forces a bifurcation between premium infant-formulated positioning and commoditized standard bottled water alternatives.
Pricing Analysis
Cost-plus contracts with food-grade PET resin indexation dominate procurement agreements between bottlers and packaging suppliers, tethering margin stability to crude oil volatility. Three-tier pricing structure across premium, standard, and economy levels separates NSF/ANSI-certified infant formulations from pediatric-recommended mineral balances and unlabeled purified alternatives. Pricing pressure stems from aluminum and resin input volatility squeezing producers maintaining aseptic cold-filling infrastructure. First-time caregivers in China's tier-one cities show lowest price sensitivity, while rural households in tier-three and tier-four cities demand economy-tier alternatives.
Supply Chain Analysis
Aquifer access concentration in Bavaria, the Alps, and Japan's Kanto region underwrites premium spring water sourcing but creates single-source vulnerability for European and Japanese producers. Reverse osmosis membrane production draws from South Korea, Japan, and the United States, while food-grade PET resin feeds from China, Saudi Arabia, and the United States. Tariff exposure on imported packaging materials threatens margin stability for regional bottlers lacking captive resin supply. Distribution runs through pharmacy and baby specialty channels for premium positioning, with e-commerce subscription platforms capturing recurring revenue in urban Chinese markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as caregiver demand splits across certification tiers, channel preferences, and mineral balance specifications, creating defendable niches for specialists against multinational volume players.
For Market Incumbents: Consolidate certification moats by accelerating NSF/ANSI Standard 60 and EU Drinking Water Directive compliance ahead of enforcement deadlines, locking out regional bottlers unable to finance extended laboratory validation cycles. Deepen backward integration into protected aquifer access and aseptic processing infrastructure to defend margin position against resin cost volatility and emerging pouch-format entrants. For New Entrants and Emerging Players: Lead with lightweight flexible packaging formats targeting Chinese e-commerce subscription channels where shipping weight reduction improves unit economics and same-day delivery density supports recurring revenue capture. Target tier-three and tier-four Chinese cities where pediatrician recommendation networks remain underdeveloped and domestic champions have not yet saturated distribution. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational beverage conglomerates divesting non-core water portfolios; these assets carry embedded bottling infrastructure and retail shelf access that accelerate market entry for focused infant-nutrition specialists. Long-term viability hinges on regulatory compliance capacity rather than brand equity alone. Watch BIS and FDA contaminant screening list expansions as inflection indicators that will determine which production configurations remain economically viable.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Filling Infrastructure Investment | Eliminates thermal degradation while meeting Japan METI safety standards for infant formulations. |
| EU Drinking Water Directive Pre-Compliance | Captures regulatory tailwind ahead of microplastics and pharmaceutical residue testing mandates. |
| Pouch Format E-Commerce Launch | Reduces shipping weight by 60-70% for Chinese subscription platforms with same-day delivery density. |
| Protected Aquifer Backward Integration | Secures natural source provenance credentials valued by European caregiver demographics. |
| Pediatrician Recommendation Network Development | Builds trust transfer infrastructure in China's tier-one and tier-two cities where substitution accelerates. |
Study Parameters
A spread of perspectives from brand managers at multinational bottlers, category buyers at pharmacy chains, regulatory affairs leads at certification bodies, and supply planners at packaging converters converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA bottled water standard filings, BIS certification registries, EU Drinking Water Directive amendments, and customs records for food-grade PET resin trade flows. Bottom-up volume estimates triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include product type hierarchy, packaging format economics, distribution channel penetration rates, and end-user developmental stage across the projection horizon. CAGRs derived from regression analysis of historical substitution patterns and regulatory enforcement intensity. Forecast inputs incorporated aseptic processing capacity buildout timelines and spring source concentration risk assessments.
The analysis sits within stated boundaries; outcomes outside sustained urban middle-class expansion in China and continued tap water quality skepticism in US coastal metros would require recalibration. Practitioners should keep alternative scenarios live as BIS certification processing delays and FDA contaminant screening list expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Asia-Pacific Spring Water Market
Beverages
US and Canada Premium Bottled Water Market
Beverages
United Kingdom Energy Drink Market
Beverages
Ready to Drink Margarita Market
Beverages
Japan Energy Drink Market
Beverages
Asia-Pacific Energy Drink Market
Beverages
Beverage Multipacks Market
Beverages
Fruit Beverages Market
Beverages
Sarsaparilla Market
Beverages
Hydrogen Water Bottle Market
Beverages
Fermented Drinks Market
Beverages
Soy Drinks Market
Beverages
Aloe Vera Drinks Market
Beverages
Foaming Creamer Market
Beverages
Fusion Beverages Market
Beverages
Sparkling Soda Market