
 Aloe Vera-Based Drink Market | 2026-2036
Aloe Vera-Based Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Aloe Vera-Based Drink Market Analysis
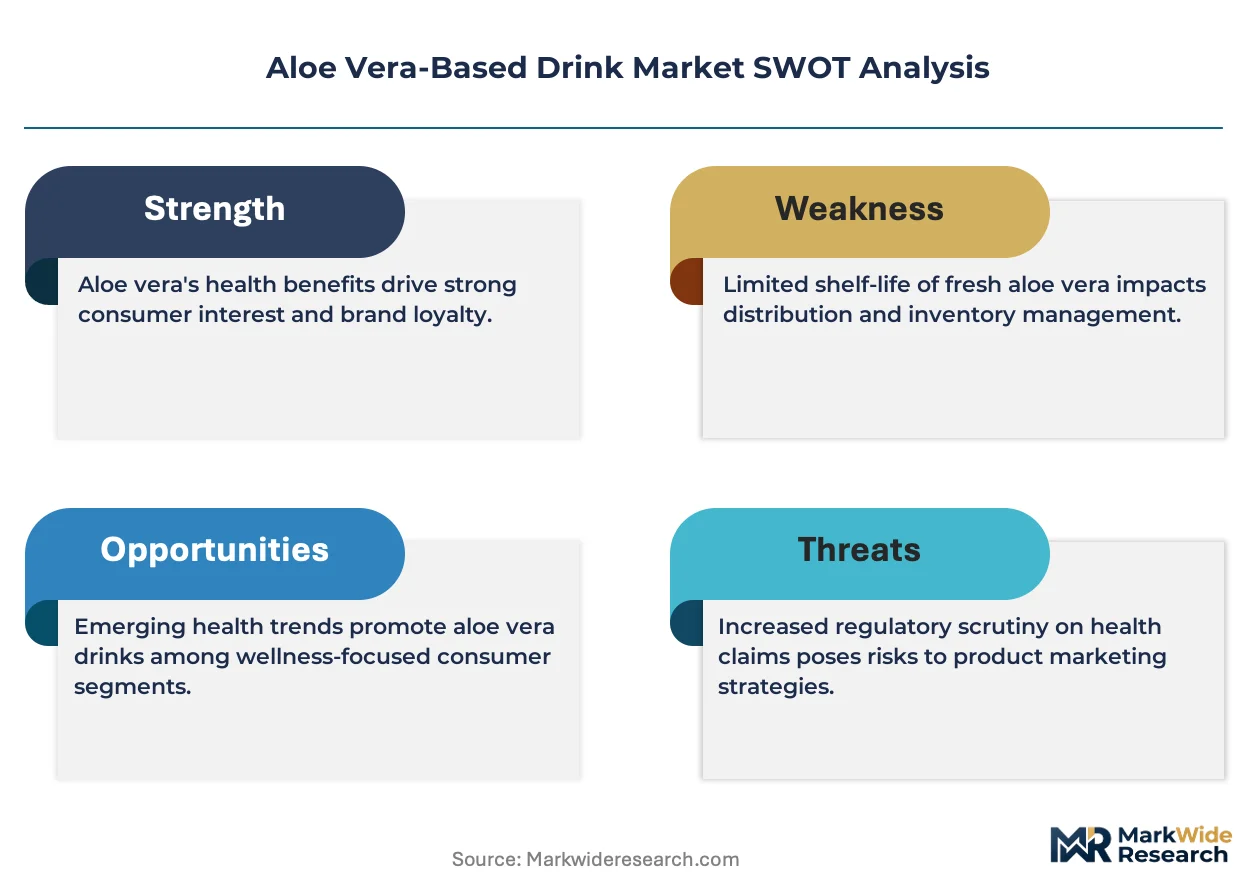
Premium organic certification is collapsing the gap between mass-market and artisanal aloe vera drinks. ALO Drink leverages its vertical integration from plantation to bottle to sustain margin control across North American health stores. Forever Living Products anchors its position through direct-to-consumer channels that bypass traditional retail markup structures. OKF Corporation dominates East Asian convenience store distribution with specialized aseptic filling lines for aloe vera gel suspensions.
An aloe vera-based drink is a non-alcoholic beverage containing processed Aloe barbadensis miller leaf extract, typically standardized to 0.3-1.0% aloin content and suspended with pulp or gel particles in aqueous solution, manufactured through cold-press extraction followed by pasteurization or high-pressure processing to preserve polysaccharide bioactivity. Its primary commercial purpose is delivering hydration with associated digestive comfort and antioxidant intake in ready-to-consume formats. Pure aloe vera juice occupies the mature volume base but faces margin compression from commodity aloe leaf sourcing in Mexico and China. Aloe vera with flavors captures the fastest-growing demand as mango, pomegranate, and green tea infusions attract younger consumers seeking palatable entry points to functional beverages. Tetra packs lead packaging type preference in European retail due to shelf stability and lightweight logistics, while bottles sustain premium positioning in North American health stores where visual pulp suspension signals freshness.
The US FDA polices structure-function claims under DSHEA and food labeling rules, compelling manufacturers to distinguish supplement-positioned aloe drinks from conventional beverages. EFSA health claim regulations in Europe restrict digestive benefit assertions without authorized Article 13.1 or 13.5 submissions, creating compliance cost barriers for new entrants. China's SAMR and national food safety standards for plant-based beverages impose aloin limits and heavy metal testing that shape import qualification protocols. Stakeholders must monitor evolving clinical evidence requirements as regulators on both sides of the Atlantic tighten substantiation thresholds for botanical functional claims.
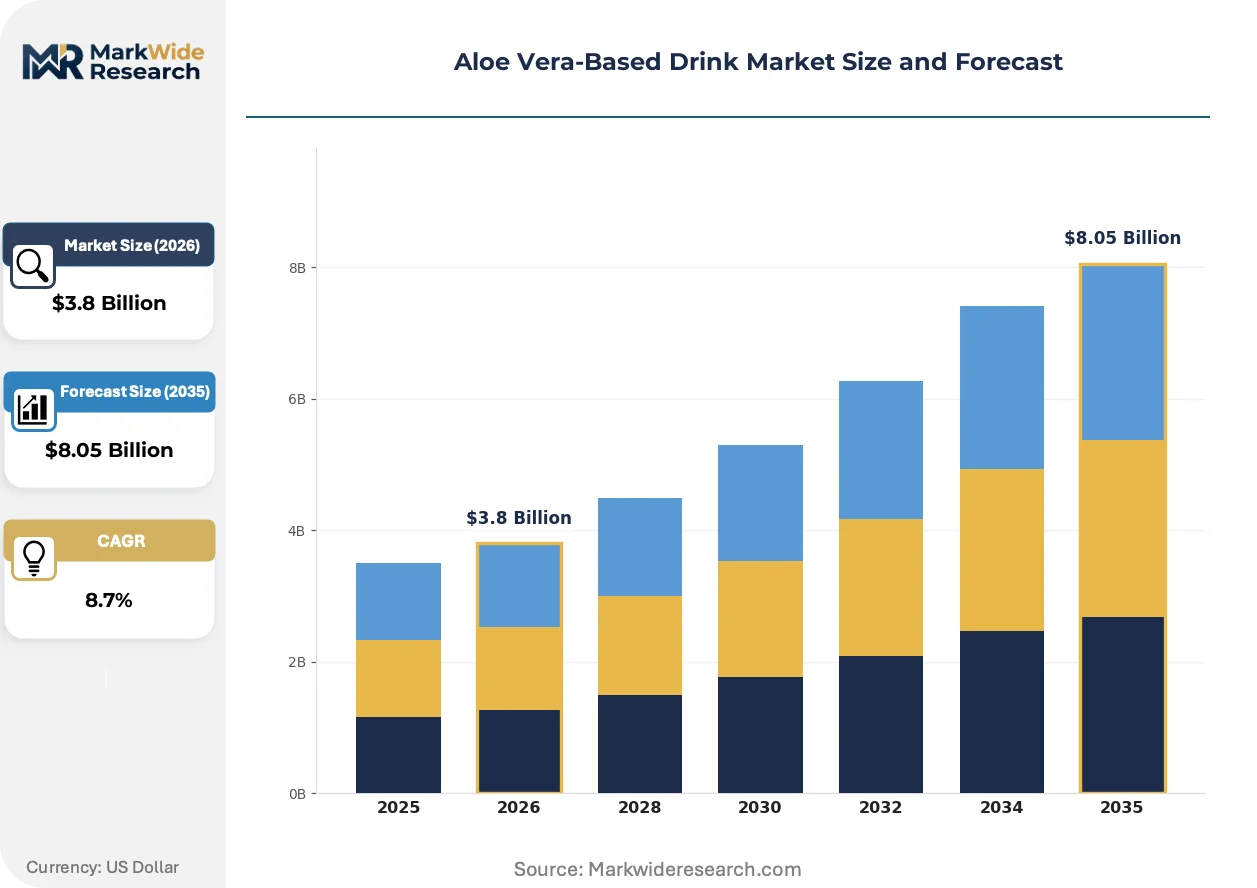
Market Dynamics
Clinical validation requirements from FDA and EFSA are compressing marketing timelines and forcing manufacturers to restructure R&D budgets toward human trials rather than traditional consumer advertising.
Growth Catalysts
- Fitness sector demand:Gym chains and boutique wellness studios are adding aloe vera drinks to post-workout retail shelves, creating new points of impulse purchase.
- EFSA Article 13.5 pathway:Successful digestive health claim authorizations would unlock premium positioning in European supermarkets previously restricted to generic hydration messaging.
- Aseptic filling technology:Specialized lines for gel suspension are reducing spoilage rates and extending shelf life without preservatives that conflict with clean-label positioning.
Market Restraints
- Aloe leaf commodity sourcing:Mexican and Chinese harvest volatility creates margin pressure when leaf prices spike during drought cycles.
- Substitution by kombucha and kefir:Fermented beverages with stronger probiotic clinical backing capture overlapping digestive health positioning at comparable price points.
- EFSA health claim substantiation costs:Article 13.1 and 13.5 submission requirements exceed €500,000 per claim, excluding smaller manufacturers from authorized benefit messaging.
Strategic Opportunities
- South Korean convenience channel:Dense urban retail networks and established consumer familiarity with functional beverages offer expansion runway for imported brands.
- Direct-to-consumer subscription models:Monthly delivery programs bypass retail slotting fees and capture recurring revenue with higher lifetime value metrics.
- High-pressure processing convergence:Cold pasteurization combined with nitrogen dosing preserves polysaccharide bioactivity while eliminating thermal degradation of flavor compounds.
Industry Challenges
- Clinical trial design expertise:Manufacturers lack in-house capability to structure GI transit time and immune marker studies that satisfy peer-review standards.
- Multi-jurisdiction label compliance:Simultaneous FDA DSHEA, EFSA food supplement, and China SAMR filings require parallel legal review teams with botanical-specific experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aloe Vera-Based Drink Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Aloe Vera Juice, Aloe Vera with Flavors, Aloe Vera Drink Mix, Aloe Vera Gel End User: Health Conscious Consumers, Fitness Enthusiasts, Culinary Professionals, Households Distribution Channel: Supermarkets, Health Stores, Online Retailers, Specialty Stores Packaging Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | ALO Drink, OKF Corporation, Forever Living Products, Lotte Chilsung Beverage, GraceKennedy Ltd., Keumkang B and F Co. Ltd., Patanjali Ayurved Ltd., Houssy Global, Tulip International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aloe Vera-Based Drink Market Emerging Trajectories
Processing technology and regulatory science are diverging competitive capabilities between capital-intensive clinical validators and marketing-dependent commodity players.
High-pressure processing is bifurcating the manufacturing base. Cold pasteurization preserves heat-sensitive acemannan polysaccharides that thermal treatment degrades. Premium health store buyers are demanding HPP certification as a quality signal. This technology is compressing margins for conventional pasteurization-dependent facilities that cannot justify equipment upgrades.
EFSA's tightening Article 13.5 evidence standards are reshaping European competitive entry. Manufacturers must now submit human intervention studies rather than in-vitro or traditional use data. This regulatory friction favors established players with existing trial infrastructure over new entrants.
Subscription-based replenishment is displacing traditional retail replenishment cycles. Direct-to-consumer platforms capture purchase data that enables flavor personalization and bundling with complementary supplements. South Korean and North American urban consumers show highest adoption of auto-ship models for functional beverages.
Aloe Vera-Based Drink Market Segmentation
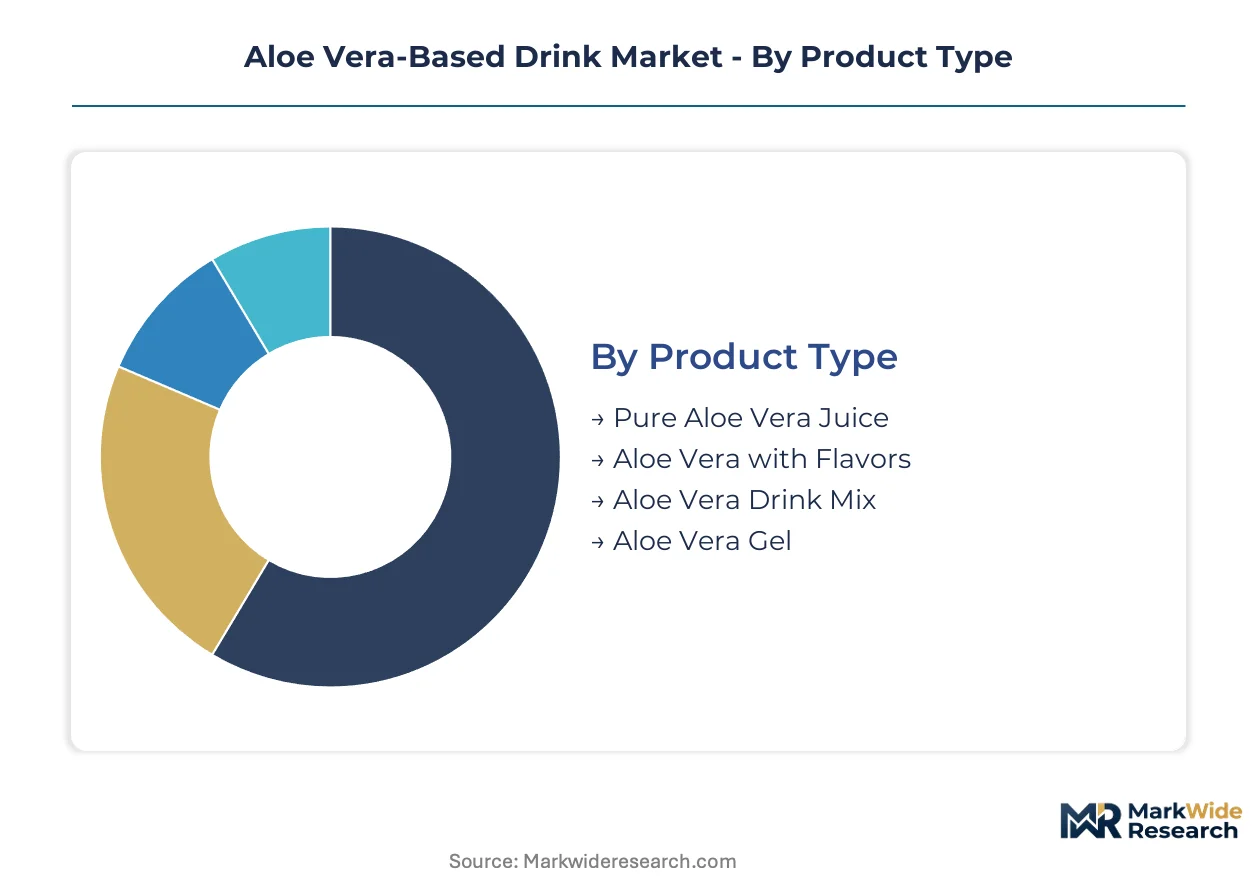
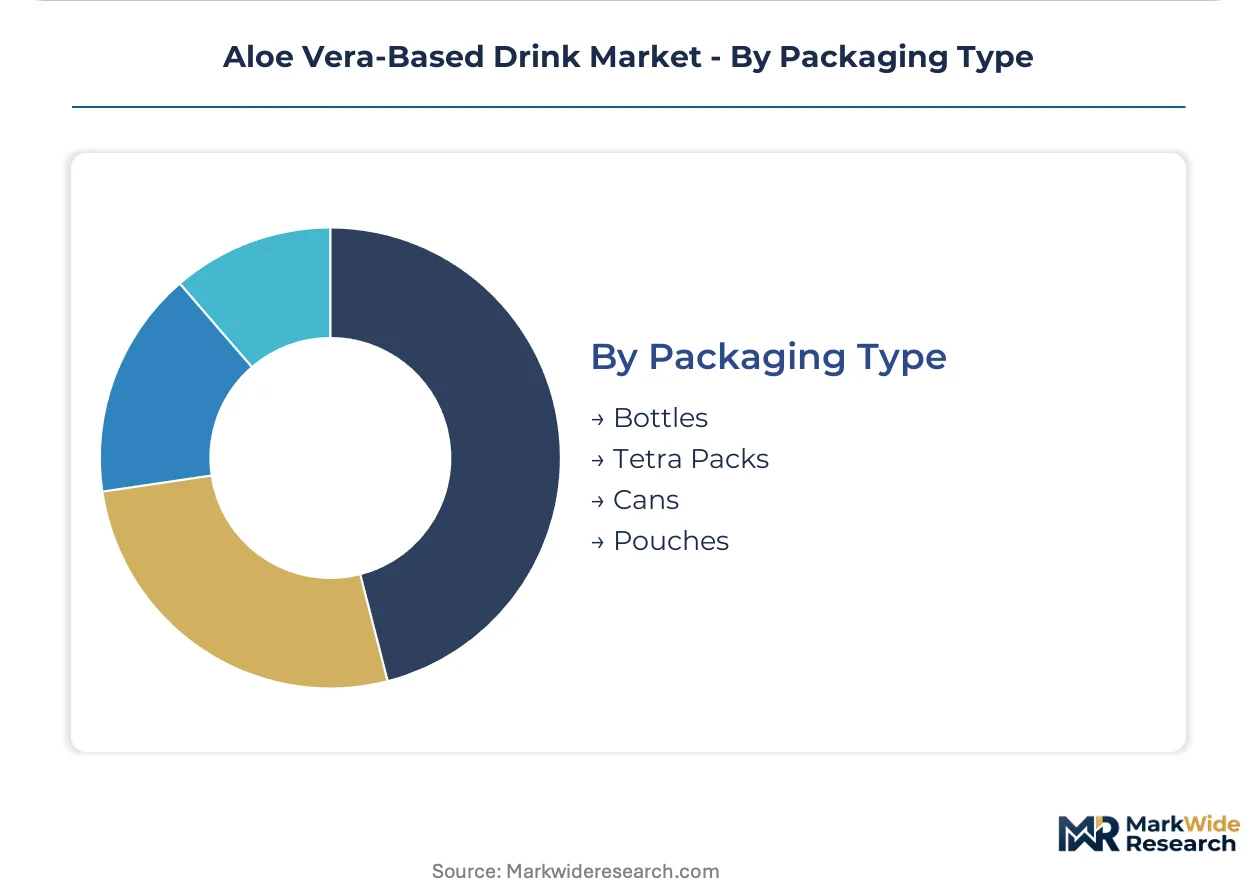
Aloe vera drinks fragment across four commercial dimensions that determine margin capture and channel access. Product composition and packaging format dictate whether brands penetrate mass retail or premium health stores. End-user targeting and distribution channel selection separate clinical validators from commodity players.
Product Type:
Pure juice and flavored variants flow through entirely different channel mixes, with the former dominating pharmacy-adjacent health stores and the latter capturing convenience retail impulse purchases.
- Pure Aloe Vera Juice:Standardized to 0.3-1.0% aloin content with suspended gel particles, this segment anchors volume in North American health stores where visual pulp signals authenticity. Mexican and Chinese leaf sourcing volatility compresses margins during drought cycles.
- Aloe Vera with Flavors:Mango, pomegranate, and green tea infusions attract younger consumers seeking palatable entry points to functional beverages. South Korean convenience stores and North American gym chains drive fastest expansion as fitness studios add post-workout retail shelves.
- Aloe Vera Drink Mix:Concentrated powders targeting culinary professionals and at-home preparation, capturing pantry-stocking demand through e-commerce subscription models.
- Aloe Vera Gel:Spoonable formats with higher viscosity for digestive wellness positioning, concentrated in European pharmacy channels where EFSA health claim scrutiny shapes permissible messaging.
Pure aloe vera juice dominates installed base. Aloe vera with flavors is where expansion concentrates.
End User:
Customer type determines price tolerance and purchase frequency, with fitness enthusiasts commanding premium positioning and households driving volume through supermarket replenishment.
- Health Conscious Consumers:Core demographic seeking digestive comfort and antioxidant intake, concentrated in urban coastal markets with established wellness infrastructure. Subscription auto-ship models capture highest lifetime value from this cohort.
- Fitness Enthusiasts:Post-workout hydration demand creates impulse purchase occasions at gym chains and boutique studios. This segment pays premium for HPP-certified cold pasteurization that preserves acemannan bioactivity.
- Culinary Professionals:Restaurants and beverage formulators sourcing aloe for smoothie and cocktail applications, demanding consistent gel suspension and neutral flavor profiles.
- Households:Family-scale consumption through supermarket multi-packs, price-sensitive and responsive to promotional depth rather than functional claims.
Health conscious consumers anchor revenue stability. Fitness enthusiasts deliver steepest expansion trajectory.
Distribution Channel:
Channel selection directly determines margin structure, with health stores and online platforms bypassing slotting fees that erode profitability in mass retail.
- Supermarkets:Mass-market volume base requiring trade promotion investment and standardized packaging formats. EFSA and FDA labeling compliance costs concentrate here due to broad consumer exposure.
- Health Stores:Premium positioning with visual pulp suspension requirements and HPP certification as quality signal. North American independents and European pharmacy chains sustain highest per-unit margins.
- Online Retailers:Direct-to-consumer platforms enabling flavor personalization and supplement bundling. Data capture supports auto-ship retention programs with superior lifetime value metrics.
- Specialty Stores:Ethnic grocery and wellness boutiques serving diaspora communities and early adopters, concentrated in South Korean and Chinese urban districts.
Health stores dominate premium revenue capture. Online retailers concentrate expansion investment.
Packaging Type:
Format selection balances shelf stability, logistics cost, and premium signaling, with material choice often predetermined by target channel and geography.
- Bottles:Premium positioning in North American health stores where transparent PET or glass showcases pulp suspension. Higher logistics cost limits distribution radius.
- Tetra Packs:Lightweight aseptic cartons dominating European retail due to shelf stability and reduced carbon footprint in transport. Standard for supermarket volume tiers.
- Cans:Aluminum formats capturing convenience store and gym vending placement, favored for chill-and-consume immediacy.
- Pouches:Flexible packaging for drink mix powders and single-serve gel portions, minimizing shipping cube for e-commerce fulfillment.
Bottles anchor premium positioning. Tetra packs capture volume scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leaf sourcing networks for aloe vera beverages concentrate in Mexico's arid highlands and China's Hainan province, with finished product demand dispersing across North American health stores, European pharmacy chains, and East Asian convenience retail.
United States
Fitness studio retail and direct-to-consumer subscription models drive demand concentration in California and New York metro corridors. FDA DSHEA structure-function claim enforcement compels manufacturers to maintain separate supplement and conventional beverage labeling. Los Angeles anchors premium health store distribution where HPP certification commands shelf placement premiums.
South Korea
Dense urban convenience store networks and established functional beverage culture sustain per-capita consumption leadership. MFDS aloin content limits and heavy metal testing protocols shape import qualification requirements. Seoul Capital Area concentrates both domestic manufacturing from Lotte Chilsung and duty-free channel distribution targeting outbound tourism.
Germany
Pharmacy-adjacent health food retail and organic certification preference support premium positioning in Bavaria and North Rhine-Westphalia. EFSA Article 13.5 health claim authorization requirements impose clinical trial cost barriers that favor established validators. Hamburg serves as import logistics hub for Tetra Pack formats entering European supermarket distribution.
China
Domestic aloe leaf cultivation in Hainan and Yunnan provinces reduces import dependency for local processors. SAMR national food safety standards for plant-based beverages mandate aloin limits and contaminant testing that foreign exporters must satisfy. Yangtze River Delta cities concentrate e-commerce fulfillment infrastructure for drink mix powder distribution.
India
Ayurvedic positioning and domestic aloe cultivation in Gujarat and Rajasthan support mass-market price tiers. FSSAI labeling requirements for ayurvedic and nutraceutical products create parallel compliance tracks distinct from conventional beverages. Maharashtra's Mumbai-Pune corridor anchors both manufacturing scale and modern trade retail expansion.
Aloe Vera-Based Drink Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with cold pasteurization specialists commanding premium health store margins while commodity processors compete on Mexican and Chinese leaf sourcing efficiency. The market structure tiers across clinical validators with trial infrastructure, vertically integrated plantation-to-bottle operators, and regional distributors with convenience channel density. Three archetypes dominate: EFSA-compliant clinical validators, backward-integrated plantation owners, and East Asian convenience store specialists. Capacity expansion in aseptic filling lines and strategic partnerships for subscription platform technology represent the dominant competitive moves.
Among plantation-integrated operators, ALO Drink and Forever Living Products exemplify archetypes with captive supply control, while OKF Corporation anchors the East Asian convenience channel specialist tier. These named entities occupy positions that reflect broader strategic patterns rather than individual firm-specific capabilities.
| Leading Market Players |
|---|
| ALO Drink |
| OKF Corporation |
| Forever Living Products |
| Lotte Chilsung Beverage |
| GraceKennedy Ltd. |
| Keumkang B and F Co. Ltd. |
| Patanjali Ayurved Ltd. |
| Houssy Global |
| Tulip International Inc. |
| Others |
Supply Flow & Price Mechanics
FDA DSHEA structure-function claim enforcement gates both supply qualification and price differentiation simultaneously, compelling manufacturers to maintain parallel supplement and conventional beverage labeling systems that bifurcate production economics. HPP certification commands shelf placement premiums in premium health stores while commodity processors compete on Mexican and Chinese leaf sourcing efficiency.
Pricing Analysis
FDA DSHEA dictates the pricing tier structure across the aloe vera drink market, separating supplement-positioned products with clinical validation costs from conventional beverages with generic hydration messaging. Three-tier pricing separates HPP-certified premium lines from standard pasteurized offerings and economy private-label alternatives. Cost compression in the pure juice segment is intensifying because Mexican and Chinese harvest volatility creates margin pressure during drought cycles. Household buyers through supermarket multi-packs show highest price sensitivity, while fitness enthusiasts at gym chains pay premium for acemannan bioactivity preservation.
Supply Chain Analysis
Mexico and China anchor aloe leaf cultivation, with arid highlands in Mexico's central plateau and Hainan province supplying the bulk of raw material for global processing. Finished beverage manufacturing draws from specialized aseptic filling lines for gel suspension, cold-press extraction equipment, and HPP pasteurization systems. Single-source vulnerability concentrates in Mexican leaf supply during drought cycles, disrupting contract pricing. Distribution runs through health stores and direct-to-consumer platforms for premium tiers, while Tetra Pack formats penetrate European supermarket volume channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of in-house clinical trial design expertise separates capital-intensive validators from marketing-dependent commodity players, creating asymmetric competitive returns for firms that can structure GI transit time and immune marker studies satisfying peer-review standards.
For Market Incumbents: Fortify backward integration into captive aloe leaf supply to defend margin position against Mexican and Chinese harvest volatility. Expand HPP-certified capacity in California and New York metro corridors where fitness studio retail commands premium positioning. Lock in EFSA Article 13.5 submission infrastructure before evidence standards tighten further. For New Entrants and Emerging Players: Anchor in South Korean convenience store distribution where established functional beverage culture reduces consumer education costs. Target the flavored aloe vera segment with mango and green tea infusions that attract younger consumers seeking palatable entry points. Deploy direct-to-consumer subscription models with auto-ship retention programs bypassing retail slotting fees. For Investors and Strategic Acquirers: EFSA Article 13.5 authorization reshapes the acquisition landscape toward clinical validators with existing trial infrastructure rather than marketing-dependent brands. Prioritize plantation-integrated operators with captive supply control over pure-play distributors. Watch for successful digestive health claim submissions as inflection indicators for premium positioning unlock in European supermarkets.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | Human intervention studies satisfying EFSA Article 13.5 standards unlock authorized benefit messaging in European pharmacy chains. |
| Backward Integration into Plantation Supply | Captive aloe leaf sourcing from Mexican highlands insulates margin control against drought-driven commodity price spikes. |
| HPP Equipment Deployment | Cold pasteurization preserves acemannan polysaccharides that thermal treatment degrades, commanding health store shelf placement premiums. |
| Direct-to-Consumer Platform Launch | Subscription auto-ship models capture purchase data enabling flavor personalization with superior lifetime value metrics. |
| South Korean Convenience Channel Expansion | Dense urban retail networks and established functional beverage culture offer expansion runway for imported brands. |
Methodological Framework
Initial hypotheses were tested against primary input from beverage formulators, health store category buyers, regulatory affairs specialists at functional drink manufacturers, and supply chain managers at aloe leaf processors, then refined through secondary validation. FDA warning letters, EFSA health claim submission databases, MFDS import qualification protocols, and customs trade records provided triangulation points. Bottom-up volume modeling across product types and top-down macroeconomic cross-checks converged on segment-level outputs.
Variance decomposition across the projection horizon isolates drivers by product composition, packaging format, end-user targeting, and distribution channel selection. CAGRs were derived from segment growth rate reconciliation with aggregate market expansion. Modeled inputs include aloe leaf harvest volatility cycles, EFSA authorization timelines, and fitness studio retail penetration rates.
Decision-makers should treat outputs as directional under stable regulatory enforcement and intact consumer wellness spending assumptions; material deviation would warrant model refresh. Specific risk factors include EFSA evidence standard tightening, substitution acceleration by fermented beverages, and drought-induced leaf supply disruption. Recalibration cycles align with material shifts in claim authorization outcomes and processing technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
GCC Bottled Water Market
Beverages
Low Calorie RTD Beverages Market
Beverages
Wellness Water Market
Beverages
Hot Beverages Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
GCC Juice Market
Beverages
Carbonate Drink Maker Market
Beverages
Fermented Foods and Beverages Market
Beverages
NFC JUICE Market
Beverages
Probiotic Beverage Market
Beverages
North America Kombucha Market
Beverages
Asia Pacific Fermented Drinks Market
Beverages
Morocco Bottled Water Market
Beverages
North America Juices Market
Beverages
Bangladesh Energy Drinks Market
Beverages
Blackstrap Molasses Market