
 Botanical Infused Beverages Market | 2026-2036
Botanical Infused Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Botanical Infused Beverages Market Analytics
Botanical extraction expertise is collapsing across traditional flavor houses, forcing beverage brands to rebuild in-house competency or lock exclusive supplier contracts. Nestlé S.A. anchors its portfolio through captive botanical gardens and proprietary drying protocols in Switzerland. PepsiCo Inc. competes via aggressive cold-chain distribution partnerships with North American specialty retailers. Martin Bauer Group dominates European bulk botanical supply, leveraging century-old relationships with German and Austrian herb cultivators.
Botanical infused beverages comprise non-alcoholic drinks incorporating plant-derived extracts, essential oils, or dried botanical matter through cold-steep, hot-infusion, or CO2 extraction methods, typically at concentrations of 0.1% to 2.0% by volume, serving functional refreshment and perceived wellness benefits. Sparkling drinks leads volume as younger consumers substitute carbonated botanicals for conventional sodas, while cold brew formats capture the fastest growth trajectory through extended steeping times that preserve volatile aromatic compounds. Glass bottle packaging commands margin concentration in premium channels, though aluminum cans extend reach into outdoor and convenience occasions where portability governs purchase decisions.
EU REACH and EFSA novel food assessments govern botanical ingredient approvals across European formulations, while FDA GRAS self-affirmation pathways shape US market entry timelines for exotic plant extracts. India's FSSAI plant-based beverage standards and China's GB food additive regulations add compliance layers for brands sourcing Asian botanicals such as chrysanthemum or goji. Stakeholders must monitor evolving caffeine-equivalent thresholds for adaptogenic botanicals, as regulators in multiple jurisdictions recalibrate stimulant classification frameworks that could reclassify functional positioning claims.
Market Dynamics
Botanical extraction expertise is consolidating among a shrinking pool of European suppliers, forcing beverage brands to rebuild in-house competency or lock exclusive supplier contracts before raw material access tightens further.
Growth Catalysts
- EU REACH compliance mandates:Clean-label certification requirements under EU REACH are tightening formulation standards, accelerating premium hospitality procurement of certified botanical-infused SKUs.
- Adaptogenic positioning:Functional beverage clusters in Cologne and Hamburg are driving German demand for botanicals with perceived wellness benefits, creating concentrated innovation hubs.
- Carbonation substitution:Sparkling botanical formats are capturing younger consumers shifting away from conventional sodas, expanding volume through cold-steep and CO2 extraction methods.
Market Restraints
- Raw material volatility:Dried herb and essential oil inputs face price instability due to weather-dependent cultivation cycles concentrated in German and Austrian growing regions.
- Supplier concentration risk:Century-old relationships between bulk botanical suppliers and Central European herb cultivators limit new entrant access to premium raw material streams.
- Novel extract approval friction:FDA GRAS self-affirmation pathways create extended timelines for exotic plant extracts, delaying US market entry for brands sourcing Asian botanicals.
Strategic Opportunities
- Underpenetrated Asian sourcing:India's FSSAI plant-based beverage standards and China's GB food additive regulations present compliance frameworks for brands developing chrysanthemum and goji-based formulations.
- Cold brew format expansion:Extended steeping technologies that preserve volatile aromatic compounds are opening premium positioning in wellness-focused foodservice channels.
- Portable packaging innovation:Aluminum can formats are extending reach into outdoor and convenience occasions where glass bottle portability constraints limit purchase decisions.
Industry Challenges
- Extraction competency gaps:Traditional flavor house consolidation is depleting available botanical processing expertise, forcing beverage brands to recruit specialized formulation talent.
- Regulatory recalibration risk:Evolving caffeine-equivalent thresholds for adaptogenic botanicals across multiple jurisdictions threaten functional positioning claims and require continuous compliance monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botanical Infused Beverages Market |
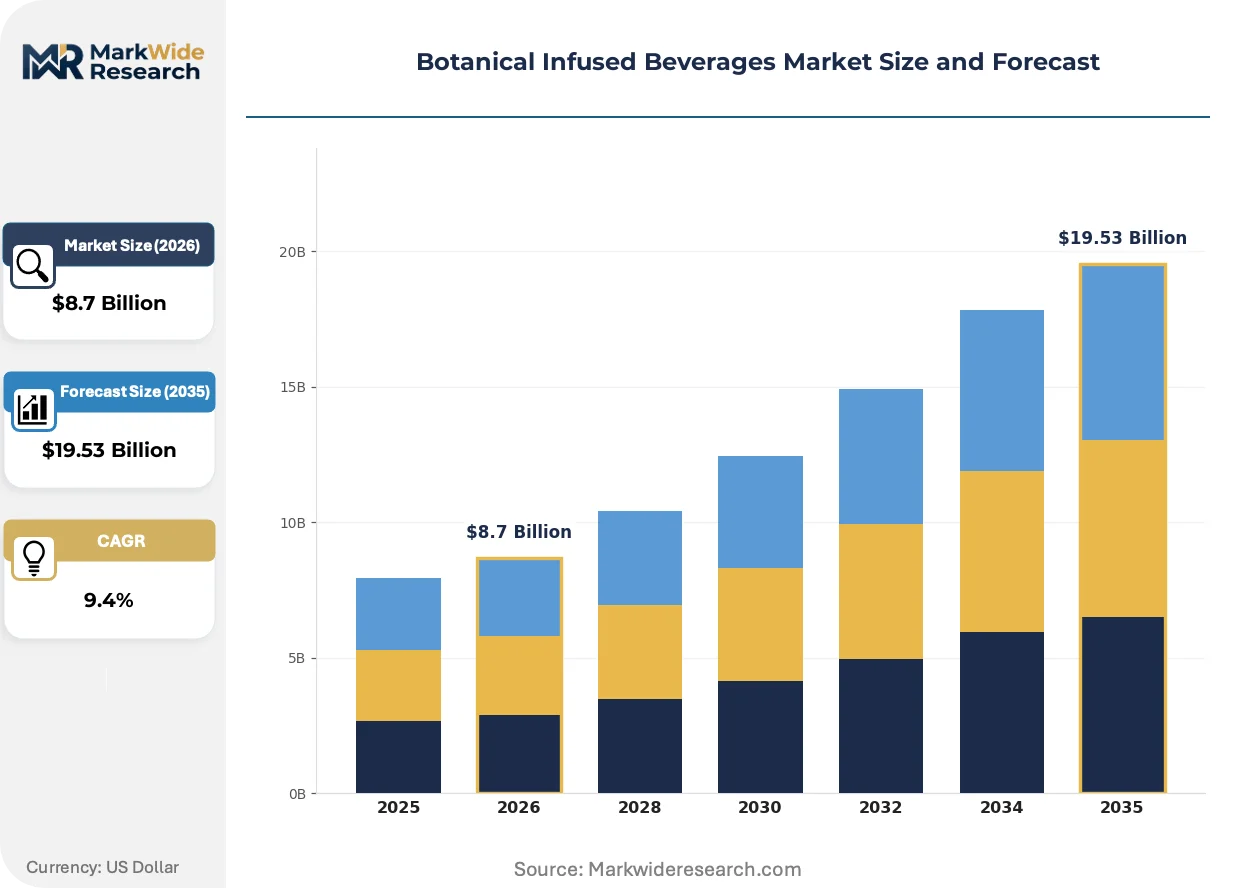
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Tea, Cold Brew, Sparkling Drinks, Infused Water Flavor Profile: Citrus, Floral, Spicy, Berry Packaging Type: Glass Bottle, Cans, Tetra Pak, Pouches Distribution Channel: Online Retail, Supermarkets, Health Stores, Cafes |
| Companies Covered | Tata Consumer Products Limited, Nestlé S.A., Coca-Cola Company, PepsiCo Inc., Danone S.A., Associated British Foods plc, Martin Bauer Group, Diageo plc, Britvic Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botanical Infused Beverages Market Evolving Landscape
Formulation science and regulatory frameworks are actively reshaping how botanical beverages achieve differentiation, with extraction methodology and compliance architecture becoming primary competitive battlegrounds.
Supercritical CO2 extraction technology is decomposing traditional solvent-based processing by enabling precise terpene preservation at lower temperatures. Premium wellness brands in Germany are adopting these systems to maintain volatile compound integrity. This shift is compressing margins for conventional hot-infusion processors unable to match aromatic fidelity.
EFSA novel food assessments are tightening approval pathways for exotic botanical extracts entering European formulations. The industrial consequence is extended product development timelines as brands accumulate safety dossiers. Functional beverage innovators in Hamburg are responding by prioritizing GRAS-affirmed ingredients with established regulatory histories.
Direct-to-glasshouse sourcing contracts are replacing spot-market herb procurement as brands seek traceability guarantees. Specialty retailers in North American cold-chain partnerships are demanding cultivator verification for premium shelf placement. This pattern is most visible in Swiss captive botanical garden models where proprietary drying protocols secure supply security.
Botanical Infused Beverages Market Segmentation
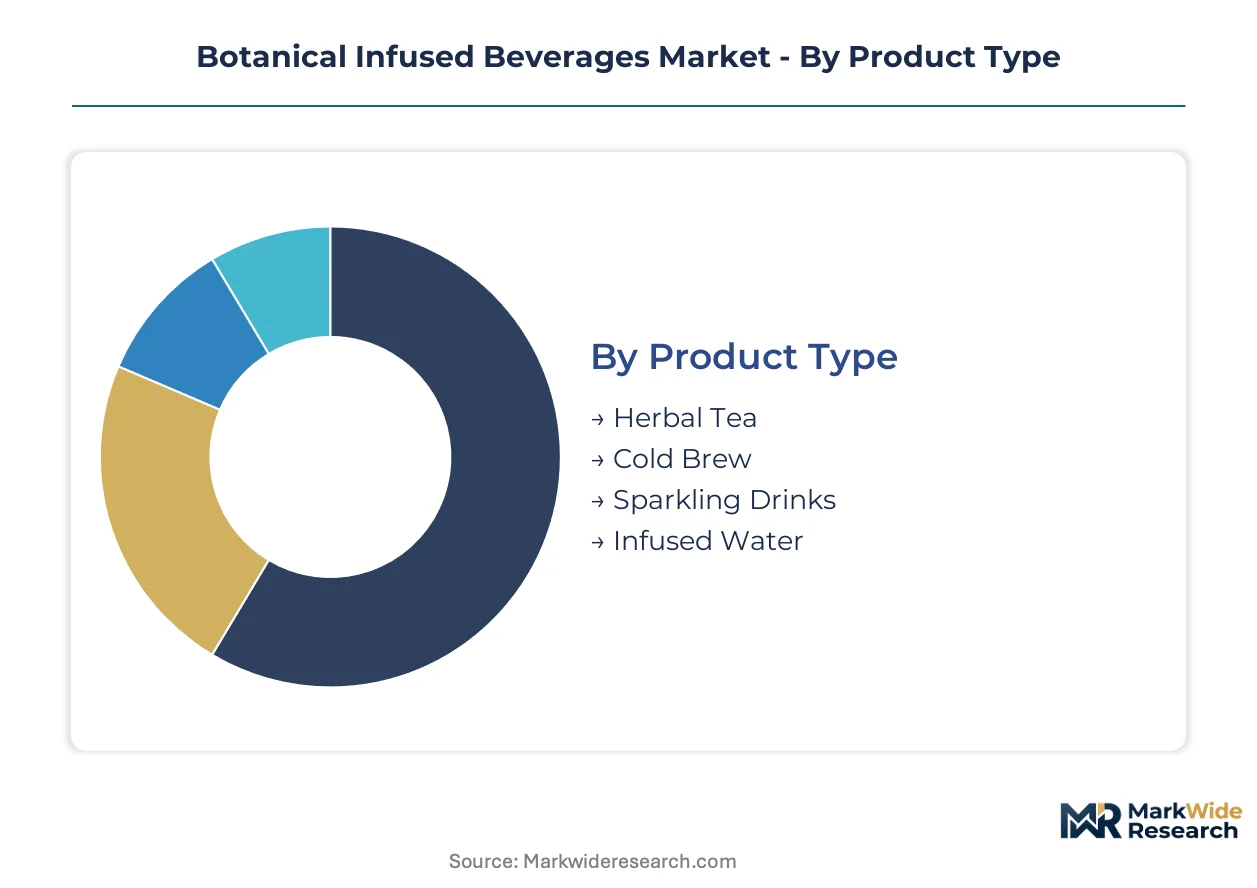
Segmentation in botanical infused beverages reveals how substitution pressures from conventional sodas, functional waters, and craft beverages reshape competitive positioning across format and channel. Understanding these divides exposes where formulation investment yields defensible margins versus commodity exposure.
Product Type:
Sparkling drinks faces the most acute substitution threat as younger consumers abandon carbonated soft drinks yet retain format preferences, forcing botanical variants to differentiate on extraction method and ingredient provenance.
- Sparkling Drinks:Carbonated botanical formulations using cold-steep or CO2 extraction methods at 0.1% to 2.0% concentration by volume. German functional beverage clusters in Cologne and Hamburg concentrate demand for these formats as soda alternatives, with premium hospitality venues driving procurement of certified SKUs.
- Cold Brew:Extended steeping protocols preserve volatile aromatic compounds through ambient-temperature extraction over 12-24 hour cycles. Wellness-focused foodservice operators in North American specialty retail channels are capturing the steepest growth trajectory through cold-chain distribution partnerships.
- Herbal Tea:Hot-infusion formats leveraging century-old relationships with German and Austrian herb cultivators for dried botanical inputs.
- Infused Water:Still formulations with minimal extraction complexity, competing directly with enhanced water categories.
Sparkling drinks anchors the volume base while cold brew gains share at the steepest rate.
Flavor Profile:
Cost tier stratification separates premium terpene-preserving formulations from commodity flavor masking, with extraction technology investment determining margin capture.
- Citrus:High-volatility terpene profiles requiring supercritical CO2 extraction to maintain aromatic fidelity. Swiss captive botanical garden models with proprietary drying protocols dominate premium supply security for these formulations.
- Floral:Delicate essential oil preservation through lower-temperature processing. EFSA novel food assessments constrain exotic floral extract approvals, compressing margins for conventional processors.
- Spicy:Adaptogenic botanicals with caffeine-equivalent regulatory scrutiny across FDA and EU REACH frameworks.
- Berry:Anthocyanin-stable extracts with established GRAS affirmation pathways accelerating US market entry.
Citrus commands premium shelf placement while floral faces the most extended development timelines.
Packaging Type:
Application occasion dictates material selection, with portability requirements in outdoor and convenience channels displacing glass dominance in premium hospitality settings.
- Glass Bottle:Premium channel margin concentration through perceived quality signaling and terpene protection. EU REACH clean-label certification requirements tighten formulation standards for glass-packaged SKUs in German hospitality procurement.
- Cans:Aluminum formats extending reach into outdoor and convenience occasions where portability governs purchase decisions. North American cold-chain partnerships prioritize can formats for specialty retailer shelf placement.
- Tetra Pak:Aseptic processing compatibility for ambient distribution in Asian markets under China's GB food additive regulations.
- Pouches:Flexible format for single-serve trial and on-the-go consumption occasions.
Glass bottle maintains hospitality dominance while cans expand most quickly through convenience channel penetration.
Distribution Channel:
Customer type fragmentation separates wellness-motivated premium purchasers from price-sensitive mainstream converters, with channel-specific compliance architectures shaping entry economics.
- Supermarkets:Mass-volume procurement with spot-market herb sourcing pressure. India's FSSAI plant-based beverage standards and evolving FDA GRAS determinations create compliance layering for brands sourcing Asian botanicals such as chrysanthemum or goji.
- Health Stores:Traceability-demanding specialty retail with direct-to-glasshouse sourcing contract requirements. Martin Bauer Group's century-old relationships with Central European cultivators limit new entrant access to premium raw material streams.
- Online Retail:Direct-to-consumer subscription models with cold-chain logistics dependency.
- Cafes:Foodservice fountain and ready-to-drink placement with batch-consistent extraction demands.
Supermarkets anchor volume throughput while health stores extract the highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers prioritize functional carbonated formats as soda alternatives, while North American buyers gravitate toward cold brew wellness positioning, and Asian markets favor still herbal infusions with traditional medicine associations.
Germany
Premium hospitality procurement and functional beverage innovation clusters drive concentrated demand in Cologne and Hamburg. EU REACH clean-label certification mandates tighten formulation standards for botanical-infused SKUs entering foodservice channels. The North Rhine-Westphalia corridor anchors European extraction expertise, with century-old supplier relationships securing raw material access for sparkling format producers.
United States
Cold brew adoption accelerates through wellness-focused foodservice operators and specialty retail cold-chain partnerships. FDA GRAS self-affirmation pathways shape market entry timelines for exotic plant extracts, compressing launch schedules for novel formulations. Pacific Northwest urban centers concentrate craft beverage innovation, where extended steeping technologies preserve volatile aromatic compounds for premium positioning.
India
Traditional herbal consumption patterns translate into commercial opportunity for chrysanthemum and tulsi-based formulations. FSSAI plant-based beverage standards establish compliance frameworks distinct from Western regulatory architectures. Maharashtra and Karnataka host emerging formulation facilities serving domestic wellness brands expanding into organized retail channels.
China
Goji and chrysanthemum extracts command established consumer recognition through traditional medicine associations. GB food additive regulations govern botanical concentration limits and novel extract approvals for domestic and imported products. The Yangtze River Delta clusters aseptic processing capacity for Tetra Pak-compatible ambient distribution formats.
Switzerland
Captive botanical garden models with proprietary drying protocols exemplify supply security strategies for premium European brands. Swissmedic food supplement oversight intersects with beverage classification debates for adaptogenic-positioned products. The Lake Geneva region concentrates extraction technology providers serving cross-border German and French brand portfolios.
Botanical Infused Beverages Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational beverage conglomerates controlling distribution infrastructure while botanical extraction specialists retain formulation leverage. The market structure rewards backward integration into raw material sourcing and captive processing capacity. Two strategic archetypes dominate: diversified conglomerates with captive botanical gardens and drying protocols, and specialist suppliers with century-old cultivator relationships. Competitive moves concentrate on exclusive supplier contract lock-ups and cold-chain distribution partnerships with premium retail channels.
Within the integrated conglomerate tier, Nestlé S.A. and PepsiCo Inc. exemplify divergent sourcing strategies, with the former anchoring supply security through proprietary cultivation infrastructure and the latter competing via aggressive North American specialty retail channel partnerships. Martin Bauer Group occupies a distinct position as a European bulk botanical supplier leveraging generational relationships with Central European herb cultivators. These three entities collectively illustrate how extraction competency access and distribution reach constitute the primary competitive battlegrounds for market positioning.
| Leading Market Players |
|---|
| Tata Consumer Products Limited |
| Nestlé S.A. |
| Coca-Cola Company |
| PepsiCo Inc. |
| Danone S.A. |
| Associated British Foods plc |
| Martin Bauer Group |
| Diageo plc |
| Britvic Plc |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German beverage brands and Austrian herb cultivators lock in both raw material access and cost visibility across volatile growing seasons, compressing spot-market exposure for premium SKUs while anchoring price stability for EU REACH-certified formulations.
Pricing Analysis
Contract-based long-term offtake agreements dominate premium tier procurement, with price differentiation driven by EU REACH certification grade and cultivator traceability tier. Cost compression in standard-tier sparkling formats is intensifying because of aluminum can format commoditization and supermarket channel spot-market sourcing. Health store buyers show least price sensitivity due to traceability demands, while mass-market supermarket converters remain highly price-responsive.
Supply Chain Analysis
Alpine herb drying capacity in Austria and Switzerland constitutes a critical chokepoint for volatile compound preservation, with German beverage brands competing for limited facility slots. Supply chains draw from dried botanical inputs, essential oil extracts, and supercritical CO2 processing equipment, with single-source vulnerability concentrated in Martin Bauer Group's generational cultivator relationships. Distribution runs through North American cold-chain partnerships for premium retail placement and ambient Tetra Pak networks for Asian market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Botanical infused beverages present a service-attach opportunity where extraction technology licensing and formulation consulting contracts expand faster than finished goods volume, as beverage brands rebuild in-house competency through recurring technical partnerships rather than capital equipment purchases alone.
For Market Incumbents: Compound defensive positioning through captive botanical garden expansion in Swiss Lake Geneva corridor and exclusive supplier contract lock-ups with German herb cultivators before extraction expertise consolidates further. Prioritize EU REACH certification investment as regulatory tightening threatens non-compliant SKU delisting from premium hospitality procurement channels.
For New Entrants and Emerging Players: Lead with cold brew format specialization targeting North American wellness-focused foodservice operators, where extended steeping technology gaps create penetrable white space. Pursue direct-to-glasshouse sourcing contracts with Indian chrysanthemum and tulsi cultivators under FSSAI compliance frameworks to bypass entrenched European supplier relationships.
For Investors and Strategic Acquirers: Specialist extraction technology providers with supercritical CO2 equipment portfolios and proprietary terpene preservation protocols represent the priority acquisition archetype. Monitor FDA GRAS affirmation timelines for exotic Asian botanicals as inflection indicator for US market entry acceleration and corresponding valuation multiples expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Brew Format Expansion | Extended steeping technology preserves volatile aromatic compounds for wellness channel premium positioning. |
| Captive Botanical Garden Development | Swiss proprietary drying protocols secure supply security against Central European herb cultivation volatility. |
| EU REACH Certification Investment | Clean-label compliance mandates tighten formulation standards for German hospitality procurement access. |
| Direct-to-Glasshouse Sourcing Contracts | Traceability guarantees unlock North American specialty retailer shelf placement and margin capture. |
| Supercritical CO2 Technology Licensing | Precision terpene preservation at lower temperatures compresses margins for conventional hot-infusion processors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU REACH regulatory filings, FSSAI plant-based beverage standards, and EFSA novel food assessment databases. Interviews with beverage formulation directors, botanical extraction equipment suppliers, German herb cultivator cooperatives, and North American specialty retail category buyers combined with customs trade data, company SEC disclosures, and hospitality procurement database analysis. Bottom-up SKU volume triangulation against top-down market value estimates validates segment-level outputs.
Segmentation dimensions modeled span product type, flavor profile, packaging material, and distribution channel across the projection horizon. CAGRs derive from trend extrapolation of carbonation substitution rates, cold brew adoption curves, and aluminum can penetration in convenience channels. Forecast inputs incorporate EU regulatory approval timelines for novel botanical extracts and cold-chain logistics capacity expansion in Pacific Northwest urban centers.
Forecasts assume regulatory continuity in EU REACH, FDA GRAS, and FSSAI frameworks; material policy shifts such as caffeine-equivalent threshold recalibration for adaptogenic botanicals would require re-modeling. Practitioners should keep alternative scenarios live as extraction technology cost curves and novel extract approval velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Water Bottle Market
Beverages
Grape Juice Concentrate for Wine Making Market
Beverages
Milk Tea Powder Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
United Kingdom Energy Drink Market
Beverages
Asia-Pacific Juices Market
Beverages
Hydrogen Water Dispenser Market
Beverages
Recovery Drinks Market
Beverages
Collagen Drinks Market
Beverages
NFC JUICE Market
Beverages
Rose Floral Water Market
Beverages
China Orange Juice Market
Beverages
Packaged Milkshake Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
Wellness Water Market
Beverages
BBQ Charcoal Market