
 Oil & Gas Static and Rotating Equipment Market | 2026-2036
Oil & Gas Static and Rotating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Oil & Gas Static and Rotating Equipment Market Insights
Deepwater exploration is repositioning demand toward high-pressure subsea rotating systems. NOV Inc. anchors offshore drilling equipment supply through its rig technology division. Baker Hughes Company competes in turbomachinery with integrated compressor and power generation platforms. Schlumberger Limited leverages digital twin capabilities to extend equipment lifecycle monitoring across client installations.
Oil and gas static and rotating equipment encompasses pressure-boundary machinery—compressors, pumps, turbines, and generators—typically manufactured from low-alloy steels with chromium-molybdenum compositions rated for sour service under NACE MR0175/ISO 15156, functioning to transport, process, and convert hydrocarbon streams across the value chain. Compressors and turbines concentrate margin pools in midstream gas processing and LNG liquefaction trains where specification intensity and aftermarket service attach rates run highest. Pumps dominate unit volume across upstream artificial lift and downstream refining applications, while generators find accelerating placement in offshore platform electrification schemes.
API standards, NACE sour service requirements, and EPA methane emissions regulations collectively dictate material selection, seal technology, and leak detection integration for equipment sold into US jurisdictions. The EU F-Gas Regulation and REACH chemical restrictions are reshaping compressor refrigerant pathways and lubricant formulations for European deployments. Stakeholders must monitor how emerging carbon border adjustments and Scope 3 accounting rules recalibrate total cost of ownership calculations against upfront equipment bids.
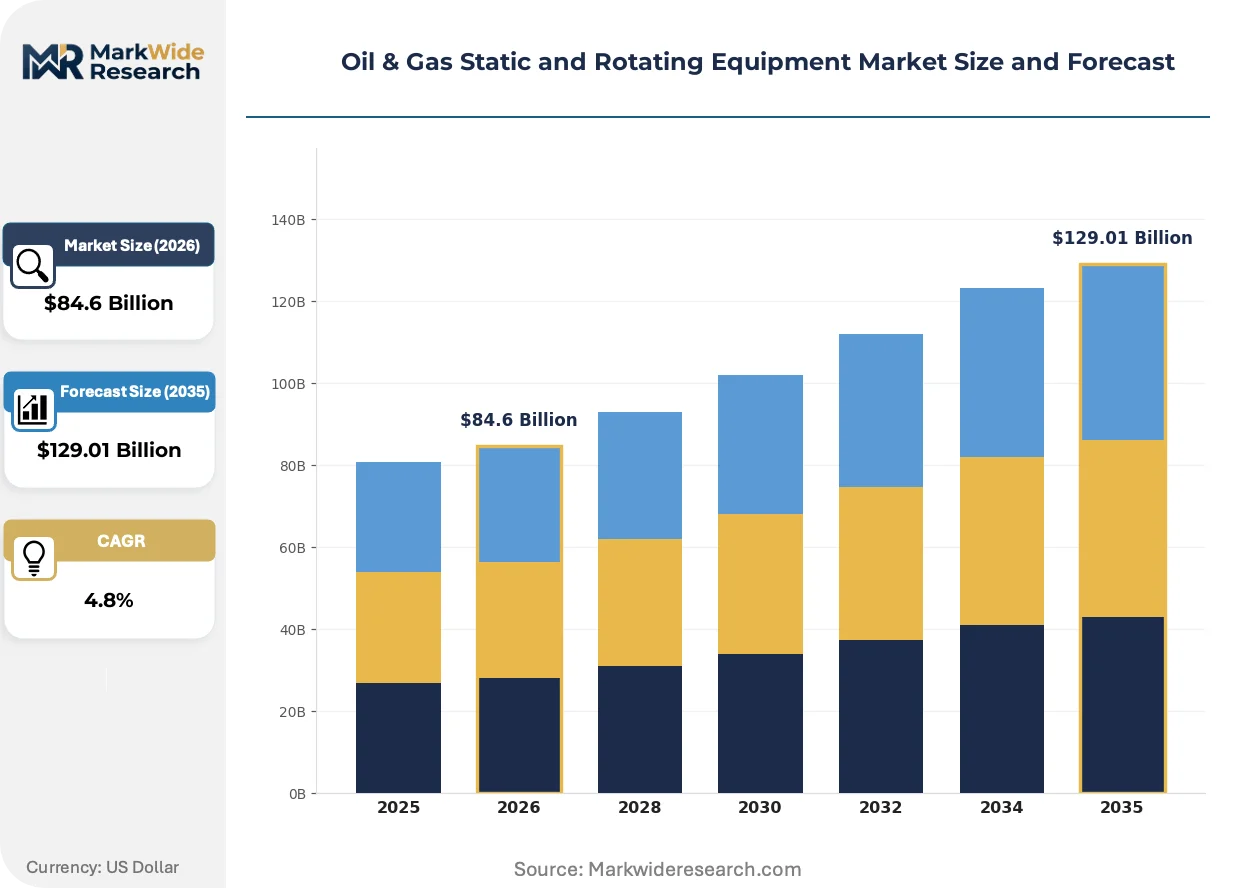
Market Dynamics
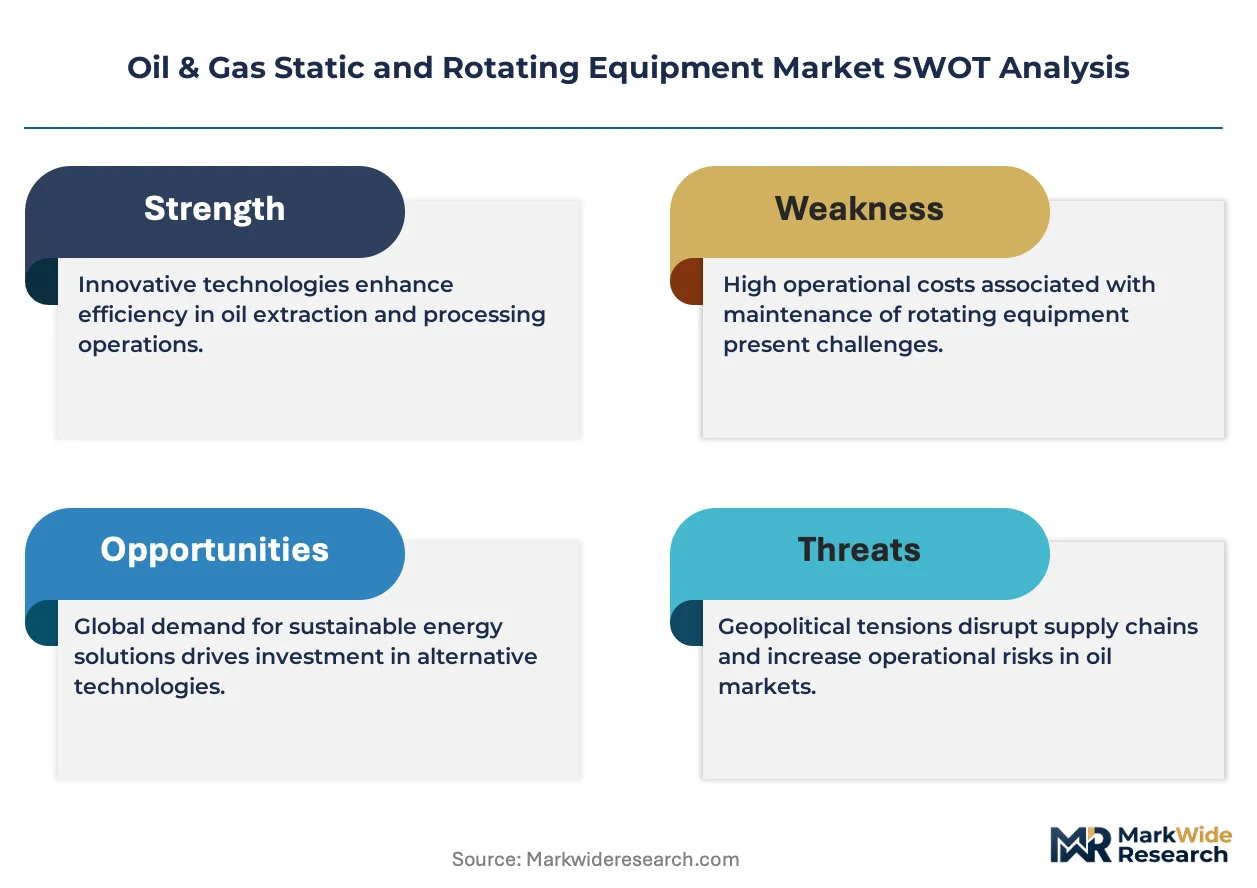
API 617 and ISO 10494 qualification tightening is compressing supplier pools for centrifugal compressors while LNG liquefaction train buildouts concentrate procurement among integrated turbomachinery platforms. This dual pressure is restructuring competitive positioning across midstream gas processing and offshore platform electrification.
Growth Catalysts
- Sour Gas Processing Expansion:Saudi Aramco and ADNOC capacity additions in the Middle East are pulling high-specification rotating equipment rated for hydrogen sulfide service under NACE MR0175/ISO 15156.
- EPA Methane Emissions Rules:Leak detection and repair mandates for US onshore production are accelerating seal technology upgrades and instrumented compressor deployments.
- Offshore Platform Electrification:North Sea and Gulf of Mexico operators are replacing gas turbine power with high-efficiency generators integrated into subsea tieback architectures.
Market Restraints
- Chromium-Molybdenum Steel Volatility:Low-alloy sour service material costs fluctuate with mining output and energy input prices, compressing fabrication margins.
- Specialized Foundry Concentration:High-pressure casting capacity for compressor casings clusters in Germany, Japan, and South Korea, creating supply vulnerability.
- Extended API Qualification Cycles:Type testing and witness requirements for 617-compliant centrifugal units stretch lead times beyond standard project schedules.
Strategic Opportunities
- Digital Twin Integration:Equipment lifecycle monitoring platforms are converging with predictive maintenance services, opening recurring revenue streams in aftermarket support.
- F-Gas Refrigerant Transition:EU compressor OEMs can capture replacement demand as the F-Gas Regulation phases down high-GWP working fluids in process cooling applications.
- Modular LNG Trains:Standardized liquefaction unit designs are enabling equipment package pre-qualification, reducing project-specific engineering for mid-scale developments.
Industry Challenges
- Welding Inspector Certification Bottlenecks:ASME Section IX and API 1104 qualified radiographic interpreters remain scarce relative to sour service project pipelines.
- Legacy Control System Integration:New rotating equipment with IIoT sensor suites must interface with decades-old DCS architectures without triggering shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil & Gas Static and Rotating Equipment Market |
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $129.01 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Compressors, Pumps, Turbines, Generators Application: Upstream, Midstream, Downstream, Refining End User: Oil Producers, Gas Companies, Petrochemical Firms, Energy Utilities Technology: Conventional, Enhanced Oil Recovery, LNG, Biogas |
| Companies Covered | NOV Inc., ChampionX Corporation, Schlumberger Limited, Cactus, Inc., Archrock, Inc., Baker Hughes Company, Weatherford International plc, Liberty Oilfield Services Inc., Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil & Gas Static and Rotating Equipment Market Trends and Innovations
Additive manufacturing of impeller geometries is compressing lead times for custom centrifugal compressor stages. Equipment suppliers are embedding condition monitoring at the factory to preempt warranty claims. Digital thread architectures now trace material certificates through operating life.
Magnetic bearing technology is converging with high-speed permanent magnet motors to eliminate lubrication systems in pipeline compressors. Kinder Morgan and TC Energy are piloting these oil-free units in remote stations. This convergence is compressing maintenance intervals and enabling unmanned facility operation.
The EU F-Gas Regulation is mandating refrigerant transitions in process cooling compressors used across refining and petrochemical complexes. Equipment OEMs are requalifying scroll and screw compressor lines for lower-GWP alternatives. German chemical operators are absorbing retrofit costs ahead of 2030 phase-down deadlines.
Long-term service agreements are displacing transactional spare parts purchasing among integrated oil companies. These contracts bundle maintenance, remote monitoring, and performance guarantees into fixed-fee structures. Operators in the Norwegian Continental Shelf are leading this shift to transfer operational risk to equipment vendors.
Oil & Gas Static and Rotating Equipment Market Segmentation
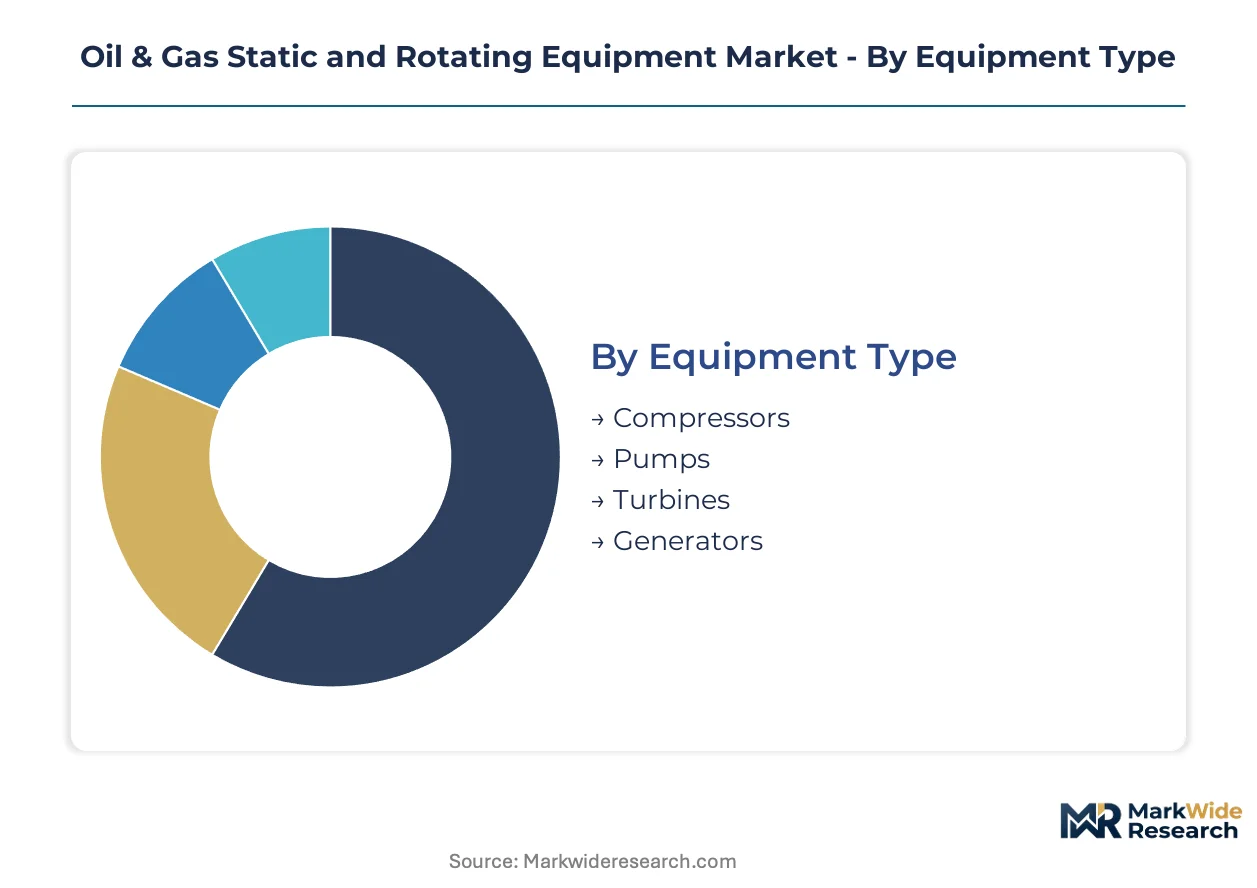
Segmentation in this market tracks how equipment specification intensity varies across pressure-boundary applications and customer integration depth. Procurement patterns diverge sharply between standalone rotating machinery and embedded systems within liquefaction trains or subsea architectures.
Equipment Type:
Standalone units dominate maintenance schedules and spare parts procurement, while embedded turbomachinery within integrated process trains shifts commercial control toward EPC consortia and long-term service contractors.
- Compressors:Centrifugal and reciprocating units rated for API 617 qualification handle gas transmission and processing duties. Demand concentrates in Middle East sour gas expansions where Saudi Aramco and ADNOC specifications require NACE MR0175-compliant materials and extended type-testing protocols.
- Pumps:These units span artificial lift, pipeline transfer, and refinery circulation with the highest unit volumes across the equipment spectrum. Downstream refiners in Texas and Louisiana drive specification intensity for API 610-compliant centrifugal models handling corrosive crude blends.
- Turbines:Gas and steam turbines convert thermal energy to mechanical drive or electric generation in platform and plant settings. Offshore electrification projects in the North Sea favor aeroderivative units for weight-constrained installations.
- Generators:Synchronous and induction machines provide power generation for remote facilities and grid-tied installations. Gulf of Mexico operators specify these for platform power replacement schemes reducing flaring intensity.
Volume placements concentrate in Pumps; the faster expansion belongs to Compressors.
Application:
Cost tiering separates commoditized upstream equipment from specification-intensive downstream systems where material traceability and witness testing inflate capital intensity.
- Upstream:Exploration and production operations deploy pumps for artificial lift and compressors for gas gathering. Permian Basin operators drive demand for modular skids combining compression and power generation in pad drilling configurations.
- Midstream:Pipeline transport and gas processing facilities require high-horsepower compression and pumping stations. Kinder Morgan and TC Energy specifications favor magnetic bearing technology for unmanned station operation.
- Downstream:Refining and petrochemical complexes specify corrosion-resistant materials for hydroprocessing and catalytic cracking service. EPA methane rules accelerate seal upgrades and instrumented compressor deployments across US Gulf Coast facilities.
- Refining:Dedicated refining applications span hydrocracking, hydrotreating, and fluid catalytic cracking with severe-service material requirements. FCC unit revamps in Rotterdam and Antwerp clusters pull high-chrome pump alloys for catalyst slurry handling.
Capital intensity peaks in Downstream; the steepest volume trajectory runs through Midstream.
End User:
Customer type determines procurement sophistication, with integrated majors commanding custom engineering and independents accepting standardized packages.
- Oil Producers:Upstream operators prioritize reliability and rapid deployment over specification customization. Shale-focused independents in the Permian and Bakken favor lease-operated pump packages with minimal site engineering.
- Gas Companies:Midstream gas processors and LNG developers specify integrated turbomachinery trains with performance guarantees. Qatargas and Cheniere Energy procurement frameworks bundle compression, power generation, and digital monitoring into single-source contracts.
- Petrochemical Firms:Chemical operators demand materials compatibility with aggressive process streams and polymer-grade product specifications. BASF and Dow facilities in Ludwigshafen and Freeport specify superduplex stainless pumps for ethylene cracker quench water service.
- Energy Utilities:Power sector buyers integrate rotating equipment into combined-cycle and cogeneration plants with grid-stability requirements. Texas ERCOT-connected generators specify fast-ramp gas turbines for renewable balancing duty.
Procurement scale concentrates with Gas Companies; contract sophistication advances fastest among Petrochemical Firms.
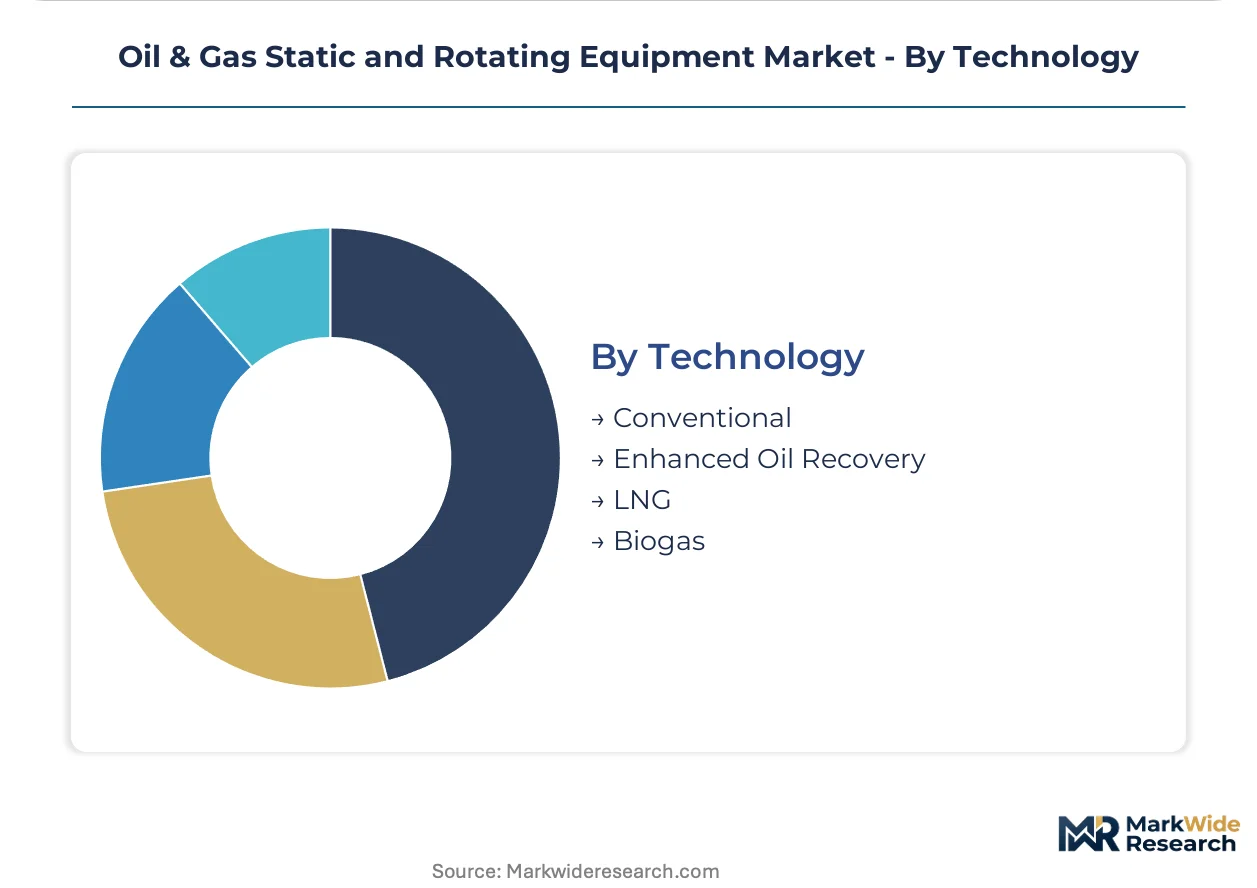
Technology:
Maturity gradients separate established conventional equipment from emerging technology categories requiring qualification cycles and performance validation.
- Conventional:Standard oil and gas extraction and processing equipment without enhanced recovery or alternative fuel integration. These systems retain the installed base majority across all geographies and customer types.
- Enhanced Oil Recovery:CO2 and steam injection systems require high-pressure pumps and compressors rated for supercritical fluid handling. Permian CO2 flood projects specify API 674 positive displacement pumps for viscous crude displacement.
- LNG:Liquefaction and regasification equipment demands cryogenic materials and tight leakage specifications. Modular train designs are standardizing compressor and turbine packages for mid-scale developments.
- Biogas:Renewable natural gas upgrading and injection equipment handles corrosive impurities and variable feedstock composition. European biomethane plants in Denmark and Germany specify oil-free compressors for grid injection compliance.
Installed base dominance rests with Conventional; the steepest expansion trajectory belongs to LNG.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States produces more oil and gas equipment than it consumes, while the Middle East imports high-specification rotating machinery for sour gas expansions. China manufactures compressors and pumps for domestic shale plays and export markets. European fabricators specialize in cryogenic LNG equipment and emissions-compliant designs.
United States
Permian Basin operators deploy modular compression skids for pad drilling configurations. EPA methane emissions rules mandate seal technology upgrades and instrumented compressor deployments across Texas and Louisiana refining clusters. Houston anchors aftermarket service networks for turbomachinery lifecycle support.
Saudi Arabia
Saudi Aramco's sour gas processing expansions pull high-specification rotating equipment rated for hydrogen sulfide service. The kingdom's national procurement frameworks prioritize NACE MR0175-compliant materials and extended type-testing protocols. Eastern Province industrial cities concentrate fabrication yards for pressure-boundary machinery.
China
Domestic shale gas development in Sichuan Basin drives demand for high-pressure fracturing pumps and gas gathering compressors. The country's national standards regulator enforces GB-compliant material specifications for sour service equipment. Yangtze River Delta manufacturing clusters produce centrifugal pumps for refinery circulation duty.
Germany
EU F-Gas Regulation mandates refrigerant transitions in process cooling compressors across Ludwigshafen chemical complexes. REACH chemical restrictions reshape lubricant formulations for European equipment deployments. Ruhr Valley foundries maintain specialized casting capacity for high-pressure compressor casings.
United Arab Emirates
ADNOC's sour gas capacity additions require rotating equipment qualified under ISO 10494 and API 617 protocols. The emirates' national oil company bundles compression, power generation, and digital monitoring into single-source procurement contracts. Abu Dhabi industrial zones host service hubs for turbomachinery maintenance.
Oil & Gas Static and Rotating Equipment Market Competitive Landscape
Top-tier vendors anchor integrated turbomachinery platforms, while mid-tier fabricators compete on modular package standardization and regional service density. The supplier pool compresses around API 617 qualification requirements, concentrating procurement among qualified centrifugal compressor manufacturers. Three archetypes dominate: full-line turbomachinery integrators, specialized pump and compressor OEMs, and aftermarket service contractors. Competitive moves center on digital twin integration for predictive maintenance revenue and magnetic bearing technology licensing for unmanned station applications.
Among US-based energy service conglomerates, NOV Inc., Baker Hughes Company, and Schlumberger Limited occupy positions across the equipment spectrum. NOV Inc. exemplifies offshore drilling equipment specialization through its rig technology division. Baker Hughes Company represents integrated turbomachinery competition with combined compressor and power generation offerings. Schlumberger Limited anchors digital lifecycle monitoring capabilities extending across client installation bases.
| Leading Market Players |
|---|
| NOV Inc. |
| ChampionX Corporation |
| Schlumberger Limited |
| Cactus, Inc. |
| Archrock, Inc. |
| Baker Hughes Company |
| Weatherford International plc |
| Liberty Oilfield Services Inc. |
| Halliburton Company |
| Others |
Pricing and Supply Chain Analysis
Chromium-molybdenum alloy price indices cascade through fabrication tiers, compressing margins for NACE MR0175-compliant compressor casings while elevating procurement premiums for Middle East sour gas projects. API 617 qualification costs concentrate pricing power among German, Japanese, and South Korean foundries with certified high-pressure casting capacity.
Pricing Analysis
Margin tightening in standard-grade pump packages reflects chromium-molybdenum volatility and extended API qualification cycles. Three-tier pricing structure across API-certified premium, standard compliance, and economy-grade equipment segments separates procurement frameworks. Price differentiation hinges on NACE sour service certification tier and bundled digital monitoring attach rates. Independent Permian operators exhibit highest price sensitivity; Qatargas and Cheniere Energy procurement contracts show lowest sensitivity due to performance-guarantee requirements.
Supply Chain Analysis
Saudi Aramco and ADNOC domestic-content mandates are reshaping sourcing patterns for rotating equipment packages. High-pressure casting capacity concentrates in Germany, Japan, and South Korea; raw material feeds draw from chromium and molybdenum mining operations in South Africa and Kazakhstan. Single-source vulnerability clusters around specialized foundry capacity for API 617 compressor casings. Distribution runs through EPC consortia and long-term service contractors for integrated turbomachinery trains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API 617 qualification tightening is compressing supplier pools and forcing consolidation among mid-tier fabricators unable to absorb extended type-testing costs. Equipment vendors must navigate this Darwinian pressure through strategic positioning across digital service layers and magnetic bearing technology licensing.
For Market Incumbents: To counter magnetic bearing technology disruption from emerging electromechanical specialists, Baker Hughes and NOV Inc. should deepen backward integration into permanent magnet motor supply chains and anchor capacity expansion in Abu Dhabi industrial zones to capture ADNOC bundled procurement contracts. Digital twin platform standardization offers defensive moat construction against predictive maintenance challengers. For New Entrants and Emerging Players: Begin with biogas upgrading equipment for European biomethane plants in Denmark and Germany, where oil-free compressor demand outpaces established OEM qualification cycles. Modular LNG train standardization creates white-space entry for mid-scale liquefaction package providers. Go-to-market positioning should emphasize F-Gas Regulation compliance acceleration ahead of 2030 phase-down deadlines. For Investors and Strategic Acquirers: Distressed-cycle entries favor API 617-qualified centrifugal compressor specialists with established NACE sour service credentials in the Eastern Province industrial cluster. Long-term viability over the next decade rests on digital service revenue attach rates exceeding hardware margins. Watch for Saudi Aramco procurement framework shifts toward single-source turbomachinery bundles as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Technology Licensing | Kinder Morgan and TC Energy pilot programs validate unmanned station economics for pipeline operators. |
| Digital Twin Platform Integration | Schlumberger's lifecycle monitoring capabilities extend recurring revenue across Norwegian Continental Shelf installations. |
| API 617 Qualification Investment | Extended type-testing protocols compress supplier pools and consolidate procurement among certified manufacturers. |
| Modular LNG Train Standardization | Mid-scale liquefaction developments reduce project-specific engineering and enable equipment package pre-qualification. |
| F-Gas Refrigerant Transition | German chemical operators in Ludwigshafen absorb retrofit costs ahead of EU regulatory phase-down deadlines. |
Research Methodology
Document review covered API and ISO standard certification databases, EPC contractor procurement disclosures, and national oil company tender documentation, complemented by interviews with turbomachinery procurement leads at Saudi Aramco and ADNOC, maintenance directors at Permian Basin operators, and aftermarket service heads at Baker Hughes and NOV Inc. Secondary validation drew from EPA methane emissions rulemaking records, EU F-Gas Regulation implementation reports, and SEC filings from listed energy service conglomerates. Bottom-up equipment shipment tracking and top-down infrastructure investment analysis were triangulated against regional project pipelines.
Segmented outputs across equipment type, application tier, end-user sophistication, and technology maturity were generated through the projection horizon. The analytical framework modeled compressor, pump, turbine, and generator demand trajectories alongside conventional, enhanced oil recovery, LNG, and biogas technology adoption curves. CAGRs were derived from regression analysis of historical qualification cycles and forward-projected sour gas capacity additions. Key inputs included NACE MR0175 material specification adoption rates and magnetic bearing technology penetration in pipeline compression stations.
Chromium-molybdenum price volatility, API qualification timeline extensions, and domestic-content mandate enforcement variations are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding EPA methane rule implementation pace and EU F-Gas phase-down adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
Canada Oil and Gas Pipeline Services Market
Oil & Gas
Singapore LNG Storage Tank Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Pumpjack Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
Global Hydrate Inhibitors Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Nigeria Upstream Oil Sector Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Oil and Gas Refinery Maintenance Services Market
Oil & Gas
Well Intervention Service Market
Oil & Gas
Europe Completion Equipment and Services Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Mexico Wireline Services Market