
 Asia- Pacific Drilling Market | 2026-2036
Asia- Pacific Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Asia- Pacific Drilling Market Outlook
The capability gap between integrated service providers and regional specialists is collapsing as offshore project complexity escalates. Schlumberger Ltd leverages its rotary steerable technology portfolio to dominate deepwater tenders across the South China Sea. Halliburton Company anchors its position through backward integration into drill bit manufacturing and real-time telemetry systems. Baker Hughes Company differentiates via managed pressure drilling capabilities that reduce non-productive time in high-pressure formations.
Asia-Pacific drilling encompasses the mechanical penetration of subsurface formations using rotary, percussive, or hybrid methods to extract hydrocarbons or access geothermal reservoirs, with modern rigs operating at depths exceeding 10,000 meters and borehole diameters ranging from 12¼ inches in production sections to 36 inches in surface holes. The primary purpose centers on creating stable wellbores that enable controlled fluid circulation, casing installation, and completion access for commercial production. Drill bits and downhole tools command concentrated margin pools as consumable replacement cycles accelerate in abrasive formations across Indonesia and Australia. Managed pressure and rotary steerable technologies are displacing conventional methods in deepwater frontiers where narrow drilling windows demand precise bottom-hole pressure management. Onshore applications sustain volume leadership across China's shale basins and India's mature fields, though offshore segments attract premium pricing for harsh-environment rig systems.
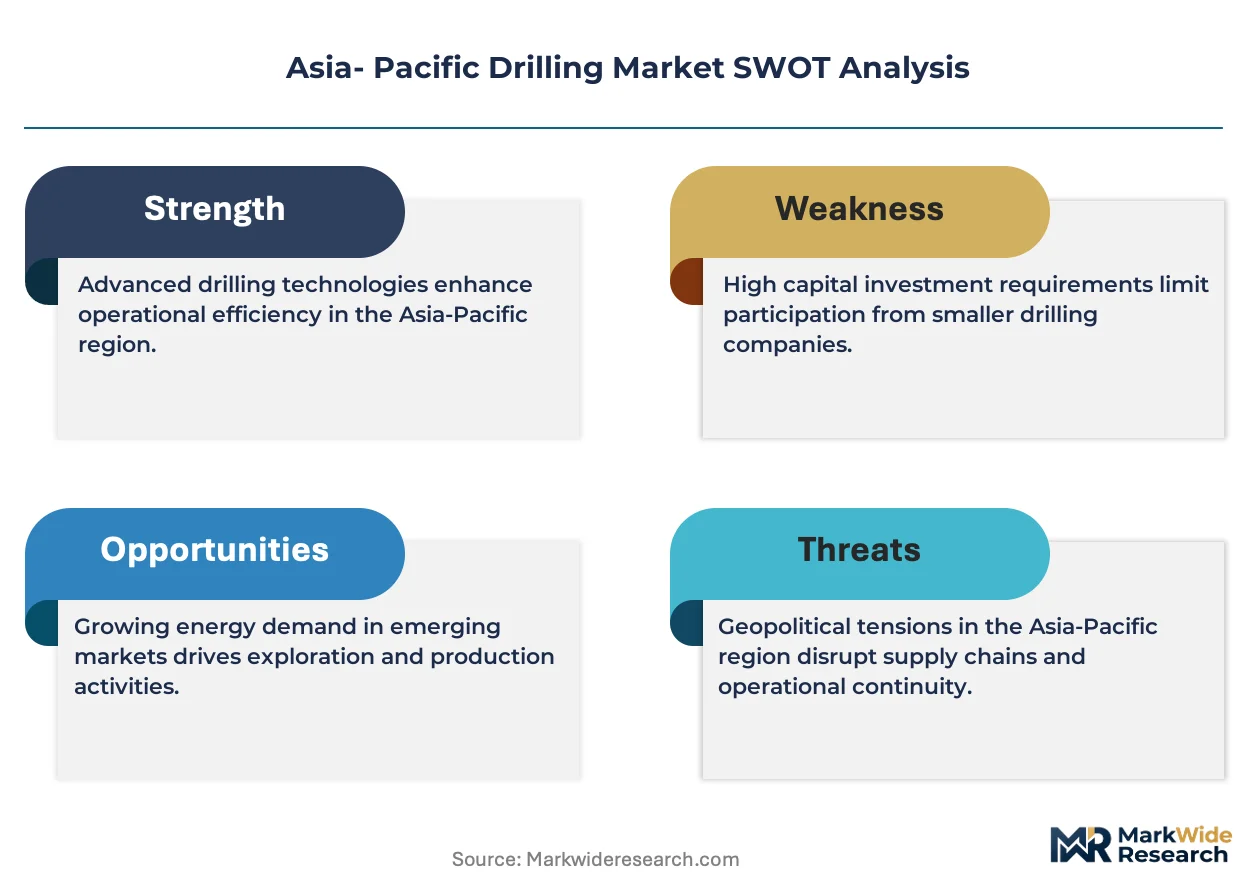
China's MEE enforces emissions caps on onshore drilling operations, while Australia's NOPSEMA mandates well integrity verification for offshore projects, and Indonesia's SKK Migas imposes local content requirements that reshape procurement patterns for rig systems and downhole tools. These frameworks collectively elevate compliance costs for imported equipment while creating preferential market access for regional manufacturers meeting certification standards. Stakeholders must monitor regulatory divergence between carbon-intensity regimes and local-content mandates to align capital allocation with jurisdictions offering operational clarity.
Market Dynamics
China's dual carbon goals and MEE emissions standards are redirecting capital flows from conventional oil and gas drilling toward geothermal and lower-carbon drilling technologies, compressing the planning horizon for equipment procurement across the region.
Growth Catalysts
- Geothermal exploration mandates:China's MEE emissions caps on onshore operations are accelerating investment in geothermal reservoir access, creating parallel demand for adapted rotary steerable systems.
- SKK Migas local content rules:Indonesia's procurement requirements for rig systems and downhole tools are stimulating domestic manufacturing capacity and import substitution.
- Deepwater frontier expansion:Southeast Asian basin intensification is driving jack-up and semi-submersible deployment across Malaysia, Vietnam, and the Philippines.
Market Restraints
- High-specification rig shortage:Harsh-environment semi-submersible availability concentrates among a limited pool of contractors, creating booking bottlenecks for 2027-2028 delivery windows.
- Abrasive formation wear rates:Indonesia's volcanic lithologies and Australia's sandstone sequences accelerate drill bit replacement cycles, elevating consumable cost intensity.
- Carbon border adjustment exposure:China's MEE standards and Australia's NOPSEMA well integrity rules impose divergent compliance architectures that fragment equipment certification pathways.
Strategic Opportunities
- Geothermal heat pump integration:Japan's METI feed-in tariff revisions and South Korea's renewable portfolio standards are opening district heating applications for medium-depth drilling.
- Managed pressure drilling convergence:Integration of real-time telemetry with automated choke systems is creating premium service tiers for narrow-margin deepwater formations.
- Vietnam offshore licensing rounds:Block awards in the Cuu Long and Nam Con Son basins are attracting first-mover rig positioning for 2026-2027 exploration campaigns.
Industry Challenges
- Directional drilling specialist scarcity:Rotary steerable system operation and maintenance expertise concentrates among aging workforce cohorts in Australia and Malaysia.
- Dual-certification burden:Equipment must simultaneously satisfy China's GB standards and Australia's NOPSEMA verification protocols, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia- Pacific Drilling Market |
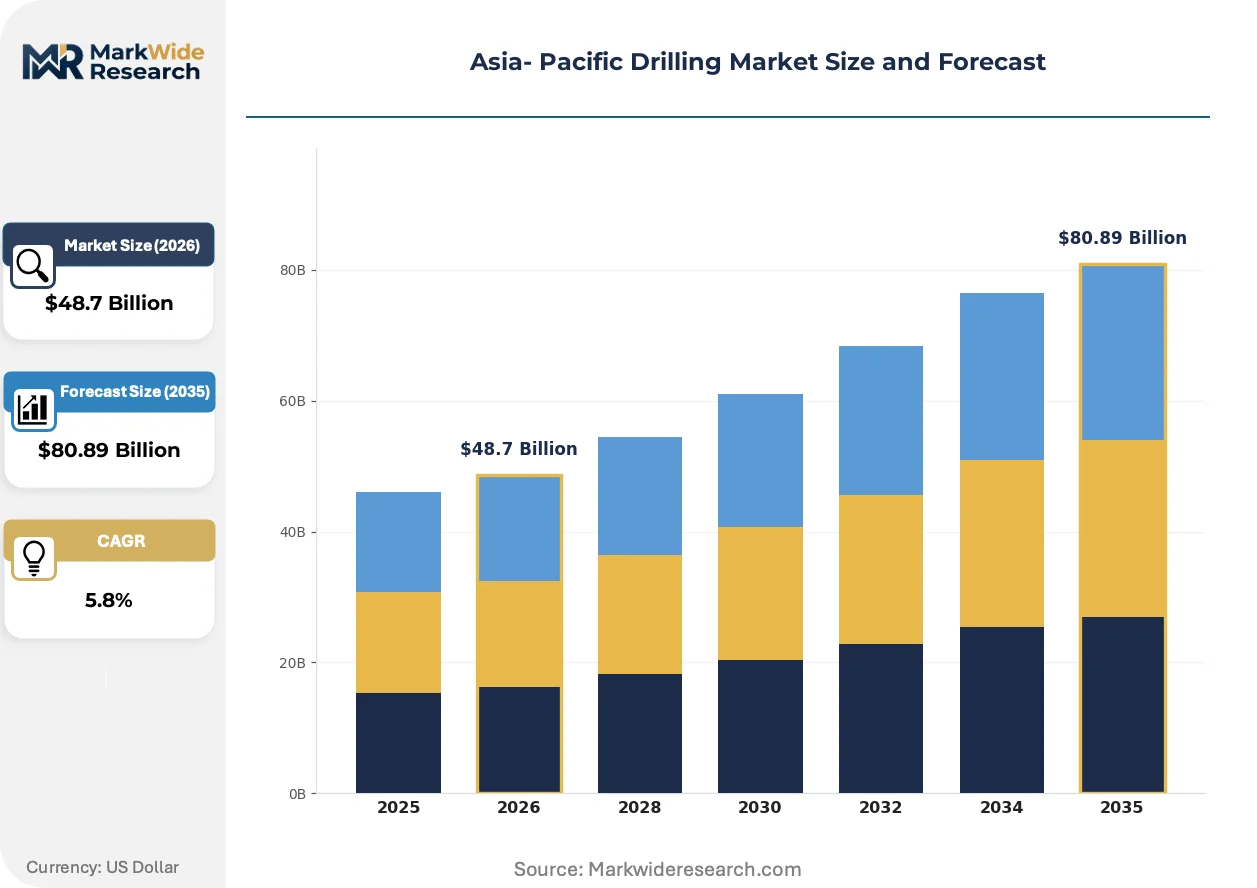
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drill Bits, Mud Pumps, Rig Systems, Downhole Tools Technology: Rotary Steerable, Managed Pressure, Conventional, Coiled Tubing Application: Onshore, Offshore, Geothermal, Oil Exploration End User: Oil Companies, Service Providers, Contractors, Government |
| Companies Covered | Schlumberger Ltd, Halliburton Company, Baker Hughes Company, Weatherford International PLC, China Oilfield Services Limited, Transocean Ltd, National Oilwell Varco Inc, Scientific Drilling International Inc, Nabors Industries Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia- Pacific Drilling Market Strategic Shifts
Automation and emissions accountability are compressing traditional service hierarchies, with real-time data systems and lower-carbon rig architectures displacing conventional operational models across Southeast Asian contract tenders.
Managed pressure drilling systems with integrated automated choke control are supplanting conventional pressure management in deepwater frontiers. National oil companies in Malaysia and Vietnam are mandating MPD capability for frontier block commitments. This technology is compressing non-productive time in high-pressure formations and elevating service provider qualification barriers.
Australia's NOPSEMA well integrity verification framework now mandates independent third-party certification for blowout preventer testing and casing design validation. Offshore project timelines have extended by 8-12 weeks to accommodate enhanced documentation requirements. Premium rig contractors are absorbing compliance costs into day-rate structures, widening the bid spread against non-certified competitors.
Performance-based contracting is displacing traditional day-rate arrangements for integrated drilling services. National oil companies in Indonesia and Thailand are unbundling equipment provision from operational execution, transferring downhole risk to service providers. This shift is most visible in Australia's Browse Basin and Indonesia's Mahakam block, where outcome metrics now govern 40-50% of contract value.
Asia- Pacific Drilling Market Segmentation
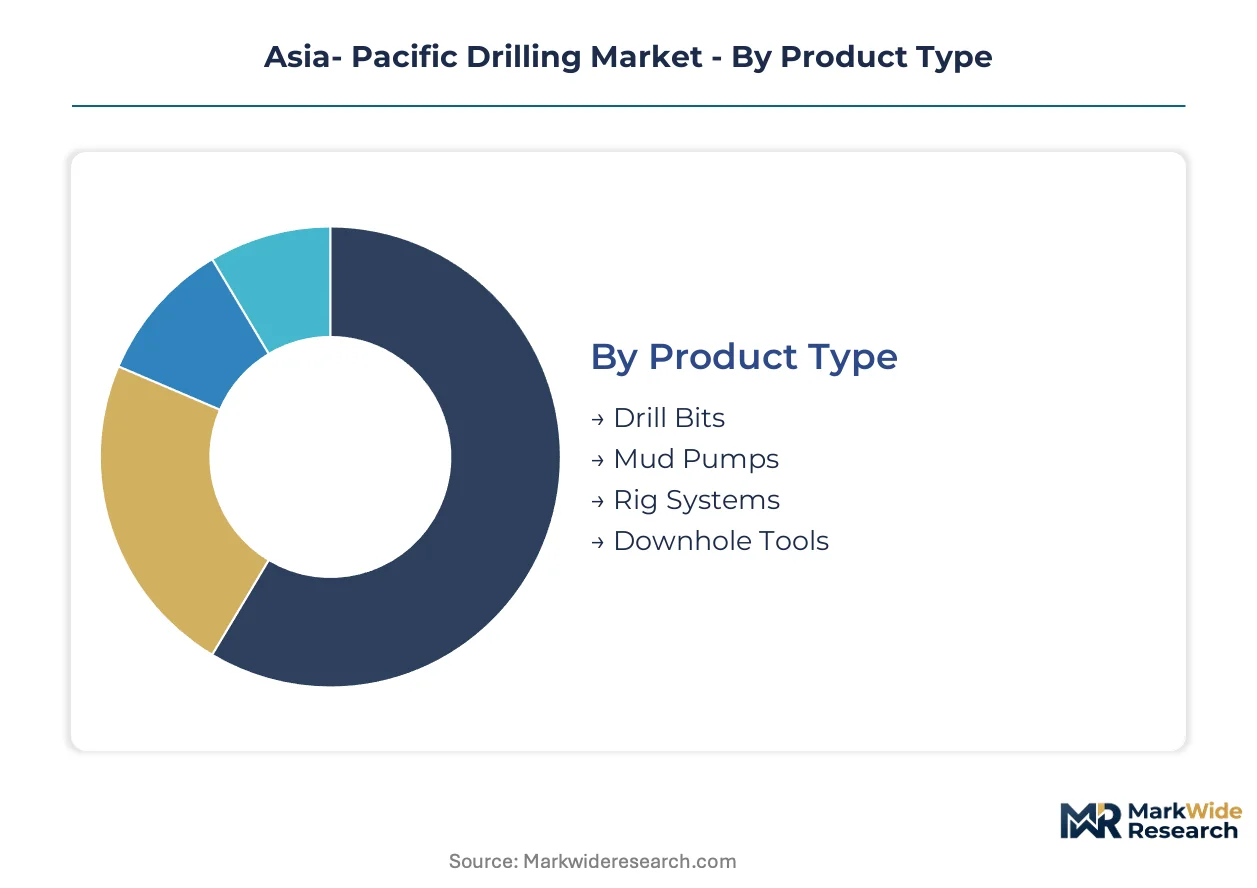
Segmentation in Asia-Pacific drilling reveals how equipment specifications, technology tiers, and regulatory exposure fragment procurement decisions across China's shale basins, Indonesia's volcanic formations, and Australia's deepwater frontiers. Understanding these fault lines exposes where margin pools concentrate and which segments face displacement from lower-carbon alternatives.
Product Type:
Rotary steerable systems and managed pressure equipment are exerting substitution pressure on conventional drill bit and mud pump categories as operators prioritize directional precision over mechanical durability in Southeast Asian deepwater blocks.
- Drill Bits:Polycrystalline diamond compact and roller cone configurations dominate abrasive formations across Indonesia's Mahakam block and Australia's Browse Basin. China's Sichuan shale operators are accelerating tungsten carbide insert replacement cycles as lateral lengths extend beyond 3,000 meters.
- Mud Pumps:High-pressure triplex and quintuplex systems circulate drilling fluid at pressures exceeding 7,500 psi in South China Sea deepwater wells. Indonesia's SKK Migas local content rules are redirecting procurement toward domestically assembled pump packages.
- Rig Systems:Jack-up and semi-submersible platforms command premium day rates in Vietnam's Cuu Long basin.
- Downhole Tools:Measurement-while-drilling and logging-while-drilling assemblies face qualification bottlenecks under dual certification requirements.
Drill bits retain volume leadership across the region's abrasive lithologies; rig systems hold the steepest expansion curve as deepwater licensing intensifies.
Technology:
Cost tier stratification separates premium automated systems from conventional mechanical approaches, with national oil companies in Malaysia and Vietnam mandating MPD capability for frontier block awards.
- Rotary Steerable:Closed-loop directional control enables continuous rotation while steering, eliminating slide drilling inefficiencies in China's Changning shale and Australia's Northwest Shelf. Real-time telemetry integration is compressing well construction timelines by 12-15% in extended-reach applications.
- Managed Pressure:Automated choke systems maintain constant bottom-hole pressure in narrow-margin formations across the South China Sea. Malaysia's Petronas now requires MPD pre-qualification for all deepwater tenders.
- Conventional:Standard rotary table and positive displacement motor configurations persist in China's mature Daqing field operations.
- Coiled Tubing:Continuous pipe technology enables live well intervention in Indonesia's high-pressure Mahakam gas developments.
Conventional technology retains volume leadership in China's onshore mature basins; managed pressure systems are climbing the fastest as regulatory mandates spread.
Application:
Customer type divergence separates volume-driven national oil companies from risk-averse independents, reshaping contract structures across geothermal and offshore exploration.
- Onshore:Extended-reach horizontal drilling dominates China's Sichuan and Tarim basins, with well depths exceeding 8,000 meters in ultra-deep gas targets. India's mature Cambay field operators are deploying slim-hole rigs to access bypassed pay zones.
- Offshore:Harsh-environment semi-submersibles concentrate in Australia's Northwest Shelf and Malaysia's Sabah deepwater blocks. Rig availability constraints are extending lead times for 2027-2028 exploration campaigns.
- Geothermal:Medium-depth drilling for district heating applications is expanding in Japan's Tohoku region under METI feed-in tariff revisions.
- Oil Exploration:Frontier wildcatting concentrates in Vietnam's Nam Con Son basin and the Philippines' Reed Bank.
Onshore applications retain volume leadership across China's shale expansion; geothermal drilling is gaining share fastest as dual carbon policies redirect capital flows.
End User:
Supply concentration among integrated service providers is compressing margins for pure-play equipment vendors as national oil companies unbundle provision from execution.
- Oil Companies:National oil companies in Indonesia, Thailand, and Malaysia are transferring downhole risk to contractors through performance-based contracts. Outcome metrics now govern 40-50% of contract value in Australia's Browse Basin.
- Service Providers:Integrated drilling contractors are absorbing compliance costs for Australia's NOPSEMA well integrity verification into day-rate structures. This is widening bid spreads against non-certified competitors.
- Contractors:Independent rig operators face equipment certification bottlenecks under China's GB standards and Australia's NOPSEMA protocols.
- Government:Direct procurement for strategic geothermal and strategic petroleum reserve access is expanding in South Korea and Japan.
Oil companies retain volume leadership in contract awards; service providers are expanding most quickly as integrated performance contracts displace traditional day-rate arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Indonesia and Vietnam exhibit the highest price elasticity for standard rig systems, while Australian and Malaysian operators absorb premium day rates for harsh-environment semi-submersibles without demand contraction.
China
Extended-reach horizontal drilling in Sichuan and Tarim basins drives equipment procurement, with well depths surpassing 8,000 meters in ultra-deep gas targets. MEE emissions caps redirect capital toward geothermal reservoir access. Yangtze River Delta manufacturing clusters supply adapted rotary steerable systems for dual carbon compliance.
Indonesia
Volcanic lithologies across the Mahakam block accelerate polycrystalline diamond compact bit replacement cycles. SKK Migas local content rules mandate domestic assembly for rig systems and downhole tools. Jakarta-Batam industrial corridors expand manufacturing capacity for mud pump packages.
Australia
Harsh-environment semi-submersible demand concentrates in the Northwest Shelf and Browse Basin, where rig availability constraints extend 2027-2028 exploration lead times. NOPSEMA well integrity verification mandates independent third-party certification for blowout preventer testing. Perth-based contractors absorb compliance costs into premium day-rate structures.
Vietnam
Frontier wildcatting in the Cuu Long and Nam Con Son basins attracts first-mover jack-up positioning for 2026-2027 exploration campaigns. Block licensing rounds mandate managed pressure drilling capability for deepwater commitments. Ho Chi Minh City service hubs coordinate real-time telemetry integration for narrow-margin formations.
Malaysia
Petronas requires managed pressure drilling pre-qualification for all deepwater tenders, elevating service provider barriers. Sabah deepwater blocks drive semi-submersible deployment as regional exploration intensifies. Kuala Lumpur procurement centers unbundle equipment provision from operational execution under performance-based contracting frameworks.
Asia- Pacific Drilling Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated service providers commanding premium positioning through real-time telemetry portfolios while regional specialists compete on asset-light flexibility. The market structure consolidates around three tiers: global integrated contractors with full-service capabilities, national champions leveraging local content rules, and independent rig operators facing certification bottlenecks. Strategic moves center on backward integration into consumable manufacturing and geographic positioning for frontier licensing rounds.
Among Houston-based integrated service providers, Schlumberger Ltd and Halliburton Company exemplify the technology-differentiated tier, while Baker Hughes Company anchors the managed pressure drilling specialization vector. China Oilfield Services Limited represents the national champion archetype capitalizing on domestic procurement preferences. These three entities occupy distinct competitive positions shaped by regulatory alignment with MEE standards, SKK Migas local content mandates, and NOPSEMA verification protocols.
| Leading Market Players |
|---|
| Schlumberger Ltd |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International PLC |
| China Oilfield Services Limited |
| Transocean Ltd |
| National Oilwell Varco Inc |
| Scientific Drilling International Inc |
| Nabors Industries Ltd |
| Others |
Value Chain & Pricing Dynamics
Performance-based contracting locks in supply access for integrated service providers while anchoring price visibility through outcome-governed payment structures across Indonesia's Mahakam block and Australia's Browse Basin. This contract form transfers downhole risk to contractors and compresses bid spreads for non-certified competitors under divergent MEE and NOPSEMA compliance architectures.
Pricing Analysis
Consumable replacement revenue from polycrystalline diamond compact bits and downhole tool assemblies drives lifetime value for equipment vendors across abrasive Indonesian volcanic formations. Three-tier pricing structure across premium, standard, and economy levels separates certified rotary steerable systems from conventional mechanical configurations, with premium tiers absorbing Australia's NOPSEMA verification costs into day-rate structures. Cost compression in standard rig systems intensifies as Jakarta-Batam industrial corridors expand domestic mud pump assembly capacity. National oil companies in Vietnam exhibit highest price elasticity for jack-up positioning, while Australian operators absorb premium semi-submersible rates without demand contraction.
Supply Chain Analysis
Extended lead times for harsh-environment semi-submersible components now stretch 2027-2028 exploration campaign windows across Australia's Northwest Shelf. Manufacturing gravity centers on China's Yangtze River Delta for adapted rotary steerable systems, Indonesia's Jakarta-Batam corridor for mud pump packages, and Perth-based fabrication yards for blowout preventer assemblies. Raw material flows draw from tungsten carbide suppliers for extended-reach drill bits, high-strength steel for pressure-rated casing, and rare-earth elements for downhole telemetry sensors. Single-source vulnerability concentrates in automated choke system controllers for managed pressure drilling. Distribution runs through Ho Chi Minh City service hubs for Vietnam frontier blocks and Kuala Lumpur procurement centers for Petronas deepwater tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific drilling market is cycling upward from 2020-2022 capital starvation as offshore licensing rounds across Vietnam and Malaysia reactivate exploration expenditure. Jack-up and semi-submersible demand recovery is compressing available rig supply and elevating contractor pricing power.
For Market Incumbents: Shield market position by deepening backward integration into drill bit manufacturing to capture consumable replacement cycles in Indonesia's abrasive lithologies. Prioritize dual-certification investment for China's GB standards and Australia's NOPSEMA protocols to extend qualification timelines that exclude non-certified competitors. Absorb compliance costs into premium day-rate structures to widen bid spreads against independent rig operators facing certification bottlenecks. For New Entrants and Emerging Players: Differentiate on geothermal drilling adaptation for China's dual carbon compliance, where MEE emissions caps redirect capital toward reservoir access technologies with lower competitive density. Target medium-depth district heating applications in Japan's Tohoku region under METI feed-in tariff revisions as the most penetrable segment. Pursue technology licensing partnerships with Yangtze River Delta manufacturing clusters to bypass SKK Migas local content barriers through domestic assembly arrangements. For Investors and Strategic Acquirers: Capital is best deployed toward integrated service providers with real-time telemetry portfolios and managed pressure drilling capabilities, as these technology tiers face regulatory mandate expansion across Malaysia and Vietnam. Long-term viability over the next decade hinges on exposure to deepwater frontier licensing rather than mature onshore basins. Watch managed pressure drilling pre-qualification requirements as the inflection signal for contractor tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Consumable Manufacturing | Captures accelerated replacement cycles in Indonesia's volcanic Mahakam block formations. |
| Dual-Certification Investment | Extends qualification timelines under China's MEE and Australia's NOPSEMA verification protocols. |
| Geothermal Technology Adaptation | Aligns with China's dual carbon goals redirecting capital from conventional hydrocarbon drilling. |
| Managed Pressure Drilling Capability Buildout | Satisfies Petronas pre-qualification mandates for all deepwater tenders across Sabah blocks. |
| Performance-Based Contracting Transition | Transfers downhole risk and governs 40-50% of contract value in Australia's Browse Basin. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through primary interviews with drilling contractors, national oil company procurement officers, rig fleet managers, and downhole tool engineering leads. Secondary validation drew from SKK Migas procurement disclosures, Australia's NOPSEMA well integrity verification records, China's MEE emissions compliance filings, and customs data for rig system imports. Bottom-up equipment deployment counts were triangulated against top-down capital expenditure estimates from national oil company budget disclosures.
Across the analysis window, the forecasting framework modeled demand trajectories by technology tier, application depth, and regulatory compliance cluster. Segmentation dimensions included product type, technology sophistication, onshore-offshore application, and end-user contracting structure. CAGRs were derived from equipment replacement cycle analysis and licensing round timing across Southeast Asian basins. Forecast inputs incorporated jack-up and semi-submersible orderbook visibility, geothermal exploration mandate acceleration under MEE standards, and SKK Migas local content procurement redirection.
Material uncertainties — licensing round delays, rig delivery slippage, and regulatory divergence between carbon-intensity regimes — sit outside the modeled envelope. Forecasts reflect assumptions about continued offshore frontier expansion and dual carbon policy implementation trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East and Africa Drill Collar Market
Oil & Gas
Distributed Fiber Optic Sensor in Oil & Gas Market
Oil & Gas
Africa Oilfield Services Market
Oil & Gas
Downhole Tools Market
Oil & Gas
Global LNG Regasification Terminals Market
Oil & Gas
Oilfield Rotary Table Market
Oil & Gas
Frac Services Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Australia LNG Bunkering Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
Libya Oil and Gas Midstream Market
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
North Sea Oilfield Equipment Market