
 Kraft Paper Bakery Bags Market | 2026-2036
Kraft Paper Bakery Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Paper Bakery Bags Market Foresight
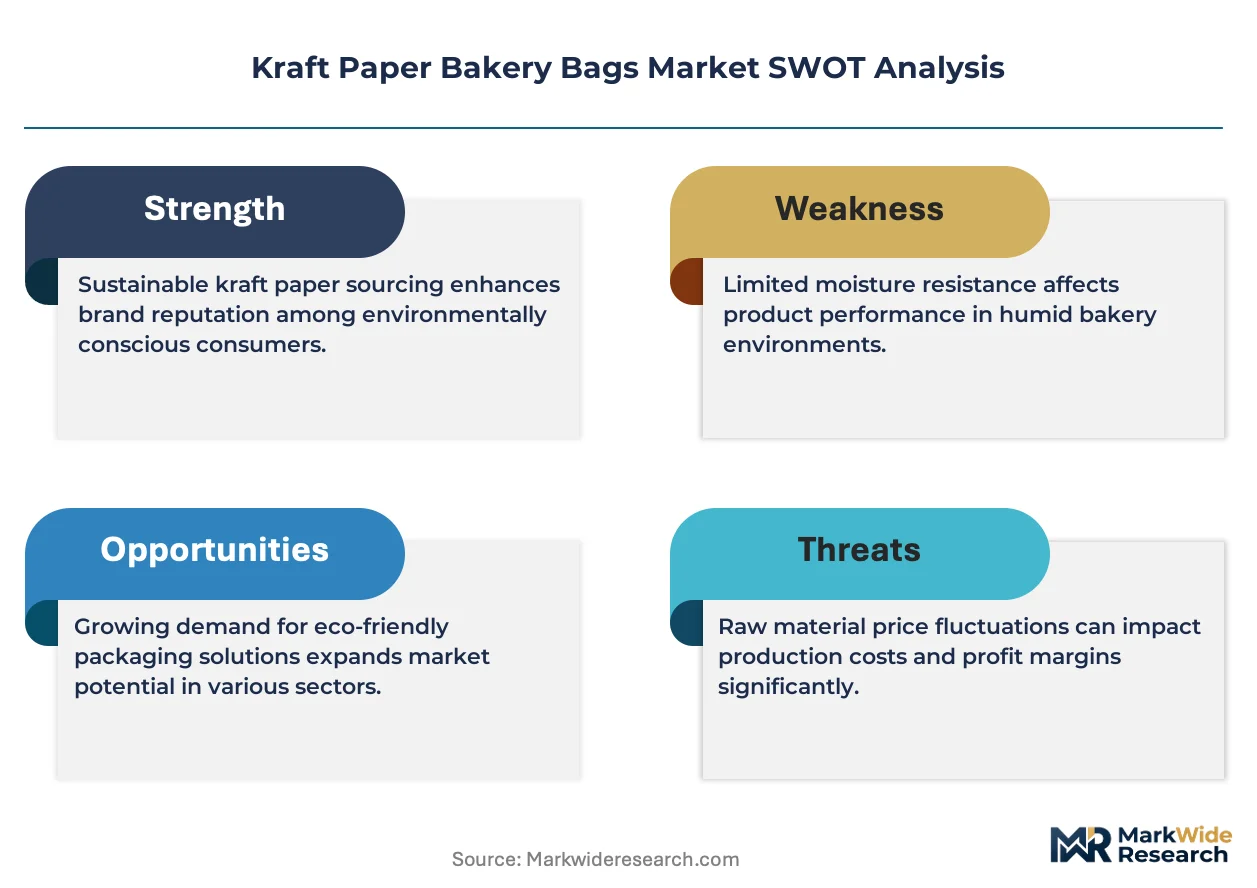
FSC certification is bifurcating the competitive landscape for kraft paper bakery bags, as chain buyers restrict vendor pools to suppliers with chain-of-custody documentation. WestRock Company leverages its integrated pulp-to-converting footprint to sustain volume commitments across North American bakery chains. Mondi Group anchors its position through specialty kraft grades engineered for high-fat resistance in artisan bread applications.
Kraft paper bakery bags are unbleached paper containers, typically constructed from 30–60 lb basis weight sulfate pulp with optional polyethylene or biodegradable barrier coatings, designed to package baked goods while managing moisture and grease migration. Window bags command premium positioning due to their dual function of product visibility and shelf appeal in retail bakery environments, while gusseted bags occupy the high-volume segment for boule and artisan loaf formats where structural expansion matters. The end-user base tilts toward bakery shops and supermarkets, with food catering services representing the fastest-growing channel as event-based pastry delivery scales.
USDA BioPreferred program requirements and FDA food-contact substance regulations govern material composition and marketing claims for kraft paper bakery bags distributed in the United States, while the EU Packaging and Packaging Waste Directive shapes recyclability mandates across member states. These frameworks elevate compliance costs for imported stock but simultaneously lock in demand for domestically certified converters. Stakeholders must monitor evolving state-level extended producer responsibility laws and assess whether early investment in home-compostable barrier technologies will yield channel access advantages before standards crystallize.
Market Dynamics
EU Single-Use Plastics Directive enforcement is forcing foodservice operators across Western Europe to eliminate conventional plastic bakery packaging, redirecting procurement volumes toward FSC-certified kraft alternatives with verified chain-of-custody documentation.
Growth Catalysts
- EU Packaging and Packaging Waste Directive:Mandatory recyclability targets for member states are locking in fiber-based packaging demand as bakeries retrofit supply chains to avoid non-compliance penalties.
- Grease-resistant barrier coatings:Advances in biodegradable PLA and water-based dispersions are expanding kraft bag applicability into high-fat artisan bread segments previously served by plastic windows.
- Artisan bakery cluster concentration:Germany, France, and the United Kingdom are witnessing coordinated supply chain upgrades as bakery chains standardize compostable packaging across multi-store networks.
Market Restraints
- Unbleached kraft pulp supply concentration:Sulfate pulp production gravitates toward integrated North American and Nordic mills, exposing converters to freight cost volatility and lead time extension.
- Polyethylene barrier coating regulatory friction:FDA food-contact substance regulations and divergent state-level extended producer responsibility laws create compliance complexity for imported stock.
- Reusable container substitution:Deposit-return schemes for rigid bakery boxes in select European municipalities are capturing a small but growing share of daily bread packaging volume.
Strategic Opportunities
- Home-compostable barrier technology:Early investment in certified home-compostable coatings yields channel access advantages before ASTM D6400 and EN 13432 standards fully crystallize across jurisdictions.
- Food catering services channel:Event-based pastry delivery scaling creates demand for premium window bags with structural integrity for transport and display.
- USDA BioPreferred program alignment:Federal procurement preference for biobased products opens institutional foodservice accounts to certified domestic converters.
Industry Challenges
- FSC chain-of-custody certification timeline:Documentation gaps between pulp suppliers and downstream converters delay vendor qualification for restricted buyer pools at major bakery chains.
- Barrier performance standardization delays:Absence of unified test protocols for grease resistance and moisture vapor transmission creates specification disputes between buyers and suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Paper Bakery Bags Market |
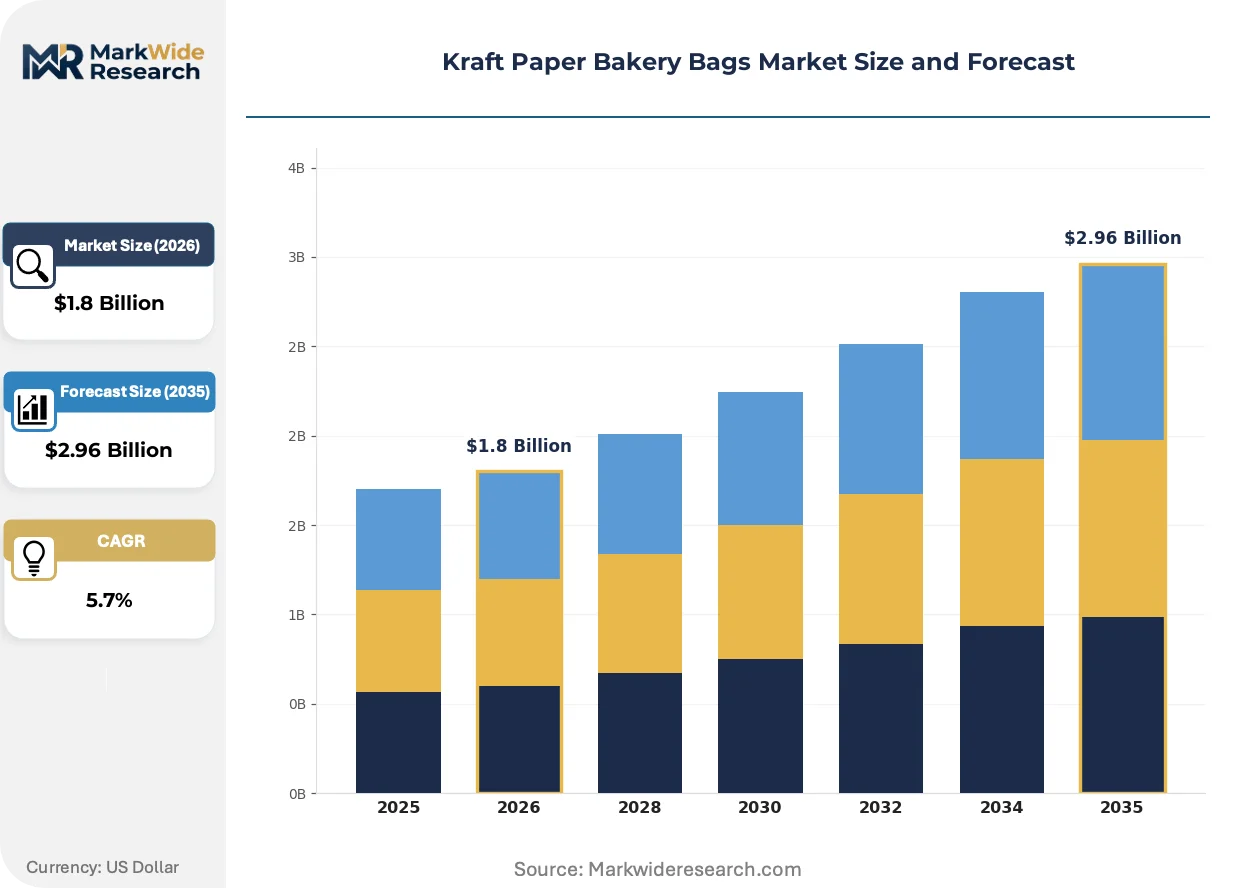
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Window Bags, Gusseted Bags, Bread Bags End User: Bakery Shops, Supermarkets, Food Catering Services, Restaurants Size: Small, Medium, Large, Extra Large Application: Packaging, Delivery, Retail Display, Storage |
| Companies Covered | WestRock Company, Fisher Paper Products, Classic Packaging Corp, Mil-Spec Packaging for GA, Inc., International Paper Company, Mondi Group, Smurfit Westrock, Novolex, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Paper Bakery Bags Market Shifts & Advancements
Barrier coating chemistry is the primary locus of technical competition, with water-based and bio-derived formulations displacing conventional polyethylene laminates as regulatory pressure intensifies and brand owners pursue compostability claims.
PLA-coated window films are miniaturizing the functional gap between fiber-based and plastic bakery packaging. Artisan bakeries in France and Germany are adopting these films at accelerated pace for viennoiserie display applications. The technology is miniaturizing the premium positioning advantage previously held by conventional plastic windows, compressing price premiums for compostable alternatives.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorochemical grease barriers from EU-sourced kraft bakery bags. Industrial consequence includes accelerated R&D spending on silicone and clay-based alternatives by coating suppliers. High-fat resistance applications in German artisan bread packaging are most affected, with buyers now requiring third-party verification of PFAS-free status.
Buyer consolidation among North American bakery chains is compressing supplier negotiation cycles and unbundling legacy distributor relationships. Direct procurement contracts with certified converters are replacing foodservice distribution intermediaries for volume accounts. This pattern is most visible in United States supermarket in-store bakery operations, where centralized packaging specification teams now mandate FSC documentation at contract award.
Kraft Paper Bakery Bags Market Segmentation
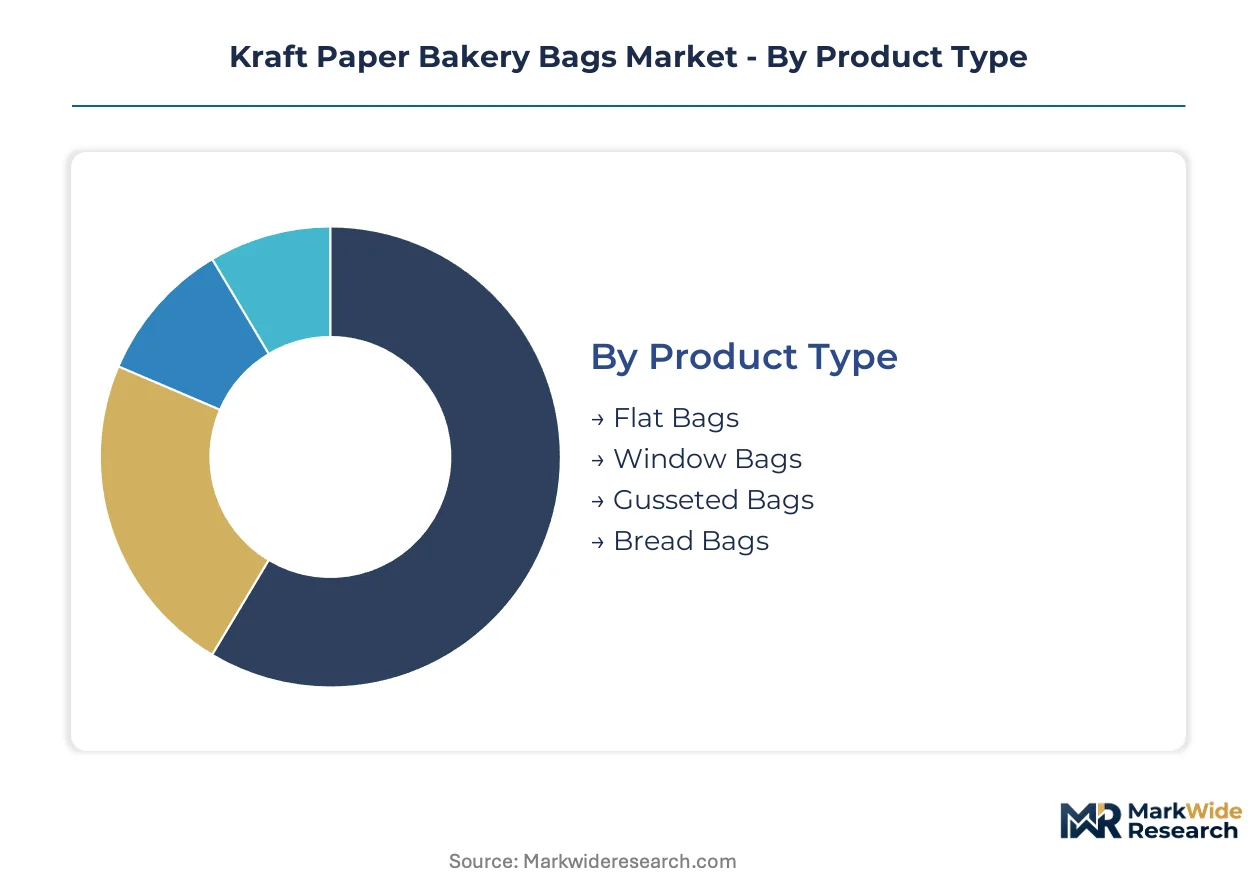
Segmentation in kraft paper bakery bags reveals how packaging specifications diverge across customer workflows. Each dimension—product format, end-user channel, sizing, and application—carries distinct margin profiles and substitution vulnerabilities that shape procurement priorities.
Product Type:
Window bags face the most acute substitution pressure from PLA-coated film alternatives, while gusseted formats resist displacement due to structural requirements for artisan loaves.
- Flat Bags:Unstructured kraft containers constructed from 30–40 lb basis weight pulp, optimized for flat pastries and cookies. German bakery chains are consolidating flat bag specifications to reduce SKU complexity in centralized procurement.
- Window Bags:Dual-layer construction combining kraft paper body with transparent film panel, typically PLA or cellulose-based, enabling product visibility without full plastic enclosure. French viennoiserie specialists are retrofitting display cases for these formats as REACH restrictions eliminate fluorochemical barriers.
- Gusseted Bags:Expandable side panels accommodate boule and batard profiles without compression. United Kingdom artisan bakery clusters specify these for sourdough distribution where crust integrity determines repurchase rates.
- Bread Bags:Standardized elongated format with twist-tie or tape closure, positioned for high-volume sliced bread segments. Supermarket in-store bakeries in the United States are migrating these specifications to FSC-certified stock.
Flat bags retain volume leadership; window bags hold the steepest expansion curve.
End User:
Cost tier differentiation separates premium-positioned channels from price-sensitive volume accounts, with certification requirements widening the procurement gap between tiers.
- Bakery Shops:Independent and small-chain operators prioritizing tactile packaging experience and compostability credentials. France and Germany lead retrofit rates as EU Single-Use Plastics Directive enforcement tightens.
- Supermarkets:Centralized specification teams mandate FSC chain-of-custody documentation and volume-scale pricing. United States supermarket in-store bakery operations are unbundling legacy distributor relationships for direct converter contracts.
- Food Catering Services:Event-based pastry delivery requiring transport durability and display readiness. This channel is expanding most quickly as corporate and wedding catering scales compostable packaging commitments.
- Restaurants:Takeout and bread-service applications with irregular order patterns and limited storage space. Smaller format preferences dominate, with small and medium bags comprising majority share.
Supermarkets dominate procurement volume; food catering services are climbing the fastest.
Size:
Application-driven sizing creates distinct performance specifications, with larger formats requiring reinforced construction for structural load-bearing.
- Small:Single-serving pastry and cookie formats, typically 4–6 inch width. United States coffeehouse chains specify these for muffin and croissant takeaway.
- Medium:Standard individual loaf or multi-pastry capacity, representing the baseline specification for most bakery shop procurement.
- Large:Multi-loaf or family-size formats with reinforced bottom construction. German artisan bakeries deploy these for weekend bread basket offerings.
- Extra Large:Catering-scale and institutional formats requiring custom printing and branded closure systems. United Kingdom event catering specialists are standardizing these for wedding and corporate pastry displays.
Medium sizes anchor baseline demand; extra large formats are expanding most rapidly through catering channel growth.
Application:
Margin concentration varies sharply by application, with retail display commanding specification premiums and delivery applications driving barrier coating innovation.
- Packaging:Primary containment function with baseline grease and moisture management. This segment captures the largest volume share across all end-user channels.
- Delivery:Transport-optimized construction with reinforced seams and stackability features. Food catering services and restaurant third-party delivery are forcing rapid specification upgrades for thermal and structural integrity.
- Retail Display:Visual merchandising priority with window integration and premium print finishes. French and German specialty retailers are mandating home-compostable barriers for display-facing packaging.
- Storage:Extended shelf-life orientation with enhanced moisture vapor transmission resistance. Artisan bakery subscribers in the United States specify these for multi-day bread preservation.
Packaging maintains volume dominance; delivery applications are gaining share fastest through foodservice channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Single-Use Plastics Directive redirects procurement volumes toward FSC-certified kraft alternatives across Western Europe. Germany, France, and the United Kingdom concentrate retrofit activity as bakery chains standardize compostable packaging.
United States
Supermarket in-store bakery operations mandate FSC chain-of-custody documentation for direct converter contracts. The USDA BioPreferred program locks in federal procurement preference for biobased packaging. California and New York Metro clusters lead specification upgrades for grease-resistant barrier coatings.
Germany
Artisan bakery networks accelerate adoption of PLA-coated window bags for viennoiserie display. REACH restrictions eliminate fluorochemical grease barriers from kraft bakery bags. Bavaria and North Rhine-Westphalia concentrate supply chain retrofit coordination across multi-store bakery chains.
France
Specialty retailers mandate home-compostable barriers for display-facing packaging in response to consumer compostability expectations. The EU Packaging and Packaging Waste Directive shapes recyclability mandates for member states. Paris and Lyon bakery clusters standardize premium window bag specifications for retail presentation.
United Kingdom
Event catering specialists drive demand for extra-large formats with custom printing and branded closure systems. Extended producer responsibility laws elevate compliance costs for imported stock. London and Southeast England concentrate food catering services channel expansion for wedding and corporate pastry displays.
Canada
Health Canada food-contact regulations govern material composition for kraft paper bakery bags distributed domestically. Provincial extended producer responsibility frameworks diverge from federal standards. Ontario and Quebec bakery chains evaluate FSC-certified sourcing against US cross-border supply alternatives.
Kraft Paper Bakery Bags Market Competitive Landscape
Player mix skews toward integrated pulp-to-converting conglomerates and specialty coating converters. The vendor base concentrates around North American and Nordic mills with captive sulfate pulp supply. Two strategic archetypes dominate: integrated paperboard conglomerates with backward control over fiber sourcing, and specialty converters engineering high-fat resistance grades. Competitive moves center on FSC chain-of-custody certification acquisition and biodegradable barrier coating R&D partnerships.
Within the integrated conglomerate tier, WestRock Company and International Paper Company exemplify scale-driven positioning through captive pulp supply and multi-regional converting footprints. Mondi Group occupies a position representing specialty-grade engineering for grease-resistant applications. These three anchors demonstrate how fiber integration and coating specialization bifurcate competitive positioning as bakery chain buyers restrict vendor pools to certified suppliers.
| Leading Market Players |
|---|
| WestRock Company |
| Fisher Paper Products |
| Classic Packaging Corp |
| Mil-Spec Packaging for GA, Inc. |
| International Paper Company |
| Mondi Group |
| Smurfit Westrock |
| Novolex |
| DS Smith |
| Others |
Supply & Pricing Matrix
FSC chain-of-custody certification gates both supplier qualification and price differentiation simultaneously, compressing vendor pools while stratifying contract values across certified and uncertified tiers. Bakery chain buyers in Germany and the United States now mandate documentation at contract award, forcing converters to absorb audit costs or exit restricted procurement channels.
Pricing Analysis
Certification level creates the primary spread between contract tiers, with FSC-certified stock commanding premium positioning against uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade differentiation and volume scale commitments. Cost compression in the standard tier is intensifying because supermarket buyers consolidate specifications for centralized procurement. Food catering services exhibit highest price sensitivity due to event-driven volume volatility, while artisan bakery shops accept premium positioning for compostable barrier credentials.
Supply Chain Analysis
Just-in-time inventory preferences dominate among United States supermarket chains, while European artisan bakery clusters maintain strategic stockpiles of certified kraft pulp to buffer sulfate supply volatility. Production concentrates in the United States, Sweden, and Finland where integrated mills control captive sulfate pulp supply. Raw material dependencies center on unbleached softwood pulp, biodegradable barrier coatings, and PLA window films. Single-source vulnerability runs through Nordic pulp suppliers exposed to energy cost fluctuations. Distribution runs through direct converter contracts replacing legacy foodservice distributor intermediaries for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from reusable container deposit schemes in select European municipalities, requiring defensive repositioning around compostability performance advantages. This substitute threat demands capability investment before standards crystallize across jurisdictions.
For Market Incumbents: Fortify FSC chain-of-custody documentation to defend restricted vendor pool access at major bakery chains. Accelerate R&D partnerships for home-compostable barrier coatings before ASTM D6400 and EN 13432 standards fully crystallize. Backward integration into sulfate pulp supply insulates margin pressure from Nordic energy cost volatility.
For New Entrants and Emerging Players: Lead with specialty coating engineering for high-fat resistance applications in German artisan bread segments where incumbent capability gaps persist. Target food catering services channel expansion in the United Kingdom where event-based pastry delivery scaling outpaces supply infrastructure. Position through certified home-compostable technology partnerships to bypass legacy distributor relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty converters lacking integrated pulp supply but holding coating formulation IP. Long-term viability over the projection horizon hinges on barrier technology differentiation rather than commodity volume positioning. Monitor REACH restriction expansion on per- and polyfluoroalkyl substances as inflection indicator for coating chemistry obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| FSC Certification Acquisition | Chain-of-custody documentation unlocks restricted bakery chain procurement pools in Germany and the United States. |
| Home-Compostable Coating R&D Partnership | Biodegradable barrier investment yields channel access before ASTM D6400 standards crystallize across jurisdictions. |
| Direct Converter Contract Conversion | Supermarket in-store bakery unbundling of legacy distributors compresses negotiation cycles for volume accounts. |
| PLA Window Film Integration | French viennoiserie specialists accelerate adoption as REACH restrictions eliminate fluorochemical alternatives. |
| Food Catering Services Channel Expansion | Event-based pastry delivery scaling in the United Kingdom creates demand for extra-large format structural integrity. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with packaging procurement directors, sustainability officers at bakery chains, coating R&D specialists, and FSC certification auditors; and secondary validation through EU Packaging and Packaging Waste Directive filings, FDA food-contact substance registrations, USDA BioPreferred program listings, and trade customs data for unbleached kraft pulp. Bottom-up volume modeling triangulated against top-down market sizing across product format, end-user channel, and application dimensions.
Across the modeling period, analytical frameworks projected value expansion through segmentation-level CAGRs derived from regulatory enforcement timelines and channel penetration curves. Modeled dimensions included product type, end-user channel, size tier, and application workflow. Forecast inputs incorporated EU Single-Use Plastics Directive compliance deadlines and biodegradable coating adoption rates in high-fat artisan bread segments.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or accelerated reusable container substitution would require recalibration. Forecasts reflect documented assumptions on certification adoption curves and barrier technology performance maturation. Revision becomes warranted when home-compostable standard harmonization crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Display Paper Box Market
Paper & Paperboard Packaging
Release Paper Market
Paper & Paperboard Packaging
Anti-Slip Coated Paper Market
Paper & Paperboard Packaging
Global Solid Board Market
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
South East Asia Corrugated Packaging Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
France Paper Packaging Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market