
 Egypt Paper Packaging Market | 2026-2036
Egypt Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Paper Packaging Market Foresight
Egypt's single-use plastics ban is pivoting investment toward fiber-based alternatives. Smurfit WestRock plc leverages integrated containerboard mills to anchor supply security for Egyptian fast-moving consumer goods brands. Huhtamaki Egypt L.L.C. specializes in molded fiber and flexible paper solutions for dairy and quick-service restaurant chains. Masr International Paper dominates recycled linerboard production, sustaining cost advantages against imported substrate.
Egypt paper packaging encompasses kraft, corrugated, and recycled fiber substrates engineered into boxes, bags, wraps, and sheets for protective containment and shelf-ready display, typically specified by burst strength, edge crush test values, and moisture resistance thresholds to survive Nile Delta humidity and palletized distribution. Corrugated paper leads volume throughput due to e-commerce fulfillment and agricultural export crating, while kraft paper captures expanding share in quick-service food wrapping driven by quick-service restaurant chain expansion. Recycled paper grades occupy the economy tier, pressured by inconsistent municipal fiber collection yields yet supported by government circular-economy procurement mandates.
Egypt's Environmental Affairs Agency enforces industrial emissions standards on paper mills, while the Egyptian Organization for Standardization and Quality certifies food-contact safety under aligned protocols. Compliance with these frameworks shapes converter capital allocation toward water-treatment upgrades and chlorine-free bleaching lines. Stakeholders must monitor enforcement consistency across Upper Egypt governorates, where informal recycling networks supply critical fiber volumes but operate below certification thresholds.
Market Dynamics
Egypt's National Waste Management Strategy is compressing plastic substitution timelines, forcing converters to reconfigure mill lines for kraft-based output while Greater Cairo's dairy and confectionery clusters absorb expanded corrugated capacity.
Growth Catalysts
- Plastic Substitution Mandates:Egypt's Environmental Affairs Agency enforces single-use plastic bans across food service, redirecting quick-service restaurant chains toward molded fiber clamshells and kraft wraps.
- Agricultural Export Crating:Nile Delta citrus and vegetable exporters accelerate corrugated box procurement to satisfy EU import packaging standards and reduce spoilage in refrigerated container transit.
- Circular Economy Procurement:Government purchasing rules mandate recycled content thresholds for state-owned food distributors, securing offtake for domestic recycled linerboard grades.
Market Restraints
- Imported Pulp Cost Volatility:Egyptian mills depend on Brazilian and Scandinavian market pulp for virgin kraft production, exposing margins to dollar-denominated input swings and Suez Canal freight surcharges.
- Upper Egypt Collection Gaps:Informal recycling networks in Sohag and Qena governorates supply critical recovered fiber volumes but operate below Egyptian Organization for Standardization and Quality certification thresholds, creating supply inconsistency.
- Coated Paper Substitution:Polyethylene-lined folding cartons retain cost advantages for high-moisture dairy applications, limiting pure fiber penetration in UHT milk and yogurt segments.
Strategic Opportunities
- Alexandria Port Zone Expansion:Underdeveloped converter capacity near Egypt's second-largest container terminal creates white space for export-focused corrugated plants serving Mediterranean shipping lanes.
- Digital Print Convergence:Combination of inkjet decoration and short-run corrugating lines enables mass customization for seasonal confectionery promotions and limited-edition FMCG launches.
- Green Bond Financing:Central Bank of Egypt sustainable finance guidelines offer preferential lending rates for water-treatment upgrades and chlorine-free bleaching line installations.
Industry Challenges
- Skilled Technician Scarcity:Advanced corrugator operation and color management for food-contact print require training pipelines that Egyptian technical institutes have not scaled to match mill expansion timelines.
- Emissions Compliance Capital Burden:Environmental Affairs Agency industrial emissions standards demand simultaneous investment in wastewater treatment, energy recovery, and dust collection systems, stretching mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Paper Packaging Market |
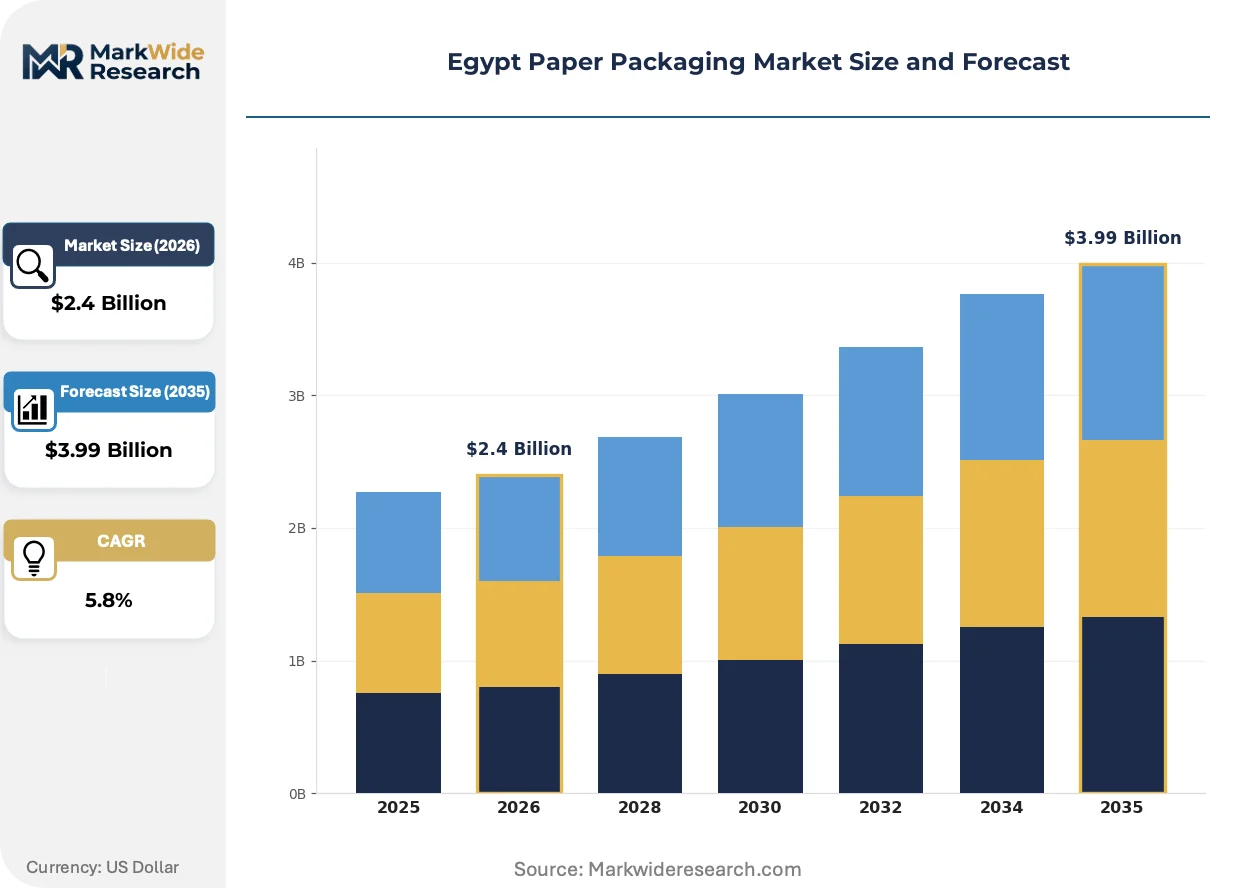
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Wraps, Sheets End User: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Form: Flat, Rolled, Padded, Foldable Material: Kraft Paper, Corrugated Paper, Recycled Paper, Others |
| Companies Covered | INDEVCO Group SAL, International Paper Company, Tetra Pak Egypt Ltd, Graphic Packaging International Egypt, Smurfit WestRock plc, Huhtamaki Egypt L.L.C., Masr International Paper, Cepack Group, Mondi plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Paper Packaging Market Shifts & Advancements
Digital production technologies and regulatory tightening are fragmenting traditional volume-based supply relationships, enabling smaller converters to capture niche specifications previously reserved for integrated mills.
Water-based barrier coatings are decentralizing protective packaging production by eliminating polyethylene lamination steps and enabling on-site application at converter locations. Quick-service restaurant chains in Greater Cairo are adopting these coatings at pilot scale for hot-food containers. This technology is decentralizing supply chain control away from centralized film suppliers toward regional paperboard finishers.
Egypt's Environmental Affairs Agency industrial emissions standards are mandating simultaneous upgrades to wastewater treatment and energy recovery systems. Paper mills face compressed compliance timelines with penalties for non-conformance. Upper Egypt governorates exhibit the widest enforcement variance, prompting converters in those zones to accelerate self-certification before mandatory inspections expand.
Direct mill-to-brand procurement contracts are displacing traditional distributor intermediaries for corrugated volume accounts. Dairy and confectionery plants in 10th of Ramadan City now negotiate specifications directly with containerboard producers, securing lot-traceability for food-contact safety documentation. This pattern concentrates most visibly in Greater Cairo's industrial corridor where clustering reduces logistics coordination costs.
Egypt Paper Packaging Market Segmentation
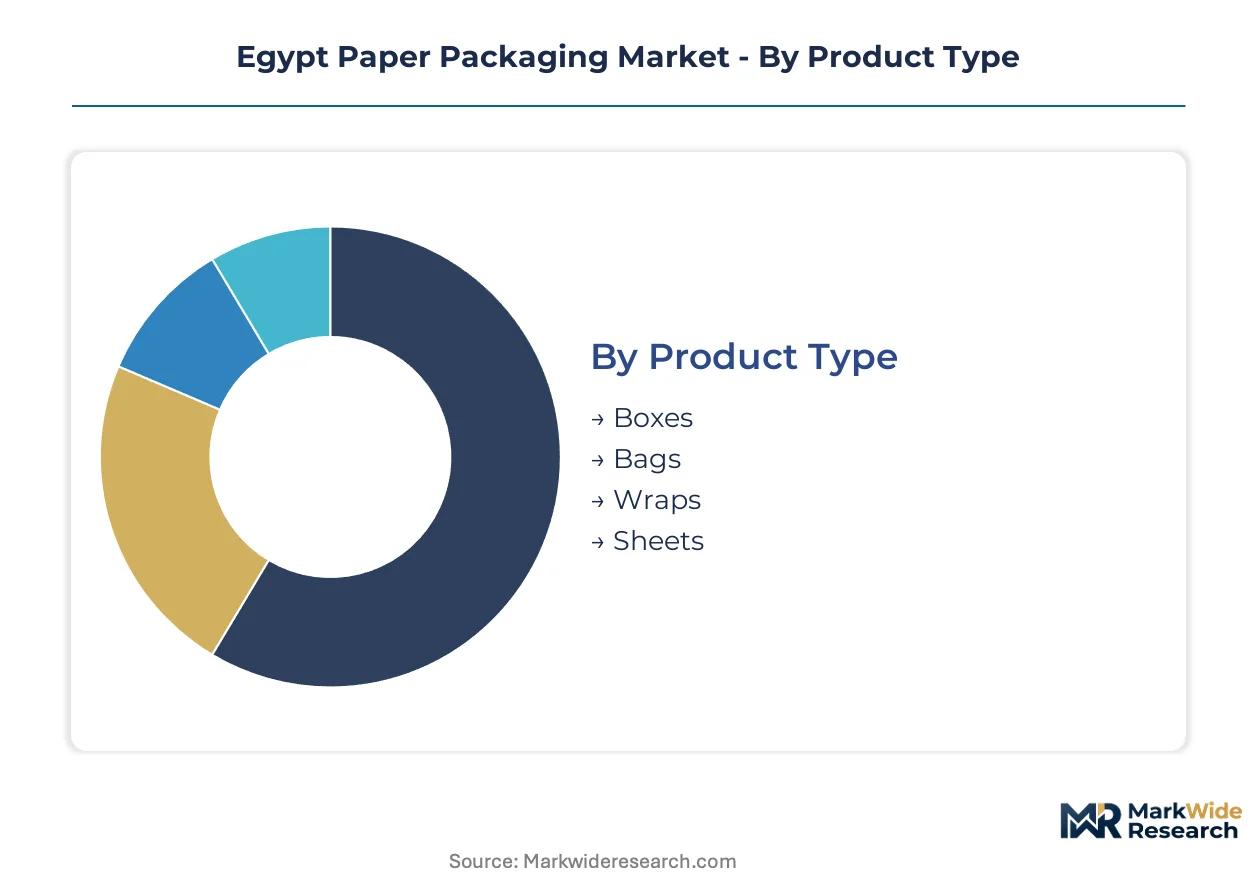
Converters across Egypt configure mill output around four intersecting dimensions that determine specification sheets and pricing tiers. Product geometry, end-use contamination risk, form factor logistics, and fiber substrate cost define how orders flow through Greater Cairo's industrial corridor versus Upper Egypt governorates.
Product Type:
Supply concentrates in corrugated formats where agricultural exporters and e-commerce fulfillment centers anchor volume commitments.
- Boxes:Corrugated fiberboard containers engineered to burst strength and edge crush test specifications dominate agricultural export crating for Nile Delta citrus shipments. Dairy and confectionery plants in 10th of Ramadan City specify food-grade liners with lot-traceability documentation for direct mill procurement.
- Bags:Multiwall k sacks and pinch-bottom constructions serve flour mills and construction material distributors across Alexandria Port Zone. Quick-service restaurant chains in Greater Cairo accelerate kraft bag purchases for bread and dry goods takeaway as polyethylene alternatives face substitution pressure.
- Wraps:Grease-resistant kraft sheets protect fresh produce and bakery items in informal retail channels.
- Sheets:Flat kraft and test liner sheets function as interleaving layers for glassware and ceramics in industrial packaging applications.
Boxes absorb the bulk of installed capacity; bags are expanding most quickly.
End User:
Cost tier stratification separates food-contact certified production from industrial-grade output.
- Food & Beverage:UHT milk, yogurt, and processed cheese producers in Greater Cairo drive coated folding carton demand while navigating moisture barrier limitations of pure fiber solutions. Environmental Affairs Agency food-contact safety protocols mandate chlorine-free bleaching and water-treatment compliance that elevate converter capital requirements.
- Personal Care:Cosmetics and hygiene product brands specify premium-grade bleached kraft for shelf-ready display cartons in pharmacy retail chains.
- Household Products:Detergent and cleaning chemical distributors utilize recycled linerboard for secondary shipping containers with lower certification thresholds.
- Pharmaceuticals:Drug manufacturers require tamper-evident folding cartons with serialization compatibility under Egyptian Organization for Standardization and Quality protocols.
Food & Beverage commands premium pricing tiers; Pharmaceuticals is climbing the fastest on regulatory compliance upgrades.
Form:
Volume throughput favors formats that minimize warehousing footprint and maximize pallet density.
- Flat:Unfolded sheet stock and die-cut blanks enable just-in-time converting at brand-owned finishing facilities, reducing inventory carrying costs for seasonal confectionery promotions.
- Rolled:Continuous kraft and linerboard rolls feed high-speed corrugators and flexographic print lines in integrated mill operations.
- Padded:Honeycomb and corrugated cushion constructions protect electronics and automotive parts in Alexandria Port export zones.
- Foldable:Pre-scored carton blanks collapse flat for efficient distribution and rapid assembly at dairy and quick-service restaurant packing stations.
Flat forms dominate converter input volumes; Foldable formats are gaining share fastest on e-commerce fulfillment automation.
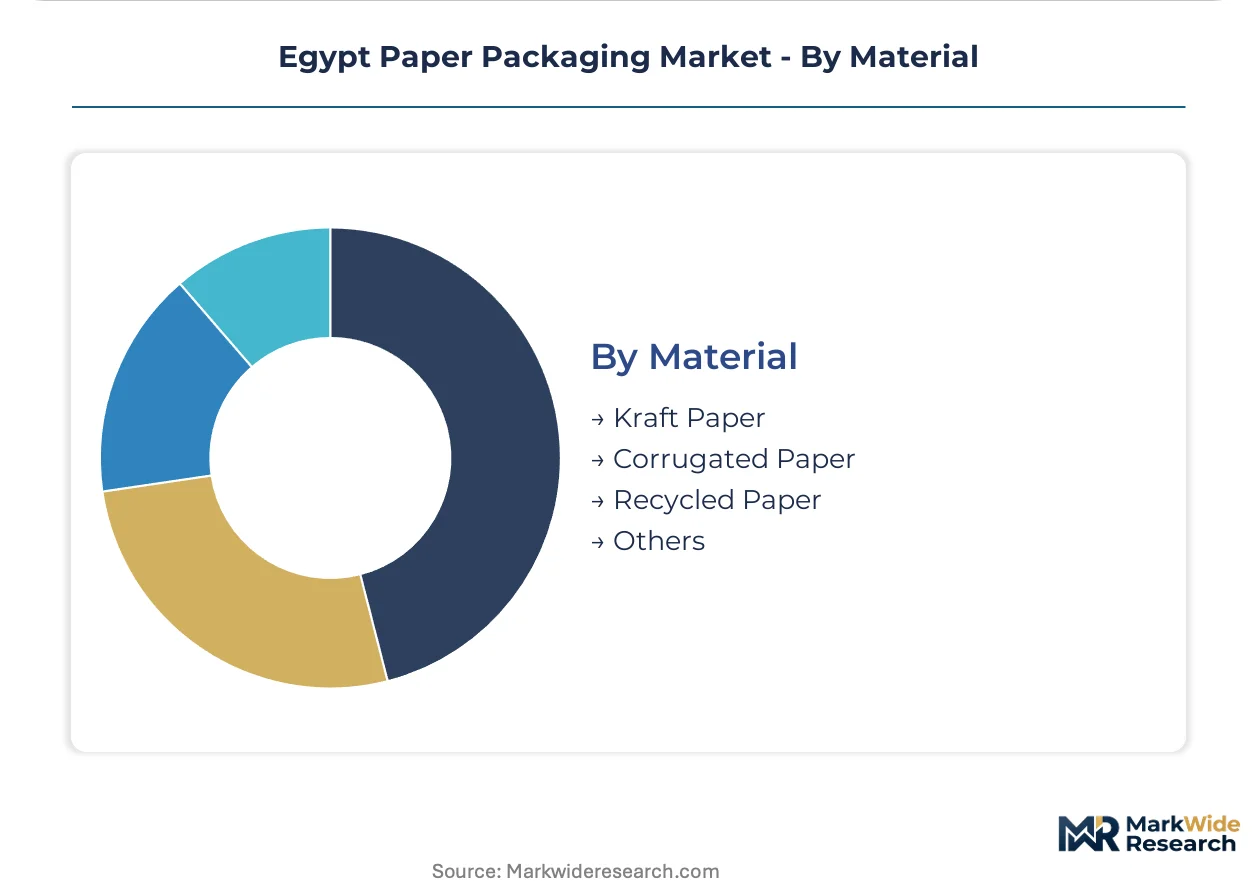
Material:
Margin structure diverges sharply between virgin kraft capacity and recycled fiber dependence on informal collection networks.
- Kraft Paper:Virgin unbleached and semi-bleached grades deliver tear resistance and printability for quick-service food wrapping and premium retail bags. Egyptian mills depend on Brazilian and Scandinavian market pulp, exposing margins to dollar-denominated input volatility and Suez Canal freight surcharges.
- Corrugated Paper:Fluted medium and linerboard combinations constitute the volume backbone for agricultural export crating and FMCG distribution, with digital print convergence enabling short-run customization.
- Recycled Paper:Post-consumer fiber grades satisfy government circular-economy procurement mandates but face supply inconsistency from uncertified Upper Egypt collection networks.
- Others:Specialty substrates including glassine and parchment occupy niche pharmaceutical and food-release applications with limited domestic production.
Corrugated Paper anchors the installed base; Kraft Paper is expanding most quickly on quick-service restaurant chain substitution mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand clusters along the Nile Delta industrial corridor where dairy, confectionery, and agricultural processing plants generate concentrated corrugated and folding carton procurement. Upper Egypt governorates supply recovered fiber through informal collection networks, while Mediterranean port zones attract export-oriented converter investment.
Greater Cairo
Dairy and confectionery plants in 10th of Ramadan City and Obour City drive premium-grade folding carton demand with direct mill-to-brand procurement contracts. Environmental Affairs Agency food-contact safety protocols mandate chlorine-free bleaching and water-treatment compliance. The industrial corridor clustering reduces logistics coordination costs for high-volume corrugated orders.
Alexandria Port Zone
Agricultural exporters and Mediterranean shipping traffic create demand for EU-import-standard corrugated crating and secondary packaging. Underdeveloped converter capacity near Egypt's second-largest container terminal attracts greenfield investment. The port zone's cold chain infrastructure supports citrus and vegetable export crating specifications.
Nile Delta Governorates
Citrus and vegetable producers in Beheira, Kafr El Sheikh, and Dakahlia accelerate corrugated box procurement for refrigerated container transit. Government circular-economy procurement mandates secure offtake for domestic recycled linerboard grades. Collection networks in these governorates feed recovered fiber into Greater Cairo mills.
Upper Egypt
Informal recycling networks in Sohag and Qena supply critical recovered fiber volumes but operate below Egyptian Organization for Standardization and Quality certification thresholds. The Environmental Affairs Agency exhibits widest enforcement variance in these zones. Converters accelerate self-certification before mandatory inspections expand southward.
Suez Canal Economic Zone
Logistics and light manufacturing tenants generate demand for industrial-grade shipping containers and protective packaging. Suez Canal freight surcharges on imported pulp affect converter margin structures in this zone. The zone's special economic status attracts packaging distributors serving Red Sea trade lanes.
Egypt Paper Packaging Market Competitive Landscape
Integrated multinational producers anchor the premium tier; domestic recycled fiber specialists hold the economy tier. Market structure tilts toward consolidation at the top with fragmented mid-tier converters competing on regional logistics proximity. Two strategic archetypes dominate: integrated containerboard mills with captive pulp supply and recycled linerboard producers leveraging informal collection networks. Capacity expansion and direct mill-to-brand procurement contracts constitute the dominant competitive moves.
Within the integrated multinational tier, Smurfit WestRock plc and Huhtamaki Egypt L.L.C. exemplify archetypes combining global substrate security with localized finishing capacity. Masr International Paper occupies a position representing domestic recycled fiber integration. These three anchors demonstrate how geographic origin and corporate structure map to competitive positioning: Irish-American integration, Finnish-African flexible packaging specialization, and Egyptian recycled linerboard dominance.
| Leading Market Players |
|---|
| INDEVCO Group SAL |
| International Paper Company |
| Tetra Pak Egypt Ltd |
| Graphic Packaging International Egypt |
| Smurfit WestRock plc |
| Huhtamaki Egypt L.L.C. |
| Masr International Paper |
| Cepack Group |
| Mondi plc |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between chlorine-free food-contact liners and uncertified recycled grades splits Egyptian converters into two pricing camps, with Environmental Affairs Agency compliance costs propagating through direct mill-to-brand contracts while informal fiber networks feed a parallel economy tier lacking traceability documentation.
Pricing Analysis
Volume throughput concentrates in corrugated agricultural crating where thin margins reward scale, while premium-grade folding cartons for Greater Cairo dairy plants capture wider spreads through food-contact certification and lot-traceability documentation. Price differentiation hinges on Egyptian Organization for Standardization and Quality compliance status and direct procurement contract structures. Pricing pressure intensifies in kraft linerboard as dollar-denominated Brazilian and Scandinavian pulp imports absorb Suez Canal freight volatility. State-owned food distributors exhibit lowest price sensitivity due to circular-economy procurement mandates; quick-service restaurant chains show highest sensitivity as polyethylene substitution deadlines compress conversion budgets.
Supply Chain Analysis
Certification gating through Egyptian Organization for Standardization and Quality protocols fragments fiber sourcing between formal Greater Cairo mills and uncertified Upper Egypt collection networks. Geographic supply concentrates in Egypt, Brazil, and Scandinavian markets for virgin kraft pulp. Raw material dependencies center on market pulp imports, recovered fiber from informal collectors, and water-treatment chemicals for emissions compliance. Supply chain risk stems from single-source vulnerability in dollar-denominated pulp contracts. Distribution runs through direct mill-to-brand procurement displacing traditional distributor intermediaries for high-volume corrugated accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's paper packaging sector functions as a cost-of-compliance market where Environmental Affairs Agency emissions standards and food-contact safety protocols erect capital barriers that favor incumbent integrated mills over undercapitalized mid-tier converters.
For Market Incumbents: Lock in fiber security through captive supply arrangements with Brazilian pulp traders and accelerated water-treatment upgrades ahead of mandatory Upper Egypt inspection expansion. Threats from polyethylene-lined folding cartons in high-moisture dairy applications demand barrier coating R&D investment. Vertical integration into recovered fiber collection networks in Sohag and Qena governorates secures feedstock against certification-gap competitors. For New Entrants and Emerging Players: Digital print convergence for short-run corrugating lines offers a technology-first wedge into seasonal confectionery promotions and limited-edition FMCG launches previously reserved for integrated mills. Alexandria Port Zone converter capacity represents the most penetrable white space, serving Mediterranean agricultural exporters with EU-import-standard crating specifications. Go-to-market positioning should target direct procurement relationships with Nile Delta citrus exporters bypassing traditional distributor markups. For Investors and Strategic Acquirers: Re-rating potential sits with domestic recycled linerboard specialists given government circular-economy procurement mandates securing long-term offtake. Acquisition targets should display informal fiber collection integration in Upper Egypt governorates with pathway to Egyptian Organization for Standardization and Quality certification. Signal to monitor: Environmental Affairs Agency enforcement consistency expansion southward triggering consolidation pressure on uncertified networks.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Treatment Upgrade Investment | Environmental Affairs Agency compliance deadlines force capital deployment ahead of mandatory inspection expansion. |
| Direct Mill-to-Brand Procurement Contracting | Dairy and confectionery plants in 10th of Ramadan City secure lot-traceability documentation bypassing distributors. |
| Digital Print Convergence Deployment | Inkjet decoration enables short-run customization for seasonal confectionery promotions and limited-edition FMCG launches. |
| Recovered Fiber Collection Network Integration | Upper Egypt informal networks in Sohag and Qena supply critical volumes with certification pathway potential. |
| Barrier Coating R&D Program | Water-based alternatives to polyethylene lamination target high-moisture dairy applications in Greater Cairo plants. |
Research Methodology
Trade association filings, Egyptian Organization for Standardization and Quality certification registries, and Environmental Affairs Agency emissions compliance records formed the secondary backbone, supplemented by primary interviews with containerboard mill operations directors, quick-service restaurant chain procurement managers, dairy plant packaging engineers, and corrugated converter technical directors. Bottom-up volume estimates from individual facility capacities triangulated against top-down demand projections from agricultural export and FMCG distribution channels.
Historical trendline analysis of linerboard pricing spreads and corrugated box shipment patterns informed the projection framework across the analysis window. Segmentation modeling incorporated product geometry, end-use contamination risk tiers, form factor logistics efficiency, and fiber substrate cost structures. CAGRs derived from fitted growth curves applied to baseline volume data, with adjustments for plastic substitution mandate acceleration and circular-economy procurement rule implementation.
Several conditions sit outside the modeled scope, including potential currency devaluation impacts on dollar-denominated pulp contracts and unannounced Environmental Affairs Agency enforcement timeline shifts. Forecasts reflect assumptions regarding sustained agricultural export growth and stable Suez Canal transit economics. A model refresh is warranted upon material change in government procurement recycled-content thresholds or major integrated mill capacity addition announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
South Korea Paper Packaging Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Paper Packaging Market
Paper & Paperboard Packaging
Plastic Toilet Paper Dispenser Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
Kraft Envelopes Market
Paper & Paperboard Packaging
Envelope Paper Market
Paper & Paperboard Packaging
Disposable Paper Cups Market
Paper & Paperboard Packaging
Global Paper Bags Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Die Cut Box Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Kraft Paper Bags Market