
 Australia Paper and Paperboard Packaging Market | 2026-2036
Australia Paper and Paperboard Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Paper and Paperboard Packaging Market Outlook
Plastic is shifting toward paperboard across Australian retail and logistics channels as brand owners face compliance pressure and consumer preference changes. Visy Industries leverages its integrated pulp-to-box manufacturing footprint to control supply security for major supermarket chains. Amcor plc competes through specialized barrier coatings that extend shelf life for chilled food applications. Orora Limited anchors the wine and beverage segment with dedicated folding carton capacity in South Australia.
Australia paper and paperboard packaging encompasses fibre-based containers, cartons, and protective structures typically manufactured from kraft pulp, recycled OCC, or coated whiteboard ranging from 200 to 800 gsm, formed through corrugation, folding, or rigid lamination processes to enclose, protect, and present goods for distribution and sale. Corrugated boxes dominate volume as e-commerce and agricultural export flows require stackable, printable, cost-efficient shipping media. Folding cartons capture premium margin pools in pharmaceutical and personal care applications where precision die-cutting and child-resistant closures command higher unit values. Biodegradable packaging variants within the packaging type dimension are gaining fastest traction as the Australian Packaging Covenant Organisation's 2025 targets approach and compostability certifications become procurement gatekeepers.
TGA standards govern pharmaceutical packaging integrity, while the Australian Packaging Covenant Organisation enforces national recycling and sustainable design obligations that reshape material specifications across all states. The National Plastics Plan and associated state-level bans on single-use plastics in Queensland, South Australia, and New South Wales directly redirect food service and retail demand into paperboard alternatives. Stakeholders must monitor emerging PFAS restrictions and fibre sourcing certification requirements as these will determine which converters retain supermarket and export channel access.
Market Dynamics
The Australian Packaging Covenant Organisation's 2025 sustainability targets are compressing plastic-to-fibre conversion timelines across retail and logistics channels. Brand owners now face procurement gatekeepers demanding certified compostable substrates, rewiring converter investment priorities and supermarket private-label specifications simultaneously.
Growth Catalysts
- E-commerce fulfillment surge:Corrugated shipping containers are capturing volume across New South Wales and Victoria as last-mile delivery networks expand. Major supermarket chains are consolidating supplier bases around fibre-based alternatives.
- National Plastics Plan implementation:State-level bans on single-use plastics in Queensland, South Australia, and New South Wales are redirecting food service demand into paperboard. Retail packaging specifications are being rewritten to exclude petroleum-derived substrates.
- Fresh produce export compliance:Queensland and South Australian exporters require protective packaging meeting international phytosanitary standards. Fibre-based solutions are displacing expanded polystyrene in horticultural cold chains.
Market Restraints
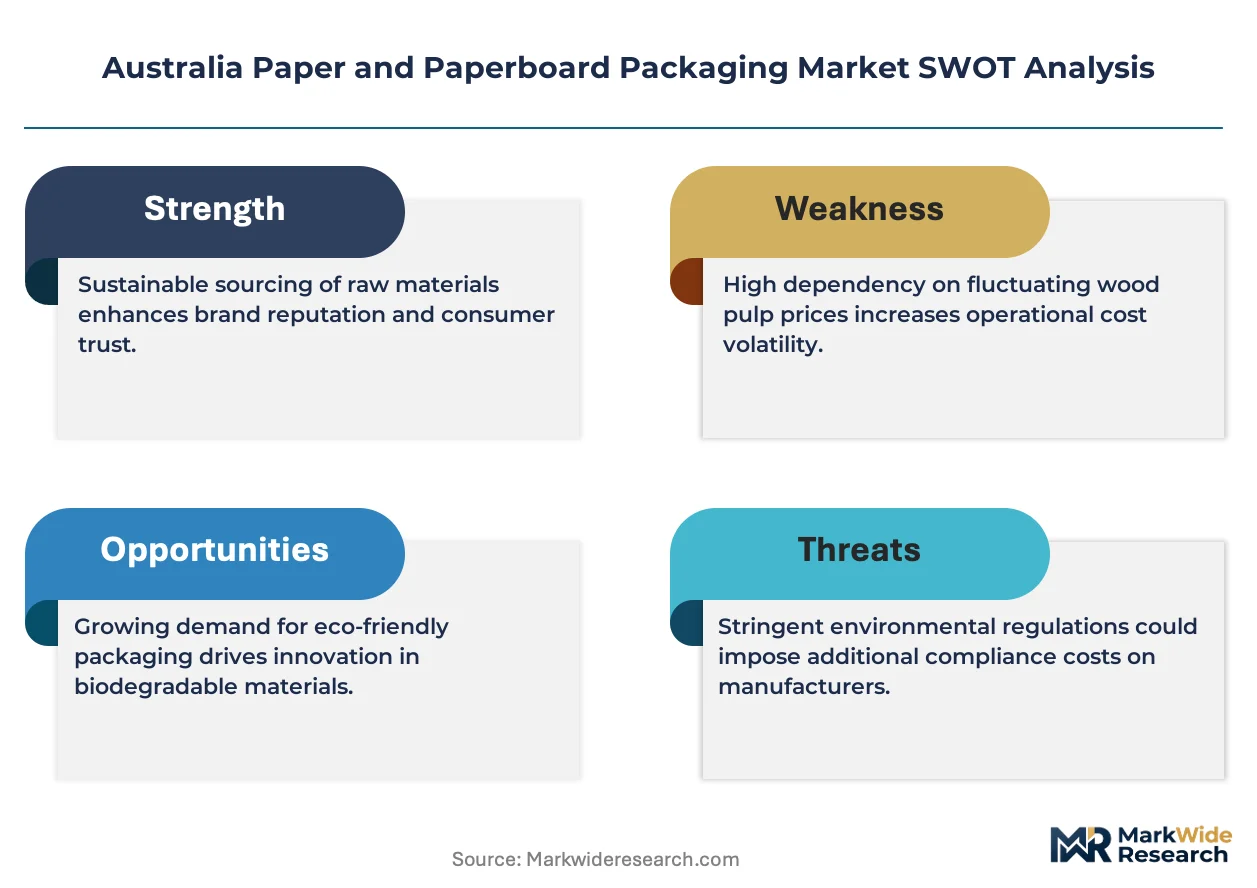
- Recycled OCC supply volatility:Domestic recovered fibre collection rates fluctuate with municipal recycling program participation. Import dependency for kraft pulp exposes converters to currency and shipping cost swings.
- Barrier coating performance gaps:Water-based and bio-based coatings struggle to match plastic multilayers for chilled protein shelf life. Extended freshness requirements in red meat and seafood segments limit material substitution.
- Energy cost concentration:Pulp drying and corrugator operations are natural gas-intensive. Manufacturing clusters in Victoria face input cost pressure from wholesale electricity market volatility.
Strategic Opportunities
- PFAS-free certification leadership:Early compliance with emerging per- and polyfluoroalkyl substance restrictions will unlock supermarket and export channel access. First-mover converters can anchor preferred supplier status.
- Wine and spirits premiumization:Dedicated folding carton capacity for high-end beverage applications commands margin premiums. South Australia's established cluster supports specialty finishing and embossing capabilities.
- Pharmaceutical barrier innovation:TGA-compliant child-resistant and senior-friendly closures present white space for precision die-cut carton specialists. Compliance-driven specifications limit commodity competition.
Industry Challenges
- Compostability certification backlog:Australian Bioplastics Association and Australasian Bioplastics Association verification timelines are extending. Product launch schedules slip while awaiting home and industrial compostability credentials.
- Legacy equipment retrofit costs:Converters with 1990s-era corrugators face capital intensity to handle lighter-weight, higher-recycled-content board. Print quality and run-speed trade-offs complicate investment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Paper and Paperboard Packaging Market |
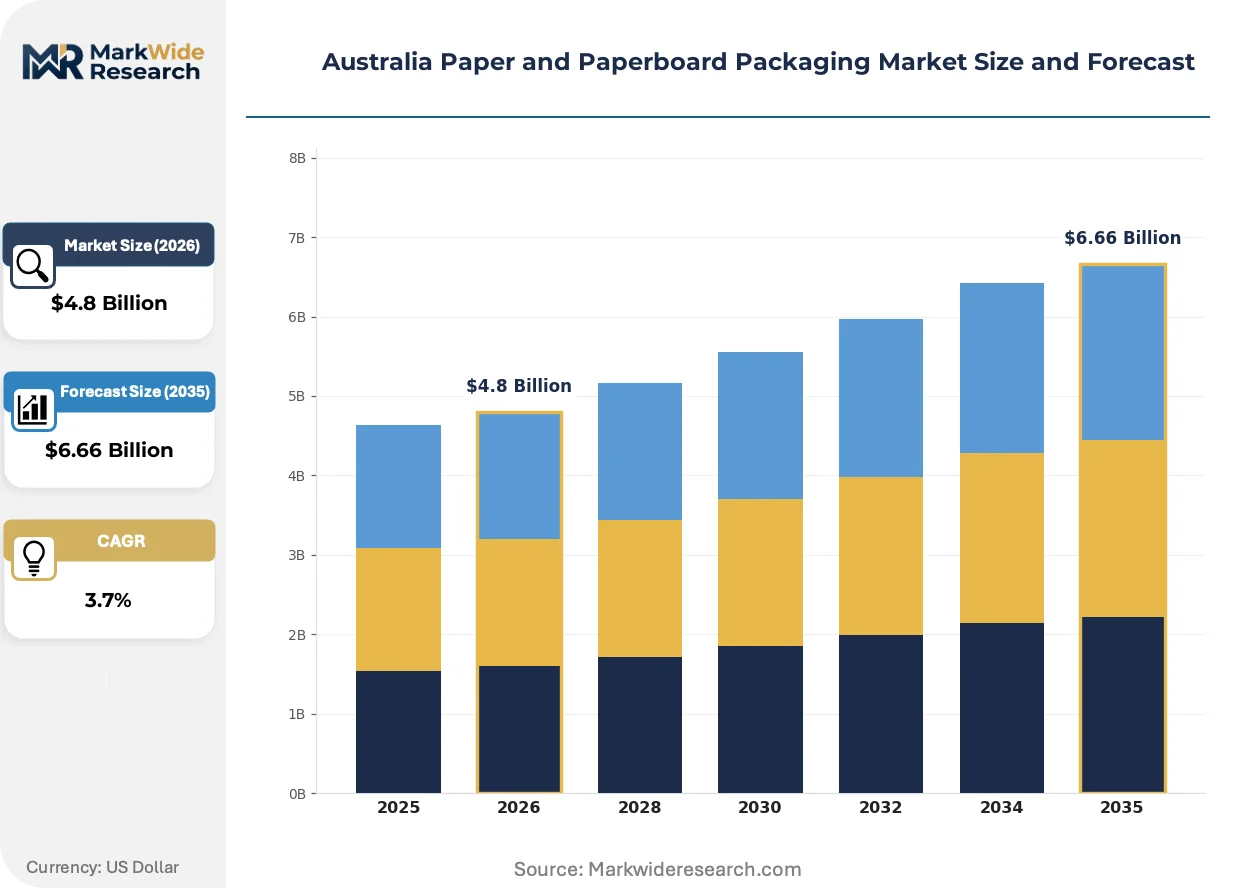
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrugated Boxes, Folding Cartons, Paper Bags, Rigid Boxes End User: Food & Beverage, Personal Care, Pharmaceutical, E-Commerce Packaging Type: Retail Packaging, Industrial Packaging, Food Packaging, Biodegradable Packaging Application: Shipping, Storage, Display, Protection |
| Companies Covered | Amcor plc, Abbe Corrugated Pty Ltd, Visy Industries, Oji Fibre Solutions, Networkpak Pty Ltd, Opal Group, Pro-Pac Packaging Limited, Austcor Packaging Pty Ltd, Orora Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Paper and Paperboard Packaging Market Strategic Shifts
Active material science breakthroughs and compliance-driven specification changes are restructuring competitive advantage across Australian packaging value chains. Technology adoption patterns now diverge sharply between commodity shipping applications and premium presentation segments.
Water-based barrier coatings with oxygen and moisture resistance are overtaking conventional polyethylene extrusion in chilled food cartons. Protein processors and ready-meal manufacturers are piloting these substrates at commercial scale during 2024-2025 procurement cycles. The shift is compressing demand for imported plastic films while creating captive coating capacity investments at major converter sites.
The Australian Packaging Covenant Organisation's recycled content mandates are forcing redesign of folding carton specifications for pharmaceutical and personal care applications. TGA stability testing protocols are being adapted to validate fibre-based alternatives without compromising product integrity. Multinational brand owners are consolidating Australian sourcing around converters with integrated recycling certification and batch-level traceability systems.
Direct-to-retailer procurement contracts are displacing traditional merchant distribution for corrugated volume. Major supermarket chains are negotiating mill-direct arrangements for private-label packaging, bypassing regional distributor networks. This concentration is most visible in Victoria and New South Wales, where two national retailers account for the majority of standard RSC box demand and are extracting logistics cost concessions in exchange for volume commitments.
Australia Paper and Paperboard Packaging Market Segmentation
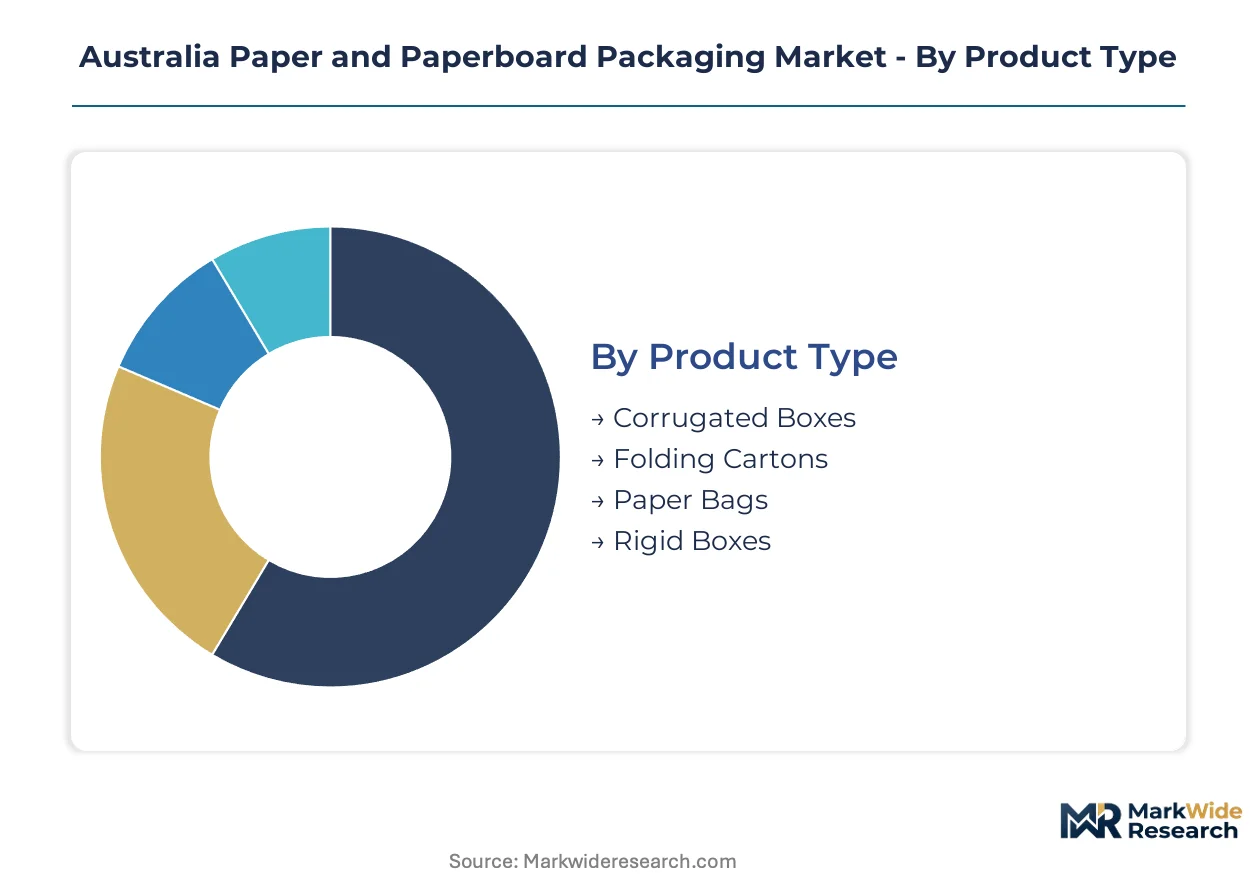
Paper and paperboard packaging specifications diverge sharply across Australian end-use channels. Converter investment priorities track directly to which segments command procurement volume and sustainability compliance premiums.
Product Type:
Structural engineering and board grammage define performance thresholds across Australian manufacturing clusters.
- Corrugated Boxes:Double-wall and triple-wall constructions from 200-800 gsm kraft linerboard dominate agricultural export and e-commerce fulfillment. Queensland fresh produce exporters and Victorian last-mile distributors specify B-flute and C-flute profiles for stack strength and printability.
- Folding Cartons:Coated whiteboard and solid bleached sulphate substrates serve pharmaceutical blister packs and premium beverage presentation. South Australian wine producers and Sydney-based personal care brands demand precision die-cutting with child-resistant locking mechanisms.
- Paper Bags:Kraft paper constructions with twisted or flat handles displace plastic carry bags under state-level bans. Quick-service restaurants in New South Wales and retail chains across Victoria drive volume specifications.
- Rigid Boxes:Thick chipboard laminated with printed wrap papers enclose luxury cosmetics and gift sets. Melbourne and Sydney specialty converters maintain hand-finishing capacity for embossed and foil-stamped applications.
Mature deployment sits with corrugated boxes across industrial logistics. Newer deployment is concentrated in rigid boxes as premium brand owners seek unboxing differentiation.
End User:
Customer procurement power reshapes converter margin structures and certification requirements.
- Food & Beverage:Chilled protein processors and ready-meal manufacturers specify water-based barrier coatings to replace polyethylene extrusion. Australian Packaging Covenant Organisation recycled content mandates are rewriting folding carton specifications for dairy and bakery applications.
- E-Commerce:Major supermarket chains negotiate mill-direct contracts for standard RSC boxes, bypassing regional distributors. New South Wales and Victorian fulfillment centers drive demand for lightweight, high-recycled-content board that withstands automated sortation.
- Pharmaceutical:TGA stability testing protocols validate fibre-based alternatives for blister pack backing and patient information leaflets. Batch-level traceability systems separate compliant converters from commodity suppliers.
- Personal Care:Precision die-cut cartons with senior-friendly closures capture premium positioning. Sydney and Melbourne brand owners consolidate sourcing around integrated recycling certification.
Food and beverage commands the deepest converter relationships. E-commerce is climbing the fastest as direct procurement contracts displace traditional merchant distribution.
Packaging Type:
Function and disposal pathway determine material specifications and regulatory exposure.
- Food Packaging:Direct-contact applications require virgin fibre or approved recycled content with migration testing. Queensland meat processors and Tasmanian seafood exporters specify oxygen barrier performance for extended shelf life.
- Biodegradable Packaging:Home and industrial compostability certifications from the Australian Bioplastics Association function as procurement gatekeepers. Food service operators in South Australia and New South Wales face compressed conversion timelines.
- Retail Packaging:Shelf-ready designs with tear-away perforations and integrated display headers serve supermarket private-label programs. Print quality and run-speed trade-offs complicate converter equipment decisions.
- Industrial Packaging:Heavy-duty corrugated and edge-protector systems secure machinery and building materials through distribution. Manufacturing clusters in Victoria specify burst strength and puncture resistance over print aesthetics.
Industrial packaging maintains the most standardized specifications. Biodegradable alternatives are expanding most quickly as the Australian Packaging Covenant Organisation's targets approach.
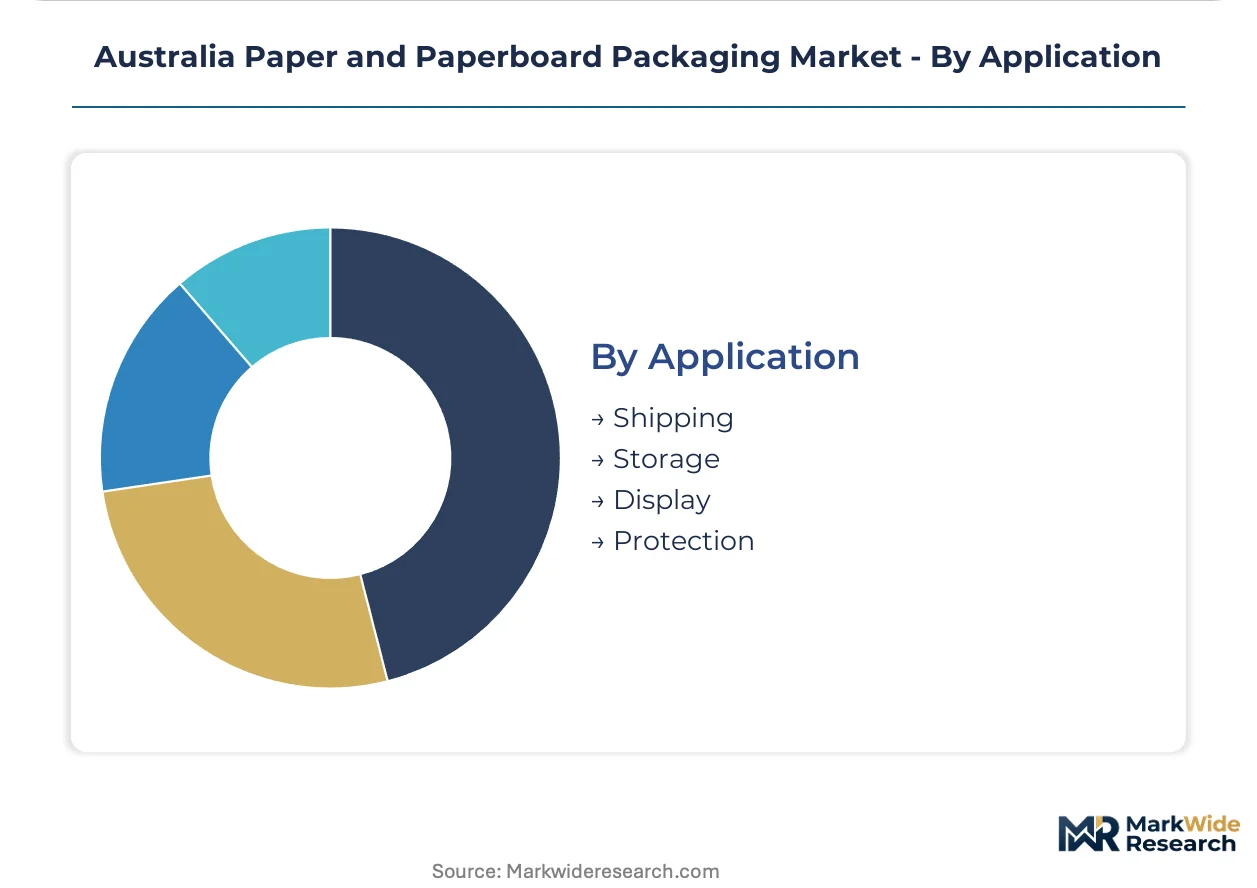
Application:
Physical stress and environmental exposure dictate board construction and protective features.
- Shipping:Stackable corrugated containers with moisture-resistant adhesives survive intermodal transfer and ocean freight. Export-oriented horticultural producers in South Australia specify international phytosanitary compliance.
- Protection:Cushioning inserts, partitions, and edge protectors prevent damage to fragile goods. Electronics distributors and glassware importers in Sydney and Melbourne drive demand for engineered paperboard dunnage.
- Storage:Archive-quality boxes with acid-free construction preserve documents and museum collections. Government and institutional procurement in Canberra maintains steady specifications.
- Display:Point-of-sale units with high-impact graphics and easy-assembly features convert retail floor space. Seasonal campaigns for confectionery and cosmetics concentrate demand in calendar-driven production windows.
Shipping applications anchor converter volume. Display packaging shows the steepest expansion trajectory as brand owners seek retail differentiation without permanent fixture investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Australian Packaging Covenant Organisation's sustainability mandates have concentrated converter investment in designated industrial zones across five states. State-level plastic bans and export compliance requirements are redirecting capital toward fibre-based manufacturing clusters.
New South Wales
E-commerce fulfillment centers in Sydney and Western Sydney demand lightweight corrugated board for automated sortation systems. The state's single-use plastics ban redirects quick-service restaurant packaging into kraft paper alternatives. Manufacturing activity clusters around the Port Botany logistics corridor where mill-direct supermarket contracts are negotiated.
Victoria
Natural gas-intensive pulp drying operations face wholesale electricity market volatility in Melbourne's southeastern manufacturing belt. The Australian Packaging Covenant Organisation's recycled content targets are forcing equipment retrofits at legacy corrugator sites. Brand owners in the state consolidate sourcing around converters with integrated recycling certification systems.
Queensland
Fresh produce exporters in the Lockyer Valley and Darling Downs require phytosanitary-compliant protective packaging for Asian market access. Fibre-based solutions displace expanded polystyrene in horticultural cold chains under state environmental regulations. Brisbane-based distributors are capturing volume from agricultural export flows.
South Australia
Wine and spirits producers in the Barossa Valley and McLaren Vale drive demand for premium folding carton capacity with specialty finishing capabilities. The state's early single-use plastics ban accelerated food service conversion to paperboard alternatives. Adelaide converters maintain dedicated embossing and foil-stamping equipment for luxury beverage presentation.
Western Australia
Mining equipment distributors in Perth specify heavy-duty corrugated and edge-protector systems for machinery export to Asian markets. Isolation from eastern manufacturing clusters creates logistics cost premiums for containerboard supply. Local converters focus on industrial protective applications rather than commodity food packaging.
Australia Paper and Paperboard Packaging Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated pulp-to-box operators commanding supermarket private-label volume while independent converters serve specialty export niches. The market exhibits moderate concentration at the national level, with three to four groups controlling corrugated linerboard supply. Strategic archetypes include vertically integrated fibre producers, regional merchant converters, and specialty folding carton specialists. Competitive moves center on mill-direct procurement contracts and PFAS-free certification investments that unlock retail channel access.
Among integrated Australian operators, Visy Industries and Orora Limited exemplify the scale-driven tier with captive pulp supply and national distribution networks. Amcor plc represents the multinational specialist archetype competing through barrier coating technology for chilled food applications. These three anchors demonstrate how control over raw material sourcing or specialized coating capabilities separates preferred suppliers from commodity competitors in procurement decisions.
| Leading Market Players |
|---|
| Amcor plc |
| Abbe Corrugated Pty Ltd |
| Visy Industries |
| Oji Fibre Solutions |
| Networkpak Pty Ltd |
| Opal Group |
| Pro-Pac Packaging Limited |
| Austcor Packaging Pty Ltd |
| Orora Limited |
| Others |
Value Chain & Pricing Dynamics
Major supermarket chains in New South Wales and Victoria anchor procurement volume and enforce contract-based long-term offtake pricing that compresses margin flexibility for converters. Their mill-direct negotiations bypass traditional distributor markups while extracting logistics concessions in exchange for volume commitments.
Pricing Analysis
Lead-time premiums reward converters with certified compostability credentials and PFAS-free substrates who can deliver against compressed Australian Packaging Covenant Organisation compliance deadlines. Spot inventory discounts apply to standard corrugated grades with higher recycled content that trade through merchant channels. Price differentiation rests on barrier coating performance tiers and integrated recycling certification systems. Margins are tightening due to natural gas cost volatility in Victorian manufacturing clusters.
Supply Chain Analysis
Direct-to-retailer channels handle hyperscale supermarket demand while regional merchant networks serve fragmented agricultural exporters. Raw material supply draws from Indonesian and Brazilian kraft pulp imports alongside domestic recovered OCC collection. Distribution runs through Port Botany and Melbourne's southeastern logistics corridor where manufacturing clusters concentrate. Single-source vulnerability sits with imported linerboard supply exposed to currency swings and shipping cost spikes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from Australian Packaging Covenant Organisation compliance deadlines and capital-intensive equipment retrofits will force smaller converters toward acquisition or exit. First-mover certification advantages separate viable competitors from distressed assets.
For Market Incumbents: To counter emerging PFAS restrictions, anchor preferred supplier status through early Australasian Bioplastics Association certification investment. Backward integration into captive coating capacity insulates against imported barrier film volatility. Channel control through mill-direct supermarket contracts locks volume against regional merchant competition. For New Entrants and Emerging Players: Capture white space in pharmaceutical barrier innovation where TGA compliance requirements limit commodity competition. South Australian wine premiumization offers penetrable specialty folding carton demand with margin premiums. Target precision die-cut capabilities for child-resistant closures as the go-to-market wedge. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale converters with legacy equipment stranded by recycled content mandates in Victorian industrial zones. Five-to-ten year viability hinges on PFAS-free certification completion and supermarket contract renewal rates. Watch compostability verification backlog clearance as the inflection signal for operational restart viability.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Certification Investment | Early compliance with emerging restrictions unlocks Coles and Woolworths procurement access. |
| Backward Integration into Coating Capacity | In-house barrier production reduces dependency on imported polyethylene extrusion films. |
| Mill-Direct Supermarket Contracting | Volume commitments with major retailers displace regional distributor networks in New South Wales. |
| Pharmaceutical Barrier R&D Partnership | TGA-validated substrates capture premium positioning in blister pack and patient leaflet applications. |
| South Australian Specialty Finishing Expansion | Embossing and foil-stamping capabilities serve Barossa Valley wine premiumization trends. |
Study Parameters
Multi-period observation of corrugated linerboard import volumes, natural gas input costs, and Australian Packaging Covenant Organisation compliance timelines anchored the trend analysis, supplemented by interviews with converter operations directors, supermarket category procurement managers, pharmaceutical packaging engineers, and Australasian Bioplastics Association certification officers. Secondary validation drew from Australian Bureau of Statistics trade data, TGA stability testing protocols, state-level plastics ban implementation schedules, and SEC filings from multinational packaging groups. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Input-output matrices modeled demand across product type, end-use vertical, packaging function, and application stress profiles over the projection horizon. CAGRs derived from recursive least squares estimation incorporating pulp price elasticity and recycled content mandate phase-in schedules. Segmentation dimensions included board grammage tiers, barrier coating technology generations, and state-level regulatory enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to kraft pulp import cost trajectories and compostability certification processing speeds. Periodic stress-testing of base assumptions around energy cost volatility and supermarket procurement consolidation is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Global Folding Boxboards Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Paper Cone Cup Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Paper Packaging Market
Paper & Paperboard Packaging
Insulated Corrugated Boxes Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Anti-Slip Coated Paper Market